
 Vanilla Sugar Market | 2026-2036
Vanilla Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Vanilla Sugar Market Analytics
Ingredient-grade vanilla extract sourcing is rewriting margin allocation across the value chain. McCormick & Company, Inc. leverages its direct Madagascar vanilla bean procurement relationships to secure supply consistency. Kerry Group plc anchors its competitive position through integrated flavor extraction capabilities that span raw bean to finished vanilla sugar formulations. Symrise AG competes via biotechnology-derived vanillin platforms that reduce agricultural dependency in core product lines.
Vanilla sugar denotes sucrose infused with natural vanilla extract, vanillin, or ground vanilla bean particles, typically containing 0.1-0.5% vanilla content by weight to deliver aromatic sweetness in finished goods. Manufacturers employ solvent extraction or supercritical CO2 methods to preserve volatile compounds before blending with crystalline or powdered sugar substrates. Granulated sugar variants occupy the dominant volume position due to shelf stability and broad recipe compatibility across industrial food production. Organic sugar segments command premium positioning as EU organic certification and USDA National Organic Program standards restrict synthetic vanillin use in labeled products.
FDA food additive regulations under 21 CFR govern vanillin safety thresholds, while EFSA flavoring substance evaluations under Regulation (EC) No 1334/2008 dictate maximum permissible concentrations in finished European food products. BIS certification requirements in India mandate labeling disclosures for artificial versus natural vanilla sources, shaping import acceptance criteria for international suppliers. Stakeholders must monitor evolving natural flavorant definitions as regulatory bodies on three continents reassess biotechnology-derived ingredient classifications.
Market Dynamics
Artisan bakery chains across Western Europe now specify vanilla sugar origin on ingredient panels, responding to EU Green Deal traceability requirements for natural flavorants. This regulatory pressure is compressing opaque supply chains and forcing upstream documentation investments.
Growth Catalysts
- EU Green Deal traceability mandates:Protected designation rules in France reinforce premium vanilla sugar positioning and drive labeled ingredient demand.
- Supercritical CO2 extraction:Food manufacturers adopt this solvent-free method to preserve volatile aromatic compounds in industrial-scale production.
- Traditional patisserie standards:French bakery certification programs mandate natural vanilla content thresholds, creating pull-through for certified suppliers.
Market Restraints
- Madagascar supply concentration:Vanilla bean procurement depends on a single-origin geography exposed to cyclone disruption and price volatility.
- Organic certification barriers:USDA National Organic Program and EU organic standards restrict synthetic vanillin use, limiting formulation flexibility for cost-sensitive producers.
- Biotechnology-derived vanillin ambiguity:EFSA and FDA natural flavorant definitions remain unresolved, creating regulatory friction for precision-fermentation alternatives.
Strategic Opportunities
- Indian import standardization:BIS certification requirements for artificial versus natural labeling create first-mover advantage for compliant international suppliers.
- Ground vanilla bean particle formulations:Visual differentiation appeals to premium consumer packaged goods seeking clean-label positioning.
- Direct-to-artisan distribution:Bakery chains bypass traditional ingredient distributors to secure origin-verified supply with full traceability documentation.
Industry Challenges
- Volatile compound preservation:Maintaining aromatic stability through solvent extraction requires precise temperature control and capital-intensive equipment.
- Cross-regulatory compliance:Simultaneous adherence to FDA 21 CFR thresholds, EFSA Regulation (EC) No 1334/2008, and BIS disclosure rules strains quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanilla Sugar Market |
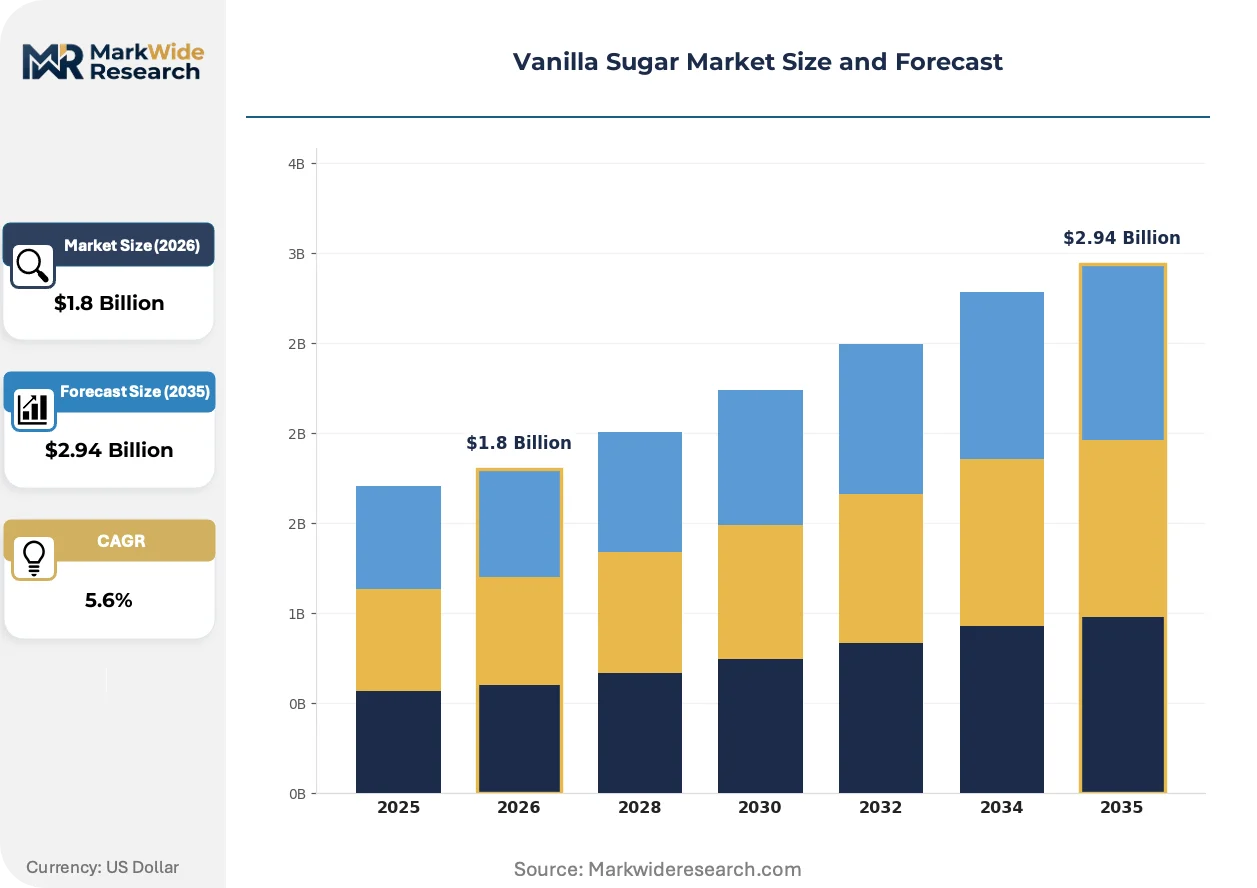
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Powdered Sugar, Liquid Sugar, Organic Sugar End User: Food Industry, Bakery Shops, Home Bakers, Restaurant Chains Application: Desserts, Beverages, Baking, Sauces Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Givaudan SA, Henkel AG & Co. KGaA, International Flavors & Fragrances Inc., McCormick & Company, Inc., Symrise AG, Sensient Technologies Corporation, Kerry Group plc, Archer Daniels Midland Company, Döhler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanilla Sugar Market Evolving Landscape
Biotechnology-derived vanillin platforms are collapsing agricultural dependency in core product lines. Three convergent developments are compressing traditional extraction economics and rewriting competitive positioning across the value chain.
Supercritical CO2 extraction technology is collapsing the cost premium between artisan-scale and industrial-scale vanilla sugar production. Mid-sized European flavor houses deploy this method to serve boutique patisserie chains without sacrificing batch consistency. The compression between small-batch and mass-market quality tiers is eliminating historical segmentation advantages.
EFSA flavoring substance evaluations under Regulation (EC) No 1334/2008 are tightening maximum permissible vanillin concentrations in finished European food products. Industrial bakers reformulate recipes to comply with revised thresholds while maintaining sensory profiles. Powdered sugar substrates with encapsulated vanillin are gaining share in export-oriented production facilities.
Ingredient specification sheets now require origin documentation from Madagascar vanilla cooperatives. French artisan bakery chains audit supplier traceability systems before contract renewal. Procurement teams in Paris and Lyon prioritize suppliers with blockchain-verified bean-to-bag tracking over traditional commodity sources.
Vanilla Sugar Market Segmentation
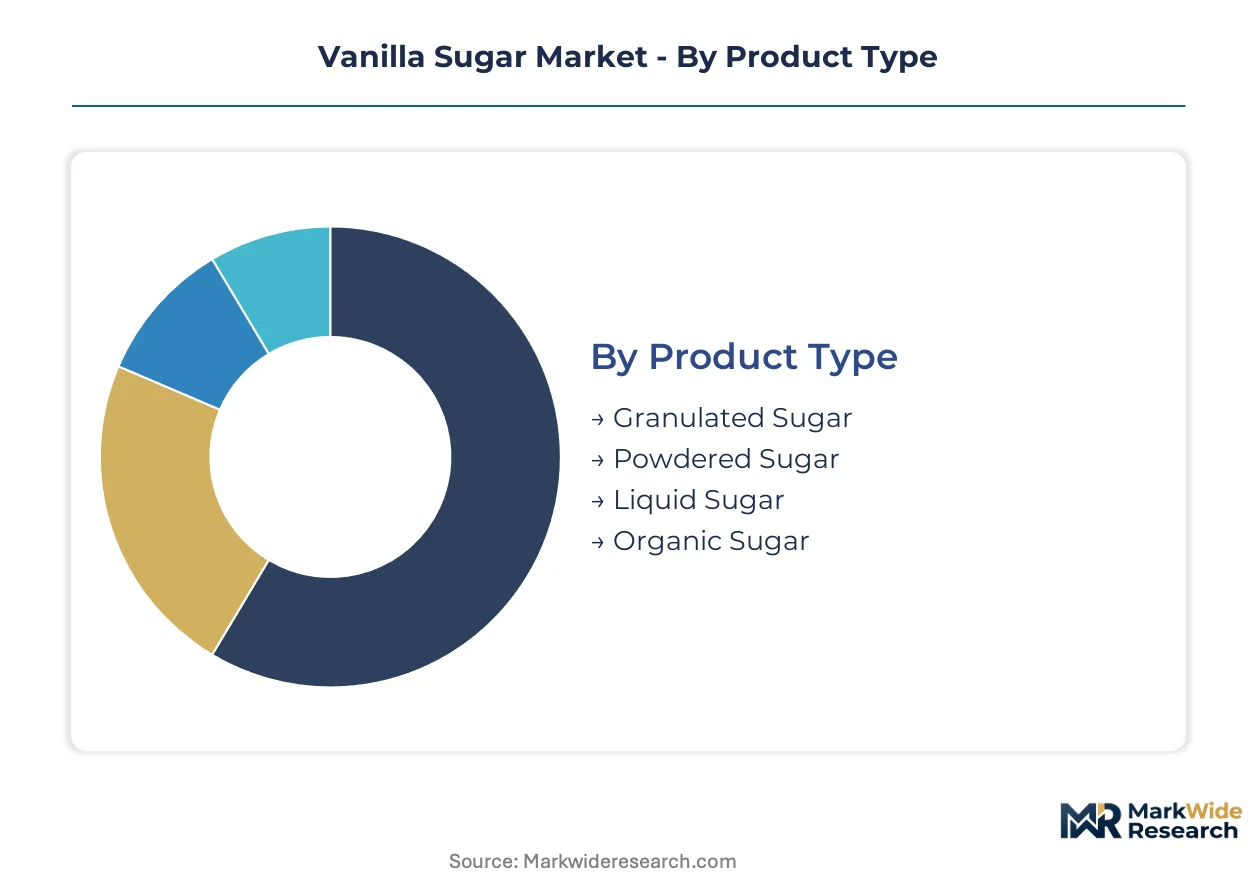
Vanilla sugar segmentation reveals divergent velocity patterns across product formats and buyer channels. Inventory turnover in artisan-facing segments runs 3-4x faster than industrial bulk contracts, compressing working capital cycles for specialized suppliers.
Product Type:
Granulated variants turn inventory fastest due to broad recipe compatibility, while organic certifications extend procurement cycles through documentation requirements. Powdered and liquid formats serve distinct production workflows with contrasting replenishment rhythms.
- Granulated Sugar:Crystalline sucrose infused with 0.1-0.5% vanilla extract or vanillin by weight delivers shelf-stable aromatic sweetness. Industrial bakeries in France specify this format for consistent dosing in high-volume patisserie production, though Madagascar supply volatility forces quarterly contract renegotiations.
- Powdered Sugar:Finely milled substrate with encapsulated vanillin enables uniform dispersion in frostings and dry mixes. Premium dessert manufacturers in Paris and Lyon favor this grade for visual smoothness, with EFSA concentration thresholds under Regulation (EC) No 1334/2008 dictating maximum inclusion rates.
- Liquid Sugar:Inverted syrup base with dissolved vanilla compounds suits beverage and sauce applications requiring homogeneous integration.
- Organic Sugar:Cane or beet sucrose certified under USDA National Organic Program or EU organic standards restricts synthetic vanillin use entirely.
Granulated sugar dominates installed base. Organic sugar is where expansion concentrates.
End User:
Margin structures vary sharply across buyer sophistication tiers. Artisan accounts accept 40-60% premiums for traceability documentation, while industrial food manufacturers prioritize unit cost minimization through long-term supply agreements.
- Food Industry:Large-scale manufacturers of packaged desserts and RTE baked goods procure vanilla sugar in bulk totes with standardized vanillin concentrations. These buyers negotiate annual contracts indexed to Madagascar bean futures, creating exposure to cyclone-driven price spikes.
- Bakery Shops:Independent and chain patisseries across Western Europe now mandate origin disclosure on ingredient panels per EU Green Deal traceability requirements. French certification programs for traditional bakery standards create pull-through demand for natural vanilla content thresholds.
- Home Bakers:Retail-packaged 50-250g formats serve occasional-use consumers through supermarket and online channels.
- Restaurant Chains:Centralized procurement teams specify vanilla sugar for dessert menu consistency across franchise locations.
Food industry absorbs highest absolute volume. Bakery shops is where specification intensity climbs fastest.
Application:
Technical requirements segment the market by thermal stability and moisture compatibility. High-heat applications degrade volatile aromatic compounds, favoring encapsulated vanillin formulations over natural extract infusions.
- Desserts:Custards, ice creams, and chilled confections preserve delicate vanilla top notes without thermal degradation. French protected designation rules reinforce premium positioning for natural extract in traditional patisserie.
- Beverages:Solubility demands drive preference for liquid sugar formats or ultra-fine powdered grades in coffee and smoothie applications.
- Baking:Oven temperatures above 180°C accelerate vanillin volatilization, necessitating higher initial dosing or microencapsulation technology.
- Sauces:Acidic and high-heat reduction processes require pH-stable vanillin variants to prevent flavor degradation.
Dessert applications anchor premium pricing. Beverage formulations is where liquid sugar penetration deepens most quickly.
Distribution Channel:
Channel selection determines margin capture and traceability verification depth. Direct-to-artisan distribution bypasses traditional ingredient distributors, compressing lead times from Madagascar cooperatives to Paris bakery chains.
- Online Retail:E-commerce platforms serve home bakers and small commercial accounts with SKU variety unavailable through brick-and-mortar. Subscription models for organic vanilla sugar build recurring revenue with lower customer acquisition costs than wholesale acquisition.
- Supermarkets:Mass-market retail chains stock granulated and powdered formats in conventional and organic variants. Shelf placement in baking aisles drives impulse purchases, though private label competition pressures branded margins.
- Specialty Stores:Gourmet food retailers and bakery supply shops curate premium vanilla sugar with visible vanilla bean particles for clean-label positioning.
- Wholesale:Foodservice distributors and industrial ingredient suppliers manage bulk logistics for restaurant chains and manufacturers.
Wholesale channels move highest tonnage. Online retail is where customer acquisition economics improve fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial food manufacturers in Germany negotiate vanilla sugar contracts with acute price sensitivity, while French artisan bakery chains absorb 40-60% premiums for Madagascar-origin traceability documentation.
France
Traditional patisserie certification programs mandate natural vanilla content thresholds, creating pull-through demand for certified suppliers. EU Green Deal traceability requirements enforce origin disclosure on ingredient panels across Western Europe. Paris and Lyon procurement teams prioritize blockchain-verified bean-to-bag tracking over commodity sources.
Germany
Large-scale packaged dessert manufacturers procure vanilla sugar in bulk totes indexed to Madagascar bean futures. EFSA Regulation (EC) No 1334/2008 governs maximum permissible vanillin concentrations in finished products. Industrial bakeries in Bavaria and North Rhine-Westphalia reformulate recipes to comply with revised sensory thresholds.
United States
Food manufacturers adopt supercritical CO2 extraction to preserve volatile aromatic compounds at industrial scale. FDA 21 CFR thresholds govern vanillin safety in finished goods. Chicago and New Jersey processing facilities manage cross-regulatory compliance for export-oriented production.
India
BIS certification requirements mandate labeling disclosures for artificial versus natural vanilla sources, shaping import acceptance criteria. Domestic bakery chains expand specification intensity for origin-verified supply. Mumbai and Bangalore distributors build direct-to-artisan distribution networks bypassing traditional channels.
Madagascar
Vanilla bean cooperatives face cyclone-driven supply disruption and price volatility concentrated in single-origin geography. EU Green Deal documentation requirements compress opaque supply chains and force upstream traceability investments. SAVA region producers deploy blockchain verification systems to secure contract renewals with European buyers.
Vanilla Sugar Market Competitive Landscape
Capability concentration sits with integrated flavor extraction specialists; scale advantage sits with diversified ingredient conglomerates. The market structures around three tiers: biotechnology-derived vanillin platforms, direct-origin procurement networks, and integrated bean-to-formulation operations. Strategic moves concentrate on traceability documentation investments and solvent-free extraction technology licensing.
Within the integrated extraction tier, Kerry Group plc and McCormick & Company, Inc. exemplify backward integration into Madagascar vanilla bean procurement relationships. Symrise AG anchors the biotechnology-derived platform segment. Givaudan SA and International Flavors & Fragrances Inc. occupy positions across multiple archetypes. Sensient Technologies Corporation, Archer Daniels Midland Company, and Döhler GmbH represent regional specialists with formulation-to-distribution capabilities. Henkel AG & Co. KGaA sits within adjacent consumer goods channels with flavorant sourcing requirements.
| Leading Market Players |
|---|
| Givaudan SA |
| Henkel AG & Co. KGaA |
| International Flavors & Fragrances Inc. |
| McCormick & Company, Inc. |
| Symrise AG |
| Sensient Technologies Corporation |
| Kerry Group plc |
| Archer Daniels Midland Company |
| Döhler GmbH |
| Others |
Value Network & Pricing Analysis
Antwerp-Rotterdam freight corridors carry Madagascar vanilla bean shipments to European flavor houses, with bunker fuel surcharges compressing margins for artisan-grade suppliers while amplifying price spreads between traceability-certified and commodity-grade vanilla sugar. This logistics cost dynamic reinforces the premium positioning of blockchain-verified origin documentation demanded by French patisserie chains under EU Green Deal mandates.
Pricing Analysis
Extended supply contracts with Madagascar cooperatives anchor lifetime value for integrated flavor houses. Three-tier pricing structure across premium traceability-certified, standard natural extract, and economy synthetic vanillin levels segments buyer willingness to pay. Cost compression in the synthetic tier intensifies as biotechnology-derived platforms achieve scale, while artisan bakery chains absorb minimal price sensitivity for SAVA-origin documentation. Industrial food manufacturers in Germany negotiate quarterly renegotiations indexed to bean futures, exposing procurement teams to cyclone-driven volatility.
Supply Chain Analysis
EU dual-use technology controls on supercritical CO2 extraction equipment limit technology transfer to non-compliant processing facilities in select jurisdictions. Madagascar, France, and India anchor vanilla sugar supply through distinct functions: raw bean cultivation, formulation and certification, and import standardization respectively. The supply chain draws from cyclone-vulnerable single-origin geography, with SAVA region weather events creating acute shortage risk. Distribution runs through direct-to-artisan networks bypassing traditional wholesale channels for traceability-verified segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-derived vanillin platforms are compressing traditional extraction economics, with EFSA and FDA natural flavorant definition resolutions poised to accelerate platform adoption across formulation tiers.
For Market Incumbents: Harden Madagascar procurement relationships through cooperative equity stakes before fermentation-derived alternatives achieve cost parity. Secure exclusive blockchain-verified bean-to-bag tracking partnerships with SAVA region producers to defend against precision-fermentation entrants. Prioritize supercritical CO2 extraction capacity expansion in EU jurisdictions to maintain solvent-free production claims under tightening EFSA thresholds. For New Entrants and Emerging Players: Build out ground vanilla bean particle formulations targeting premium consumer packaged goods seeking visible clean-label differentiation. Target Indian bakery chains expanding specification intensity for BIS-compliant origin-verified supply. Launch direct-to-artisan distribution with full traceability documentation to bypass entrenched wholesale relationships in Paris and Lyon. For Investors and Strategic Acquirers: Integrated extraction specialists with captive Madagascar relationships represent the most defensible acquisition archetype against biotechnology disruption. Frame long-term viability around 5-10 year windows where natural extract premiums persist despite fermentation cost compression. Watch EFSA natural flavorant classification rulings as the critical inflection signal for platform economics shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Madagascar Cooperatives | Captive bean supply secures volume commitments from EU Green Deal-compliant bakery chains. |
| Supercritical CO2 Extraction Licensing | Technology transfer agreements enable solvent-free production claims under EFSA Regulation (EC) No 1334/2008. |
| Blockchain Traceability Deployment | Bean-to-bag verification systems satisfy French protected designation audit requirements. |
| Biotechnology Platform Investment | Precision-fermentation vanillin reduces agricultural dependency for cost-sensitive industrial segments. |
| Direct-to-Artisan Distribution Buildout | Bypassing traditional wholesalers compresses lead times for origin-verified supply in Western Europe. |
Research Methodology
Initial hypotheses were tested against primary input from flavor house procurement directors, Madagascar cooperative managers, French patisserie chain technical buyers, and EU regulatory affairs specialists and refined through secondary validation. Customs data from EU import registries, EFSA flavoring substance evaluation databases, FDA 21 CFR threshold documentation, and BIS certification requirement filings anchored quantitative triangulation. Bottom-up volume estimates from Madagascar bean production statistics converged with top-down value projections from industrial bakery procurement surveys.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product format, end-user sophistication tier, application thermal stability requirements, and distribution channel traceability depth. CAGRs derived from historical price elasticity patterns and Madagascar supply volatility indices, calibrated against EU Green Deal implementation timelines and biotechnology platform scale-up trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by precision-fermentation specialists or accelerated EFSA natural flavorant reclassification would shift outcomes. Material shifts in Madagascar cyclone frequency or EU organic certification threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
North America Stevia Market
Sweeteners
Agave Syrup Market
Sweeteners
United States Xylitol Market
Sweeteners
Stevia Mints Market
Sweeteners
South America Stevia Market
Sweeteners
Isomaltulose Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Xylitol Market
Sweeteners
Dextrates Market
Sweeteners
D-Mannose Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Trehalose Market
Sweeteners
South Korea Allulose Market
Sweeteners
China Saccharin Market
Sweeteners
Monk Fruit Sweetener Market