
 Isomaltulose Market | 2026-2036
Isomaltulose Market Size, Share, and Industry Trends Forecast 2026-2036
Isomaltulose Market Outlook
Market Context with Strategic Players
Germany is tilting the competitive balance through concentrated enzymatic conversion capacity along the Rhine corridor. BENEO GmbH leverages its Palatinate manufacturing complex to sustain backward integration into sucrose refining and crystallization. Südzucker anchors Central European supply through its sugar beet processing network, while Roquette competes from its Lestrem starch derivatives hub with alternative fermentation pathways.
Technical Definition and Structural Segments
Isomaltulose is a reducing disaccharide composed of glucose and fructose linked by an alpha-1,6-glycosidic bond, manufactured industrially through enzymatic rearrangement of sucrose using Protaminobacter rubrum-derived isomaltulose synthase; its slow hydrolysis rate delivers sustained glucose release with minimal insulin spike, making it valuable for metabolic management applications. Crystal Isomaltulose dominates margin pools due to superior shelf stability and clean-label positioning in premium confectionery, while Powder Isomaltulose extends fastest across beverage dry-mix formulations where dispersibility commands formulation priority. The Bakery Products application segment occupies mature volume leadership, though Nutritional Companies as an end-user category is displacing traditional food manufacturers in procurement intensity for clinical and sports formulations.
Regulatory Frame and Forward Outlook
EFSA novel food evaluations, FDA GRAS self-affirmation pathways, and Japan's FOSHU functional claims system collectively determine market access timelines and label positioning across the three largest demand jurisdictions. REACH chemical registration requirements in Europe and China's GB standards for food additives impose compositional testing burdens that favor producers with established regulatory affairs infrastructure. Stakeholders must monitor evolving glycemic index labeling mandates and sugar reduction targets, as these policy instruments will determine which isomaltulose formats capture formulation slots in next-generation product development cycles.
Market Dynamics
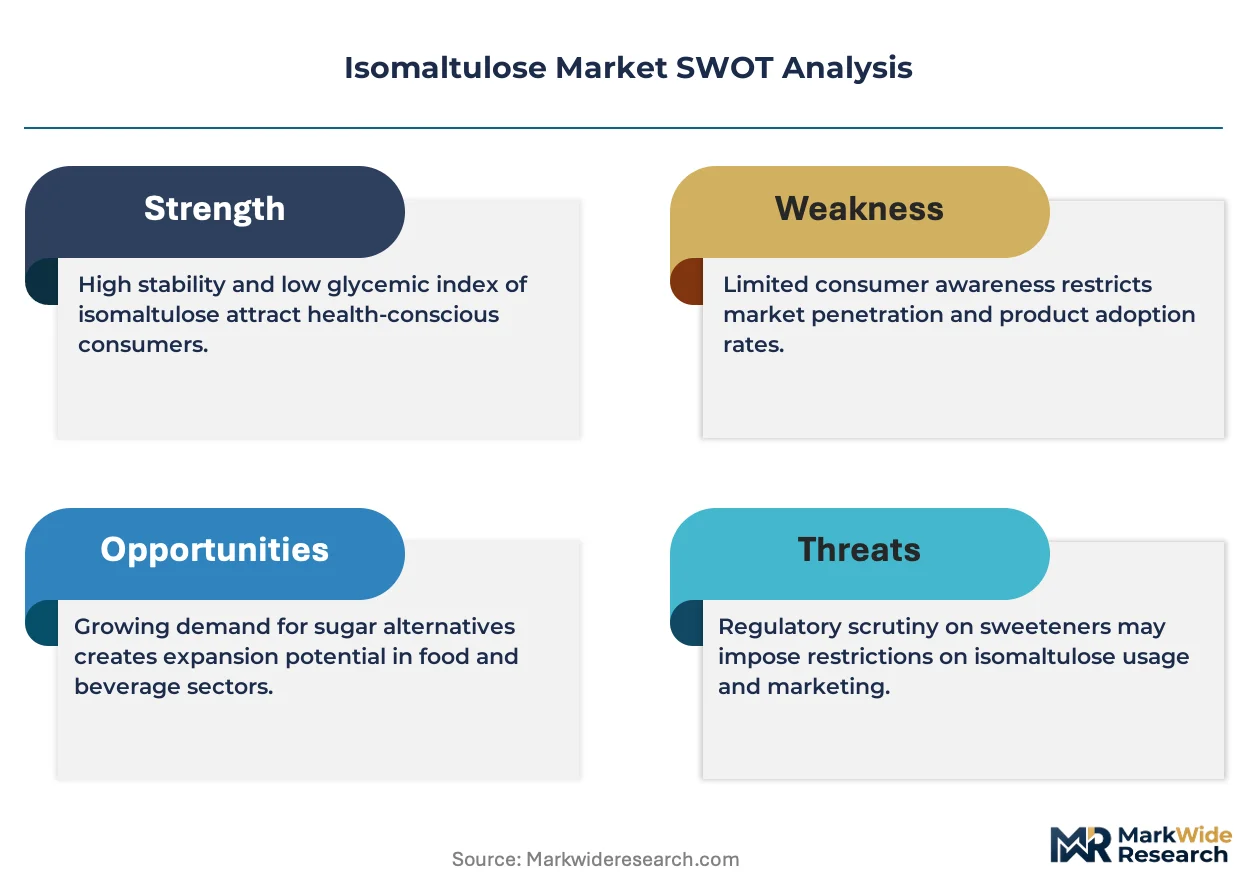
Enzymatic conversion capacity concentration along the Rhine corridor is concentrating supply-side leverage, while EFSA novel food pathways and Japan's FOSHU functional claims system are simultaneously compressing regulatory access timelines for metabolic management formulations.
Growth Catalysts
- Sports nutrition demand:Athletes and fitness consumers are prioritizing low-glycemic carbohydrate sources in pre-workout and endurance formulations, pulling isomaltulose into premium positioning.
- EFSA novel food streamlining:The European Union's centralized approval pathways under EFSA jurisdiction are reducing member-state fragmentation and accelerating cross-border ingredient commercialization.
- Metabolic management applications:Clinical nutrition and diabetes-friendly product lines are expanding procurement intensity for sustained-release carbohydrate systems.
Market Restraints
- Sucrose input volatility:Beet sugar and cane sugar price swings directly compress enzymatic conversion economics, squeezing margin pools for crystallization-heavy producers.
- Supply concentration risk:Palatinate manufacturing complexes and Central European starch derivatives hubs create geographic single-point vulnerability for global formulation supply.
- Allulose substitution threat:Rare sugar alternatives with comparable glycemic properties are capturing beverage formulation slots through FDA GRAS self-affirmation speed advantages.
Strategic Opportunities
- China functional food white space:GB standards for food additives and dual carbon goals are creating regulatory runway for clean-label carbohydrate innovation in sports beverages.
- Beverage dry-mix channel expansion:Powder isomaltulose dispersibility advantages are opening e-commerce direct-to-consumer protein and hydration mix formats.
- EU Green Deal procurement incentives:Sustainability-linked sourcing mandates in public nutrition programs are favoring enzymatic over petrochemical-derived sweetener systems.
Industry Challenges
- Enzyme engineering talent scarcity:Protaminobacter rubrum strain optimization and isomaltulose synthase yield improvement require specialized biocatalysis expertise concentrated in German and Dutch research clusters.
- REACH chemical registration timelines:ECHA compositional testing burdens for novel food-grade derivatives are extending product launch cycles by 18-24 months for producers without established regulatory affairs infrastructure.
- Legacy confectionery equipment retrofit costs:Crystal isomaltulose melting and tempering properties differ from sucrose, forcing capital-intensive production line modifications for clean-label chocolate and candy manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isomaltulose Market |
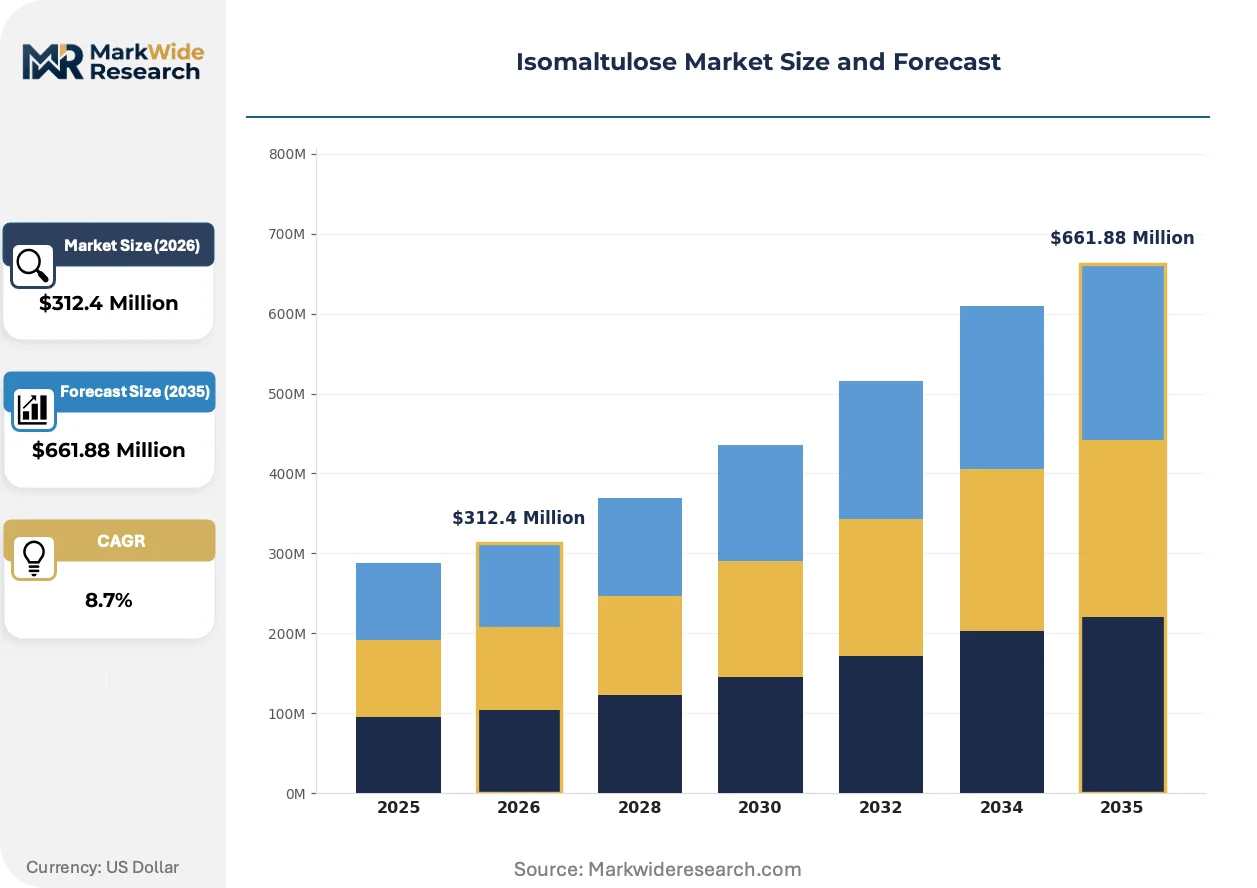
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystal Isomaltulose, Liquid Isomaltulose, Powder Isomaltulose, Granulated Isomaltulose Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Dietary Supplement Providers, Nutritional Companies, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Matsutani Chemical Industry, Frusano GmbH, BENEO GmbH, Roquette, Ingredion, Cargill, Inc., Mitsui Sugar Co. Ltd., Tate & Lyle, Südzucker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isomaltulose Market Strategic Shifts
Continuous enzymatic conversion systems and precision fermentation pathways are compressing production economics, while glycemic index labeling mandates and sugar reduction targets are rewriting formulation priorities across confectionery, beverage, and clinical nutrition verticals.
Continuous flow enzymatic reactors are collapsing batch processing economics for isomaltulose synthesis. German and French ingredient manufacturers are retrofitting sucrose refining infrastructure with immobilized enzyme fixed-bed systems, cutting conversion cycle times from 48 hours to 6 hours. This technology is collapsing the cost gap between crystalline isomaltulose and commodity sucrose in high-volume bakery applications.
Japan's FOSHU functional claims system is tightening evidentiary standards for blood glucose moderation labeling. Manufacturers must now submit human clinical trial data demonstrating measurable postprandial glycemic response reduction, raising R&D compliance costs. Sports nutrition and diabetes-care product categories are responding by partnering with Japanese contract research organizations to generate jurisdiction-specific efficacy dossiers.
Direct procurement from enzymatic conversion specialists is displacing traditional sugar trader intermediaries in North American and European formulation supply chains. Large nutritional companies are establishing multi-year offtake agreements with Palatinate and Lestrem production hubs, securing volume allocation and price stability. This pattern is most visible in Germany, where BENEO GmbH headquarters proximity enables just-in-time delivery coordination for clinical nutrition manufacturers.
Isomaltulose Market Segmentation
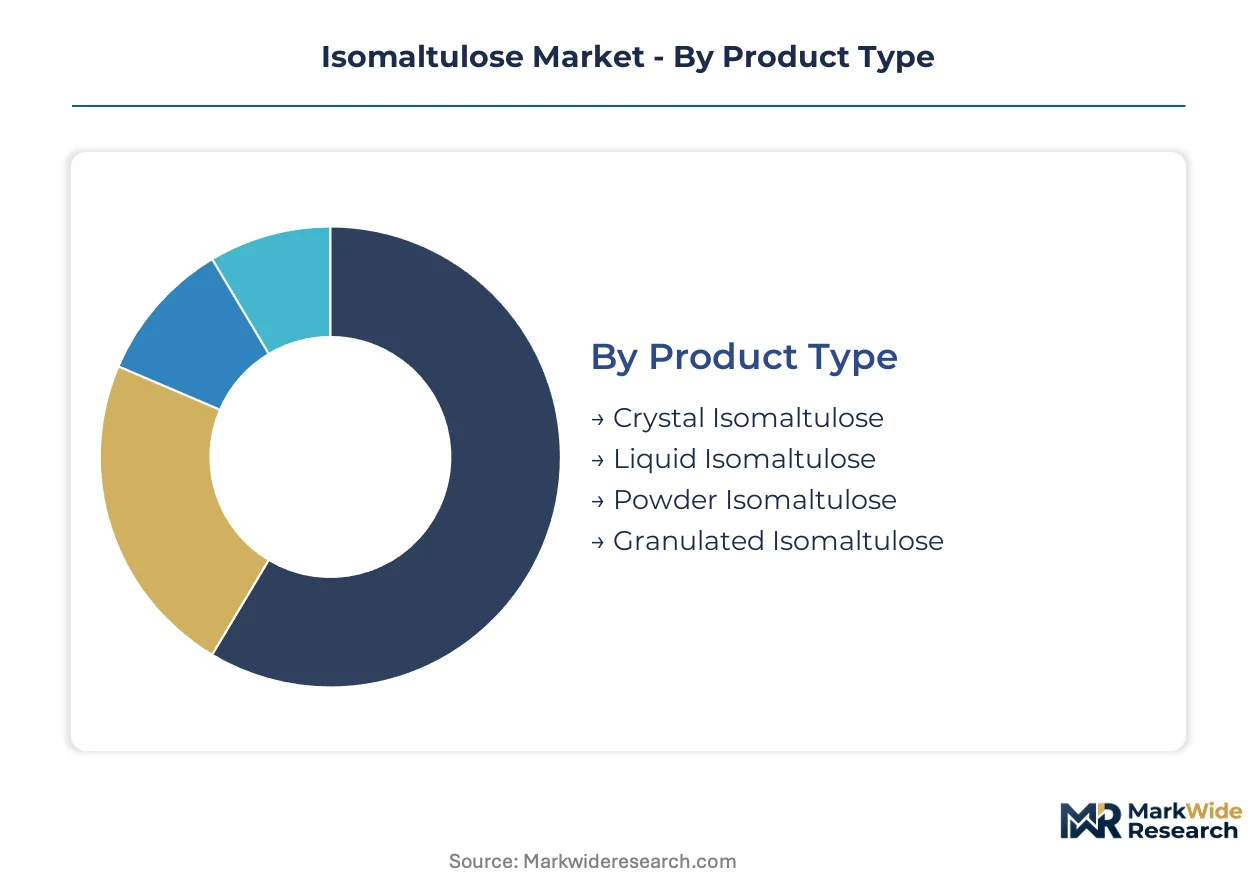
Isomaltulose formulation requirements diverge sharply across product formats, end-use applications, and procurement channels. Understanding these segment boundaries reveals where enzymatic conversion capacity concentrates and which customer types command pricing leverage.
Product Type:
Crystal formats turn inventory slowest due to confectionery production cycles, while powder grades cycle rapidly through beverage dry-mix channels.
- Crystal Isomaltulose:High-purity crystalline form with superior shelf stability and clean-label positioning in premium chocolate and candy applications. German confectionery manufacturers in the Palatinate region dominate procurement for tempered product lines requiring precise melting behavior.
- Powder Isomaltulose:Micronized particles optimized for dispersibility in protein shakes and hydration mixes. E-commerce direct-to-consumer brands in North American sports nutrition are pulling volume fastest through just-in-time fulfillment models.
- Liquid Isomaltulose:Aqueous syrup concentrate for industrial beverage formulation. German and French syrup blenders in the Rhine corridor control primary offtake for ready-to-drink applications.
- Granulated Isomaltulose:Free-flowing granules for tabletop sweetener and baking blends. Health-conscious consumer co-manufacturers in EU member states drive specification requirements.
Crystal Isomaltulose dominates installed base. Powder Isomaltulose is where expansion concentrates.
Application:
Cost tiers separate commodity bakery substitution from premium metabolic management positioning.
- Beverages:Sports drinks and functional waters requiring sustained glucose release without insulin spikes. Japanese FOSHU functional claims system demands clinical trial dossiers for blood glucose moderation labeling, raising compliance investment thresholds.
- Confectionery:Clean-label chocolates and hard candies leveraging minimal glycemic impact. Legacy equipment retrofit costs for tempering and molding operations constrain adoption among mid-tier European candy manufacturers.
- Bakery Products:Bread and pastry applications where slow carbohydrate release improves satiety signaling. German industrial bakeries along the Rhine corridor anchor volume through long-term supply contracts with Palatinate enzymatic conversion facilities.
- Dairy Products:Yogurt and flavored milk formulations targeting diabetes-friendly positioning. EFSA novel food approval pathways enable cross-border commercialization across EU member states.
Bakery Products holds the deepest volume foundation. Beverages is climbing the fastest.
End User:
Customer type determines whether procurement runs through spot markets or captive supply agreements.
- Nutritional Companies:Clinical and sports formulation specialists requiring batch-certified low-glycemic carbohydrates. These buyers are displacing traditional food manufacturers in procurement intensity through multi-year offtake agreements with enzymatic conversion specialists.
- Food Manufacturers:Established confectionery and bakery producers seeking clean-label sugar reduction. REACH chemical registration requirements at ECHA extend product launch cycles for derivative formulations lacking established regulatory affairs infrastructure.
- Dietary Supplement Providers:Capsule, tablet, and powder blenders serving fitness and wellness segments. Chinese GB standards for food additives create regulatory runway for sports beverage innovation under dual carbon policy alignment.
- Health-Conscious Consumers:Direct purchasers through e-commerce and specialty retail channels. Online retail dispersibility requirements favor powder and granulated formats with extended shelf stability.
Food Manufacturers retain the broadest installed base. Nutritional Companies is gaining share fastest.
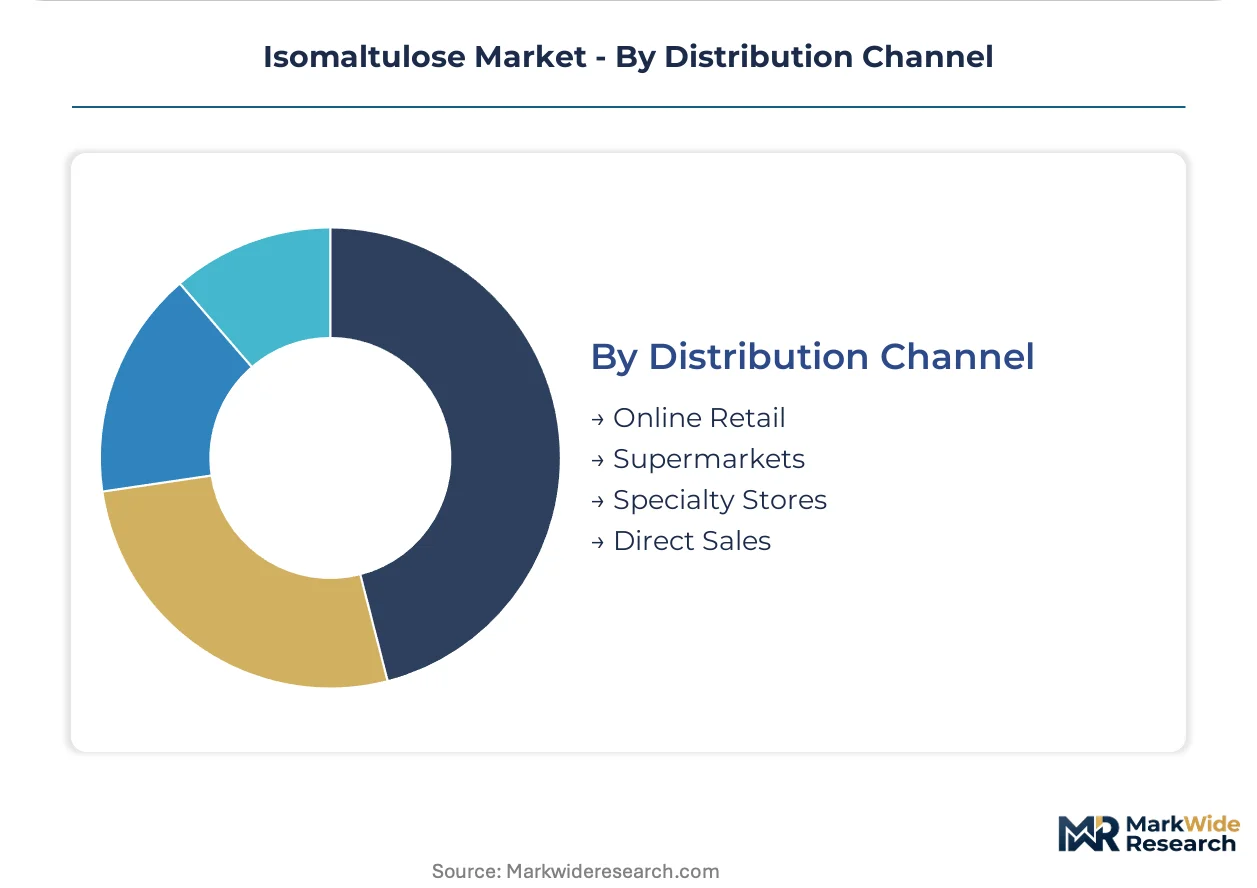
Distribution Channel:
Channel selection tracks customer scale and specification complexity.
- Direct Sales:Volume offtake agreements between enzymatic conversion specialists and large formulation houses. BENEO GmbH headquarters proximity enables just-in-time coordination for clinical nutrition manufacturers in Germany.
- Online Retail:E-commerce platforms serving health-conscious consumers and small-batch supplement blenders. Powder Isomaltulose dispersibility advantages open direct-to-consumer protein and hydration mix formats.
- Supermarkets:Mass-market tabletop sweetener and baking blend placement. Clean-label positioning competes with allulose and other rare sugar alternatives in GRAS-affirmed product lines.
- Specialty Stores:Premium confectionery and diabetes-care product curation. Japan's FOSHU functional claims system tightens evidentiary standards for in-store blood glucose moderation messaging.
Direct Sales commands the largest contract value. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food pathways anchor European access, while FDA GRAS self-affirmation and Japan's FOSHU functional claims system shape commercialization timelines in their respective jurisdictions.
Germany
Sports nutrition demand and clinical formulation procurement pull isomaltulose through enzymatic conversion capacity concentrated along the Rhine corridor. EU Green Deal sustainability-linked sourcing mandates favor enzymatic over petrochemical-derived sweetener systems in public nutrition programs. The Palatinate manufacturing complex sustains backward integration into sucrose refining and crystallization.
United States
Low-glycemic carbohydrate prioritization among athletes and fitness consumers drives pre-workout and endurance formulation demand. FDA GRAS self-affirmation pathways accelerate rare sugar alternatives through faster regulatory access than centralized approval systems. North American nutritional companies establish multi-year offtake agreements directly with enzymatic conversion specialists, displacing traditional sugar trader intermediaries.
Japan
Blood glucose moderation functional claims under FOSHU tighten evidentiary standards, requiring human clinical trial data for postprandial glycemic response reduction. METI oversight of functional food labeling raises R&D compliance costs for manufacturers seeking sports nutrition and diabetes-care positioning. Japanese contract research organizations generate jurisdiction-specific efficacy dossiers for market access.
China
GB standards for food additives and dual carbon policy goals create regulatory runway for clean-label carbohydrate innovation in sports beverages. SAMR oversight of food additive approvals imposes compositional testing burdens that favor producers with established regulatory affairs infrastructure. Domestic sports beverage manufacturers expand procurement for sustained-release carbohydrate systems.
France
Starch derivatives processing from the Lestrem hub competes with sucrose-based enzymatic conversion through alternative fermentation pathways. REACH chemical registration requirements at ECHA extend product launch cycles for derivative formulations lacking established regulatory affairs infrastructure. French syrup blenders in the Rhine corridor control primary offtake for ready-to-drink liquid isomaltulose applications.
Isomaltulose Market Competitive Environment
Specialized enzymatic conversion specialists and diversified carbohydrate ingredient conglomerates split the market between premium metabolic management positioning and commodity-scale bakery substitution. Supply-side concentration clusters in Central European manufacturing corridors, with backward integration into sucrose refining creating margin advantages for established producers. Three archetypes dominate: Palatinate-based enzymatic specialists with captive sucrose supply, French starch-derivative processors leveraging fermentation alternatives, and North American ingredient conglomerates with GRAS-affirmed rare sugar portfolios. Competitive moves center on multi-year offtake agreements securing volume allocation and continuous flow enzymatic reactor retrofits collapsing batch processing economics.
Among German enzymatic specialists, BENEO GmbH exemplifies the backward-integrated archetype with Palatinate headquarters proximity enabling just-in-time delivery coordination. Südzucker represents the diversified sugar conglomerate model anchoring Central European supply through sugar beet processing networks. Roquette occupies the starch-derivative fermentation pathway position from its Lestrem hub, competing with alternative production routes. These three entities collectively illustrate how geographic concentration of enzymatic capacity and raw material access shapes competitive positioning in metabolic management carbohydrate supply.
| Leading Market Players |
|---|
| Matsutani Chemical Industry |
| Frusano GmbH |
| BENEO GmbH |
| Roquette |
| Ingredion |
| Cargill, Inc. |
| Mitsui Sugar Co. Ltd. |
| Tate & Lyle |
| Südzucker |
| Others |
Value Chain & Pricing Dynamics
Rhine corridor freight economics compress delivered cost spreads between Palatinate enzymatic conversion facilities and downstream formulation hubs, concentrating pricing power with backward-integrated producers while forcing spot-market buyers into premium tiers for volume security.
Pricing Analysis
Geographic price spreads widen substantially between contract-based long-term offtake agreements and spot-market procurement, with German enzymatic specialists commanding premiums through just-in-time delivery coordination. Three-tier pricing structure across premium, standard, and economy levels separates batch-certified pharmaceutical-grade crystal from commodity bakery powder and liquid syrup concentrates. Cost compression in standard-tier powder grades is intensifying because allulose substitution in beverage formulations forces isomaltulose producers to absorb margin erosion. Nutritional companies with multi-year agreements exhibit least price sensitivity, while mid-tier confectionery manufacturers retrofitting legacy equipment face acute procurement cost pressure.
Supply Chain Analysis
Contract manufacturing concentration rests with BENEO GmbH's Palatinate complex, Südzucker's Central European beet processing network, and Roquette's Lestrem starch derivatives hub. Geographic supply concentrates in Germany, France, and Belgium, with enzymatic conversion capacity clustering along Rhine logistics corridors. Raw material dependencies center on sucrose from beet and cane sources, Protaminobacter rubrum-derived isomaltulose synthase enzymes, and crystallization-grade processing chemicals. Single-source vulnerability pervades the Palatinate manufacturing complex, where any disruption cascades through global clinical nutrition supply chains. Distribution runs through direct sales agreements with large formulation houses, supplemented by e-commerce channels for powder-grade dry-mix products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biocatalysis expertise for Protaminobacter rubrum strain optimization is concentrated in German and Dutch research clusters, creating acquisition premiums for producers with captive enzyme engineering capabilities and regulatory affairs infrastructure.
For Market Incumbents: Pre-empt allulose substitution in beverage formulations by accelerating continuous flow enzymatic reactor deployments that collapse batch processing economics. Secure backward integration into sucrose refining through long-term beet supply agreements with Central European agricultural cooperatives, insulating margin pools from commodity price volatility while EFSA novel food pathways compress competitor access timelines. For New Entrants and Emerging Players: Pursue China's sports beverage white space where GB standards and dual carbon policy goals create regulatory runway for clean-label carbohydrate innovation. Target dietary supplement providers in North American e-commerce channels, where powder isomaltulose dispersibility advantages enable direct-to-consumer protein and hydration mix formats without legacy equipment retrofit burdens. For Investors and Strategic Acquirers: Enzymatic conversion specialists with established EFSA regulatory dossiers and REACH compliance infrastructure represent priority acquisition targets. Long-term viability hinges on sustained glycemic index labeling mandates and sugar reduction targets across EU member states. Monitor Japan's FOSHU evidentiary standard tightening as inflection indicator for R&D compliance cost escalation that favors incumbent scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Enzymatic Reactor Deployment | Immobilized enzyme fixed-bed systems at Palatinate facilities cut conversion cycles from 48 hours to 6 hours. |
| Backward Integration into Sucrose Refining | Captive beet sugar processing insulates BENEO GmbH and Südzucker from raw material price volatility. |
| EFSA Novel Food Dossier Investment | Centralized approval pathways reduce member-state fragmentation and accelerate cross-border commercialization. |
| China GB Standards Compliance Program | SAMR-aligned compositional testing opens sports beverage formulation slots under dual carbon policy alignment. |
| Japan FOSHU Clinical Trial Partnership | METI-mandated efficacy data generation secures blood glucose moderation functional claims for metabolic management positioning. |
Study Parameters
The analysis maps crystal, powder, liquid, and granulated isomaltulose formats, each validated through formulation scientists at nutritional companies, procurement leads at enzymatic conversion specialists, regulatory affairs directors navigating EFSA and FDA pathways, and plant managers at Rhine corridor manufacturing complexes. Primary interview insights triangulate against secondary sources including EFSA novel food opinions, FDA GRAS self-affirmation notices, REACH registration dossiers at ECHA, and customs trade data for sucrose-derived carbohydrate flows. Bottom-up segment sizing and top-down macroeconomic reconciliation anchor value projections.
Assumption-sets held regulatory approval timelines and enzyme engineering yield curves fixed while varying sucrose input price scenarios and sports nutrition demand elasticity parameters across the projection horizon. Segmentation dimensions span product type, application vertical, end-user procurement archetype, and distribution channel intensity. CAGRs derive from iterative convergence of demand-side adoption curves and supply-side capacity expansion schedules, with continuous enzymatic conversion technology maturation and FOSHU evidentiary standard evolution as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in eurozone agricultural subsidy regimes, energy costs affecting enzymatic processing economics, or Chinese carbon policy enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about EFSA streamlining continuity and FDA GRAS pathway stability. Quarterly review of sucrose futures pricing, novel food approval queue lengths, and Japan METI functional claims guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sucrose Esters Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Aspartame Market
Sweeteners
Methyl Glucose Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Sour Sugar Market
Sweeteners
Compressible Sugar Market
Sweeteners
North America Food Sweetener Market