
 Digital TV Market | 2026-2036
Digital TV Market Size, Share, and Industry Trends Forecast 2026-2036
Digital TV Market Analysis
Hospitality end-use is shifting from passive in-room displays to interactive smart TV platforms that integrate property management systems and guest streaming services. Samsung Electronics leverages its vertical display manufacturing to dominate premium hospitality contracts across North America and Asia. LG Electronics anchors its position through OLED panel specialization, while TCL Technology competes aggressively on cost-engineered LED volumes in emerging markets.
Digital TV encompasses display devices that receive, decode, and render broadcast or internet-protocol video signals, typically featuring liquid-crystal or organic light-emitting diode panels with resolutions from 1080p to 8K and integrated system-on-chip processors for smart functionality. The primary commercial purpose is to deliver audiovisual content to residential and institutional viewers through terrestrial, satellite, cable, or broadband networks. Smart TV product types now command the dominant margin pool as operating-system licensing and advertising revenue supplement hardware economics, while OLED technology leads in premium residential segments and IPTV delivery infrastructure is displacing traditional cable distribution fastest in urban markets. Streaming content types have overtaken live broadcast in subscriber hours across multiple geographies.
The FCC governs digital tuner mandates and spectrum allocation in the United States, while the EU applies Ecodesign and Energy Label regulations to television efficiency standards, and China's SAMR enforces national GB standards for electromagnetic compatibility and display performance. These frameworks collectively elevate compliance costs for non-compliant manufacturers while accelerating replacement demand where older sets fail new efficiency or connectivity requirements. Stakeholders must monitor regulatory divergence between energy-efficiency regimes and data-privacy rules embedded in smart TV operating systems.
Market Dynamics
IPTV infrastructure is decentralizing content delivery away from traditional cable operators, compressing distribution margins while forcing hardware manufacturers to integrate broadband-ready chipsets as standard equipment.
Growth Catalysts
- FCC Spectrum Repacking:Mandated tuner upgrades in the United States are accelerating replacement cycles for ATSC 3.0-compatible sets.
- EU Ecodesign Directives:Stricter standby power limits and material efficiency rules are phasing out older LCD inventories across member states.
- Hospitality Smart Integration:Hotels in China are procuring displays with embedded property management interfaces and guest streaming portals.
Market Restraints
- Panel Supply Concentration:OLED substrate production clusters heavily in South Korea, creating vulnerability to single-source disruption.
- Raw Material Volatility:Indium tin oxide and rare earth phosphor prices swing with mining output from Chinese processing facilities.
- Terrestrial Broadcast Decline:Younger demographics bypass tuner hardware entirely, reducing addressable market for integrated digital receivers.
Strategic Opportunities
- Rural Broadband Expansion:India's BharatNet fiber rollout creates first-time smart TV demand in previously unserved districts.
- Healthcare Display Convergence:Telemedicine platforms in Brazil are repurposing commercial 4K panels for remote diagnostic imaging.
- EU Right-to-Repair Mandates:Modular component designs open aftermarket service revenue streams previously captured by OEMs.
Industry Challenges
- ATSC 3.0 Certification Bottlenecks:Testing backlog at FCC-authorized laboratories delays product launches by six to nine months.
- Legacy Hotel Infrastructure:Coaxial distribution systems in older properties resist IP-based retrofit without full rewiring investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital TV Market |
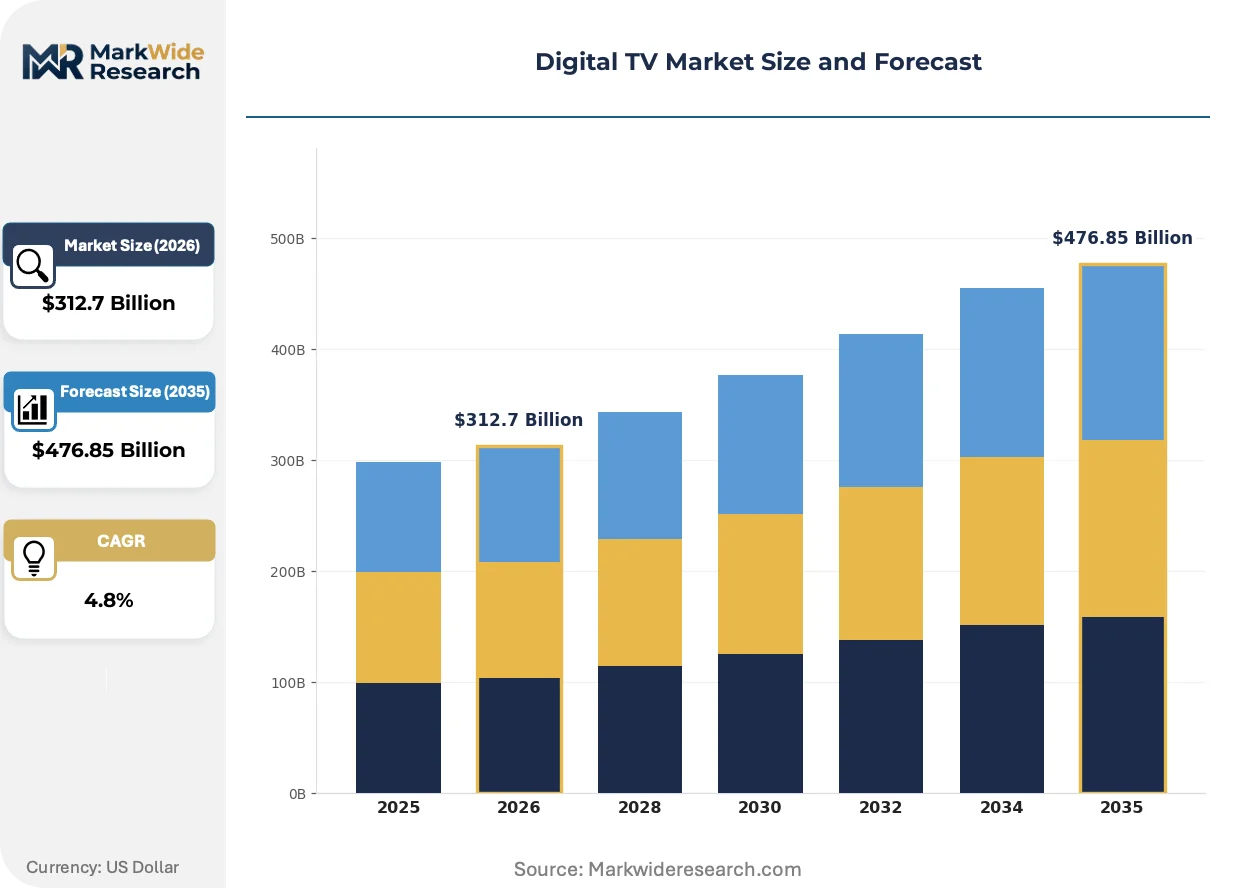
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TV, LED TV, OLED TV, QLED TV Technology: IPTV, Satellite, Cable, Streaming End User: Residential, Commercial, Hospitality, Educational Content Type: Live Broadcast, On-Demand, Subscription, Free-to-Air |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, TCL Technology, Hisense Group, Panasonic Corporation, Philips, Xiaomi Corporation, Roku, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital TV Market Emerging Trajectories
Edge computing architectures are redistributing processing load from centralized servers to display-embedded chipsets, enabling real-time personalization without cloud latency. This shift compresses the traditional set-top box supply chain while elevating system-on-chip specifications as the primary competitive battleground.
MicroLED backlighting is decentralizing zone-based dimming control to individual diode clusters, delivering contrast ratios previously limited to emissive OLED panels. Luxury residential installers in Dubai and Singapore specify these modules for dedicated home cinema environments. The technology compresses premium pricing power away from Korean OLED specialists toward Chinese LED assembly houses mastering chip-transfer yields.
REACH substance restrictions are forcing reformulation of flame retardants in plastic chassis and solder alloys in power supply boards. German and French customs authorities now detain shipments lacking updated SCIP database entries for SVHC content. Manufacturers with pre-certified component libraries capture shelf space faster than competitors awaiting third-party laboratory retesting.
Direct-to-consumer subscription bundling is collapsing the traditional retail channel for mid-tier sets. Walmart and Best Buy floor space for non-exclusive brands shrinks as Roku, Amazon, and Google license their operating systems directly to Shenzhen assemblers. This pattern concentrates most visibly in North American markets where streaming hours exceeded broadcast consumption.
Digital TV Market Segmentation
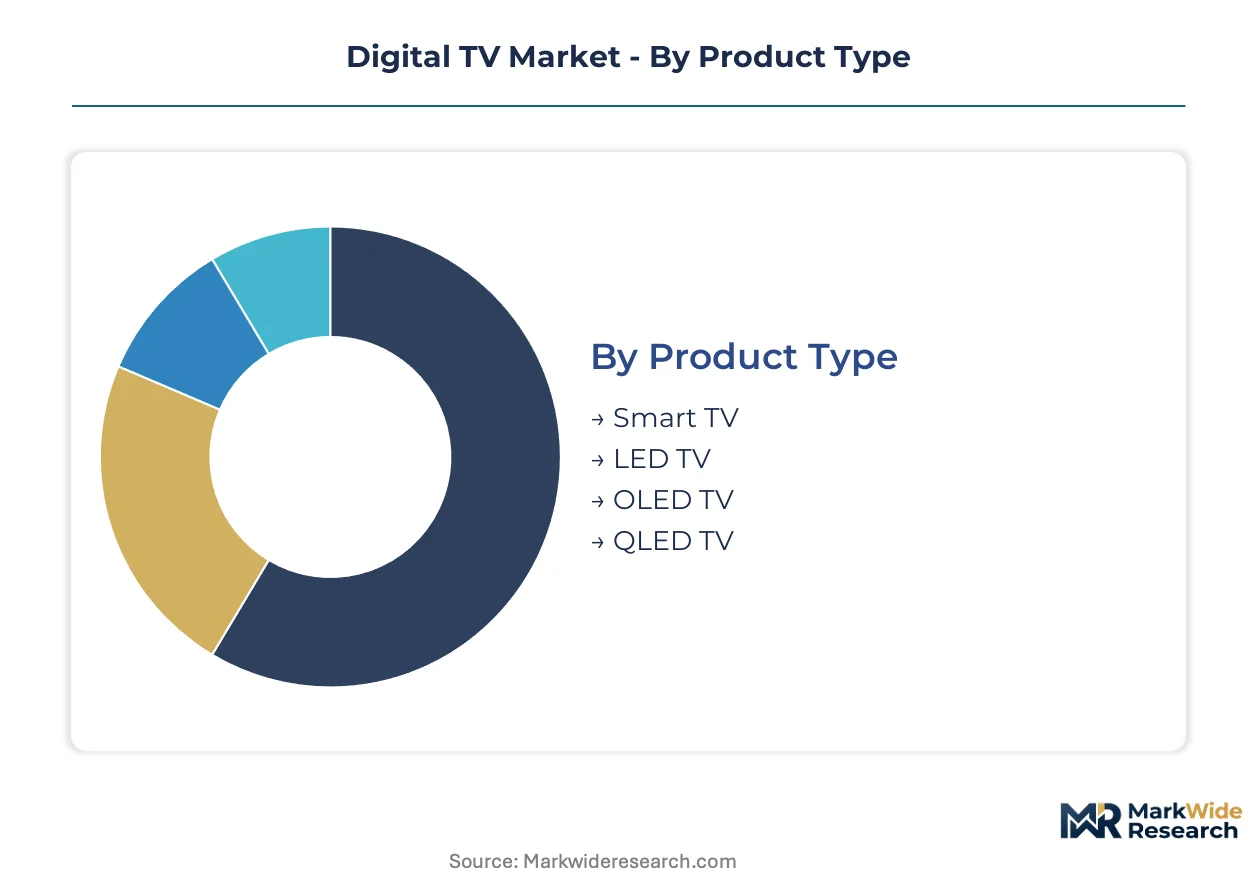
Digital TV procurement patterns diverge sharply across integration contexts, from standalone residential purchases to embedded hospitality systems requiring property management interfaces. Understanding these segment boundaries clarifies where hardware margins concentrate versus where software and service layers capture value.
Product Type:
Integration depth separates displays that operate as independent computing platforms from those functioning as dumb panels within larger systems.
- Smart TV:System-on-chip architectures embed streaming applications, voice assistants, and advertising platforms directly into display hardware. Hotels in China now specify these units with locked-down enterprise operating systems that integrate guest check-in data and streaming service authentication. Volume placements concentrate in this segment; the faster expansion belongs to hospitality-optimized configurations with remote management toolkits.
- LED TV:Conventional liquid-crystal panels with edge-lit or direct backlighting serve as cost-optimized displays where external set-top boxes handle intelligence. India's BharatNet fiber expansion drives first-time purchases in rural districts where broadband infrastructure arrives before smart TV penetration. This segment dominates absolute unit shipments across emerging markets.
- OLED TV:Organic light-emitting diode panels deliver per-pixel illumination without backlight layers, enabling form factors under 4mm depth. South Korean substrate manufacturers control critical supply stages.
- QLED TV:Quantum-dot-enhanced LED systems filter blue backlight emission through nanocrystal layers for expanded color gamut. Samsung Electronics anchors production volume through captive quantum-dot film manufacturing.
Shipments stratify across cost tiers rather than technology generations alone.
Technology:
Delivery infrastructure determines whether display hardware requires integrated tuners, broadband chipsets, or hybrid architectures.
- IPTV:Internet-protocol television streams content through managed broadband networks with quality-of-service guarantees, common in European fiber deployments. France and Germany regulate these services under converged media frameworks that differ from broadcast licensing. Regulatory divergence between telecom and broadcast regimes complicates cross-border service deployment.
- Streaming:Over-the-top delivery bypasses managed networks entirely, relying on best-effort internet connectivity and application-layer content negotiation. Younger demographics in the United States now consume more hours through these platforms than through all linear sources combined. This segment is gaining share fastest as advertising-supported tiers expand addressable markets.
- Satellite:Direct-to-home satellite transmission reaches geographies where terrestrial infrastructure remains uneconomical, including remote Australian cattle stations and Canadian northern territories.
- Cable:Hybrid fiber-coaxial networks persist in legacy infrastructure zones, though subscriber counts decline in markets with viable broadband alternatives.
Distribution economics favor streaming where fiber density permits; satellite retains dominance where topography obstructs terrestrial buildout.
End User:
Procurement authority separates consumer-driven replacement cycles from institutional purchasing governed by total-cost-of-ownership models.
- Residential:Individual households select displays based on room size, content preferences, and aesthetic integration with interior design. Replacement cycles stretch toward seven years as panel reliability improves and 4K resolution saturates perceived quality thresholds.
- Hospitality:Hotel operators specify displays with centralized management platforms, guest streaming authentication, and anti-theft mounting hardware. China's mid-scale hotel chains now mandate 55-inch minimum screen sizes with embedded property management system interfaces. This segment commands premium pricing through software integration requirements.
- Commercial:Corporate environments deploy displays for digital signage, video conferencing, and lobby information systems, often prioritizing brightness and durability over consumer-oriented features.
- Educational:Schools and universities procure interactive flat panels with touch overlay and collaborative software, distinct from passive television viewing use cases.
Institutional contracts concentrate procurement volume; residential replacement cycles determine baseline manufacturing scale.
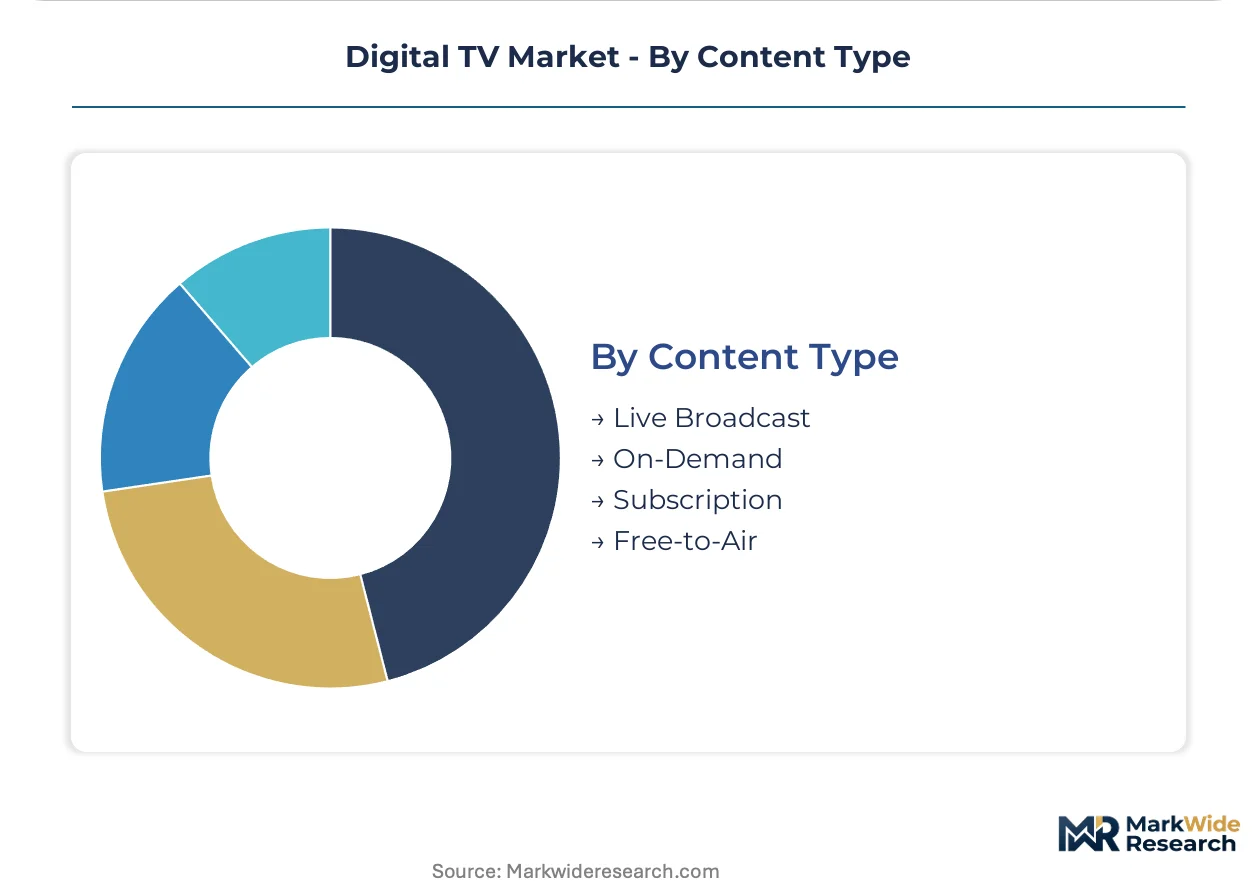
Content Type:
Monetization architecture separates advertising-supported, subscription-funded, and publicly financed content ecosystems with distinct hardware implications.
- Subscription:Recurring revenue models fund original content production and exclusive licensing arrangements, with platforms investing in application performance across device ecosystems. Netflix and Disney+ certification programs influence smart TV chipset selection by manufacturers seeking preferred placement.
- On-Demand:Transactional and library-based viewing without live linear component, common in airline entertainment systems and hotel guest room platforms. Brazil's telemedicine initiatives repurpose commercial 4K panels for diagnostic imaging applications within this content framework. This segment is expanding most quickly as healthcare and enterprise use cases proliferate.
- Live Broadcast:Scheduled linear programming with real-time distribution, still dominant for sports and election coverage despite aggregate hour declines.
- Free-to-Air:Advertising-supported terrestrial transmission requiring ATSC 3.0 or DVB-T2 tuner hardware, mandated by FCC repacking timelines in the United States.
Subscription services capture revenue concentration; on-demand architectures enable the steepest expansion trajectory as vertical applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of display panels while the United States and Europe absorb premium-tier hardware. South Korea controls OLED substrate production. India represents the fastest-expanding consumption base as fiber infrastructure reaches rural districts.
United States
FCC spectrum repacking mandates ATSC 3.0 tuner compatibility for new devices, accelerating replacement cycles. The Infrastructure Investment and Jobs Act funds rural broadband expansion that enables streaming-first households. Austin and Dallas host engineering centers where semiconductor firms design broadband-ready chipsets for smart TV integration.
China
Domestic panel production from BOE and CSOT reduces import dependency for display components. SAMR enforces GB standards for electromagnetic compatibility and energy efficiency. Shenzhen and Guangzhou anchor assembly operations where streaming platform integration is built directly into hardware firmware.
South Korea
OLED substrate manufacturing concentrates near Seoul and Gumi, creating single-source vulnerability for premium panel supply. METI-coordinated technology roadmaps in neighboring Japan influence regional R&D alignment. Suwon and Gumi host facilities where quantum-dot film deposition and organic vapor phase deposition processes operate at scale.
Germany
EU Ecodesign directives phase out inefficient LCD inventories while REACH substance restrictions reformulate flame retardants in chassis materials. Berlin and Munich host certification laboratories where SCIP database compliance is verified before customs release. German retailers now prioritize pre-certified component libraries to avoid detention delays.
India
BharatNet fiber rollout creates first-time smart TV demand in previously unserved rural districts. BIS certification requirements for electronic goods standardize safety and performance benchmarks. Noida and Chennai host assembly operations where cost-engineered LED volumes target price-sensitive consumers entering the connected display market.
Digital TV Market Vendor Landscape
Top-tier vendors anchor premium display manufacturing, while mid-tier fabricators compete on cost-engineered volumes. The market structures around three tiers: integrated panel-and-device manufacturers, operating-system licensors, and contract assemblers. Two strategic archetypes dominate—Korean conglomerates with captive OLED substrate production, and Chinese scale players leveraging domestic supply chains. Competitive moves concentrate on vertical integration into panel manufacturing and direct-to-consumer distribution bypassing traditional retail.
Among Korean electronics conglomerates, Samsung Electronics and LG Electronics exemplify the integrated-manufacturer archetype with captive display production. TCL Technology occupies a position within the Chinese cost-optimization tier, leveraging domestic panel supply chains. These three entities represent distinct competitive vectors: technology specialization, manufacturing scale, and platform integration.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| TCL Technology |
| Hisense Group |
| Panasonic Corporation |
| Philips |
| Xiaomi Corporation |
| Roku, Inc. |
| Others |
Supply Flow & Price Mechanics
EU REACH substance restrictions on flame retardants and solder alloys gate qualified supply access and premium-tier pricing power for manufacturers seeking German and French customs clearance without detention delays.
Pricing Analysis
Margin tightening in mid-tier LED volumes reflects Shenzhen assembly houses competing aggressively on cost-engineered chipsets. Three-tier pricing structure across premium, standard, and economy levels separates OLED specialists from quantum-dot-enhanced LED fabricators from basic edge-lit LCD assemblers. Certification investment for ATSC 3.0 and Ecodesign compliance commands premium positioning. Hospitality procurement with embedded property management interfaces shows lowest price sensitivity; rural Indian first-time buyers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with South Korean OLED substrate manufacturers near Seoul and Gumi. Panel production concentrates in China, South Korea, and Taiwan; assembly operations cluster in Shenzhen, Guangzhou, and Noida. Indium tin oxide and rare earth phosphor feed from Chinese processing facilities. Tariff exposure on display components threatens margin stability. Distribution runs through direct-to-consumer streaming platform licensing and traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED substrate production capacity constraints prop pricing power for integrated Korean manufacturers while limiting supply expansion for premium-tier market penetration.
For Market Incumbents: Anchor market position through captive OLED vapor phase deposition capacity and quantum-dot film manufacturing scale. Defend against Chinese LED assembly cost pressure by deepening hospitality software integration and property management system certification. Prioritize REACH pre-certified component libraries to accelerate European customs clearance. For New Entrants and Emerging Players: Begin with rural broadband expansion corridors in India where BharatNet fiber creates first-time smart TV demand without entrenched brand loyalty. Target cost-engineered LED volumes for price-sensitive consumers entering connected display markets. Pursue direct-to-consumer streaming platform bundling partnerships to bypass traditional retail slotting fees. For Investors and Strategic Acquirers: ATSC 3.0 certification bottlenecks at FCC-authorized laboratories are the leading indicator that testing capacity scarcity will constrain product launch velocity and consolidate share among pre-qualified manufacturers. Long-term viability favors vertically integrated panel-and-device producers with captive substrate supply. Watch for hospitality procurement mandates specifying embedded enterprise operating systems as inflection signal for software-layer value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OLED Substrate Production | Samsung Electronics and LG Electronics secure supply autonomy against Chinese LED cost pressure through captive organic vapor phase deposition facilities. |
| Hospitality Software Platform Certification | Enterprise operating system integration with property management interfaces commands premium procurement contracts from Chinese mid-scale hotel chains. |
| REACH Pre-Certification Investment | SCIP database compliance ahead of German and French customs enforcement accelerates shelf access versus competitors awaiting third-party laboratory retesting. |
| Rural Distribution Partnership | BharatNet fiber corridor alignment captures first-time smart TV demand in previously unserved Indian districts before national brands establish presence. |
| Streaming Platform Direct Licensing | Roku, Amazon, and Google operating system partnerships enable Shenzhen assemblers to collapse traditional retail channel margins in North American markets. |
Methodological Framework
SEC 10-K filings, customs and trade databases, and EIA energy consumption data formed the secondary backbone for supply chain and pricing intelligence. Primary interviews with display panel procurement managers, hospitality technology directors, semiconductor platform engineers, and retail category buyers validated secondary findings. Bottom-up shipment data from panel manufacturers combined with top-down consumer electronics spending patterns enabled triangulation across the analysis window.
Bottom-up modeling aggregated unit shipments by product type, technology delivery infrastructure, and end-user procurement context. Top-down validation cross-checked against regional household formation rates, broadband penetration curves, and hospitality construction pipelines. CAGRs derived from regression analysis of historical replacement cycles and regulatory mandate timing. Forecast inputs incorporated FCC spectrum repacking schedules and EU Ecodesign phase-out timelines.
Underlying measurement precision varies by segment; streaming technology and hospitality end-use carry tighter precision than satellite distribution and educational procurement due to disclosure transparency. Forecasts reflect assumptions about regulatory enforcement consistency and raw material price stability. Panel supply disruption, tariff regime shifts, or accelerated terrestrial broadcast decline could revise trajectory materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cloud TV Market
Television
Cloud Television (TV) Market
Television
Television Broadcasting Services Market
Television
Television and Set Top Box Market
Television
Broadcasting and Cable TV Market
Television
HDTV Market
Television
Mobile TV Market
Television
Pay TV Market
Television
Print Newspapers and Magazines Market
Television
Global Broadcast Equipment Market
Television
Cable Television Networks Market
Television
Television Advertising Market
Television
TV Advertising Market
Television
Pay TV Operator Market
Television
Holographic TV Market
Television
Curved Television Market