
 Television Broadcasting Services Market | 2026-2036
Television Broadcasting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Television Broadcasting Services Market Outlook
Specialized broadcast engineering talent is unwinding capacity constraints across the television broadcasting services ecosystem as legacy transmitter maintenance expertise retires faster than IP-native technicians enter the workforce. Comcast Corporation leverages its hybrid cable-IP infrastructure to sustain subscriber retention in fragmented viewing markets. Warner Bros. Discovery anchors its competitive stance through deep content libraries that span linear and streaming formats. The Walt Disney Company dominates premium sports rights negotiations, using ESPN's brand strength to control distribution leverage across multiple delivery modes.
Television broadcasting services encompass the acquisition, production, aggregation, and distribution of audiovisual content through terrestrial radio-frequency transmission, satellite uplink, coaxial cable plant, or packet-switched internet protocol networks operating at bit rates from 2 Mbps for standard-definition streams to 50 Mbps for 4K ultra-high-definition broadcasts. These services serve advertisers, content licensors, and end consumers by aggregating attention into scheduled and on-demand programming inventories. Live TV delivery through satellite and cable infrastructure still occupies the largest revenue pool, though internet protocol delivery is accelerating fastest as fiber-to-the-home penetration deepens. Consumer end users generate the dominant share of subscription and advertising revenue, while businesses and governmental bodies represent higher-margin specialized segments with stricter service-level requirements.
The FCC governs spectrum allocation and ownership concentration limits in the United States, directly shaping which broadcasters can operate in specific designated market areas and how many stations a single entity may control. EMA and national regulators across Europe enforce the Audiovisual Media Services Directive, mandating domestic content quotas and advertising limits that alter programming economics for cross-border operators. Stakeholders must monitor spectrum auction timelines, net neutrality rulings, and content localization mandates to anticipate which delivery modes and geographic markets will face regulatory pressure or unlock expansion permissions.
Market Dynamics
IP-native infrastructure is displacing legacy terrestrial transmission systems as broadcasters retool for hybrid delivery models, forcing capital reallocation from RF transmitters to cloud playout and edge caching networks.
Growth Catalysts
- Rural broadband expansion:India's BharatNet initiative unlocks subscriber bases in previously underserved districts, enabling regional broadcasters to extend IP delivery into tier-3 and tier-4 markets.
- ATSC 3.0 deployment:The next-generation broadcast standard enables targeted advertising and enhanced emergency alerts, incentivizing US station groups to upgrade transmission infrastructure.
- Cloud playout adoption:Educational institutions accelerate migration from satellite downlinks to software-defined streaming workflows, reducing capital intensity for content distribution.
Market Restraints
- RF engineer attrition:Specialized transmitter maintenance expertise retires faster than IP-native technicians enter the workforce, constraining legacy system upkeep.
- Spectrum auction costs:FCC-mandated reallocation proceedings force broadcasters to bid for reduced frequency assignments or relocate facilities, elevating operational overhead.
- Streaming substitution:Direct-to-consumer platforms capture viewing hours from scheduled linear programming, compressing advertising inventory values for traditional broadcasters.
Strategic Opportunities
- Regional language content:India's rural broadband expansion enables localized programming for non-Hindi markets, creating first-mover advantages for vernacular broadcasters.
- 5G broadcast multicast:Convergence of cellular and broadcast technologies permits spectrum-efficient live event delivery to mobile devices without consuming unicast capacity.
- Production tax incentives:The IRA's domestic content provisions incentivize US-based studio construction, lowering effective production costs for scripted programming.
Industry Challenges
- Hybrid workflow integration:Broadcasters struggle to synchronize SDI-based production suites with IP routing fabrics, delaying facility modernization timelines.
- Skills bifurcation:Operations teams require simultaneous fluency in RF transmission physics and cloud orchestration, lengthening training cycles and elevating labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Television Broadcasting Services Market |
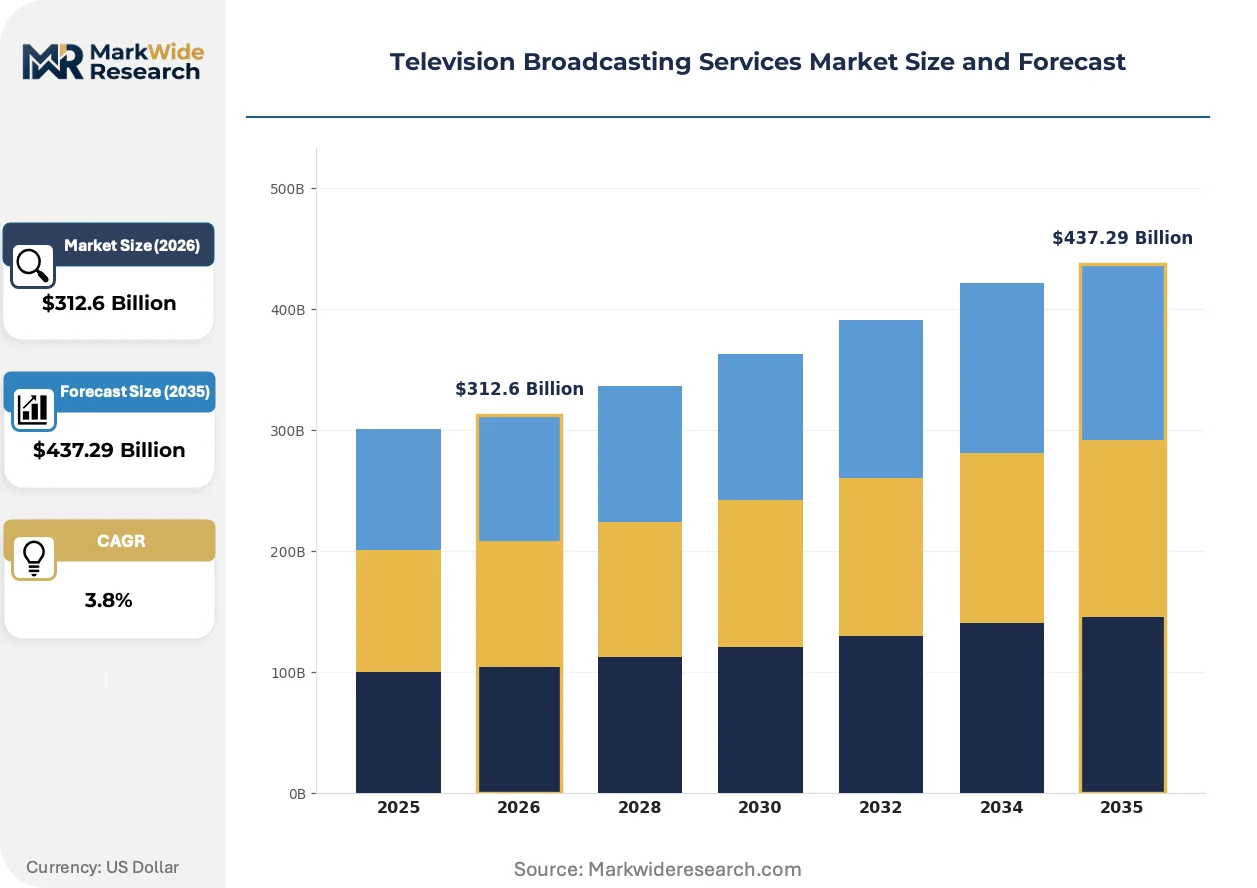
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $437.29 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Live TV, On-Demand Streaming, Pay-Per-View, Network Broadcasting Delivery Mode: Satellite, Cable, Internet Protocol, Terrestrial End User: Consumers, Businesses, Educational Institutions, Governmental Bodies Content Type: News, Sports, Entertainment, Educational |
| Companies Covered | Comcast Corporation, The Walt Disney Company, Warner Bros. Discovery, Paramount Global, AT&T Inc., Fox Corporation, British Broadcasting Corporation, Discovery, Inc., Vivendi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Television Broadcasting Services Market Strategic Shifts
Compression algorithms and edge computing architectures are redistributing processing loads across the broadcast chain, collapsing latency gaps between live production and consumer delivery.
High-efficiency video coding (HEVC) reduces bandwidth requirements for 4K ultra-high-definition streams by approximately fifty percent relative to AVC predecessors. Regional broadcasters in India adopt HEVC encoders aggressively as fiber-to-the-home penetration deepens in metropolitan clusters. The codec transition is miniaturizing headroom requirements for satellite uplink capacity, enabling transponder cost reductions.
The FCC's spectrum repack mandates continue compressing UHF channel assignments through auction mechanisms and relocation deadlines. US station groups face accelerated transmitter replacement cycles and antenna reconfiguration costs. Broadcast engineers respond by consolidating master control operations into centralized hubs serving multiple designated market areas.
Subscription fatigue among streaming households is rotating viewing hours back toward ad-supported linear and free ad-supported streaming television (FAST) channels. Broadcasters repurpose library content into FAST-optimized programming blocks distributed through connected TV platforms. This behavioral shift is most pronounced in North American markets where streaming subscription counts peaked in 2022-2023.
Television Broadcasting Services Market Segmentation
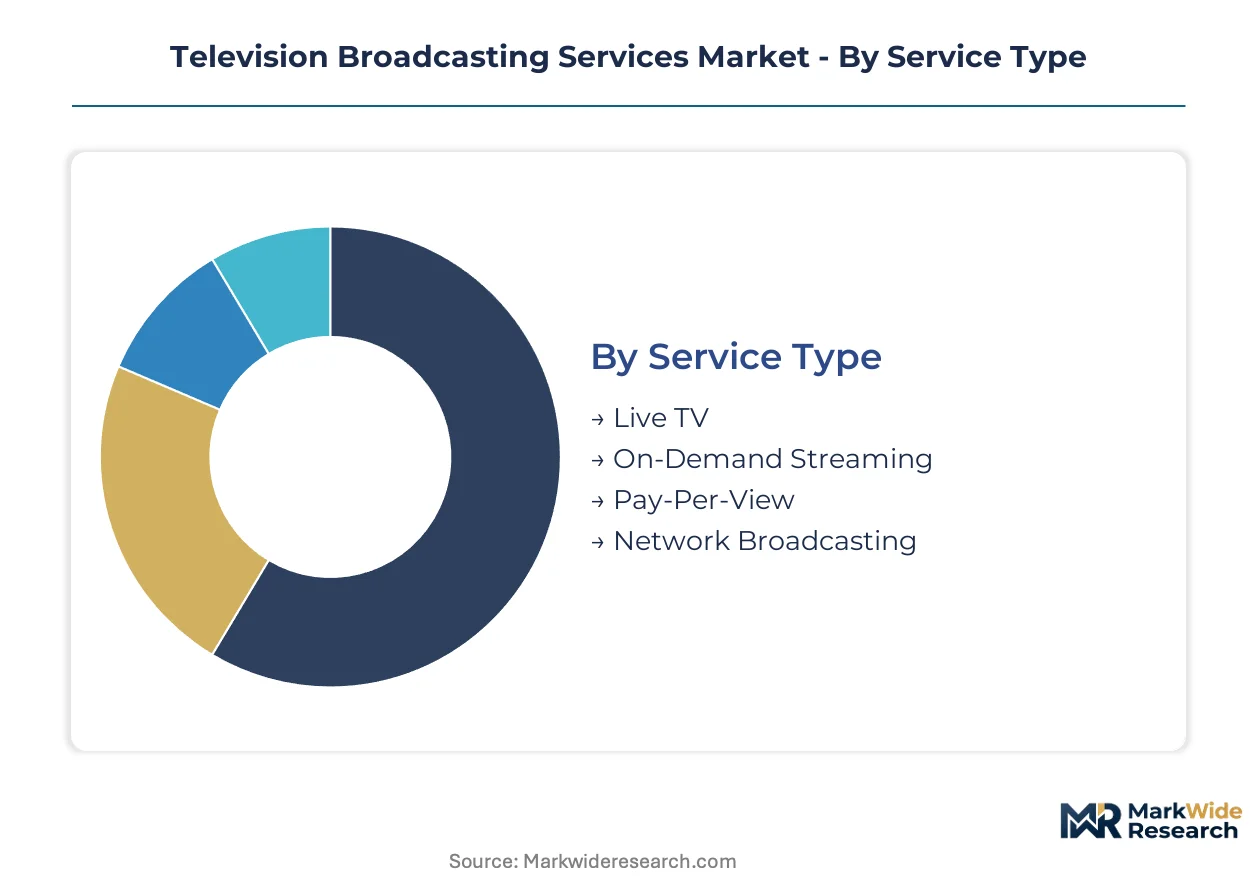
Television broadcasting services fragment across multiple dimensions that determine infrastructure investment priorities and revenue model selection. Each segmentation axis reveals distinct margin profiles and capital intensity requirements that shape competitive positioning.
Service Type:
Live TV commands satellite and cable infrastructure for synchronous delivery, while on-demand formats exploit internet protocol networks with asynchronous caching architectures.
- Live TV:Synchronous transmission requires dedicated satellite transponder capacity or fiber backhaul with sub-five-second latency tolerances. India's rural broadband expansion drives demand concentration in regional sports and election coverage, where ad inventory commands premium pricing.
- On-Demand Streaming:Asynchronous delivery through cloud playout and edge caching enables personalized advertising insertion. Educational institutions in North America accelerate migration from satellite downlinks to software-defined workflows, reducing capital intensity.
- Pay-Per-View:Transactional access model for premium live events with conditional access systems and dynamic pricing engines.
- Network Broadcasting:Scheduled programming distributed through affiliate relationships with retransmission consent negotiations.
Live TV dominates installed base across terrestrial and satellite footprints. On-Demand Streaming is where expansion concentrates as fiber-to-the-home penetration deepens.
Delivery Mode:
Cost tiers separate capital-heavy transmission infrastructure from variable-cost packet networks, with hybrid deployments emerging as the dominant operational model.
- Satellite:Geostationary transponder leases provide nationwide coverage with deterministic latency for live events. Broadcasters consolidate master control operations into centralized hubs serving multiple designated market areas to offset RF engineer attrition costs.
- Cable:Hybrid fiber-coaxial plant delivers linear bundles with dedicated spectrum for broadcast basic tiers. Comcast Corporation sustains subscriber retention through DOCSIS 4.0 upgrades in fragmented viewing markets.
- Internet Protocol:Packet-switched delivery at 2-50 Mbps enables 4K ultra-high-definition with HEVC compression. Regional broadcasters in India adopt IP-native infrastructure aggressively as BharatNet unlocks tier-3 and tier-4 markets.
- Terrestrial:ATSC 3.0 deployment in the United States enables targeted advertising and enhanced emergency alerts, incentivizing station groups to upgrade transmission infrastructure despite spectrum auction cost pressures.
Satellite and Cable dominate installed base in revenue terms. Internet Protocol is where expansion concentrates with the steepest trajectory.
End User:
Customer type determines service-level requirements, with governmental and educational segments demanding higher reliability at corresponding margin premiums.
- Consumers:Subscription and advertising revenue generator with price sensitivity varying by household income tier. Subscription fatigue in North American markets rotates viewing hours back toward ad-supported linear and FAST channels.
- Businesses:Corporate communications and hospitality verticals require dedicated channels with strict uptime guarantees.
- Educational Institutions:K-12 and university systems accelerate streaming adoption for distance learning, migrating from satellite downlinks to cloud playout. TRAI regulations in India shape content licensing frameworks for educational broadcasters.
- Governmental Bodies:Emergency alert systems and public information networks mandate hardened infrastructure with failover redundancy. FCC spectrum reallocation policies directly impact terrestrial broadcast infrastructure requirements for public safety applications.
Consumers dominate installed base by volume. Educational Institutions is where expansion concentrates as remote learning normalizes.
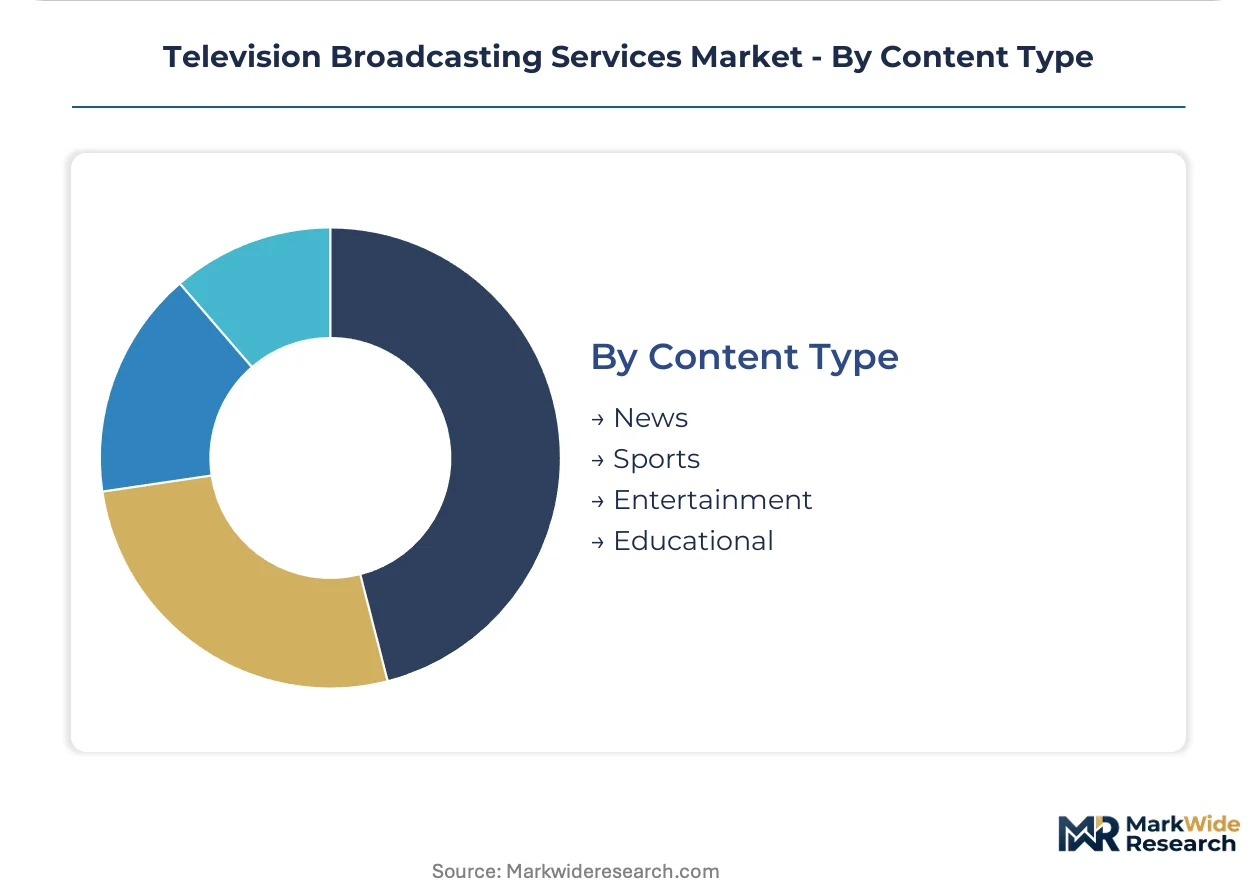
Content Type:
Application-specific production economics vary dramatically, with sports rights commanding exclusive distribution premiums against commoditized entertainment libraries.
- Sports:Live event rights with exclusive windowing strategies across linear and streaming platforms. The Walt Disney Company leverages ESPN's brand strength to control distribution leverage through multiple delivery modes.
- Entertainment:Scripted and unscripted programming with library monetization through FAST channel repurposing. Warner Bros. Discovery anchors competitive stance through deep content libraries spanning linear and streaming formats.
- News:Time-sensitive production with continuous operations and regulatory content obligations under EMA Audiovisual Media Services Directive in Europe.
- Educational:Curriculum-aligned programming with production tax incentives under IRA domestic content provisions lowering effective costs for US-based studio construction.
Entertainment dominates installed base by library hours. Sports is where expansion concentrates as exclusive rights negotiations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum reallocation policies anchor infrastructure investment patterns in the United States, while India's BharatNet initiative and Europe's Audiovisual Media Services Directive create divergent regulatory environments that reshape competitive positioning across national markets.
United States
ATSC 3.0 deployment drives transmitter replacement cycles and antenna reconfiguration investments. FCC spectrum repack mandates compress UHF channel assignments through auction mechanisms. Station groups in designated market areas consolidate master control operations into centralized hubs serving multiple regions.
India
BharatNet rural broadband expansion unlocks subscriber bases in tier-3 and tier-4 districts for regional broadcasters. TRAI regulations shape content licensing frameworks for educational and vernacular programming. Metropolitan clusters in Maharashtra and Karnataka adopt HEVC encoders aggressively as fiber-to-the-home penetration deepens.
Germany
Public service broadcasting obligations under domestic media law sustain infrastructure investment in terrestrial transmission networks. EMA content quota enforcement through the Audiovisual Media Services Directive alters programming economics for cross-border operators. Media production clusters in North Rhine-Westphalia and Bavaria concentrate technical talent for hybrid IP-SDI workflows.
United Kingdom
Ofcom spectrum management and public service remit requirements shape broadcaster investment priorities. GDPR and domestic data protection frameworks constrain targeted advertising capabilities in IP-delivered services. London and Greater Manchester anchor production facility modernization for cloud playout migration.
Japan
METI industrial policy supports 4K and 8K ultra-high-definition broadcast standardization. NHK's technical leadership in next-generation broadcasting creates reference architectures for regional commercial broadcasters. Kanto and Kansai metropolitan areas concentrate satellite uplink facilities and terrestrial transmission infrastructure.
Television Broadcasting Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer structure where scale determines content rights access and distribution leverage. The upper tier controls premium sports rights and deep library inventories, while specialists concentrate on regional language programming or technical infrastructure services. Three archetypes dominate: integrated media conglomerates with hybrid cable-IP infrastructure, pure-play content aggregators with streaming-native operations, and broadcast technology vendors enabling facility modernization. Competitive moves center on exclusive rights negotiations for live events and cloud playout partnerships that reduce capital intensity.
Within the integrated conglomerate tier, Comcast Corporation and The Walt Disney Company exemplify divergent infrastructure strategies. Warner Bros. Discovery occupies a position bridging linear and streaming formats through library depth. These entities represent how scale in content acquisition translates into distribution leverage across terrestrial, satellite, cable, and IP delivery modes.
| Leading Market Players |
|---|
| Comcast Corporation |
| The Walt Disney Company |
| Warner Bros. Discovery |
| Paramount Global |
| AT&T Inc. |
| Fox Corporation |
| British Broadcasting Corporation |
| Discovery, Inc. |
| Vivendi |
| Others |
Value Chain & Pricing Dynamics
FCC spectrum reallocation mandates gate both infrastructure qualification and price differentiation simultaneously, compressing UHF channel assignments while elevating transmitter replacement costs for station groups. This regulatory compression forces broadcasters to consolidate master control operations or absorb elevated operational overhead, with pricing power bifurcating between spectrum-rich incumbents and capital-constrained regional operators.
Pricing Analysis
Long-term transponder leases and multi-year retransmission consent agreements anchor pricing structures for satellite and cable delivery, while spot-market IP bandwidth purchases introduce volatility into streaming cost bases. Price differentiation rests on content exclusivity tiers and geographic market density, with premium sports rights commanding distribution leverage against commoditized entertainment libraries. Pricing pressure intensifies in ad-supported tiers as FAST channel proliferation compresses CPM rates for traditional broadcasters. Educational institutions exhibit highest price sensitivity due to budget constraints, while governmental emergency alert contracts tolerate premium pricing for hardened infrastructure guarantees.
Supply Chain Analysis
Just-in-time component sourcing dominates transmitter and encoder procurement, though strategic stockpiling of RF power amplifiers and satellite transponder capacity buffers against FCC-mandated relocation deadlines. Supply concentration centers on the United States for ATSC 3.0 chipset design, Japan for 4K/8K broadcast standard components, and Taiwan for HEVC encoder manufacturing. Raw material dependencies include gallium nitride for high-power amplifiers, rare earth elements for antenna systems, and specialized optical fiber for fiber-to-the-home backhaul. Single-source vulnerability concentrates in geostationary satellite manufacturing. Distribution runs through broadcast technology integrators serving designated market areas with turnkey facility upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The accelerating retirement of RF transmission specialists against lagging IP-native technician pipeline entry creates acute capability scarcity, constraining legacy system maintenance while inflating labor costs for hybrid workflow operations.
For Market Incumbents: Fortify master control consolidation into centralized hubs serving multiple designated market areas, reducing per-station RF engineer headcount exposure while extending ATSC 3.0 infrastructure lifetime. Secure exclusive sports rights windows across linear and streaming formats to defend against streaming-native competitors capturing live event audiences. Prioritize cloud playout partnerships that reduce capital intensity for educational and governmental segments.
For New Entrants and Emerging Players: Vernacular content gaps in India's tier-3 and tier-4 districts present penetrable white space where BharatNet expansion outpaces regional broadcaster localization capabilities. Target educational institution streaming migrations with software-defined workflow solutions displacing legacy satellite downlinks. Pursue channel partnerships with connected TV platforms for FAST channel distribution, exploiting subscription fatigue rotation toward ad-supported linear formats.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native broadcast technology segments as edge computing and software-defined playout displace hardware-heavy transmission infrastructure. Long-term viability favors acquisition targets with hybrid IP-SDI workflow expertise bridging legacy and next-generation operations. Monitor 5G broadcast multicast standardization progress as inflection indicator for spectrum-efficient mobile delivery economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Master Control Consolidation | Comcast Corporation leverages centralized hub architecture to offset RF engineer attrition across fragmented designated market areas. |
| Cloud Playout Migration | Educational institutions accelerate software-defined workflow adoption, reducing satellite downlink capital intensity for distance learning delivery. |
| ATSC 3.0 Infrastructure Upgrade | US station groups deploy next-generation transmitters enabling targeted advertising and enhanced emergency alert capabilities under FCC mandates. |
| Regional Language Content Expansion | Vernacular broadcasters in India capture first-mover advantages as BharatNet unlocks tier-3 and tier-4 subscriber bases for localized programming. |
| 5G Broadcast Multicast Development | Convergence of cellular and broadcast technologies permits spectrum-efficient live event delivery to mobile devices without unicast capacity consumption. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with broadcast engineering directors, content licensing executives, satellite transponder procurement managers, and educational technology officers. Secondary validation drew from FCC spectrum auction records, TRAI regulatory filings, EMA Audiovisual Media Services Directive implementations, and SEC 10-K disclosures from integrated media conglomerates. Bottom-up service type and delivery mode sizing triangulated against top-down macroeconomic consumption projections.
Across the analysis window, forecasts modeled segmentation dimensions including service type, delivery mode, end user category, and content type with regional regulatory cluster differentiation. CAGRs derived from historical infrastructure investment patterns and projected fiber-to-the-home penetration curves, incorporating HEVC encoder adoption rates and ATSC 3.0 deployment timelines as broadcast-specific inputs.
Underlying assumptions cover spectrum reallocation timelines, rural broadband expansion trajectories, and streaming substitution elasticities, with deviation risk concentrated in FCC auction timing and 5G broadcast multicast standardization progress. Revision becomes warranted when fiber-to-the-home penetration or RF engineer attrition rates cross thresholds outside modeled bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Mobile TV Market
Television
Holographic TV Market
Television
Television Advertising Market
Television
Cloud Television (TV) Market
Television
Cable Television Networks Market
Television
Print Newspapers and Magazines Market
Television
Free-To-Air (FTA) Service Market
Television
Cloud TV Market
Television
Pay TV Market
Television
Television Services Market
Television
Global Broadcast Equipment Market
Television
HDTV Market
Television
TV Advertising Market
Television
Pay TV Operator Market
Television
Broadcasting and Cable TV Market
Television
Television Market