
 Global Over-The-Top Market | 2026-2036
Global Over-The-Top Market Size, Share, and Industry Trends Forecast 2026-2036
Global Over-The-Top Market Outlook
Cloud-native streaming architecture is reshaping how over-the-top content is encoded, distributed, and monetized at scale. Netflix leverages its proprietary content delivery network to sustain low-latency playback across heterogeneous last-mile conditions. Amazon anchors its OTT position through backward integration into cloud infrastructure and advertising technology stacks. Apple differentiates through tight hardware-software coupling that controls the premium viewing endpoint.
Over-the-top services deliver audio, video, and interactive content directly to end-users via internet protocol, bypassing traditional broadcast, cable, or satellite distribution, with typical streaming bitrates ranging from 5 Mbps for HD to 25 Mbps for 4K HDR depending on codec efficiency. The primary commercial purpose centers on direct monetization of attention through subscription fees, advertising impressions, or transactional purchases. Video streaming dominates revenue contribution within the service type dimension as studios accelerate direct-to-consumer windowing strategies. The subscription model segment stratifies sharply, with SVOD facing churn pressure while AVOD captures price-sensitive cohorts through ad-supported tiers. Smart TVs anchor the device type landscape as operating system consolidation reduces fragmentation for application developers.
The FCC governs net neutrality and broadband classification in the United States, directly shaping interconnection costs and streaming quality-of-service guarantees for OTT distributors. EMA content rating harmonization and GDPR data portability rules in Europe constrain cross-border content licensing and subscriber data utilization. India's TRAI tariff orders and BIS digital security standards impose localization requirements on foreign platforms operating in the market. Stakeholders must monitor how fragmentation between national content quotas and data sovereignty regimes affects platform economics and catalog universality.
Market Dynamics
Cloud-native encoding pipelines and edge caching infrastructure are compressing distribution economics while EU AI Act compliance mandates are forcing algorithmic transparency investments that reshape content recommendation architectures.
Growth Catalysts
- Broadband Infrastructure Rollout:Fiber-to-the-home deployments in India, Brazil, and Indonesia are expanding addressable connected TV households and reducing buffering friction for 4K HDR streams.
- GDPR Data Portability Rules:Subscriber data mobility mandates in Europe are lowering switching costs and intensifying platform competition for exclusive content licensing.
- AVOD Tier Expansion:Advertising-supported subscription models are capturing price-sensitive cohorts previously excluded from SVOD price points, broadening total monetizable audience base.
Market Restraints
- Codec Licensing Fragmentation:Patent pool disputes around HEVC and VVC compression standards are inflating content preparation costs for independent distributors without captive IP portfolios.
- Last-Mile Infrastructure Gaps:Rural broadband deserts in Indonesia and northeastern Brazil impose quality-of-service ceilings that limit premium tier penetration outside metropolitan clusters.
- Content Quota Localization:India's TRAI tariff orders mandating domestic programming percentages are inflating production procurement costs for foreign platforms operating under BIS digital security compliance frameworks.
Strategic Opportunities
- Interactive Streaming Convergence:Real-time audience participation features merging live sports wagering with synchronized second-screen experiences are opening new revenue pools in Brazil's regulated gaming markets.
- Edge Computing Distribution:Micro-datacenter deployments at ISP aggregation points are enabling ultra-low-latency cloud gaming and live event streaming without core network transit costs.
- EU AI Act Algorithmic Auditing:Mandatory explainability requirements for recommendation engines are creating competitive differentiation for platforms with transparent content curation methodologies.
Industry Challenges
- Cross-Border Licensing Complexity:Territorial content windowing restrictions and divergent EMA rating harmonization standards are fragmenting catalog universality and inflating rights negotiation overhead.
- Churn Prediction Model Accuracy:Behavioral signal noise from shared household accounts and VPN masking is degrading subscriber lifetime value forecasting precision for retention algorithm training sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Over-The-Top Market |
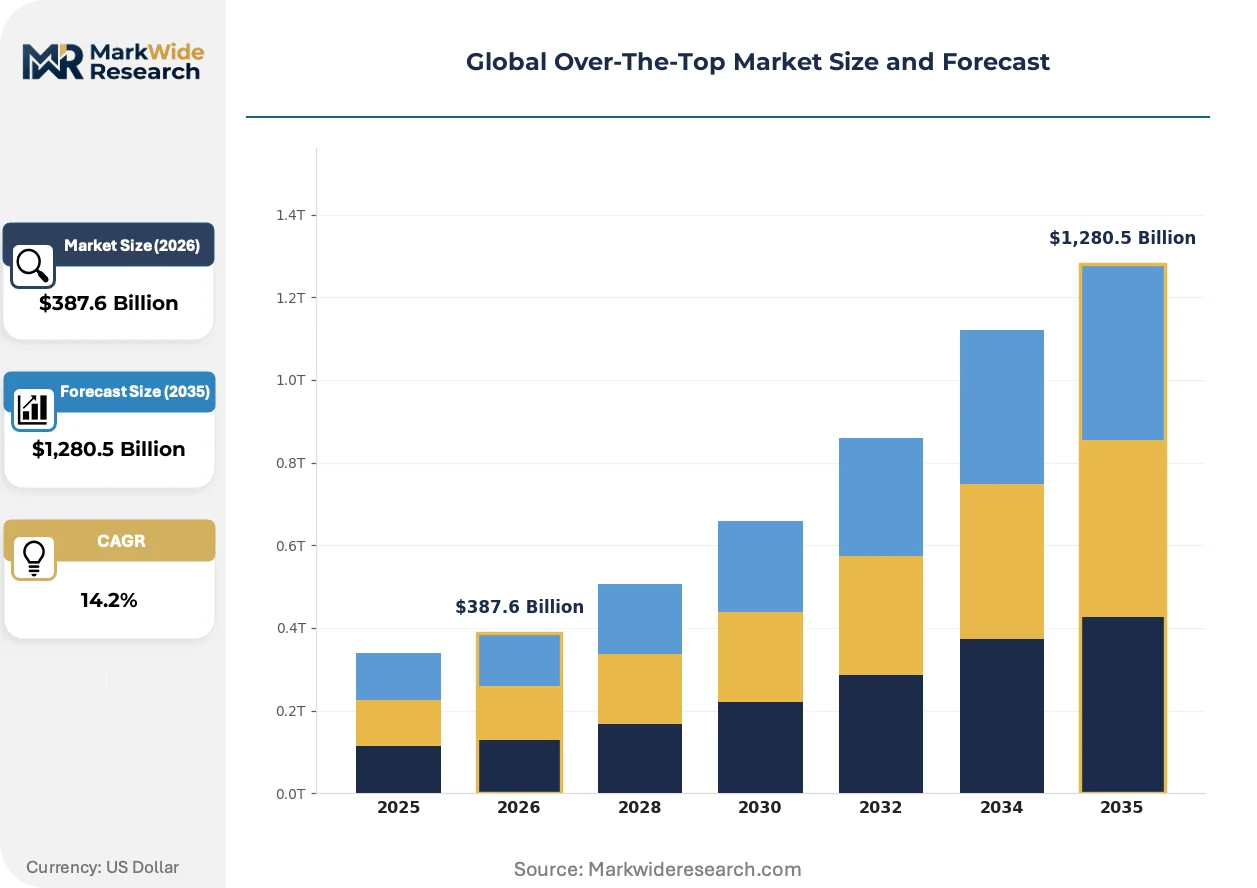
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Music Streaming, Gaming, VoIP Device Type: Smart TVs, Smartphones, Tablets, Laptops Content Type: Movies, TV Shows, Live Sports, User-Generated Subscription Model: SVOD, AVOD, TVOD, Freemium |
| Companies Covered | Netflix Inc., Amazon.com Inc., Alphabet Inc., Apple Inc., The Walt Disney Co., Tencent Holdings Ltd., Microsoft Corp., Paramount Global, Comcast Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Over-The-Top Market Strategic Shifts
Encoding efficiency gains and regulatory algorithmic mandates are simultaneously compressing distribution costs and expanding compliance scope across streaming infrastructure stacks.
AI-powered content moderation and automated subtitle generation is digitizing post-production workflows previously requiring manual localization labor. Studios in India and Indonesia are deploying neural machine translation pipelines to accelerate regional release windows. This compression of dubbing timelines is enabling day-and-date global premieres that collapse traditional theatrical-to-streaming windows.
The EU AI Act's transparency requirements for algorithmic recommendation systems are forcing platforms to document content ranking logic and provide user override controls. This regulatory friction is most acute for personalized home feed architectures that previously operated as black-box engagement optimization engines. European operators are responding by deploying hybrid curation models blending editorial oversight with automated suggestions.
Mobile-first consumption patterns in India and Indonesia are displacing lean-back television viewing as the primary streaming context. Short-form vertical video integration within long-form platform interfaces is capturing fragmented attention spans and reducing average session durations. This behavioral pivot is most visible in Indonesia's commuter-centric viewing peaks and India's tier-two city youth demographics.
Global Over-The-Top Market Segmentation
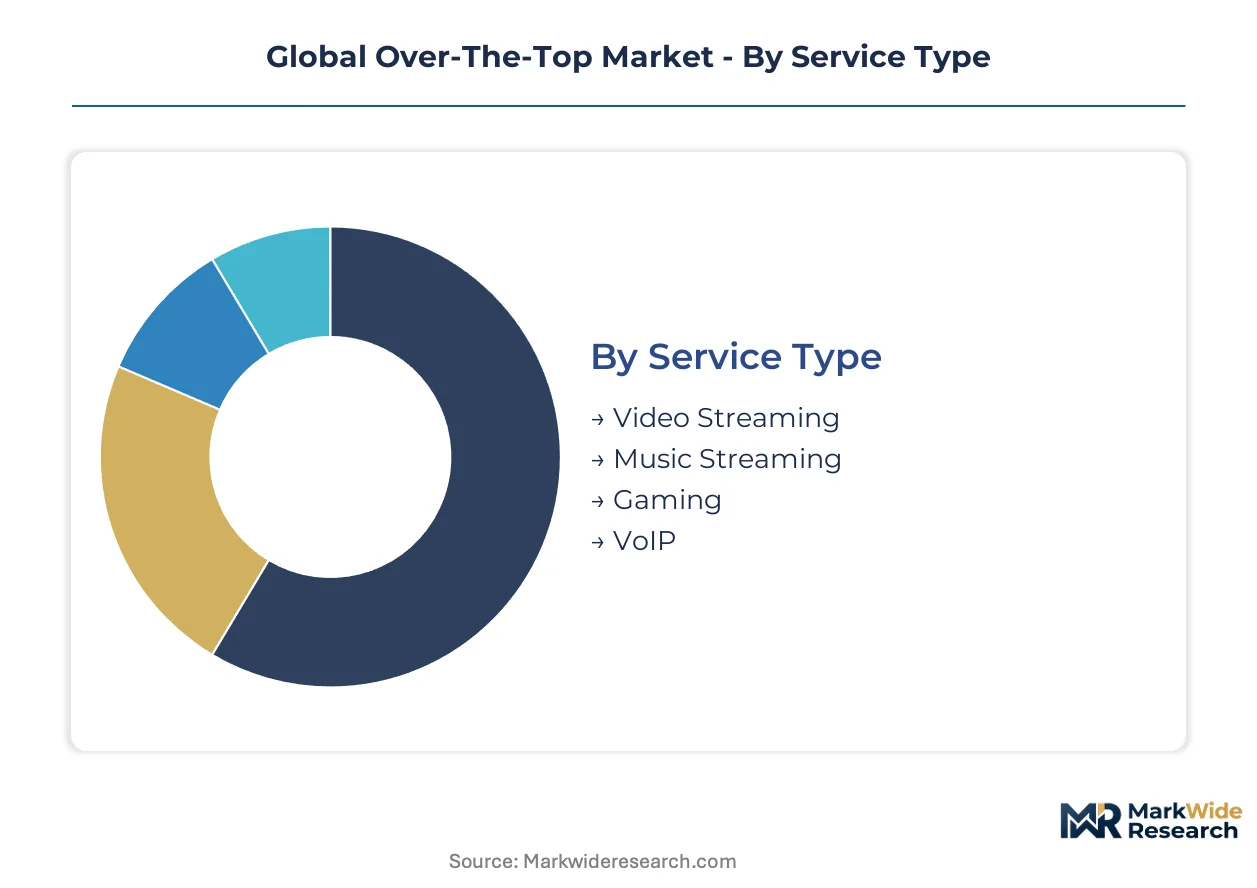
Segmentation in the over-the-top market illuminates how consumption contexts, monetization mechanics, and content formats create divergent growth trajectories. Each dimension carries distinct infrastructure requirements, regulatory exposure, and margin structures that shape platform strategy.
Service Type:
Use-case spectrum spans passive entertainment consumption through interactive communication, with each service category demanding specialized encoding pipelines and latency architectures.
- Video Streaming:Delivers on-demand and live audiovisual content via adaptive bitrate protocols, with 4K HDR streams requiring 15-25 Mbps sustained throughput. Demand concentrates in India and Brazil as fiber-to-the-home deployments expand connected TV penetration among price-sensitive households. Studios accelerate direct-to-consumer windowing, collapsing traditional theatrical exclusivity periods.
- Music Streaming:Provides audio-on-demand and curated playlist services with significantly lower bandwidth requirements, typically 320 kbps for high-fidelity tiers. Subscriber concentration clusters in Indonesia's mobile-first youth demographics, where bundled telco partnerships reduce payment friction. Licensing costs for major label catalogs consume substantial revenue share.
- Gaming:Cloud-rendered interactive entertainment delivered via low-latency streaming protocols, requiring sub-20ms response times for competitive viability. Edge computing deployments at ISP aggregation points enable quality-of-service guarantees.
- VoIP:Voice and video communication services bypassing traditional telephony infrastructure, with end-to-end encryption compliance varying by jurisdiction. Enterprise adoption drives premium tier subscriptions.
Established volume favors video streaming; emerging adoption favors gaming.
Device Type:
Hardware endpoint diversity creates fragmentation in codec support, display capabilities, and interaction paradigms that complicate cross-platform development.
- Smart TVs:Large-format displays with embedded operating systems anchoring lean-back consumption in living room contexts. Operating system consolidation around proprietary platforms reduces application certification overhead. Demand concentrates in Brazil's metropolitan clusters where broadband infrastructure supports 4K HDR throughput.
- Smartphones:Pocket-sized mobile endpoints dominating commuter and fragmented attention contexts, particularly in Indonesia's tier-two cities. Vertical video formats and short-form integration reshape content packaging.
- Tablets:Mid-size portable screens occupying hybrid use cases between mobile and fixed viewing. Lower replacement cycles dampen hardware-driven upgrade revenue.
- Laptops:General-purpose computing devices with browser-based streaming dominance in work-adjacent consumption. Corporate security policies constrain personal subscription usage.
Smart TVs capture premium monetization; smartphones expand addressable base fastest.
Content Type:
Production budget tiers and windowing flexibility separate professionally produced catalogs from user-generated volume plays.
- Movies:Feature-length theatrical productions with high per-title acquisition costs and exclusive licensing windows. Day-and-date global premieres compress regional release stagger.
- TV Shows:Serialized episodic content driving sustained engagement and binge-consumption patterns. Season drops versus weekly releases create divergent retention curves.
- Live Sports:Real-time event broadcasting with zero latency tolerance and peak concurrent load engineering challenges. Wagering integration in Brazil's regulated markets opens ancillary revenue.
- User-Generated:Platform-hosted creator content with minimal curation overhead and algorithmic distribution. Short-form vertical formats capture fragmented attention spans in India.
Movies and TV shows anchor subscription pricing power; live sports commands premium tier premiums.
Subscription Model:
Monetization architecture separates recurring revenue predictability from transactional flexibility and advertising scale.
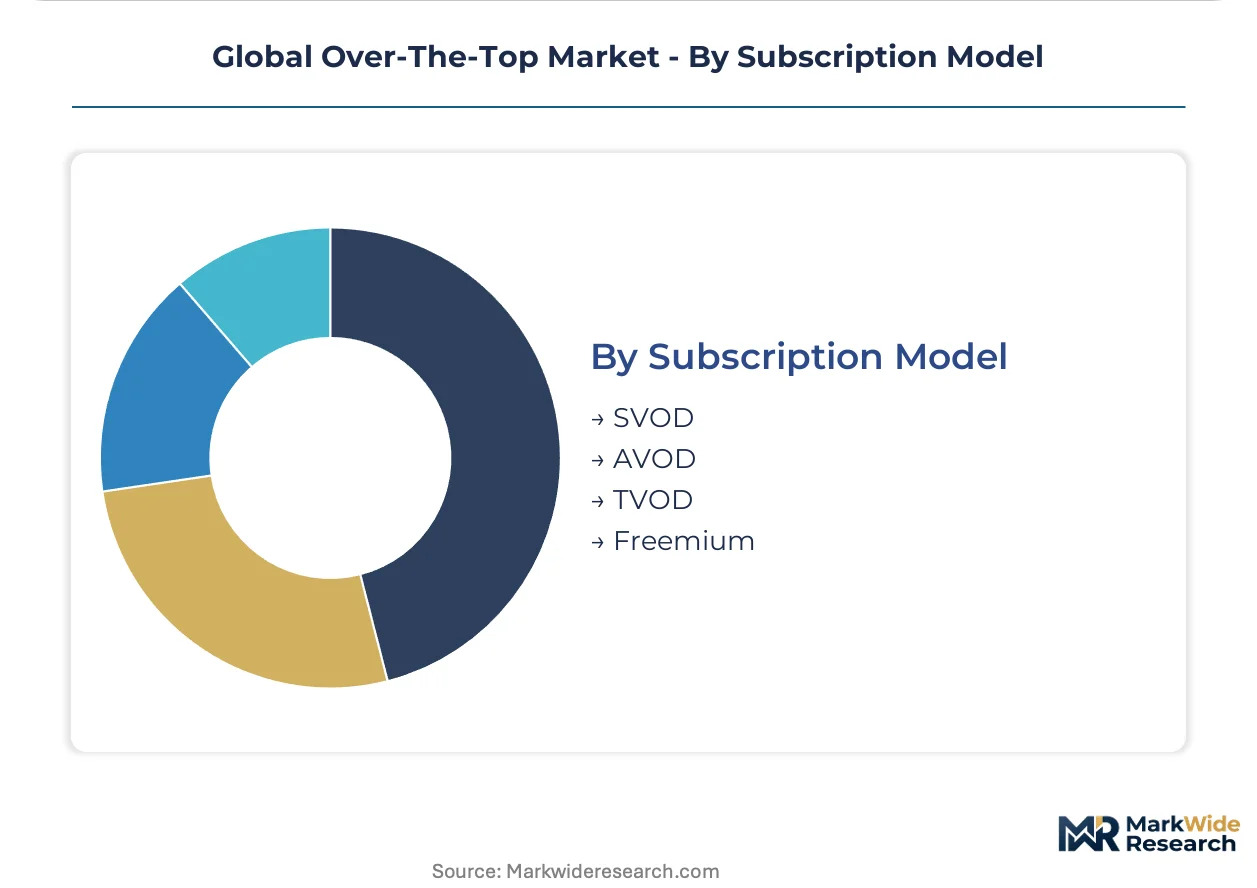
- SVOD:Subscription video-on-demand with fixed monthly fees and ad-free consumption. Churn pressure intensifies as GDPR data portability reduces switching costs in Europe.
- AVOD:Advertising-supported tiers capturing price-sensitive cohorts excluded from premium pricing. Ad load tolerance varies dramatically by content category and geography.
- TVOD:Transactional video-on-demand for premium new releases and library titles without subscription commitment. Windowing restrictions limit catalog depth.
- Freemium:Tiered access with basic functionality at no cost and feature unlocking via subscription conversion. Conversion rates concentrate in gaming and music categories.
SVOD maintains revenue concentration; AVOD expands fastest among emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content licensing flows and platform revenue repatriation create persistent trade imbalances in audiovisual services, with major exporters capturing subscription value while import-dependent markets absorb foreign catalog saturation.
United States
FCC net neutrality rulings and broadband infrastructure subsidies shape interconnection economics for streaming distributors operating across heterogeneous last-mile conditions. Hollywood studio concentration in Los Angeles anchors original production capacity, while Seattle and San Francisco Bay Area cloud infrastructure clusters encode and distribute global content pipelines.
India
TRAI tariff orders mandating domestic programming percentages and BIS digital security compliance reshape foreign platform operating economics. Mumbai's entertainment production ecosystem and Bangalore's technology development corridor concentrate localization engineering and regional content creation for mobile-first audiences.
Brazil
ANVISA content classification harmonization and regulated sports wagering frameworks enable interactive streaming revenue models. São Paulo's metropolitan broadband infrastructure supports 4K HDR penetration, while Rio de Janeiro's production facilities serve Portuguese-language original programming for Latin American expansion.
Germany
GDPR data portability enforcement and EU AI Act algorithmic transparency mandates intensify compliance investment for recommendation engine architectures. Berlin's startup ecosystem and Munich's media technology clusters develop privacy-preserving personalization methodologies for European market deployment.
Indonesia
National data localization requirements and mobile-first consumption patterns concentrate platform infrastructure investment in Jakarta and Surabaya. Java-based content production studios accelerate neural machine translation pipelines to compress regional dubbing timelines for day-and-date release windows.
Global Over-The-Top Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated technology stacks that combine cloud infrastructure, content production, and endpoint hardware control. Three strategic archetypes dominate: infrastructure-anchored platforms leveraging captive distribution networks, hardware-coupled ecosystems controlling premium viewing endpoints, and content-origin studios accelerating direct-to-consumer windowing. Competitive maneuvering concentrates on exclusive licensing acquisitions and algorithmic personalization investments that reduce subscriber churn.
Within the infrastructure-anchored tier, Amazon.com Inc. and Microsoft Corp. exemplify cloud-native distribution architectures that compress encoding and delivery economics. Netflix Inc. occupies a position bridging proprietary content delivery network investment with original production scale. These three entities represent divergent pathways for sustaining low-latency playback across fragmented last-mile conditions while managing regulatory compliance across multiple jurisdictions.
| Leading Market Players |
|---|
| Netflix Inc. |
| Amazon.com Inc. |
| Alphabet Inc. |
| Apple Inc. |
| The Walt Disney Co. |
| Tencent Holdings Ltd. |
| Microsoft Corp. |
| Paramount Global |
| Comcast Corp. |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in the United States—anchored by hyperscaler data center clusters in Northern Virginia, Oregon, and Iowa—feeds directly into margin capture at the content delivery tier, where bandwidth arbitrage and edge caching investments separate profitable distributors from cost-burdened competitors.
Pricing Analysis
Industrial OEM buyers anchor the three-tier pricing structure across premium, standard, and economy levels in the enterprise streaming segment. Price differentiation stems from content exclusivity windows and ISO 27001 certification tiers for data governance. Cost compression in the AVOD tier is intensifying because programmatic advertising yield optimization demands continuous algorithmic investment. Price-sensitive cohorts in India and Indonesia gravitate toward ad-supported models, while premium subscribers in Brazil and Germany absorb higher SVOD fees for 4K HDR and live sports bundles.
Supply Chain Analysis
Upstream encoding hardware and CDN server fabrication concentrates in Taiwan, South Korea, and China, with specialized GPU and ASIC foundries supplying the computational backbone for real-time transcoding pipelines. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and rare earth elements for magnetic storage arrays. Supply chain risk centers on single-source vulnerability for advanced node semiconductors under export control restrictions. Distribution runs through hyperscaler-operated private backbone networks that bypass public internet transit for quality-of-service guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global over-the-top market sits in early-cycle expansion, with broadband infrastructure buildouts in India, Brazil, and Indonesia creating fresh addressable audiences for streaming platforms.
For Market Incumbents: Entrench proprietary content delivery networks through edge computing deployments at ISP aggregation points in São Paulo and Mumbai, insulating against latency degradation as regulatory fragmentation around EU AI Act compliance raises algorithmic transparency costs. Deepen backward integration into original production capacity in Los Angeles and Berlin to secure exclusive licensing windows that reduce churn vulnerability from GDPR data portability rules. For New Entrants and Emerging Players: Tier-two cities in Indonesia's Java corridor represent the most penetrable entry point, where mobile-first consumption patterns and commuter-centric viewing peaks remain underserved by global platform localization. AVOD tiers with telco bundling partnerships offer the lowest customer acquisition friction, while neural machine translation pipelines enable rapid regional content adaptation without legacy dubbing infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platforms with captive cloud infrastructure and original production scale, as these archetypes sustain margin compression better than pure-play distributors dependent on third-party encoding pipelines. The signal to watch is regulatory enforcement velocity around India's TRAI domestic programming quotas and BIS digital security compliance, which will reshape foreign platform operating economics.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Micro-datacenter placement at ISP aggregation points in São Paulo reduces core network transit costs for live sports streaming. |
| Original Production Scale-Up | Proprietary content pipelines in Berlin and Mumbai secure exclusive licensing windows that reduce subscriber churn pressure. |
| Algorithmic Transparency Investment | EU AI Act compliance documentation for recommendation engines creates competitive differentiation in European market deployment. |
| Telco Bundling Partnership | Pre-paid mobile integration in Jakarta and Surabaya lowers payment friction for price-sensitive AVOD tier adoption. |
| Neural Localization Pipeline | Machine translation acceleration in Java-based studios compresses regional dubbing timelines for day-and-date global premieres. |
Study Parameters
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed streaming platform CTOs, content licensing directors, telco partnership leads, and post-production facility operators across India, Brazil, Germany, and Indonesia. Secondary sources include TRAI tariff orders, EU AI Act compliance documentation, FCC net neutrality rulings, and hyperscaler infrastructure capex disclosures. Bottom-up subscriber modeling and top-down addressable market sizing triangulate volume estimates.
Calibration against historical broadband penetration curves and content spend-to-subscriber conversion ratios shapes the projection framework across the analysis window. Segmentation dimensions encompass service type, device endpoint, content format, and subscription model, with regional regulatory clusters treated as distinct adoption environments. CAGRs derive from fitted growth curves adjusted for infrastructure deployment timelines and content localization velocity. Forecast inputs include fiber-to-the-home rollout schedules and mobile data tariff trajectories in priority markets.
Macroeconomic conditions sit as an overlay; deviation in emerging market currency stability and advertising expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about codec licensing resolution and cross-border content windowing flexibility. Cross-checking against ISP infrastructure deployment announcements and studio content spend disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Video Streaming Market