
 Global Digital Terrestrial Television Market | 2026-2036
Global Digital Terrestrial Television Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Terrestrial Television Market Foresight
The unbundling of transmission infrastructure from content production is rebalancing procurement patterns across the broadcast value chain. Samsung Electronics Co., Ltd. leverages its semiconductor fabrication capabilities to dominate integrated tuner chipset supply. Rohde & Schwarz GmbH & Co KG anchors its position through precision transmitter manufacturing for national multiplex operators. Sony Group Corporation differentiates via professional broadcast camera-to-transmission workflow integration.
Digital terrestrial television constitutes a wireless broadcasting system transmitting compressed digital video and audio via terrestrial radio waves using standardized modulation schemes such as OFDM with typically 6-8 MHz channel bandwidth, enabling multi-program carriage within a single frequency allocation. The technology serves as the backbone for free-to-air public service broadcasting and commercial television distribution to mass audiences without subscription infrastructure. Among component categories, transmitter systems command the largest capital allocation due to national network buildouts, while set-top box demand concentrates in markets completing analog switchover. Service type segmentation shows free-to-air platforms retaining the widest household penetration, though hybrid services combining broadcast with broadband return paths are gaining traction in developed markets seeking interactive functionality.
The International Telecommunication Union coordinates global spectrum allocation for terrestrial broadcasting through regional radio regulations that shape national deployment timelines. EBU technical standards and country-level communications regulators such as Ofcom in the United Kingdom, ARCEP in France, and Anatel in Brazil enforce emission masks, coverage obligations, and interoperability requirements that determine equipment certification pathways. Stakeholders must monitor spectrum reallocation proceedings in the 600-700 MHz bands, as mobile broadband encroachment threatens channel availability and compels broadcasters to evaluate single-frequency network densification or platform migration strategies.
Market Dynamics
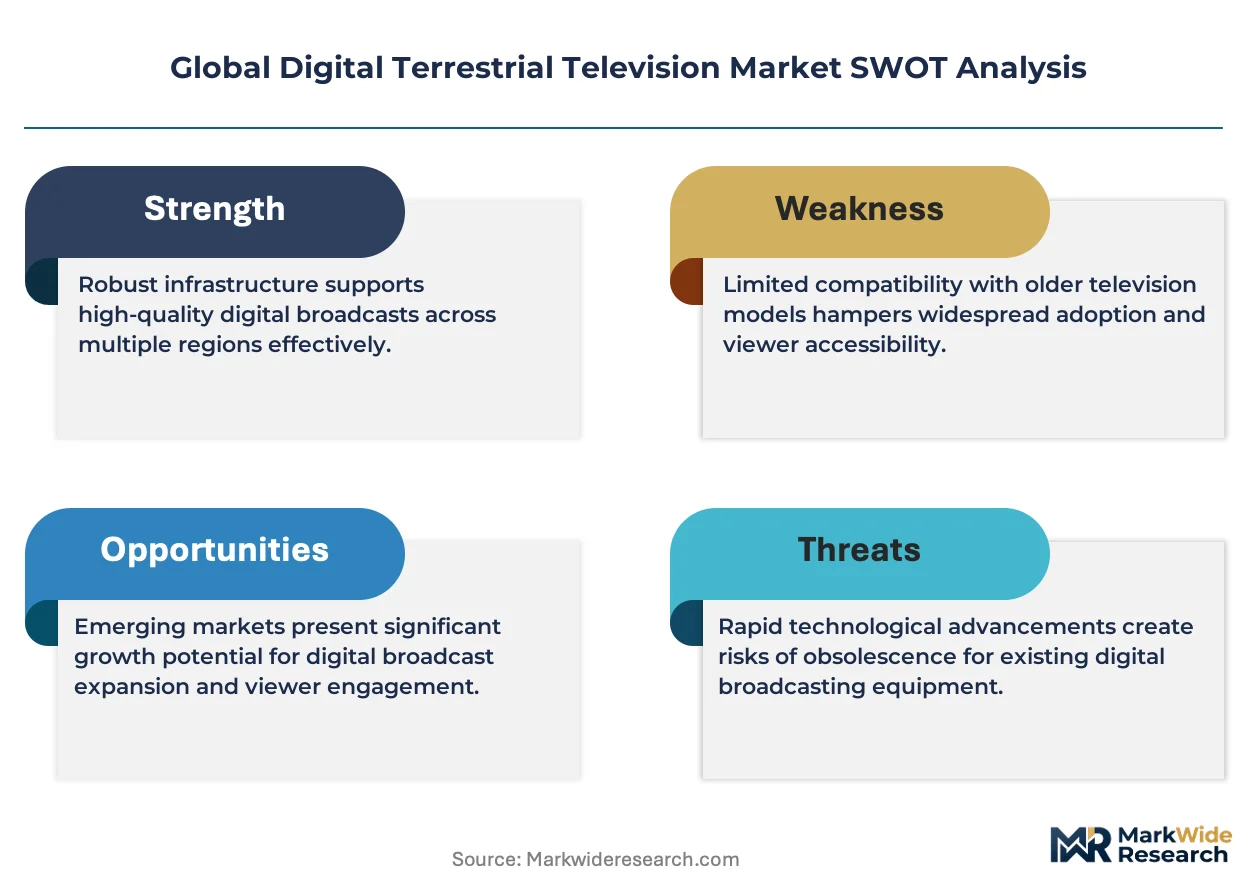
Spectrum reallocation mandates across multiple jurisdictions are compressing channel availability for terrestrial broadcasters, forcing infrastructure densification and accelerating platform migration decisions.
Growth Catalysts
- Digital Switchover Mandates:Brazil, India, and Indonesia are completing nationwide analog-to-digital transitions, compelling equipment replacement cycles and transmitter system procurement.
- High-Definition Content Delivery:Residential broadcasters are upgrading transmission infrastructure to support HD broadcasting standards, driving demand for integrated tuner chipsets and precision transmitters.
- Hybrid Service Integration:Broadband return paths are converging with broadcast platforms in developed markets, enabling interactive functionality and subscriber retention for free-to-air operators.
Market Restraints
- Semiconductor Supply Concentration:Integrated tuner chipset fabrication concentrates among East Asian foundries, exposing equipment manufacturers to geopolitical supply disruptions.
- Spectrum Scarcity:Mobile broadband encroachment into 600-700 MHz bands reduces channel availability, forcing broadcasters toward costly single-frequency network densification.
- Platform Substitution:Over-the-top streaming services displace traditional terrestrial viewership among younger demographics in bandwidth-abundant markets.
Strategic Opportunities
- Indonesia Infrastructure Buildout:Archipelago geography creates demand for gap-filler transmitters and satellite-terrestrial hybrid distribution to reach remote island populations.
- Energy-Efficient Transmitter Technology:Liquid-cooled solid-state transmitter architectures reduce operational expenditure and align with national carbon reduction frameworks.
- Professional Workflow Integration:Camera-to-transmission pipeline unification offers margin expansion for broadcast equipment vendors serving national multiplex operators.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in OFDM modulation optimization and antenna pattern design remains concentrated among aging practitioner cohorts in Europe and Japan.
- Legacy System Interoperability:MPEG-2 to HEVC codec migration requires simultaneous simulcast infrastructure, doubling capital requirements during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Terrestrial Television Market |
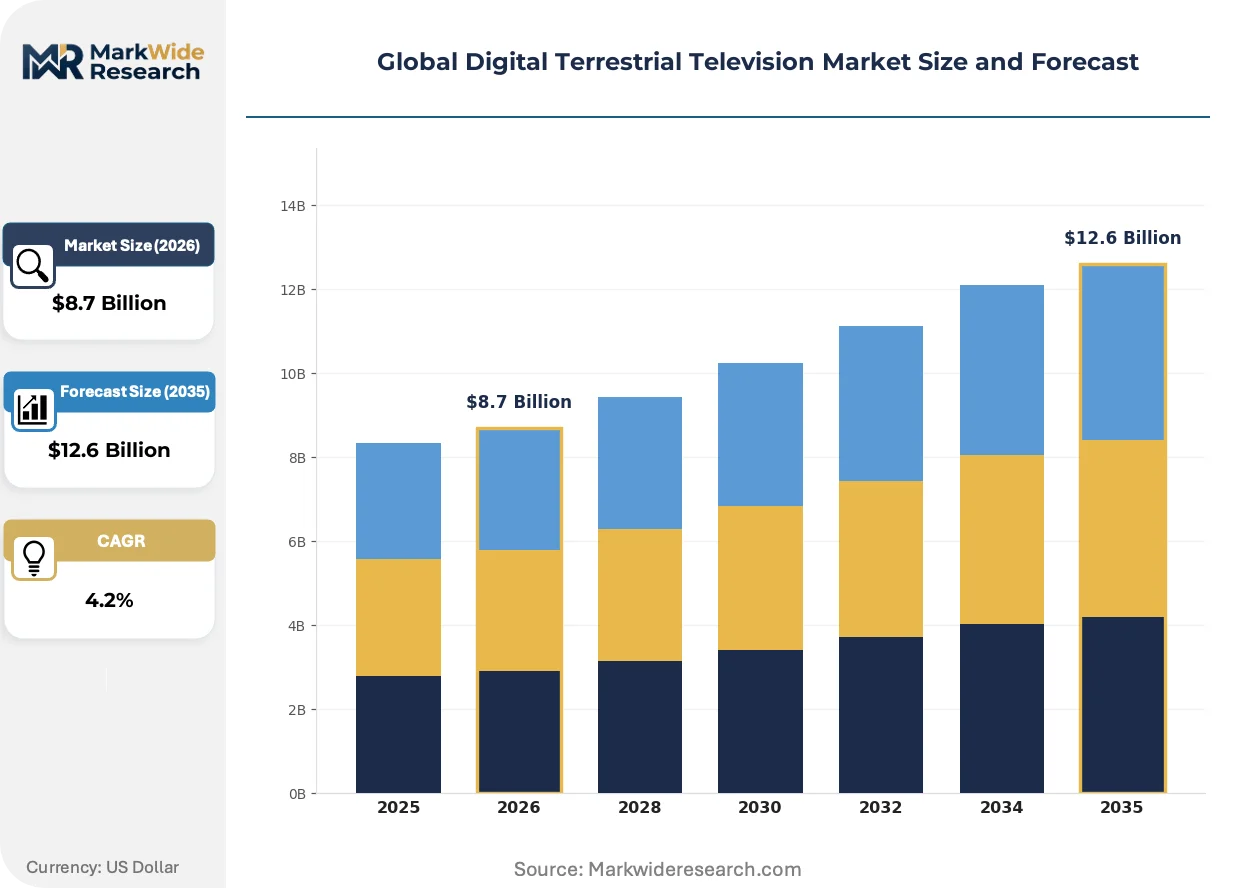
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DVB-T, ATSC, ISDB-T, DTMB Component: Transmitter, Receiver, Antenna, Set-Top Box End User: Residential, Commercial, Educational, Hospitality Service Type: Subscription, Free-to-Air, Pay-Per-View, Hybrid |
| Companies Covered | Panasonic Corporation, NEC Corporation, Samsung Electronics Co., Ltd., Evertz Microsystems Ltd., Harmonic Inc., Sony Group Corporation, Rohde & Schwarz GmbH & Co KG, Fox Corporation, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Terrestrial Television Market Shifts & Advancements
Terrestrial broadcasting infrastructure is undergoing compression as spectrum economics favor densification over coverage expansion, while modulation efficiency gains enable multi-program carriage within tightening bandwidth constraints.
HEVC encoding is consolidating transmission efficiency for digital terrestrial platforms. National multiplex operators in Germany and the United Kingdom are deploying HEVC-enabled headends to quadruple program capacity within existing 8 MHz channel allocations. This codec transition is consolidating vendor positions around integrated encoder-transmitter suppliers capable of end-to-end workflow delivery.
REACH substance restrictions and RoHS amendments are reshaping transmitter manufacturing compliance in the European Union. Cadmium and lead limitations in high-power semiconductor packages are forcing redesigns of RF power amplifier modules. German and French national operators are prioritizing CE-marked equipment with full material disclosure documentation to preempt regulatory enforcement actions.
Equipment procurement is fragmenting between national multiplex operators and regional broadcast associations. Brazil's Anatel certification requirements and India's BIS registration mandates are lengthening vendor qualification timelines. This procurement fragmentation is most visible in emerging markets where state-owned broadcasters retain centralized purchasing authority while commercial operators negotiate direct equipment supply agreements.
Global Digital Terrestrial Television Market Segmentation
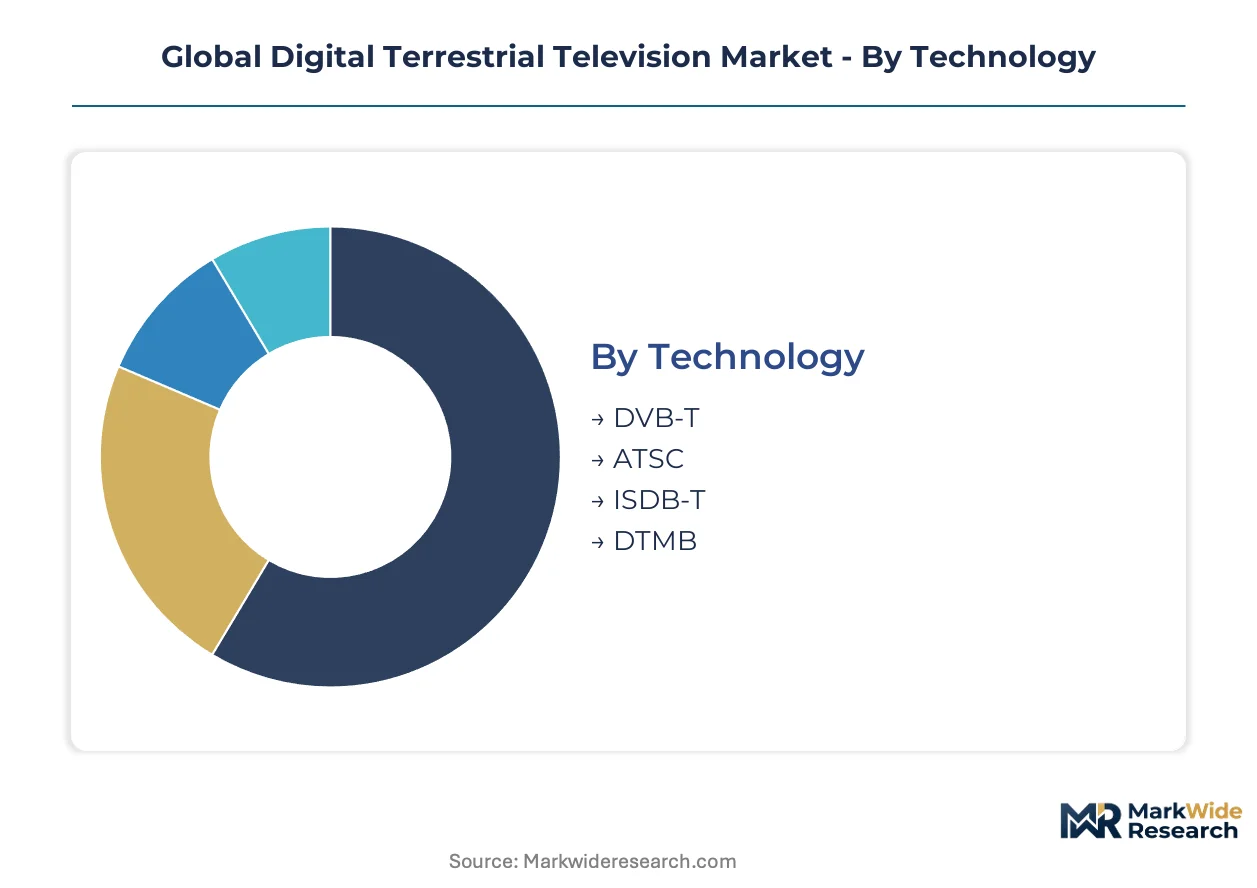
Technology standards, component specifications, and service models fragment procurement patterns across terrestrial broadcast infrastructure. Equipment vendors must align product roadmaps with divergent national regulatory mandates and operator business models.
Technology:
Standardization intensity varies sharply across this category, with some specifications dominating entire continents while others serve single-nation deployments.
- DVB-T:Orthogonal frequency-division multiplexing architecture dominates European and African terrestrial deployments, with DVB-T2 extensions enabling ultra-high-definition carriage. German and Italian national multiplex operators drive transmitter procurement for DVB-T2 migration, compelled by spectrum efficiency targets and HEVC codec integration timelines.
- ATSC:Advanced Television Systems Committee specifications govern North American broadcasting, with ATSC 3.0 next-generation standard enabling internet-protocol convergence and targeted advertising insertion. US station groups in major metropolitan markets are prioritizing ATSC 3.0 infrastructure for mobile reception and enhanced emergency alerting capabilities.
- ISDB-T:Integrated Services Digital Broadcasting standard serves Japan and Latin American markets including Brazil, with built-in mobile reception and interactive data casting features. Brazil's Anatel mandates ISDB-Tb variant for nationwide switchover completion.
- DTMB:Digital Terrestrial Multimedia Broadcasting standard anchors China's terrestrial television infrastructure, with DTMB-A extension supporting 4K and mobile broadcasting services.
Most installed capacity flows through DVB-T. Expansion is steepest in ATSC as North American broadcasters accelerate next-generation platform deployment.
Component:
Capital intensity and replacement cycles diverge widely, from decade-long transmitter investments to consumer-priced set-top boxes with 3-5 year obsolescence windows.
- Transmitter:High-power terrestrial broadcast transmitters utilizing solid-state or tube-based RF amplification represent the largest capital expenditure category for national network buildouts. India's Prasar Bharati and Indonesia's TVRI are procuring liquid-cooled solid-state transmitters for energy efficiency compliance with national carbon reduction frameworks.
- Receiver:Integrated digital tuners in television sets and mobile devices eliminate external equipment needs in mature markets, while standalone receivers serve vehicle and portable applications. Japanese automotive manufacturers embed ISDB-T receivers for traffic and entertainment services in domestic market vehicles.
- Antenna:Directional and omnidirectional reception antennas complete the RF signal path from broadcast tower to end-user device, with outdoor installations required in fringe coverage areas.
- Set-Top Box:External decoding devices bridge analog television sets to digital broadcasts during transition periods, with concentrated demand in Brazil, India, and Indonesia completing nationwide analog switchover programs.
Transmitter systems absorb the majority of infrastructure capital. Set-top box volume is climbing fastest in emerging markets completing digital switchover mandates.
End User:
Application requirements span from mass-market consumer reliability to specialized professional display and content distribution needs.
- Residential:Household television reception constitutes the core demand base, with consumers expecting free-to-air high-definition and ultra-high-definition services without subscription fees. Brazilian residential subscribers are driving set-top box demand as Anatel enforces analog signal termination deadlines.
- Commercial:Retail, healthcare, and corporate environments utilize terrestrial broadcast for customer-facing display and employee information distribution. Indian hospitals and railway stations deploy commercial-grade receivers for public information and entertainment programming.
- Educational:Schools and universities leverage terrestrial broadcast for distance learning content distribution, particularly in rural areas with limited broadband infrastructure. Indonesian educational institutions receive government-subsidized reception equipment for curriculum broadcasting.
- Hospitality:Hotels and resorts provide in-room terrestrial television as a baseline amenity, with premium properties upgrading to integrated smart television systems.
Residential deployment accounts for the bulk of installed base. Commercial applications are expanding most quickly as digital signage and public venue networks proliferate.
Service Type:
Revenue model architecture determines equipment specification requirements, from basic decryption-free reception to conditional access-protected premium tiers.
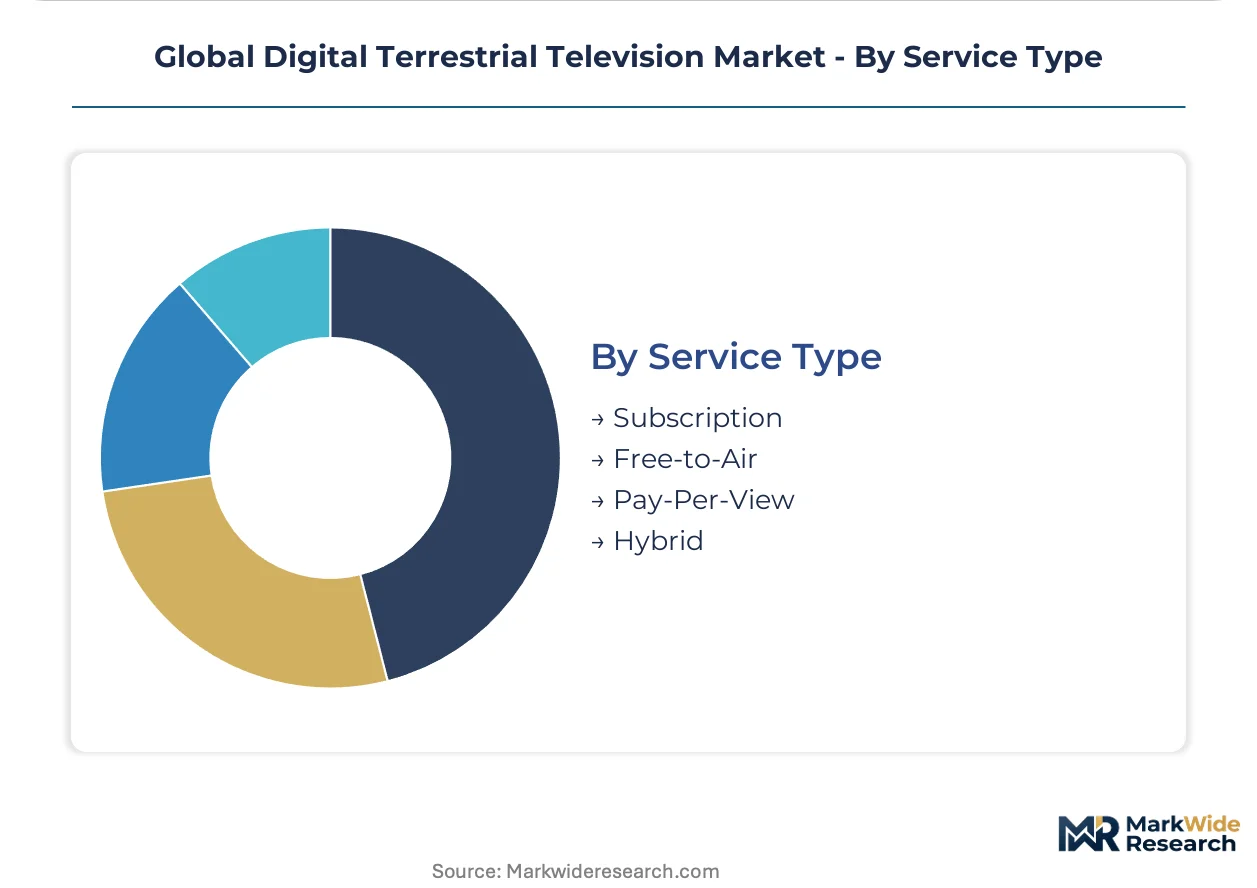
- Free-to-Air:Unencrypted broadcasting supported by advertising revenue and public funding dominates household penetration globally, requiring no subscriber management infrastructure. UK Freeview and German DVB-T2 HD platforms demonstrate sustained free-to-air viability in developed markets with strong public service broadcasting traditions.
- Subscription:Encrypted pay-television services over terrestrial multiplexes compete with satellite and cable platforms, requiring integrated conditional access systems in receiver devices. Italian Mediaset Premium and French Canal+ terrestrial offerings drive conditional access chipset integration.
- Pay-Per-View:Event-based transactional viewing for sports and entertainment programming utilizes return-path broadband connectivity for authorization and billing.
- Hybrid:Broadcast-broadband convergence combines terrestrial linear delivery with internet-based interactivity, catch-up services, and targeted advertising. UK Freeview Play and German HbbTV implementations are gaining traction as broadband penetration enables interactive functionality without dedicated return channels.
Free-to-Air platforms command the widest installed footprint. Hybrid services are gaining share fastest as broadband return paths enable interactive features without infrastructure duplication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital terrestrial television infrastructure originated in European laboratories during the 1990s, with Germany and the United Kingdom pioneering OFDM-based transmission systems before deployment scaled across Asia-Pacific and Latin America.
Germany
Public broadcaster ARD and commercial operator Media Broadcast are completing DVB-T2 infrastructure upgrades for ultra-high-definition carriage. ECHA REACH substance restrictions and RoHS amendments are forcing redesigns of RF power amplifier modules in high-power semiconductor packages. Bavaria's transmitter manufacturing cluster around Munich anchors precision equipment supply for national multiplex operators.
United States
Station groups in major metropolitan markets are prioritizing ATSC 3.0 infrastructure for mobile reception and emergency alerting capabilities. FCC spectrum reallocation proceedings in the 600-700 MHz bands are compressing channel availability for terrestrial broadcasters. California's Silicon Valley semiconductor ecosystem supplies integrated tuner chipsets for next-generation receiver devices.
Brazil
Anatel mandates ISDB-Tb variant completion for nationwide analog switchover, compelling set-top box procurement and transmitter system replacement cycles. The national communications regulator enforces emission masks and coverage obligations that determine equipment certification pathways. São Paulo's industrial corridor concentrates assembly operations for gap-filler transmitters serving remote Amazon basin populations.
India
Prasar Bharati is procuring liquid-cooled solid-state transmitters for energy efficiency compliance with national carbon reduction frameworks. BIS registration mandates are lengthening vendor qualification timelines for imported broadcast equipment. Gujarat's electronics manufacturing zone is emerging as a domestic assembly hub for set-top boxes serving rural switchover completion.
Japan
ISDB-T standard deployment supports built-in mobile reception and interactive data casting features for automotive and handheld applications. METI technical standards coordinate spectrum allocation and interoperability requirements for terrestrial broadcasting infrastructure. Tokyo-Osaka-Nagoya metropolitan corridors concentrate RF engineering expertise for OFDM modulation optimization and antenna pattern design.
Global Digital Terrestrial Television Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with semiconductor fabrication capabilities and precision transmitter manufacturing commanding pricing power over standard component suppliers. The vendor base organizes around three strategic archetypes: integrated electronics conglomerates with captive semiconductor supply, specialized broadcast equipment manufacturers with RF engineering heritage, and diversified technology providers leveraging adjacent consumer electronics scale. Competitive moves concentrate on strategic partnerships for codec integration and geographic expansion into switchover markets.
Among diversified electronics conglomerates, Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify the integrated-tuner-chipset archetype, while Rohde & Schwarz GmbH & Co KG anchors the precision-transmitter tier for national multiplex operators. Sony Group Corporation occupies a position bridging professional broadcast workflow integration with consumer receiver technology. Panasonic Corporation and NEC Corporation represent Japanese industrial diversification into terrestrial infrastructure, with geographic origins in Osaka and Tokyo respectively.
| Leading Market Players |
|---|
| Panasonic Corporation |
| NEC Corporation |
| Samsung Electronics Co., Ltd. |
| Evertz Microsystems Ltd. |
| Harmonic Inc. |
| Sony Group Corporation |
| Rohde & Schwarz GmbH & Co KG |
| Fox Corporation |
| LG Electronics Inc. |
| Others |
Supply & Pricing Matrix
Premium transmitter systems from Rohde & Schwarz and commodity set-top boxes from Asian contract manufacturers occupy opposite ends of a bifurcated pricing architecture that simultaneously rewards RF engineering depth and punishes undifferentiated assembly. This divergence manifests in procurement patterns where national multiplex operators in Germany and Brazil negotiate multi-year transmitter service contracts while Indonesian retail channels compete on set-top box unit economics.
Pricing Analysis
Three-tier pricing structure across precision transmitter, mid-range broadcast equipment, and consumer receiver levels dominates procurement negotiations. Price differentiation hinges on CE certification grade and after-sales service bundling, with German and French operators paying premiums for full material disclosure documentation under ECHA REACH requirements. Cost compression in the receiver tier is intensifying because of semiconductor foundry concentration in Taiwan and South Korea. Commercial broadcasters exhibit highest price sensitivity, while public service operators prioritize technical compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Munich, São Paulo, and Singapore anchor hub-and-spoke patterns for spare parts and field replacement units. Manufacturing concentration centers on Germany for precision transmitters, South Korea and Taiwan for integrated tuner chipsets, and China for set-top box assembly. Raw material dependencies include gallium nitride semiconductors, high-purity copper for RF transmission lines, and rare earth elements for antenna components. Single-source vulnerability in East Asian foundry capacity exposes equipment vendors to geopolitical disruption. Distribution runs through national broadcast equipment distributors with direct relationships to multiplex operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as nationwide digital switchover mandates in Brazil, India, and Indonesia create predictable equipment replacement cycles across the projection horizon.
For Market Incumbents: To counter platform substitution from over-the-top streaming services, Samsung Electronics and LG Electronics should deepen backward integration into gallium nitride semiconductor fabrication while Rohde & Schwarz expands transmitter service contracts into energy-efficiency retrofit programs. Channel control through exclusive distribution agreements with national multiplex operators remains essential for margin defense.
For New Entrants and Emerging Players: HEVC encoder-transmitter integration offers entry into fragmented procurement patterns where German and UK operators seek end-to-end workflow suppliers. White-space targets include Indonesia's gap-filler transmitter market for remote island coverage and India's liquid-cooled solid-state transmitter segment for carbon-compliant infrastructure. A direct equipment supply model bypassing state-owned broadcaster procurement channels unlocks commercial operator relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where RF engineering talent scarcity in Europe and Japan meets fragmented vendor qualification timelines in emerging markets. The five-to-ten-year viability frame favors precision transmitter manufacturers with captive semiconductor relationships over commodity receiver assemblers. Watch FCC and Anatel spectrum reallocation proceedings as inflection indicators for platform migration capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| HEVC Codec Integration | German DVB-T2 HD and UK Freeview Play deployments quadruple program capacity within existing spectrum allocations. |
| Liquid-Cooled Transmitter Deployment | India's Prasar Bharati procurement aligns with national carbon reduction frameworks and reduces operational expenditure. |
| ATSC 3.0 Infrastructure Buildout | US station groups in major metropolitan markets enable mobile reception and enhanced emergency alerting capabilities. |
| ISDB-Tb Certification Investment | Brazil's Anatel mandates create barrier to entry for transmitter vendors serving nationwide switchover completion. |
| Broadcast-Broadband Hybrid Platform | UK Freeview Play and German HbbTV implementations retain subscribers without dedicated return channel infrastructure. |
Research Methodology
Bottom-up residential and commercial end-use modeling reconciled against top-down transmitter and receiver supply tracking forms the analytical core of this study. Primary interviews with multiplex operations directors, RF engineering leads at national broadcasters, procurement managers at state-owned television networks, and semiconductor foundry account executives combined with secondary validation from FCC spectrum allocation filings, Anatel certification databases, ECHA REACH substance restriction updates, and BIS equipment registration records. Triangulation between demand-side deployment timelines and supply-side manufacturing capacity ensures consistency across the analysis window.
Historical trendline analysis of digital switchover completion rates and transmitter replacement cycles informed projection frameworks. Segmentation dimensions modeled include technology standard, component category, service type, and national regulatory cluster. CAGRs derived from equipment procurement volume tracking and average selling price trajectories across the modeling period incorporate HEVC migration timelines, spectrum reallocation proceedings, and energy-efficiency compliance deadlines as industry-specific forecast inputs.
The model holds under stable regulatory enforcement of analog switchover deadlines; deviation in spectrum reallocation timing or semiconductor supply disruption would shift equipment procurement trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cloud Television (TV) Market
Television
Mobile TV Market
Television
Pay TV Operator Market
Television
Curved Television Market
Television
HDTV Market
Television
Broadcasting and Cable TV Market
Television
Pay TV Market
Television
Television Market
Television
Free-To-Air (FTA) Service Market
Television
Television Advertising Market
Television
Print Newspapers and Magazines Market
Television
Pay TV Services Market
Television
Global Broadcast Equipment Market
Television
Digital TV Market
Television
Holographic TV Market
Television
TV Advertising Market