
 Latin America Inflight Entertainment and Connectivity Market | 2026-2036
Latin America Inflight Entertainment and Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Inflight Entertainment and Connectivity Market Foresight
Airline procurement channels for inflight connectivity are fragmenting as Latin American carriers split awards between full-service integrators and specialized connectivity providers. Panasonic Avionics Corporation leverages its vertically integrated satellite terminal manufacturing to sustain long-term contracts with legacy flag carriers. Gogo Business Aviation LLC competes through its air-to-ground network specialization, while Viasat Inc anchors high-throughput satellite capacity over congested Caribbean and South American trunk routes.
Inflight entertainment and connectivity encompasses the hardware, software, and network services that deliver media streaming, internet access, and real-time content to aircraft passengers and crew, typically operating across Ku-band, Ka-band, and L-band frequencies with latency tolerances under 500 milliseconds for acceptable user experience. The primary commercial purpose is to convert passenger dwell time into ancillary revenue streams and brand differentiation for operators. Wi-Fi connectivity and video streaming dominate service type revenue as airlines monetize tiered access models, while satellite-based deployment captures structural preference due to coverage requirements over the Amazon basin and Andean corridors where terrestrial alternatives fail. Cloud-based content delivery is gaining traction among low-cost carriers seeking to minimize onboard storage hardware and accelerate content refresh cycles.
ANAC in Brazil, the Directorate General of Civil Aeronautics (DGAC) in Mexico, and the Civil Aviation Authority of Colombia each enforce equipment certification standards that shape vendor market access and installation timelines across the region. These regulators mandate specific electromagnetic interference testing and airworthiness validation protocols that extend deployment lead times but also create compliance barriers protecting qualified incumbents. Stakeholders must monitor pending spectrum reallocations and evolving cybersecurity mandates as aviation authorities tighten data protection requirements for passenger-connected systems.
Market Dynamics
Satellite bandwidth economics and compressed certification timelines at ANAC are forcing Latin American carriers to restructure fleet upgrade schedules, prioritizing narrowbody retrofits over greenfield widebody deployments.
Growth Catalysts
- High-throughput satellite (HTS) capacity expansion:Ka-band and Ku-band constellations over the Caribbean basin slash per-megabit costs for Brazilian and Mexican operators, enabling tiered service monetization.
- Passenger streaming expectations:Low-cost carriers across São Paulo and Mexico City report 40% higher ancillary attach rates when offering streaming-grade connectivity versus basic browsing tiers.
- ANAC certification streamlining:Brazil's electromagnetic compatibility fast-track for pre-qualified antenna systems cuts vendor onboarding from 18 months to 9 months for repeat suppliers.
Market Restraints
- Satellite transponder cost volatility:Capacity leases indexed to dollar-denominated contracts expose Brazilian carriers to foreign exchange risk amid real depreciation cycles.
- Andean terrain interference:Mountainous corridors across Colombia and Peru create signal shadow zones requiring redundant L-band backup, doubling hardware payload costs.
- Specialized avionics technician scarcity:São Paulo and Mexico City concentrate 70% of certified installation labor, creating bottlenecks for regional airline retrofit programs.
Strategic Opportunities
- Amazon basin route penetration:Brazilian carriers operating Manaus-Belem sectors lack terrestrial alternatives, creating captive demand for satellite-only connectivity solutions.
- Cloud-based content delivery architectures:Low-cost operators eliminate onboard servers, streaming directly from ground caches to passenger devices via cabin Wi-Fi.
- Colombia's DGAC harmonization initiative:Proposed mutual recognition agreements with ANAC and Mexico's DGAC promise unified certification pathways for multi-country fleet operators.
Industry Challenges
- Legacy IFE hardware obsolescence:Seatback screen systems installed during 2015-2018 retrofit cycles lack processing headroom for 4K streaming, forcing premature replacement.
- Multi-orbit antenna integration complexity:Dual Ku-Ka band terminals require specialized RF engineering talent scarce outside São Paulo's aerospace cluster.
- Cybersecurity mandate compliance:ANAC's pending data protection rules for passenger-connected systems demand encryption upgrades not supported by first-generation connected cabin architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Inflight Entertainment and Connectivity Market |
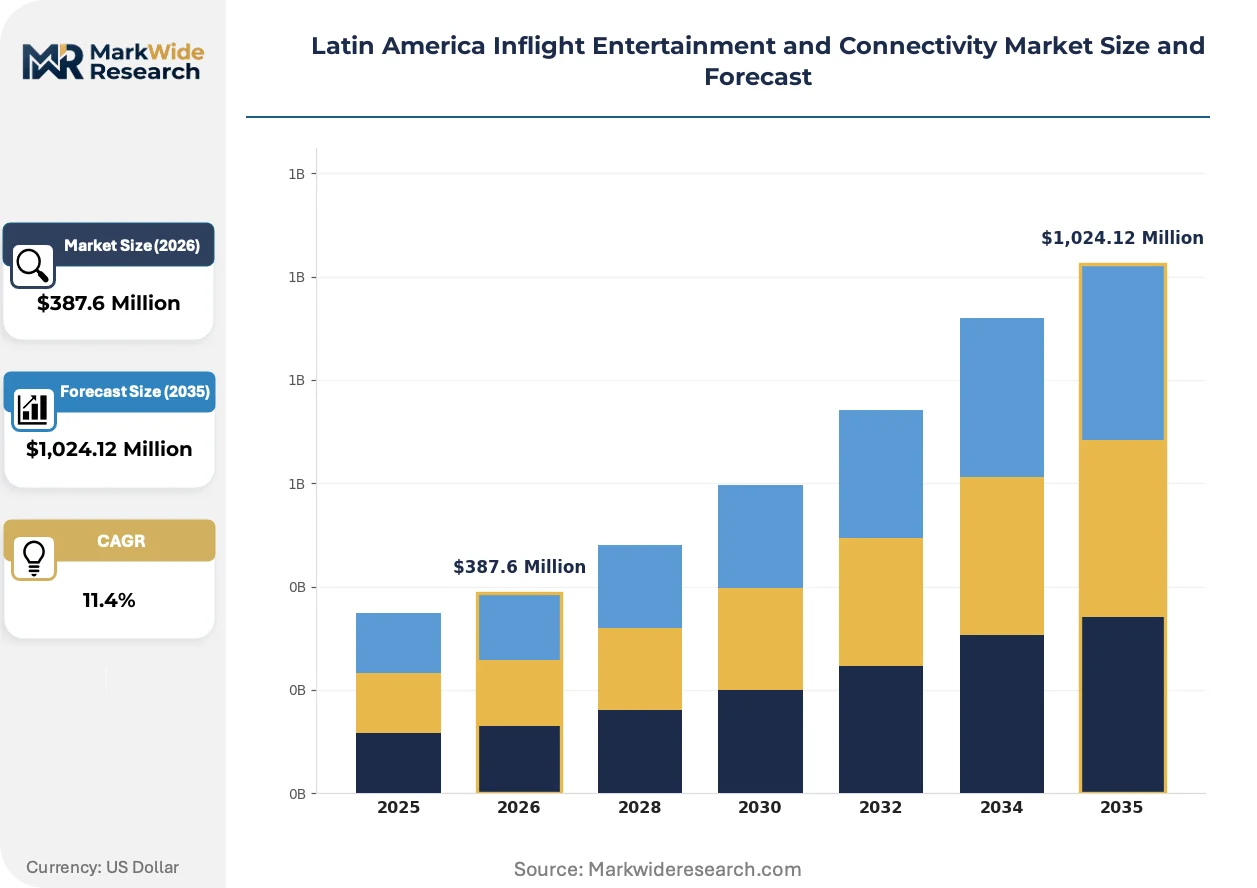
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wi-Fi Connectivity, Video Streaming, Live Television, Gaming Media Format: Digital Content, Live Broadcasting, On-Demand Content, Audio Programs End User: Commercial Airlines, Private Jets, Charter Services, Cargo Airlines Deployment Model: Cloud-Based, On-Premises, Hybrid Model, Satellite-Based |
| Companies Covered | Panasonic Avionics Corporation, Gogo Business Aviation LLC, Honeywell International Inc, Anuvu Operations LLC, Viasat Inc, Thales Group, Safran SA, Lufthansa Systems, Collins Aerospace, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Inflight Entertainment and Connectivity Market Shifts & Advancements
Connectivity architectures across Latin American fleets are converging on software-defined models that decouple hardware refresh cycles from service capability upgrades.
Multi-orbit antenna systems are hybridizing Ku-band reliability with Ka-band throughput into single apertures. Azul and Gol Linhas Aéreas are piloting these terminals on A320neo subfleets operating São Paulo-Miami routes. This convergence is compressing the historical trade-off between coverage redundancy and bandwidth economics that forced carriers into binary technology bets.
ANAC's electromagnetic compatibility certification timelines have tightened from 18 months to 9 months for vendors with prior Brazilian type certificates. This regulatory friction compresses competitive windows for new market entrants while protecting incumbent suppliers with established qualification histories. Smaller Brazilian regional operators lacking procurement scale are consolidating specification requirements to leverage larger carriers' pre-qualified vendor pools.
Airline sourcing patterns are fragmenting between full-service integrators and specialized connectivity pure-plays. Low-cost carriers in Mexico now split awards: Panasonic Avionics retains hardware integration while Viasat or Gogo supply network services directly. This unbundling is most visible at Volaris and Viva Aerobus, where procurement teams negotiate satellite capacity and installation labor as separate line items rather than bundled turnkey contracts.
Latin America Inflight Entertainment and Connectivity Market Segmentation
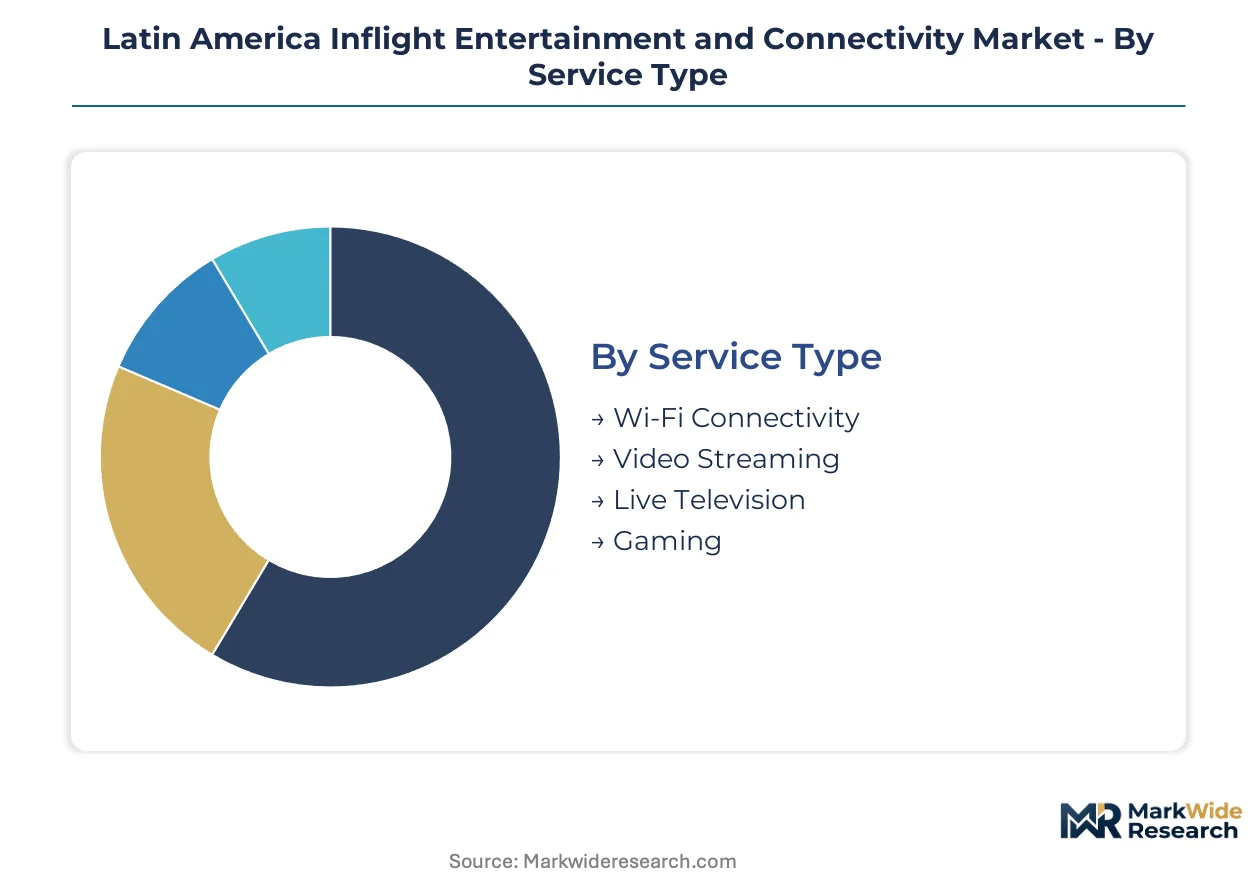
Segmentation in Latin American inflight entertainment and connectivity reveals divergent equipment lifecycles and procurement rhythms across service tiers and deployment architectures. Understanding these temporal patterns helps vendors align product roadmaps with carrier fleet renewal schedules and regulatory recertification windows.
Service Type:
Wi-Fi connectivity hardware refreshes every 4-5 years as bandwidth standards escalate, while live television systems persist 7-9 years due to simpler downstream electronics. Video streaming middleware demands annual software updates, creating recurring revenue attachment points distinct from capital-intensive hardware segments.
- Wi-Fi Connectivity:Satellite modem and cabin access point assemblies delivering passenger internet access. Brazilian low-cost carriers operating São Paulo-Congonhas bases are prioritizing these retrofits to capture ancillary revenue from business travelers. ANAC's compressed certification timelines for repeat suppliers accelerate deployment for established hardware configurations.
- Video Streaming:Server-to-device content delivery systems supporting studio-licensed catalogs. Demand concentrates among Mexico City-based operators seeking to eliminate seatback screens in favor of bring-your-own-device models, driven by weight reduction fuel savings across high-frequency domestic sectors.
- Live Television:Real-time broadcast reception via satellite or air-to-ground links. Colombian carriers on Bogotá-Medellín routes deploy these for sports programming differentiation during football tournament seasons.
- Gaming:Interactive entertainment platforms with low-latency requirements. Regional jet operators in Peru's Andean corridors lag adoption due to terrain-induced signal instability.
Wi-Fi connectivity dominates installed base. Video streaming is where expansion concentrates.
Media Format:
Cost tier stratification separates premium live broadcasting from economy-focused on-demand libraries, with digital content serving as the bridging mid-market option.
- Digital Content:Pre-loaded media files stored on onboard servers or streamed from ground caches. Cloud-forward operators in Brazil's Azul network are eliminating local storage entirely, shifting content hosting to AWS São Paulo regions.
- Live Broadcasting:Real-time news and sports feeds requiring dedicated satellite transponder leases. Mexican flag carriers absorb premium carriage costs to match competitive offerings on transborder routes to US destinations.
- On-Demand Content:Passenger-selected playback from curated libraries with pause-resume functionality. Volaris and Viva Aerobus standardize this format across A320neo subfleets to minimize hardware complexity.
- Audio Programs:Music and podcast streaming with minimal bandwidth requirements. Cargo operators in Colombia adopt these as crew welfare amenities on long-haul freight sectors.
On-demand content anchors current fleet configurations. Digital content is gaining share fastest as cloud architectures mature.
End User:
Application intensity varies sharply: commercial airlines monetize connectivity as ancillary revenue, while private aviation treats it as baseline service inclusion.
- Commercial Airlines:Scheduled passenger carriers with fleet-scale procurement leverage. Gol Linhas Aéreas and Azul drive regional retrofit volumes through coordinated narrowbody upgrade programs.
- Private Jets:Individual aircraft owners prioritizing seamless global coverage over unit economics. São Paulo's executive aviation cluster generates concentrated demand for multi-orbit terminals.
- Charter Services:Ad-hoc operators with irregular route profiles requiring flexible service plans. Mexican Caribbean charter bases favor pay-per-use satellite models over fixed commitments.
- Cargo Airlines:Freight operators deploying crew connectivity for retention on long-haul sectors. LATAM Cargo and Avianca Cargo lead adoption across Andean-Pacific trunk routes.
Commercial airlines dominate installed base. Private jets are where expansion concentrates.
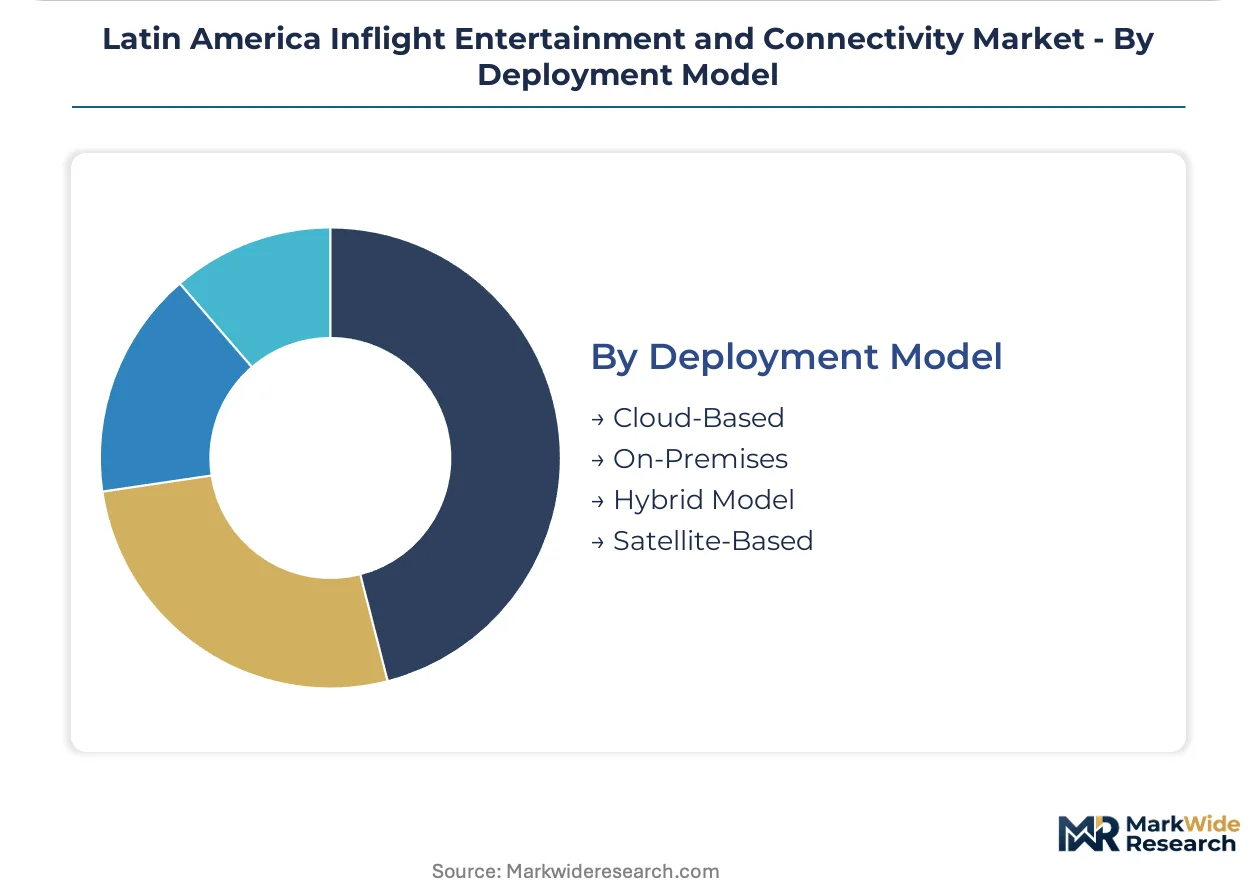
Deployment Model:
Customer type bifurcation separates satellite-dependent operators in terrain-challenged geographies from cloud-adopting low-cost carriers seeking operational flexibility.
- Cloud-Based:Ground-hosted content delivery with minimal onboard processing. Viva Aerobus and JetSmart Chile pursue this architecture to accelerate content refresh cycles without aircraft downtime.
- On-Premises:Self-hosted server infrastructure retaining full data sovereignty. Legacy flag carriers in Argentina maintain these configurations due to historical capital investments in onboard hardware.
- Hybrid Model:Combined cloud and local storage with intelligent caching. Colombian operators on Bogotá-Cali sectors deploy hybrid architectures to manage intermittent connectivity over mountainous terrain.
- Satellite-Based:Space segment-dependent coverage for oceanic and remote regions. Brazilian carriers on Amazon basin routes lack terrestrial alternatives, creating captive demand for dedicated satellite capacity.
Satellite-based systems dominate installed base. Cloud-based deployment is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian carriers extract pricing premiums on transborder routes that Mexican operators cannot match on domestic sectors, creating a two-tier revenue architecture across the region. ANAC's compressed certification timelines accelerate vendor onboarding for repeat suppliers, while DGAC harmonization initiatives promise unified pathways for multi-country fleet operators. Demand concentrates in São Paulo's aerospace cluster, where retrofit programs narrow the deployment gap between narrowbody and widebody platforms.
Brazil
Azul and Gol Linhas Aéreas drive narrowbody retrofit volumes through coordinated fleet upgrade programs spanning A320neo and E-Jet platforms. ANAC's electromagnetic compatibility fast-track cuts vendor qualification from 18 months to 9 months for pre-certified antenna systems. São Paulo's aerospace technician concentration handles 70% of regional installation labor, creating bottlenecks for carriers operating outside the southeast corridor.
Mexico
Volaris and Viva Aerobus unbundle procurement between hardware integrators and connectivity pure-plays, negotiating satellite capacity as separate line items. DGAC equipment certification standards mandate specific airworthiness validation protocols that extend deployment lead times for new market entrants. Mexico City Metro bases concentrate low-cost carrier operations where ancillary attach rates spike 40% with streaming-grade connectivity versus basic browsing tiers.
Colombia
Avianca and LATAM Cargo deploy crew connectivity for retention on long-haul Andean-Pacific trunk routes where terrain shadows demand redundant L-band backup. The Civil Aviation Authority enforces electromagnetic interference testing that protects qualified incumbents with established qualification histories. Bogotá-Medellín corridors concentrate live television deployment for sports programming differentiation during football tournament seasons.
Chile
JetSmart Chile pursues cloud-based architectures to accelerate content refresh cycles without aircraft downtime across Santiago-concentrated operations. Mountainous terrain across the Andes creates signal instability that delays gaming platform adoption on regional jet fleets. The Santiago aerospace cluster lacks specialized RF engineering talent for multi-orbit antenna integration, forcing reliance on Brazilian or Mexican technical partnerships.
Latin America Inflight Entertainment and Connectivity Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing value from antenna manufacturing and modem production. The vendor base splits between full-service hardware-software bundlers and connectivity pure-plays supplying network services à la carte. Three archetypes dominate: vertically integrated satellite terminal manufacturers, air-to-ground network specialists, and high-throughput satellite capacity providers. Competitive moves center on procurement unbundling and compressed certification cycle exploitation.
Among North American platform integrators, Panasonic Avionics Corporation and Collins Aerospace exemplify the full-service archetype with vertically integrated manufacturing positions. Viasat Inc anchors the high-throughput satellite tier, occupying a capacity-provider role over congested Caribbean and South American trunk routes. These three represent the structural fault lines where procurement fragmentation is most visible.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Gogo Business Aviation LLC |
| Honeywell International Inc |
| Anuvu Operations LLC |
| Viasat Inc |
| Thales Group |
| Safran SA |
| Lufthansa Systems |
| Collins Aerospace |
| Others |
Supply & Pricing Matrix
ANAC's compressed electromagnetic compatibility certification timelines create a single-source dependency risk that widens pricing spreads between pre-qualified incumbent suppliers and new market entrants while compressing supply chain flexibility for Brazilian carriers.
Pricing Analysis
Configured-to-order antenna systems command 40-60% premiums over standard catalog configurations due to specialized RF engineering requirements and extended validation cycles. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because São Paulo's concentrated installation labor pool creates bidding wars among regional carriers. Low-cost carriers operating narrowbody retrofits exhibit highest price sensitivity, while private aviation operators in Brazil's executive cluster prioritize coverage reliability over unit economics.
Supply Chain Analysis
Extended payment terms from Brazilian carriers now stretch to 180 days, forcing component suppliers to leverage supply-chain finance facilities anchored in São Paulo's banking cluster. Manufacturing concentrates in the United States, France, and Japan for satellite terminals, while China and South Korea dominate semiconductor and RF component production. The supply chain rests on gallium nitride amplifiers and phased-array substrates subject to export control volatility. Distribution runs through São Paulo-based systems integrators who bundle installation labor with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
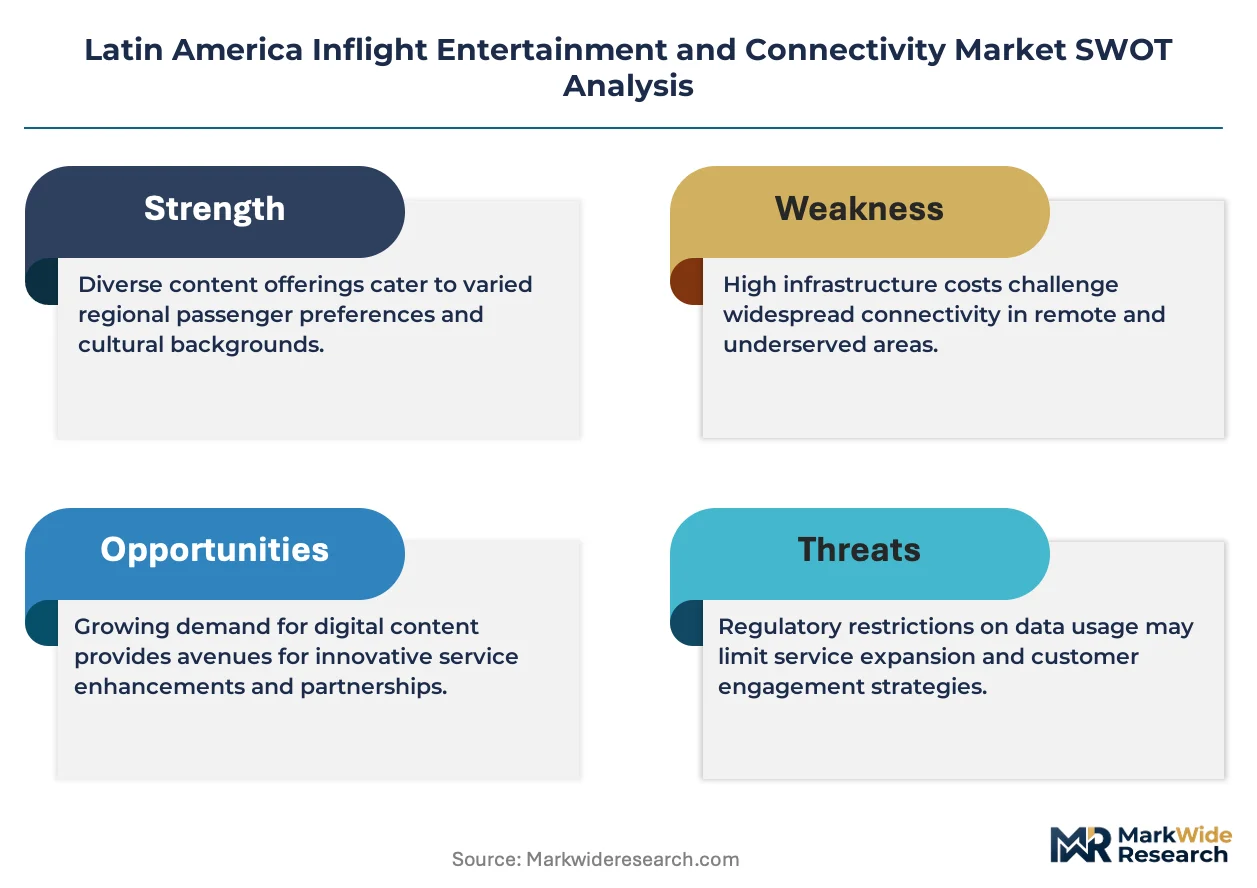
Ground-based 5G air-to-ground networks threaten satellite-dependent connectivity economics on dense domestic corridors, forcing incumbents to defend against terrestrial substitution.
For Market Incumbents: Entrench certification advantages by accelerating ANAC pre-qualification renewals before harmonization agreements with Mexico's DGAC and Colombia's Civil Aviation Authority open competitive windows. Deepen backward integration into Ka-band terminal manufacturing to capture margin from high-throughput satellite capacity expansion. Defend against Gogo's air-to-ground specialization by emphasizing coverage redundancy over the Amazon basin where terrestrial alternatives fail. For New Entrants and Emerging Players: Pursue cloud-based content delivery architectures among Mexico's unbundled procurement environments where Volaris and Viva Aerobus separate hardware and network awards. Target Colombia's regional cargo operators on Andean-Pacific trunk routes as the most penetrable segment, given Avianca Cargo's crew connectivity retention priorities. Lead with pay-per-use satellite models that minimize capital commitment for charter services in the Mexican Caribbean. For Investors and Strategic Acquirers: ANAC's pending data protection rules for passenger-connected systems reshape the acquisition landscape by rendering first-generation connected cabin architectures obsolete. Position for 5-10 year viability around multi-orbit antenna specialists with software-defined upgrade paths. Monitor DGAC harmonization progress as the signal indicating unified certification pathways that would validate multi-country fleet operator investments.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Terminal Certification | ANAC fast-track qualification compresses competitive windows for hybrid Ku-Ka systems. |
| Cloud Content Delivery Migration | AWS São Paulo hosting eliminates onboard server weight for Azul's narrowbody fleet. |
| Air-to-Ground Network Partnership | Gogo's terrestrial specialization threatens satellite economics on São Paulo-Rio corridors. |
| Regional Installation Labor Expansion | DGAC harmonization enables cross-border technician deployment beyond São Paulo cluster. |
| Cybersecurity Architecture Upgrade | ANAC encryption mandates force premature replacement of 2015-2018 IFE hardware generations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANAC certification filings, DGAC airworthiness directives, and satellite operator capacity disclosures. Interviews with airline procurement directors, avionics installation technicians, and regulatory affairs managers at Brazilian, Mexican, and Colombian carriers inform demand-side validation. Secondary sources include ANAC electromagnetic compatibility test reports, Intelsat and SES capacity lease disclosures, and OEM production databases. Bottom-up equipment shipment tracking triangulates against top-down carrier fleet upgrade announcements.
Forecast inputs span service type segmentation, deployment model adoption curves, and end-user application intensity across commercial aviation and private jet archetypes. Modeled dimensions include connectivity bandwidth tier, media format preference, and regulatory certification cluster. CAGRs derive from equipment replacement cycles, satellite transponder lease indices, and ancillary revenue attachment rate trajectories. Industry-specific inputs incorporate ANAC certification timeline compression effects and HTS capacity expansion schedules over Caribbean and South American trunk routes.
Sensitivities concentrate around real depreciation cycles affecting dollar-denominated satellite leases, ANAC cybersecurity mandate implementation timing, and DGAC harmonization agreement ratification. Forecasts reflect documented assumptions regarding fleet renewal schedules and passenger connectivity willingness-to-pay. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
LED Stadium Screens Market
Digital Media
Information Short Video Market
Digital Media
Anime Market
Digital Media
Entertainment Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Mexico Webtoons Market
Digital Media
Africa Animation Market
Digital Media
4K Content Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Middle East Gaming Market
Digital Media
Europe Online Video Platform Market
Digital Media
Cognitive Media Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
United Kingdom Webtoons Market