
 Middle East and Africa Programmatic Advertising Market | 2026-2036
Middle East and Africa Programmatic Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Programmatic Advertising Market Foresight
Data science talent scarcity across the Middle East and Africa is redrawing competitive boundaries for automated advertising platforms. Publicis Groupe leverages its regional agency networks to embed local trading desk expertise in Dubai and Johannesburg. Microsoft anchors cloud infrastructure investments that underpin real-time bidding latency requirements for Gulf markets. Criteo specializes in retail media retargeting, sustaining performance advertiser budgets amid currency volatility.
Middle East and Africa programmatic advertising denotes the algorithmic buying and selling of digital ad impressions through software platforms, executing transactions within milliseconds via real-time bidding protocols and audience data matching. The primary commercial purpose centers on eliminating manual insertion orders while optimizing media spend toward measurable consumer actions across fragmented publisher ecosystems. Mobile advertising commands structural priority given smartphone penetration rates that exceed desktop access across Kenya, Egypt, and Saudi Arabia, though video advertising captures expanding CPM premiums as connected TV inventory localizes. Real-time bidding dominates transaction volume, yet private marketplaces concentrate brand safety budgets from multinational FMCG and automotive advertisers seeking curated publisher environments.
Saudi Arabia's Communications and Information Technology Commission enforces data sovereignty requirements that localize consumer information processing, compelling platform operators to establish in-country server infrastructure. South Africa's Protection of Personal Information Act constrains third-party data brokerage, reshaping audience targeting toward publisher first-party cohorts and contextual signals. Stakeholders must weigh compliance investment thresholds against addressable market depth when prioritizing country entry sequences across the region's divergent regulatory maturity levels.
Market Dynamics
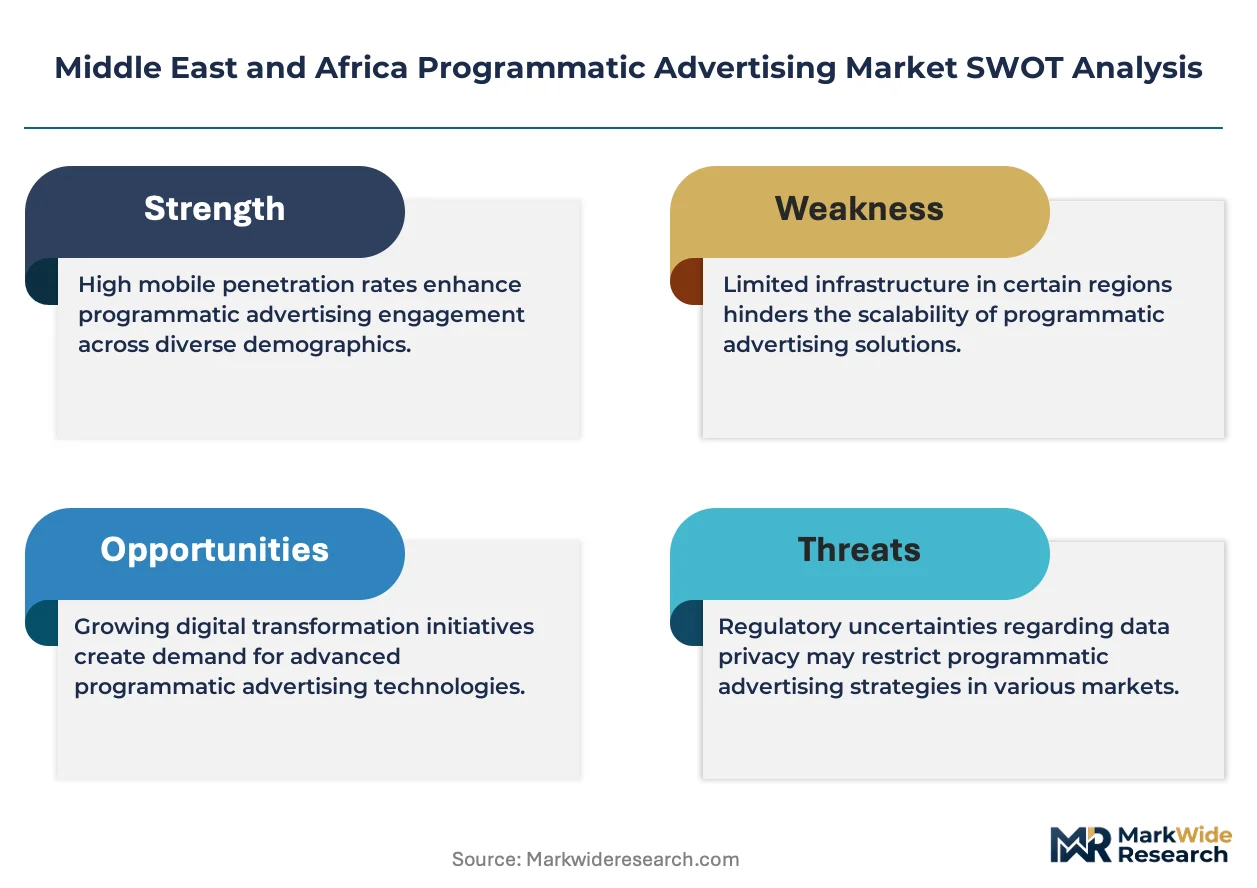
Data localization mandates from Saudi Arabia's Communications and Information Technology Commission and South Africa's Protection of Personal Information Act are forcing programmatic platforms to rebuild cloud infrastructure inside national borders, raising fixed costs while creating defensive moats for compliant operators.
Growth Catalysts
- Smartphone penetration thresholds:Mobile-first inventory access across Kenya, Egypt, and Saudi Arabia now exceeds desktop reach, concentrating advertiser spend on in-app and mobile web formats.
- Retail media networks:E-commerce marketplaces across the Gulf Cooperation Council are opening proprietary first-party data pools to programmatic buyers, bypassing deprecating third-party cookies.
- POPIA compliance adaptation:South Africa's data protection framework is redirecting targeting budgets toward publisher-direct private marketplaces and contextual signal providers.
Market Restraints
- Data center capex concentration:In-country server requirements for Saudi and UAE markets demand capital commitments that smaller DSPs cannot underwrite.
- Currency volatility exposure:Nigerian naira and Egyptian pound fluctuations compress CPM yields for dollar-denominated platform contracts.
- Cross-border data friction:Divergent national telecom regulator stances on consumer information flows fragment audience scale across Morocco, Israel, and Gulf markets.
Strategic Opportunities
- Connected TV inventory localization:Premium video publishers in Dubai and Johannesburg are building addressable television stacks for brand safety-conscious FMCG advertisers.
- First-party data co-ops:Publisher consortiums in Nigeria are pooling authenticated user graphs to compete with walled garden targeting precision.
- Real-time bidding latency arbitrage:Microsoft Azure and AWS regional edge deployments in Cape Town and Dubai enable sub-100-millisecond auction completion for performance buyers.
Industry Challenges
- Data science talent scarcity:Trading desk operations in Lagos and Cairo compete with fintech and telecom sectors for machine learning engineers capable of building bid optimization algorithms.
- Legacy insertion order workflows:Established media agencies across the region maintain manual buying relationships that slow automated budget migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Programmatic Advertising Market |
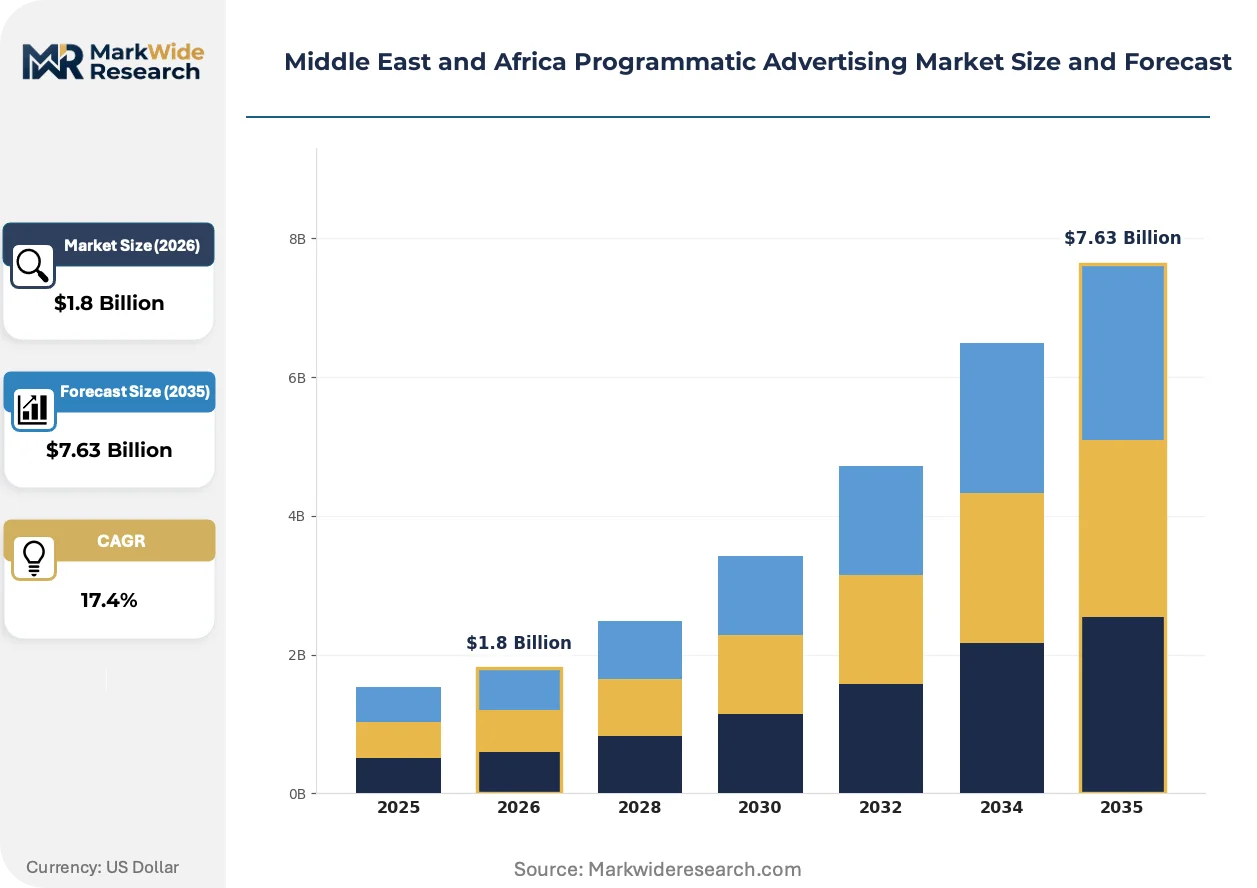
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.63 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Display Advertising, Video Advertising, Mobile Advertising, Social Media Advertising Industry Vertical: Retail, Automotive, Telecommunications, Travel Target Audience: Millennials, Gen Z, Professionals, Families Buying Method: Real-Time Bidding, Direct Deals, Private Marketplaces, Programmatic Guaranteed |
| Companies Covered | Magnite, Publicis Groupe, Adobe, Smaato, MGID, Microsoft, Omnicom Group, Digital Turbine, Criteo, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Programmatic Advertising Market Shifts & Advancements
Identity resolution infrastructure is diverging between authenticated cohort models and contextual signal stacks, with platform operators placing parallel bets rather than converging on a single replacement for deprecated tracking mechanisms.
Server-side ad insertion technology is fragmenting the competitive landscape for video inventory monetization. Premium broadcasters in Dubai and Johannesburg are adopting SSAI to bypass client-side ad blockers and enable frame-accurate podding. This capability is compressing margins for traditional client-side VAST tag vendors while opening new inventory pools for demand-side platforms with server-to-server integration capacity.
South Africa's Protection of Personal Information Act enforcement is tightening consent requirements for audience data brokerage. The regulation is redirecting programmatic spend toward publisher-direct private marketplace deals and contextual targeting providers. Multinational FMCG advertisers operating across Johannesburg and Cape Town are renegotiating agency contracts to mandate first-party data provenance disclosures.
Buying patterns among Gulf Cooperation Council e-commerce retailers are rotating toward outcome-based performance guarantees rather than impression-based CPM commitments. Retail media networks in Riyadh and Dubai are unbundling managed service fees from media costs, exposing pure-play DSPs to price compression. This shift is most visible in app install and purchase conversion campaigns where attribution windows have tightened to seven-day click-through models.
Middle East and Africa Programmatic Advertising Market Segmentation
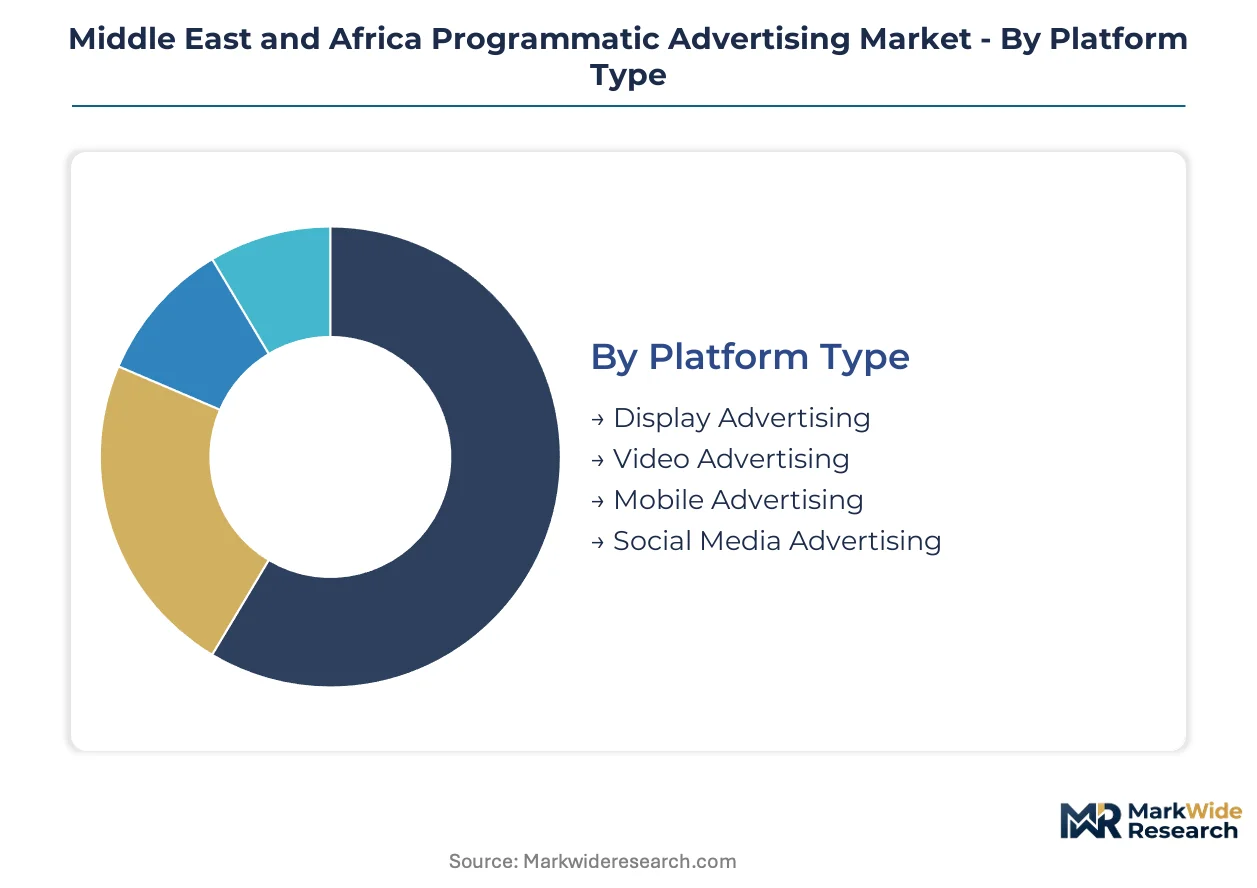
Platform operators across the Middle East and Africa must align technology stacks with divergent regulatory maturity and device penetration patterns. Segmentation reveals where data localization costs concentrate and which audience pools justify compliance investment.
Platform Type:
Saudi Arabia's data sovereignty mandates and South Africa's POPIA enforcement create divergent infrastructure requirements across format categories.
- Mobile Advertising:In-app and mobile web inventory dominates transaction volume across Kenya, Egypt, and Saudi Arabia where smartphone penetration exceeds desktop access. Advertisers concentrate spend on rewarded video and interstitial formats that accommodate constrained screen real estate and variable connectivity.
- Video Advertising:Connected TV and premium publisher inventory commands expanding CPM premiums as broadcasters in Dubai and Johannesburg deploy server-side ad insertion to bypass client-side blockers. Brand safety-conscious FMCG and automotive advertisers drive private marketplace demand for frame-accurate podding capabilities.
- Display Advertising:Standard banner and native formats serve as the programmatic entry point for mid-market advertisers across Nigeria and Egypt, though viewability measurement remains fragmented across local publisher networks.
- Social Media Advertising:Walled garden inventory on regional platforms operates outside open RTB protocols, capturing budgets from advertisers prioritizing authenticated user graphs over independent DSP reach.
Mobile Advertising handles the majority of throughput; Video Advertising is the fastest mover on share.
Industry Vertical:
Vertical concentration tracks e-commerce infrastructure maturity and foreign exchange stability across national markets.
- Retail:Gulf Cooperation Council e-commerce marketplaces are unbundling managed service fees from media costs, exposing pure-play DSPs to price compression as retailers demand outcome-based performance guarantees tied to seven-day attribution windows.
- Automotive:Premium brand advertisers in Johannesburg and Riyadh prioritize private marketplace environments with verified publisher provenance, redirecting budgets from open exchange inventory amid viewability concerns.
- Telecommunications:Carrier-owned data assets in Nigeria and South Africa face POPIA and national telecom regulator constraints on third-party brokerage, pushing operators toward first-party activation partnerships.
- Travel:Recovery-dependent spend from Dubai and Cairo-based hospitality groups concentrates on seasonal flight and booking campaigns with flexible cancellation terms complicating conversion attribution.
Retail commands the largest committed budgets; Automotive is expanding most quickly as premium localization accelerates.
Target Audience:
Demographic targeting precision diverges between authenticated cohort models and contextual signal stacks as identity resolution infrastructure fragments.
- Gen Z:Short-form video and gaming app engagement concentrates demand in Saudi Arabia and Egypt, where TikTok and local platform inventory captures discretionary spend from fashion and entertainment advertisers.
- Millennials:Finance and family-oriented purchase intent signals drive retargeting investment across Lagos and Nairobi, though cross-device graph matching remains unreliable outside walled garden environments.
- Professionals:B2B and premium service advertisers in Dubai and Johannesburg target LinkedIn and niche publisher inventory with account-based targeting that bypasses consumer data protection constraints.
- Families:Household purchase decision-makers activate on connected TV and parenting content verticals, with Saudi and UAE markets showing strongest programmatic video adoption for this segment.
Gen Z delivers the highest engagement rates; Professionals show the steepest expansion trajectory as B2B platforms localize.
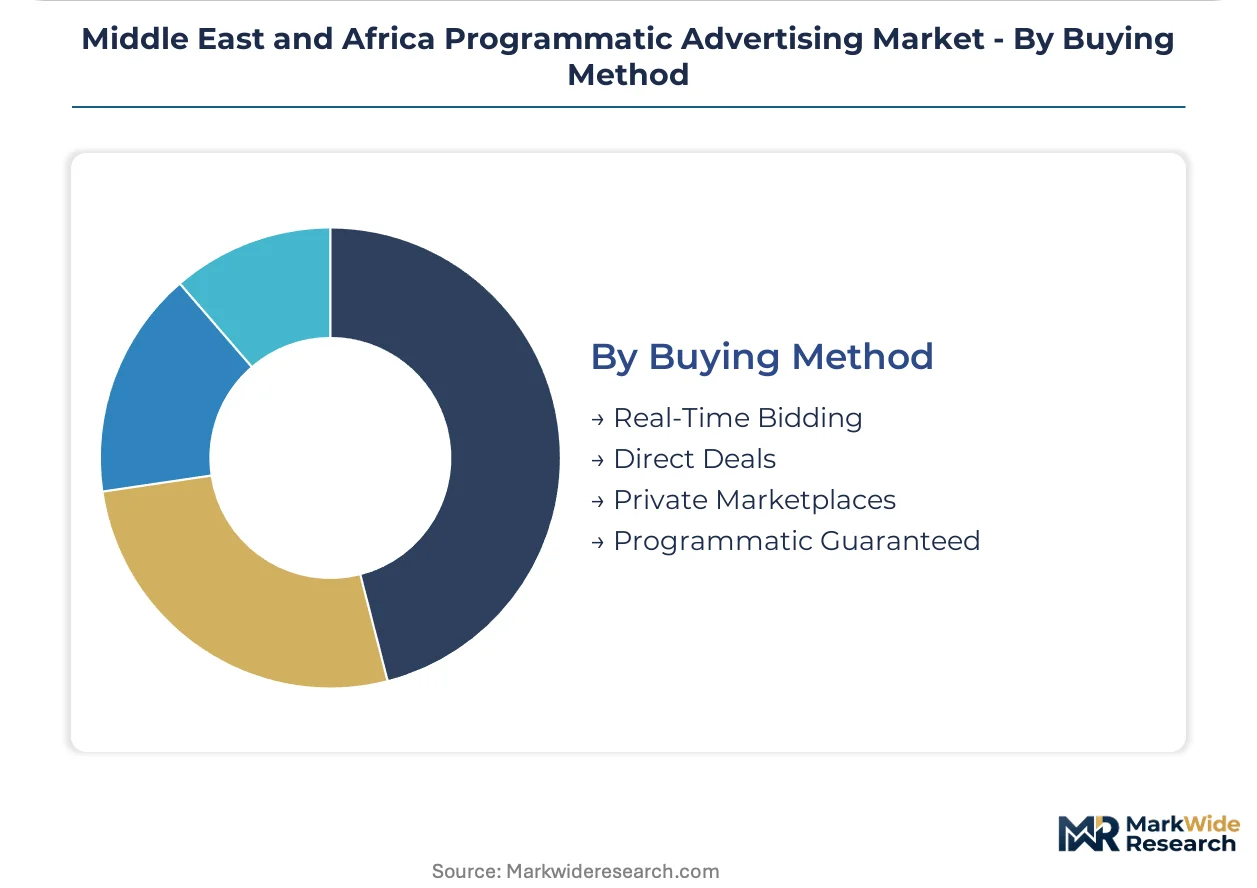
Buying Method:
Transaction mechanics reflect advertiser risk tolerance and publisher inventory scarcity across regulated markets.
- Real-Time Bidding:Open auction volume dominates performance advertiser activity, though latency requirements demand Microsoft Azure and AWS regional edge deployments in Cape Town and Dubai to achieve sub-100-millisecond auction completion.
- Private Marketplaces:Curated publisher environments concentrate brand safety budgets from multinational FMCG advertisers, with South Africa's POPIA enforcement accelerating migration from open exchange to direct-sold programmatic.
- Programmatic Guaranteed:Fixed-price automation of reserved inventory appeals to broadcasters in Johannesburg and Dubai seeking yield optimization without auction volatility, though workflow adoption lags legacy insertion order habits.
- Direct Deals:Manual negotiation of programmatic execution terms persists among established media agencies across the region, slowing automated budget migration despite platform efficiency advantages.
Real-Time Bidding processes the greatest transaction volume; Private Marketplaces are gaining share fastest as compliance constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Communications and Information Technology Commission anchors regional regulatory gravity through data sovereignty mandates that reshape cloud infrastructure deployment across the Middle East and Africa programmatic advertising market.
Saudi Arabia
E-commerce retailers in Riyadh and Jeddah drive automated media buying adoption as smartphone penetration exceeds desktop access. The Communications and Information Technology Commission enforces strict data localization requirements compelling platforms to establish in-country server infrastructure. Eastern Province industrial clusters host expanding data center capacity serving Gulf Cooperation Council markets.
United Arab Emirates
Dubai-based broadcasters and premium publishers concentrate connected TV inventory investment for brand safety-conscious FMCG advertisers. The country's national telecom regulator maintains data flow standards that influence regional platform compliance architecture. Dubai Internet City clusters trading desk operations and cloud edge deployments from Microsoft Azure and AWS.
South Africa
Johannesburg and Cape Town anchor demand for private marketplace environments as Protection of Personal Information Act enforcement tightens consent requirements. The national data protection authority constrains third-party data brokerage, redirecting programmatic spend toward publisher-direct deals. Sandton financial district hosts agency trading desks competing with fintech sectors for data science talent.
Nigeria
Lagos concentrates mobile-first programmatic inventory demand amid currency volatility compressing CPM yields for dollar-denominated contracts. The country's national telecom regulator oversees consumer data protection standards that fragment cross-border audience scale. Victoria Island media agencies maintain manual insertion order workflows slowing automated budget migration.
Egypt
Cairo-based hospitality groups and retail advertisers activate seasonal campaigns with flexible attribution windows complicating conversion measurement. The country's national data protection framework remains under development, creating uncertainty for platform operators weighing compliance investment thresholds. New Cairo technology corridors attract trading desk operations seeking cost-advantaged talent pools.
Middle East and Africa Programmatic Advertising Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with holding company agency networks and cloud infrastructure providers commanding defensive positions through compliance-advantaged operations. The market structure rewards players with capital capacity to underwrite in-country server deployments and local trading desk expertise. Three archetypes dominate: vertically integrated agency-holding networks, hyperscale cloud infrastructure operators, and performance-focused ad tech specialists. Competitive moves concentrate on geographic expansion through regulatory-compliant infrastructure builds and strategic partnerships with local publisher consortiums.
Within the integrated agency network tier, Publicis Groupe and Omnicom Group exemplify archetypes embedding regional trading desk capabilities in Dubai and Johannesburg. Microsoft anchors the hyperscale infrastructure vector through Azure regional edge deployments enabling sub-100-millisecond auction completion. Criteo occupies a specialist position representing retail media retargeting expertise sustaining performance advertiser budgets amid currency volatility. These three players illustrate how compliance capacity and latency optimization now outweigh pure algorithmic sophistication in competitive positioning.
| Leading Market Players |
|---|
| Magnite |
| Publicis Groupe |
| Adobe |
| Smaato |
| MGID |
| Microsoft |
| Omnicom Group |
| Digital Turbine |
| Criteo |
| Others |
Supply & Pricing Matrix
Ninety-day server deployment cycles for in-country data infrastructure anchor cost structures across Saudi Arabia and South Africa, compressing margin flexibility for programmatic platforms while amplifying pricing power for compliant hyperscale cloud operators. This lead-time rigidity concentrates buyer leverage among Gulf Cooperation Council retailers with outcome-based performance contracts.
Pricing Analysis
Dubai-to-Lagos CPM spreads widen during Nigerian naira depreciation cycles, exposing dollar-denominated platform contracts to foreign exchange volatility. Pricing stratifies across premium private marketplace inventory, standard open-exchange mobile formats, and economy-tier remnant display, with differentiation resting on brand safety certification and latency performance. Cost compression in the standard tier intensifies because retail media networks unbundle managed service fees from media costs. Small and mid-market advertisers in Egypt and Nigeria show greatest price sensitivity, while multinational FMCG buyers in Riyadh and Johannesburg prioritize verified publisher provenance over rate efficiency.
Supply Chain Analysis
Strait of Hormuz transit routes underpin sub-100-millisecond latency requirements for real-time bidding infrastructure serving Gulf markets. Cloud compute capacity concentrates in Saudi Arabia, United Arab Emirates, and South Africa, with raw material dependencies spanning server hardware components, fiber optic cable, and redundant power systems. Single-source vulnerability runs through Microsoft Azure and AWS regional edge deployments in Dubai and Cape Town. Distribution runs through agency trading desks embedded in Johannesburg's Sandton district and Dubai Internet City clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to e-commerce advertising budget replenishment following regional currency stabilization periods.
For Market Incumbents: Secure defensive moats through POPIA-compliant data infrastructure in Johannesburg and CITC-certified server deployments in Riyadh. Incumbents should deepen backward integration into publisher first-party data partnerships to counter retail media network disintermediation. Capacity addition in Eastern Province industrial clusters reinforces Gulf Cooperation Council market position against emerging regional challengers. For New Entrants and Emerging Players: Differentiate on contextual signal specialization for South African automotive and FMCG advertisers migrating from deprecating third-party cookie targeting. White-space concentration sits with mid-market Egyptian retail advertisers seeking seven-day attribution window solutions. Lagos-based mobile-first inventory access offers the most penetrable geography, with go-to-market leverage through fintech sector data science talent recruitment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because data localization mandates create durable competitive barriers with high capital replacement costs. Acquisition targets should display established in-country server presence and local trading desk expertise across multiple jurisdictions. The signal to watch is Saudi Communications and Information Technology Commission enforcement intensity against non-compliant platform operators.| Strategic Initiative | Industry Significance |
|---|---|
| In-Country Data Center Deployment | CITC and POPIA mandates make local server presence a license-to-operate requirement for Saudi and South African markets. |
| Publisher First-Party Data Partnership | Retail media networks and publisher consortiums bypass deprecating third-party cookies for authenticated audience targeting. |
| Trading Desk Talent Acquisition | Lagos and Cairo operations compete with fintech sectors for machine learning engineers capable of bid optimization. |
| Connected TV Inventory Localization | Dubai and Johannesburg broadcasters deploy server-side ad insertion for frame-accurate podding capabilities. |
| Regional Edge Computing Expansion | Microsoft Azure and AWS Cape Town deployments enable sub-100-millisecond auction completion for performance buyers. |
Research Methodology
A standing panel of programmatic trading desk directors, cloud infrastructure procurement leads, publisher monetization heads, and national telecom regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from Communications and Information Technology Commission filings, Protection of Personal Information Act enforcement notices, hyperscaler regional capex disclosures, and Gulf Cooperation Council e-commerce transaction data. Bottom-up segment sizing and top-down market reconciliation ensured triangulation integrity.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled platform type, industry vertical, target audience demographic, and buying method dimensions alongside regulatory compliance tier and latency performance band. CAGRs were derived from segment-level trajectory analysis incorporating smartphone penetration thresholds, retail media network expansion rates, and currency-adjusted CPM yield patterns.
The analysis sits within stated boundaries; outcomes outside current Saudi data sovereignty and South African consent enforcement trajectories would require recalibration. Forecasts reflect documented assumptions regarding e-commerce advertising budget cyclicality and cross-border data flow regulatory stances. Practitioners should keep alternative scenarios live as Nigerian naira stability and Egyptian data protection framework finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market