
 TV Advertising Market | 2026-2036
TV Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
TV Advertising Market Insights
Programmatic addressability is recalibrating inventory valuation across linear and digital TV convergence. Comcast Corporation leverages its broadband-video bundle to control premium ad-tech infrastructure. The Walt Disney Company anchors streaming ad loads through Hulu and Disney+ tiered inventory. WPP plc sustains agency dominance via data-integrated media buying platforms.
TV advertising comprises audiovisual promotional content distributed through broadcast, cable, satellite, and internet-protocol television networks, typically delivered in 15- to 60-second spot lengths with audience measurement based on gross rating points and impression verification. Its commercial purpose centers on mass-reach brand awareness campaigns with demographic targeting validated by panel-based and return-path data. Streaming within broadcast type captures the fastest expansion as cord-cutting shifts inventory to connected TV environments. Standard commercial formats within ad format retain the largest revenue pool despite declining linear viewership. Automotive and FMCG within industry vertical dominate upfront commitments due to high-consideration purchase cycles and household penetration metrics.
The FCC governs ownership caps and political advertising disclosure in the United States, while the EU Audiovisual Media Services Directive harmonizes ad frequency limits across member states. China's SAMR and MIIT enforce content review and data localization for programmatic platforms operating within its jurisdiction. India's TRAI mandates tariff transparency for broadcast channels carrying advertising. Stakeholders must monitor measurement standardization battles between panel-based and census-level methodologies as currency fragmentation threatens pricing coherence.
Market Dynamics
Programmatic addressability is collapsing the valuation gap between linear and digital TV inventory, forcing broadcasters to rebuild yield management systems around real-time impression-level bidding rather than upfront guaranteed rating points.
Growth Catalysts
- Connected TV penetration:Streaming adoption in the United States, China, and India is migrating premium audiences to IP-delivered environments where addressable advertising commands measurable CPM premiums over panel-based linear equivalents.
- EU Audiovisual Media Services Directive:Cross-border harmonization of ad frequency limits and content standards is reducing compliance fragmentation for pan-European campaigns, lowering operational barriers to multi-territory media buying.
- E-commerce advertiser influx:Direct-to-consumer brands now anchor upfront commitments previously dominated by automotive and FMCG verticals, injecting new demand into scatter markets and compressed booking windows.
Market Restraints
- Measurement currency fragmentation:Competing methodologies between panel-based Nielsen systems and census-level return-path data from smart TVs are creating pricing opacity and contract disputes between buyers and sellers.
- Linear inventory oversupply:Cord-cutting is hollowing out broadcast and cable audiences faster than CPM inflation can compensate, compressing revenue per available rating point in mature markets.
- Data localization mandates:China's SAMR and MIIT requirements for domestic storage of viewer data are raising infrastructure costs for global demand-side platforms operating within the jurisdiction.
Strategic Opportunities
- Retail media convergence:Walmart and Amazon are expanding their closed-loop attribution capabilities into connected TV, creating new inventory channels where purchase data directly informs audience targeting.
- India's tariff transparency regime:TRAI-mandated pricing disclosures for broadcast channels are reducing information asymmetry and enabling more efficient programmatic access to regional language inventory.
- Political advertising cycles:FCC disclosure requirements and cyclical election spending are creating predictable demand spikes that broadcasters can pre-position through advance inventory allocation systems.
Industry Challenges
- Ad-tech talent scarcity:The intersection of television operations and programmatic engineering requires specialized fluency in both legacy traffic systems and real-time bidding protocols, a skill set concentrated among a narrow cohort of practitioners.
- Legacy system integration:Broadcast traffic and billing platforms built for guaranteed upfront deals require expensive middleware development to interface with demand-side platform APIs, delaying addressable rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TV Advertising Market |
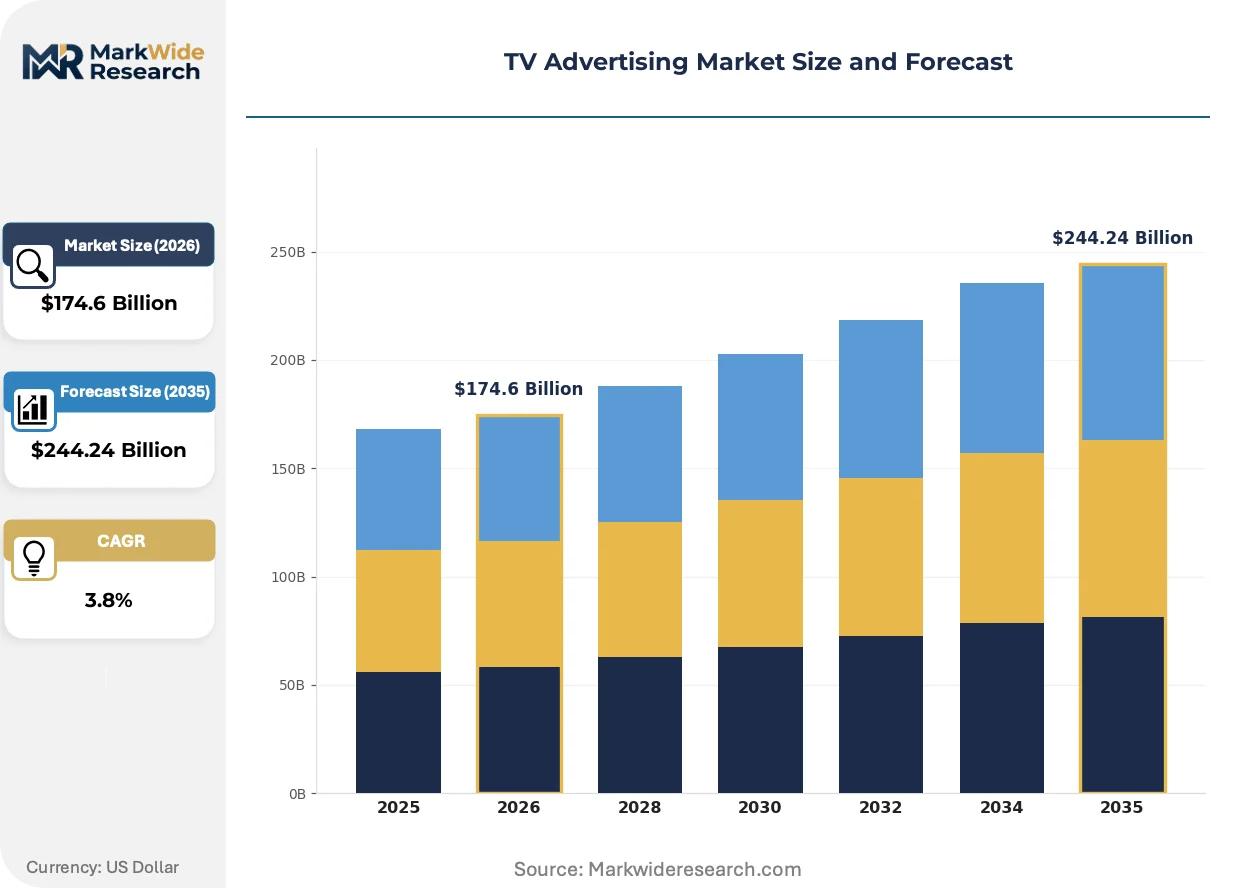
| Market Size in 2026 | $174.6 Billion |
| Market Size in 2035 | $244.24 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Standard Commercial, Infomercial, Sponsorship, Branded Content Broadcast Type: Live Broadcasting, Cable, Satellite, Streaming Audience Demographic: Children, Teens, Adults, Seniors Industry Vertical: Automotive, Consumer Electronics, FMCG, Healthcare |
| Companies Covered | Comcast Corporation, The Walt Disney Company, Fox Corporation, NBCUniversal Media, LLC, AT&T Inc., Sony Pictures Television, WPP plc, Omnicom Group Inc., Publicis Groupe SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TV Advertising Market Trends and Innovations
Television advertising infrastructure is bifurcating between remnant automation and premium direct sales, with technology investments concentrating on the middleware layer that bridges these historically separate transaction modes.
Server-side ad insertion (SSAI) is expanding into live streaming environments, stitching personalized commercials into content streams at the distribution edge rather than the client device. Broadcasters adopting SSAI include Hulu, Peacock, and major sports leagues seeking to eliminate ad-blocking and improve quality of experience. The structural consequence is that linear-simulcast inventory is expanding into addressable formats previously reserved for on-demand content, compressing the technology gap between live and time-shifted advertising capabilities.
The FCC's ownership rule modernization is relaxing local market concentration limits, enabling broadcasters to achieve scale in ad-tech infrastructure investment across consolidated station groups. This regulatory shift permits shared services agreements that centralize programmatic sales operations across multiple DMAs. Small and mid-market stations are responding by outsourcing addressable capabilities to national rep firms rather than building in-house platforms.
Buyer concentration among holding-company media agencies is compressing negotiation leverage for standalone broadcasters, with procurement teams demanding audience-based guarantees that transcend individual network or publisher boundaries. The upfront marketplace is fragmenting into audience-agnostic commitments that sellers must fulfill across linear, connected TV, and digital video endpoints. This behavioral shift is most visible in the United States, where agency consolidation has reduced the number of distinct negotiating entities by over half since 2015.
TV Advertising Market Segmentation
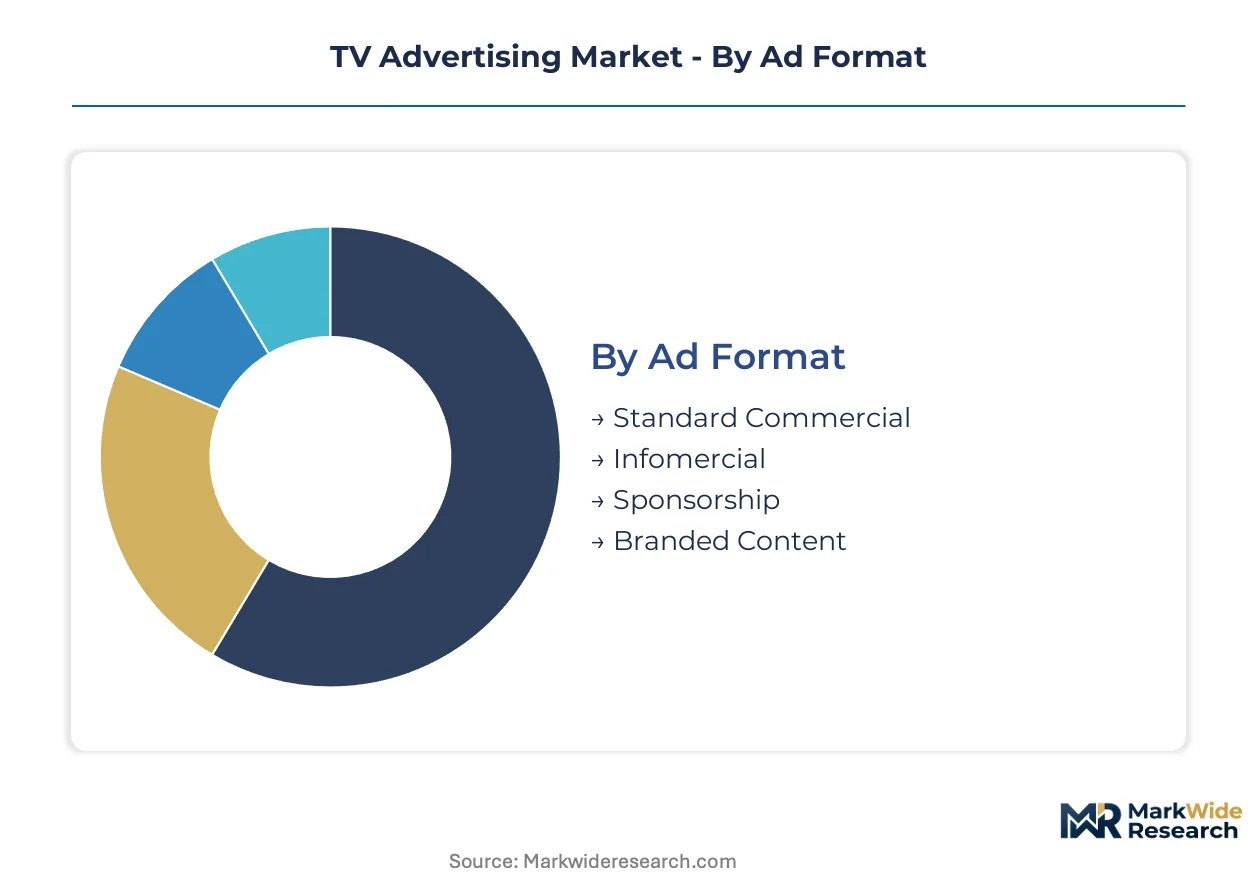
Inventory valuation in television advertising diverges sharply by delivery mechanism and audience addressability. Buyers now optimize across legacy guaranteed ratings and programmatic impression pools, forcing sellers to maintain parallel yield systems. Segmentation clarity determines which inventory commands premium CPMs versus remnant pricing.
Ad Format:
Volume-heavy standardized units anchor upfront commitments, while premium custom integrations capture scarcity value in cluttered environments.
- Standard Commercial:Fifteen- to sixty-second interruptive spots delivered within program breaks constitute the revenue base. Automotive and FMCG buyers in the United States, China, and India lock in annual commitments during upfront windows to secure rating point guarantees.
- Infomercial:Extended-form direct-response programming typically airing in overnight or fringe dayparts. Fitness equipment and financial services marketers dominate this inventory, leveraging toll-free and URL attribution to measure immediate conversion against media spend.
- Sponsorship:Exclusive advertiser association with specific program segments or entire series. Live sports broadcasts in the United States command the highest sponsorship premiums due to unduplicated reach and brand safety assurances.
- Branded Content:Native integration where advertiser messaging embeds within editorial or entertainment narrative. Streaming platforms expanding most quickly in this format as subscription fatigue opens ad-supported tiers to product placement innovation.
Mature deployment sits with Standard Commercial. Newer deployment is concentrated in Branded Content.
Broadcast Type:
Delivery infrastructure determines addressability depth and measurement precision, with IP-based systems offering granular targeting unavailable to spectrum-dependent distribution.
- Live Broadcasting:Real-time transmission over terrestrial spectrum with mass simultaneous reach. Political advertising cycles and major sporting events in the United States concentrate demand here, though panel-based measurement limits optimization.
- Cable:Multichannel video programming distributor systems with regional footprint concentration. Fragmented ownership across Comcast, Charter, and regional operators in the United States complicates national addressable activation.
- Satellite:Direct-to-home transmission via orbital relay, dominant in rural United States markets and emerging economies with weak terrestrial infrastructure. India's DTH penetration sustains this segment despite streaming migration in urban centers.
- Streaming:Internet-protocol delivery across connected TV, mobile, and desktop endpoints. E-commerce and direct-to-consumer brands in the United States, China, and India are climbing the fastest here as cord-cutting shifts premium audiences to IP environments.
Legacy infrastructure investment centers on Cable and Satellite. Capital deployment is accelerating fastest in Streaming.
Audience Demographic:
Life-stage targeting determines creative strategy and daypart selection, with purchasing power concentration driving inventory scarcity.
- Children:Programming blocks with regulatory-constrained ad loads under FCC and EU Audiovisual Media Services Directive limits. Toy and entertainment licensors in the United States concentrate spending in Saturday morning and after-school dayparts.
- Teens:Transitional demographic with declining linear engagement and elevated streaming adoption. Social platform competition in China and India reduces TV's share of this cohort's video consumption.
- Adults:Core purchasing demographic spanning eighteen to forty-nine or twenty-five to fifty-four in standard currency definitions. Automotive, financial services, and retail marketers in the United States anchor upfront commitments against this segment.
- Seniors:Fifty-plus audience with elevated linear loyalty and healthcare category concentration. Pharmaceutical advertisers in the United States dominate daytime and early fringe inventory to reach this cohort.
Established buying patterns persist in Adults. Emerging opportunity concentrates in Seniors as longevity economics expand category relevance.
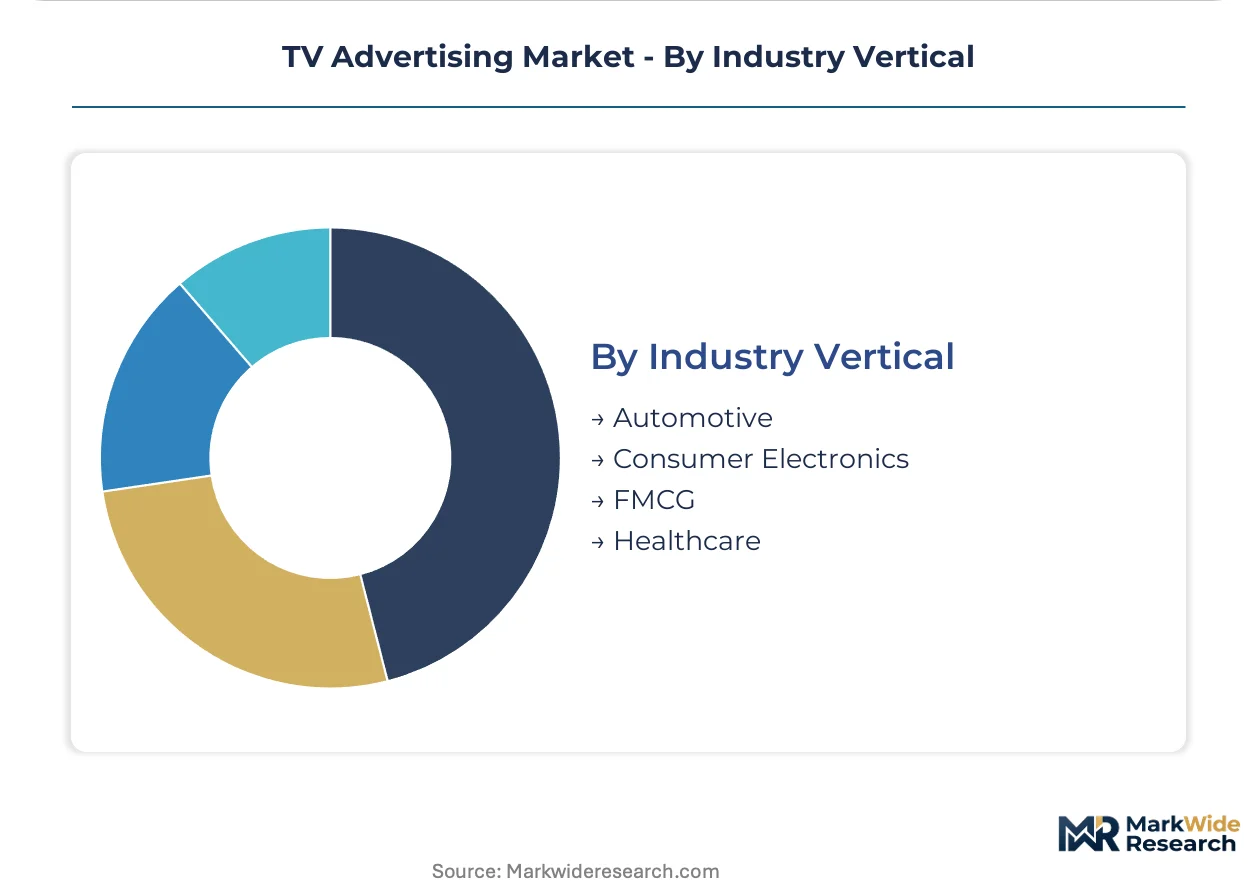
Industry Vertical:
Purchase cycle length and household penetration determine media mix weight, with high-consideration categories sustaining heavier TV investment.
- Automotive:High-consideration purchases with model-year launch calendars dictating seasonal spending spikes. OEMs and dealer associations in the United States commit largest upfront shares to secure sports and news adjacencies.
- Consumer Electronics:Holiday-concentrated demand with product refresh cycles aligned to fourth-quarter promotional windows. Smartphone and television manufacturers in China time launches to coincide with Singles Day and Lunar New Year programming.
- FMCG:High-frequency packaged goods with household penetration metrics driving continuous maintenance media. Procter & Gamble and Unilever procurement teams in the United States negotiate audience-based guarantees across linear and digital endpoints.
- Healthcare:Prescription drug and medical device advertising with regulatory disclosure requirements under FDA and China's NMPA. Direct-to-consumer pharmaceutical spots in the United States concentrate in evening news and drama programming.
Traditional volume leadership rests with FMCG. Fastest share gain is occurring in Healthcare as regulatory clarity expands addressable categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertiser spending concentrates in the United States, China, and India as these markets retain the largest linear and connected TV viewership bases. E-commerce platforms and direct-to-consumer brands now represent the fastest-expanding advertiser category across all three markets. Regulatory modernization in each jurisdiction is reshaping cross-border ad placement frameworks.
United States
Connected TV penetration and upfront commitment volumes from automotive and FMCG buyers sustain the largest national ad market. The FCC's ownership rule modernization relaxes local market concentration limits, enabling consolidated station groups to centralize programmatic sales. New York and Los Angeles anchor national scatter market liquidity, with shared services agreements spreading addressable capabilities into mid-market DMAs.
China
E-commerce advertiser influx and Singles Day promotional cycles concentrate demand in IP-delivered environments. SAMR and MIIT enforce content review and data localization for programmatic platforms, raising infrastructure costs for global demand-side platforms. The Yangtze River Delta and Pearl River Delta clusters host the densest concentration of closed-loop attribution capabilities linking retail media to connected TV inventory.
India
Direct-to-consumer brands and regional language content expansion drive streaming inventory growth. TRAI mandates tariff transparency for broadcast channels carrying advertising, reducing information asymmetry for programmatic access. Mumbai and Delhi-NCR sustain the largest upfront commitment volumes, while Bangalore's ad-tech infrastructure supports addressable activation across southern language markets.
United Kingdom
Agency consolidation and audience-based guarantee demands from procurement teams compress standalone broadcaster leverage. The EU Audiovisual Media Services Directive harmonizes ad frequency limits, lowering operational barriers for pan-European campaigns. London anchors holding-company media buying headquarters, with Manchester and Birmingham clusters supporting regional addressable inventory aggregation.
Germany
Automotive sector maintenance media and pharmaceutical regulatory clarity sustain premium CPM tiers. GDPR compliance requirements and the EU Audiovisual Media Services Directive shape data governance for addressable campaigns. Hamburg and Munich concentrate broadcast group headquarters, while the Cologne media cluster supports mid-market programmatic infrastructure development.
TV Advertising Market Competitive Landscape
Consolidation through broadband-video bundling and ad-tech infrastructure control dominates the current landscape. The market structures around three tiers: integrated media conglomerates with streaming platforms, broadcast-cable operators with addressable distribution, and holding-company agencies with data-integrated buying platforms. Strategic archetypes include inventory owners building yield management systems, agencies demanding audience-based guarantees across endpoints, and technology vendors bridging legacy traffic systems with real-time bidding protocols. M&A activity and middleware development for legacy system integration represent the dominant competitive moves.
Within the integrated media conglomerate tier, Comcast Corporation and The Walt Disney Company exemplify divergent approaches to premium ad-tech infrastructure. Comcast leverages its broadband-video bundle to control distribution and addressable capabilities across linear and streaming endpoints. Disney anchors streaming ad loads through Hulu and Disney+ tiered inventory while maintaining upfront commitment relationships with automotive and FMCG buyers. Among holding-company agencies, WPP plc occupies a position representing data-integrated media buying platforms that sustain procurement leverage through consolidated negotiating entities.
| Leading Market Players |
|---|
| Comcast Corporation |
| The Walt Disney Company |
| Fox Corporation |
| NBCUniversal Media, LLC |
| AT&T Inc. |
| Sony Pictures Television |
| WPP plc |
| Omnicom Group Inc. |
| Publicis Groupe SA |
| Others |
Pricing and Supply Chain Analysis
CPM index volatility in the United States, China, and India cascades through television advertising supply chains into three distinct pricing tiers: premium addressable inventory, standard guaranteed ratings, and remnant programmatic pools. Broadcasters with consolidated station groups leverage scale to absorb data localization infrastructure costs, while mid-market operators face margin compression from middleware investments required for real-time bidding integration.
Pricing Analysis
Volume-heavy standard commercial spots anchor the revenue base with contract-based long-term upfront commitments, while addressable streaming inventory captures scarcity premiums. Price differentiation separates automotive and FMCG buyers securing guaranteed rating points from e-commerce advertisers bidding impression-by-impression in scatter markets. Cost compression in linear inventory is intensifying because cord-cutting hollows out panel-measured audiences faster than CPM inflation compensates. Direct-to-consumer brands exhibit highest price sensitivity due to compressed booking windows and performance marketing discipline, whereas pharmaceutical advertisers demonstrate lowest sensitivity given regulatory disclosure requirements and fixed launch calendars.
Supply Chain Analysis
China's SAMR and MIIT data localization mandates are reshaping sourcing decisions for global demand-side platforms, forcing infrastructure investment within domestic jurisdictions. Ad-tech engineering talent concentrates in the United States, India, and Germany, with Bangalore and Berlin clusters feeding specialized programmatic expertise to multinational agencies. Raw material dependencies include broadband infrastructure, smart TV return-path data pipelines, and cloud computing capacity for server-side ad insertion. Single-source vulnerability sits with Nielsen's panel-based measurement currency as competing census-level methodologies from smart TV manufacturers fragment pricing coherence. Distribution runs through holding-company media agencies that consolidated negotiating leverage by over half since 2015.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The television advertising market functions as a cost-of-compliance story where FCC ownership rule modernization creates a barrier-to-entry moat for consolidated station groups capable of centralized programmatic infrastructure investment.
For Market Incumbents: Acquire addressable ad-tech capabilities across multiple DMAs through shared services agreements rather than building in-house platforms station-by-station. Consolidated broadcasters should deepen yield management integration between linear traffic systems and demand-side platform APIs before scatter market liquidity fragments further. The threat of agency procurement teams demanding audience-based guarantees across endpoints compresses standalone broadcaster leverage; vertical integration into broadband-video bundling provides defensive scale. For New Entrants and Emerging Players: EU Audiovisual Media Services Directive harmonization opens a window for pan-European demand-side platforms to reduce compliance fragmentation and capture cross-border campaign flows. White-space targets include regional language inventory aggregation in India under TRAI-mandated tariff transparency, and closed-loop attribution partnerships between retail media networks and connected TV publishers. A direct-to-consumer brand vertical specialization offers the most penetrable entry angle given e-commerce advertiser influx into upfront commitments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market broadcasters with undervalued spectrum assets in the United States where FCC ownership rule relaxation enables rollup economics. Long-term viability hinges on five-to-ten year windows for addressable infrastructure deployment before linear-simulcast inventory fully migrates to IP delivery. The signal to watch is measurement currency standardization battles between panel-based and census-level methodologies as inflection indicator for pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Development for Legacy Integration | Bridges broadcast traffic systems with demand-side platform APIs to accelerate addressable rollout timelines. |
| Server-Side Ad Insertion Deployment | Eliminates ad-blocking and improves quality of experience for Hulu, Peacock, and major sports league live streaming. |
| Shared Services Agreement Expansion | Centralizes programmatic sales operations across multiple DMAs under FCC ownership rule modernization. |
| Retail Media Network Partnership | Creates closed-loop attribution capabilities where Walmart and Amazon purchase data informs connected TV audience targeting. |
| Regional Language Inventory Aggregation | Reduces information asymmetry for programmatic access under India's TRAI-mandated tariff transparency regime. |
Research Methodology
Independent corroboration across broadcast traffic system operators, demand-side platform engineers, and holding-company media procurement leads underwrites the qualitative findings in this study. Primary interviews with station group ad-tech directors, agency trading desk heads, and regulatory affairs specialists at multichannel video programming distributors combined with secondary validation from FCC filings, EU Audiovisual Media Services Directive implementation reports, and TRAI tariff orders. Bottom-up inventory flow analysis and top-down advertising expenditure triangulation anchored the market sizing.
Comparable-period anchoring to historical upfront commitment volumes and scatter market liquidity patterns structured the projection framework across the analysis window. Segmentation dimensions modeled include ad format, broadcast type, audience demographic, and industry vertical with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of connected TV penetration curves and linear audience erosion rates, calibrated against e-commerce advertiser spend trajectory and political advertising cycle amplitude.
The model assumes a particular technology adoption path; alternative pathways for server-side ad insertion and census-level measurement currency would alter the outlook. Forecasts reflect assumptions regarding FCC ownership rule implementation pace, EU directive harmonization completeness, and data localization compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cloud Television (TV) Market
Television
Digital TV Market
Television
Television Broadcasting Services Market
Television
Broadcasting and Cable TV Market
Television
Global Digital Terrestrial Television Market
Television
Cloud TV Market
Television
Traditional TV and Home Video Market
Television
Pay TV Services Market
Television
Free-To-Air (FTA) Service Market
Television
Holographic TV Market
Television
Television and Set Top Box Market
Television
Print Newspapers and Magazines Market
Television
Television Advertising Market
Television
Television Market
Television
Television Services Market
Television
Cable Television Networks Market