
 Cloud TV Market | 2026-2036
Cloud TV Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud TV Market Analysis
Platform licensing revenue is reshaping competitive economics in video delivery, shifting value from hardware ownership to recurring software contracts. Kaltura, Inc. leverages its open-source architecture to anchor enterprise and educational deployments across multiple continents. Brightcove, Inc. sustains its position through specialized video hosting tools for media companies requiring broadcast-grade reliability. Comcast Technology Solutions dominates North American operator-tier deployments through backward integration into CDN and ad-tech infrastructure.
Cloud TV refers to television content delivery, management, and consumption systems that operate entirely through internet-based server infrastructure rather than terrestrial, satellite, or dedicated cable distribution networks, typically encoding video at bitrates adaptive to available bandwidth while storing subscriber data and content libraries in distributed data centers. Its primary commercial purpose is enabling broadcasters, operators, and content owners to launch, scale, and monetize video services without capital-intensive headend or transmission equipment. Public cloud deployments now capture the largest revenue share among deployment models because hyperscaler partnerships reduce infrastructure latency for live streaming workloads. Subscription services within the service type dimension generate the most predictable margin pools, though advertising-based models are expanding fastest as connected TV ad budgets migrate from linear broadcast.
The FCC governs net neutrality and broadband classification rules that directly affect how cloud TV providers negotiate interconnection with internet service providers, while the EMA and national audiovisual regulators in Europe enforce content quota and data localization requirements that shape platform architecture for cross-border services. GDPR compliance costs influence whether providers centralize or fragment subscriber databases across EU member states. Stakeholders must monitor how pending spectrum reallocation and cloud security certification mandates alter total cost of ownership calculations for operator-grade deployments.
Market Dynamics
Platform licensing economics are compressing capital requirements for video service launches, shifting operator investment from hardware ownership toward recurring software contracts and API-based infrastructure orchestration.
Growth Catalysts
- Net Neutrality Frameworks:The FCC's broadband classification rules in the United States mandate equal treatment of streaming traffic, reducing interconnection friction between cloud TV platforms and internet service providers.
- Edge Computing Deployment:Hyperscaler partnerships with telecom operators are reducing live streaming latency below broadcast thresholds, enabling real-time sports and interactive viewing experiences.
- Ad-Tech Integration:Programmatic advertising infrastructure within cloud TV stacks is capturing connected TV budgets migrating from linear broadcast systems.
Market Restraints
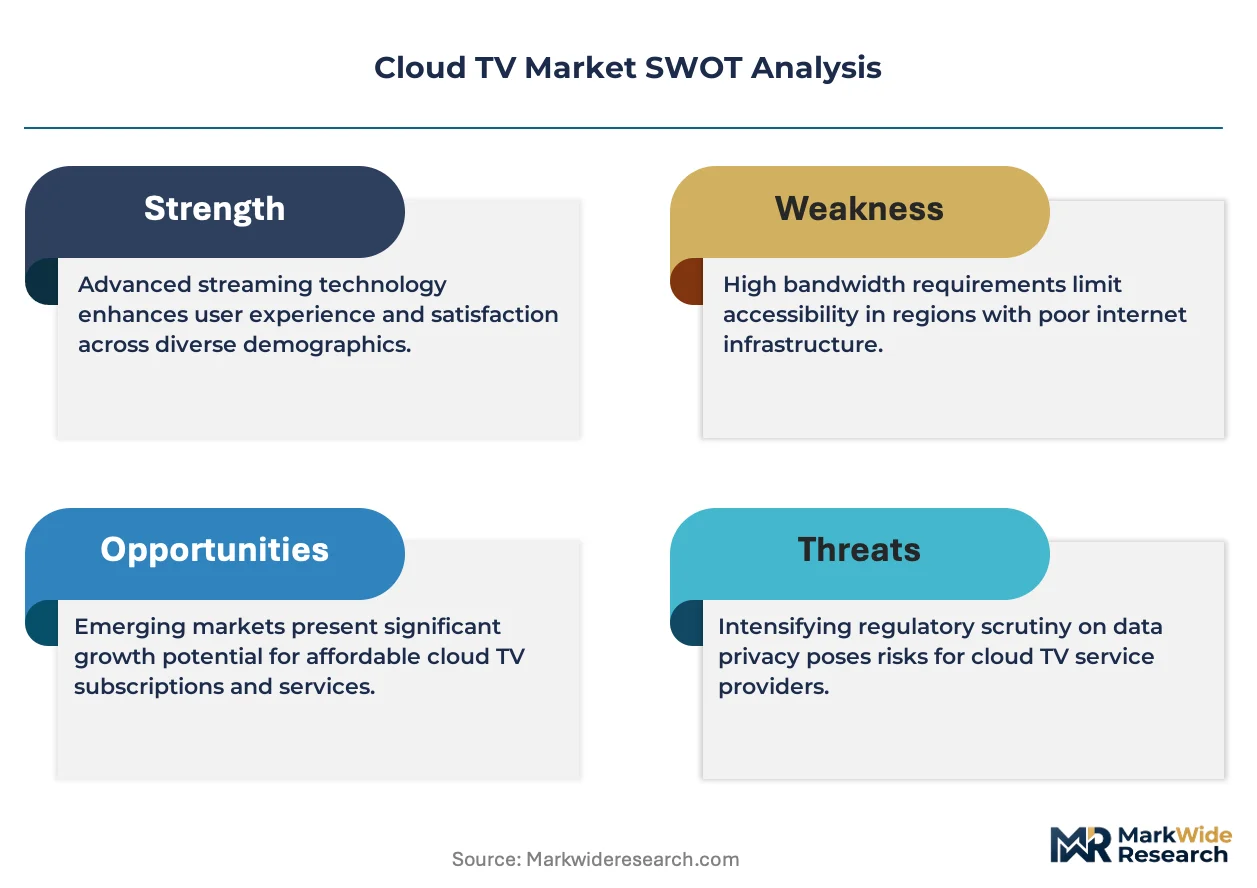
- Content Licensing Fragmentation:Exclusive territorial rights agreements between studios and legacy distributors create geographic gaps in cloud TV content libraries.
- Bandwidth Cost Volatility:Peering disputes between content delivery networks and last-mile internet service providers introduce unpredictable egress pricing for high-bitrate streaming.
- Data Localization Mandates:GDPR requirements in European Union member states force infrastructure fragmentation, raising operational complexity for cross-border services.
Strategic Opportunities
- Educational Vertical Expansion:Universities and corporate training departments in Germany and France are deploying cloud TV platforms for lecture capture and distributed learning.
- 5G Broadcast Convergence:Integration of 5G multicast capabilities with cloud-native headends enables spectrum-efficient live streaming to mobile devices.
- India Market Entry:TRAI's regulatory clarity on over-the-top services and expanding fiber-to-the-home infrastructure create favorable conditions for platform localization.
Industry Challenges
- Legacy System Integration:Cable operators migrating subscriber management systems to cloud architectures face API incompatibility with decades-old conditional access modules.
- Live Event Scaling:Sudden audience spikes during premier sports broadcasts strain auto-scaling algorithms, requiring manual capacity pre-provisioning that undermines cloud elasticity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud TV Market |
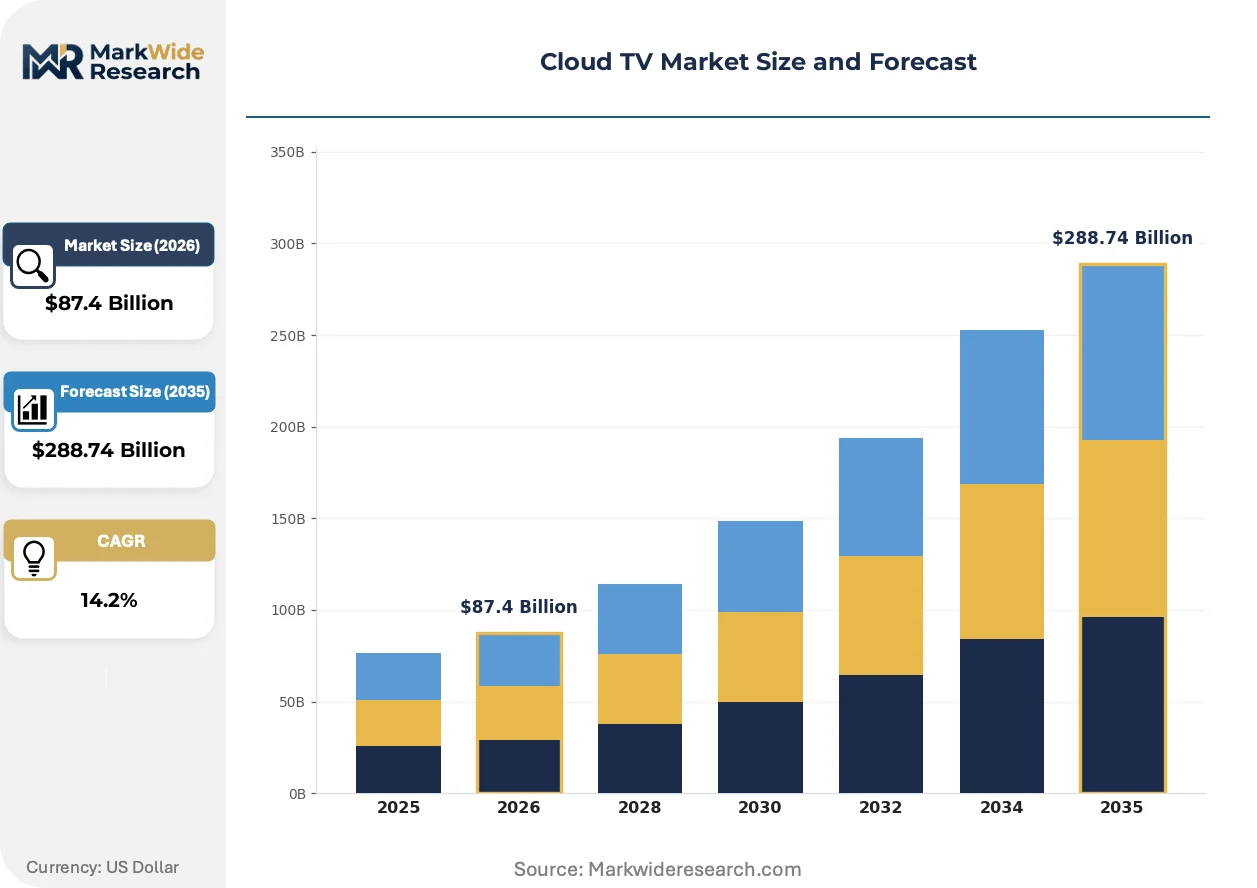
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Video-On-Demand, Live Streaming, Subscription Services, Advertising-Based End User: Enterprises, Educational Institutions, Media Companies, Consumers Content Type: Movies, TV Shows, Sports, Documentaries |
| Companies Covered | Kaltura, Inc., Brightcove, Inc., Amino Technologies PLC, MatrixStream Technologies, Inc., IntelliMedia Networks, Minerva Networks, Inc., CSG Systems International, Inc., MediaKind, Comcast Technology Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud TV Market Emerging Trajectories
Software-defined video processing is dissolving the boundary between broadcast and broadband delivery, enabling unified content preparation pipelines that adapt output formats to any screen or network condition.
Server-side ad insertion technology is rendering obsolete client-side ad loading that allowed ad-blockers and introduced latency jitter. Major broadcasters in the United States and United Kingdom are deploying SSAI for live sports inventory. This compression of ad-tech middleware into the encoding pipeline is consolidating vendor relationships around integrated platform providers.
The European Union's Digital Services Act imposes transparency requirements on algorithmic content recommendation systems. Cloud TV operators serving EU audiences must document ranking parameters and provide user override controls. France and Germany are moving fastest on enforcement, with national audiovisual regulators issuing technical implementation guidance.
Enterprise procurement teams are consolidating video platform contracts under single-vendor master service agreements, displacing the previous pattern of point solutions for live, on-demand, and internal communications. Media companies with diversified streaming portfolios are centralizing vendor management through procurement departments rather than engineering-led evaluation. This shift is most visible among North American broadcasters with multiple branded services.
Cloud TV Market Segmentation
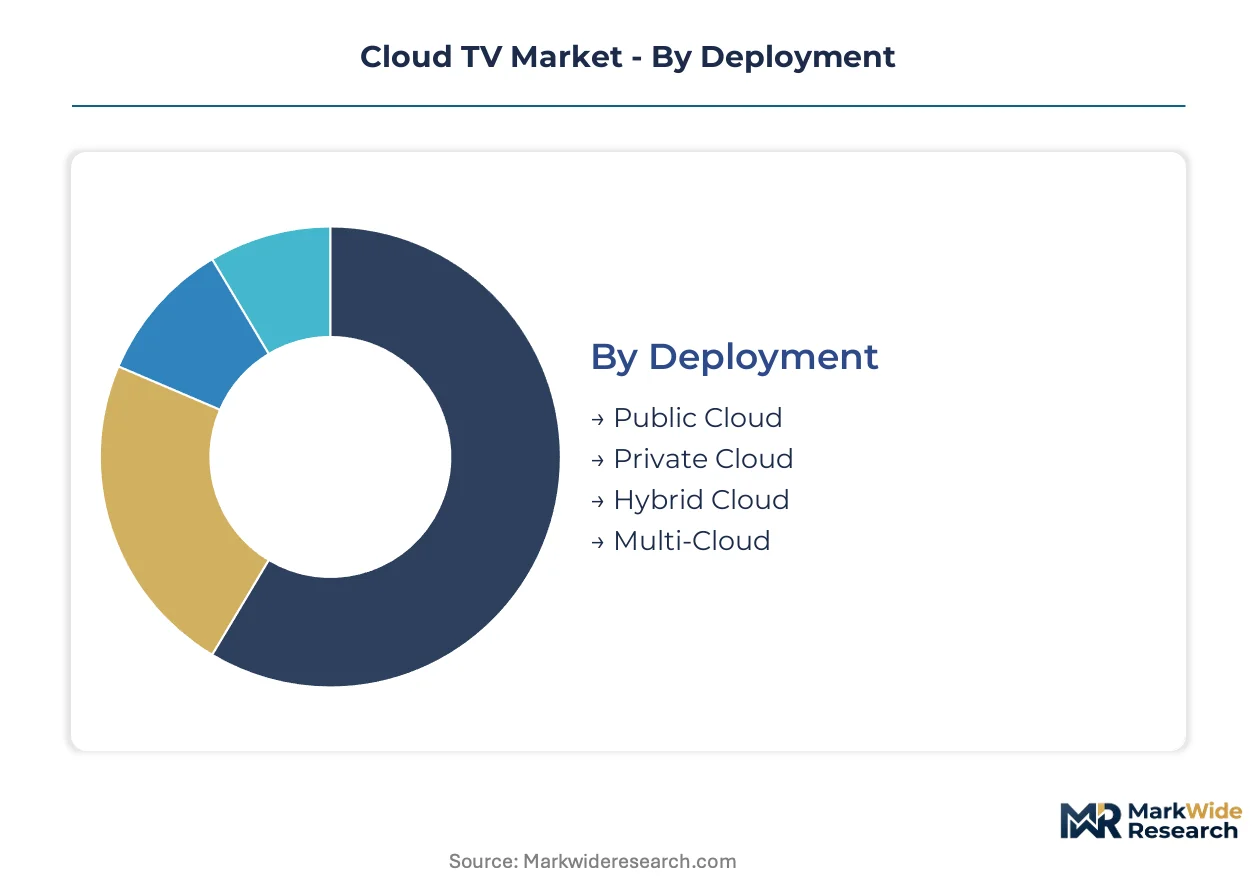
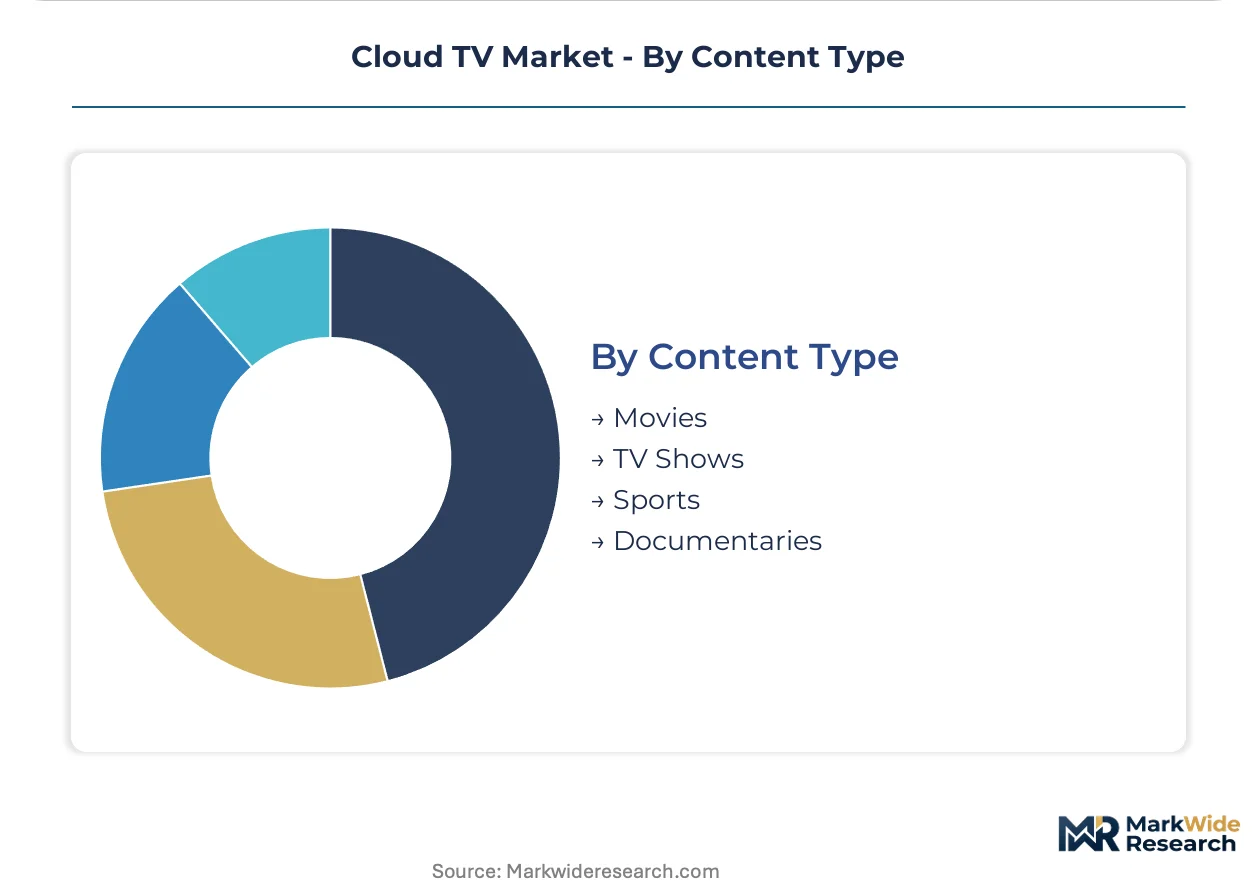
Cloud TV segmentation reveals how infrastructure choices, monetization models, and audience targeting stratify investment priorities across broadcasters and platform operators. Understanding these dimensions clarifies where capital concentrates and which configurations capture margin expansion.
Deployment:
Use-case spectrum spans hyperscaler partnerships for latency-sensitive live events to sovereign infrastructure for regulated content archives.
- Public Cloud:Hyperscaler partnerships reduce infrastructure latency for live streaming workloads. Demand concentrates among broadcasters in the United States launching direct-to-consumer services without capital-intensive headend equipment.
- Private Cloud:Dedicated server infrastructure within operator-controlled data centers ensures deterministic performance for subscriber management systems. European media companies facing GDPR data localization mandates favor this model to maintain sovereign data control.
- Hybrid Cloud:Combines public edge nodes for content delivery with private core infrastructure for subscriber databases.
- Multi-Cloud:Distributes workloads across competing hyperscalers to mitigate vendor lock-in and optimize regional egress pricing.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
Service Type:
Monetization architecture determines recurring revenue predictability versus advertising yield volatility.
- Video-On-Demand:Library-based streaming with adaptive bitrate encoding enables time-shifted consumption across devices. Media companies in the United Kingdom deploy VOD infrastructure to monetize back-catalog content through subscription tiers.
- Live Streaming:Real-time encoding pipelines with sub-second latency targets support sports and news broadcasts. Indian telecom operators integrating 5G multicast capabilities are expanding live streaming to mobile-first audiences.
- Subscription Services:Recurring billing integration with cloud-native CRM systems generates predictable margin pools.
- Advertising-Based:Server-side ad insertion technology captures connected TV budgets migrating from linear broadcast.
Subscription Services anchor current revenue stability; Advertising-Based models are climbing the fastest as programmatic infrastructure matures.
End User:
Customer procurement sophistication ranges from enterprise IT departments to individual subscriber acquisition funnels.
- Enterprises:Internal communications and training video platforms require SSO integration and granular access controls. Corporate procurement teams in Germany are consolidating video platform contracts under single-vendor master service agreements.
- Educational Institutions:Lecture capture systems with searchable transcript indexing support distributed learning. Universities in France deploy cloud TV platforms for hybrid classroom models.
- Media Companies:Broadcast-grade reliability requirements drive specialized video hosting tool selection.
- Consumers:Direct-to-subscriber apps compete on content exclusivity and user interface responsiveness.
Media Companies dominate current platform licensing revenue; Educational Institutions are gaining share fastest as academic digitization accelerates.
Content Type:
Genre-specific encoding requirements and rights complexity shape infrastructure investment profiles.
- Movies:Premium 4K HDR encoding with wide color gamut support commands higher per-stream infrastructure costs. Studio libraries in the United States leverage cloud TV for theatrical window compression and early digital release strategies.
- Sports:Multi-camera live production with real-time clipping and social media integration demands edge computing deployment. Brazilian broadcasters are expanding sports streaming infrastructure to capture mobile-first viewership.
- TV Shows:Episodic release scheduling with binge-drop flexibility requires elastic storage scaling.
- Documentaries:Niche audience targeting with lower bitrate requirements suits cost-optimized encoding profiles.
Movies and Sports command premium infrastructure investment; Documentaries represent the most efficient marginal expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure investment concentrates in the United States, Germany, India, United Kingdom, and Brazil, where regulatory clarity and fiber density enable cloud-native video delivery at scale.
United States
Major broadcasters and cable operators are migrating legacy headend systems to cloud-native platforms. The FCC's net neutrality framework mandates equal treatment of streaming traffic, reducing interconnection friction between cloud TV platforms and internet service providers. Silicon Valley and Los Angeles clusters host the primary engineering centers for platform development.
Germany
Universities and corporate training departments are deploying cloud TV infrastructure for lecture capture and distributed learning. GDPR compliance costs influence whether providers centralize or fragment subscriber databases across EU member states. Berlin and Munich host the dominant platform engineering and content localization operations.
India
Telecom operators integrating 5G multicast capabilities are expanding live streaming to mobile-first audiences. TRAI's regulatory clarity on over-the-top services and expanding fiber-to-the-home infrastructure create favorable conditions for platform localization. Mumbai and Bangalore concentrate the primary development centers for regional platform adaptation.
United Kingdom
Media companies deploy video-on-demand infrastructure to monetize back-catalog content through subscription tiers. The national audiovisual regulator enforces content quota requirements that shape platform architecture for cross-border services. London anchors the primary broadcast-grade reliability engineering clusters.
Brazil
Broadcasters are expanding sports streaming infrastructure to capture mobile-first viewership in Latin America's largest media market. Local content quota regulations require platform adaptation for territorial rights management. São Paulo hosts the dominant regional platform deployment and content aggregation operations.
Cloud TV Market Vendor Landscape
Platform specialists and operator-integrated providers split the market between API-first software licensing and vertically bundled infrastructure stacks. The vendor base concentrates around three strategic archetypes: open-source platform licensors, broadcast-grade hosting specialists, and operator-tier systems integrators. Competitive moves center on hyperscaler partnership expansion and server-side ad insertion technology consolidation.
Within the open-source platform tier, Kaltura, Inc. and Brightcove, Inc. exemplify contrasting geographic and architectural positioning. Kaltura, Inc. anchors enterprise and educational deployments across multiple continents through its modular architecture. Brightcove, Inc. occupies a position among broadcast-grade hosting specialists serving media companies requiring deterministic performance. Comcast Technology Solutions represents the operator-integrated archetype, leveraging backward integration into CDN and ad-tech infrastructure to dominate North American deployments.
| Leading Market Players |
|---|
| Kaltura, Inc. |
| Brightcove, Inc. |
| Amino Technologies PLC |
| MatrixStream Technologies, Inc. |
| IntelliMedia Networks |
| Minerva Networks, Inc. |
| CSG Systems International, Inc. |
| MediaKind |
| Comcast Technology Solutions |
| Others |
Supply Flow & Price Mechanics
Los Angeles and Silicon Valley engineering clusters anchor hyperscaler capacity expansion for live streaming workloads, concentrating encoding infrastructure investment among three dominant cloud providers and compressing marginal compute pricing for broadcast-grade deployments.
Pricing Analysis
FCC net neutrality rules dictate the pricing tier structure for interconnection agreements between cloud TV platforms and last-mile internet service providers. Three-tier pricing structure across premium, standard, and economy levels separates broadcasters demanding sub-second latency from educational institutions tolerating higher buffering thresholds. Cost compression in the economy tier is intensifying because hyperscaler price wars on egress bandwidth are forcing mid-market platform vendors to absorb margin erosion. Educational institutions exhibit the highest price sensitivity, while sports broadcasters with live event inventory show minimal elasticity due to deterministic performance requirements.
Supply Chain Analysis
Video encoding hardware and specialized GPU accelerators draw from Taiwan, South Korea, and United States fabrication facilities, with hyperscaler datacenter equipment sourcing concentrated among Taiwanese ODMs. Cloud TV infrastructure rests on three critical input streams: hyperscaler compute instances, CDN edge node capacity, and ad-tech middleware licenses. Single-source vulnerability persists in specialized video processing ASICs where Broadcom and NVIDIA dominate merchant silicon supply. Distribution runs through direct enterprise sales teams for operator-tier deployments and self-serve API portals for mid-market media companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud TV represents a service-attach opportunity where server-side ad insertion and subscription management layers expand faster than base platform licensing, shifting valuation multiples toward recurring revenue durability.
For Market Incumbents: Pre-empt hyperscaler encroachment by deepening backward integration into CDN infrastructure and capturing exclusive sports rights that mandate proprietary edge node deployment. Threat substitution from AWS Elemental and Google Cloud Media services demands territorial exclusivity in live event encoding. Certification investment in GDPR-compliant data residency architectures protects European operator relationships from compliance-driven vendor switches.
For New Entrants and Emerging Players: Establish a beachhead in Indian educational institutions where TRAI regulatory clarity and fiber expansion create first-mover advantages for lecture capture platforms. White-space targets include 5G multicast integration for Brazilian mobile operators and corporate training verticals in Germany seeking SSO-enabled video platforms. Go-to-market angle: API-first pricing with consumption-based billing displaces incumbent perpetual license models.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform providers with >60% subscription services revenue mix and embedded ad-tech stacks. Long-term viability across the analysis window favors vendors consolidating server-side ad insertion, CRM, and encoding into unified stacks. Acquisition target archetype: regional specialists with sovereign cloud certifications in EU member states. Signal to watch: hyperscaler partnership exclusivity announcements indicating platform-tier vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Ad Insertion Integration | Consolidates ad-tech middleware into encoding pipelines, displacing client-side loading vulnerable to blockers. |
| Hyperscaler Partnership Expansion | Reduces latency for live sports workloads through AWS, Azure, or Google Cloud edge node co-location. |
| Educational Vertical Platform Localization | Captures German and French university procurement consolidating video contracts under single-vendor agreements. |
| 5G Multicast Capability Development | Enables spectrum-efficient mobile streaming for Indian telecom operators expanding live sports to handheld devices. |
| GDPR-Compliant Data Architecture | Preserves European operator relationships against fragmentation mandates from national audiovisual regulators. |
Methodological Framework
A standing panel of platform engineering directors, broadcast CTOs, educational IT procurement managers, and ad-tech integration specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FCC broadband classification filings, TRAI over-the-top service consultations, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model segmentation and top-down cross-check against CDN traffic growth curves anchored volume estimates.
Scenario-bracketing around net neutrality enforcement intensity and 5G multicast adoption pace bounded the projection horizon. Segmentation dimensions modeled include deployment architecture, service type monetization model, end-user procurement sophistication, and content genre encoding intensity. CAGRs derived from elasticity-adjusted capacity expansion curves and platform licensing contract renewal rates. Industry-specific inputs incorporated live event scaling thresholds and GDPR compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in hyperscaler pricing wars or spectrum reallocation timelines would shift the trajectory. Forecasts reflect documented assumptions on interconnection fee stability and ad-tech middleware consolidation velocity. Cross-checking against Akamai and Fastly traffic growth benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
TV Advertising Market
Television
Global Broadcast Equipment Market
Television
Television Services Market
Television
Pay TV Market
Television
Mobile TV Market
Television
Free-To-Air (FTA) Service Market
Television
Print Newspapers and Magazines Market
Television
Traditional TV and Home Video Market
Television
Broadcasting and Cable TV Market
Television
Global Digital Terrestrial Television Market
Television
Curved Television Market
Television
Television Advertising Market
Television
HDTV Market
Television
Television and Set Top Box Market
Television
Cloud Television (TV) Market
Television
Pay TV Operator Market