
 Broaching Tools Market | 2026-2036
Broaching Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Broaching Tools Market Analysis
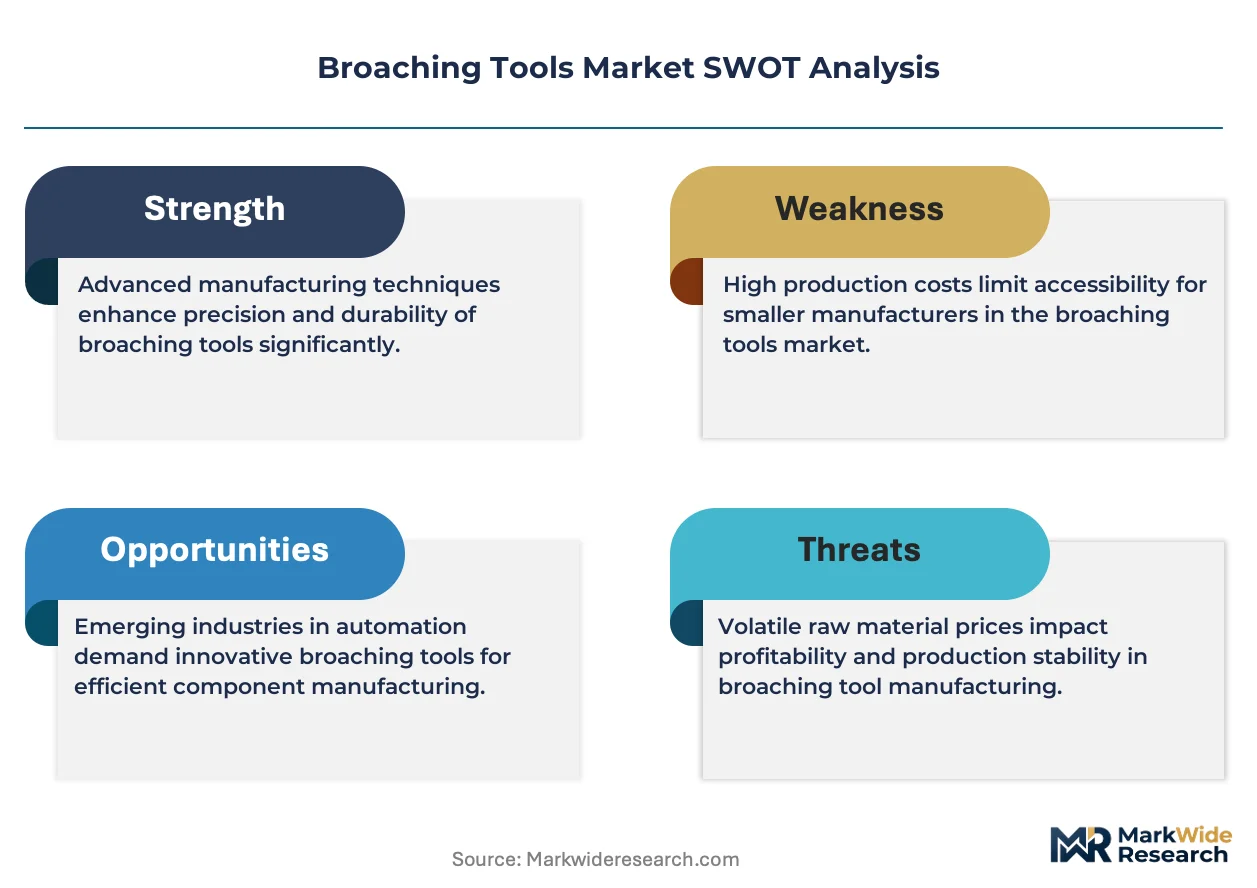
REACH is recalibrating the cost-of-entry calculus for European broaching tool suppliers by mandating restricted substance documentation across the supply chain. Pioneer Broach Company leverages its vertical integration to control coating chemistry compliance in-house. Colonial Tool Group anchors its competitive stance through deep specialization in pull-type internal broaches for aerospace OEMs. Mitsubishi Heavy Industries dominates large-format broaching systems for power generation turbine slots.
Broaching tools are precision metal-cutting instruments featuring multiple progressively sized teeth arranged along a bar or stick, typically manufactured from high-speed steel or cemented carbide substrates and operating at cutting speeds of 6–15 m/min with pull forces exceeding 50 kN to generate accurate internal or external profiles. Their primary industrial purpose centers on producing splines, keyways, and complex contours in mass-production environments where dimensional repeatability exceeds grinding economics. Internal broaches command the deepest margin pools due to aerospace and automotive transmission demand for precision spline cutting. Carbide-tipped variants represent the fastest-expanding material segment as manufacturers substitute cobalt-bearing grades to extend tool life in hardened steel applications above 45 HRC.
ISO 230 standards govern broaching machine tool accuracy verification, while OSHA mandates govern chip containment and operator exposure limits in US production facilities. Germany's KBA enforces traceable tooling documentation for automotive powertrain suppliers under type-approval frameworks. Stakeholders must monitor how evolving REACH substance restrictions and China's GB standards for cutting tool materials reshape raw material sourcing and coating technology roadmaps.
Market Dynamics
Carbide-tipped broach adoption is compressing tool replacement cycles as aerospace and automotive transmission manufacturers push cutting speeds beyond 15 m/min in hardened steel applications above 45 HRC.
Growth Catalysts
- REACH substance restrictions:European coating chemistry mandates are accelerating demand for compliant carbide substrates that reduce cobalt leaching during high-speed machining operations.
- Turbine disc production expansion:Aerospace OEMs in Germany and Japan are scaling precision spline cutting capacity for next-generation power generation equipment.
- Automotive transmission sector:Powertrain manufacturers across India and Mexico are installing dedicated broaching lines for dual-clutch and electric vehicle gearbox output shafts.
Market Restraints
- Tungsten carbide supply concentration:Powder metallurgy feedstock sourcing clusters in China create vulnerability to export license delays and price volatility.
- High-speed steel displacement ceiling:Cobalt-bearing HSS retains cost advantage below 45 HRC workpiece hardness, limiting carbide penetration in general machining job shops.
- OSHA chip containment mandates:US facilities face capital expenditure pressure for enclosed broaching cells and automated coolant recovery systems.
Strategic Opportunities
- India automotive corridor:Transmission plants in Pune and Chennai lack qualified local broach regrinding services, creating white space for technical service partnerships.
- GB standards alignment:China's cutting tool material certification pathway offers first-mover advantage for suppliers achieving MEE emissions-compliant coating chemistries.
- Hybrid PVD-CVD coating convergence:Combining physical and chemical vapor deposition techniques extends tool life in titanium alloy aerospace applications.
Industry Challenges
- Broach design engineering talent:The specialized skill of calculating progressive tooth geometry for complex internal profiles faces generational attrition in Western manufacturing regions.
- ISO 230 verification timeline:Machine tool accuracy certification for large-format turbine slot broaching systems extends delivery schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broaching Tools Market |
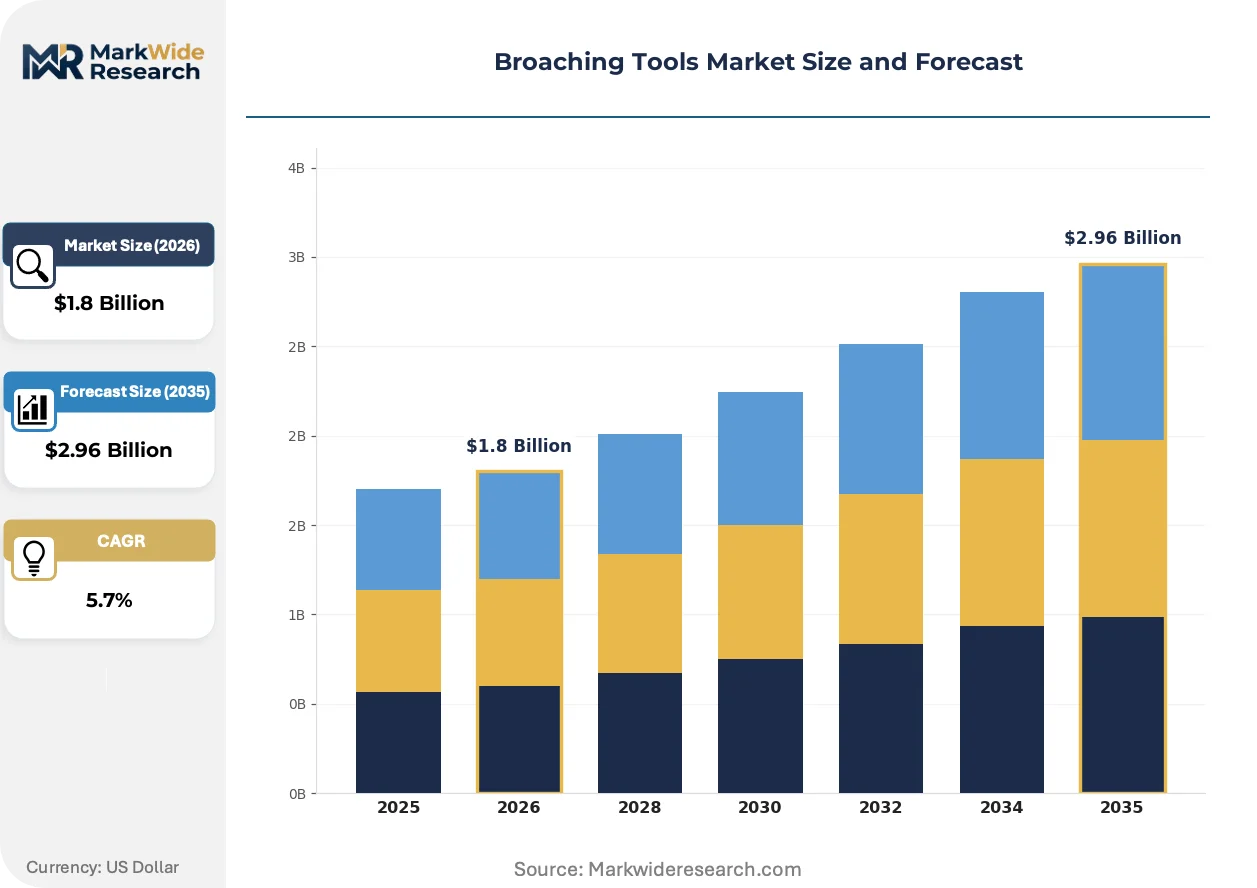
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Broaches, External Broaches, Continuous Broaches, Specialty Broaches Material: High-Speed Steel, Carbide, Cobalt, Tool Steel End User: Aerospace, Automotive, Machinery, Electronics Application: Metalworking, Woodworking, Plastics Processing, Industrial Assembly |
| Companies Covered | Pioneer Broach Company, Colonial Tool Group, Mitsubishi Heavy Industries, Ohio Broach & Machine Co., Broaching Machine Specialties, Nachi-Fujikoshi, Apex Broaching Systems, CNC Broach Tool LLC, LMT Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broaching Tools Market Emerging Trajectories
Coating technology roadmaps and procurement model compression are restructuring how broaching tool suppliers capture value across aerospace and automotive supply chains.
Multi-layer PVD coatings with alternating aluminum-chromium nitride and titanium-silicon layers are extending tool life in nickel-based superalloy turbine disc applications. Rolls-Royce and Pratt & Whitney tier suppliers are specifying these coatings for pull-type internal broaches operating at 12-15 m/min cutting speeds. This performance tier is electrifying competitive differentiation among specialty coating houses.
REACH Annex XIV authorization requirements for cobalt compounds are forcing reformulation of cemented carbide substrates across European supply chains. Tool manufacturers must document substance volumes above 0.1% threshold through ECHA SCIP database entries. Carbide-grade suppliers with captive powder production are accelerating R&D into nickel-iron binder alternatives to preserve market access.
Powertrain OEMs are consolidating vendor bases from 8-12 broaching suppliers per plant to 3-4 strategic partners with integrated regrind and coating capabilities. This consolidation is displacing independent job shops in Germany and Japan. Tier-1 transmission manufacturers now demand vendor-managed inventory with 48-hour replenishment guarantees.
Broaching Tools Market Segmentation
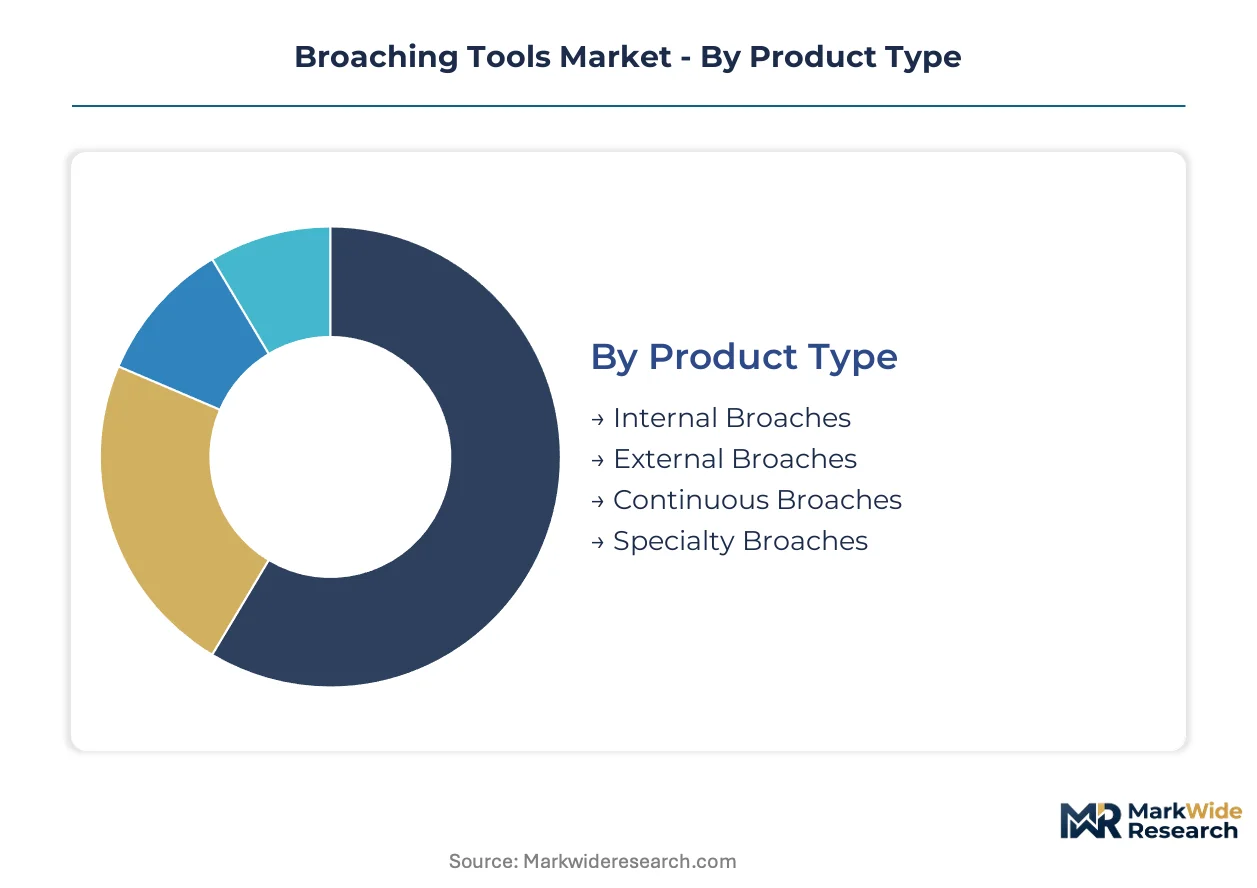
Broaching tool procurement patterns diverge sharply across product geometries and substrate materials. Aerospace and automotive OEMs impose distinct performance specifications that reshape supplier priorities within each segment.
Product Type:
Tool geometry dictates pull-force requirements and machine tool compatibility across production environments.
- Internal Broaches:These pull-type or push-type cutters generate precision splines, keyways, and polygonal profiles inside bored workpieces. Aerospace turbine disc manufacturers in Germany and Japan specify these for nickel-based superalloy machining where dimensional tolerances fall below 0.025 mm.
- External Broaches:Surface-cutting configurations machine external splines, gear teeth, and contoured profiles on shafting and housings. Automotive transmission plants across India and Mexico deploy these for dual-clutch gearbox output shaft production at cycle times under 45 seconds.
- Continuous Broaches:Rotary or chain-type systems for high-volume surface generation on castings and forgings.
- Specialty Broaches:Custom-engineered profiles for medical device bone screws and firearm receiver rails.
Mature deployment sits with internal broaches in established aerospace corridors. Newer deployment is concentrated in external broaches serving electrified powertrain architectures.
Material:
Substrate selection hinges on workpiece hardness thresholds and coating compatibility requirements.
- High-Speed Steel:Cobalt-bearing M35 and M42 grades retain cost advantage for workpieces below 45 HRC. General machining job shops across the US Midwest and Eastern Europe continue specifying HSS for short-run production where carbide economics fail.
- Carbide:Cemented tungsten carbide with cobalt or nickel-iron binders enables cutting speeds exceeding 15 m/min in hardened steels. REACH Annex XIV cobalt restrictions are accelerating R&D into alternative binder systems among European suppliers.
- Cobalt:Specialized grades for extreme heat resistance in superalloy applications.
- Tool Steel:A2 and D2 grades for prototype and low-volume broaching where regrindability outweighs speed.
Established volume concentrates in high-speed steel for general-purpose job shops. The steepest expansion trajectory belongs to carbide as powertrain manufacturers push process speeds.
End User:
Industry-specific certification requirements and volume profiles determine supplier qualification pathways.
- Aerospace:Turbine disc, landing gear, and structural component manufacturers demand ISO 230-certified machine tool accuracy and full material traceability. Rolls-Royce and Pratt & Whitney tier suppliers specify multi-layer PVD coatings for superalloy machining.
- Automotive:Transmission and engine block producers prioritize 48-hour replenishment guarantees and vendor-managed inventory. Powertrain OEMs are consolidating from 8-12 suppliers per plant to 3-4 strategic partners with integrated regrind capabilities.
- Machinery:Industrial equipment builders seeking spline and keyway cutting for gearboxes and pumps.
- Electronics:Connector housing and heat sink producers requiring micro-scale broaching for aluminum and copper alloys.
Qualification depth is greatest in aerospace. Procurement velocity is climbing fastest in automotive as electrification reshapes gearbox architectures.
Application:
Workpiece material properties determine tooth geometry, coating selection, and coolant system design.
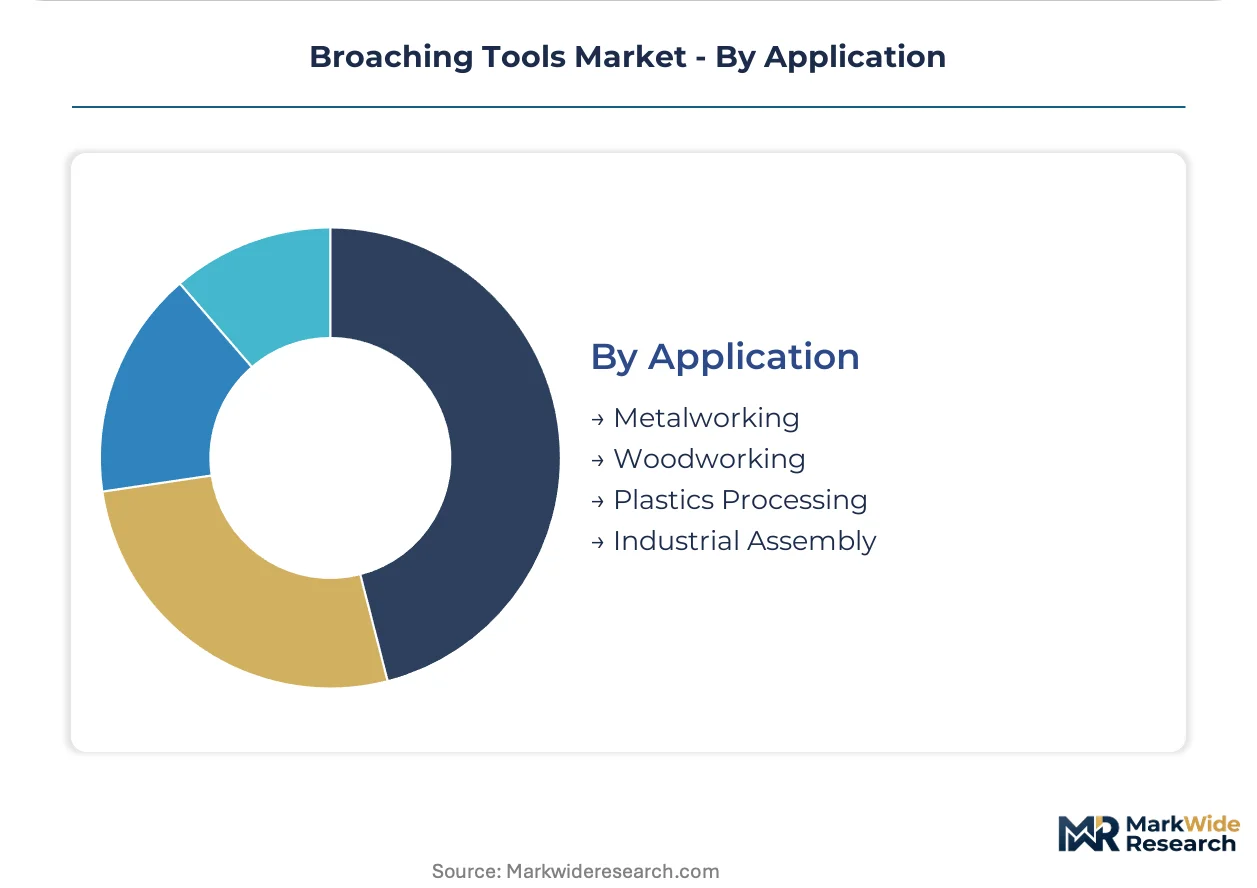
- Metalworking:Ferrous and non-ferrous alloy machining dominates volume, spanning automotive transmission gears, aerospace turbine slots, and hydraulic valve bodies. OSHA chip containment mandates are driving US facilities toward enclosed broaching cells.
- Woodworking:Profile cutting for musical instrument components and architectural millwork requiring polished surface finishes.
- Plastics Processing:Glass-filled polymer and composite machining for medical device housings and automotive underhood components.
- Industrial Assembly:Fastener and fitting production for construction and agricultural equipment.
Process maturity centers on metalworking with decades of standardized parameters. Technology transfer is accelerating most quickly into plastics processing as fiber-reinforced polymers displace metal in lightweighting programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive transmission plants and aerospace turbine disc manufacturers concentrate procurement across five manufacturing corridors, each shaped by distinct regulatory pressures and industrial clustering patterns.
Germany
KBA type-approval frameworks mandate traceable tooling documentation for automotive powertrain suppliers. REACH Annex XIV cobalt restrictions force cemented carbide suppliers to document substance volumes through ECHA SCIP database entries. The Stuttgart and Munich aerospace corridors host turbine disc manufacturers scaling precision spline cutting capacity for next-generation power generation equipment.
Japan
METI industrial standards govern cutting tool material certification for export-oriented machinery producers. JIS standards for high-speed steel and carbide substrates shape supplier qualification pathways. The Nagoya aerospace cluster and Osaka precision manufacturing belt dominate large-format broaching systems procurement for power generation turbine slots.
United States
OSHA chip containment mandates drive capital expenditure pressure for enclosed broaching cells and automated coolant recovery systems. The Midwest automotive corridor spanning Michigan and Ohio installs dedicated broaching lines for dual-clutch and electric vehicle gearbox output shafts. Greater Detroit transmission plants consolidate vendor bases from 8-12 suppliers to 3-4 strategic partners with integrated regrind capabilities.
China
GB standards for cutting tool materials reshape raw material sourcing and coating technology roadmaps. MEE emissions standards push shops toward coated carbide broaches that reduce coolant dependency. The Yangtze River Delta and Pearl River Delta manufacturing belts face tungsten carbide powder metallurgy feedstock sourcing vulnerability to export license delays.
India
BIS certification requirements and PLI scheme incentives for automotive component manufacturing accelerate capital equipment deployment. Transmission plants in Pune and Chennai lack qualified local broach regrinding services, creating white space for technical service partnerships. The Tamil Nadu automotive corridor concentrates demand for external broaches serving electrified powertrain architectures.
Broaching Tools Market Vendor Landscape
German and Japanese producers anchor the premium-tier specialist segment; US and Chinese fabricators hold volume-driven positions in general-purpose and cost-optimized tiers. The vendor base stratifies across three structural archetypes: captive aerospace specialists with in-house coating capabilities, automotive-focused service integrators managing vendor-managed inventory programs, and regional job shops competing on regrind turnaround speed. Competitive moves center on backward integration into powder metallurgy feedstock and strategic partnerships for hybrid PVD-CVD coating technology access.
Among US-based fabricators, Pioneer Broach Company and Colonial Tool Group occupy positions within the aerospace-specialist tier, with the former representing vertical integration into coating chemistry compliance and the latter exemplifying deep specialization in pull-type internal broaches. Mitsubishi Heavy Industries anchors the large-format systems segment. These three entities illustrate how geographic origin and organizational structure map onto divergent competitive strategies across the market.
| Leading Market Players |
|---|
| Pioneer Broach Company |
| Colonial Tool Group |
| Mitsubishi Heavy Industries |
| Ohio Broach & Machine Co. |
| Broaching Machine Specialties |
| Nachi-Fujikoshi |
| Apex Broaching Systems |
| CNC Broach Tool LLC |
| LMT Tools |
| Others |
Supply Flow & Price Mechanics
Specialist-coating certification ladders bifurcate the broaching tools market into aerospace-qualified premium tiers and general-machinery commodity tiers, with REACH-compliant chemistry documentation and captive powder production capabilities determining which suppliers command pricing power versus which compete on regrind turnaround speed.
Pricing Analysis
Volume-mass automotive transmission contracts trade at thin margins against aerospace pull-type internal broaches carrying 3-4x unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 230 machine tool certification status and multi-layer PVD coating specifications. Cost compression in the automotive tier intensifies because powertrain OEMs consolidate vendor bases and demand 48-hour replenishment guarantees. General machining job shops exhibit highest price sensitivity, while Rolls-Royce and Pratt & Whitney tier suppliers prioritize performance consistency over unit cost.
Supply Chain Analysis
Broach design engineering talent shortages in Germany and Japan constrain production scaling for complex progressive tooth geometries. Powder metallurgy feedstock sourcing clusters in China, with secondary concentration in Austria and Sweden for cobalt-alternative binder R&D. Tungsten carbide supply rests on export license vulnerability and price volatility from Chinese customs authorities. Distribution runs through captive service networks for aerospace OEMs and independent job shops for general machining applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The broaching tools market functions as a supply-constrained environment where qualified coating chemists and progressive tooth geometry engineers prop pricing power for incumbents with captive technical capabilities.
For Market Incumbents: Hedge against REACH Annex XIV cobalt restriction escalation by accelerating nickel-iron binder alternative R&D and securing ECHA SCIP database compliance infrastructure. Defensive consolidation into powder metallurgy feedstock production reduces exposure to Chinese export license delays. Priority capacity addition in India addresses the Pune-Chennai regrinding service gap before technical service partnerships crystallize competitive moats.
For New Entrants and Emerging Players: Capture the India automotive corridor white space by establishing broach regrinding and recoating facilities in Tamil Nadu with BIS certification pathways. The most penetrable segment lies in external broaches for electrified powertrain architectures where incumbent service networks remain underdeveloped. Go-to-market positioning as integrated regrind-coating partners aligns with OEM vendor consolidation mandates.
For Investors and Strategic Acquirers: Re-rating potential sits with captive-coating mid-cap specialists given hybrid PVD-CVD technology convergence as a margin expansion catalyst. Long-term viability over a multi-year horizon favors suppliers with backward integration into powder production and documented REACH compliance infrastructure. The signal to watch is tier-1 transmission manufacturer vendor base consolidation velocity as an inflection indicator for service-integrated players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Metallurgy | Captive tungsten carbide feedstock production insulates against Chinese export license volatility and price spikes. |
| Hybrid PVD-CVD Coating Development | Combining physical and chemical vapor deposition extends tool life in Rolls-Royce turbine disc applications above 12 m/min. |
| India Technical Service Partnership | Pune and Chennai transmission plants lack qualified local regrinding, creating first-mover advantage for integrated service entrants. |
| REACH Annex XIV Compliance Infrastructure | ECHA SCIP database documentation capabilities preserve European market access as cobalt restrictions tighten. |
| Vendor-Managed Inventory Programs | 48-hour replenishment guarantees align with powertrain OEM consolidation from 8-12 suppliers to 3-4 strategic partners. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with broach design engineers, coating technology directors, automotive powertrain procurement managers, and aerospace tier supplier quality leads. ECHA substance restriction databases, KBA type-approval documentation, GB standards certification records, and BIS product registration filings provided secondary validation. Bottom-up tooling volume estimates triangulated against top-down machine tool installation data across Germany, Japan, the United States, China, and India.
Segmentation granularity modeled product type at the internal-external broach level, material at the HSS-carbide-cobalt substrate tier, end user across aerospace-automotive-machinery-electronics sectors, and application through metalworking-plastics-woodworking categories. CAGRs derived from fitted growth curves against historical procurement patterns and projected capacity expansion schedules. Industry-specific forecast inputs included turbine disc production scaling in Stuttgart and Nagoya, transmission plant buildouts in Pune and Chennai, and REACH substance restriction phase-in timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to tungsten carbide export policy shifts in China and generational attrition in broach design engineering talent pools. Forecasts reflect documented assumptions regarding coating technology roadmaps and OEM vendor consolidation velocity. Material deviation in REACH authorization timelines or MEE emissions enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wire Cutters Market
Tools
Automotive Torque Tools Market
Tools
Europe Woodworking Power Tools Market
Tools
Power Press Machines Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Thread Milling Machine Market
Tools
Pipe Alignment Clamps Market
Tools
Floor Pads Market
Tools
Friction Washer Market
Tools
Crimping Tool Market
Tools
Tape Measure Market
Tools
Post Drivers Market
Tools
Bandsaw Market
Tools
Tension Tester Market
Tools
Air Drills Market
Tools
China Power Tools and Hand Tools Market