
 Crimping Tool Market | 2026-2036
Crimping Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Crimping Tool Market Analytics
Capital-intensity divergence between automated hydraulic platforms and entry-level manual kits is bifurcating competitive positioning across the supplier base. TE Connectivity Ltd. leverages captive die design capabilities and in-house metallurgy to command premium positioning in aerospace-qualified termination systems. Klein Tools, Inc. anchors its presence through deep distribution in North American electrical contractor channels, while Panduit competes on integrated cable management-to-termination workflows that reduce field installation labor.
A crimping tool applies compressive force to deform a metal sleeve or terminal around a conductor, creating a gas-tight electrical or mechanical joint with pull-strength ratings typically verified per UL 486A-486B or MIL-DTL-22520 specifications. Electric and pneumatic crimping tools are capturing expanded share in high-volume automotive wire harness plants where cycle-time consistency outweighs capital cost, while manual crimping tools retain durable demand among repair services and construction electricians requiring field portability without power dependency. Application segmentation shows automotive pulling ahead of telecommunications as 48V and high-voltage EV architectures multiply crimped junction density per vehicle platform.
FCC equipment authorization rules shape electromagnetic compatibility requirements for battery-powered electric crimping tools deployed in telecommunications infrastructure, while OSHA electrical safety standards govern insulated-handle specifications and operator protection protocols in construction environments. ISO 9001 quality management certification remains a baseline threshold for supplier qualification across aerospace and automotive OEM procurement gates. Stakeholders must weigh automation capital deployment against the resilience of manual tool demand in fragmented repair and retrofit channels.
Market Dynamics
Automotive electrification is multiplying termination points per vehicle platform, forcing wire harness manufacturers to recalibrate capital deployment between manual field kits and automated hydraulic systems for high-volume production lines.
Growth Catalysts
- 48V and High-Voltage EV Architectures:Battery-electric and hybrid vehicle platforms now require 40% more crimped junctions per harness than internal combustion equivalents, pulling precision termination equipment into assembly plants.
- EU RoHS and REACH Compliance:Tightening restrictions on hexavalent chromium coatings and cadmium-plated dies are accelerating replacement cycles for non-compliant tool inventories across European automotive supplier networks.
- Telecommunications Infrastructure Buildouts:Fiber-to-the-premises and 5G backhaul deployments in Germany and South Korea are expanding demand for coaxial and fiber optic crimping tools with MIL-spec pull-strength verification.
Market Restraints
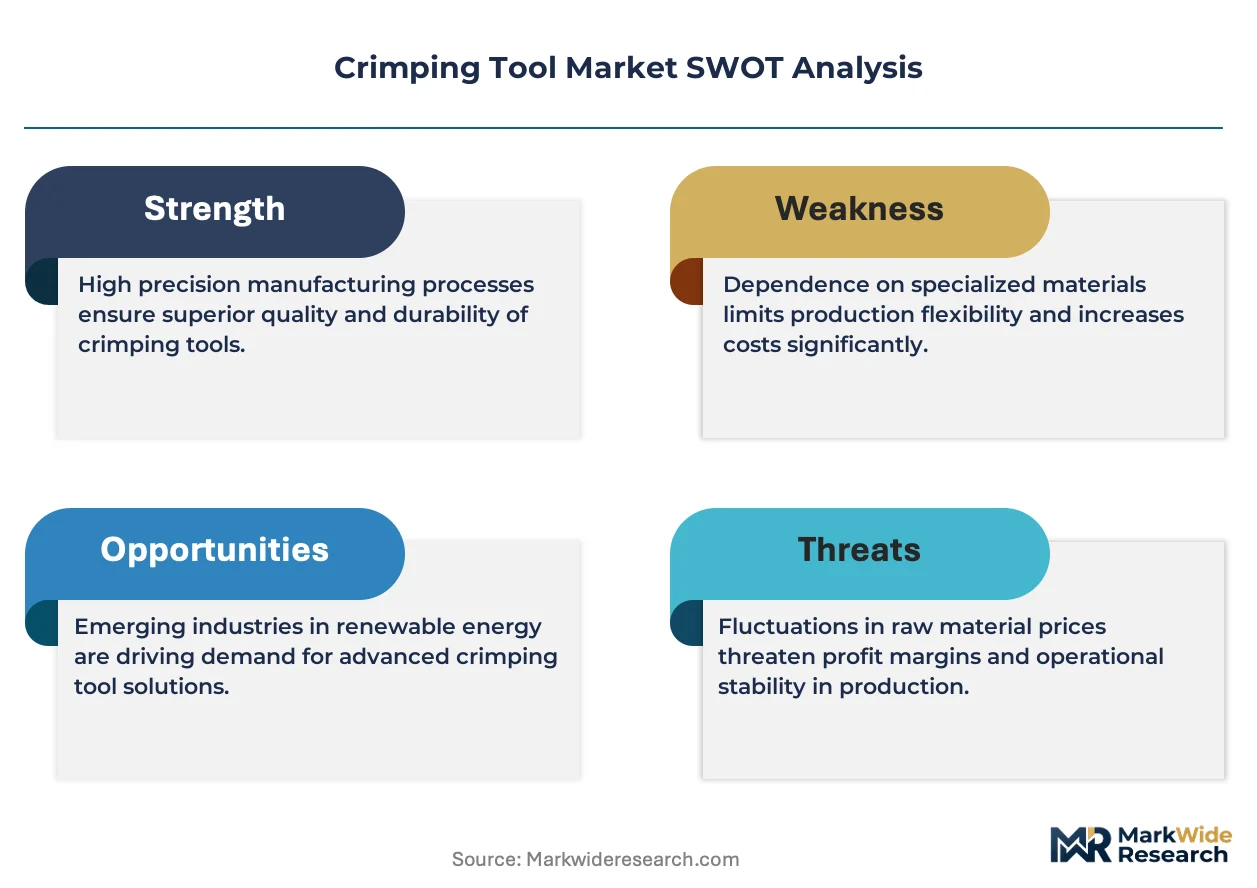
- Specialized Alloy Supply Concentration:Tool-grade tungsten carbide and high-speed steel production concentrates in China, exposing die manufacturers to export control volatility and input cost spikes.
- Technical Limitation of Battery-Powered Units:Cordless electric crimpers still deliver 15-20% lower peak force consistency than pneumatic equivalents, constraining adoption in aerospace-qualified termination workflows.
- Substitution by Ultrasonic Welding:Battery pack manufacturers are displacing crimped busbar connections with ultrasonic metal welding for high-current paths above 200A, compressing addressable market in EV power electronics.
Strategic Opportunities
- India Wire Harness Export Manufacturing:Suzuki, Hyundai, and Tata Motors are expanding captive harness production in Gujarat and Tamil Nadu, creating demand for mid-tier automated crimping platforms with localized service support.
- CSRD-Driven Tool Lifecycle Tracking:The EU Corporate Sustainability Reporting Directive mandates supply chain emissions disclosure, opening software-integrated crimping systems with usage analytics and predictive maintenance alerts.
- Convergence of Crimping and Cable Management:Panduit and integrated workflow providers are bundling termination tools with automated cable cutting and labeling systems, capturing labor savings in data center and commercial building installations.
Industry Challenges
- Crimp Technician Certification Bottlenecks:IPC/WHMA-A-620 and UL 486A-486B operator certification programs face 6-12 month backlogs, constraining workforce expansion for automotive harness suppliers in Germany and Mexico.
- Multi-Platform Die Compatibility:Proprietary die interfaces across TE Connectivity, Molex, and Amphenol terminal families force contract manufacturers to maintain redundant tool inventories, inflating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crimping Tool Market |
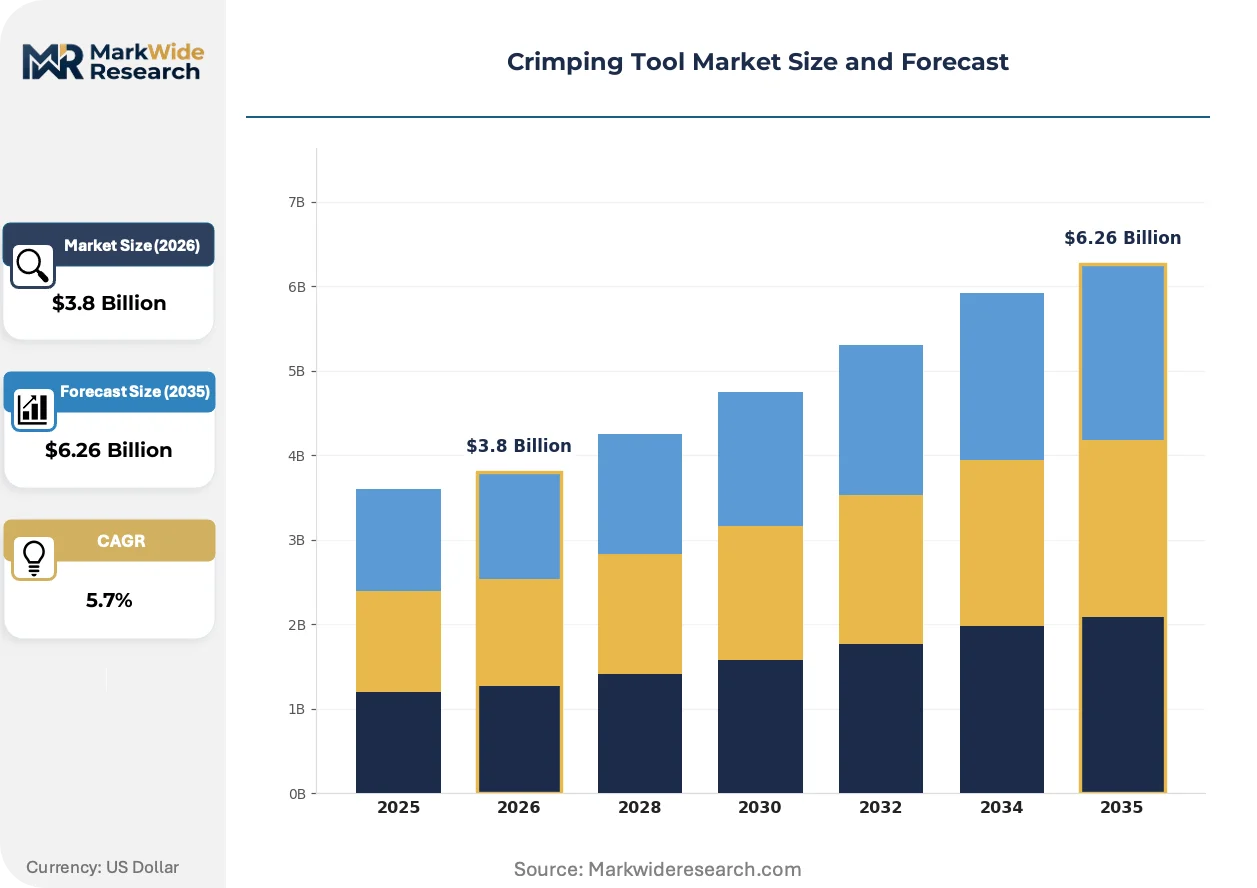
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Crimping Tools, Electric Crimping Tools, Pneumatic Crimping Tools, Hydraulic Crimping Tools Application: Electronics, Automotive, Telecommunications, Aerospace End User: Manufacturers, Repair Services, Construction, DIY Enthusiasts Size: Small, Medium, Large, Heavy-Duty |
| Companies Covered | Channellock, Inc., Molex, TE Connectivity Ltd., Panduit, Daniels Manufacturing Corporation, Phoenix Contact, Greenlee, Klein Tools, Inc., DEWALT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crimping Tool Market Evolving Landscape
Process control digitization and force-feedback integration are redefining quality assurance protocols, compressing the gap between manual operator skill and automated precision in high-mix, low-volume production environments.
Force-monitoring crimping technology is embedding piezoelectric sensors and real-time curve analysis directly into handheld and benchtop tools. Automotive tier-1 suppliers in Stuttgart and Detroit are adopting these systems to eliminate destructive pull-testing sampling. The technology is bifurcating quality assurance workflows: high-volume plants deploy fully automated hydraulic platforms with SPC integration, while job shops adopt sensor-equipped manual tools that flag out-of-spec crimps without stopping production.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are phasing out PTFE-based lubricants and certain anti-galling coatings used in crimp die assemblies. Tool manufacturers are reformulating surface treatments with ceramic-based alternatives and ion-plated titanium nitride. European aerospace suppliers face the steepest compliance timelines, with ECHA authorization requirements forcing die replacement programs ahead of typical wear-based refresh cycles.
Aftermarket service unbundling is disrupting traditional distributor relationships. Electrical contractors and maintenance fleets are sourcing replacement dies and calibration services directly from manufacturer digital portals, bypassing wholesale channels that previously captured 25-30 point margins. This pattern is most pronounced in North American construction verticals, where Klein Tools and Greenlee have established direct-to-user e-commerce platforms with same-day shipping for consumable die sets.
Crimping Tool Market Segmentation
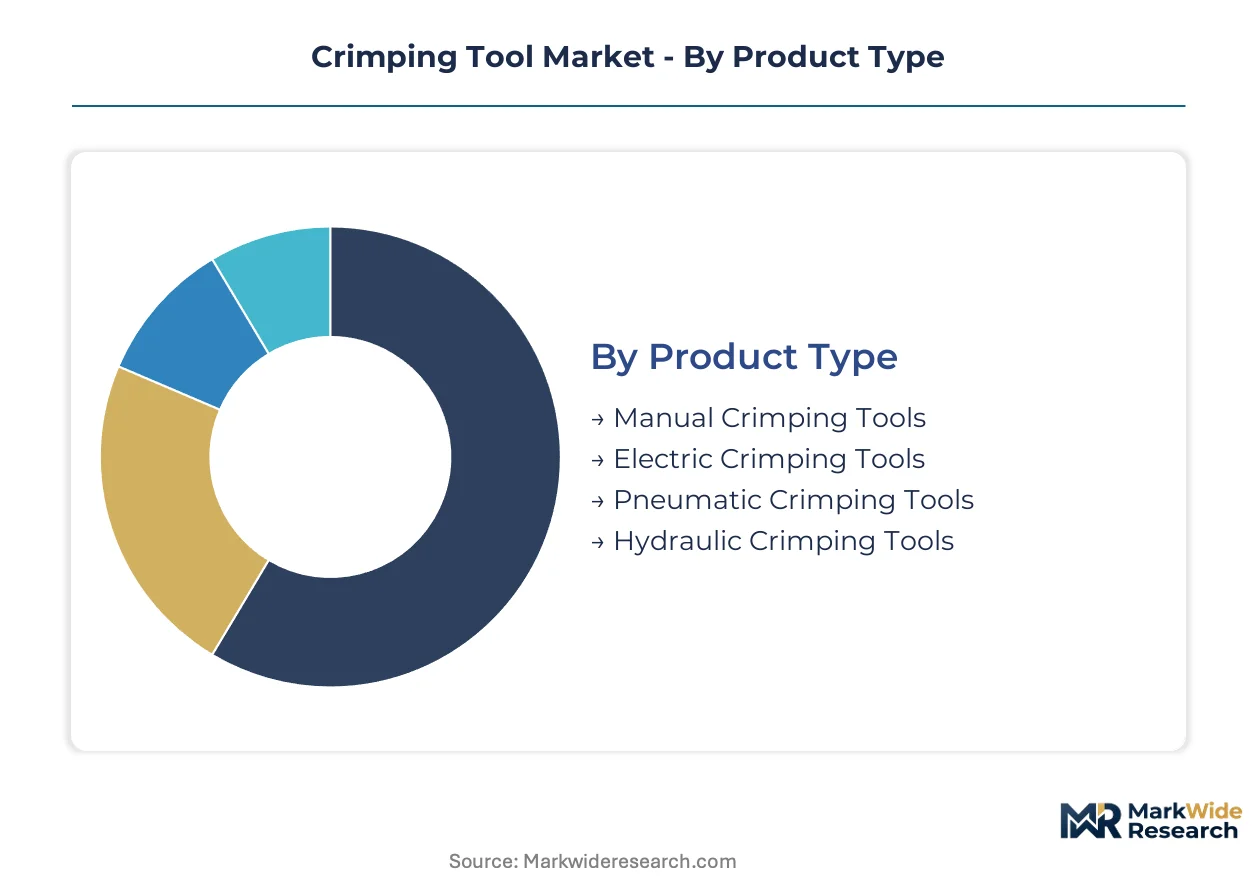
Crimping tool procurement patterns diverge sharply between high-volume automotive assembly plants requiring automated force consistency and fragmented field service channels prioritizing portability. Understanding these segment boundaries clarifies where suppliers can defend premium positioning versus competing on unit economics.
Product Type:
Margin pools concentrate in automated hydraulic and precision electric platforms where aerospace and automotive OEMs pay premiums for force verification and SPC integration.
- Manual Crimping Tools:Hand-actuated mechanical devices with ratchet or lever mechanisms delivering operator-dependent force. Repair services and construction electricians in Germany and the United States sustain durable demand for field-portable kits requiring no power infrastructure.
- Electric Crimping Tools:Battery-powered or corded motor-driven units with programmable force curves. Automotive wire harness plants in Stuttgart and Detroit are expanding procurement of these systems where cycle-time consistency outweighs capital cost premiums.
- Pneumatic Crimping Tools:Compressed-air-actuated platforms delivering superior peak force consistency for MIL-spec termination workflows. Aerospace suppliers favor these units despite facility infrastructure requirements.
- Hydraulic Crimping Tools:Fluid-pressure systems generating highest force ranges for heavy-gauge cable and busbar applications. EV battery pack manufacturers deploy these for high-current junctions above 200A.
The dominant share belongs to manual tools, while electric platforms are closing the gap fastest as automotive electrification multiplies factory automation requirements.
Application:
Volume concentration tracks vehicle platform electrification intensity, with termination point density per platform varying 40% between battery-electric and internal combustion architectures.
- Electronics:Miniaturized crimping for consumer device connectors and PCB-mounted terminals. South Korean and Taiwanese contract manufacturers drive demand for micro-precision dies with sub-millimeter tolerance.
- Automotive:Wire harness termination for 48V mild-hybrid through 800V high-voltage EV platforms. German OEMs and tier-1 suppliers in Baden-Württemberg represent the densest procurement cluster globally.
- Telecommunications:Coaxial and fiber optic connector crimping for 5G backhaul and fiber-to-the-premises buildouts. German and South Korean infrastructure deployments are expanding MIL-spec pull-strength verification requirements.
- Aerospace:Qualified termination systems for airframe and avionics harnesses governed by AS9100 and MIL-DTL-22520. European aerospace suppliers face accelerated die replacement cycles from REACH Annex XVII substance restrictions.
Automotive commands the largest revenue pool, though telecommunications is expanding most quickly as 5G infrastructure investment accelerates.
End User:
Procurement authority separates between capital-equipment buyers with multi-year amortization horizons and consumable-driven purchasers with immediate replacement cycles.
- Manufacturers:Tier-1 wire harness producers and OEM captive plants with automated production lines. These buyers prioritize force-monitoring integration and predictive maintenance analytics over unit cost.
- Repair Services:Independent automotive and industrial equipment maintenance providers. Indian wire harness export manufacturers in Gujarat and Tamil Nadu are emerging as significant mid-tier equipment buyers.
- Construction:Electrical contractors requiring insulated-handle specifications per OSHA electrical safety standards. North American distributors serve this channel through same-day die replacement logistics.
- DIY Enthusiasts:Consumer-grade manual kits for home wiring and hobbyist electronics. E-commerce direct-to-user platforms are compressing traditional wholesale margins in this segment.
Manufacturers retain the dominant procurement volume, while repair services are gaining share fastest as vehicle electrification extends aftermarket harness complexity.
Size:
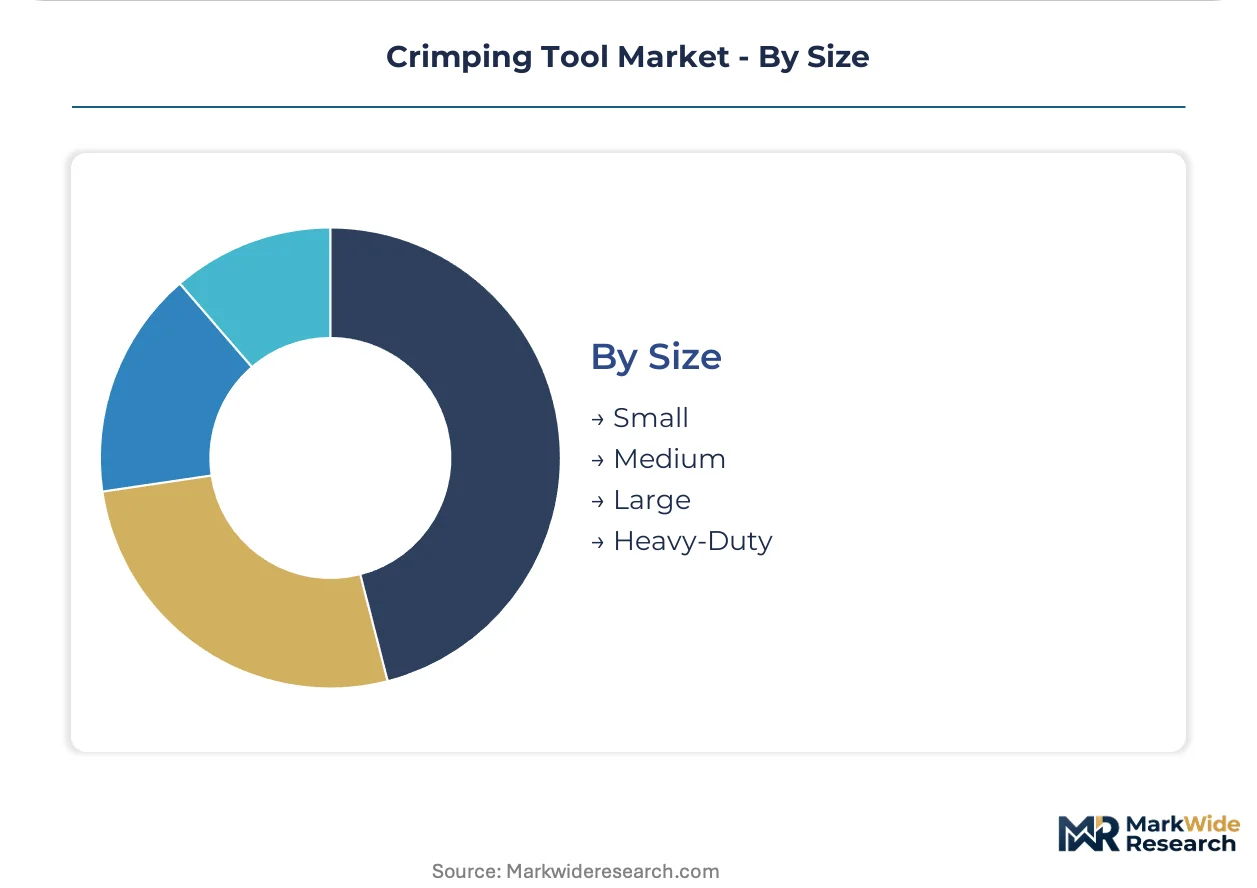
Tool specification scales with conductor gauge and termination force requirements, creating distinct supplier specialization zones.
- Small:Precision tools for AWG 30-20 gauge terminals in consumer electronics and medical devices. Miniaturization trends in wearable technology are sustaining demand for micro-die compatibility.
- Medium:General-purpose platforms covering AWG 18-10 gauge applications across automotive and industrial control systems. This specification band captures the broadest cross-industry demand.
- Large:Heavy-gauge termination for AWG 8-2/0 power distribution and industrial machinery. EV charging infrastructure buildouts are expanding procurement of large-format crimping systems.
- Heavy-Duty:Specialized platforms for busbar, substation, and grid-scale cable applications. Utility-grade procurement concentrates with hydraulic and pneumatic force delivery systems.
Medium-size tools hold the dominant position, while heavy-duty specifications are climbing the fastest as grid modernization and EV infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive supplier networks, where precision termination equipment commands 30-40% premiums over comparable platforms in Indian export manufacturing. This asymmetry reflects divergent certification requirements and labor cost structures rather than technical capability gaps.
Germany
Baden-Württemberg hosts the densest cluster of tier-1 wire harness suppliers serving Mercedes-Benz, Porsche, and BMW electrification programs. EU REACH Annex XVII substance restrictions on PFAS lubricants are accelerating die replacement cycles ahead of normal wear intervals. Stuttgart-based automotive electronics manufacturers are deploying force-monitoring crimping systems to eliminate destructive pull-testing sampling from quality workflows.
United States
Detroit-area automotive wire harness plants are expanding procurement of electric crimping platforms where cycle-time consistency outweighs capital cost premiums. OSHA electrical safety standards govern insulated-handle specifications for construction electrician channels. North American electrical contractor distribution runs through same-day die replacement logistics centered on Illinois and Texas warehouse networks.
China
Tool-grade tungsten carbide and high-speed steel production concentrates in Jiangsu and Hunan provinces, exposing die manufacturers to export control volatility. MIIT industrial equipment standards shape electromagnetic compatibility requirements for battery-powered electric crimping tools. Shenzhen and Dongguan electronics contract manufacturers drive demand for micro-precision dies with sub-millimeter tolerance for consumer device connectors.
India
Suzuki, Hyundai, and Tata Motors are expanding captive harness production in Gujarat and Tamil Nadu, creating procurement pull for mid-tier automated crimping platforms. BIS certification requirements for industrial electrical equipment are tightening import compliance for European and East Asian tool suppliers. Chennai and Ahmedabad industrial corridors are emerging as service hubs for localized maintenance and die refurbishment.
South Korea
5G backhaul and fiber-to-the-premises deployments are expanding MIL-spec pull-strength verification requirements for coaxial and fiber optic crimping tools. MFDS equipment safety frameworks apply to battery-powered tools deployed in telecommunications infrastructure buildouts. Seoul and Busan metropolitan areas concentrate demand from Samsung and LG electronics supply chains as well as KT and SK Telecom network expansion programs.
Crimping Tool Market Competitive Landscape
Concentration sits with diversified electrical component manufacturers that bundle termination tools with connector systems and cable management portfolios. The supplier base fragments between premium-tier platforms with captive metallurgy and die design capabilities, mid-tier automated systems for automotive volume production, and field-portable manual kits for construction and repair channels. Two strategic archetypes dominate: integrated workflow providers competing on labor reduction in commercial installations, and precision specialists defending position through aerospace qualification and automotive OEM certification. Competitive moves center on predictive maintenance software integration and direct-to-user e-commerce unbundling of aftermarket die replacement.
Among North American electrical tool specialists, Channellock, Inc., Klein Tools, Inc., and Greenlee exemplify the construction-channel archetype with deep distributor relationships and same-day consumable logistics. TE Connectivity Ltd. and Molex occupy positions within the integrated component-manufacturing tier, where captive terminal design drives proprietary die interface strategies. Daniels Manufacturing Corporation represents the aerospace-qualified precision specialist archetype with MIL-spec certification workflows. These named entities anchor competitive positioning without exhausting the supplier map, as regional fabricators and private-label assemblers fill volume tiers across Asian and European markets.
| Leading Market Players |
|---|
| Channellock, Inc. |
| Molex |
| TE Connectivity Ltd. |
| Panduit |
| Daniels Manufacturing Corporation |
| Phoenix Contact |
| Greenlee |
| Klein Tools, Inc. |
| DEWALT |
| Others |
Value Network & Pricing Analysis
Ceramic-based die coatings replacing PTFE lubricants under REACH Annex XVII are redrawing supplier economics, compressing margins for European toolmakers while elevating input costs for aerospace-qualified termination systems. This substitution dynamic simultaneously concentrates procurement leverage with Jiangsu-based tungsten carbide producers and forces pricing recalibration across die replacement cycles.
Pricing Analysis
The customization-premium spread between configured-to-order hydraulic platforms and standard manual kits reaches three-to-one in automotive procurement. Three-tier pricing structure across aerospace-certified, automotive-production, and field-portable economy levels tracks certification grade and force-monitoring integration. Pricing pressure stems from ultrasonic welding displacement in EV battery busbar applications above 200A. Construction electricians exhibit highest price sensitivity, while aerospace OEMs prioritize pull-strength verification over unit cost.
Supply Chain Analysis
China anchors global production of tool-grade tungsten carbide and high-speed steel dies in Jiangsu and Hunan provinces. Raw material flows draw from Australian cobalt concentrates, Japanese precision ceramics, and German hydraulic componentry. Single-source vulnerability concentrates in export-controlled carbide substrates. Distribution runs through regional distributor networks with same-day die replacement logistics in North America and captive service hubs in Indian industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect where proprietary die interfaces lock contract manufacturers into redundant tool inventories, creating interoperability arbitrage for open-standard challengers.
For Market Incumbents: Secure captive metallurgy capabilities and accelerate predictive maintenance software integration to defend against ultrasonic welding substitution in high-current EV applications. Prioritize backward integration into ceramic-based surface treatments ahead of REACH Annex XVII compliance deadlines. Channel control through direct-to-user e-commerce portals compresses wholesale margin capture from aftermarket die replacement. For New Entrants and Emerging Players: Lead with open-architecture die compatibility targeting Indian wire harness export manufacturers in Gujarat and Tamil Nadu seeking to reduce redundant tool inventories. The most penetrable white space sits in mid-tier automated platforms with localized service support. A software-integrated go-to-market bundling usage analytics and predictive maintenance alerts captures CSRD-driven procurement preference. For Investors and Strategic Acquirers: Capital is best deployed toward precision specialists with captive aerospace qualification and in-house die design capabilities. Long-term viability hinges on force-monitoring technology integration and software-enabled lifecycle tracking. The signal to watch is adoption velocity of piezoelectric sensor-equipped manual tools in high-mix, low-volume production environments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Coatings | Eliminates REACH Annex XVII compliance risk for aerospace die replacement cycles. |
| Predictive Maintenance Software Launch | Captures CSRD-driven procurement preference with usage analytics integration. |
| Open-Standard Die Platform Development | Reduces contract manufacturer working capital burden from redundant inventories. |
| Direct-to-User E-Commerce Expansion | Bypasses wholesale channels capturing 25-30 point margins on consumable die sets. |
| Localized Service Hub Establishment | Supports Suzuki, Hyundai, and Tata Motors harness production expansion in India. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with wire harness procurement directors, plant engineers at tier-1 automotive suppliers, aftermarket service heads, and distributor category managers; and secondary validation through customs trade data, SEC filings from diversified electrical component manufacturers, OSHA electrical safety standard documentation, and EU REACH Annex XVII regulatory filings. Bottom-up sizing triangulated equipment unit shipments against top-down value aggregation across product type, application, and end-user segments.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation dimensions including tool actuation mechanism, termination force range, industry certification tier, and regional production cluster concentration. CAGRs derived from trend extrapolation of automotive electrification intensity, telecommunications infrastructure buildout pacing, and regulatory compliance-driven replacement cycles. Industry-specific forecast inputs incorporated EV platform crimped junction density differentials and REACH substance restriction phase-out timelines.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital deployment, stable alloy supply from Chinese production centers, and continued REACH enforcement stringency would require recalibration. Forecasts reflect documented assumptions regarding technician certification pipeline expansion and ultrasonic welding displacement limits in power electronics. Recalibration cycles align with material shifts in EU substance restrictions, export control volatility, and force-monitoring technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Ladder Market
Tools
Hydraulic Tools and Equipment Market
Tools
Bandsaw Machines Market
Tools
Global Flange Fasteners Market
Tools
Europe Woodworking Power Tools Market
Tools
DIY Ball Mill Market
Tools
Mechanical Hand Tools Market
Tools
Chainsaw Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Digital Cutting Machine Market
Tools
Quick Release Pins Market
Tools
Pneumatic Bolting Tools Market
Tools
Global Cordless Power Tools Market
Tools
Masonry Cleaners Market
Tools
Industrial Hand Tools Market
Tools
Indexable Inserts Market