
 Europe Woodworking Power Tools Market | 2026-2036
Europe Woodworking Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Woodworking Power Tools Market Foresight
Tool-as-a-service subscription models for fleet maintenance and software-enabled diagnostics is realigning how European woodworking operations procure equipment. Bosch leverages its service network to anchor long-term contracts with industrial furniture manufacturers. Festool GmbH differentiates through precision-specialized systems for high-end cabinet making workflows. Makita Corporation competes on battery platform interoperability across contractor segments.
Woodworking power tools encompass motorized equipment designed for material removal, shaping, and joinery in timber and engineered wood products, typically operating at speeds from 10,000 to 25,000 RPM for routing applications and requiring dust extraction interfaces compliant with workplace exposure limits. These tools serve furniture factories, installation trades, and fabrication workshops where dimensional accuracy and surface finish determine product value. Saws dominate value generation in industrial settings where beam processing and panel sizing constitute core production steps. Cordless electric technology is displacing pneumatic systems in mobile applications across flooring installation and on-site joinery, though compressed air retains cost advantages in fixed factory lines. Hobbyist use represents a margin-accretive segment where premium-brand positioning commands price premiums despite lower absolute volumes.
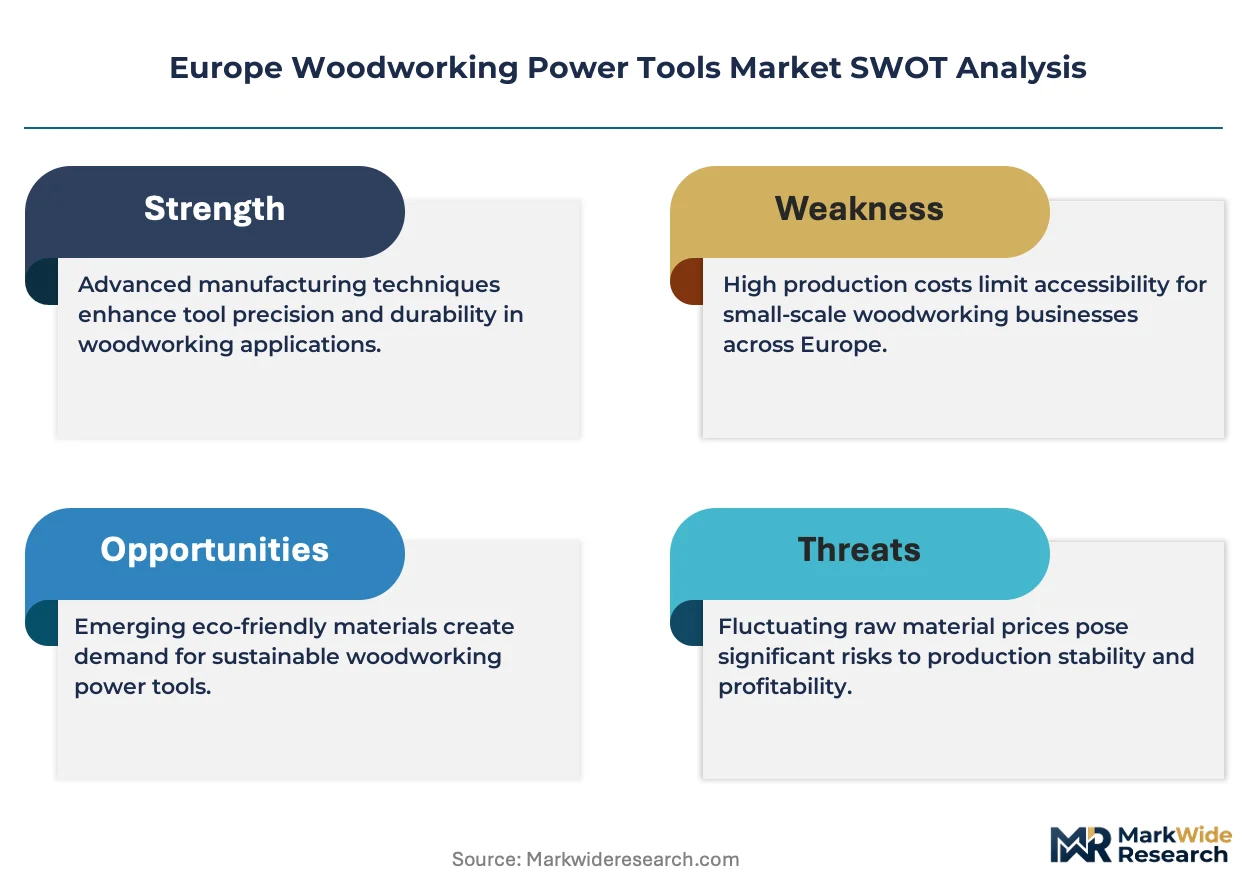
CE marking under the EU Machinery Directive and REACH compliance for chemical substances in surface coatings constrain product design and market entry for non-European suppliers. The EU F-Gas Regulation and national implementations of the EU Green Deal are accelerating demand for brushless motor architectures and energy-efficient drive systems in woodworking equipment. Stakeholders must monitor evolving Ecodesign requirements and battery passport regulations that will reshape component sourcing and end-of-life obligations across the value chain.
Market Dynamics
Brushless motor architectures and battery platform standardization are compressing replacement cycles across European woodworking operations, while the EU Green Deal's machinery efficiency mandates force capital redeployment toward cordless electric fleets in German and Italian industrial clusters.
Growth Catalysts
- F-Gas Regulation Phase-Down:The EU F-Gas Regulation's refrigerant restrictions accelerate factory equipment upgrades, pulling demand for compliant dust extraction and climate-controlled storage systems in Northern Italian cabinetry districts.
- Cordless Battery Interoperability:Shared battery platforms across multiple tool categories reduce fleet complexity for flooring contractors and on-site joinery crews operating across Belgium and the Netherlands.
- Furniture Export Resurgence:German industrial furniture manufacturers expand production capacity to serve Middle Eastern and North African markets, driving beam processing and panel sizing equipment procurement.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell sourcing concentrates among East Asian suppliers, exposing European tool assemblers to raw material price volatility and logistics bottlenecks.
- CE Marking Compliance Burden:The EU Machinery Directive's conformity assessment procedures extend time-to-market for non-European suppliers, protecting incumbent regional manufacturers.
- Pneumatic System Lock-In:Fixed factory lines in Poland and Czech Republic retain compressed air infrastructure due to lower lifecycle costs, slowing cordless displacement in high-volume beam processing.
Strategic Opportunities
- Tool-as-a-Service Expansion:Subscription-based fleet maintenance and predictive diagnostics penetrate mid-sized Austrian and Swiss woodworking cooperatives previously priced out of premium service tiers.
- EU Battery Passport Mandate:Upcoming regulations on battery traceability and end-of-life obligations create first-mover advantage for manufacturers with established circular supply chains.
- High-End Hobbyist Segment:Precision-specialized systems for home workshop users in France and Scandinavia command margin premiums despite lower absolute volumes compared to industrial procurement.
Industry Challenges
- Mechatronics Skill Shortage:Maintenance of brushless motor controllers and smart diagnostics requires technicians trained in firmware troubleshooting, a capability scarce in traditional woodworking regions.
- Legacy Pneumatic Integration:Hybrid workshops struggle to synchronize cordless electric workflows with existing compressed air lines, creating operational friction during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Woodworking Power Tools Market |
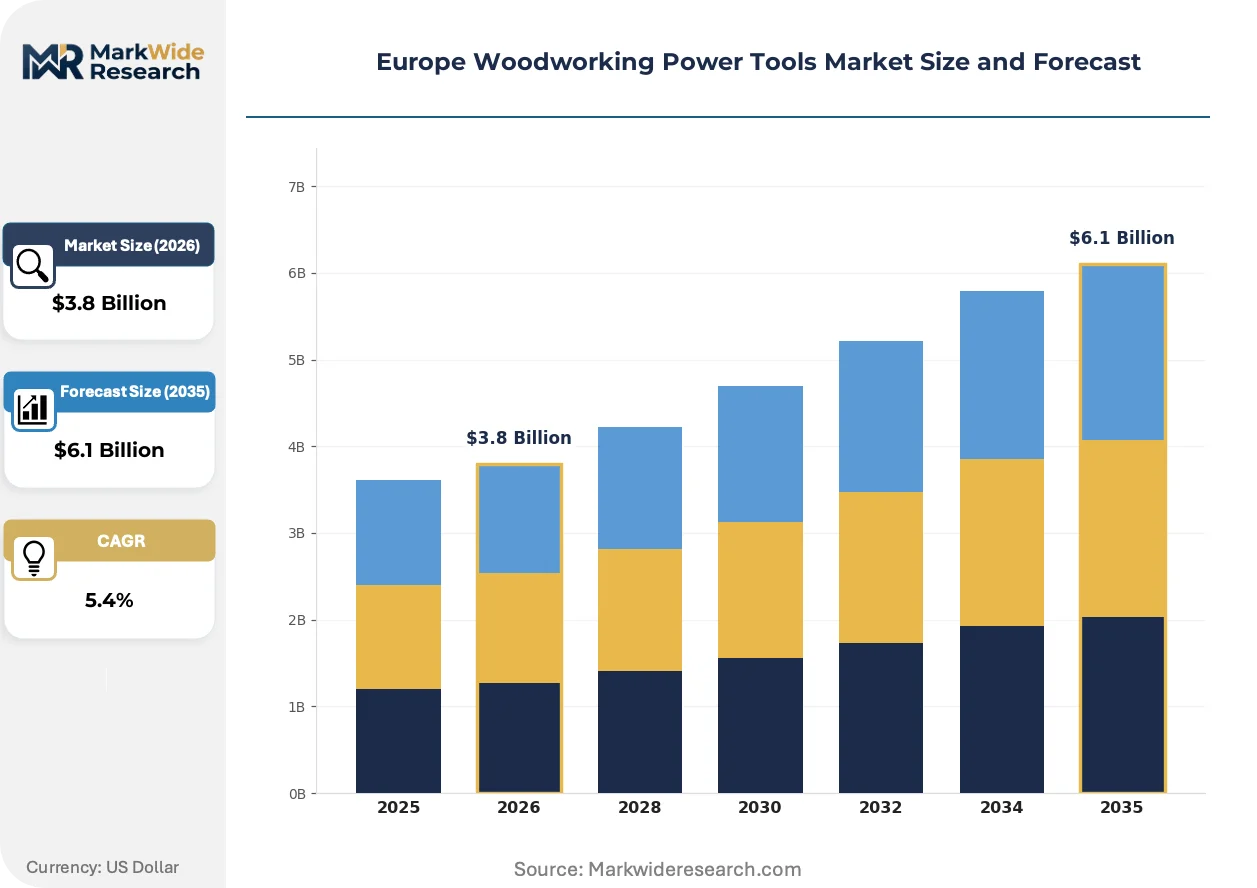
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saws, Drills, Routers, Sanders Technology: Electric, Pneumatic, Hydraulic, Manual Application: Furniture Production, Cabinet Making, Flooring Installation, Hobbyist Use Customer Type: Industrial Users, Contractors, DIY Enthusiasts, Retailers |
| Companies Covered | Bosch, Makita Corporation, Stanley Black & Decker, Festool GmbH, Hilti Corporation, DeWalt, FEIN Power Tools, Milwaukee Tool, Ferm International B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Woodworking Power Tools Market Shifts & Advancements
Intelligent tool connectivity and embedded diagnostics are redefining equipment value propositions, shifting competitive differentiation from raw specifications toward software-enabled productivity guarantees and uptime commitments.
Brushless DC motor systems with integrated variable-speed controllers are expanding into heavy-duty routing and beam processing applications previously dominated by corded AC motors. German industrial furniture manufacturers adopt these platforms fastest, driven by energy efficiency mandates and factory electrification roadmaps. The technology is expanding into cost-sensitive segments as motor controller costs decline and battery energy density improves.
The EU Ecodesign Directive's expanding scope now covers woodworking machinery standby power consumption and motor efficiency classes. Manufacturers must redesign drive systems to meet minimum efficiency thresholds or face market exclusion. Italian panel processing equipment suppliers respond fastest, leveraging existing relationships with efficiency-focused German buyers to certify compliant product lines ahead of enforcement deadlines.
Buying committees at large furniture factories now unbundle equipment procurement from aftermarket service contracts, pitting specialized maintenance providers against original manufacturers. This pattern concentrates in German industrial clusters where procurement functions have professionalized. Austrian flooring installation cooperatives follow, demanding transparent parts pricing and third-party diagnostic access as conditions of purchase.
Europe Woodworking Power Tools Market Segmentation
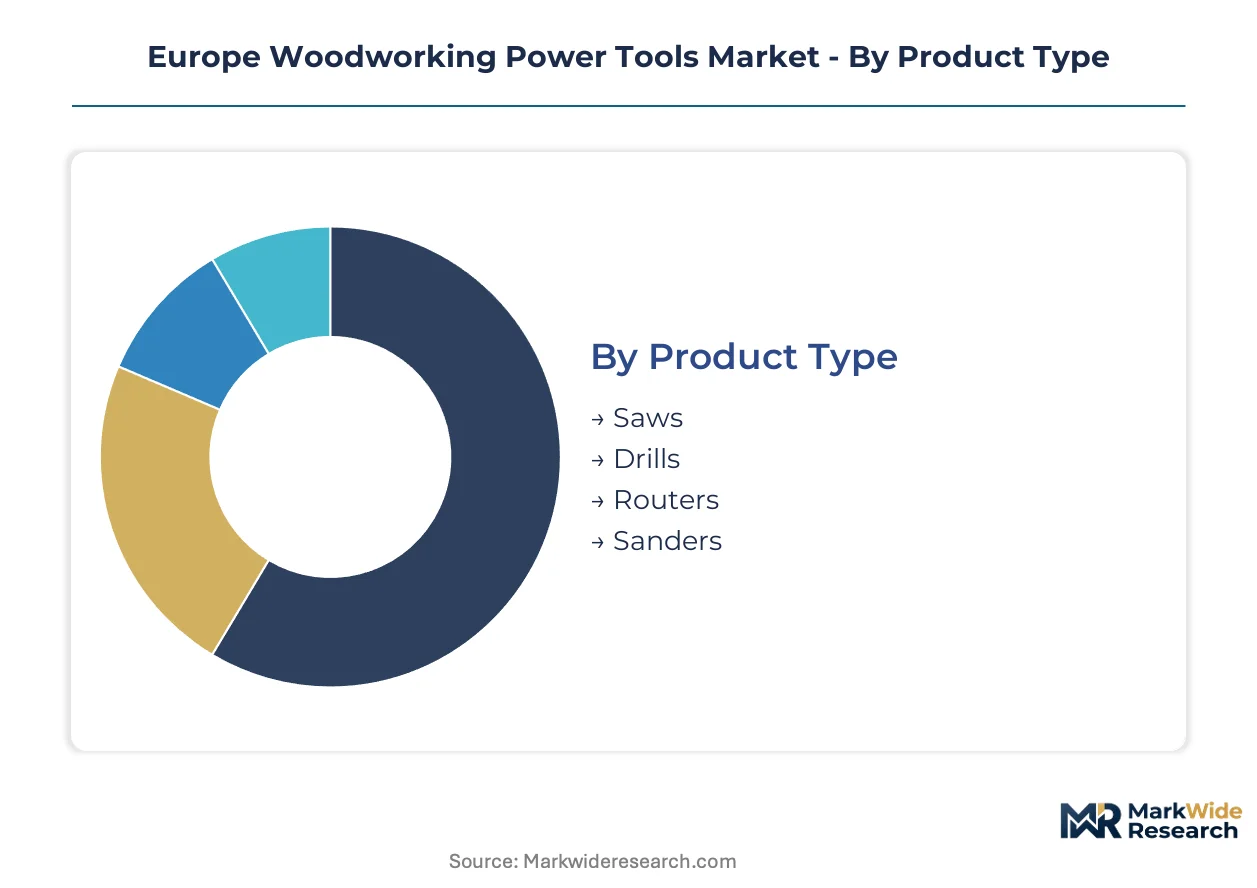
Woodworking power tools serve distinct operational contexts across European manufacturing clusters, with equipment specifications diverging sharply between stationary factory installations and mobile on-site deployment. Segmentation reveals where cordless architectures displace legacy systems and where pneumatic infrastructure retains cost advantages.
Product Type:
Standalone cutting equipment dominates capital allocation in German beam processing facilities, while embedded shaping tools integrate into automated panel sizing lines across Northern Italian districts.
- Saws:Beam processing and panel sizing equipment generate the highest value per unit in industrial furniture factories. German manufacturers serving Middle Eastern export markets drive procurement of high-capacity sliding table saws and CNC beam saws.
- Drills:Cordless drill drivers with brushless motor architectures penetrate flooring installation crews and on-site joinery teams across Belgium and the Netherlands. Interoperable battery platforms reduce fleet complexity for contractors managing mixed tool inventories.
- Routers:Precision spindle motors operating at 10,000-25,000 RPM shape edge profiles and joinery in high-end cabinet making workflows.
- Sanders:Random orbital and belt sanding systems with integrated dust extraction interfaces serve surface finish requirements in Austrian woodworking cooperatives.
Volume placements concentrate in Saws; the faster expansion belongs to Drills.
Technology:
Cost tier separation runs deepest between capital-intensive factory electrification and low-investment pneumatic retention in Polish and Czech beam processing halls.
- Electric:Brushless DC motor systems with integrated variable-speed controllers displace corded AC platforms in heavy-duty routing applications. EU Ecodesign Directive efficiency mandates and F-Gas Regulation compliance accelerate factory upgrades toward electrified dust extraction and climate-controlled storage.
- Pneumatic:Compressed air infrastructure retains lifecycle cost advantages in fixed high-volume production lines across Poland and Czech Republic industrial zones. Legacy system lock-in slows cordless displacement despite energy efficiency penalties.
- Hydraulic:High-torque systems persist in specialized timber framing and engineered wood beam pressing operations.
- Manual:Hand-powered tools serve hobbyist segments and backup applications where power access is unreliable.
Electric platforms command the steepest expansion trajectory; pneumatic systems defend installed base in cost-sensitive production environments.
Application:
Customer maturity separates industrial procurement functions with professionalized buying committees from fragmented hobbyist demand concentrated in French and Scandinavian home workshops.
- Furniture Production:German industrial manufacturers unbundle equipment procurement from aftermarket service contracts, demanding transparent parts pricing and third-party diagnostic access. Beam processing and panel sizing constitute core production steps with highest capital intensity.
- Cabinet Making:Northern Italian cabinetry districts respond fastest to EU Ecodesign Directive efficiency mandates, leveraging existing relationships with German buyers to certify compliant product lines.
- Flooring Installation:Mobile contractor crews across Austria and Switzerland adopt shared battery platforms to reduce fleet complexity during on-site deployment.
- Hobbyist Use:Premium-brand positioning commands margin premiums in French and Scandinavian home workshops despite lower absolute volumes compared to industrial procurement.
Revenue concentration sits with Furniture Production; Cabinet Making gains share fastest among precision-specialized system suppliers.
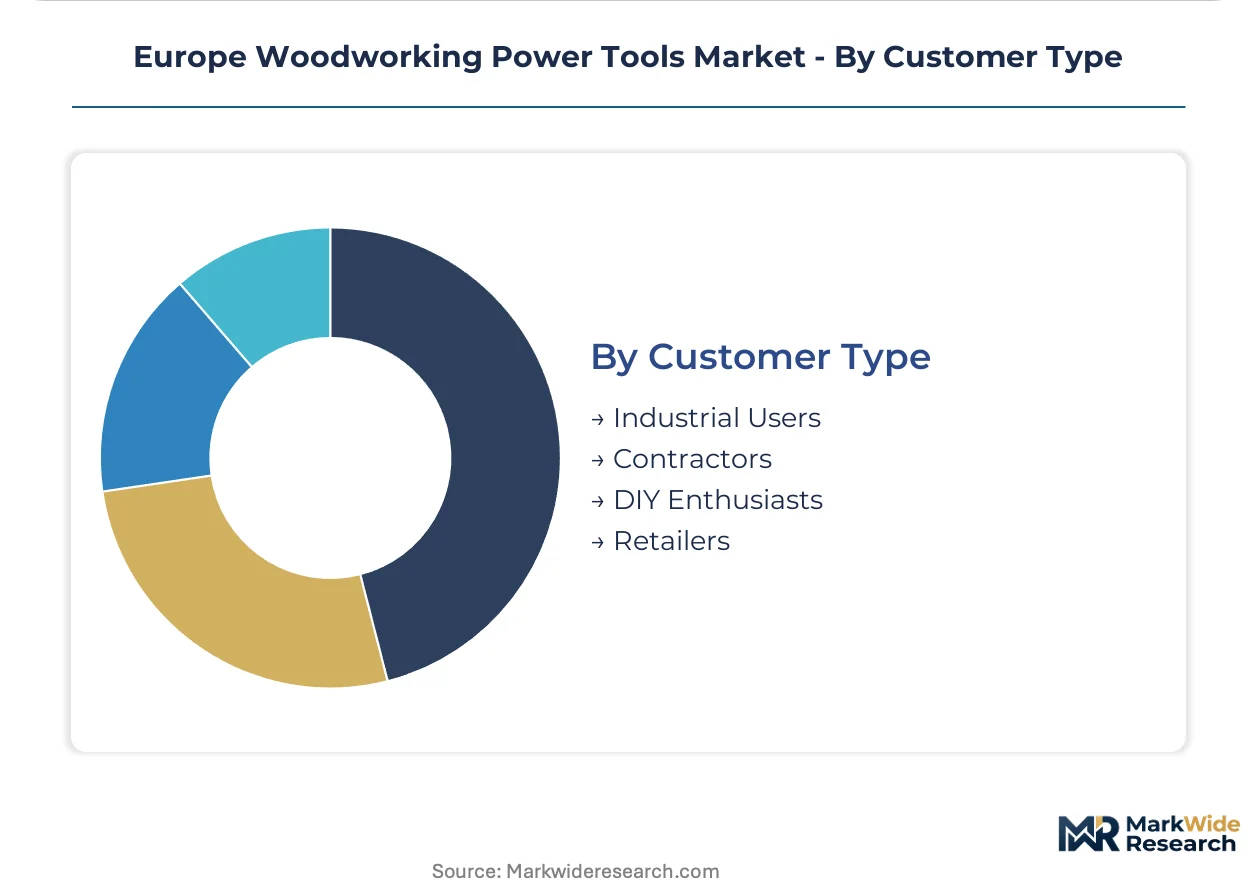
Customer Type:
Supply concentration aligns with procurement sophistication, as industrial users and contractors consolidate purchasing through tool-as-a-service subscriptions while DIY enthusiasts and retailers fragment across dispersed channels.
- Industrial Users:Large furniture factories professionalize procurement functions, pitting specialized maintenance providers against original manufacturers in aftermarket service competition. Tool-as-a-service models penetrate previously premium-excluded segments.
- Contractors:Flooring and joinery crews operating across Belgium, Netherlands, and Swiss border regions prioritize battery platform interoperability across multiple tool categories.
- DIY Enthusiasts:Home workshop users in France and Scandinavia drive demand for precision-specialized systems with premium positioning.
- Retailers:Distribution channels stock margin-accretive hobbyist equipment while industrial sales run direct through manufacturer service networks.
Contractor segment placements expand most quickly; Industrial Users anchor absolute volume through fleet-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's industrial corridor anchors European woodworking power tool demand through its dense concentration of precision machinery manufacturers and furniture production facilities serving export markets.
Germany
Furniture factories in North Rhine-Westphalia expand beam processing capacity to serve Middle Eastern export contracts. The EU Green Deal's machinery efficiency mandates accelerate brushless motor adoption in dust extraction systems. Industrial clusters around Stuttgart and Bielefeld drive procurement of high-capacity sliding table saws and CNC beam processing equipment.
Italy
Northern Italian cabinetry districts in Lombardy and Veneto respond fastest to Ecodesign Directive efficiency thresholds for standby power consumption. REACH compliance requirements for chemical substances in surface coatings constrain supplier qualification. The Brianza furniture manufacturing zone near Milan certifies compliant product lines ahead of enforcement deadlines.
Netherlands
Flooring installation crews operating across the Randstad prioritize battery platform interoperability to reduce fleet complexity during cross-border deployment. The EU F-Gas Regulation's refrigerant restrictions pull demand for climate-controlled storage systems. Amsterdam-Rotterdam corridor contractors consolidate purchasing through shared battery platforms.
Switzerland
Austrian and Swiss woodworking cooperatives adopt tool-as-a-service subscriptions previously priced out of premium maintenance tiers. National implementations of EU Green Deal efficiency standards accelerate cordless electric fleet conversion. Zurich and Basel industrial zones witness predictive diagnostics penetration among mid-sized fabrication workshops.
Poland
Fixed factory lines in Silesian and Greater Poland industrial zones retain compressed air infrastructure due to lower lifecycle costs in high-volume beam processing. CE marking conformity assessment procedures extend time-to-market for non-European equipment suppliers. Warsaw and Łódź manufacturing corridors defend pneumatic system lock-in despite energy efficiency penalties.
Europe Woodworking Power Tools Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated vendor base where incumbent European manufacturers defend position through service network density. The market structure tiers between premium precision specialists, battery platform consolidators, and industrial fleet service providers. Strategic moves concentrate on tool-as-a-service subscription expansion and predictive diagnostics integration.
Within the premium precision tier, Festool GmbH and FEIN Power Tools exemplify specialized system suppliers targeting high-end cabinet making workflows. Bosch anchors the industrial service network vector through long-term fleet maintenance contracts with furniture manufacturers. Makita Corporation occupies a position defined by battery platform interoperability across contractor segments in Belgium and Netherlands border regions.
| Leading Market Players |
|---|
| Bosch |
| Makita Corporation |
| Stanley Black & Decker |
| Festool GmbH |
| Hilti Corporation |
| DeWalt |
| FEIN Power Tools |
| Milwaukee Tool |
| Ferm International B.V. |
| Others |
Supply & Pricing Matrix
Lithium-ion battery cells feed from East Asian suppliers through three pricing tiers before reaching European tool assemblers, with raw material volatility compressing margins at the standard tier while premium brands absorb costs through service bundling.
Pricing Analysis
Outcome-based pricing anchors premium tier positioning, where uptime guarantees and predictive maintenance contracts command 40-60% markups over transactional equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates Festool and FEIN precision systems from mid-market Bosch and Makita platforms, with entry-tier pneumatic tools defending share in Polish beam processing halls. Cost compression in the standard tier is intensifying because battery cell sourcing concentrates among South Korean and Chinese suppliers. DIY enthusiasts in French and Scandinavian markets exhibit lowest price sensitivity, while Austrian flooring cooperatives negotiate aggressively on fleet-scale subscriptions.
Supply Chain Analysis
Refurbishment flows for brushless motor controllers and battery packs are creating secondary supply channels that compete with original manufacturer spare parts pricing. Component sourcing concentrates in China for battery cells, Germany for precision spindle motors, and Taiwan for motor controller semiconductors. The supply chain rests on rare earth magnet dependencies for brushless architectures and copper winding supplies for traditional motors. Single-source vulnerability in battery management system chips exposes assemblers to allocation risk during semiconductor cycles. Distribution runs through manufacturer-direct service networks for industrial accounts and specialized trade distributors for contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor architectures are displacing corded AC platforms across European woodworking operations, compressing replacement cycles and forcing capital redeployment toward battery-interoperable fleets.
For Market Incumbents: Acquire predictive diagnostics software capabilities to anchor tool-as-a-service contracts against emerging fleet-management platforms. Consolidate aftermarket service density in Stuttgart and Bielefeld industrial corridors before specialized maintenance providers capture buying committee procurement. CE marking compliance investment protects against non-European entrants exploiting extended conformity timelines. For New Entrants and Emerging Players: Direct-to-contractor digital channels bypass incumbent service network advantages in Belgian and Dutch border regions. White-space concentration sits with mid-sized Austrian woodworking cooperatives previously priced out of premium predictive maintenance tiers. Target entry through battery platform interoperability certifications that reduce fleet complexity for flooring installation crews. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-specialized system suppliers with established CE marking pathways and Northern Italian cabinetry district relationships. Five-to-ten year viability hinges on circular supply chain readiness for EU Battery Passport mandates. Monitor brushless motor controller firmware development pipelines as inflection indicator for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Makita's interoperability investments reduce fleet complexity for Belgian flooring contractors. |
| Predictive Diagnostics Integration | Bosch leverages service network density to anchor long-term furniture manufacturer contracts. |
| Tool-as-a-Service Expansion | Subscription models penetrate Austrian cooperatives previously excluded from premium tiers. |
| CE Marking Fast-Track Certification | Italian panel equipment suppliers certify ahead of Ecodesign Directive enforcement deadlines. |
| Circular Supply Chain Development | EU Battery Passport readiness creates first-mover advantage for end-of-life obligation compliance. |
Research Methodology
Multi-period observation of cordless displacement rates and pneumatic retention patterns anchored the trend analysis, supplemented by interviews with maintenance directors at German furniture factories, aftermarket service heads at Bosch and Festool, procurement leads at Austrian flooring cooperatives, and plant engineers in Polish Silesian industrial zones. Secondary validation drew from EU Machinery Directive implementation records, ECHA REACH substance databases, F-Gas Regulation phase-down schedules, and customs data on woodworking equipment imports. Bottom-up equipment procurement tracking and top-down manufacturing capacity estimates were triangulated against regional production cluster surveys.
Input-output matrices modeled demand drivers across product type, technology architecture, application intensity, and customer procurement sophistication dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included EU Green Deal machinery efficiency mandate implementation timelines and battery energy density improvement curves from cell supplier technical disclosures.
The model holds under stable lithium-ion supply conditions and gradual CE marking enforcement; deviation in raw material export restrictions or accelerated Ecodesign Directive scope expansion would shift equipment upgrade timing and cordless adoption trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Metal Forming Machine Tools Market
Tools
End Mill Holder Market
Tools
US Hitter Based Hand Tools Market
Tools
Brushcutter Market
Tools
Water Pump Pliers Market
Tools
Trim Press Market
Tools
Pipe Alignment Clamps Market
Tools
Woodworking Tools Market
Tools
Total Station Market
Tools
Boring Tools Market
Tools
Drill Presses Market
Tools
Global Construction Camera Market
Tools
Global Vertical Grinding Machine Market
Tools
End Milling Machine Market
Tools
Global Standard Parts for Tool Making Market
Tools
Cordless Trim Routers Market