
 Right Angle Fastener Market | 2026-2036
Right Angle Fastener Market Size, Share, and Industry Trends Forecast 2026-2036
Right Angle Fastener Market Analytics
ASTM-grade and aerospace-specification fastener tiers are redrawing competitive boundaries in the right angle fastener category. Penn Engineering leverages captive cold-heading capacity to dominate precision aerospace and electronics applications. BOSSARD Group anchors European supply through its vendor-managed inventory systems and local engineering centers. Simpson Strong-Tie Company specializes in structural-rated connectors for timber and concrete construction, sustaining brand authority in building codes.
A right angle fastener is a mechanical joining device engineered with a perpendicular axis configuration, typically manufactured through cold forging, thread rolling, and heat treatment to achieve tensile strengths exceeding 800 MPa in alloy steel variants. Its primary function is to create rigid, orthogonal connections in confined assembly spaces where conventional axial fasteners cannot operate. Steel material grades retain the largest volume share due to load-bearing requirements in construction and machinery, while aluminum variants are gaining traction in automotive lightweighting programs where corrosion resistance and mass reduction intersect. The construction end-user segment represents the most mature demand pool, whereas electronics assembly applications exhibit the fastest specification escalation as miniaturization drives finer thread pitches and tighter tolerances.
The EPA regulates surface coating chemistries under air quality standards, restricting hexavalent chromium conversion coatings and redirecting demand toward trivalent and zinc-nickel alternatives. ASTM International and ISO 898-1 govern mechanical property classifications, creating compliance thresholds that filter low-specification imports from critical-load applications. Stakeholders must monitor evolving building code adoptions in North American jurisdictions and automotive OEM material qualification timelines to align capacity with specification-grade demand shifts.
Market Dynamics
Specification-grade fastener demand is bifurcating around REACH-mandated coating chemistries and automotive OEM lightweighting programs, compressing margins for commodity-grade suppliers while rewarding certified precision manufacturers with captive heat-treatment capacity.
Growth Catalysts
- Aerospace fastener specifications:FAA airworthiness directives and Boeing/Airbus qualification protocols are expanding procurement of corrosion-resistant alloy systems for next-generation airframe assembly.
- REACH Article 33 compliance:ECHA substance restrictions on hexavalent chromium are redirecting coating line investments toward trivalent and zinc-nickel alternatives across German and French manufacturing clusters.
- Automotive lightweighting:Aluminum right-angle variants with 30-40% mass reduction are penetrating electric vehicle battery tray and motor mount applications.
Market Restraints
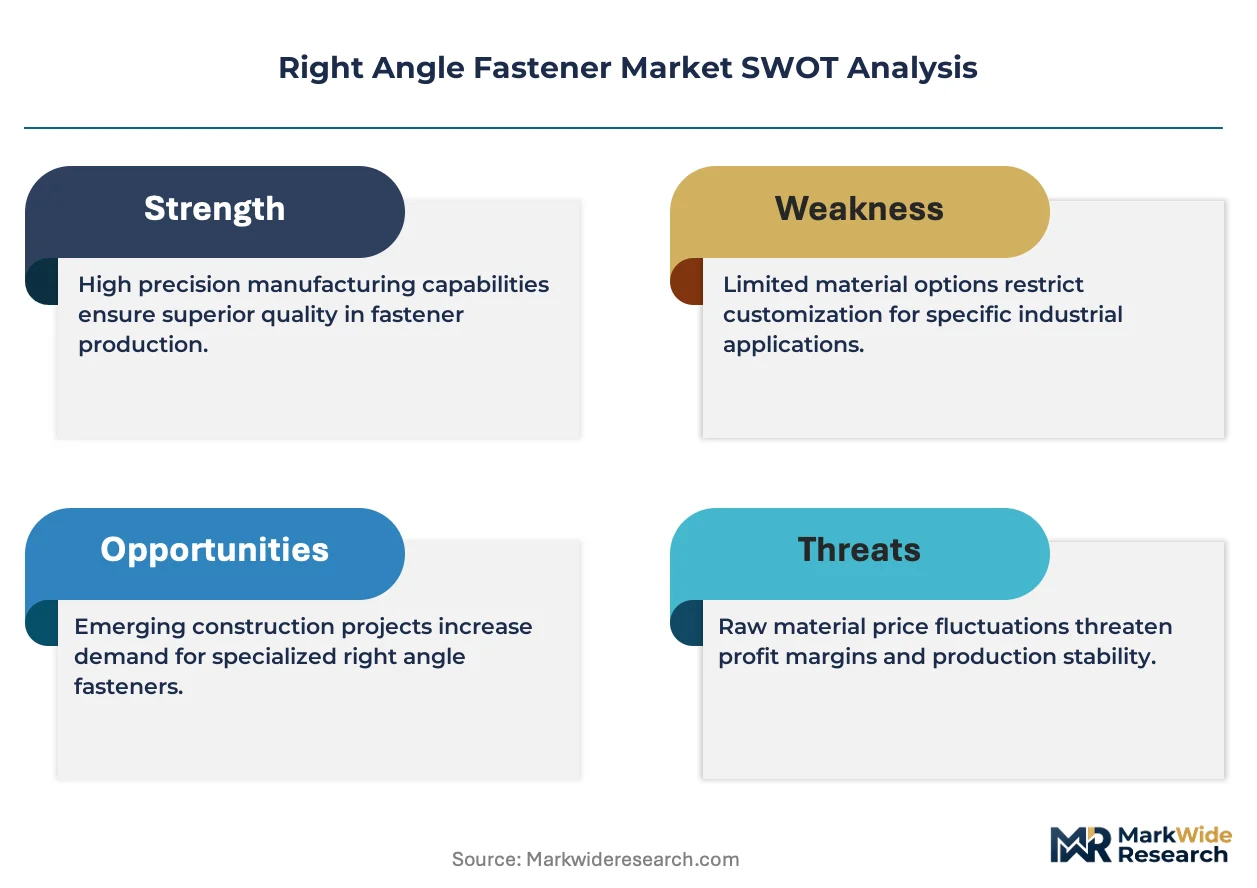
- Alloy steel input volatility:Scrap metal and nickel price swings compress margin predictability for cold-forging operations dependent on commodity-grade feedstock.
- Heat-treatment capacity concentration:Vacuum carburizing and nitriding infrastructure clusters in Germany and Japan create supply bottlenecks for aerospace-qualified fasteners.
- Adhesive bonding substitution:Structural acrylics and epoxy systems are displacing mechanical fasteners in electronics enclosure applications where space constraints favor chemical joining.
Strategic Opportunities
- India precision engineering corridors:BIS certification adoption and PLI scheme incentives for auto component manufacturing are opening specification-grade demand in Pune and Chennai industrial belts.
- Medical device miniaturization:ISO 13485-qualified titanium right-angle fasteners for surgical robotics and implantable devices command 4-6x construction-grade pricing.
- Digital thread integration:Blockchain-enabled material traceability systems are penetrating aerospace and nuclear supply chains, creating service-layer revenue for fastener vendors with serialized batch records.
Industry Challenges
- Metallurgical qualification timelines:ASTM F2282 and ISO 3506 certification cycles for new alloy grades extend 18-24 months, freezing product development pipelines.
- Coating line retooling costs:EPA air quality standards and hexavalent chromium phase-outs require $2-4 million capital deployment per facility for compliant surface treatment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Right Angle Fastener Market |
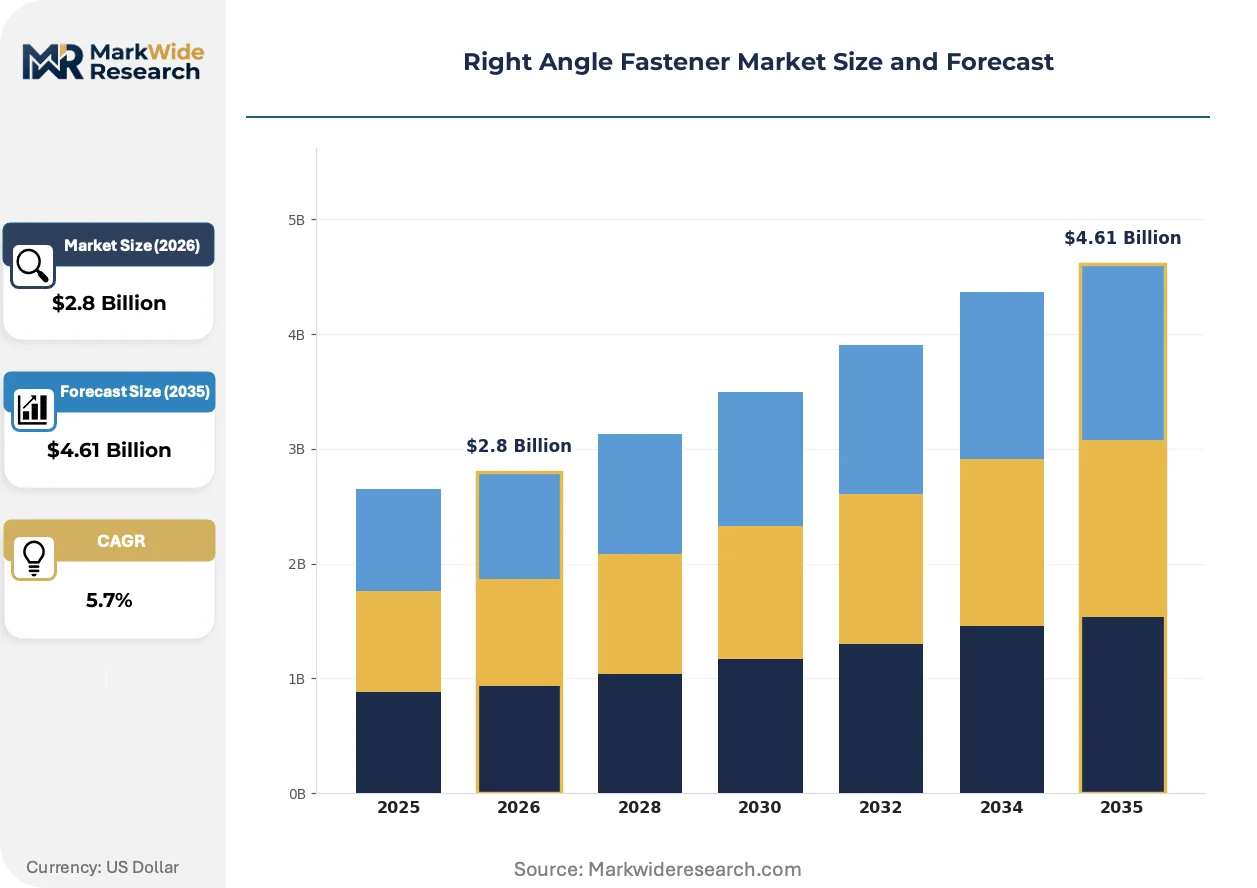
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
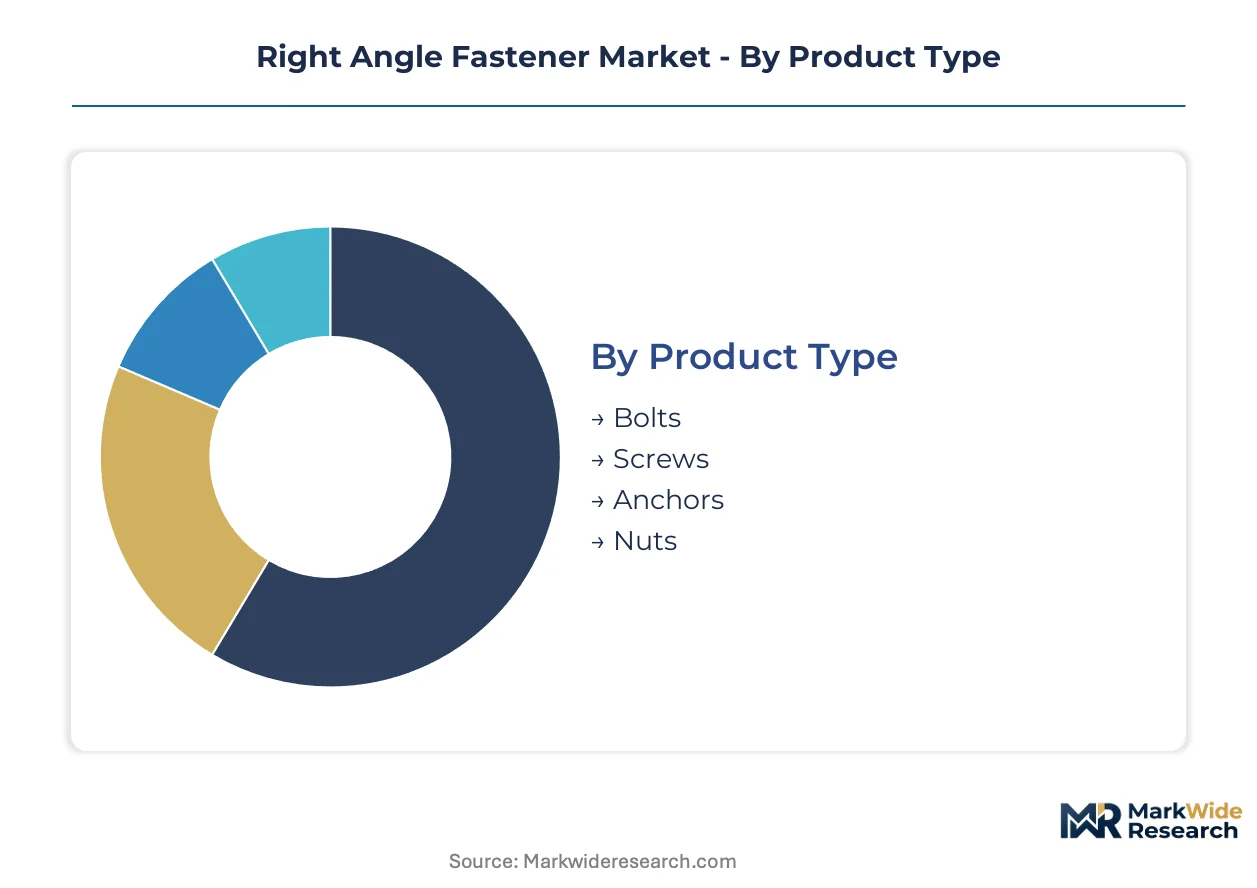
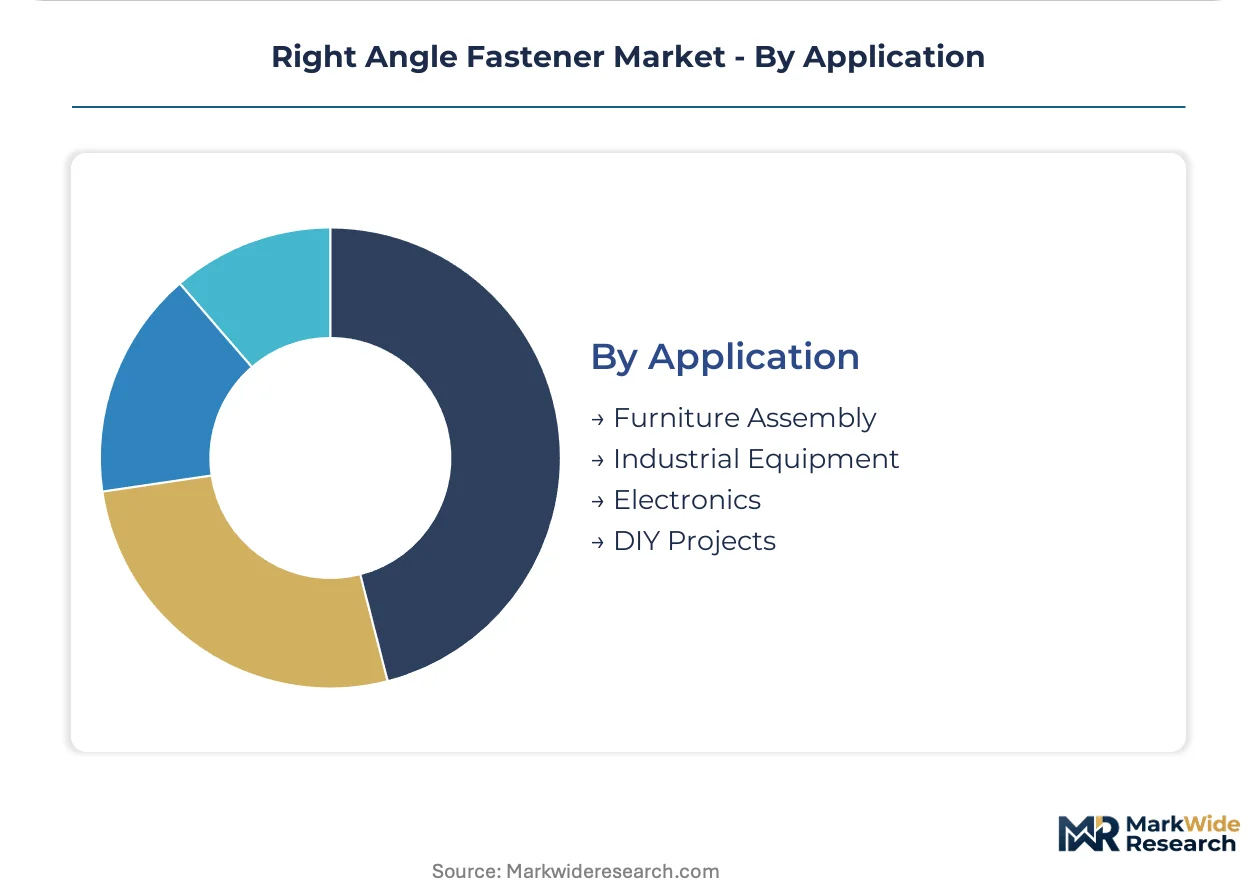
| Segmentation | Product Type: Bolts, Screws, Anchors, Nuts Material: Steel, Aluminum, Plastic, Brass End User: Construction, Automotive, Aerospace, Machinery Application: Furniture Assembly, Industrial Equipment, Electronics, DIY Projects |
| Companies Covered | Penn Engineering, Protocase, S.W. Anderson, Zygology Ltd, Fastenal Company, Stanley Black & Decker, BOSSARD Group, Illinois Tool Works, Simpson Strong-Tie Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Right Angle Fastener Market Evolving Landscape
Material science advances and digital supply chain traceability are compressing traditional procurement cycles while elevating mechanical property verification to real-time monitoring protocols.
Cold-formed titanium alloys with beta-annealed microstructures are supplanting precipitation-hardened stainless steels in satellite and drone structural joints. SpaceX and Northrop Grumman suppliers are qualifying Ti-6Al-4V variants for launch vehicle payload adapters. This substitution is compressing supplier qualification timelines from 36 months to 18 months for proven aerospace metallurgists.
REACH SVHC candidate list expansions are forcing coating chemistry reformulations across European fastener distributors. ECHA 2023-2024 substance restrictions on chromium trioxide and nickel compounds are redirecting specification-grade demand toward zinc-flake and organic topcoat systems. German automotive OEMs are accelerating trivalent chromium adoption ahead of 2026 sunset dates for hexavalent conversion coatings.
Vendor-managed inventory programs with RFID-enabled bin monitoring are displacing traditional purchase-order cycles in high-volume electronics assembly. Foxconn and Jabil facilities in Mexico and Eastern Europe are piloting automated replenishment systems that trigger fabrication orders based on real-time consumption telemetry. This shift is most visible in consumer electronics verticals where thread pitch tolerances below 0.05mm require just-in-time quality verification.
Right Angle Fastener Market Segmentation
Right angle fastener procurement splits sharply across specification grades, with ASTM certification tiers determining supplier eligibility for aerospace and automotive contracts. Material composition and coating chemistry further partition the addressable market, as REACH-mandated substance restrictions disqualify commodity-grade inventory from European industrial channels.
Product Type:
REACH Article 33 SVHC thresholds and Boeing/Airbus qualification protocols bifurcate demand between specification-grade and commercial-grade fastening systems.
- Bolts:Cold-forged alloy steel variants with tensile strengths exceeding 800 MPa dominate airframe assembly applications where FAA airworthiness directives mandate corrosion-resistant metallurgy. German automotive OEMs in Stuttgart and Munich specify zinc-nickel coated bolts for electric vehicle battery tray assemblies under ECHA substance restrictions.
- Screws:Miniaturized thread pitches below 0.05mm penetrate electronics assembly as Foxconn and Jabil facilities adopt RFID-enabled vendor-managed inventory for just-in-time quality verification. Precision rolling operations in Japan's Aichi Prefecture supply satellite payload adapter applications for Northrop Grumman contractors.
- Anchors:Expansion and adhesive-bonded variants serve timber and concrete structural connections governed by North American building code adoptions.
- Nuts:Hex and square configurations complete orthogonal joint assemblies in machinery and construction end-uses.
Bolts handle the majority of throughput; screws are expanding most quickly on specification-grade share.
Material:
Cost tiers separate commodity feedstock from certified alloy systems with captive heat-treatment infrastructure.
- Steel:Scrap metal and nickel price volatility compress margin predictability for cold-forging operations dependent on commodity-grade feedstock, yet alloy steel retains volume leadership in construction and heavy machinery load-bearing requirements. Vacuum carburizing capacity concentration in Germany and Japan creates supply bottlenecks for aerospace-qualified batches.
- Aluminum:30-40% mass reduction versus steel variants penetrates electric vehicle motor mount and battery enclosure applications as automotive OEMs accelerate lightweighting programs. BIS certification adoption in India's Pune corridor opens specification-grade demand for extruded aluminum right-angle fasteners.
- Plastic:Nylon and polypropylene variants serve furniture assembly and DIY applications where corrosion immunity and electrical isolation outweigh mechanical load requirements.
- Brass:Copper-zinc alloys address decorative and low-corrosion electrical grounding applications in consumer goods.
Steel commands the dominant share of tonnage; aluminum is climbing the fastest on automotive electrification demand.
End User:
Customer maturity stratifies between specification-captive aerospace procurement and price-sensitive construction distribution.
- Construction:Structural-rated connectors for timber and concrete sustain the most mature demand pool, with building code adoptions in North American jurisdictions filtering non-compliant imports from critical-load applications.
- Automotive:OEM material qualification timelines extend 18-24 months for new alloy grades, freezing product development pipelines for suppliers lacking metallurgical certification resources.
- Aerospace:Ti-6Al-4V titanium variants with beta-annealed microstructures supplant precipitation-hardened stainless steels in satellite and drone structural joints as SpaceX suppliers compress qualification timelines.
- Machinery:General industrial equipment maintenance generates recurring demand for standard-grade right-angle fastening systems.
Construction absorbs the highest absolute volume; aerospace delivers the steepest pricing premium per kilogram.
Application:
Supply concentration clusters around high-volume electronics corridors and dispersed DIY retail networks.
- Furniture Assembly:Flat-pack manufacturers in Poland and Vietnam drive consumption of zinc-plated steel and plastic variants for knock-down joint systems.
- Industrial Equipment:Heavy machinery OEMs in China's Jiangsu Province specify heat-treated alloy systems for vibration-resistant orthogonal connections.
- Electronics:Miniaturization drives finer thread pitches and tighter tolerances as consumer electronics verticals demand thread pitch tolerances below 0.05mm.
- DIY Projects:Home improvement retail channels distribute commodity-grade assortments through big-box networks in North America and Europe.
Industrial equipment anchors procurement scale; electronics is gaining share fastest on miniaturization intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters export specification-grade fasteners to aerospace OEMs in France and the United States, while Chinese cold-forging operations supply construction-grade volumes to Southeast Asian infrastructure projects.
United States
FAA airworthiness directives drive procurement of corrosion-resistant alloy systems for Boeing and Lockheed Martin airframe programs. EPA air quality standards restrict hexavalent chromium conversion coatings, redirecting surface treatment investments toward trivalent alternatives. The Pacific Northwest aerospace corridor concentrates heat-treatment infrastructure for Ti-6Al-4V qualification.
Germany
Automotive OEMs in Stuttgart and Munich specify zinc-nickel coated fasteners for electric vehicle battery tray assemblies. ECHA substance restrictions under REACH Article 33 accelerate coating line retooling ahead of 2026 sunset dates for hexavalent chromium. The Baden-Württemberg precision engineering cluster anchors vendor-managed inventory systems for continental supply.
China
Heavy machinery OEMs in Jiangsu Province consume heat-treated alloy systems for vibration-resistant industrial equipment. MIIT industrial standards govern mechanical property classifications for domestic infrastructure projects. The Yangtze River Delta cold-forging belt exports commodity-grade fasteners to Vietnam and Indonesia construction markets.
Japan
METI technology roadmaps prioritize titanium alloy development for satellite payload adapters. JIS standards create compliance thresholds that filter non-certified imports from precision electronics applications. Aichi Prefecture rolling operations supply miniaturized thread pitches below 0.05mm for Northrop Grumman contractors.
India
BIS certification adoption and PLI scheme incentives open specification-grade demand for auto component manufacturing. CDSCO medical device regulations create pathways for ISO 13485-qualified titanium fasteners in surgical robotics. The Pune and Chennai industrial belts attract coating line investments for zinc-flake system qualification.
Right Angle Fastener Market Competitive Landscape
Listed leaders compete with private specialists across specification-grade certification tiers, producing a bifurcated structure where aerospace-qualified manufacturers capture premium margins while commodity-grade fabricators face input cost volatility. Publicly traded conglomerates with captive heat-treatment capacity anchor supply to Boeing and Airbus qualification protocols. Three archetypes dominate: precision metallurgists with aerospace certifications, scale-driven distributors with vendor-managed inventory systems, and regional cold-forging specialists serving construction distribution. Competitive moves concentrate on coating line retooling for REACH compliance and backward integration into vacuum carburizing infrastructure.
Among North American fabricators, Penn Engineering exemplifies the precision metallurgist archetype through captive cold-heading capacity for aerospace and electronics applications. BOSSARD Group anchors European supply coordination through local engineering centers and inventory management systems. Simpson Strong-Tie Company occupies a position within structural-rated construction segments, sustaining specification authority through building code alignment.
| Leading Market Players |
|---|
| Penn Engineering |
| Protocase |
| S.W. Anderson |
| Zygology Ltd |
| Fastenal Company |
| Stanley Black & Decker |
| BOSSARD Group |
| Illinois Tool Works |
| Simpson Strong-Tie Company |
| Others |
Value Network & Pricing Analysis
Cold-forging capacity utilization above 85% in Germany and Japan anchors premium pricing power for specification-grade fasteners while compressing margin floors for commodity-grade fabricators dependent on volatile scrap metal feedstock. This scale asymmetry bifurcates the market into certified precision manufacturers capturing aerospace and automotive OEM contracts versus undifferentiated suppliers exposed to spot-price nickel volatility.
Pricing Analysis
Specification-grade Ti-6Al-4V fasteners command 4-6x construction-grade pricing as SpaceX and Northrop Grumman suppliers compress qualification timelines from 36 months to 18 months. Three-tier pricing structure across aerospace-certified, automotive-grade, and commercial construction levels reflects ASTM F2282 and ISO 898-1 certification thresholds. Cost compression in commodity-grade steel variants is intensifying because Chinese cold-forging exports from Jiangsu Province flood Southeast Asian infrastructure markets. DIY retail channels exhibit highest price sensitivity, whereas FAA-qualified aerospace procurement shows least elasticity due to airworthiness directive mandates.
Supply Chain Analysis
Port congestion on transpacific lanes and container availability constraints at Shanghai and Busan elevate inbound logistics costs for European and North American distributors sourcing from Asian cold-forging operations. Supply concentrates in Germany, Japan, and China, with vacuum carburizing infrastructure clustering in Baden-Württemberg and Aichi Prefecture creating single-source vulnerability for aerospace-qualified batches. Raw material flows draw from nickel scrap markets, alloy steel billets, and titanium sponge feedstock. Distribution runs through vendor-managed inventory systems with RFID-enabled bin monitoring at Foxconn and Jabil facilities displacing traditional purchase-order cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Boeing, Airbus, and German automotive OEMs consolidate supplier panels around qualified metallurgists with captive heat-treatment capacity, squeezing margin share from fragmented commodity-grade fabricators.
For Market Incumbents: Fortify aerospace certification moats by accelerating Ti-6Al-4V beta-annealing qualification for satellite payload adapters before emerging titanium specialists achieve ASTM F2282 approval. Deepen backward integration into vacuum carburizing infrastructure in Germany and Japan to lock out competitors from heat-treatment bottlenecks. Prioritize coating line retooling for REACH Article 33 compliance ahead of 2026 hexavalent chromium sunset dates. For New Entrants and Emerging Players: Blockchain-enabled material traceability services represent a service-layer gap where incumbents under-serve aerospace and nuclear supply chains demanding serialized batch records. Penetrate India's Pune and Chennai industrial belts where BIS certification adoption and PLI scheme incentives create specification-grade demand without entrenched competitor presence. Deploy digital thread integration as a go-to-market wedge to bypass capital-intensive metallurgical qualification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision metallurgists with captive cold-heading capacity and existing aerospace qualifications over scale-driven distributors exposed to commodity margin compression. Five-to-ten-year viability hinges on coating chemistry transition completion and titanium alloy adoption curves. Target acquisition archetype: mid-cap specialists with ISO 13485 medical device pathways and proven heat-treatment infrastructure. Monitor ECHA SVHC candidate list expansions as inflection indicator for coating line retooling cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Carburizing | Captive heat-treatment capacity locks out competitors from aerospace qualification bottlenecks in Germany and Japan. |
| Coating Line Retooling for REACH Compliance | Trivalent chromium and zinc-nickel alternatives secure European automotive OEM contracts ahead of 2026 sunset dates. |
| Digital Thread Integration | Blockchain-enabled traceability creates service-layer revenue from Boeing and nuclear supply chain serialization demands. |
| Medical Device Certification Pathway | ISO 13485 qualification for titanium surgical robotics fasteners commands 4-6x construction-grade pricing premiums. |
| India Precision Engineering Expansion | BIS certification and PLI scheme incentives open specification-grade auto component demand in Pune and Chennai corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade data, ASTM International certification registries, and ECHA substance restriction databases. Primary interviews engaged fastener procurement managers at Boeing and Airbus tier-1 suppliers, cold-forging plant engineers in Germany and Japan, coating line operations directors, and regulatory compliance officers at European automotive OEMs. Bottom-up demand modeling triangulates against top-down industry association data from precision engineering clusters.
Segmentation dimensions modeled include specification grade tier, material composition, coating chemistry, end-user industry, and application vertical across the projection horizon. CAGRs derive from shipment volume analysis by product type and price-point trajectories informed by raw material input cost modeling. Industry-specific forecast inputs incorporate aerospace OEM material qualification timeline compression and REACH-mandated coating chemistry transition schedules.
Forecasts assume regulatory continuity in FAA airworthiness directives, EPA air quality standards, and ECHA substance restrictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Global Ball Screw Market