
 CNC Metal Cutting Machine Tools Market | 2026-2036
CNC Metal Cutting Machine Tools Market Size, Share, and Industry Trends Forecast 2026-2036
CNC Metal Cutting Machine Tools Market Analysis
The distributor-dealer network for precision metalworking equipment is reconfiguring as OEMs build direct service arms in manufacturing corridors. DMG MORI leverages its global spare parts logistics to lock in multi-year service contracts with tier-one automotive suppliers. Makino anchors its position through captive training academies that certify operator proficiency on five-axis machining centers. Haas Automation competes on standardized control architecture that reduces technician onboarding across its installed base.
CNC metal cutting machine tools are programmable, servo-driven fabrication systems that remove material from metal workpieces through controlled spindle motion, typically achieving positional accuracy within micrometers for finished components. These systems serve as capital equipment backbone for discrete manufacturing, converting raw stock into precision parts across batch sizes from single prototypes to continuous production runs. Milling machines command the largest product type share due to versatility across face cutting, contouring, and pocketing operations on hardened alloys. Electric drive technology is displacing hydraulic actuation in new installations, reflecting priorities on energy efficiency and thermal stability during extended cutting cycles. Aerospace end users represent the fastest-expanding demand pool, driven by airframe programs requiring titanium and nickel superalloy machining at tight tolerances.
The EU Machinery Directive and CE marking framework mandate interlocked guarding and functional safety validation for CNC systems sold across member states, elevating compliance costs for non-European builders. OSHA lockout/tagout standards and EPA metalworking fluid discharge rules in the United States shape shop floor configuration and coolant system investments for domestic operators. ISO 230 machine tool performance testing standards provide common benchmarking language that reduces procurement friction across multinational supply chains. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking requirements reshape material sourcing and energy consumption specifications for next-generation equipment procurement.
Market Dynamics
Electric drive technology is collapsing the installed base of hydraulic actuation systems, while aerospace demand for titanium machining capacity concentrates procurement power among tier-one airframe integrators.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for interlocked guarding and functional safety validation are accelerating replacement cycles of legacy equipment across European metalworking facilities.
- Titanium airframe component demand:Aerospace manufacturers are expanding five-axis machining capacity to handle nickel superalloy workpieces at micrometer tolerances for next-generation commercial aircraft programs.
- Baden-Württemberg supplier density:Germany's machine tool cluster enables just-in-time integration with automotive OEM supply chains, reducing logistics friction for precision component sourcing.
Market Restraints
- REE magnet supply concentration:Rare earth permanent magnet sourcing for high-torque spindle motors remains concentrated in Chinese processing facilities, exposing builders to export restriction risks.
- CE marking compliance costs:Non-European equipment manufacturers face elevated certification expenses and extended validation timelines to access member state markets under Machinery Directive requirements.
- Ball screw thermal drift:Positional accuracy degradation during extended titanium cutting cycles limits achievable tolerances without active compensation systems, constraining aerospace workpiece complexity.
Strategic Opportunities
- Captive training academy models:Equipment builders can certify operator proficiency on five-axis machining centers through in-house programs, locking in multi-year service relationships with automotive tier-one suppliers.
- Dual carbon goal alignment:China's national carbon peak and neutrality targets are reshaping procurement specifications toward energy-efficient electric drives, creating preference windows for compliant builders.
- Direct service arm expansion:OEMs establishing proprietary spare parts logistics and field service teams in manufacturing corridors can disintermediate traditional distributor-dealer networks.
Industry Challenges
- G-code programmer scarcity:Shortages of operators capable of CAM programming for simultaneous five-axis contouring are constraining utilization rates of installed high-complexity machining centers.
- ISO 230 performance validation:Multinational supply chains require documented geometric accuracy testing under standardized protocols, extending qualification timelines for new equipment approvals.
- Legacy control architecture integration:Standardized FANUC or Siemens interfaces on new machines must communicate with shop floor MES systems running proprietary legacy protocols, complicating digital thread implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNC Metal Cutting Machine Tools Market |
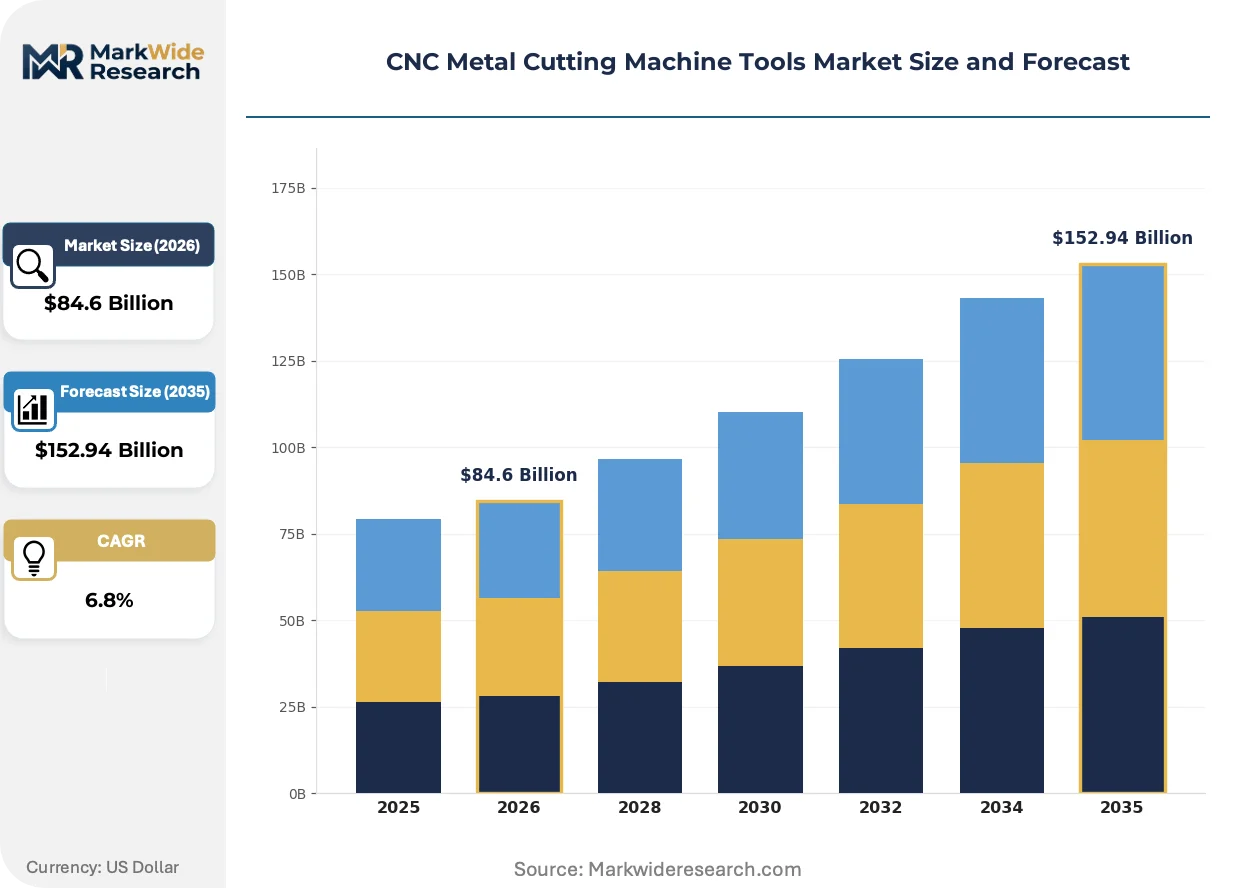
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathe Machines, Milling Machines, Drilling Machines, Grinding Machines Technology: Electric, Hydraulic, Pneumatic, Hybrid End User: Aerospace, Defense, Automotive OEMs, Manufacturing Application: Prototyping, Mass Production, Tooling, Maintenance |
| Companies Covered | Okuma, FANUC, DMG MORI, Doosan, Hurco, Mazak Corporation, Makino, TRUMPF Group, Haas Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNC Metal Cutting Machine Tools Market Emerging Trajectories
Control architecture standardization and predictive maintenance algorithms are compressing technician onboarding timelines while reshaping competitive differentiation from hardware specifications to software-enabled uptime guarantees.
Direct-drive torque motor technology is collapsing the mechanical complexity of rotary table designs by eliminating gear trains and backlash compensation mechanisms. Aerospace machine shops in Germany and Japan are specifying these tables for titanium blisk machining where angular positioning repeatability below five arc-seconds is mandatory. The technology is collapsing the competitive advantage of builders relying on conventional worm-drive designs, forcing rapid product line refreshes.
The EU Green Deal's embodied carbon tracking requirements are mandating lifecycle emissions disclosure for capital equipment procurement above specified thresholds. Machine tool builders must now document energy consumption per cubic centimeter of material removed and coolant system carbon intensity. German automotive OEMs are embedding these specifications into supplier qualification scorecards, favoring builders with verified low-carbon manufacturing processes.
Buyers are unbundling after-sales service contracts from initial equipment purchases, negotiating multi-year maintenance agreements separately through competitive tender processes. Tier-one automotive suppliers in Baden-Württemberg are consolidating spindle rebuild and ball screw replacement services with third-party specialists rather than captive OEM service arms. This behavior is most visible in Germany's automotive manufacturing corridor, where procurement functions have established preferred vendor lists for predictive maintenance analytics independent of machine tool original suppliers.
CNC Metal Cutting Machine Tools Market Segmentation
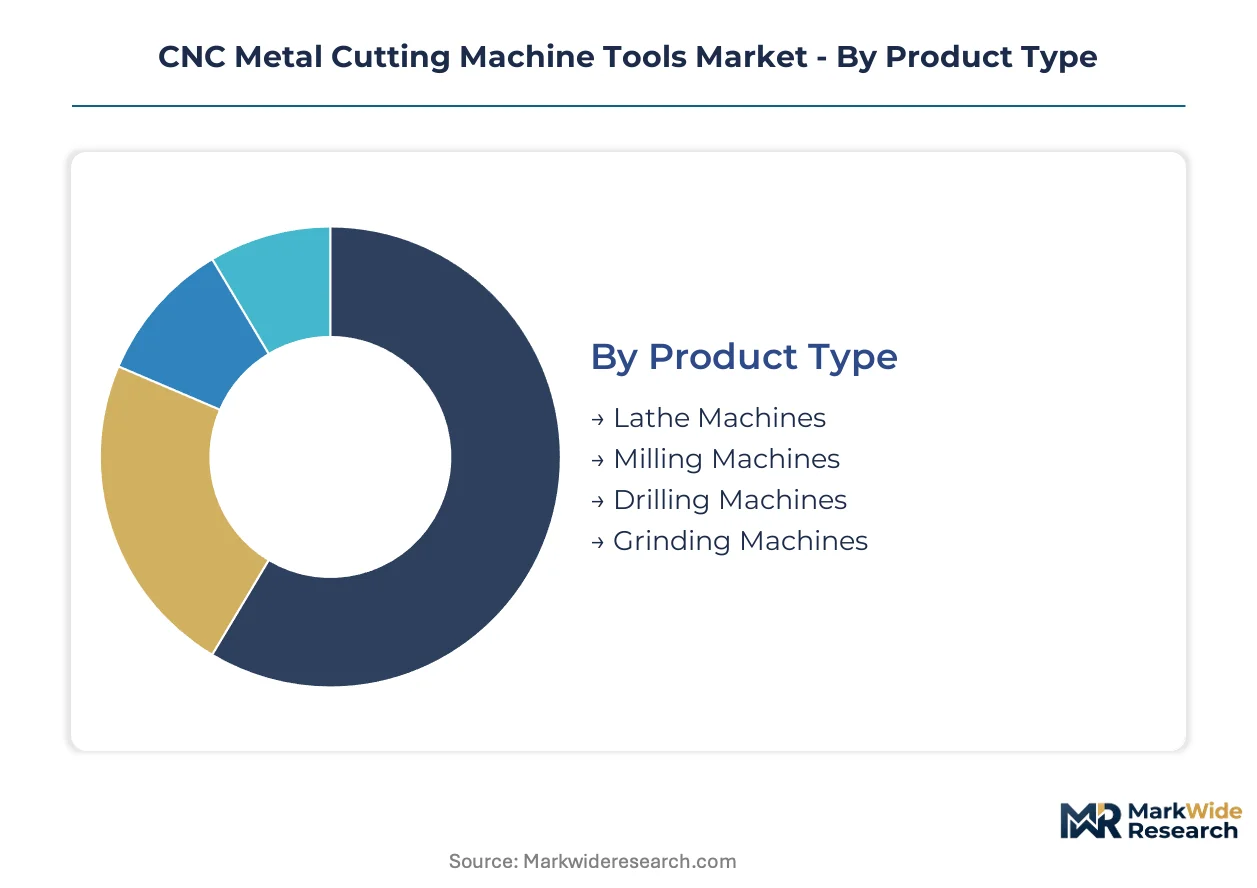
CNC metal cutting machine tools segment across multiple technical and commercial dimensions that determine procurement specifications, service requirements, and competitive positioning. Understanding these divisions reveals where capital equipment investments concentrate and how builders differentiate their product architectures.
Product Type:
Mature machining platforms dominate installed bases while emerging configurations capture replacement cycles and greenfield capacity expansions.
- Milling Machines:These systems execute face cutting, contouring, and pocketing operations on hardened alloys through multi-axis spindle motion. Aerospace manufacturers in Germany's Baden-Württemberg cluster specify five-axis variants for titanium airframe components, driving demand for micrometer-level positional accuracy and thermal stability during extended cutting cycles.
- Lathe Machines:Rotational workpiece machining systems achieve cylindrical precision through CNC-controlled chuck rotation and tool post positioning. Automotive OEM supply chains in Germany concentrate procurement of twin-spindle turning centers for high-volume shaft and hub production, prioritizing rapid tool changeover and automated bar feeder integration.
- Drilling Machines:Dedicated hole-making systems deliver axial material removal for through-holes and blind holes in structural metal components.
- Grinding Machines:Abrasive finishing systems achieve surface tolerances and dimensional refinement beyond conventional machining capabilities.
Milling machines handle the majority of throughput across aerospace and automotive applications; lathe machines are expanding most quickly in electric vehicle powertrain manufacturing.
Technology:
Cost tier stratification separates premium electric drive platforms from legacy hydraulic installations and transitional hybrid configurations.
- Electric:Servo motor and ball screw actuation delivers precise positional control with superior energy efficiency and reduced thermal drift. China's dual carbon goals are reshaping procurement specifications toward these drives, creating compliance-driven replacement windows for builders with verified low-carbon manufacturing processes.
- Hydraulic:Fluid power actuation systems persist in heavy-duty roughing applications requiring high force density.
- Pneumatic:Compressed air systems serve auxiliary functions and light-duty material handling integrations.
- Hybrid:Combined electric-hydraulic architectures balance precision and power for specialized forming and heavy cutting operations.
Electric technology commands the premium tier; hybrid configurations are climbing the fastest as transitional solutions for shops modernizing incrementally.
End User:
Application concentration varies sharply across customer types, with volume scale and tolerance requirements driving divergent equipment specifications.
- Aerospace:Airframe and engine component manufacturers demand five-axis machining centers capable of titanium and nickel superalloy processing at tight tolerances. Tier-one integrators are consolidating procurement power for next-generation commercial aircraft programs, concentrating supplier relationships among builders with proven aerospace qualification protocols.
- Automotive OEMs:Volume manufacturers prioritize standardized control architectures that reduce technician onboarding across multi-site production networks. Just-in-time integration requirements in Germany's manufacturing corridor favor suppliers with localized spare parts logistics and rapid field service response.
- Defense:Military component specifications emphasize traceability, security protocols, and domestic sourcing requirements.
- Manufacturing:General industrial machine shops span job shop, contract manufacturing, and captive production operations with heterogeneous equipment needs.
Automotive OEMs generate the largest equipment volume; aerospace represents the steepest expansion trajectory on capital intensity per installed unit.
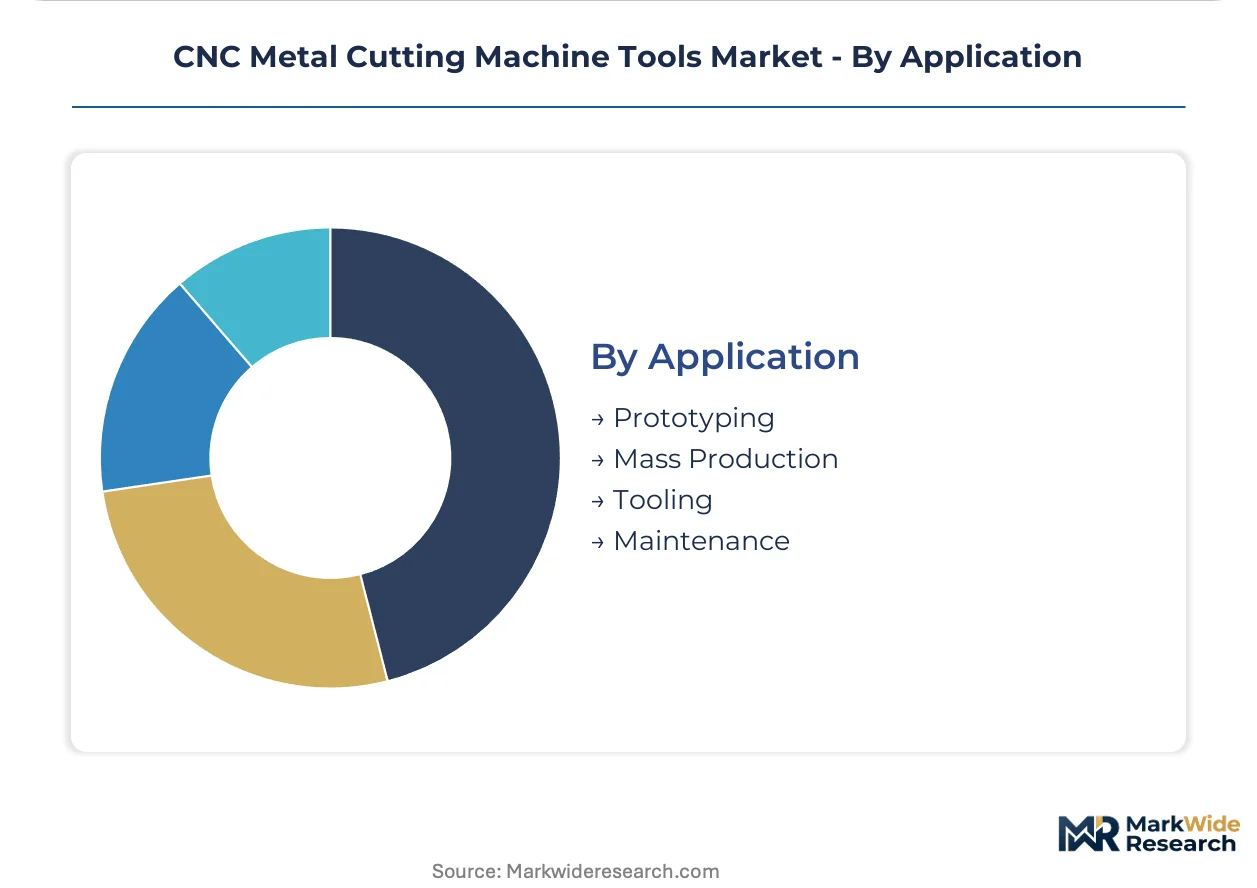
Application:
Volume tier differentiation separates continuous production environments from intermittent, high-mix operational modes with distinct uptime and flexibility requirements.
- Mass Production:Continuous manufacturing lines demand maximum spindle utilization, automated workpiece handling, and predictive maintenance integration. Tier-one automotive suppliers are unbundling after-sales contracts from initial purchases, negotiating multi-year maintenance agreements through competitive tender processes independent of OEM service arms.
- Prototyping:Low-volume, high-complexity work requires rapid program changeover and five-axis contouring capability.
- Tooling:Die and mold manufacturing applications prioritize surface finish quality and hard material machining.
- Maintenance:Repair and refurbishment operations serve aftermarket component replacement and equipment life extension.
Mass production accounts for the dominant share of installed base value; prototyping is gaining share fastest as product development cycles compress across manufacturing sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in precision machinery trade, while China's high-speed rail network connects Yangtze River Delta manufacturing hubs to interior machine tool demand centers.
Germany
Baden-Württemberg's automotive supplier density drives five-axis machining center procurement for just-in-time component integration. CE marking requirements under the EU Machinery Directive mandate interlocked guarding validation, elevating compliance costs for imported equipment. Stuttgart's machine tool cluster concentrates spindle rebuild and predictive maintenance service capabilities.
China
Dual carbon goals are reshaping procurement specifications toward energy-efficient electric drives in Yangtze River Delta manufacturing corridors. MIIT national standards align with ISO 230 performance testing protocols for domestic equipment qualification. Shanghai's Pudong district hosts concentrated CNC system integration facilities serving aerospace tier-one suppliers.
United States
OSHA lockout/tagout standards shape shop floor configuration for automotive powertrain machining lines in the Midwest manufacturing belt. EPA metalworking fluid discharge rules drive coolant system investments across Ohio and Michigan job shops. Detroit's automotive corridor concentrates demand for standardized FANUC control architectures.
Japan
METI industrial policy supports domestic builder retention of five-axis machining technology for aerospace superalloy applications. JIS standards provide common benchmarking language reducing procurement friction across multinational supply chains. Nagoya's Chubu region anchors precision ball screw and linear motion component manufacturing.
South Korea
Seoul Capital Area defense contractors drive demand for titanium machining centers with traceability protocols. MFDS-equivalent industrial safety regulations align with international functional safety standards for automated metalworking. Busan-Ulsan's heavy industrial zone concentrates shipbuilding component machining capacity.
CNC Metal Cutting Machine Tools Market Vendor Landscape
On the supply side, the industry is consolidating around builders with captive service logistics and standardized control platforms that reduce customer onboarding friction. Japanese and German manufacturers anchor the premium tier through precision component integration, while Korean and Taiwanese builders compete on electric drive technology transitions. Strategic archetypes include full-lifecycle service integrators, control architecture standardizers, and regional volume specialists. Dominant competitive moves encompass direct service arm establishment in manufacturing corridors and multi-year maintenance contract capture.
Among Japanese precision builders, Okuma and Makino exemplify the premium-tier archetype through integrated spindle and control system development. DMG MORI occupies a position bridging German engineering heritage with Asian manufacturing scale. Haas Automation represents the standardized-control strategy that reduces technician training requirements across distributed automotive supplier networks.
| Leading Market Players |
|---|
| Okuma |
| FANUC |
| DMG MORI |
| Doosan |
| Hurco |
| Mazak Corporation |
| Makino |
| TRUMPF Group |
| Haas Automation |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's machine tool cluster concentrates five-axis machining capacity for automotive just-in-time supply chains, translating supplier density into pricing leverage for tier-one OEMs negotiating multi-year service bundles. CE marking compliance costs under the EU Machinery Directive widen the cost gap between European builders and non-European imports, reshaping procurement decisions across the continent.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates builders with captive training academies and direct service arms from commodity competitors. Premium tiers command markups through ISO 230 performance validation documentation and aerospace qualification protocols, while economy tiers compete on standardized FANUC control architectures that reduce technician onboarding costs. Pricing pressure stems from tier-one automotive suppliers unbundling after-sales contracts and negotiating spindle rebuild services through competitive tender. Job shops in Germany's manufacturing corridor exhibit highest price sensitivity due to margin compression from energy cost volatility, whereas aerospace integrators prioritize tolerance capability over unit cost.
Supply Chain Analysis
Extended payment terms from tier-one automotive suppliers in Stuttgart strain working capital for precision component subcontractors, accelerating consolidation among ball screw and linear motion specialists. Rare earth permanent magnet processing concentrates in Chinese facilities, while precision casting and spindle assembly anchor in Germany and Japan. Ball screw thermal drift compensation systems and direct-drive torque motors represent critical component dependencies. Single-source vulnerability in rare earth magnet supply exposes builders to export restriction risks. Distribution runs through OEM direct service arms that disintermediate traditional distributor-dealer networks in manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where standardized control architectures are collapsing competitive differentiation from hardware specifications toward software-enabled uptime guarantees. Interoperability between FANUC interfaces and shop floor MES systems determines procurement outcomes for multi-site automotive networks.
For Market Incumbents: Entrench multi-year service relationships by expanding captive training academies that certify operator proficiency on five-axis machining centers, locking in automotive tier-one suppliers against third-party maintenance specialists. Accelerate backward integration into precision ball screw and linear motion component manufacturing to mitigate thermal drift supply constraints. Prioritize CE marking compliance investment to defend European market access against non-European competitors facing extended validation timelines. For New Entrants and Emerging Players: Establish a beachhead in electric vehicle powertrain machining applications where twin-spindle turning center demand outpaces established service infrastructure. Target China's Yangtze River Delta manufacturing corridor where dual carbon goals are reshaping procurement specifications toward energy-efficient electric drives, creating compliance-driven replacement windows. Lead with predictive maintenance analytics platforms that integrate with legacy MES protocols, bypassing incumbent hardware lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because direct service arm establishment and spare parts logistics networks exhibit scale economies that favor scaled operators over fragmented regional specialists. Acquisition targets include mid-cap builders with verified low-carbon manufacturing processes and aerospace qualification protocols. Monitor tier-one automotive supplier procurement consolidation in Baden-Württemberg as the signal for service contract capture inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Training Academy Expansion | Makino's operator certification programs lock in multi-year automotive service relationships. |
| Direct Service Arm Establishment | DMG MORI's global spare parts logistics disintermediates traditional distributor networks. |
| Electric Drive Platform Transition | Energy-efficient servo systems align with China's dual carbon procurement specifications. |
| CE Marking Compliance Investment | Interlocked guarding validation secures European market access against non-EU competitors. |
| Predictive Maintenance Analytics | Software-enabled uptime guarantees shift differentiation from hardware to service contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across Germany, China, Japan, and the United States. Secondary validation drew from MIIT national standards documentation, EU Machinery Directive regulatory filings, ISO 230 performance testing protocols, and customs trade data for precision machinery imports. Bottom-up equipment shipment data triangulated against top-down capital expenditure surveys from automotive and aerospace manufacturing sectors.
Calibration against historical replacement cycles and greenfield capacity announcements anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, drive technology architecture, end-user industry, application volume tier, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories, adjusted for technology transition rates from hydraulic to electric actuation systems. Aerospace program timelines and automotive just-in-time integration requirements served as industry-specific demand inputs.
Sensitivities concentrate around rare earth export restrictions, CE marking compliance timeline extensions, and titanium airframe program delays. Forecasts reflect documented assumptions regarding technology substitution rates and regional procurement policy alignment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Foam Cutting Machine Market
Tools
Europe Paint Spray Guns Market
Tools
Rivet Busters Market
Tools
Taps and Dies Market
Tools
Collated Screws Market
Tools
Wood Floor Grinding Machine Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Aluminum Folding Ladders Market
Tools
Wire Cutters Market
Tools
Metal Cutting Machine Market
Tools
Turning Centers Market
Tools
Pliers Market
Tools
China Power Tools Market
Tools
Broaching Tools Market
Tools
Global Metal Forming Machine Tools Market
Tools
Spray Painting Machine Market