
 Wire Cutters Market | 2026-2036
Wire Cutters Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Cutters Market Analytics
Market Context
Vietnam's expanding manufacturing corridor is rewriting regional supply dynamics for precision hand tools. Knipex leverages its Solingen heritage to dominate premium-grade diagonal cutter segments across European industrial distribution. Stanley Black and Decker sustains broad channel control through multi-brand portfolios spanning professional and consumer hardware tiers. Klein Tools specializes in electrician-focused insulated designs that anchor its position in North American electrical contractor supply chains.
Technical Definition and Structural Segments
Wire cutters are lever-actuated cutting instruments engineered to sever metallic conductors, typically incorporating hardened steel jaws with Rockwell hardness ratings between 54 and 64 HRC for clean shearing action. These tools serve essential functions in electrical installation, telecommunications infrastructure maintenance, and automotive harness assembly where precise conductor termination prevents circuit failure. Manual wire cutters still occupy the largest value share due to universal applicability and minimal maintenance requirements, though electric variants are capturing faster growth in high-volume production environments. Ergonomic-featured products command premium positioning as occupational safety regulations tighten across industrial end-use sectors. Multi-function designs incorporating stripping and crimping capabilities concentrate margin pools in the professional electrical segment.
Regulatory Framework
OSHA mandates insulated tool ratings for live electrical work in the United States, directly shaping product certification requirements and procurement specifications across contractor channels. REACH compliance in Europe restricts certain chrome plating chemistries, forcing manufacturers toward alternative surface treatments that meet durability standards without restricted substances. China's GB standards and SAMR enforcement protocols govern export-bound production, creating dual-certification burdens for suppliers serving multiple geographies. Stakeholders must monitor evolving interoperability between national safety mark schemes to preserve market access without fragmenting inventory pools.
Market Dynamics
China's GB standard tightening is forcing wholesale design upgrades across export supply chains, compressing margins for manufacturers dependent on legacy plating chemistries while creating certification moats for compliant producers.
Growth Catalysts
- Renewable energy grid buildouts:Electrical contractors in Germany and the United States face surging conductor termination workloads as solar farms and wind installations multiply, driving replacement cycles for insulated precision tools.
- REACH compliance deadlines:European surface treatment restrictions are accelerating adoption of trivalent chrome and ceramic coating alternatives that extend jaw durability beyond traditional hexavalent plating lifespans.
- Telecommunications infrastructure densification:Fiber-to-the-home rollouts in India and Brazil require specialized micro-cutter geometries for ribbon cable severing, opening premium product tiers in emerging supply chains.
Market Restraints
- High-grade alloy steel volatility:Tool-grade chromium-molybdenum stock prices fluctuate with mining output from South African and Kazakh deposits, squeezing margin predictability for forged-jaw manufacturers.
- Solingen production concentration:Premium diagonal cutter capacity clusters in a single German city cluster, exposing distribution networks to localized logistics disruptions or labor actions.
- Electric crimping system substitution:Automated harness assembly lines in automotive Tier-1 plants are displacing manual cutter-striper combinations in high-volume contract manufacturing.
Strategic Opportunities
- Vietnam manufacturing corridor expansion:Industrial parks near Hanoi and Ho Chi Minh City offer tariff-advantaged export platforms for hand tool assembly serving ASEAN electrical markets.
- OSHA 1910.335 live-work mandates:Expanded U.S. enforcement of insulated tool requirements for energized circuit work creates compliance-driven replacement demand across contractor fleets.
- Multi-function convergence:Integration of thermal wire strippers with precision cutting heads addresses aerospace harness shops seeking single-tool workflow consolidation.
Industry Challenges
- Dual-certification complexity:Manufacturers serving both European and Chinese markets must maintain parallel testing protocols for REACH substance restrictions and GB hardness validation, extending product development timelines.
- Heat treatment skill scarcity:Rockwell 58-62 HRC jaw hardening requires experienced metallurgists increasingly concentrated in aging German and Japanese technical workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Cutters Market |
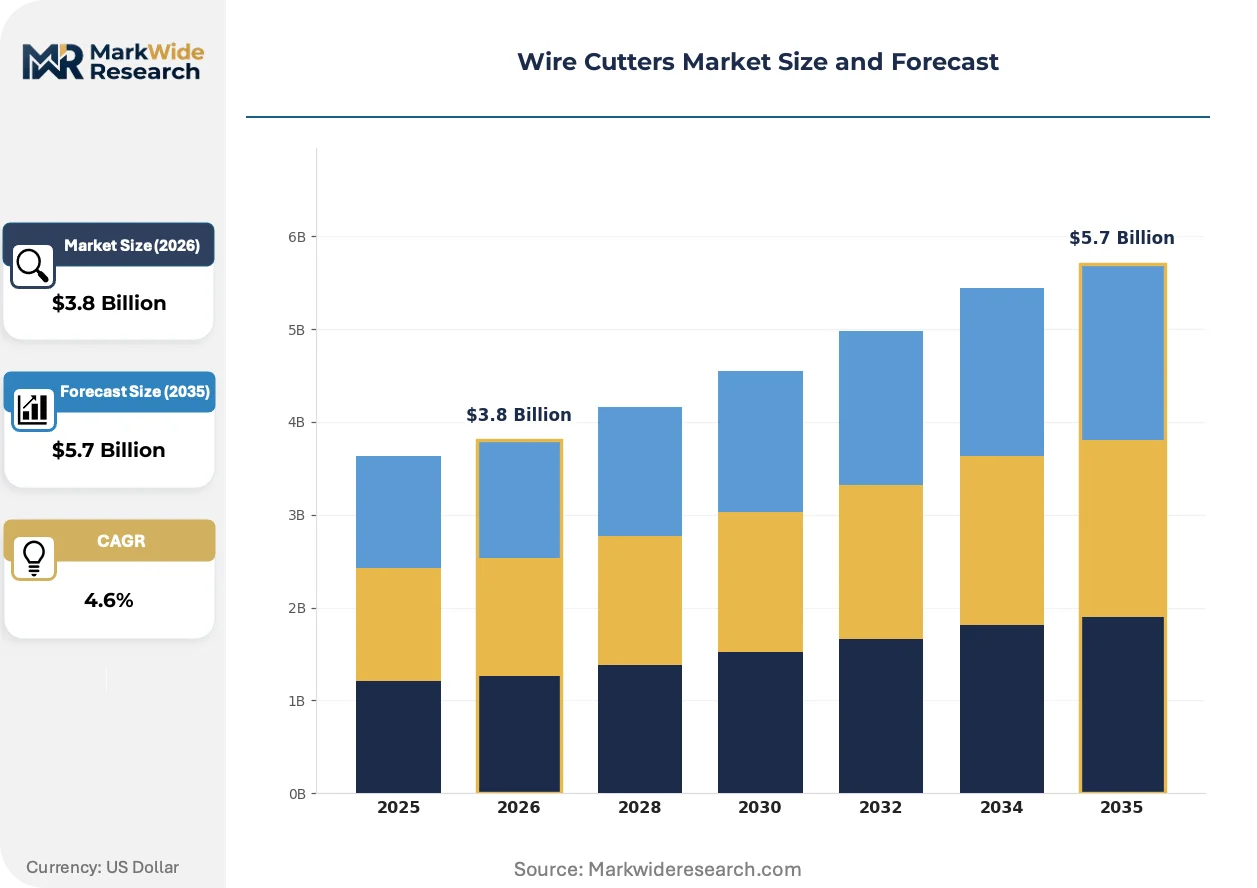
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Pneumatic, Hydraulic End User: Construction, Electrical, Automotive, Telecommunications Material: Steel, Carbon Fiber, Alloy, Plastic Feature: Insulated, Ergonomic, Multi-Function, Overload Protection |
| Companies Covered | Knipex, Stanley Black and Decker, Klein Tools, Techtronic Industries, RS Pro, Apex Tool Group, Snap-On Incorporated, Bahco, Facom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Cutters Market Evolving Landscape
Digital calibration and connected tool ecosystems are penetrating professional electrical supply chains, while material science advances compress traditional durability-performance tradeoffs.
Connected torque-sensing cutter heads is virtualizing quality assurance workflows in aerospace wire harness shops. Maintenance teams at Boeing and Airbus suppliers now capture cut-force telemetry for traceability compliance. This capability is virtualizing manual inspection labor while compressing defect liability exposure for precision assembly contractors.
REACH Annex XVII chromium restrictions are eliminating hexavalent plating from European-distributed hand tools by enforced sunset dates. Manufacturers are migrating toward trivalent chrome and physical vapor deposition finishes that match corrosion resistance without restricted substances. German industrial distributors now stock exclusively compliant SKUs, forcing non-European suppliers into rapid formulation switches.
Electrical contractors are consolidating supplier relationships around single-source insulated tool programs with integrated asset tracking. Independent hardware distributors lose share to direct manufacturer portals offering fleet management dashboards and calibrated replacement scheduling. This concentration is most visible across North American unionized construction markets where procurement standardization reduces insurance liability exposure.
Wire Cutters Market Segmentation
Wire cutter procurement patterns diverge sharply across operational contexts, with replacement cycles stretching from months in high-wear automotive plants to years in occasional-use residential electrical work. Understanding these velocity differentials helps suppliers calibrate inventory depth and service models to actual consumption rhythms rather than aggregate demand figures.
Product Type:
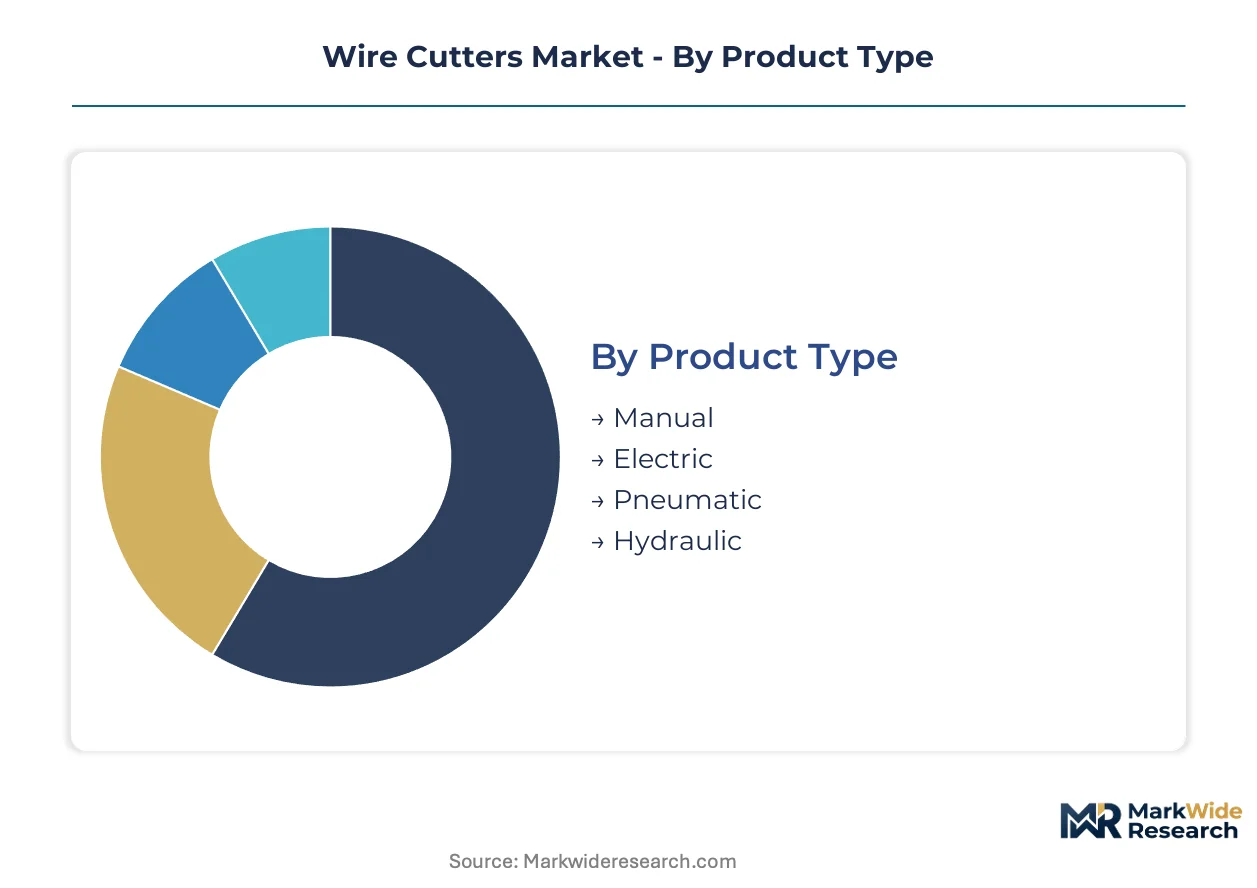
Electric variants turn inventory fastest in high-volume contract manufacturing, while pneumatic and hydraulic systems linger on warehouse shelves awaiting specialized industrial orders.
- Manual:Lever-actuated designs with hardened steel jaws between 54-64 HRC dominate universal maintenance applications. Electrical contractors in Germany's industrial belt consume these at accelerated rates due to renewable energy grid buildouts requiring constant conductor termination. This segment anchors the volume base while electric variants gain share at the steepest rate.
- Electric:Motorized cutting heads with programmable force limits serve automotive Tier-1 harness assembly lines where throughput requirements exceed human operator capacity. Boeing and Airbus suppliers in the United States deploy connected torque-sensing electric cutters for aerospace wire harness quality traceability.
- Pneumatic:Compressed-air actuation delivers high cutting force for heavy-gauge industrial cable in shipbuilding and heavy equipment manufacturing. Japanese shipyards in Nagasaki and Yokohama maintain substantial installed bases of pneumatic severing tools.
- Hydraulic:Fluid-power systems handle armored cable and submarine power line maintenance where mechanical advantage requirements exceed pneumatic capacity. Offshore wind installation vessels in the North Sea deploy hydraulic cutters for subsea cable severing operations.
Manual cutters still move the highest unit volumes through distributor channels, though electric systems are climbing fastest in value terms as production automation penetrates precision assembly sectors.
End User:
Cost tier stratification separates premium insulated tool programs from commodity-grade construction procurement, with certification requirements driving wedge pricing between compliant and non-compliant supply sources.
- Construction:General contractors prioritize durability and multi-function capability for mixed-material jobsite use. OSHA 1910.335 enforcement in the United States is accelerating insulated tool adoption among electrical subcontractors working energized circuits.
- Electrical:Licensed electricians demand precision-ground jaws and VDE-certified insulation ratings for live-work applications. This segment commands the steepest premium pricing due to liability exposure and insurance compliance requirements.
- Automotive:Harness manufacturers in Stuttgart and Detroit specify Rockwell 58-62 HRC jaw hardness for clean copper severing without conductor deformation. Electric crimping systems are displacing manual cutter-striper combinations in high-volume Tier-1 plants.
- Telecommunications:Fiber-to-the-home rollouts in India and Brazil require specialized micro-cutter geometries for ribbon cable severing. Ribbon fiber precision tools represent the fastest-expanding subsegment within telecommunications procurement.
Electrical contractors concentrate margin pools through certified insulated tool programs, while construction volume flows through price-sensitive hardware distribution.
Material:
Supply concentration for tool-grade alloys creates procurement vulnerability, with chromium-molybdenum stock price volatility squeezing forged-jaw manufacturers dependent on South African and Kazakh mining output.
- Steel:Chrome-vanadium and chrome-molybdenum alloys deliver the hardness-toughness balance required for precision cutting edges. REACH Annex XVII restrictions are forcing European suppliers toward trivalent chrome and ceramic coating alternatives.
- Carbon Fiber:Reinforced polymer handles reduce operator fatigue in high-repetition assembly environments. Aerospace harness shops in Toulouse and Seattle specify carbon fiber grip systems for ergonomic compliance.
- Alloy:Specialized cobalt and tungsten formulations extend jaw life in high-cycle production environments. Japanese metallurgical expertise in Sendai and Osaka clusters supports premium alloy development.
- Plastic:Glass-filled nylon handles serve consumer-grade and occasional-use professional segments where cost minimization dominates specification. Chinese export production concentrates in this material tier for price-sensitive developing markets.
Steel alloys retain dominance in professional-grade jaw construction, while carbon fiber composite handles expand fastest in ergonomic-featured premium positioning.
Feature:
Customer type segmentation separates fleet-managed contractor programs from individual tradesman purchasing, with integrated asset tracking consolidating procurement around direct manufacturer portals.
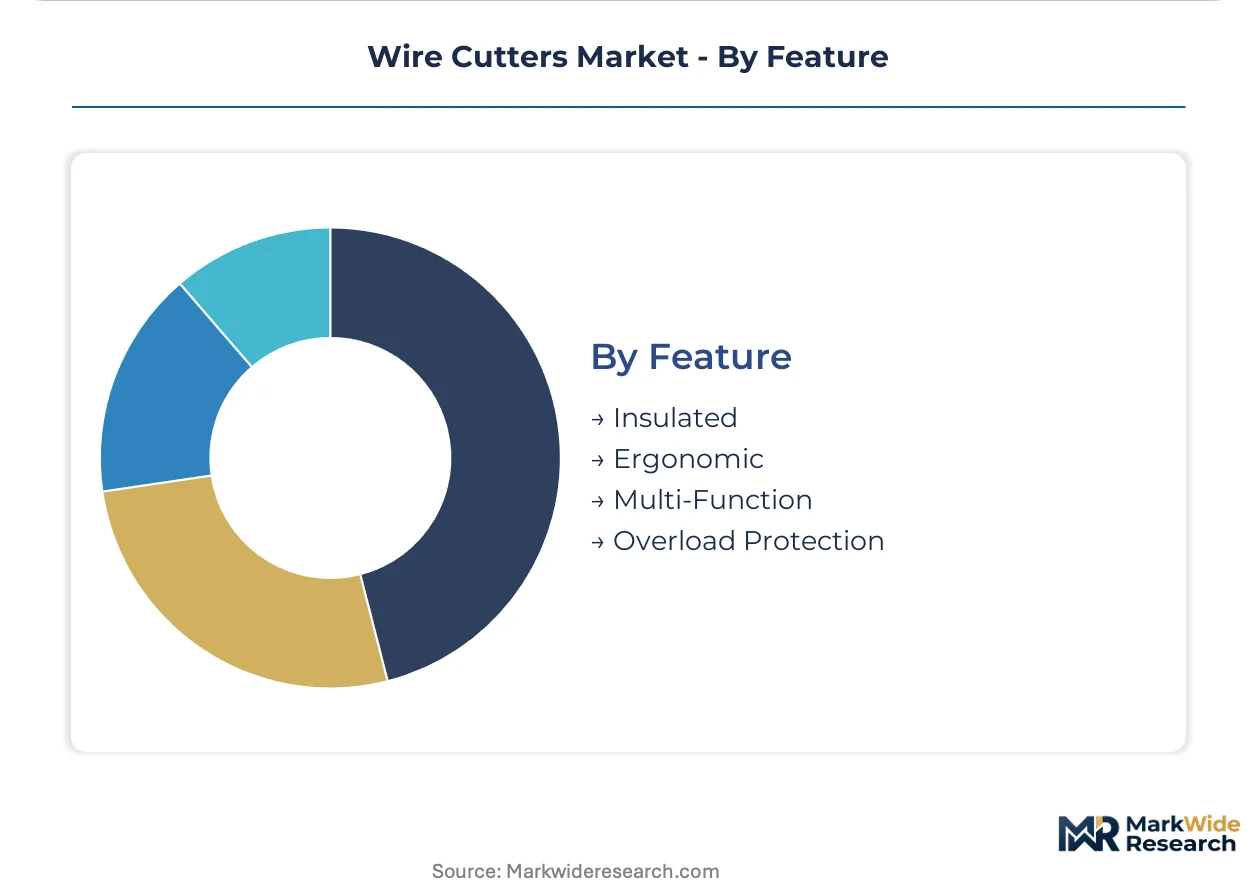
- Insulated:VDE and IEC 60900 certification ratings for live electrical work command substantial price premiums and create compliance moats. OSHA mandates in the United States and GB standard tightening in China are expanding addressable demand for certified insulated tools.
- Ergonomic:Biomechanically optimized handle geometries reduce repetitive strain injury risk in high-volume assembly operations. German industrial distributors now stock exclusively REACH-compliant ergonomic SKUs, forcing formulation switches across export supply chains.
- Multi-Function:Integrated stripping, crimping, and cutting heads consolidate tool inventory for mobile electrical contractors. Klein Tools and Knipex compete intensely in this configuration for North American and European professional segments respectively.
- Overload Protection:Shear pins and torque-limiting mechanisms prevent jaw damage when cutting beyond rated capacity. Mining and utility maintenance operations in Australia and Canada specify overload-protected designs for remote-site reliability.
Insulated features anchor professional electrical procurement requirements, while ergonomic configurations are expanding most quickly as occupational safety regulations tighten across industrial end-use sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial manufacturing belt consumes precision wire cutters at rates exceeding broader European averages, while electrical contractors in the United States drive insulated tool demand through renewable energy infrastructure deployment.
Germany
Renewable energy grid buildouts and automotive harness manufacturing dominate procurement volumes. REACH Annex XVII chromium restrictions force trivalent chrome and ceramic coating adoption across export supply chains. Solingen's tool-grade forging cluster anchors premium diagonal cutter production for industrial distribution.
United States
Electrical contractors face surging conductor termination workloads from solar farms and wind installations. OSHA 1910.335 mandates insulated tool ratings for live electrical work, shaping procurement specifications across contractor channels. Boeing and Airbus suppliers in Washington and Kansas deploy connected torque-sensing cutters for aerospace harness traceability.
China
GB standard tightening for hand tool safety forces design upgrades across export-oriented production. SAMR enforcement protocols create dual-certification burdens for suppliers serving multiple geographies. Manufacturing parks in Guangdong and Zhejiang concentrate price-sensitive consumer-grade output for developing markets.
Japan
Specialized alloy development and heat treatment expertise support premium jaw hardening at Rockwell 58-62 HRC. METI industrial standards govern professional-grade tool certification. Sendai and Osaka metallurgical clusters supply cobalt and tungsten formulations for high-cycle production environments.
Vietnam
Industrial parks near Hanoi and Ho Chi Minh City offer tariff-advantaged export platforms for ASEAN electrical markets. National technical regulations align with international safety mark schemes to preserve market access. Expanding manufacturing corridors attract hand tool assembly serving regional infrastructure buildouts.
Wire Cutters Market Competitive Landscape
Capability concentration sits with heritage-forged specialists; scale advantage sits with multi-brand portfolio operators. The vendor base separates into three tiers: Solingen-heritage precision manufacturers, diversified tool conglomerates with channel control, and regional specialists serving compliance-driven electrical segments. Consolidation pressure favors M&A activity among mid-tier fabricators seeking certification breadth, while capacity expansion concentrates in Vietnam and Mexico for tariff-advantaged export positioning.
Within the heritage-specialist tier, Knipex anchors premium-grade diagonal cutter positioning across European industrial distribution. Stanley Black and Decker exemplifies scale-driven portfolio breadth spanning professional and consumer hardware tiers. Klein Tools occupies the electrician-focused specialization vector, anchoring insulated design presence in North American electrical contractor supply chains.
| Leading Market Players |
|---|
| Knipex |
| Stanley Black and Decker |
| Klein Tools |
| Techtronic Industries |
| RS Pro |
| Apex Tool Group |
| Snap-On Incorporated |
| Bahco |
| Facom |
| Others |
Value Network & Pricing Analysis
Undercapacity in Solingen's heat treatment facilities is compressing lead times for Rockwell 58-62 HRC jaw hardening, forcing premium manufacturers to prioritize long-term contract customers while spot buyers absorb escalating price premiums for expedited delivery.
Pricing Analysis
Long-term offtake agreements dominate procurement between German heritage manufacturers and industrial distributors, insulating premium tier suppliers from spot market volatility in chromium-molybdenum alloy feedstock. Price differentiation hinges on VDE certification grade and volume scale, with certified insulated tools commanding substantial premiums over uncertified alternatives. Pricing pressure stems from REACH compliance costs accelerating across European supply chains. Construction contractors exhibit highest price sensitivity, while aerospace harness shops demonstrate lowest sensitivity due to traceability requirements.
Supply Chain Analysis
Extended payment terms from German industrial distributors are squeezing working capital for Vietnamese assembly operations, forcing regional suppliers toward supply-chain finance facilities anchored by export credit agencies. Production draws from Germany, China, and Vietnam, with raw material dependencies on South African chromium, Kazakh molybdenum, and Japanese cobalt formulations. Single-source vulnerability concentrates in Solingen's forging cluster. Distribution runs through professional electrical distributors and direct manufacturer portals serving fleet-managed contractor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wire cutters market functions as a regulatory-entrenchment story, where VDE and OSHA certification requirements create switching costs that protect incumbent positions against commodity competition.
For Market Incumbents: Insulate premium positioning through captive heat treatment capacity expansion in Solingen and accelerated trivalent chrome plating R&D ahead of REACH sunset enforcement. Electric crimping system substitution in automotive Tier-1 plants threatens manual cutter volumes. Certification investment in dual GB-VDE protocols preserves Chinese market access. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's tariff-advantaged manufacturing corridor for ASEAN electrical infrastructure buildouts. Ribbon fiber micro-cutters for India's fiber-to-the-home rollout represent the most penetrable white space. Direct manufacturer portals with integrated asset tracking offer the strongest go-to-market angle against entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pneumatic and hydraulic system manufacturing as Vietnamese assembly platforms achieve scale efficiency. Long-term viability favors vertically integrated specialists with captive metallurgical expertise rather than pure-brand marketers. The signal to watch is migration of aerospace harness procurement toward connected torque-sensing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Treatment Capacity Expansion | Solingen facility investments anchor Rockwell 58-62 HRC jaw supply for premium diagonal cutter output. |
| Trivalent Chrome Plating Transition | REACH Annex XVII compliance eliminates hexavalent plating from European-distributed hand tool SKUs. |
| Vietnam Manufacturing Footprint | Hanoi and Ho Chi Minh City industrial parks offer tariff-advantaged export platforms for ASEAN markets. |
| Connected Tool Ecosystem Development | Torque-sensing cutter heads with telemetry capture address Boeing and Airbus supplier traceability mandates. |
| Dual-Certification Protocol Investment | Parallel GB standard and VDE testing preserves market access across Chinese and European procurement channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed tool manufacturers, and professional electrical distributor inventory records. Primary interviews engaged product managers at heritage forging operations, procurement leads at German industrial distributors, and safety officers at North American electrical contractor fleets. Secondary sources included OSHA enforcement databases, ECHA REACH substance restriction updates, and SAMR GB standard documentation. Bottom-up unit economics triangulate against top-down market sizing from trade flow analysis.
Forecast inputs span product type segmentation across manual, electric, pneumatic, and hydraulic configurations; end-user verticals including construction, electrical, automotive, and telecommunications; and material tiers from chrome-vanadium steel through carbon fiber composites. CAGRs derive from replacement cycle velocity differentials across operational contexts and penetration curve modeling for insulated and ergonomic feature adoption. Industry-specific inputs incorporate renewable energy grid buildout timelines and fiber-to-the-home deployment schedules.
Stress conditions across chromium-molybdenum price volatility, Solingen logistics disruption, and electric crimping substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and infrastructure investment continuity. Macroeconomic contraction, accelerated REACH substance restrictions, or breakthrough automated termination technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodworking Tools Market
Tools
US Hitter Based Hand Tools Market
Tools
Woodpecker Tools Market
Tools
Automated Plasma Beveller Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Riveting Tools Market
Tools
Global Scarifiers Market
Tools
Machining Centers Market
Tools
Coil Thread Insert Market
Tools
Friction Washer Market
Tools
Multi Spindle Machines Market
Tools
Sander Market
Tools
North America Power Tools Market
Tools
Squeegee Market
Tools
Crimping Tool Market
Tools
Machine Tools Market