
 Bridal Wear Market | 2026-2036
Bridal Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Bridal Wear Market Intelligence
China is tilting toward large-scale bridal manufacturing clusters in Guangdong and Suzhou, drawing fabric suppliers and embellishment workshops into dense production corridors. Pronovias Fashion Group leverages its Barcelona ateliers and Asian licensing partnerships to sustain European design credibility with Asian cost structures. Vera Wang anchors premium positioning in North America through controlled distribution at flagship salons and select department store concessions. Elie Saab France competes at the haute couture tier, occupying a narrow but defensible position in hand-beaded luxury bridal gowns.
Bridal wear comprises ceremonial garments engineered for formal wedding rites, typically constructed from layered textiles with internal corsetry, boning, and structured skirts requiring twenty to eighty hours of specialized labor per unit. Wedding gowns command the dominant revenue share across product categories, while accessories and veils capture disproportionate margin contribution relative to their production cost. Fabric type segmentation shows lace and satin maintaining volume leadership, though tulle is gaining share in destination wedding applications where lighter construction aids transportability. Distribution through specialty boutiques retains the highest conversion rate, yet online retailers are capturing growing inquiry volume through virtual try-on integrations.
REACH and the EU Green Deal impose chemical disclosure and circularity obligations on European-sourced textiles, while China's GB standards govern formaldehyde limits and color fastness in domestically sold bridal fabrics. The US FTC maintains truth-in-labeling enforcement on fiber content claims, affecting import compliance for offshore manufacturers. Stakeholders must monitor how digital product passport requirements under CSRD reshape traceability investments and supplier qualification timelines across their sourcing networks.
Market Dynamics
Destination wedding planners are expanding procurement budgets while REACH chemical standards in Europe force dye reformulation across textile supply chains, compressing supplier qualification timelines and reshaping competitive positioning in bridal manufacturing.
Growth Catalysts
- REACH compliance investments:European dye houses upgrading formulation capabilities are capturing premium positioning among sustainability-focused bridal brands seeking verified chemical disclosure.
- Guangdong-Suzhou corridor concentration:Fabric suppliers and embellishment workshops clustering in China's dense production corridors are shortening lead times for domestic bridal atelier networks.
- Virtual try-on integrations:Online retailers deploying augmented reality fitting tools are converting inquiry volume previously lost to physical boutique visits.
Market Restraints
- Silk and lace input volatility:Natural fiber price swings and embroidery labor shortages in traditional craft regions are compressing margin predictability for mid-tier gown producers.
- Single-region dye concentration:European REACH-compliant dye capacity concentrates among a handful of specialized chemical suppliers, creating bottleneck risk for brands dependent on EU-sourced textiles.
- Corsetry construction limitations:Twenty-to-eighty-hour specialized labor requirements per gown cap production scalability regardless of capital investment.
Strategic Opportunities
- CSRD digital product passports:Early compliance with EU traceability mandates is creating qualification advantages for European bridal brands in corporate sustainability procurement.
- Destination wedding logistics:Tulle-dominant lightweight construction for transportability is opening specialized product lines among travel-focused bridal boutiques.
- Veil and accessory margin capture:Disproportionate margin contribution relative to production cost in accessories is attracting capital toward captive embellishment production.
Industry Challenges
- Hand-beading craft scarcity:Haute couture-tier embroidery specialists are aging out of the workforce faster than apprenticeship programs replenish skill pipelines.
- CSRD supplier qualification timelines:Digital product passport requirements are extending vendor onboarding cycles by six to twelve months for European-sourced collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridal Wear Market |
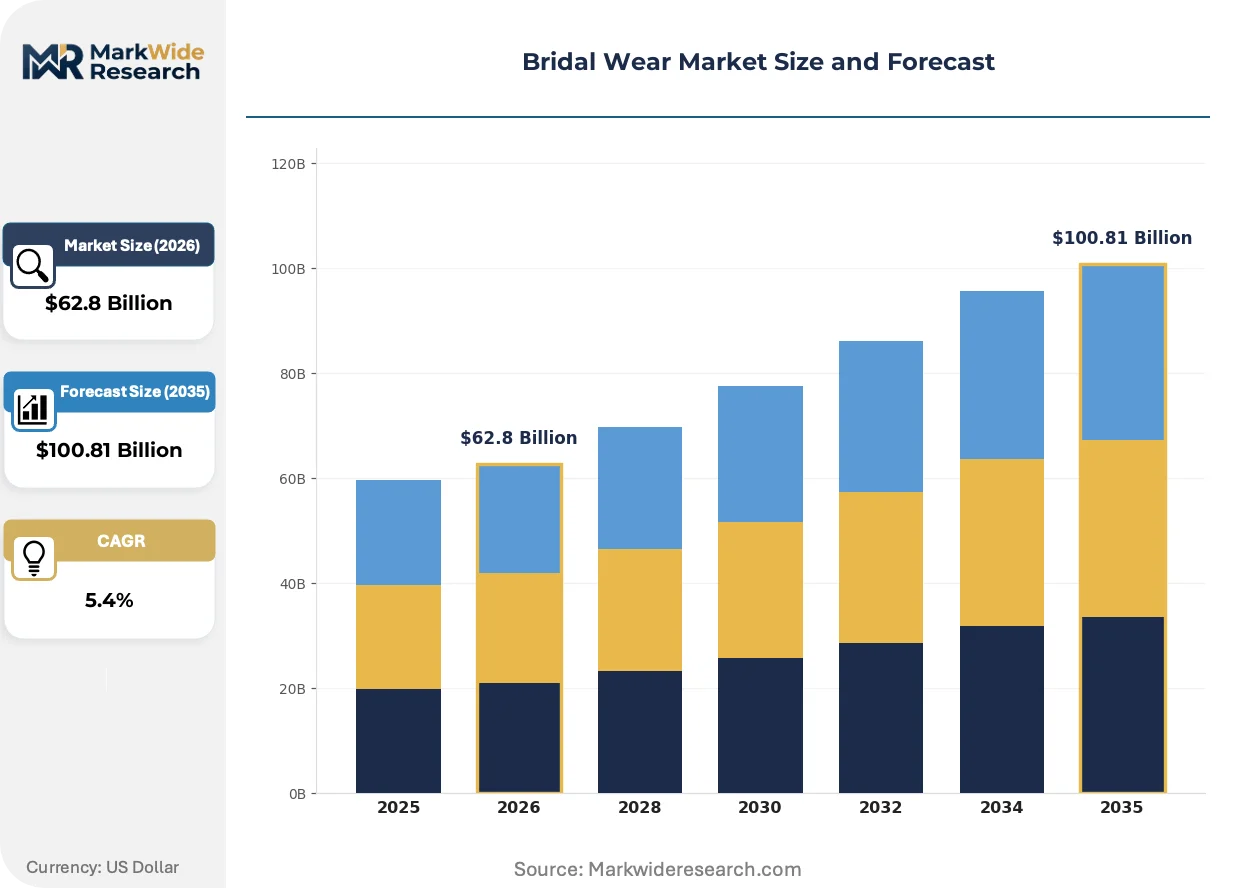
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $100.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wedding Gowns, Bridesmaid Dresses, Veils, Shawls, Accessories Fabric Type: Lace, Satin, Tulle, Chiffon, Organza, Velvet Occasion: Traditional Ceremonies, Destination Weddings, Engagement Parties, Receptions, Bridal Showers Distribution Channel: Specialty Boutiques, Online Retailers, Department Stores, Bridal Expos, Custom Tailors |
| Companies Covered | Zuhair Murad, Oscar de la Renta, Pronovias Fashion Group, Demetrios, Rosa Clará, Vera Wang, Monique Lhuillier Inc., JLM Couture Inc., Elie Saab France, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridal Wear Market Strategic Shifts & Innovations
Three intersecting forces are compressing traditional bridal production models: augmented reality is collapsing the physical-digital boundary in customer acquisition, chemical disclosure mandates are rewriting supplier qualification protocols, and destination wedding logistics are favoring lighter construction methods over traditional layered textiles.
AI-powered virtual fitting engines are rendering obsolete the appointment-only salon model that historically gated premium bridal access. Destination wedding planners and millennial first-time buyers are adopting these tools at accelerating velocity, compressing the traditional six-to-twelve-month purchase cycle into weeks. The structural consequence is disintermediating boutique intermediaries and forcing flagship salons to reposition around experiential services rather than inventory access.
REACH chemical standards and the EU Green Deal are imposing mandatory circularity obligations on European-sourced textiles. Industrial consequence includes forced dye reformulation investments and accelerated supplier consolidation among compliance-capable chemical houses. Haute couture hand-beaded collections and lace-dominant product lines face the steepest cost adjustments, with several Barcelona and Paris ateliers restructuring Asian licensing partnerships to buffer European regulatory exposure.
Buyer concentration among destination wedding planners is fragmenting traditional seasonal purchasing patterns. These planners now coordinate multi-gown logistics for international ceremonies, replacing single-gown bridal salon relationships with direct-atelier procurement. This shift is most visible in Mediterranean and Southeast Asian resort corridors where planners maintain preferred vendor status with Guangdong and Suzhou manufacturers, bypassing traditional wholesale distribution entirely.
Bridal Wear Market Segmentation
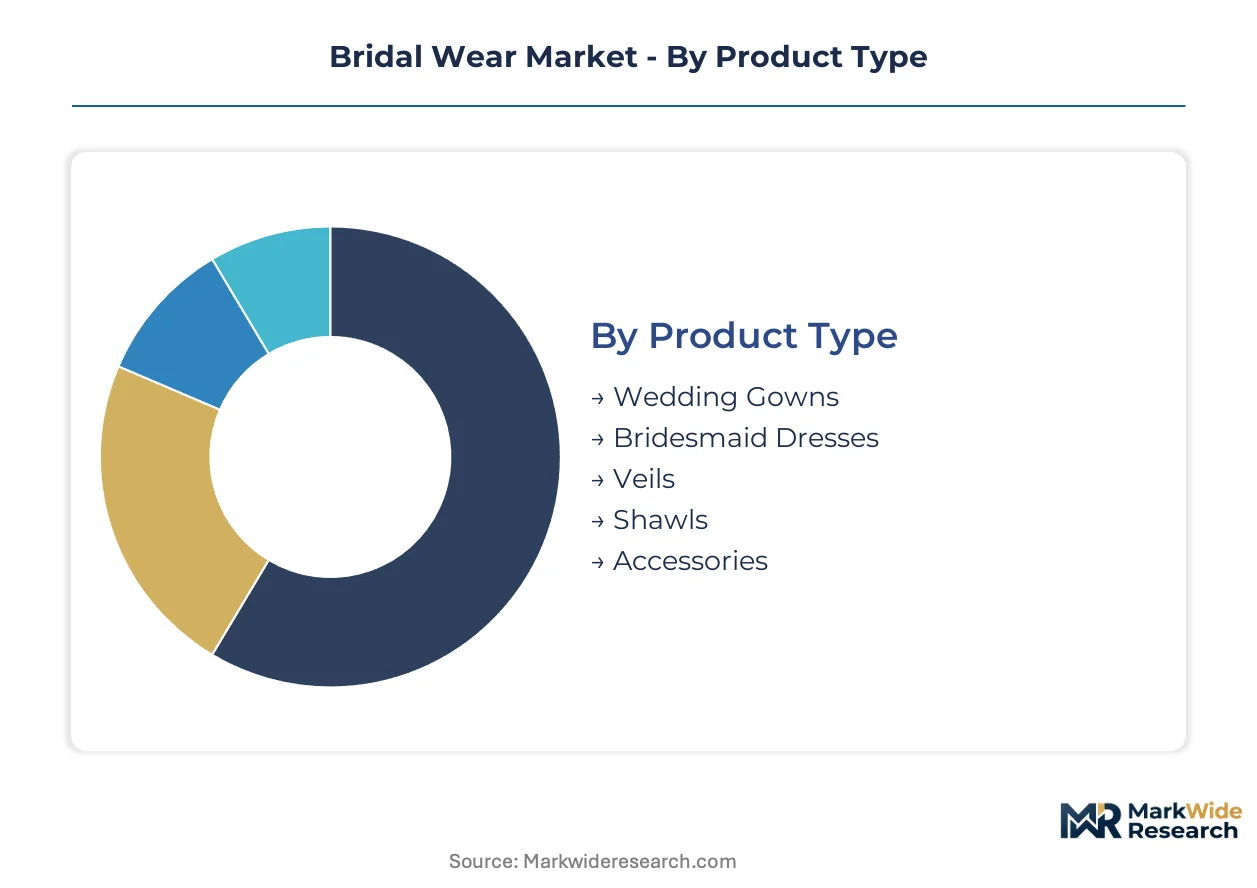
Bridal wear segmentation reveals stark turnover velocity differences across product lines, with accessories cycling in weeks while corseted gowns require months of construction. Understanding these temporal dynamics helps manufacturers allocate specialized labor and inventory capital across divergent production timelines.
Product Type:
Wedding gowns turn over slowest due to corsetry labor intensity, while accessories and veils rotate fastest through retail channels with minimal fitting requirements.
- Wedding Gowns:Layered ceremonial garments with internal boning and structured skirts demand twenty to eighty hours of specialized labor per unit. Demand concentrates among destination wedding planners in Mediterranean and Southeast Asian resort corridors who now coordinate multi-gown logistics for international ceremonies.
- Veils:Sheer headpieces constructed from tulle or lace netting require minimal structural labor yet capture disproportionate margin contribution relative to production cost. Brides in North America favor cathedral-length dramatic silhouettes, while European buyers prefer fingertip-length practicality for transportability.
- Bridesmaid Dresses:Coordinated attendant apparel with simpler construction cycles than bridal gowns, typically ordered in batch quantities for wedding parties.
- Shawls:Covering garments for temperature management during ceremonies, experiencing seasonal demand spikes in autumn and winter wedding calendars.
- Accessories:Jewelry, belts, and hairpieces with the fastest inventory velocity and lowest barrier to impulse purchase at bridal expos and online channels.
Wedding gowns anchor the volume base while accessories gain share at the steepest rate.
Fabric Type:
Cost tiers separate naturally by fiber origin and finishing complexity, with synthetic bases dominating entry price points and natural fibers commanding premium positioning.
- Lace:Open-weave decorative fabric produced through needlework or chemical etching, requiring hand-finishing for haute couture applications. Suzhou embroidery workshops supply European ateliers facing REACH dye compliance pressures, though craft scarcity among aging specialists constrains volume scaling.
- Satin:Glossy weave with high thread count creating reflective surface characteristics, historically preferred for formal ceremonies. Guangdong mills produce satin bases for domestic Chinese bridal brands expanding atelier networks, shortening lead times through corridor concentration.
- Tulle:Lightweight net fabric gaining preference in destination wedding applications where transportability outweighs structural drama. Mediterranean planners specify tulle-dominant construction for multi-location ceremonies.
- Chiffon:Sheer plain-weave fabric with slight stretch, favored for flowing silhouettes in bridesmaid dresses and reception attire.
- Organza:Crisp transparent fabric with more body than chiffon, selected for structured overlays and voluminous skirt layers.
- Velvet:Dense pile fabric with light-absorbing surface, niche seasonal demand concentrated in winter ceremonies and vintage-inspired collections.
Satin and lace together capture the dominant revenue share, though tulle is climbing the fastest as destination logistics reshape material specifications.
Occasion:
Application context determines construction weight, with travel-intensive ceremonies demanding lighter builds than static traditional rites.
- Destination Weddings:International ceremonies requiring gown transportability and climate adaptability. Planners in Caribbean and Southeast Asian corridors maintain direct procurement relationships with Guangdong manufacturers, bypassing wholesale distribution entirely.
- Traditional Ceremonies:Formal religious or cultural rites in fixed locations permitting heavier construction and elaborate trains. European cathedrals and North American churches sustain demand for layered silhouettes with extended hemlines.
- Engagement Parties:Pre-wedding celebrations generating demand for white or ivory cocktail attire distinct from full ceremonial gowns.
- Receptions:Post-ceremony celebrations where brides often change into lighter dance-appropriate alternatives with reduced structural elements.
- Bridal Showers:Gift-giving gatherings with casual dress codes, minimal specialized apparel demand beyond thematic accessories.
Traditional ceremonies anchor the volume base while destination weddings gain share at the steepest rate.
Distribution Channel:
Customer type stratifies sharply between appointment-driven experiential seekers and convenience-oriented digital buyers.
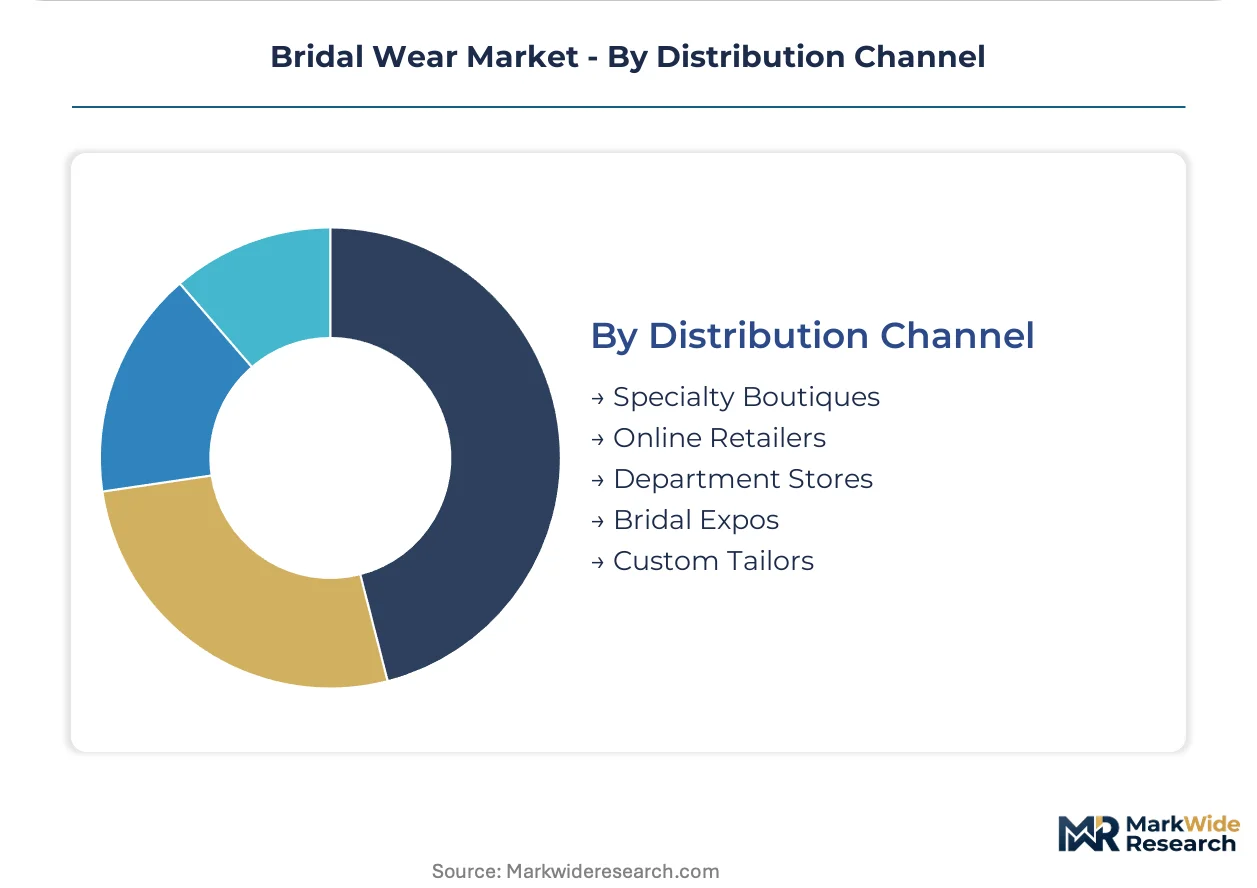
- Specialty Boutiques:Appointment-only salons with highest conversion rates through personalized fitting services. Flagship locations in New York and Paris reposition around experiential value as virtual try-on tools disintermediate inventory access.
- Online Retailers:Digital channels capturing growing inquiry volume through augmented reality fitting integrations, compressing traditional six-to-twelve-month purchase cycles into weeks.
- Department Stores:Select concessions at luxury retailers offering bridal alongside broader occasion wear, dependent on foot traffic correlation with general apparel purchasing.
- Bridal Expos:Periodic exhibition events generating concentrated lead generation for regional ateliers and accessory vendors.
- Custom Tailors:Bespoke construction services for non-standard sizing or design modifications, extending production timelines significantly.
Specialty boutiques anchor the volume base while online retailers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical standards in Europe anchor the regulatory framework reshaping textile dye compliance across bridal supply chains. ECHA enforcement of substance restrictions is forcing reformulation investments among European dye houses. Production corridors in Asia and atelier networks in North America are adapting qualification protocols to maintain market access.
United States
Destination wedding planners in Florida and California are expanding multi-gown procurement for Caribbean and Pacific ceremonies. FTC truth-in-labeling enforcement on fiber content claims affects import compliance for offshore manufacturers. New York flagship salons reposition around experiential services as virtual try-on tools disintermediate inventory access.
China
Domestic bridal brands are scaling atelier networks in Guangdong and Suzhou, drawing fabric suppliers and embellishment workshops into dense production corridors. GB standards govern formaldehyde limits and color fastness in domestically sold bridal fabrics. Suzhou embroidery workshops supply hand-finishing capabilities for lace applications facing craft scarcity pressures.
Spain
Barcelona ateliers sustain European design credibility through Asian licensing partnerships that buffer REACH regulatory exposure. EU Green Deal circularity obligations accelerate supplier consolidation among compliance-capable chemical houses. Catalan manufacturing clusters specialize in corseted construction requiring twenty-to-eighty-hour labor per gown.
France
Parisian haute couture houses occupy narrow but defensible positions in hand-beaded luxury bridal gowns. ANSM chemical disclosure requirements extend supplier qualification timelines for European-sourced collections. Île-de-France ateliers face aging craft specialist pipelines faster than apprenticeship programs replenish embroidery talent.
United Kingdom
London specialty boutiques retain highest conversion rates through personalized fitting services despite online channel growth. CSRD digital product passport requirements reshape traceability investments for bridal brands sourcing European textiles. British bridal expos generate concentrated lead generation for regional accessory vendors and veil specialists.
Bridal Wear Market Key Industry Players
Capability concentration sits with haute couture ateliers possessing hand-beading craft expertise; scale advantage sits with Asian licensing partnerships leveraging cost-optimized production corridors. The market structures around three tiers: European heritage houses with design credibility, Asian manufacturing platforms with corridor density, and North American distribution specialists with flagship salon networks. Dominant competitive moves include Asian licensing partnerships that buffer regulatory exposure and virtual try-on integrations that compress traditional purchase cycles.
Within the European heritage tier, Pronovias Fashion Group and Elie Saab France exemplify atelier-based positioning sustained through Asian production partnerships. Vera Wang anchors North American premium positioning through controlled distribution at flagship salons. These three represent distinct archetypes: the Barcelona-licensed European house, the Parisian haute couture specialist, and the New York-based salon-centric brand.
| Leading Market Players |
|---|
| Zuhair Murad |
| Oscar de la Renta |
| Pronovias Fashion Group |
| Demetrios |
| Rosa Clará |
| Vera Wang |
| Monique Lhuillier Inc. |
| JLM Couture Inc. |
| Elie Saab France |
| Others |
Cost & Logistics Intelligence
REACH dye reformulation bottlenecks in European chemical houses determine both the premium-to-economy spread in bridal textiles and the geographic reconfiguration of supplier networks toward Asian licensing partnerships.
Pricing Analysis
Barcelona and Paris ateliers command three-to-five-fold premiums over Guangdong contract production, with price differentiation resting on hand-beading certification tiers and corsetry labor intensity. Cost compression in mid-tier satin gowns is intensifying because Suzhou corridor manufacturers are absorbing REACH compliance overhead for European export-bound collections. Destination wedding planners exhibit the lowest price sensitivity, while online direct-to-consumer buyers drive economy-tier pricing softness.
Supply Chain Analysis
Guangdong and Suzhou manufacturing clusters hold dominant contract capacity for global bridal production, with Barcelona and Paris ateliers retaining specialized corsetry and hand-finishing capabilities. Raw material dependencies center on Italian silk suppliers, French lace mills, and Chinese synthetic fiber bases. Single-source vulnerability concentrates in REACH-compliant European dye houses, where reformulation investments have consolidated capacity among three specialized chemical suppliers. Distribution runs through specialty boutiques with highest conversion rates, though direct-atelier procurement by destination planners is fragmenting traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-powered virtual fitting engines that collapse the traditional salon appointment model into digital-first purchase cycles.
For Market Incumbents: Harden flagship salon positioning around experiential services rather than inventory access, as virtual try-on tools disintermediate traditional intermediaries. Deepen Asian licensing partnerships in Guangdong to buffer REACH regulatory exposure and secure cost-optimized production corridors. Prioritize captive veil and accessory production to capture disproportionate margin contribution.
For New Entrants and Emerging Players: Southeast Asian resort corridors present underpenetrated white space where destination planners maintain direct procurement relationships bypassing wholesale distribution entirely. Target tulle-dominant lightweight construction for multi-location ceremonies. Enter through digital-native channels with augmented reality fitting integrations that compress traditional purchase cycles.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors Asian-licensed European heritage houses with established atelier credibility. Long-term viability hinges on controlling hand-beading craft pipelines as aging specialists exit faster than apprenticeship programs replenish talent. Watch CSRD digital product passport compliance timelines as the inflection signal—brands with qualified supplier networks will capture corporate sustainability procurement advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Asian Licensing Partnership | Barcelona ateliers leverage Guangdong production to buffer REACH dye reformulation costs. |
| Virtual Try-On Integration | Online retailers deploy augmented reality tools to convert inquiry volume previously lost to boutiques. |
| Captive Accessory Production | Vertical control over veil manufacturing captures disproportionate margin contribution relative to gown construction. |
| CSRD Compliance Investment | Early digital product passport qualification creates procurement advantages with corporate sustainability buyers. |
| Destination Wedding Product Line | Tulle-dominant lightweight construction addresses transportability requirements in Mediterranean and Caribbean corridors. |
Research Approach
The analysis maps wedding gowns, veils, accessories, and bridesmaid dresses, each validated through bridal salon operators, destination wedding planners, textile procurement leads, and atelier production managers. Primary interviews with these stakeholders combined with secondary validation from customs trade data, ECHA substance restriction filings, and SEC disclosures from publicly traded fashion houses. Bottom-up unit economics triangulated against top-down market sizing across product type, fabric category, occasion application, and distribution channel dimensions.
Assumptions held fixed include REACH enforcement timelines and GB standard formaldehyde limits, while variables tested included virtual try-on adoption velocity and destination wedding planner procurement share. The projection framework modeled volume and value across the analysis window using CAGRs derived from historical bridal expenditure patterns and demographic cohort sizing. Key inputs included corsetry labor hour requirements per gown tier and dye house capacity constraints under EU Green Deal circularity mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native entrants or accelerated CSRD enforcement would shift outcomes beyond modeled ranges. Quarterly review of virtual try-on conversion rates, REACH-compliant dye house capacity utilization, and Suzhou embroidery workshop labor availability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Stockings Market
Apparel Textiles
Europe Footwear Sole Material Market