
 United Kingdom Home Textile Market | 2026-2036
United Kingdom Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Home Textile Market Analytics
Recycled polyester is restructuring cost and sustainability profiles across mid-market bedding lines. Dunelm Group plc leverages vertical sourcing partnerships to control margin exposure on cotton-dominant categories. John Lewis & Partners sustains premium positioning through certified organic linen collections. IKEA (UK) anchors volume throughput with flat-pack logistics integration for textile accessories.
United Kingdom Home Textile encompasses woven, knitted, and non-woven fabric goods designed for interior domestic environments, typically specified by thread count, GSM weight, or flammability performance ratings for upholstery and bedding applications. The segment serves residential decoration, hospitality provisioning, and healthcare hygiene requirements. Bedding dominates value contribution given replacement frequency and premiumization potential in temperature-regulating and hypoallergenic specifications. Online Retail captures the fastest expansion as platform infrastructure and return logistics mature, while Specialty Stores retain margin concentration through tactile purchase validation and bespoke measurement services.
The UK's Furniture and Furnishings (Fire) (Safety) Regulations and BSI flammability standards shape product compliance costs and restrict untreated natural fiber penetration in upholstery applications. Trading Standards officers enforce labeling requirements that differentiate domestic from contract-grade specifications. Stakeholders must monitor evolving Extended Producer Responsibility consultations for textile waste, as collection infrastructure obligations will recast cost allocation between manufacturers and retailers.
Market Dynamics
The UK's Furniture and Furnishings (Fire) (Safety) Regulations are compressing untreated natural fiber penetration while mandating flame-retardant chemistry investments across upholstery supply chains. This regulatory pressure intersects with hospitality procurement teams extending linen replacement cycles, creating margin tension between compliance costs and volume throughput.
Growth Catalysts
- London's design-led residential renovation cluster:High-value refurbishment projects in Kensington, Chelsea, and Shoreditch are specifying thread-count-differentiated bedding and certified organic linen collections, pulling premium tier demand upward.
- Extended Producer Responsibility consultations:Anticipated textile waste collection infrastructure obligations are accelerating retailer-manufacturer partnerships for closed-loop recycling programs before mandates crystallize.
- Temperature-regulating fiber technology:Phase-change material integration into mid-market bedding lines is capturing replacement-cycle demand from allergy-sensitive households seeking hypoallergenic specifications.
Market Restraints
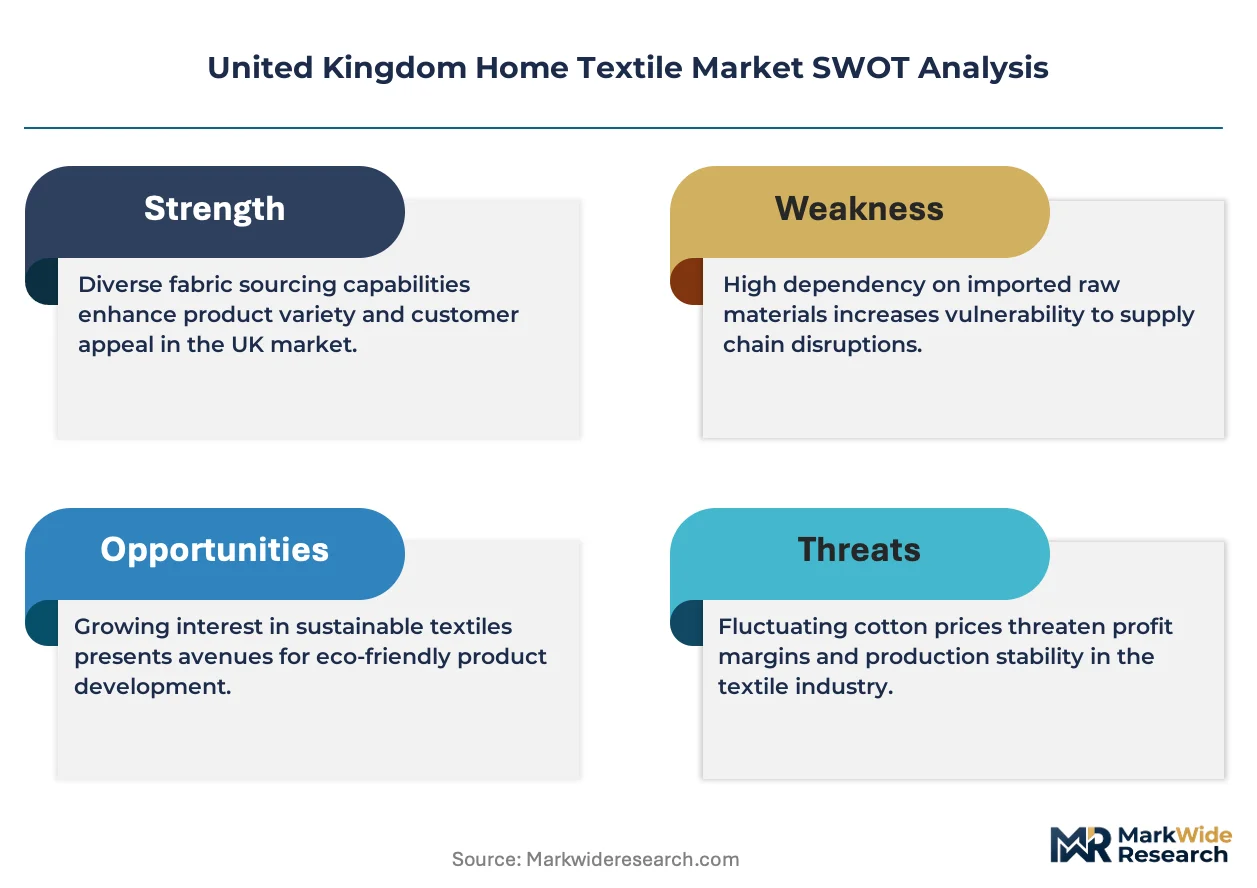
- Cotton price volatility:Egyptian and Pima cotton premium grades face input cost swings that compress margin on cotton-dominant categories where vertical sourcing partnerships cannot fully hedge exposure.
- Flammability compliance cost layering:BSI standards and Trading Standards enforcement create dual certification burdens for upholstery suppliers serving both domestic and contract-grade specifications.
- Polyester microfiber substitution pressure:Lower-cost synthetic alternatives displace natural fiber volume in price-sensitive hospitality procurement, particularly for high-turnover institutional bedding.
Strategic Opportunities
- Scotland's hospitality supply gap:Edinburgh and Glasgow hotel development pipelines lack localized linen provisioning capacity, creating white space for regional fulfillment hubs serving Highland and Islands tourism expansion.
- Online Retail platform maturation:Return logistics infrastructure investment by marketplace operators enables direct-to-consumer bedding brands to bypass tactile validation barriers historically protecting Specialty Stores.
- NHS hygiene textile specification:Healthcare procurement frameworks for antimicrobial and fluid-resistant bedding represent an underpenetrated institutional vertical with standardized volume contracts.
Industry Challenges
- Flame-retardant chemistry talent scarcity:Formulation chemists with UK-specific regulatory expertise command premium compensation, constraining mid-tier manufacturers' compliance timeline acceleration.
- Legacy ERP integration with traceability systems:Batch-level fiber origin tracking required by emerging sustainability certifications conflicts with decades-old inventory management infrastructure at established weaving operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Home Textile Market |
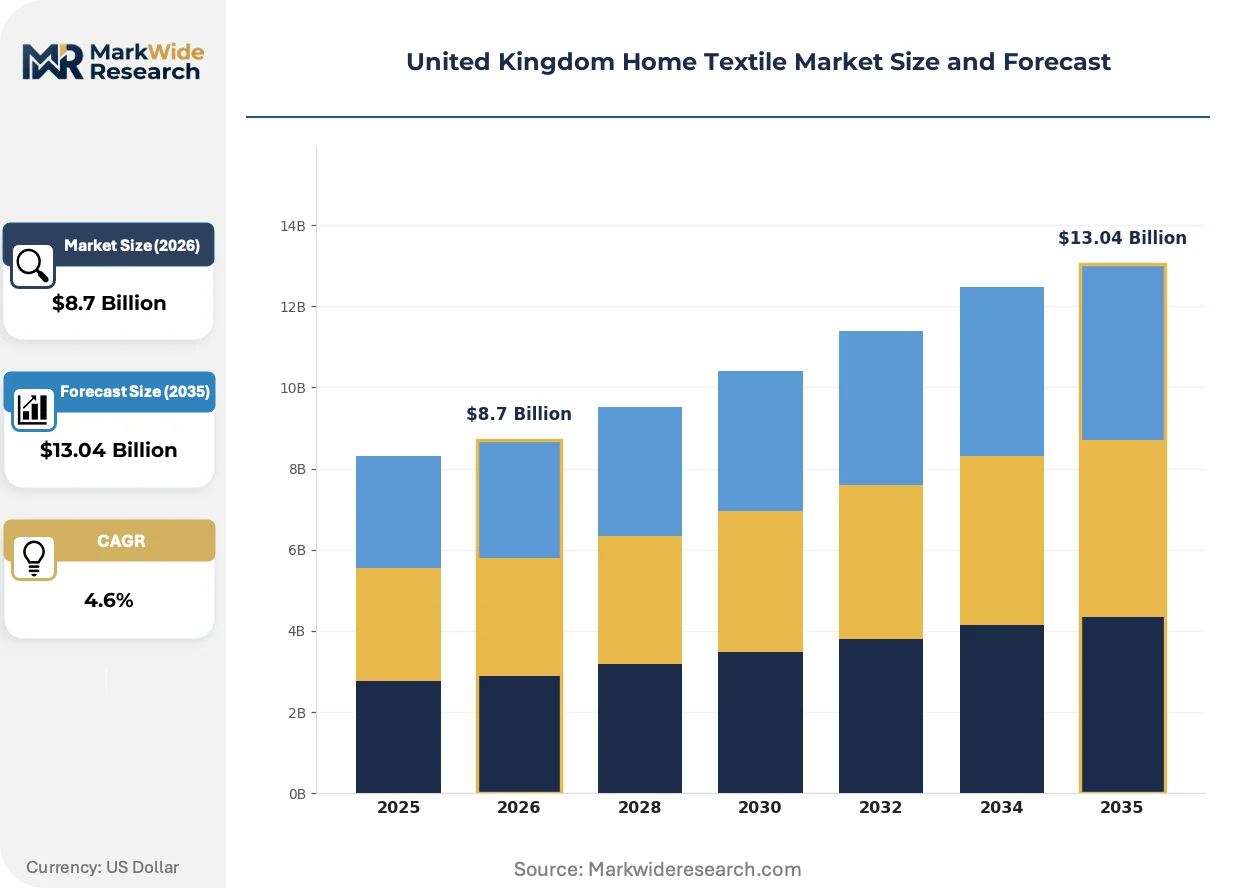
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Curtains, Rugs, Towels Material: Cotton, Polyester, Linen, Wool End User: Residential, Hotels, Retail Stores, Hospitals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | John Lewis & Partners, Amazon (UK Home and Kitchen), Dunelm Group plc, The Range, Wayfair UK, IKEA (UK), Marks and Spencer, B&M Home, NEXT plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Home Textile Market Evolving Landscape
Material science advances and regulatory tightening are converging to restructure product specifications across bedding and upholstery categories. Three developments are actively compressing traditional competitive advantages while opening new specification tiers.
Recycled polyester fiber technology is expanding into temperature-regulating bedding applications through advanced extrusion processes that embed phase-change materials directly into yarn structures. Hospitality procurement teams in Manchester and Birmingham are piloting these specifications for high-occupancy properties where thermal comfort drives guest satisfaction scores. The technology is expanding into mid-market retail channels previously blocked by premium pricing, compressing the performance gap between certified organic linen and synthetic alternatives.
Extended Producer Responsibility frameworks under UK government consultation are mandating producer-funded textile waste collection infrastructure. Trading Standards officers are preparing enforcement protocols for labeling differentiation between domestic and contract-grade specifications, raising compliance documentation burdens. Upholstery manufacturers serving London's residential renovation sector are responding by consolidating supply chains to reduce audit complexity across fewer certified finishing facilities.
Design-led consumers in London's renovation cluster are compressing purchase cycles for statement bedding and window treatments, treating textiles as disposable seasonal elements rather than decade-long investments. This behavioral shift is displacing traditional department store loyalty with platform-driven discovery through visual search and influencer curation. The pattern is most visible in Kensington and Notting Hill, where rapid refurbishment turnover supports premium pricing for limited-edition collaborations.
United Kingdom Home Textile Market Segmentation
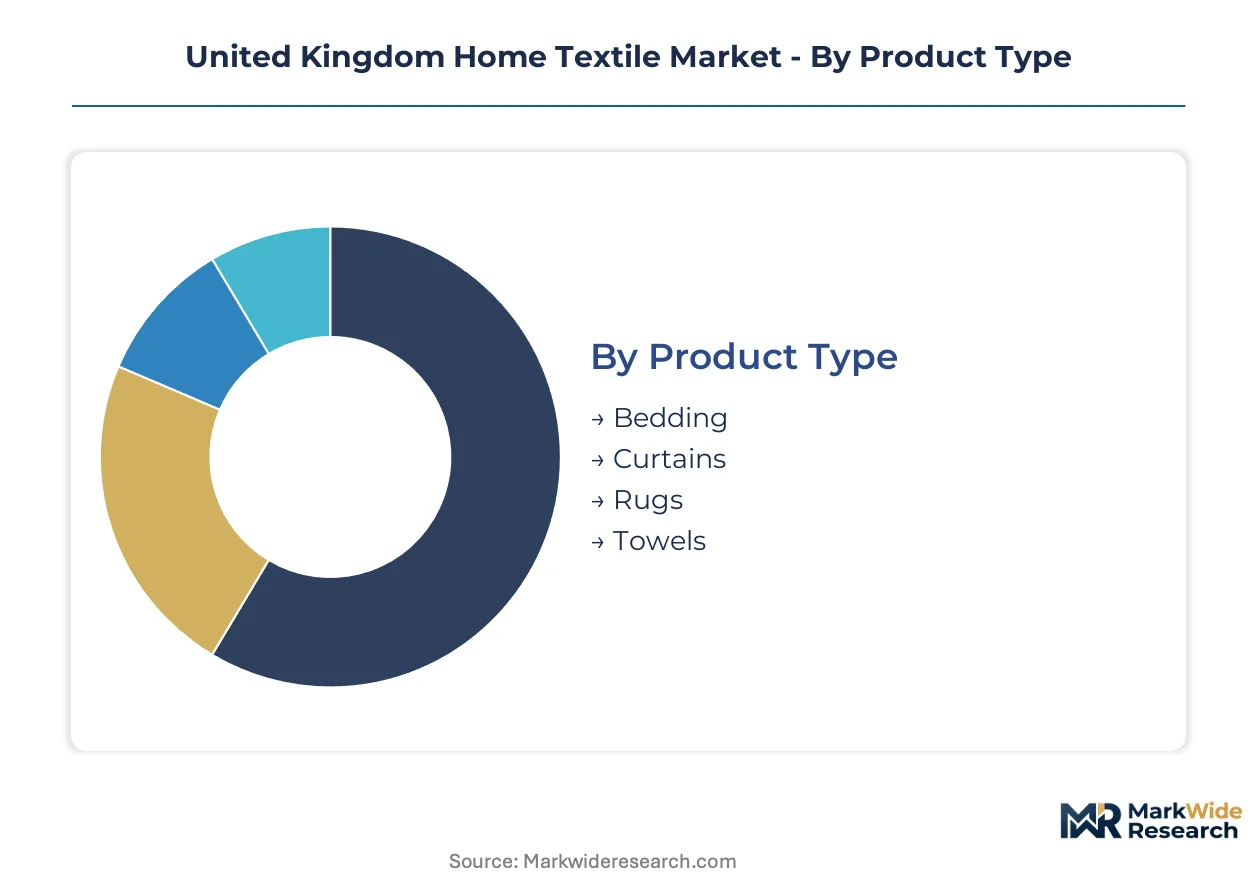
Home textile purchasing in the United Kingdom fragments across functional use cases, material specifications, and procurement contexts. Each dimension carries distinct margin profiles and compliance obligations that reshape competitive positioning.
Product Type:
Bedding operates as standalone replacement purchases driven by thread-count differentiation, while curtains and rugs embed into broader interior renovation projects with longer decision cycles.
- Bedding:Thread-count specifications and temperature-regulating fiber technology dominate purchasing criteria. Demand clusters in London's design-led residential renovation sector and Manchester's hospitality procurement pipelines, where replacement frequency sustains volume throughput despite extended cycles in institutional segments.
- Curtains:Flame-retardant treatment requirements under Furniture and Furnishings (Fire) (Safety) Regulations elevate compliance costs. Kensington and Chelsea refurbishment projects specify bespoke measurements, while mass-market channels compete on flat-pack logistics integration.
- Rugs:Natural fiber penetration faces synthetic substitution pressure in price-sensitive segments. Edinburgh hotel developments source contract-grade specifications with durability warranties.
- Towels:GSM weight ratings differentiate institutional procurement from retail tiers. NHS hygiene frameworks specify antimicrobial treatments for healthcare environments.
Volume placements concentrate in Bedding; the faster expansion belongs to temperature-regulating and hypoallergenic specifications.
Material:
Cost tiers separate premium natural fibers from mid-market synthetics, with recycled alternatives restructuring sustainability positioning.
- Cotton:Egyptian and Pima premium grades face input cost volatility. Vertical sourcing partnerships in Lancashire spinning operations attempt margin protection against commodity swings.
- Polyester:Recycled fiber extrusion with embedded phase-change materials is capturing mid-market bedding share. Birmingham hospitality pilots validate thermal comfort performance against certified organic alternatives.
- Linen:Certified organic collections sustain premium retail positioning. John Lewis & Partners and design-led independents in Notting Hill specify Belgian and French provenance for thread-count differentiation.
- Wool:Natural flame resistance offers compliance advantages under BSI standards. Scottish Highlands tourism properties specify wool-dominant upholstery for fire safety without chemical treatment.
Procurement volume tilts toward Polyester for institutional applications; Linen commands the steepest expansion trajectory in residential premium tiers.
End User:
Customer type determines specification intensity, with contract-grade requirements layering compliance documentation onto base product costs.
- Residential:Design-led consumers in Shoreditch and Notting Hill compress purchase cycles, treating textiles as seasonal elements. Visual search and influencer curation displace traditional department store loyalty.
- Hotels:Procurement teams extend linen replacement cycles to manage margin pressure. Glasgow and Edinburgh development pipelines lack localized provisioning capacity.
- Retail Stores:Tactile validation protects margin concentration through bespoke measurement services. Trading Standards enforcement of labeling requirements differentiates domestic from contract-grade specifications.
- Hospitals:NHS procurement frameworks for antimicrobial and fluid-resistant bedding represent underpenetrated institutional volume. Standardized contracts favor suppliers with batch-level traceability systems.
Residential channels absorb the greatest absolute volume; Healthcare procurement is climbing the fastest as NHS hygiene specifications crystallize.
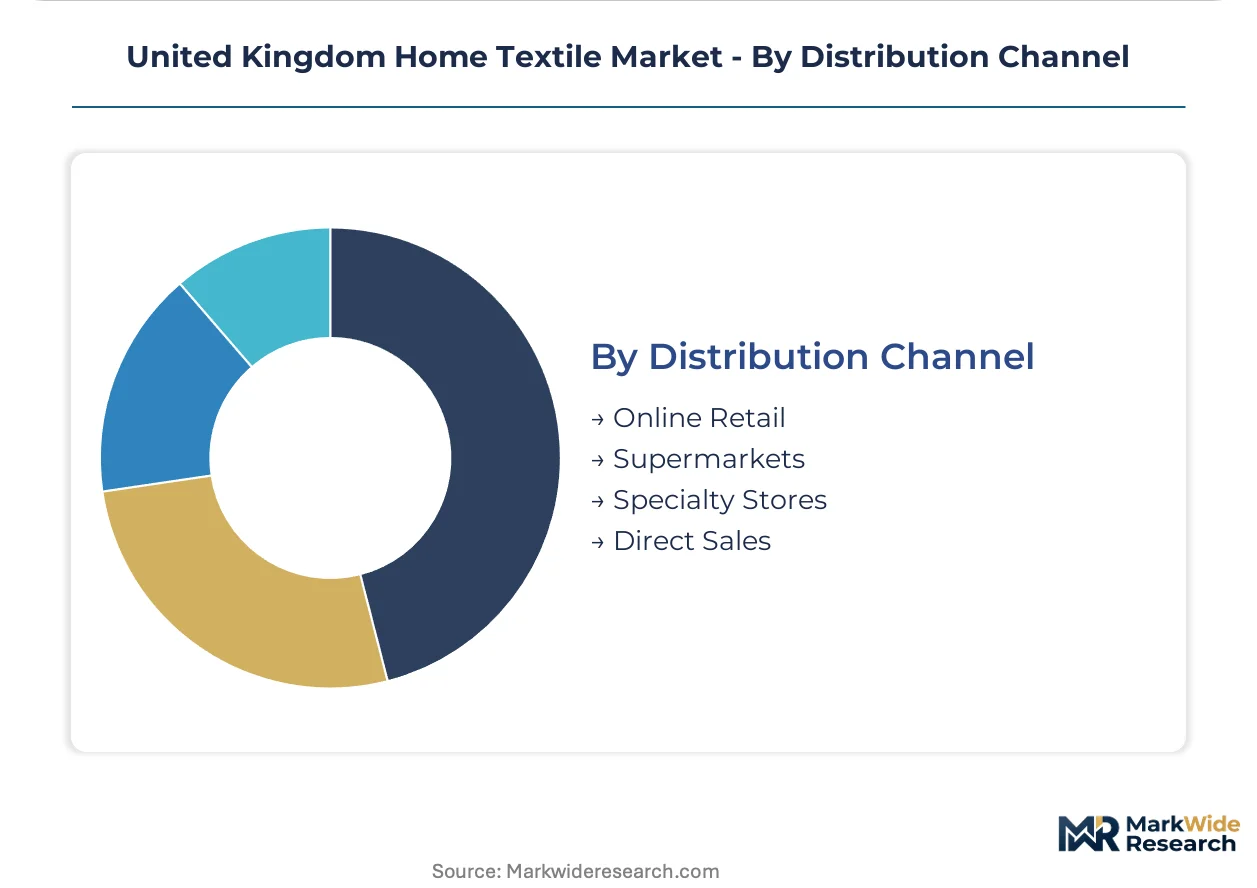
Distribution Channel:
Supply concentration varies by fulfillment infrastructure maturity, with platform operators investing in return logistics to bypass historical tactile barriers.
- Online Retail:Marketplace infrastructure investment enables direct-to-consumer bedding brands to scale without physical presence. Return logistics maturation reduces friction for thread-count-differentiated purchases.
- Supermarkets:Volume throughput competes on price positioning for basic cotton-dominant categories. Dunelm Group plc and IKEA (UK) anchor mass-market penetration.
- Specialty Stores:Tactile validation and measurement services sustain margin concentration. London clusters in Chelsea and Kensington support premium pricing for limited-edition collaborations.
- Direct Sales:Hospitality procurement teams in Manchester and Birmingham source contract-grade specifications through manufacturer relationships. Consolidated supply chains reduce audit complexity across fewer certified finishing facilities.
Supermarkets and Specialty Stores retain current volume leadership; Online Retail is gaining share fastest as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise Zone incentives in the Midlands are concentrating textile finishing capacity near Birmingham's logistics corridors. Scotland's hospitality development pipeline lacks localized linen provisioning infrastructure. Welsh manufacturing zones attract recycled fiber processing investments.
London and the Southeast
Kensington and Chelsea refurbishment projects specify thread-count-differentiated bedding and certified organic linen collections. Trading Standards officers enforce Furniture and Furnishings (Fire) (Safety) Regulations labeling requirements that differentiate domestic from contract-grade specifications. Shoreditch design studios compress purchase cycles, treating textiles as seasonal disposable elements rather than long-term investments.
Midlands
Birmingham hospitality procurement teams pilot temperature-regulating recycled polyester bedding for high-occupancy properties. BSI flammability standards shape upholstery compliance costs across contract-grade specifications. Manchester's spinning operations maintain vertical sourcing partnerships attempting margin protection against Egyptian cotton price volatility.
Scotland
Edinburgh and Glasgow hotel development pipelines lack localized linen provisioning capacity. Extended Producer Responsibility consultations for textile waste accelerate retailer-manufacturer partnerships for closed-loop recycling. Highland tourism properties specify wool-dominant upholstery leveraging natural flame resistance without chemical treatment.
North England
Lancashire weaving operations face legacy ERP integration conflicts with batch-level fiber origin tracking required by sustainability certifications. NHS procurement frameworks for antimicrobial bedding represent underpenetrated institutional volume. Yorkshire textile finishing facilities consolidate supply chains to reduce audit complexity across fewer certified operations.
Wales
Recycled polyester fiber extrusion facilities locate near port infrastructure for imported PET feedstock. The country's national environmental regulator monitors emerging Extended Producer Responsibility collection infrastructure obligations. Cardiff retail corridors attract mass-market volume throughput competing on flat-pack logistics integration.
United Kingdom Home Textile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail-led brands commanding residential volume and hospitality-direct suppliers capturing institutional contracts. The market structure tilts toward consolidated mass-market penetration alongside fragmented premium-tier independents. Three archetypes dominate: vertically integrated retailers controlling cotton-dominant categories, platform-native direct-to-consumer brands bypassing tactile validation barriers, and contract-grade specialists serving NHS and hotel procurement frameworks. Competitive moves concentrate on return logistics infrastructure investment and consolidated supply chain auditing to reduce compliance complexity.
Within the mass-market retail tier, Dunelm Group plc and IKEA (UK) anchor volume throughput through flat-pack logistics integration and vertical sourcing partnerships. John Lewis & Partners occupies a position exemplifying premium-tier positioning through certified organic linen collections and thread-count differentiation. These three entities represent the dominant competitive archetypes: scale-driven logistics integration, backward integration into cotton sourcing, and sustainability-certified premium retail.
| Leading Market Players |
|---|
| John Lewis & Partners |
| Amazon (UK Home and Kitchen) |
| Dunelm Group plc |
| The Range |
| Wayfair UK |
| IKEA (UK) |
| Marks and Spencer |
| B&M Home |
| NEXT plc |
| Others |
Value Network & Pricing Analysis
Egyptian cotton futures volatility transmits directly through Lancashire spinning operations into thread-count-differentiated bedding tiers, compressing margins on premium natural fiber collections while accelerating polyester substitution in institutional procurement.
Pricing Analysis
Short lead-time premiums of three to four weeks command fifteen to twenty percent markups over standard replenishment cycles in London's design-led renovation cluster. Three-tier pricing structure across premium, standard, and economy levels separates certified organic linen collections from temperature-regulating synthetic alternatives and basic cotton-dominant lines. Pricing pressure stems from hospitality procurement teams extending replacement cycles to manage operating cost inflation. Mass-market supermarket buyers exhibit highest price sensitivity, while Kensington refurbishment clients prioritize thread-count differentiation over unit economics.
Supply Chain Analysis
UK Furniture and Furnishings (Fire) (Safety) Regulations mandate domestic finishing capacity for flame-retardant treatment compliance, reshaping sourcing patterns toward certified facilities in Lancashire and Yorkshire. Raw material flows draw from Egyptian and Pima cotton growers, Belgian linen processors, and recycled PET feedstock through port infrastructure in Wales. Single-source vulnerability concentrates in specialty chemical suppliers for flame-retardant formulations. Distribution runs through flat-pack logistics integration at mass-market retailers and direct manufacturer relationships for contract-grade hospitality specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom home textile market is becoming a vertical-integration race, with backward integration into cotton sourcing and captive finishing capacity emerging as the decisive margin lever.
For Market Incumbents: Hedge Egyptian cotton price exposure through multi-origin sourcing agreements with Pima and Sea Island alternatives. Consolidate supply chains across fewer certified finishing facilities to reduce audit complexity under Trading Standards enforcement. Capacity concentration in Yorkshire textile zones protects against flame-retardant chemistry talent scarcity.
For New Entrants and Emerging Players: Scotland's hospitality supply gap offers immediate white-space capture, with Edinburgh and Glasgow hotel pipelines lacking localized linen provisioning infrastructure. NHS hygiene textile frameworks represent an underpenetrated institutional vertical with standardized volume contracts and antimicrobial specification requirements. Direct-to-consumer platform launches bypass tactile validation barriers through return logistics investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier weaving operations with legacy ERP infrastructure in North England, where batch-level traceability system upgrades unlock sustainability certification premiums. Long-term viability hinges on closed-loop recycling program partnerships crystallizing before Extended Producer Responsibility mandates. Watch for Trading Standards enforcement intensity as the inflection signal for compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Sourcing | Lancashire spinning partnerships insulate Dunelm and John Lewis from Egyptian commodity swings. |
| Flame-Retardant Certification Investment | BSI-compliant finishing capacity becomes mandatory entry ticket for London upholstery contracts. |
| Direct-to-Consumer Platform Launch | Return logistics maturation enables bedding brands to bypass tactile validation at Specialty Stores. |
| Closed-Loop Recycling Partnership | Retailer-manufacturer alliances anticipate Extended Producer Responsibility collection obligations. |
| Regional Fulfillment Hub Establishment | Scotland's hospitality pipeline lacks localized provisioning capacity for Highland tourism expansion. |
Research Methodology
Multi-period observation of thread-count specification shifts, flame-retardant compliance cost trajectories, and hospitality procurement cycle extensions anchored the trend analysis, supplemented by interviews with category buyers at mass-market retailers, procurement directors at Manchester and Birmingham hotel groups, spinning operation managers in Lancashire, and Trading Standards enforcement officers. Secondary validation drew from UK government Extended Producer Responsibility consultation documents, BSI flammability standard updates, NHS hygiene framework specifications, and customs data on cotton and polyester fiber imports. Bottom-up volume modeling across product type, material, end user, and distribution channel segments triangulated against top-down market sizing.
Input-output matrices mapped fiber origin through spinning, weaving, finishing, and retail distribution stages across the analysis window. Segmentation dimensions modeled include product function, material specification tier, end-use procurement context, and channel fulfillment infrastructure. CAGRs derived from trend extrapolation of replacement frequency patterns, premiumization trajectories in temperature-regulating specifications, and platform penetration rates in online retail. Forecast inputs incorporated hospitality development pipeline data for Edinburgh and Glasgow, and NHS antimicrobial bedding procurement framework evolution.
Revisions become necessary when flame-retardant chemistry regulation tightens beyond current BSI standards, cotton futures volatility exceeds historical bands, or Extended Producer Responsibility implementation timelines accelerate. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Bath Towel Market
Home Textiles
Global Theater Linen Market
Home Textiles
Textile Floorings Market
Home Textiles
United States Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Home Textiles Market
Home Textiles
Plush Blanket Market
Home Textiles
UAE Home Textiles Market
Home Textiles
China Home Textiles Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Germany Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Baby Crib Sheet Market