
 Middle East and Africa Textile Garment Market | 2026-2036
Middle East and Africa Textile Garment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Textile Garment Market Foresight
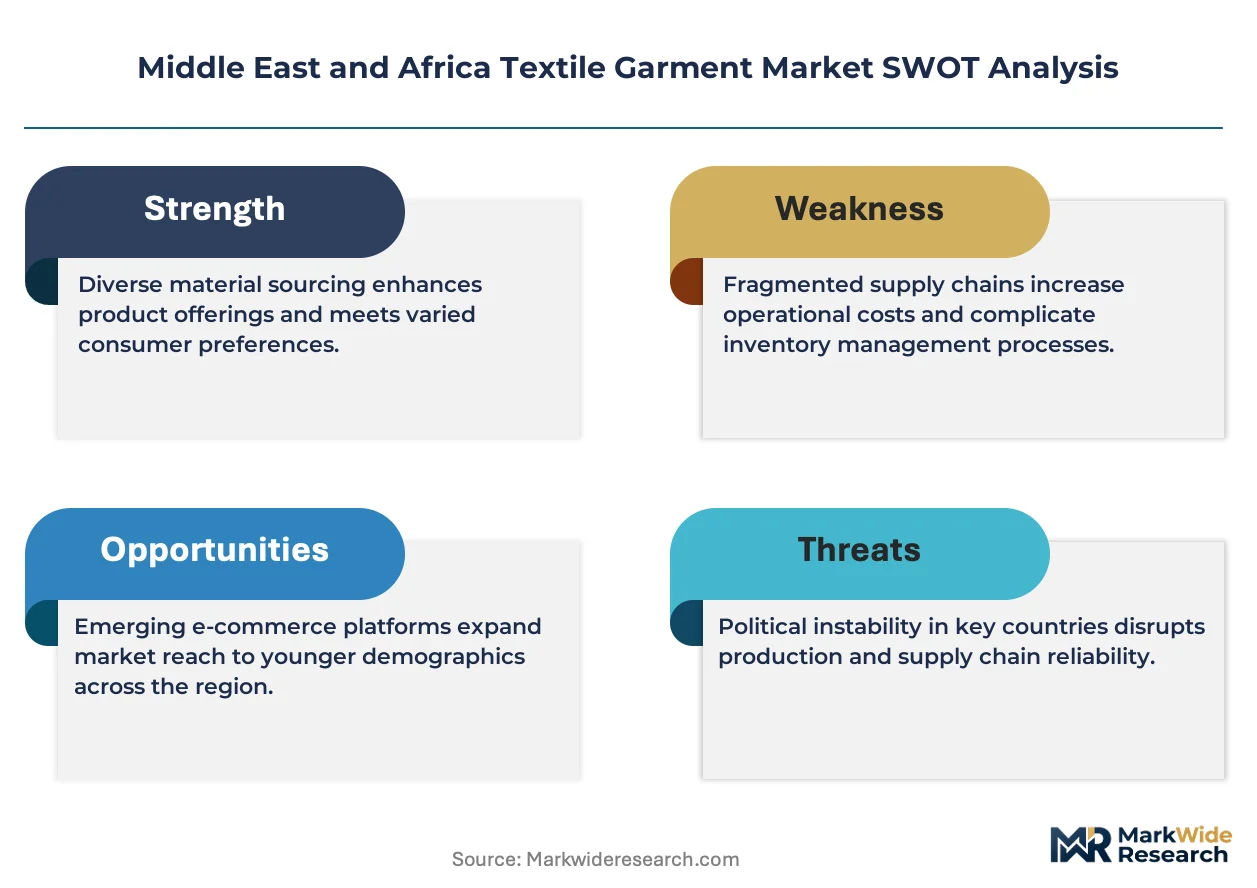
A shift from single-source cotton procurement toward multi-source blended-fiber sourcing is recalibrating supply-chain risk profiles across the Middle East and Africa textile garment market. Vlisco leverages its wax-print heritage and West African distribution depth to sustain brand loyalty among regional consumers. Egyptian Spinning & Weaving Co. anchors Nile Delta production clusters with integrated spinning-to-garment capacity. Da Gama Textiles specializes in authentic shweshwe fabric, competing on cultural authenticity rather than cost parity.
The Middle East and Africa textile garment sector encompasses finished apparel, fabric intermediates, accessories, and footwear manufactured through cut-make-trim, weaving, knitting, and dyeing processes with fiber compositions spanning cotton, polyester, wool, and silk, primarily serving consumer wear, industrial uniform, and fashion export end-uses. Cotton retains dominance in casual wear and traditional garment segments where breathability and regional cultivation advantages persist, while polyester commands sportswear and workwear applications demanding moisture-wicking durability and lower unit costs. Accessories and footwear represent margin-accretive categories where brand licensing and import substitution policies are redirecting regional manufacturing investment.
Egypt's General Authority for Investment and Free Zones, South Africa's National Regulator for Compulsory Specifications, and Morocco's Office des Changes collectively shape fiber-content labeling, import-duty structures, and export-processing zone eligibility that determine factory location decisions and product-standard compliance costs. The EU Green Deal's extended producer responsibility provisions for textile waste are beginning to penetrate North African export-oriented production through buyer-imposed audit requirements. Stakeholders must monitor how carbon-border adjustment mechanisms and shifting rules-of-origin clauses in EU-association agreements reshape competitive standing between Maghreb and sub-Saharan manufacturing alternatives.
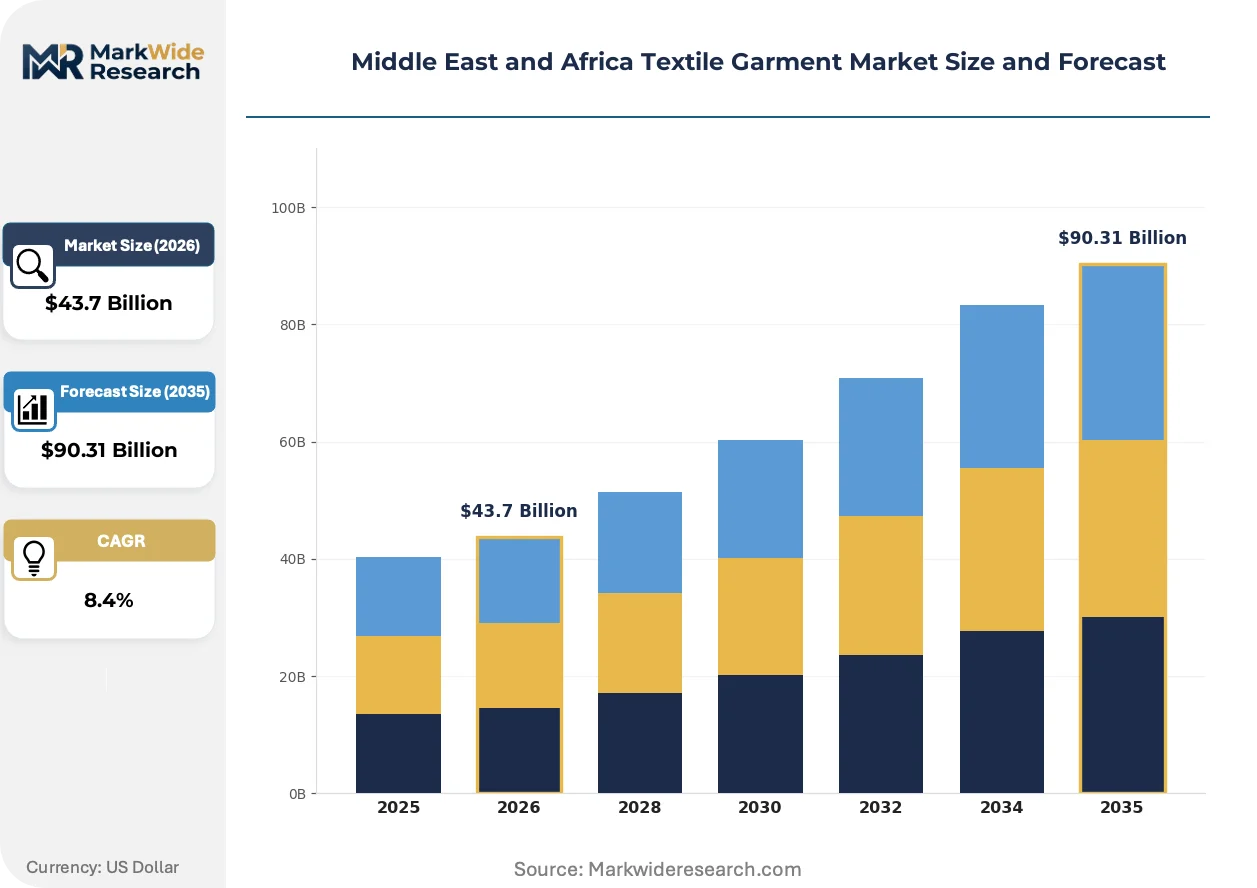
Market Dynamics
Blended-fiber sourcing strategies are restructuring procurement networks across the Middle East and Africa textile garment market, as manufacturers diversify beyond cotton monocultures to hedge climate and price volatility.
Growth Catalysts
- Egypt's updated investment frameworks:New industrial zone incentives under the General Authority for Investment and Free Zones are drawing polyester-intensive sportswear production to Nile Delta clusters with integrated spinning-to-garment capacity.
- EU Green Deal extended producer responsibility:Buyer-imposed audit requirements for textile waste management are penetrating North African export corridors, accelerating compliance infrastructure investment among Moroccan fast-fashion suppliers.
- West African distribution depth:Heritage wax-print manufacturers leverage established retail networks across Nigeria, Ghana, and Côte d'Ivoire to sustain brand loyalty against lower-cost Asian imports.
Market Restraints
- Cotton price volatility:Irrigation-dependent Egyptian and Sudanese cultivation faces Nile water allocation disputes and erratic rainfall patterns, compressing margin predictability for natural-fiber-dependent producers.
- Concentrated European buyer power:Moroccan and Tunisian export-oriented factories depend on a narrow base of fast-fashion purchasing offices in Barcelona, Amsterdam, and London, amplifying order cancellation risk.
- Shweshwe authenticity constraints:Da Gama Textiles' cultural copyright enforcement limits replication by competitors, but also caps production scalability for this heritage segment.
Strategic Opportunities
- Kenya's underdeveloped technical textiles:Automotive and medical textile manufacturing remains minimal despite AGOA preferential access, presenting first-mover potential for industrial fabric producers.
- Ethiopia's renewable energy garment parks:Hydroelectric-powered industrial zones offer carbon-intensive European buyers a compliance-aligned nearshoring alternative to South and Southeast Asian suppliers.
- Digital textile printing convergence:Combination of reactive ink chemistry and on-demand production software enables shorter run lengths for regional fashion brands testing localized capsule collections.
Industry Challenges
- Technical skills fragmentation:Pattern engineering and automated cutting expertise concentrates in Casablanca and Johannesburg, leaving secondary cities dependent on expatriate contractors or delayed training pipelines.
- EU-association agreement rule-of-origin complexity:Third-country fabric sourcing restrictions require meticulous documentation across Egyptian, Moroccan, and Tunisian customs regimes, extending order-to-delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Textile Garment Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $90.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Fabrics, Accessories, Footwear End User: Retail Consumers, Manufacturers, Designers, Distributors Material: Cotton, Polyester, Wool, Silk Application: Casual Wear, Formal Wear, Sportswear, Workwear |
| Companies Covered | Vlisco, Nile Textiles, National Spinning Company, Al Rais Manufacturing Co., Springwood Industries, Egyptian Spinning & Weaving Co., Da Gama Textiles, United Nigeria Textiles Plc, Classic Fashion, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Textile Garment Market Shifts & Advancements
Digital traceability infrastructure and circular material flows are reconfiguring how Middle East and Africa textile manufacturers demonstrate compliance and capture premium positioning in European export channels.
Blockchain-enabled fiber provenance tracking is consolidating supply-chain transparency into a competitive baseline rather than a differentiator. Leading Moroccan denim exporters to Spanish retailers now embed QR-linked dye-lot records at the greige fabric stage. This compression of verification costs is squeezing smaller Tunisian competitors lacking IT integration budgets.
EU Green Deal carbon-border adjustment mechanisms are tightening emissions documentation requirements for Egyptian and Turkish textile intermediates entering EU garment assembly. The European Chemicals Agency's expanding restricted substance lists now capture perfluorinated compounds common in Egyptian water-repellent finishes. North African dye houses are accelerating substitution toward bio-based alternatives to maintain EU association agreement tariff advantages.
Direct-to-retailer platform procurement is shortening traditional buying cycles for West African wax-print distributors. Lagos-based fashion brands now place sub-container-load orders through Alibaba's African trade channel rather than consolidating through Dakar import agents. This disintermediation compresses working capital cycles for Nigerian retailers but fragments volume predictability for Ghanaian printing mills calibrated to seasonal bulk shipments.
Middle East and Africa Textile Garment Market Segmentation
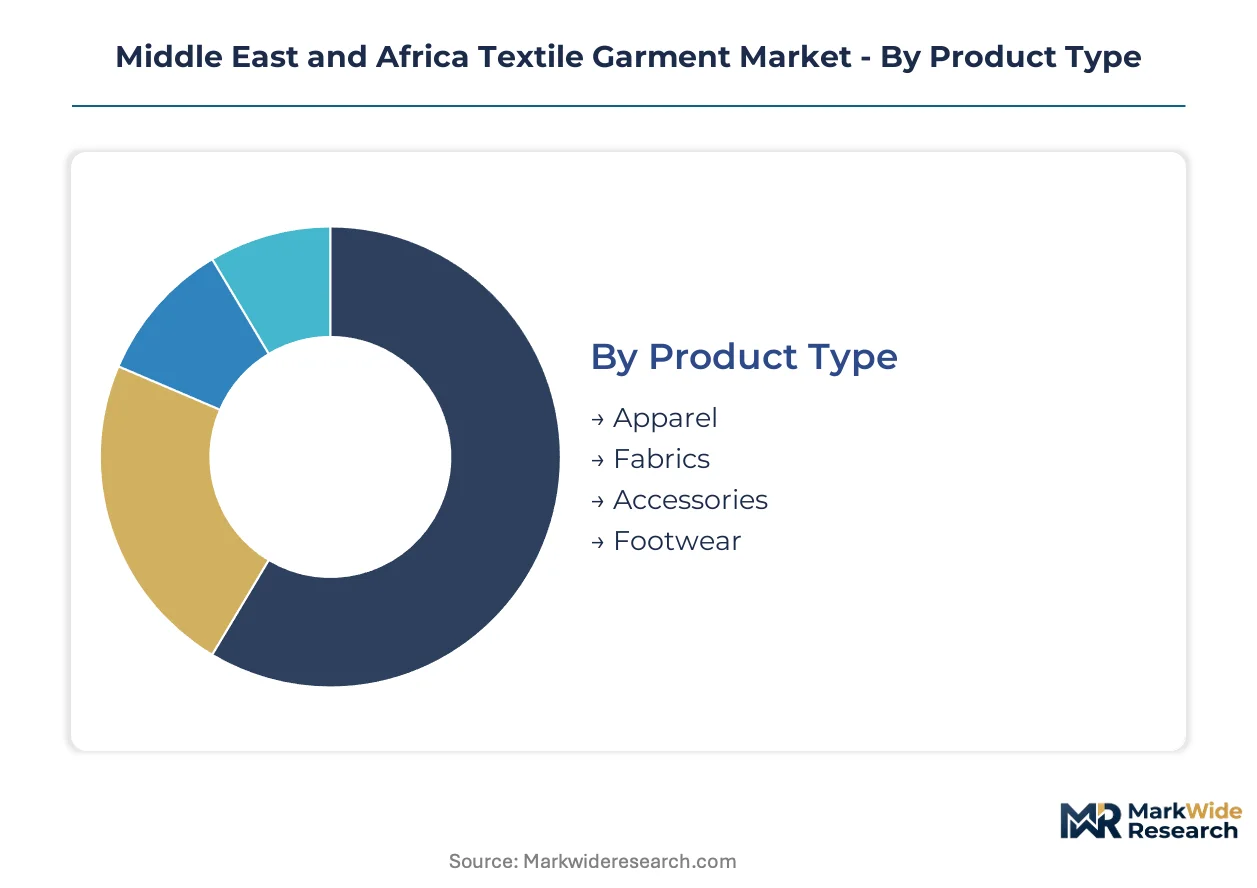
Segmentation in the Middle East and Africa textile garment market reveals how fiber composition, end-user procurement patterns, and application-specific performance requirements create distinct competitive arenas. Manufacturers calibrate capacity investments against these divides, as Egyptian cotton spinners, Moroccan polyester weavers, and South African wool finishers serve fundamentally different customer economics.
Product Type:
Buyer procurement scale and margin structure separate these categories, with export-oriented volume buyers dominating fabrics while fragmented retail channels shape accessories and footwear.
- Apparel:Cut-make-trim operations across Nile Delta and Casablanca-Rabat corridors produce finished garments for European fast-fashion brands and domestic retail. Moroccan export-oriented factories capture the largest order volumes through proximity to Barcelona and Amsterdam purchasing offices.
- Fabrics:Greige and finished textiles from Egyptian Spinning & Weaving Co. and Tunisian denim mills supply regional cut-make-trim operators and direct EU garment assemblers. This segment concentrates investment in dyeing and finishing capacity to meet EU Green Deal chemical compliance.
- Accessories:Margin-accretive belts, bags, and trim products from Johannesburg and Lagos workshops serve brand-licensing arrangements and import substitution programs.
- Footwear:Leather and synthetic upper production in Addis Ababa and Tangier-Med zones targets AGOA and EU association agreement tariff advantages.
Volume sits with Fabrics; growth tilts toward Accessories.
End User:
Procurement sophistication and order predictability distinguish these buyers, from specification-driven manufacturers to trend-responsive designers.
- Retail Consumers:Individual purchasers across Nigeria, Egypt, and South Africa drive wax-print shweshwe heritage segments and mass-market casual wear. Da Gama Textiles and Vlisco maintain brand loyalty through cultural authenticity rather than price competition.
- Manufacturers:Cut-make-trim operators and garment assemblers in Ethiopia's Hawassa Industrial Park and Kenya's Export Processing Zones purchase greige fabrics and accessories under long-term supply contracts with volume discounts.
- Designers:Lagos and Nairobi fashion houses commission short-run capsule collections through digital textile printing services, prioritizing speed and customization over unit cost.
- Distributors:West African import agents in Dakar and Accra consolidate container-load shipments for inland retail networks, capturing working capital spreads between Asian suppliers and Nigerian end-markets.
Manufacturers command the heaviest procurement volumes; designers are expanding most quickly.
Material:
Climate exposure and cultivation geography lock in fiber sourcing patterns that manufacturers cannot easily substitute without reformulating entire supply chains.
- Cotton:Nile Delta cultivation and Sudanese irrigation-dependent production supply natural-fiber garment segments where breathability and regional heritage positioning matter. Water allocation disputes and erratic rainfall compress margin predictability for Egyptian and Sudanese growers.
- Polyester:Petrochemical-derived fiber dominates sportswear and workwear applications across Moroccan and Egyptian industrial zones, leveraging moisture-wicking durability and lower unit costs against cotton alternatives.
- Wool:South African merino and Lesotho mohair feed premium formal wear and cold-weather garment production in Johannesburg and Cape Town clusters.
- Silk:Minimal regional cultivation leaves this segment dependent on imported raw material, limiting scale to niche luxury applications in Dubai and Casablanca ateliers.
Cotton retains volume leadership; polyester gains share fastest.
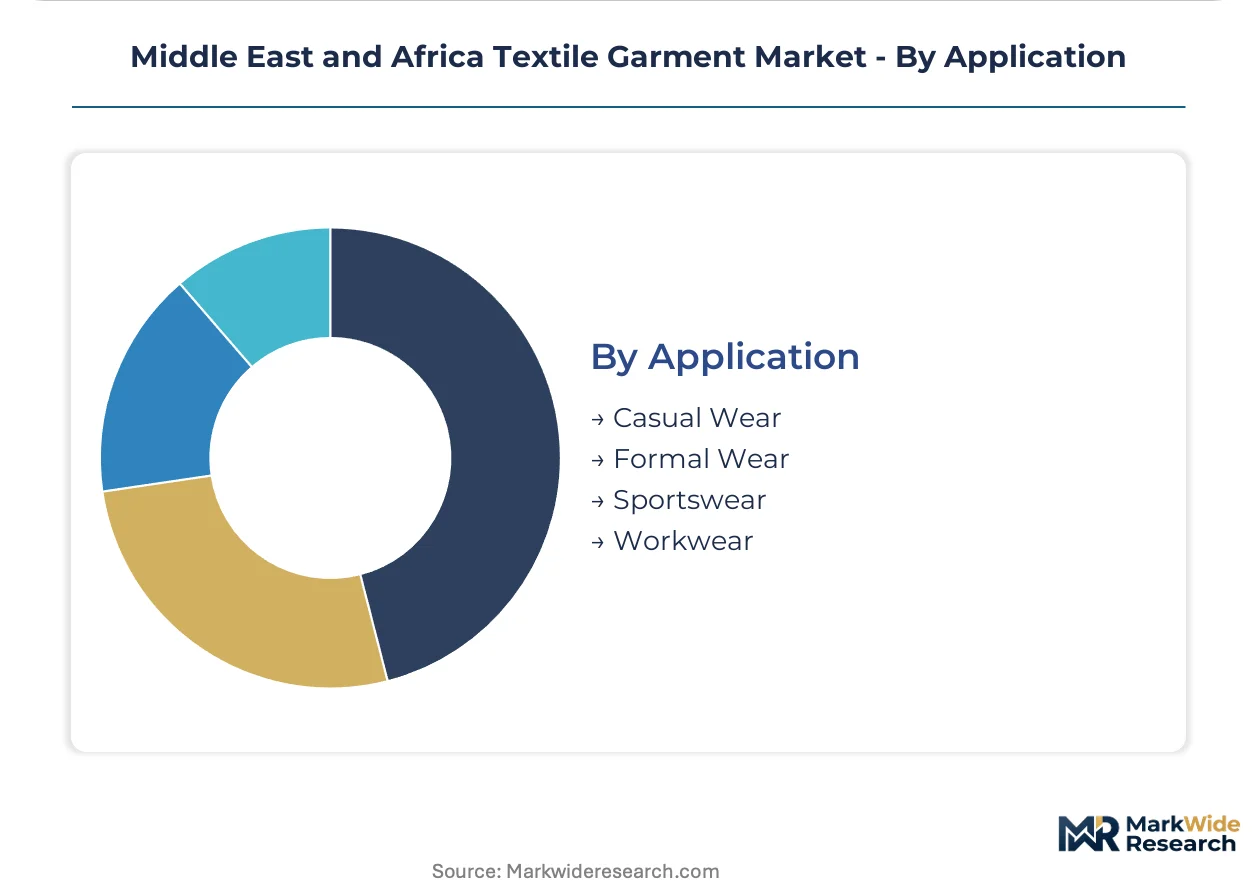
Application:
Performance specifications and replacement frequency separate these end-uses, with workwear and sportswear demanding technical durability while casual wear emphasizes cost and cultural resonance.
- Casual Wear:Cotton-intensive everyday garments for Middle Eastern and North African retail channels, where regional heat drives preference for breathable natural fibers. Egyptian and Moroccan producers compete on speed-to-market for seasonal collections.
- Formal Wear:Wool-blend suits and traditional garments for Gulf state and South African professional markets, requiring precise tailoring capabilities concentrated in Casablanca and Johannesburg.
- Sportswear:Polyester-intensive athletic apparel production in Egypt's new industrial zones serves both domestic fitness demand and European export orders, with moisture-wicking and stretch specifications driving fiber selection.
- Workwear:Industrial uniform manufacturing for mining, oil and gas, and logistics sectors across South Africa and the Gulf, where flame resistance and high-visibility standards require certified fabric treatments.
Casual Wear holds the largest volume base; Sportswear shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the Middle East and Africa textile garment market centers on export-oriented manufacturing clusters serving European fast-fashion buyers and domestic retail networks across Nigeria, Egypt, and South Africa. Procurement gravity pulls toward North African corridors with EU association agreement access and Ethiopian industrial parks leveraging AGOA preferential terms. Regulatory frameworks in each jurisdiction determine factory location decisions and compliance cost structures.
Egypt
Polyester-intensive sportswear production is expanding across Nile Delta industrial zones under updated General Authority for Investment and Free Zones incentives. Egyptian Spinning & Weaving Co. anchors integrated spinning-to-garment capacity that reduces lead times for European buyers. Water allocation disputes along the Nile compress margin predictability for cotton-dependent cultivation in Upper Egypt.
Morocco
Fast-fashion export corridors serving Barcelona and Amsterdam purchasing offices concentrate garment assembly in Casablanca-Rabat industrial zones. The Office des Changes administers export-processing zone eligibility and import-duty structures that shape fiber-content compliance costs. EU Green Deal extended producer responsibility provisions are penetrating production through buyer-imposed audit requirements for textile waste management.
South Africa
Wool-blend formal wear and heritage shweshwe fabric production clusters in Johannesburg and Cape Town serve domestic professional markets and cultural authenticity positioning. The National Regulator for Compulsory Specifications shapes product-standard compliance for industrial uniform applications. Merino and mohair sourcing from Eastern Cape and Lesotho feeds premium garment segments with limited scalability.
Ethiopia
Hydroelectric-powered industrial parks in Hawassa offer carbon-intensive European buyers a compliance-aligned nearshoring alternative with AGOA tariff advantages. Technical skills fragmentation in pattern engineering and automated cutting creates dependency on expatriate contractors or delayed training pipelines. Renewable energy positioning attracts sportswear and workwear manufacturers seeking emissions documentation for EU export channels.
Nigeria
Wax-print heritage segments sustain brand loyalty through established retail networks across Lagos, Kano, and Port Harcourt distribution corridors. Direct-to-retailer platform procurement via Alibaba's African trade channel is shortening traditional buying cycles and compressing working capital cycles for domestic retailers. Import substitution policies are redirecting regional manufacturing investment toward accessories and footwear production.
Middle East and Africa Textile Garment Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale dyeing and finishing infrastructure to meet EU Green Deal chemical compliance requirements. The vendor base spans state-affiliated Egyptian spinning conglomerates, West African heritage print specialists, and North African export-oriented cut-make-trim operators. Three archetypes prevail: integrated spinning-to-garment conglomerates, heritage authenticity specialists, and fast-fashion export assemblers. Competitive moves center on backward integration into captive fiber supply and geographic expansion toward Ethiopian renewable energy zones.
Among heritage authenticity specialists, Vlisco leverages wax-print heritage and West African distribution depth to sustain regional brand loyalty against lower-cost Asian imports. Egyptian Spinning & Weaving Co. occupies a position exemplifying the integrated conglomerate archetype with Nile Delta production clusters spanning raw material through finished garment. Da Gama Textiles anchors the cultural copyright enforcement tier, limiting replication by competitors while capping production scalability for its authentic shweshwe fabric segment.
| Leading Market Players |
|---|
| Vlisco |
| Nile Textiles |
| National Spinning Company |
| Al Rais Manufacturing Co. |
| Springwood Industries |
| Egyptian Spinning & Weaving Co. |
| Da Gama Textiles |
| United Nigeria Textiles Plc |
| Classic Fashion |
| Others |
Supply & Pricing Matrix
EU Green Deal extended producer responsibility mandates are compressing margin structures for North African export-oriented manufacturers, forcing Egyptian and Moroccan suppliers to absorb compliance audit costs or cede volume to Ethiopian renewable-energy zones with embedded carbon documentation. This demand-side specification shift fragments pricing power across heritage-authenticity specialists, integrated spinning conglomerates, and fast-fashion assemblers serving divergent buyer archetypes.
Pricing Analysis
Volume concentrates in greige and finished fabrics where Egyptian Spinning & Weaving Co. and Tunisian denim mills compete on contract-based long-term offtake with European garment assemblers, while margins accrete in accessories and heritage wax-print segments where Vlisco and Da Gama Textiles command brand premiums. Price differentiation hinges on EU chemical compliance certification and vertical integration depth, with integrated Nile Delta producers capturing 15-20 point margin advantages over cut-make-trim operators dependent on third-party dye houses. Cost compression in polyester-intensive sportswear reflects Moroccan industrial zone overcapacity and concentrated European buyer power, while shweshwe authenticity constraints insulate Da Gama from price erosion. Retail consumers in Nigeria and Ghana show highest price sensitivity to Asian import alternatives, whereas Gulf state professional markets absorb wool-blend formal wear premiums.
Supply Chain Analysis
Regional distribution centers in Casablanca, Dakar, and Johannesburg operate hub-and-spoke patterns consolidating container-load shipments from Egyptian spinning mills and Asian polyester suppliers for West African inland retail networks. Manufacturing concentrates in Egypt, Morocco, and Ethiopia, with raw material dependencies spanning Nile Delta cotton, imported petrochemical-derived polyester fiber, and Lesotho mohair for premium wool segments. Single-source vulnerability pervades Egyptian cotton cultivation exposed to Nile water allocation disputes, while logistics chokepoints at Tangier-Med and Port Said delay order-to-delivery timelines for EU-bound fast-fashion. Distribution runs through fragmented import agents in Lagos and Accra facing disintermediation pressure from Alibaba's African trade channel direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU Green Deal compliance costs and technical skills fragmentation will force sub-scale Tunisian dye houses and expatriate-dependent Ethiopian cut-make-trim operators toward acquisition or exit over the projection horizon.
For Market Incumbents: Hedge cotton price volatility through backward integration into Sudanese irrigation partnerships or pivot capacity toward polyester-intensive sportswear in Egypt's new industrial zones. Secure EU chemical compliance certification ahead of carbon-border adjustment mechanism enforcement to defend margin position against Turkish intermediates with superior emissions documentation. Channel control through captive retail networks in Lagos and Accra insulates wax-print heritage segments from Alibaba disintermediation. For New Entrants and Emerging Players: Direct-to-retailer platform procurement via trade-channel digitization offers the most penetrable route for Kenyan technical textile specialists targeting underdeveloped automotive and medical fabric segments with AGOA preferential access. Ethiopia's hydroelectric-powered industrial parks present white-space entry for carbon-conscious European sportswear buyers seeking compliance-aligned nearshoring alternatives. Digital textile printing convergence enables short-run capsule collection services for Nairobi and Lagos fashion houses prioritizing speed over scale. For Investors and Strategic Acquirers: The window for entry favors integrated spinning-to-garment conglomerates with captive Nile Delta fiber supply and established EU buyer relationships, as technical skills fragmentation and compliance infrastructure gaps raise barriers for greenfield alternatives. Acquisition targets should demonstrate verified dye-lot traceability systems and renewable energy sourcing documentation aligned with EU association agreement tariff advantages. Monitor Ethiopian industrial park occupancy rates and AGOA renewal negotiations as inflection indicators for nearshoring competitiveness against South and Southeast Asian alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fiber Supply | Egyptian Spinning & Weaving Co. secures margin predictability against Nile water allocation volatility. |
| EU Chemical Compliance Certification Investment | Moroccan denim exporters embed QR-linked dye-lot records to maintain tariff advantages under Green Deal audit requirements. |
| Digital Textile Printing Capability Buildout | On-demand production software enables shorter run lengths for Lagos fashion brands testing localized capsule collections. |
| Renewable Energy Sourcing Documentation | Hawassa Industrial Park hydroelectric positioning attracts carbon-intensive European buyers seeking emissions compliance. |
| Heritage Brand Distribution Network Control | Vlisco's West African retail depth sustains price premiums against lower-cost Asian wax-print imports. |
Research Methodology
Multi-period observation of Egyptian industrial zone investment flows, Moroccan export-processing zone eligibility changes, and Ethiopian AGOA utilization rates anchored the trend analysis, supplemented by interviews with cut-make-trim operations managers, European fast-fashion purchasing officers, West African import agents, dye house technical directors, and heritage brand distribution heads. Secondary validation drew from Egyptian General Authority for Investment and Free Zones filings, Moroccan Office des Changes trade statistics, South African National Regulator for Compulsory Specifications product-standard databases, and EU Green Deal implementation guidance documents. Bottom-up capacity and shipment data triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches calibrated fiber composition splits, end-user procurement scale distributions, and application-specific performance requirements against Egyptian cotton cultivation volumes, Moroccan polyester weaving capacity, and South African wool finishing throughput. CAGRs derived from regression analysis of historical investment patterns and projected buyer-imposed compliance cost trajectories, with sensitivity testing around Nile water allocation scenarios and AGOA preferential access continuity assumptions.
Inputs from Egyptian regulatory filings and EU association agreement negotiation records were available through the study window; gaps in real-time Ethiopian industrial park operational data and confidential buyer audit scorecards introduce uncertainty bands around near-term capacity utilization forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Rain Apparel Market