
 Global Textile Garment Market | 2026-2036
Global Textile Garment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Garment Market Foresight
Sportswear as an end-use vertical is expanding faster than formal attire as athleisure permeates office and social settings. Inditex S.A. controls rapid-response supply chains that compress design-to-rack cycles. Toray Industries specializes in high-performance synthetic fibers that dominate athletic applications. Texhong Textile Group anchors massive spindle capacity across Vietnam and China.
Textile garments encompass finished apparel and accessory products fabricated from natural, synthetic, or blended fibers through weaving, knitting, or nonwoven bonding processes, with specifications ranging from 80 to 400 grams per square meter in base fabric weight depending on end-use thermal and durability requirements. Woven fabrics retain structural rigidity that supports formal attire and workwear margins, while technical textiles command premium pricing in protective clothing where flame resistance and ballistic performance justify specialized certification. Knitted fabrics lead volume growth in casual wear and sportswear due to stretch recovery and breathability advantages.
The EU Green Deal's textile strategy mandates extended producer responsibility and fiber recycling targets that reshape European market access conditions. REACH and the EU AI Act intersect where automated visual inspection systems verify compliance across supply chains. China's GB standards and dual carbon goals impose parallel emissions intensity ceilings on export-oriented manufacturers. Stakeholders must monitor regulatory divergence between European chemical restrictions and Asian production efficiency standards to anticipate compliance cost allocation.
Market Dynamics
EU Green Deal mandates on fiber traceability are compressing supply chain transparency timelines while Bangladesh's ready-made garment export cluster concentrates volume production capacity. REACH chemical restrictions intersect with China's GB standards to create dual compliance burdens for cross-border suppliers.
Growth Catalysts
- Athleisure penetration:Fitness-conscious consumers are integrating sportswear into office and social settings, expanding addressable demand beyond traditional athletic contexts. Knitted fabrics with stretch recovery properties capture this behavioral shift.
- EU Green Deal textile strategy:Extended producer responsibility mandates and fiber recycling targets are creating compliance-driven upgrade cycles across European supply chains. Automated visual inspection systems verify certification requirements.
- Bangladesh export concentration:Ready-made garment clusters achieve scale efficiencies through specialized labor pools and consolidated finishing capacity. Dhaka-Chittagong corridor infrastructure supports rapid turnaround times.
Market Restraints
- Cotton price volatility:Input cost swings in natural fiber markets compress margin predictability for woven fabric producers serving formal attire segments. Synthetic fiber alternatives face parallel petrochemical feedstock exposure.
- Technical textile certification barriers:Flame resistance and ballistic performance standards impose multi-year testing timelines for protective clothing entrants. Specialized certification costs exclude smaller manufacturers.
- Single-region supply concentration:Bangladesh's dominance in basic garment assembly creates geographic risk concentration for brands dependent on low-cost volume production. Alternative sourcing lacks equivalent scale.
Strategic Opportunities
- Vietnam spindle capacity expansion:Texhong Textile Group and comparable operators are adding integrated spinning-weaving capacity outside China tariff exposure. Vietnamese industrial zones offer preferential trade access.
- EU AI Act compliance automation:Machine vision systems for defect detection and traceability documentation qualify as high-risk AI applications requiring conformity assessment. First-movers capture audit-ready positioning.
- Technical textiles in protective applications:Flame-resistant workwear and ballistic-rated garments command premium pricing through specialized fiber engineering. Toray Industries' high-performance synthetics anchor material supply.
Industry Challenges
- Dual carbon compliance engineering:China's emissions intensity ceilings and European carbon border adjustments require simultaneous monitoring of divergent measurement methodologies. Manufacturers must maintain parallel accounting systems.
- Legacy dyeing process retrofitting:Water-intensive finishing operations face tightening discharge permits under MEE and EPA frameworks. Capital requirements for closed-loop systems strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Garment Market |
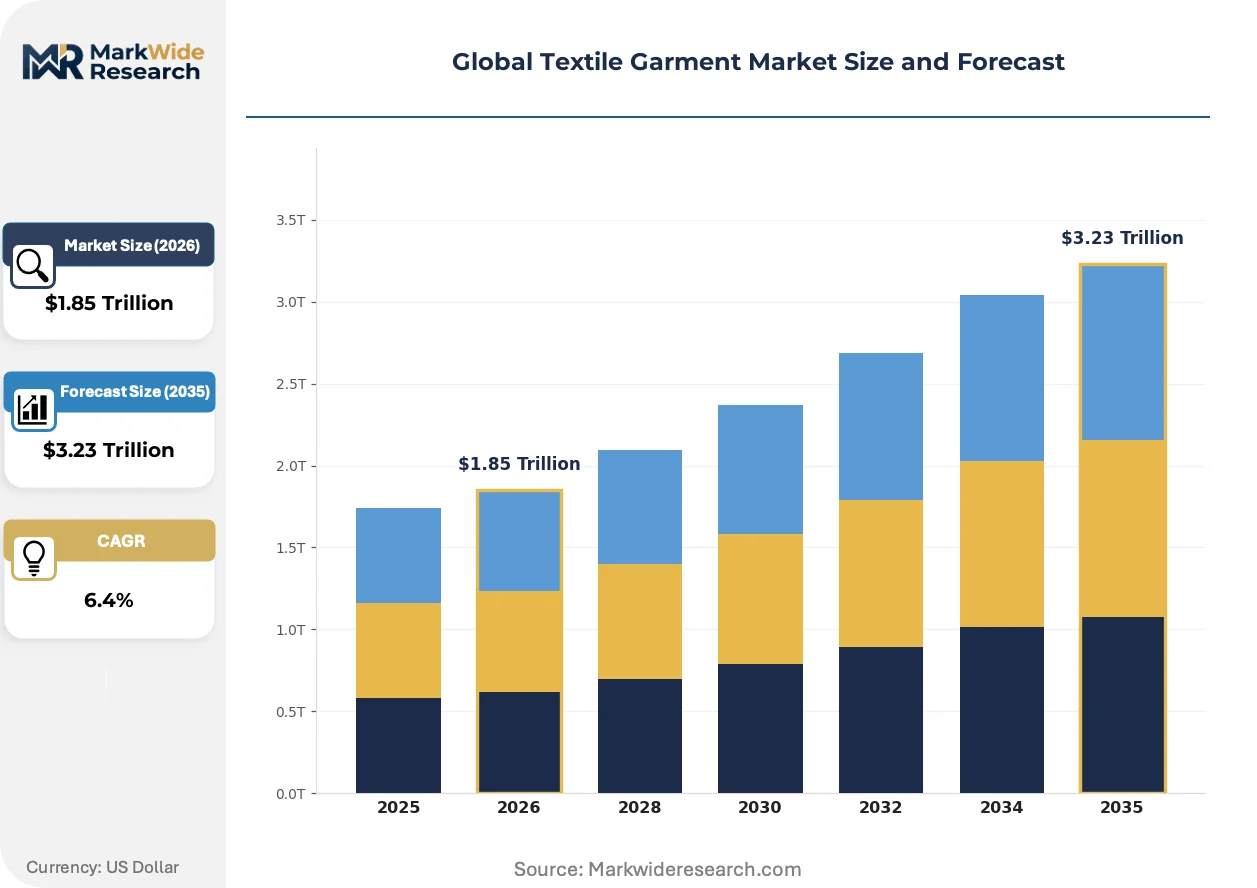
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $3.23 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Nonwoven Fabrics, Technical Textiles, Composite Materials Application: Sportswear, Casual Wear, Workwear, Outdoor Gear, Formal Attire, Protective Clothing Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale Distributors, Brand Outlets Customer Type: Fashion Designers, Clothing Manufacturers, Uniform Suppliers, Textile Exporters, Private Label Brands |
| Companies Covered | Texhong Textile Group, Milliken & Company, Inditex S.A., Arvind, Grasim Industries, Toray Industries, Aditya Birla Fashion & Retail, DuPont, Weiqiao Pioneering Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Garment Market Shifts & Advancements
Digital traceability infrastructure and fiber-to-fiber recycling technologies are restructuring how textile garments move from raw material to end-of-life recovery. Regulatory pressure on chemical inputs accelerates substitution timelines.
Blockchain-enabled supply chain documentation is absorbing verification costs previously borne by manual audit programs. Luxury and mass-market brands alike are deploying distributed ledger systems to satisfy EU Green Deal traceability mandates. This technology is absorbing compliance overhead while compressing documentation cycle times from months to days.
REACH chemical restrictions are tightening permissible substance thresholds for textile finishing agents. ECHA's SVHC candidate list expansion forces reformulation of dyes, water repellents, and anti-microbial treatments. European formalwear and technical textile producers are accelerating partnerships with chemical suppliers holding pre-registered alternatives.
Direct-to-consumer channel expansion is fragmenting traditional wholesale dependency for mid-tier apparel brands. Digital-native labels are bypassing department store concessions in favor of owned e-commerce and social commerce integration. This pattern is most visible in sportswear verticals where athleisure brands build community-driven demand before retail placement.
Global Textile Garment Market Segmentation
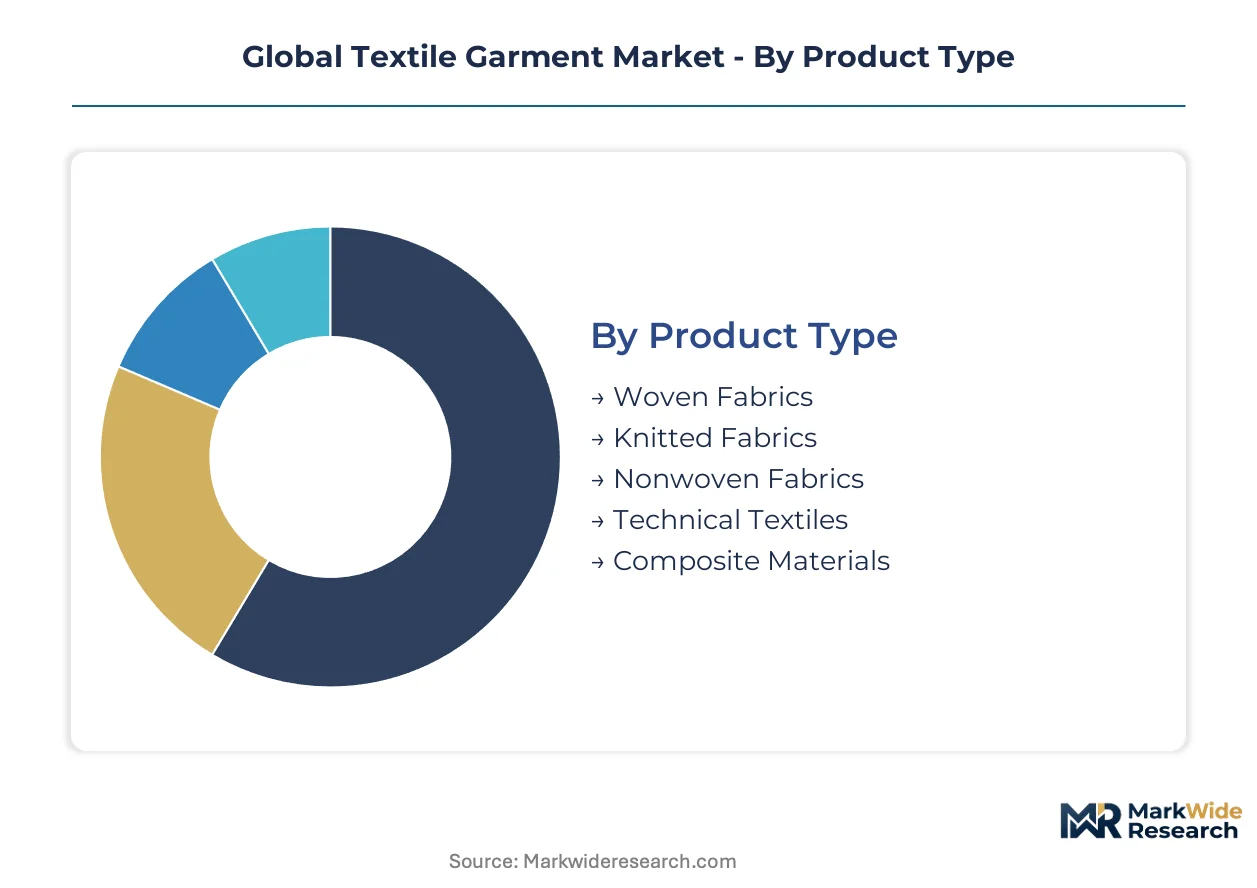
Segmentation in textile garments reflects how fiber engineering, end-use thermal requirements, and channel economics fragment production capacity across distinct value pools. Supply chain configuration varies sharply between commodity volume segments and certified specialty tiers.
Product Type:
Supply concentration tilts toward integrated spinning-weaving complexes that capture margin through captive fiber production.
- Woven Fabrics:Interlaced warp and weft construction delivers structural rigidity for 80-200 GSM formal attire and workwear specifications. Dhaka-Chittagong corridor clusters absorb the bulk of global volume for basic woven shirting and suiting.
- Knitted Fabrics:Loop-structured construction enables 150-400 GSM stretch recovery essential to sportswear and athleisure applications. Vietnam's integrated zones are expanding most quickly to serve fitness-conscious consumer demand.
- Nonwoven Fabrics:Bonded fiber webs serve disposable protective and hygiene applications through meltblown and spunlace processes.
- Technical Textiles:Engineered fiber architectures meet flame resistance and ballistic performance certifications for protective end-uses.
- Composite Materials:Multi-layer laminates combine textile substrates with polymer films for extreme-environment outdoor gear.
Woven fabrics absorb the bulk of installed capacity; knitted fabrics are expanding most quickly.
Application:
End-use margins diverge based on certification burden and replacement frequency rather than fiber input costs alone.
- Sportswear:Moisture-wicking knitted constructions with four-way stretch dominate fitness and athleisure demand. EU Green Deal traceability mandates are reshaping sourcing patterns for European market access.
- Casual Wear:Basic cotton and cotton-blend knits serve high-frequency purchase cycles through fast-fashion channels. Bangladesh's ready-made garment clusters concentrate basic casual volume.
- Workwear:Durable woven cotton duck and synthetic blends withstand industrial laundering cycles.
- Outdoor Gear:Waterproof-breathable laminates with taped seams command technical performance premiums.
- Formal Attire:Worsted wool and polyester-viscose wovens face demand compression from workplace casualization.
- Protective Clothing:Arc-rated and high-visibility certified garments require specialized fiber engineering and multi-year testing timelines.
Casual wear captures the greatest volume throughput; sportswear shows the steepest expansion trajectory.
Distribution Channel:
Channel economics fragment based on inventory risk allocation and speed-to-market requirements.
- Online Retail:Direct-to-consumer platforms absorb markdown risk while capturing first-party demand data. Digital-native sportswear labels are bypassing wholesale entirely.
- Specialty Stores:Curated assortments with trained staff support technical outdoor and performance categories requiring fit expertise.
- Department Stores:Concession models shift inventory risk to brands while diluting margin through promotional dependency.
- Wholesale Distributors:Aggregated volume purchasing serves uniform suppliers and private label brands with extended payment terms.
- Brand Outlets:Off-price channels clear excess inventory from full-line stores without damaging mainline pricing architecture.
Wholesale distributors handle the greatest volume tonnage; online retail is climbing the fastest.
Customer Type:
Buyer sophistication determines specification complexity and supplier qualification timelines.
- Fashion Designers:Small-batch sampling and rapid iteration require flexible minimum order quantities and quick-turn prototyping.
- Clothing Manufacturers:Full-package contractors source fabric, trim, and labor across integrated supply chains for brand clients.
- Uniform Suppliers:Contract-driven procurement with multi-year specifications prioritizes consistency over seasonal novelty.
- Textile Exporters:Bangladesh and Vietnam-based traders consolidate finished garments for destination market distribution.
- Private Label Brands:Retailer-owned labels leverage existing store footprints with cost-optimized specifications.
Clothing manufacturers represent the dominant demand aggregation point; private label brands are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Dinh Vu-Cat Hai Economic Zone is absorbing relocated spindle capacity as manufacturers seek tariff-advantaged production bases outside China. Integrated textile parks in Hai Phong and Quang Ninh provinces now host spinning-weaving-dyeing clusters serving export markets.
China
Domestic athleisure consumption is driving knitted fabric demand in first-tier cities while export manufacturers face dual carbon compliance pressure. GB standards and MEE emissions intensity ceilings require parallel carbon accounting systems for European-bound shipments. The Yangtze River Delta retains concentrated finishing capacity around Shaoxing and Suzhou industrial zones.
United States
Fitness-conscious consumers are expanding sportswear addressable demand through workplace casualization and social setting integration. EPA discharge permits for textile finishing operations are tightening in Southeast manufacturing corridors. North Carolina's Piedmont Triad hosts remnant integrated denim and technical fabric operations serving domestic military and workwear contracts.
Germany
EU Green Deal extended producer responsibility mandates are forcing fiber traceability system investments across mid-tier apparel brands. ECHA's SVHC candidate list expansion accelerates dye and finishing agent reformulation partnerships. Baden-Württemberg's technical textile cluster around Reutlingen specializes in automotive and protective applications requiring multi-year certification timelines.
Bangladesh
Ready-made garment export volume is concentrating in Dhaka-Chittagong corridor clusters achieving scale through specialized labor pools and consolidated finishing. The country's national export promotion authority is negotiating preferential market access terms with European buyers. Ashulia and Gazipur industrial zones support rapid turnaround times for fast-fashion contract manufacturers.
India
Cotton-based woven fabric production serves domestic formal attire demand while technical textile investments target protective clothing certifications. BIS standards and DGFT export incentive schemes are restructuring capacity allocation toward higher-value segments. Tamil Nadu's Tiruppur knitwear cluster and Gujarat's Surat synthetic fabric belt anchor regional specialization patterns.
Global Textile Garment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated apparel retailers controlling design-to-rack velocity while pure-play fabric suppliers capture commodity volume. The market structures around three tiers: rapid-response fashion conglomerates with captive retail networks, integrated fiber-to-fabric operators with tariff-advantaged geographic positioning, and specialized technical textile engineers holding multi-year certification moats. Dominant competitive moves include capacity relocation to Vietnam and Bangladesh industrial zones, and backward integration into captive fiber production to secure margin against cotton price volatility.
Among Asia-Pacific integrated operators, Texhong Textile Group and Weiqiao Pioneering Group exemplify the scale-driven archetype with concentrated spindle capacity across Vietnam and China industrial zones. Toray Industries occupies a position within the high-performance synthetic tier, anchoring material supply for athletic and protective applications where engineered fiber architectures command premium positioning. Inditex S.A. represents the rapid-response retail model, compressing design-to-rack cycles through vertically controlled supply chains.
| Leading Market Players |
|---|
| Texhong Textile Group |
| Milliken & Company |
| Inditex S.A. |
| Arvind |
| Grasim Industries |
| Toray Industries |
| Aditya Birla Fashion & Retail |
| DuPont |
| Weiqiao Pioneering Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between flame-resistant technical textiles and basic cotton knits manifests in both margin structures and supply chain topology. Premium protective garments command sustained pricing power through multi-year testing timelines and specialized fiber engineering, while commodity casual wear segments face compression from Bangladesh's volume concentration and spot-market cotton volatility.
Pricing Analysis
Short lead-time premiums separate rapid-response sportswear from scheduled bulk orders in formal attire. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, fiber engineering complexity, and brand positioning. Pricing pressure stems from Bangladesh's ready-made garment export concentration compressing basic segment margins. Fast-fashion buyers exhibit highest price sensitivity; technical textile procurement teams prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EU Green Deal traceability mandates are forcing brands to qualify secondary spindle operators beyond Vietnam and Bangladesh. Raw material flows draw from petrochemical feedstocks for synthetic fibers and cotton futures markets for natural inputs. Single-region supply concentration in Bangladesh's Dhaka-Chittagong corridor creates geographic risk exposure. Distribution runs through integrated textile parks with captive spinning-weaving-dyeing clusters serving export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized certification capacity in technical textiles functions as the binding constraint propping premium pricing. Bangladesh's basic garment assembly dominance leaves limited alternative sourcing at equivalent scale.
For Market Incumbents: Deepen backward integration into captive fiber production to insulate margin from cotton price volatility. Secure ECHA pre-registered chemical alternatives ahead of SVHC list expansion. Anchor capacity in Vietnam's Dinh Vu-Cat Hai Economic Zone to capture tariff-advantaged positioning outside China exposure. For New Entrants and Emerging Players: Enter via EU AI Act compliance automation for machine vision defect detection systems serving mid-tier apparel brands. Target technical textile protective applications where flame resistance certification creates multi-year barriers. Build direct-to-consumer sportswear channels before wholesale placement to capture first-party demand data. For Investors and Strategic Acquirers: Re-rating potential sits with integrated Vietnam-based spindle operators given preferential trade access and tariff sheltering. Long-term viability centers on five-to-ten year capacity relocation cycles toward regulatory-advantaged production bases. Watch Bangladesh infrastructure investment signals as inflection indicator for volume concentration sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fiber Production | Secures margin insulation against cotton futures volatility and petrochemical feedstock swings. |
| EU AI Act Compliance Automation | Machine vision systems for traceability documentation capture audit-ready positioning ahead of enforcement. |
| Vietnam Spindle Capacity Expansion | Dinh Vu-Cat Hai Economic Zone offers tariff-advantaged production outside China exposure. |
| Technical Textile Certification Investment | Flame resistance and ballistic performance standards create multi-year competitive moats in protective applications. |
| Direct-to-Consumer Channel Launch | Digital-native sportswear brands bypass wholesale dependency to capture first-party demand data. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across this analysis. Primary interviews with textile mill procurement directors, brand supply chain managers, and chemical supplier technical leads validated demand assumptions. ECHA SVHC candidate lists, Bangladesh Export Promotion Bureau statistics, and Vietnam industrial zone development records supplied bottom-up triangulation against top-down market sizing.
Granularity-level modeling captured product type splits across woven, knitted, technical textile, and nonwoven fabric categories. Application dimensions spanned sportswear, casual wear, formal attire, workwear, outdoor gear, and protective clothing end-uses. Distribution channel and customer type segments were projected across the analysis window. CAGRs derived from volume-weighted capacity expansion rates in Vietnam and Bangladesh against EU Green Deal compliance cost absorption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration or cotton supply disruption scenarios. Deviation in EU carbon border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Maternity Wear Market