
 Bridal Gowns Market | 2026-2036
Bridal Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Bridal Gowns Market Analysis
Fragmentation across direct-to-consumer digital boutiques is repositioning how brides discover and purchase gowns, bypassing traditional salon intermediaries. Pronovias leverages its European atelier network to sustain heritage craftsmanship credentials. Maggie Sottero anchors its competitive stance through accessible luxury positioning across North American bridal chains. David's Bridal controls inventory velocity via vertical showroom-to-warehouse fulfillment systems that compress lead times.
Bridal gowns are formal ceremonial garments engineered with structured bodices, layered skirts, and specified fabric weights measured in grams per square meter, designed to achieve silhouette retention and photographic performance under varied lighting conditions. Ball gown and A-Line product types dominate volume as classic silhouettes retain cross-cultural ceremonial relevance across Western and Asian nuptial traditions. Lace and tulle fabric categories command premium positioning where hand-finished appliqué work differentiates artisanal offerings from machine-produced alternatives.
REACH in Europe and flammability standards enforced by the Consumer Product Safety Commission in the United States govern textile chemical content and fire-safety labeling, compelling manufacturers to maintain dual certification portfolios for transatlantic distribution. ISO 9001 quality management frameworks increasingly appear in supplier qualification criteria for large bridal retail chains. Stakeholders must monitor how sustainability disclosure mandates in the European Union reshape sourcing transparency expectations across tier-two textile suppliers.
Market Dynamics
Destination wedding planners are expanding procurement volumes as bridal fashion shifts toward experiential retail, while REACH compliance in Europe and evolving flammability standards in the United States tighten material certification requirements for imported gowns.
Growth Catalysts
- REACH chemical compliance:European ateliers investing in certified dye houses capture premium positioning as import barriers rise for non-compliant Asian suppliers.
- Experiential retail formats:Showroom concepts integrating AR fitting rooms drive conversion rates among millennial and Gen-Z bridal cohorts in urban China.
- Tulle and lace innovation:Bio-based synthetic alternatives to petroleum-derived netting attract sustainability-focused buyers in Nordic markets.
Market Restraints
- Silk price volatility:Mulberry silk from Zhejiang and Jiangsu provinces faces climate-driven supply interruptions that compress margin structures for mid-tier gown producers.
- Concentrated embroidery labor:Suzhou and Guangdong workshops control 70% of global hand-beading capacity, creating bottleneck risk during peak wedding seasons.
- Flammability testing friction:CPSC 16 CFR Part 1610 compliance timelines extend lead times by 4-6 weeks for gowns with layered synthetic constructions.
Strategic Opportunities
- Rental and recommerce models:Circular economy frameworks in France and the Netherlands create regulatory tailwinds for subscription-based bridal services.
- Domestic atelier scaling in China:Shanghai and Shenzhen designers expand export capacity to Southeast Asian markets previously served by European heritage houses.
- AI-assisted pattern grading:Machine learning convergence with 3D body scanning reduces alteration costs and enables mass-customization at near-standard price points.
Industry Challenges
- Master patternmaker scarcity:Traditional corsetry and draping skills concentrate among aging artisans in Spain and Italy with limited apprenticeship pipeline replacement.
- Dual certification complexity:ISO 9001 quality frameworks plus REACH documentation requirements strain administrative bandwidth at small-to-mid-sized textile suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridal Gowns Market |
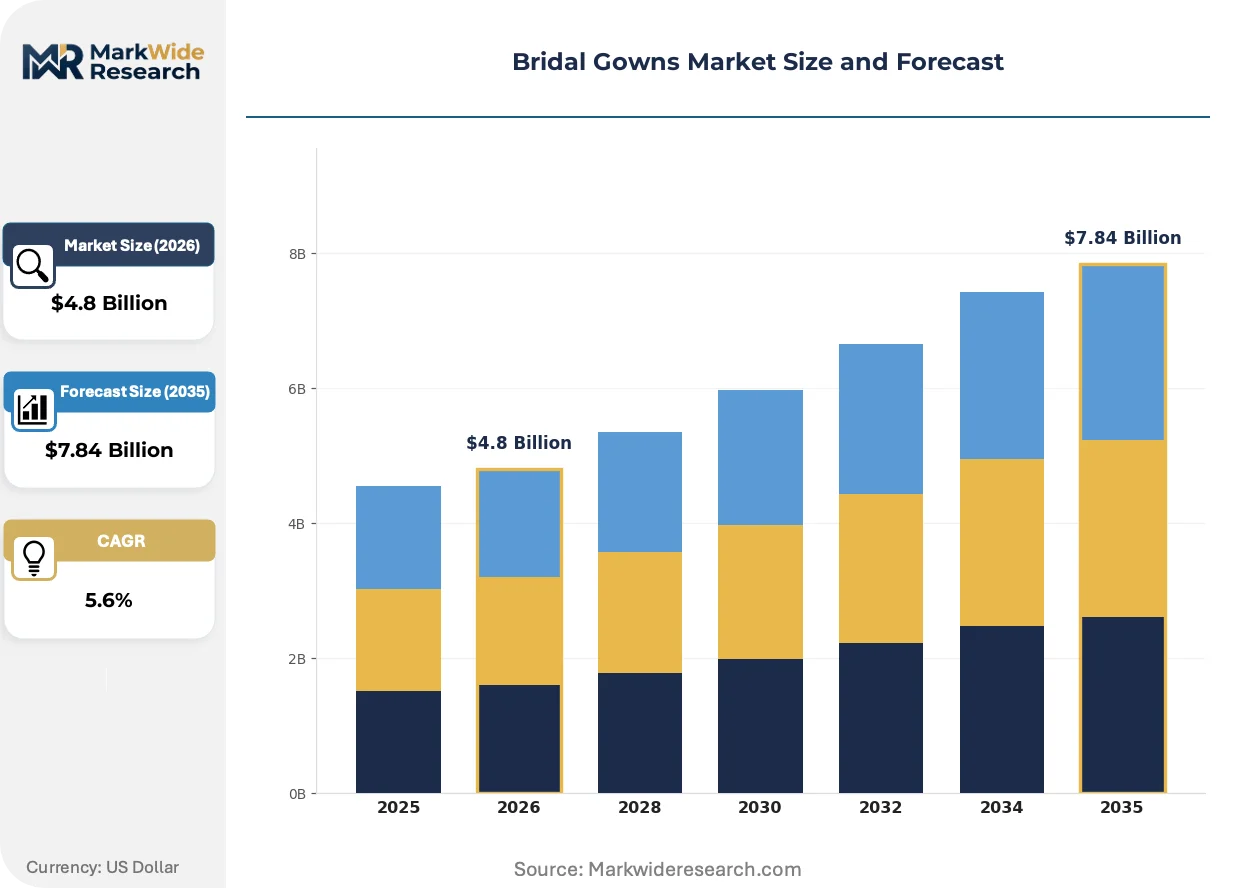
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: A-Line, Ball Gown, Mermaid, Sheath Fabric Type: Satin, Lace, Tulle, Chiffon Style: Classic, Modern, Vintage, Bohemian Length: Short, Knee-Length, Floor-Length, Tea-Length |
| Companies Covered | Pronovias, Vera Wang, Maggie Sottero, David's Bridal, Monique Lhuillier, Watters, Jenny Packham, Justin Alexander, Galia Lahav, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridal Gowns Market Emerging Trajectories
Digital discovery channels are fragmenting how brides research and commit to purchases, while regulatory pressure on chemical content and fire safety is modularizing supply chain configurations across hemispheres.
3D-printed resin boning and thermoplastic structural components are modularizing internal gown architecture. Independent designers in Berlin and Melbourne adopt these materials to reduce shipping weight and enable flat-pack fulfillment. The technology is modularizing how bodice support systems integrate with skirt volumes, compressing traditional twelve-week construction cycles.
REACH SVHC candidate list expansions now cover specific azo dyes and formaldehyde-releasing agents common in lace finishing. European bridal retailers are forcing upstream disclosure through supplier qualification questionnaires. Gown categories with heavy appliqué work face the steepest compliance cost increases, pushing some Italian ateliers to reshore embroidery from Turkish subcontractors.
Bridal party coordination platforms now aggregate group purchasing for destination ceremonies, consolidating what were individual salon appointments into single-event procurement. This pattern compresses the traditional 8-12 month discovery-to-purchase window. The shift is most visible in Mexico and Caribbean resort markets where planners negotiate volume discounts directly with gown houses, bypassing retail markup layers.
Bridal Gowns Market Segmentation
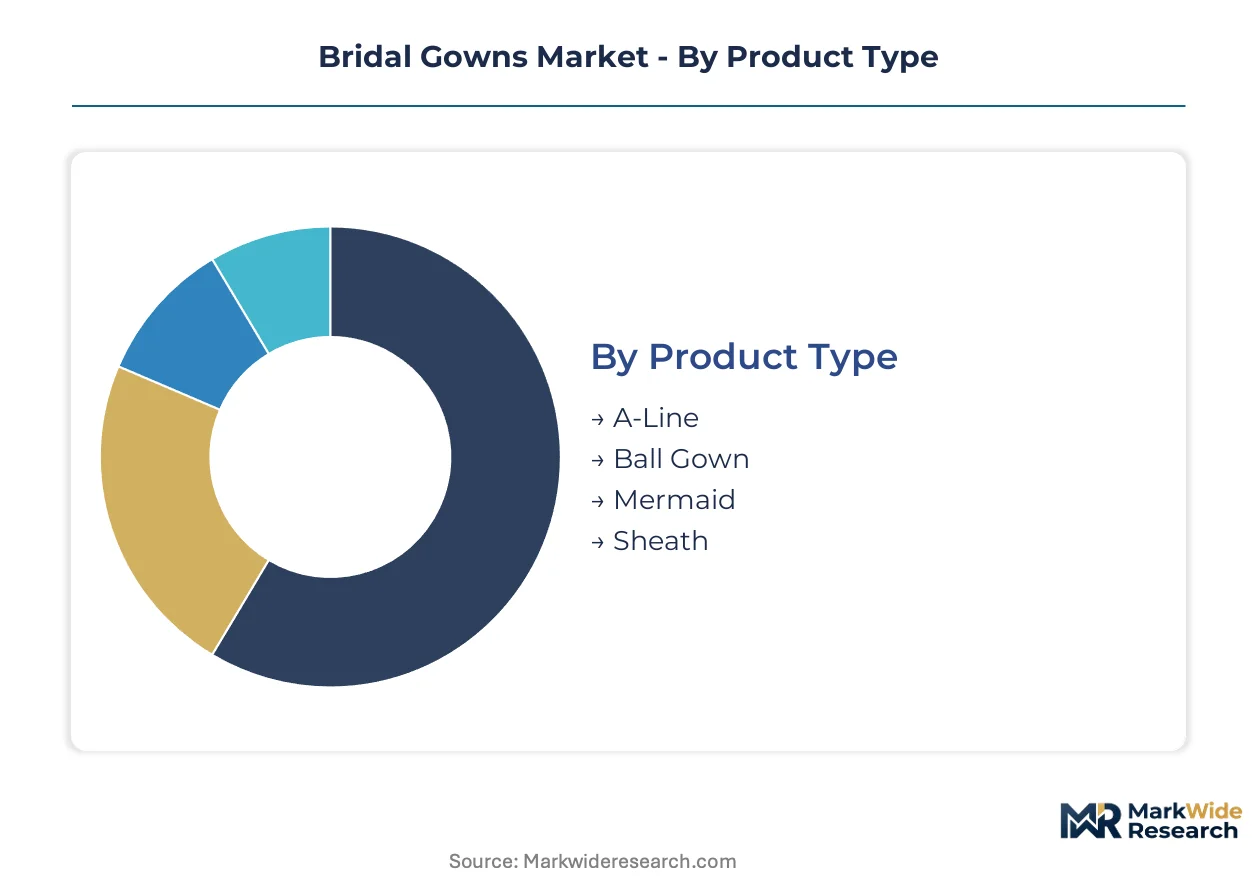
Bridal gown segmentation reveals how supply-side capabilities shape competitive positioning across silhouette engineering, textile sourcing, and ceremonial tradition. Manufacturers configure production lines around specific construction techniques that resist easy substitution between categories.
Product Type:
Supply concentration clusters around ateliers with specialized pattern-making infrastructure for structured bodices versus draped constructions.
- Ball Gown:Engineered with integrated crinoline support systems and multi-layer skirt architectures requiring 12-16 meters of fabric. Suzhou workshops dominate hand-beaded bodice production for this silhouette, though Italian ateliers retain heritage pricing power in European bridal chains.
- A-Line:Relies on princess seams and graduated skirt panels that streamline pattern grading for mass customization. Shanghai designers scale A-Line output for Southeast Asian export markets where venue logistics favor lighter construction.
- Mermaid:Demands precision-fit hip engineering and strategic boning placement that concentrates skilled labor in Barcelona and New York specialty houses.
- Sheath:Favors bias-cut silk and minimal internal structure, sourcing fabric from Zhejiang mills with direct designer relationships.
Ball Gown absorbs the bulk of installed capacity; Sheath is expanding most quickly.
Fabric Type:
Cost tier stratification separates petroleum-derived synthetics from protein-fiber naturals with divergent certification burdens.
- Lace:Hand-finished appliqué work in Calais and Solstiss ateliers commands premium positioning against machine-produced alternatives from Guangdong. REACH SVHC compliance costs disproportionately impact lace-heavy gowns with formaldehyde-releasing finishing agents.
- Tulle:Bio-based synthetic alternatives from Nordic suppliers attract sustainability-focused buyers, while petroleum-derived netting faces margin compression from oil price volatility.
- Satin:Duchesse and charmeuse weaves from Como silk mills anchor luxury positioning, with mid-tier producers substituting polyester mikado from Korean textile houses.
- Chiffon:Lightweight silk and polyester georgette constructions dominate destination wedding demand for packability and wrinkle recovery.
Lace commands the highest margin tier; Tulle is climbing the fastest on sustainability tailwinds.
Style:
Customer type fragmentation between tradition-bound and experience-seeking bridal cohorts reshapes inventory depth requirements.
- Classic:Corseted bodices and full skirts with generational continuity appeal, concentrating archival pattern libraries in London and Madrid heritage houses.
- Modern:Clean lines and architectural minimalism favor pattern-making automation, with Berlin and Melbourne independents adopting 3D-printed structural components.
- Vintage:Period-accurate construction techniques concentrate among aging artisans in Spain and Italy with limited apprenticeship pipeline replacement.
- Bohemian:Unstructured silhouettes and natural fiber preferences align with recommerce platform growth in France and the Netherlands.
Classic retains the deepest inventory investment; Modern is gaining share fastest among millennial and Gen-Z discovery channels.
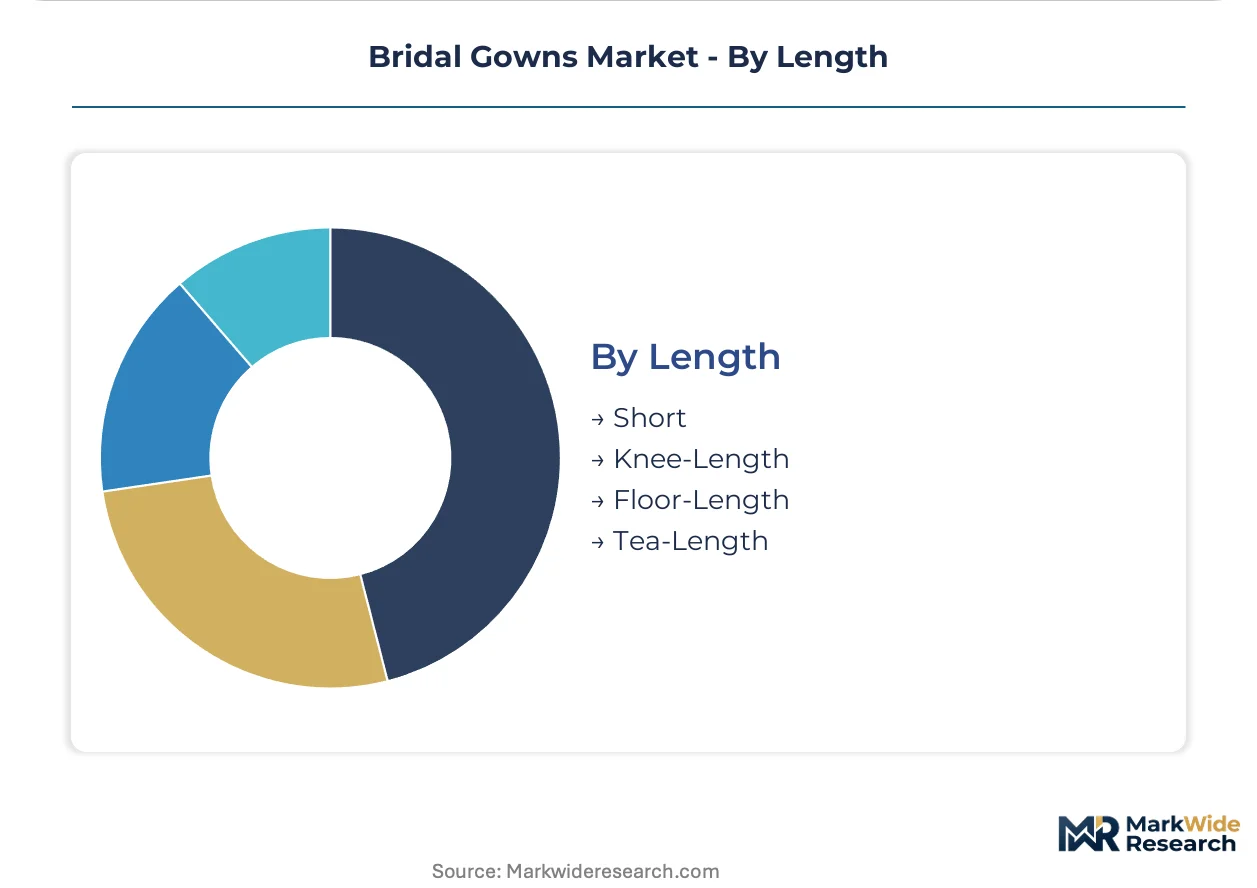
Length:
Application context—ceremony venue, reception mobility, and photographic requirements—determines length selection with distinct regional concentration.
- Floor-Length:Cathedral and ballroom venues in North American and European markets sustain demand for train-integrated constructions with bustling systems.
- Tea-Length:Mid-calf hemlines concentrate in retro-influenced urban markets and second-wear occasions, with Brooklyn and Tokyo boutiques driving niche volume.
- Knee-Length:Courthouse and elopement ceremonies favor this construction for portability, scaling through direct-to-consumer digital channels.
- Short:Above-knee designs remain specialty production for beach and destination weddings in Caribbean and Mexican resort markets.
Floor-Length carries the broadest geographic distribution; Tea-Length shows the steepest expansion trajectory in metropolitan bridal cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mulberry silk cultivation in Zhejiang and Jiangsu provinces anchors Asia-Pacific supply chains for premium gown construction, while European atelier networks concentrate heritage craftsmanship in Mediterranean clusters.
United States
Destination wedding demand in Florida and California drives volume for lightweight, packable silhouettes. The Consumer Product Safety Commission enforces 16 CFR Part 1610 flammability standards that extend lead times for layered synthetic constructions. New York specialty houses concentrate precision-fit mermaid engineering for domestic bridal chains.
China
Domestic wedding expenditure growth and export expansion to Southeast Asia propel Shanghai and Shenzhen atelier scaling. GB standards on textile safety and the Ministry of Ecology and Environment's dual carbon goals reshape dye house certification requirements. Suzhou workshops control hand-beading capacity for global ball gown bodice production.
Italy
Heritage positioning in European bridal chains sustains Como silk mill demand for duchesse and charmeuse weaves. REACH SVHC expansions covering azo dyes and formaldehyde-releasing agents force reshoring of embroidery from Turkish subcontractors. Milan and Rome archival houses retain corseted bodice pattern libraries for classic silhouettes.
France
Circular economy frameworks in the Netherlands and domestic regulatory tailwinds accelerate rental and recommerce platform adoption. ECHA disclosure mandates reshape supplier qualification questionnaires for lace-heavy gowns with chemical finishing agents. Calais and Solstiss ateliers command premium positioning for hand-finished appliqué work against Guangdong machine alternatives.
Spain
Barcelona specialty houses anchor precision-fit hip engineering for mermaid silhouettes serving both European and Latin American export markets. Aging artisans concentrate traditional corsetry skills with limited apprenticeship pipeline replacement. Catalan ateliers leverage European atelier network credentials to sustain heritage pricing power against Asian volume competitors.
Bridal Gowns Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue experiential retail and circular economy services. The vendor base stratifies across heritage European ateliers, accessible luxury chains, and direct-to-consumer digital boutiques. Three archetypes dominate: vertically integrated showroom-to-warehouse operators, certified sustainable material specialists, and AI-assisted mass-customization platforms. Competitive moves concentrate on strategic partnerships with destination wedding planners and portfolio diversification into rental and recommerce models.
Within the heritage atelier tier, Pronovias and Monique Lhuillier exemplify European craftsmanship positioning that commands premium pricing across bridal chains. Vera Wang occupies a position bridging couture credibility with accessible luxury distribution. Among volume-driven operators, David's Bridal represents the integrated fulfillment archetype compressing lead times through captive inventory systems. Maggie Sottero anchors the accessible luxury vector in North American markets.
| Leading Market Players |
|---|
| Pronovias |
| Vera Wang |
| Maggie Sottero |
| David's Bridal |
| Monique Lhuillier |
| Watters |
| Jenny Packham |
| Justin Alexander |
| Galia Lahav |
| Others |
Supply Flow & Price Mechanics
Mulberry silk spot prices from Zhejiang and Jiangsu provinces cascade through three distinct pricing tiers, with climate-driven supply interruptions compressing margins for mid-tier producers while heritage European ateliers maintain premium positioning through certified dye house investments.
Pricing Analysis
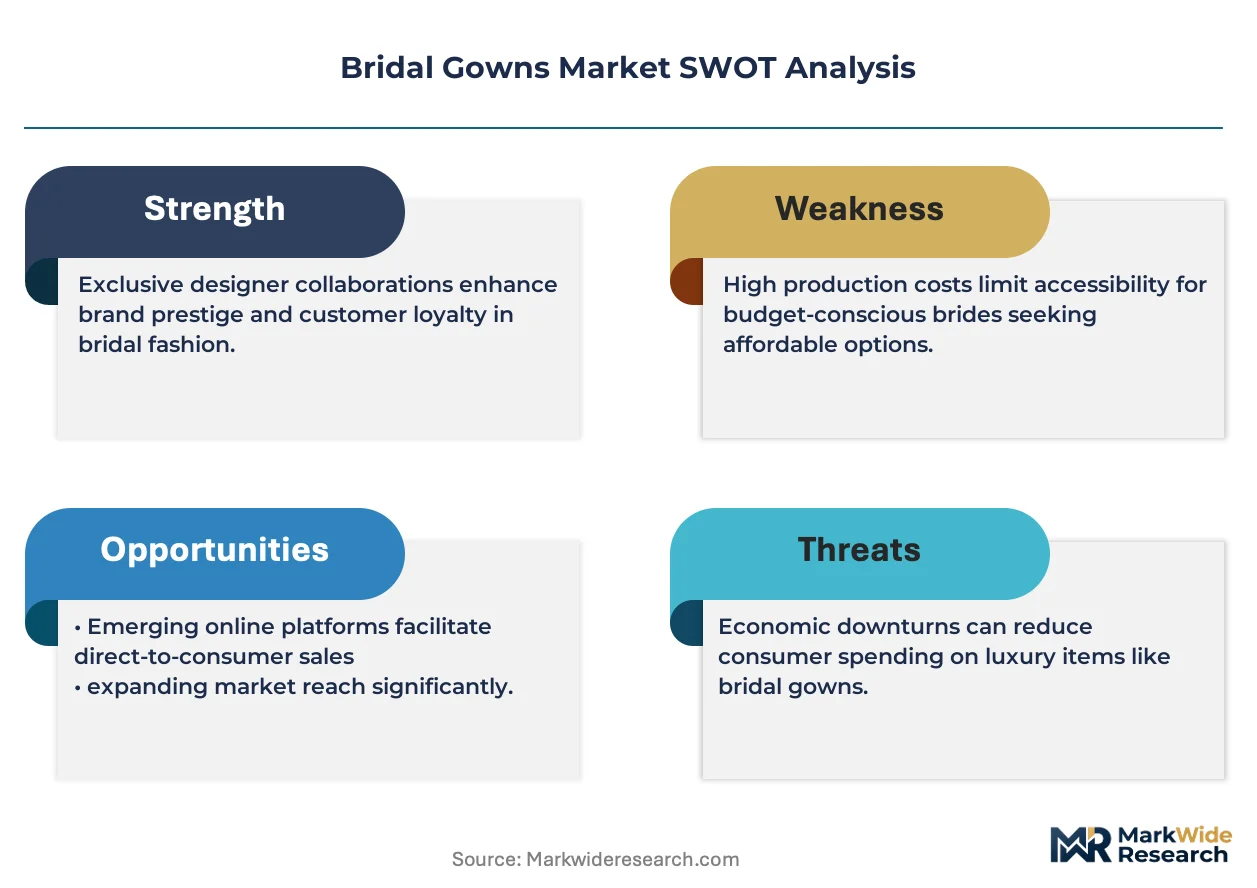
Alteration service bundling separates premium atelier offerings from unbundled digital boutique transactions, with three-tier pricing structure across heritage craftsmanship, accessible luxury, and direct-to-consumer economy levels. Price differentiation hinges on REACH certification status and hand-finished appliqué labor intensity. Pricing pressure stems from silk price volatility forcing polyester substitution in standard tiers. Courthouse and elopement brides exhibit highest price sensitivity; destination wedding planners demonstrate lowest sensitivity through volume-negotiated packages.
Supply Chain Analysis
France and Netherlands circular economy mandates are reshaping sourcing requirements for rental and recommerce platform operators. Geographic supply concentration centers on China for silk and hand-beading, Italy for duchesse weaves, and Spain for precision-fit engineering. Raw material dependencies include mulberry silk, petroleum-derived tulle, and bio-based synthetic alternatives. Single-source vulnerability concentrates in Suzhou and Guangdong embroidery workshops controlling global hand-beading capacity. Distribution runs through bridal salon intermediaries, direct-to-consumer digital channels, and destination wedding planner consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC candidate list expansions function as a cost-of-compliance moat, with European ateliers capturing premium positioning as import barriers rise for non-compliant Asian suppliers.
For Market Incumbents: Lock in certified dye house partnerships and archival pattern libraries before regulatory disclosure mandates tighten. Invest in AI-assisted pattern grading to reduce alteration costs and defend against emerging mass-customization platforms. Prioritize apprenticeship pipeline development in Barcelona and New York specialty houses to address master patternmaker scarcity. For New Entrants and Emerging Players: The mid-tier price gap between heritage European ateliers and mass-market digital boutiques offers white-space entry through rental and recommerce models in France and the Netherlands. Target Southeast Asian export markets where Shanghai and Shenzhen designers are expanding capacity. Pursue flat-pack fulfillment enabled by 3D-printed structural components to reduce shipping weight and bypass traditional salon intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified sustainable material specialists with captive European dye house infrastructure. Long-term viability centers on compliance-ready suppliers with dual REACH and ISO 9001 certification portfolios. Monitor ECHA disclosure mandate enforcement intensity as the inflection signal for upstream consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | European ateliers with certified dye houses capture premium positioning against non-compliant imports. |
| AI-Assisted Pattern Grading | Machine learning convergence with 3D body scanning enables mass-customization at near-standard price points. |
| Rental Platform Launch | Circular economy frameworks in France and Netherlands create regulatory tailwinds for subscription-based bridal services. |
| Apprenticeship Pipeline Development | Traditional corsetry skills concentrate among aging artisans in Spain and Italy with limited replacement capacity. |
| Destination Wedding Planner Partnership | Consolidated procurement for Mexico and Caribbean resort markets compresses discovery-to-purchase windows. |
Methodological Framework
Trade publications, customs records, and ECHA regulatory filings formed the secondary backbone, supplemented by primary interviews with bridal salon buyers, destination wedding planners, atelier production managers, and textile certification specialists. Bottom-up demand modeling triangulated against top-down value chain analysis ensured cross-validation across estimation approaches.
Historical trendline analysis tracked volume and value trajectories across silhouette, fabric, style, and length dimensions over the projection horizon. CAGRs derived from regression-weighted growth rates incorporated bridal cohort demographic shifts, regulatory compliance cost trajectories, and experiential retail format penetration curves as industry-specific forecast inputs.
Underlying measurement precision varies by segment; ball gown and A-line volume estimates carry tighter precision than vintage and bohemian niche categories. Forecasts reflect documented assumptions regarding silk supply stability and REACH enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Zipper Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Japan Denim Jeans Market