
 Stockings Market | 2026-2036
Stockings Market Size, Share, and Industry Trends Forecast 2026-2036
Stockings Market Outlook
Knitwear technician shortages across European manufacturing hubs is redrawing where production capacity gets built and retained. Hanesbrands leverages its North American distribution network to sustain volume leadership in mass-market channels. Wolford anchors its premium positioning through vertically controlled Austrian manufacturing and direct retail presence. Calzedonia competes on rapid style turnover and dense Southern European store networks.
Stockings are close-fitting leg coverings knitted from synthetic or natural yarns, typically constructed on circular hosiery machines with 400-needle gauge precision for sheer varieties and engineered with graduated compression ratings for medical applications. Sheer and opaque product types dominate unit volume, though thigh-high variants command stronger per-unit margins due to specialized elastic band construction and fashion positioning. Nylon and spandex material blends lead technical performance for durability and stretch recovery, while cotton segments serve thermal and skin-sensitivity niches with steadier but slower expansion trajectories.
EU REACH chemical restrictions and the EU Green Deal textile strategy shape fiber sourcing decisions and end-of-life accountability across European supply chains. The US FTC enforces labeling standards for fiber content and country-of-origin disclosure, affecting import competitiveness and consumer transparency. China's GB standards and SAMR oversight govern domestic quality certification and cross-border e-commerce compliance. Stakeholders must track how diverging sustainability mandates across Brussels, Washington, and Beijing will fragment acceptable material specifications and testing protocols.
Market Dynamics
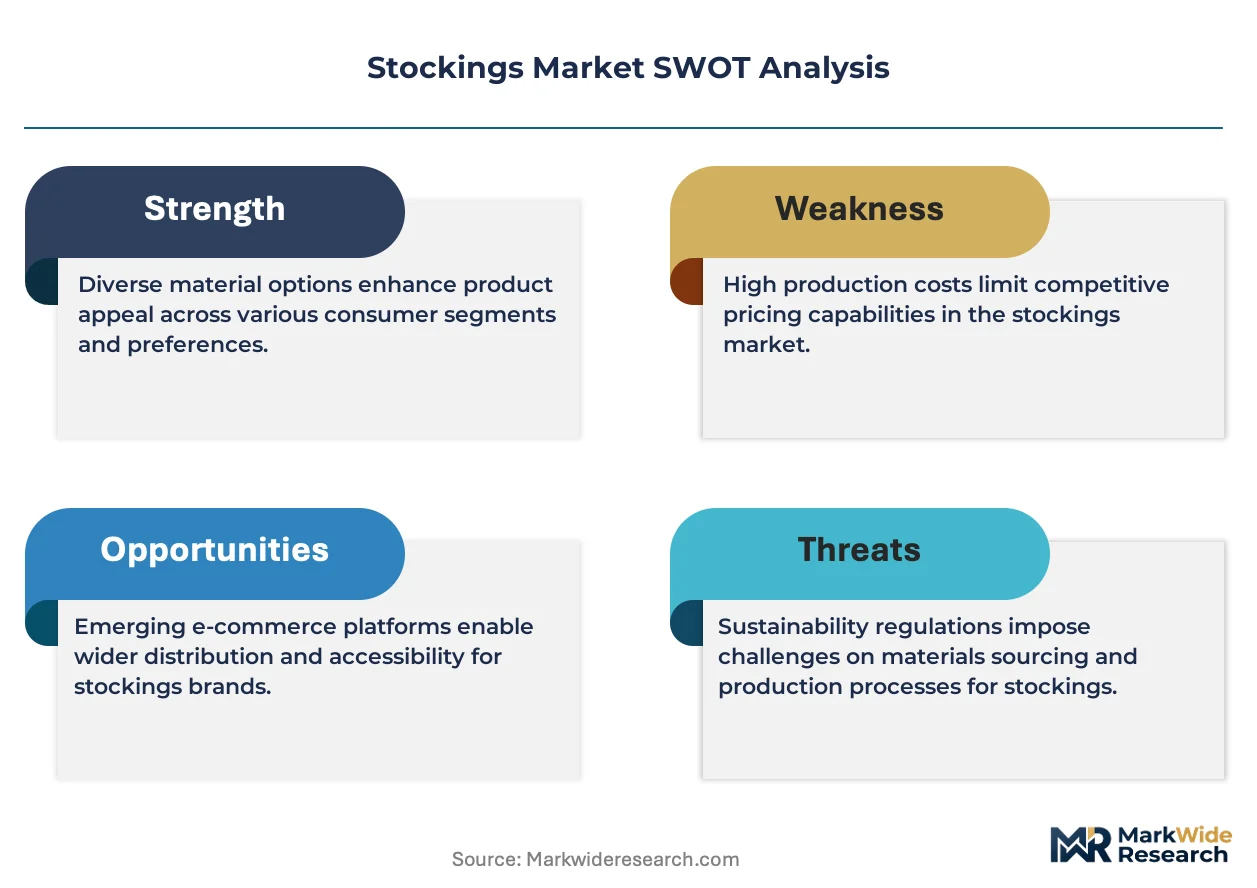
EU Green Deal textile mandates and REACH chemical restrictions are forcing fiber substitution across European supply chains while digital retail infrastructure accelerates channel migration for women's hosiery purchases.
Growth Catalysts
- EU Green Deal textile strategy:Mandates for recycled content and extended producer responsibility are pulling manufacturers toward certified nylon recycling streams and biodegradable fiber R&D.
- E-commerce channel maturation:Direct-to-consumer platforms and marketplace integrations are compressing traditional wholesale layers, enabling millennial and Gen Z purchase conversion through virtual try-on and subscription models.
- China domestic fashion brand expansion:Local premium hosiery labels are capturing share from European imports by aligning sheer and opaque collections with regional aesthetic preferences and faster style cycles.
Market Restraints
- Petrochemical input volatility:Nylon 6,6 and spandex feedstock prices track caprolactam and MDI chemical markets, exposing margin compression when energy costs spike.
- Knitwear technician scarcity:European circular hosiery machine operation requires specialized skills that vocational training pipelines have failed to replenish, constraining capacity expansion in Italy and Portugal.
- Medical-grade certification timelines:FDA and CE marking processes for graduated compression stockings extend 18-24 months, delaying product commercialization and tying up working capital.
Strategic Opportunities
- India organized retail penetration:Modern trade and quick-commerce platforms in tier-2 cities present whitespace for branded hosiery where unorganized sector currently dominates.
- Smart textile convergence:Integration of conductive yarns and microsensor knitting is enabling wellness-monitoring compression garments for diabetes and venous insufficiency management.
- EU CSRD reporting requirements:Mandatory sustainability disclosures are creating competitive differentiation for early adopters of blockchain-tracked recycled nylon and carbon-footprint labeling.
Industry Challenges
- Circular knitting machine operator deficit:The 400-600 needle gauge expertise required for sheer hosiery production lacks formal apprenticeship pathways, forcing manufacturers to poach from declining pools.
- Multi-jurisdiction compliance stacking:Simultaneous navigation of EU REACH, US FTC fiber labeling, and China GB standards fragments testing budgets and extends product development cycles.
- Legacy ERP integration with traceability systems:Batch-level fiber provenance tracking required by EU digital product passports conflicts with decades-old manufacturing execution software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stockings Market |
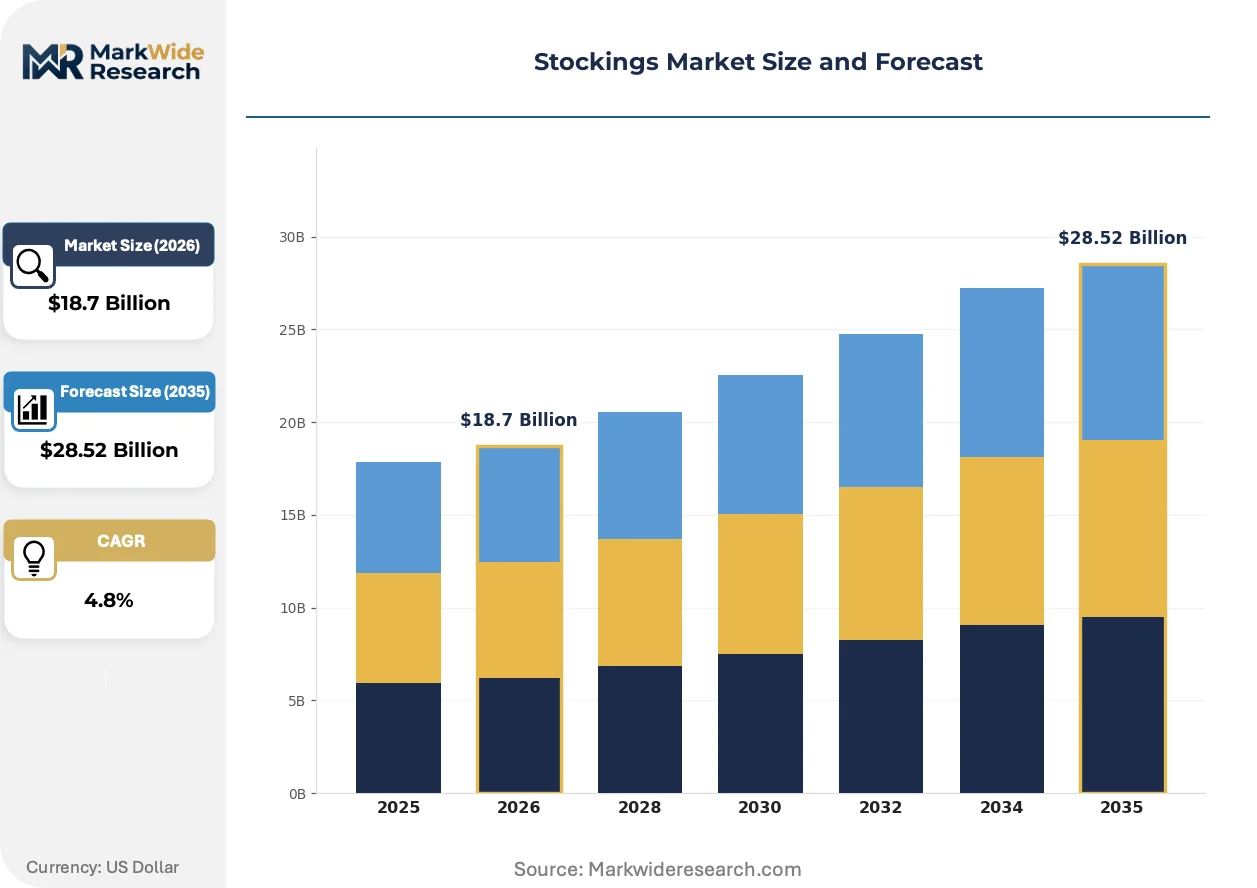
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheer, Opaque, Knee-High, Thigh-High Material: Nylon, Cotton, Spandex, Polyester Style: Silk, Lace, Fishnet, Patterned End User: Women, Men, Children, Fashion Enthusiasts |
| Companies Covered | Hanesbrands, Berkshire Hathaway, Wolford, Calzedonia, Spanx, Falke Group, Golden Lady, CSP International Fashion Group, Jockey International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stockings Market Strategic Shifts
Material science breakthroughs and regulatory disclosure mandates are compressing traditional supply chain opacity while reshaping how compression and fashion hosiery categories differentiate.
Biodegradable polyamide yarns derived from castor oil and other bio-based feedstocks are displacing conventional petroleum-derived nylon in premium sheer segments. Italian and Austrian manufacturers are piloting these materials for luxury fashion partnerships where end-of-life credentials command price premiums. The displacement is compressing reliance on traditional petrochemical supply chains while extending R&D amortization periods.
REACH restrictions on N-methyl-2-pyrrolidone (NMP) and other solvent chemicals are forcing spandex producers to reformulate polymerization processes. The industrial consequence is capital-intensive retooling of European elastane manufacturing, with capacity consolidation favoring larger chemical groups. Medical compression applications face the tightest compliance timelines given biocompatibility testing requirements.
Subscription-based hosiery replenishment models are bypassing seasonal retail buying cycles, with direct-to-consumer platforms capturing repeat purchase data for predictive inventory. This pattern is most visible in Germany and the UK, where urban professionals prioritize convenience over tactile pre-purchase evaluation. Traditional department store hosiery departments are responding with private-label exclusives and in-store fitting technology investments.
Stockings Market Segmentation
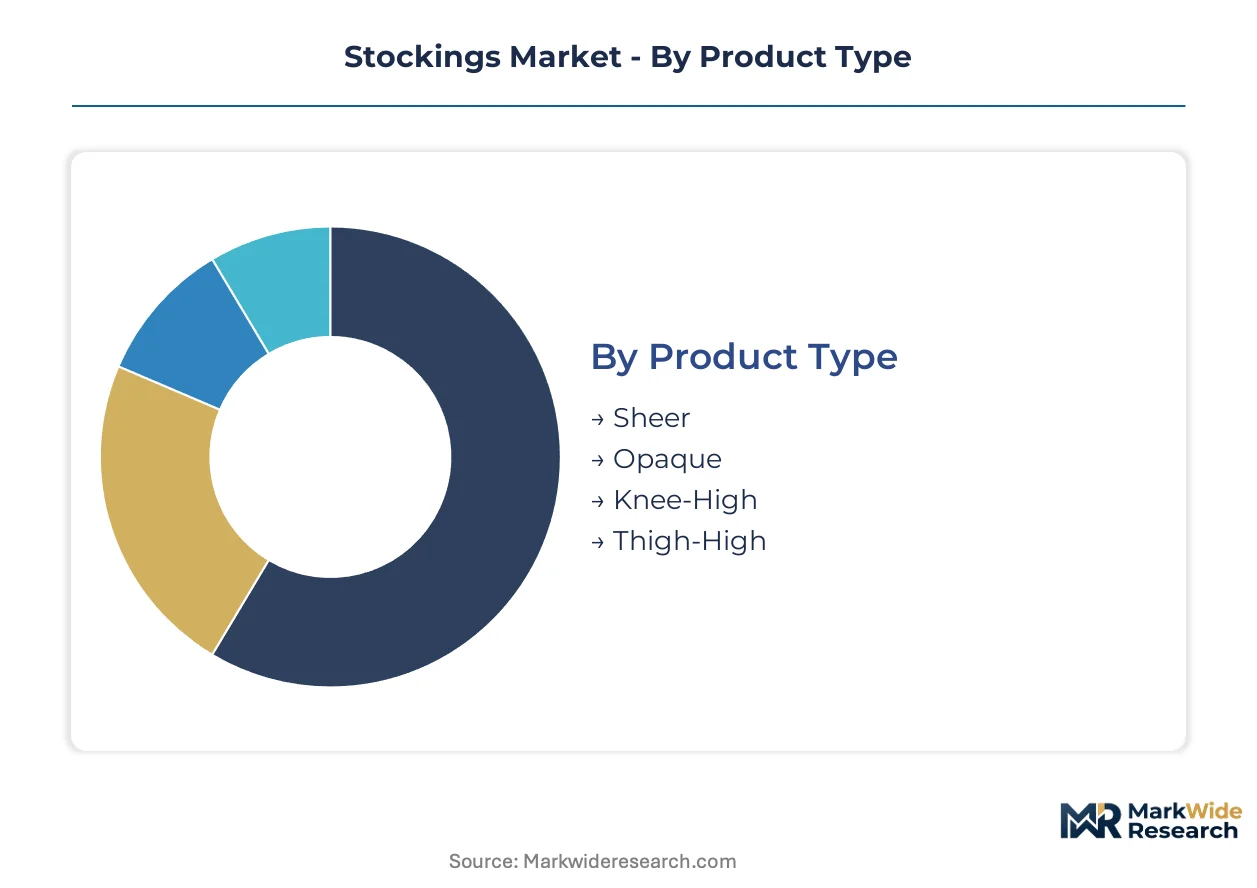
Stockings manufacturers must align production specifications with divergent regulatory thresholds across sheer medical-grade compression, fashion opacity grades, and bio-based material certifications. Segmentation discipline determines which needle gauges, fiber blends, and finishing chemistries justify dedicated line investments.
Product Type:
REACH chemical restrictions and FDA compression classification rules create divergent compliance burdens across sheer medical applications versus fashion-forward opacity variants.
- Sheer:400-needle gauge circular knitting produces 10-20 denier transparency for professional and formal wear. European demand concentrates in Germany and France where office dress codes sustain replenishment cycles; EU Green Deal mandates are accelerating recycled nylon feedstock adoption in premium sheer lines.
- Opaque:70-200 denier construction delivers thermal insulation and uniform coverage for colder climates. Demand clusters in Nordic countries and Northeast US urban corridors; opacity grades face less stringent biocompatibility testing than medical sheer variants, compressing certification timelines.
- Knee-High:Shorter leg coverage with reinforced toe and band construction for circulation support.
- Thigh-High:Extended coverage with silicone or elastic band retention systems commanding specialized manufacturing.
Opaque handles the majority of throughput; thigh-high is expanding most quickly on share.
Material:
Petrochemical input volatility and bio-based certification premiums stratify procurement strategies across synthetic and natural fiber camps.
- Nylon:Polyamide 6 and 6,6 polymers dominate durability and stretch recovery performance. Italian and Portuguese manufacturers anchor European supply; REACH NMP solvent restrictions are forcing polymerization process retooling with 18-month validation cycles.
- Spandex:Elastane content of 5-25% enables graduated compression engineering for medical applications. FDA 510(k) pathways for compression stockings require spandex biocompatibility documentation; Chinese GB standards for domestic spandex differ from EU testing protocols, fragmenting export compliance.
- Cotton:Natural fiber serving thermal and dermatological sensitivity segments with steadier pricing.
- Polyester:Lower-cost synthetic alternative with moisture-wicking properties for athletic hosiery applications.
Nylon commands the dominant volume position; spandex is gaining share fastest on medical compression demand.
Style:
Fashion cycle velocity and luxury partnership requirements determine which decorative constructions justify specialized knitting head investments.
- Silk:Natural protein fiber with superior moisture absorption and temperature regulation. Austrian and Italian luxury manufacturers control premium silk hosiery production; silk's biodegradability aligns with EU digital product passport requirements for end-of-life traceability.
- Lace:Openwork patterns requiring specialized raschel or tricot knitting machines. Calzedonia and Wolford anchor European lace hosiery positioning; lace construction generates higher per-unit margins but requires skilled technician oversight that vocational pipelines have failed to replenish.
- Fishnet:Open diamond mesh construction with punk and retro fashion positioning.
- Patterned:Jacquard and intarsia knitting for seasonal novelty and designer collaboration lines.
Silk absorbs the majority of premium pricing power; lace is climbing the fastest on direct-to-consumer subscription attachment.
End User:
Demographic targeting determines channel strategy, with gender-specific sizing grades and age-appropriate compression ratings driving SKU proliferation.
- Women:Primary demand segment spanning fashion, professional, and medical compression applications. Millennial and Gen Z purchase conversion concentrates through German and UK direct-to-consumer platforms; virtual try-on technology reduces return rates for fit-critical sheer varieties.
- Men:Growing compression therapy and athletic performance segments with distinct sizing matrices. FDA-cleared graduated compression for venous insufficiency management drives clinical channel placement; men's fashion hosiery remains underdeveloped in North American markets relative to European adoption.
- Children:Specialized sizing for dance, formal wear, and medical compression needs.
- Fashion Enthusiasts:Trend-responsive buyers prioritizing limited-edition collaborations and sustainability credentials.
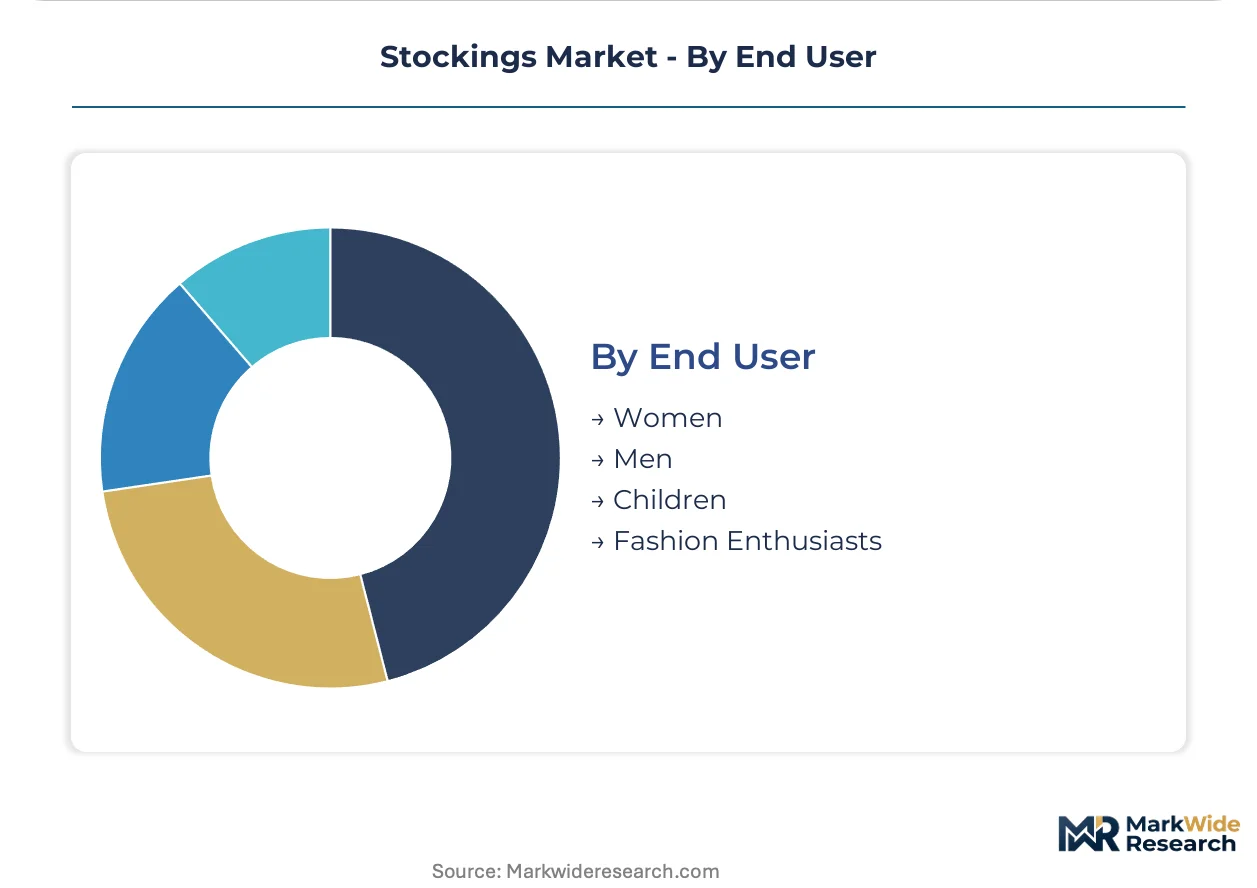
Women account for the dominant consumption base; men are expanding most rapidly on medical-grade compression penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic fashion brands now serve millennial consumers with faster style cycles than European imports, while EU Green Deal mandates pull German and Italian manufacturers toward certified recycled nylon streams.
United States
Professional office dress codes in New York and Chicago sustain replenishment cycles for sheer hosiery, though remote work patterns have compressed frequency. The FTC enforces fiber content and country-of-origin labeling standards that affect import competitiveness from Asian suppliers. North Carolina hosts Hanesbrands' distribution infrastructure serving mass-market channels.
Germany
Urban professionals in Berlin and Munich prioritize subscription-based hosiery replenishment through direct-to-consumer platforms. EU CSRD reporting requirements and REACH chemical restrictions shape procurement decisions for recycled content verification. The Rhine-Ruhr industrial corridor concentrates textile machinery expertise for circular knitting operations.
China
Domestic fashion brands in Shanghai and Guangzhou capture premium hosiery share by aligning sheer collections with regional aesthetic preferences. SAMR oversight and GB standards govern quality certification for cross-border e-commerce compliance. The Yangtze River Delta anchors manufacturing clusters serving both domestic consumption and export processing.
Italy
Luxury fashion partnerships in Milan drive demand for biodegradable polyamide yarns and bio-based feedstocks. REACH NMPA solvent restrictions force polymerization process retooling with extended validation cycles. Tuscany and Lombardy retain specialized lace hosiery production despite knitwear technician shortages constraining capacity expansion.
United Kingdom
Virtual try-on technology adoption in London reduces return rates for fit-critical sheer varieties among millennial purchasers. The UK's post-Brexit regulatory divergence from EU REACH creates parallel compliance obligations for importers. Manchester maintains historical textile expertise now pivoting toward sustainable fiber innovation.
Stockings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with mass-market volume players and premium vertical manufacturers occupying distinct competitive spaces. The structure rewards scale-driven distribution efficiency at the lower end and Austrian-Italian manufacturing heritage at the premium tier. Three archetypes predominate: North American mass-market distributors, European vertically integrated luxury producers, and Southern European fast-fashion specialists. Capacity expansion and direct-to-consumer platform development represent the dominant competitive moves reshaping channel control.
Among North American mass-market distributors, Hanesbrands exemplifies scale-driven channel dominance through captive distribution infrastructure. Within the European premium tier, Wolford and Calzedonia occupy positions anchored by vertically controlled manufacturing and dense retail presence. Falke Group represents German engineering heritage in compression and fashion hosiery segments.
| Leading Market Players |
|---|
| Hanesbrands |
| Berkshire Hathaway |
| Wolford |
| Calzedonia |
| Spanx |
| Falke Group |
| Golden Lady |
| CSP International Fashion Group |
| Jockey International |
| Others |
Value Chain & Pricing Dynamics
Certified recycled nylon feedstock substitution is redrawing procurement geography while compressing margin structures for manufacturers locked into virgin polyamide contracts. EU Green Deal mandates accelerate this displacement, forcing price realignment across premium and mass-market tiers as Italian and Portuguese mills retool for circular material streams.
Pricing Analysis
Long-term offtake agreements dominate procurement between major European manufacturers and certified recycling facilities, insulating premium tiers from spot volatility in caprolactam markets. Price differentiation rests on certification grade—OEKO-TEX and GRS verification command 15-25% premiums—and volume scale, with subscription-based direct-to-consumer platforms securing favorable unit economics. Cost compression in mass-market channels intensifies as Hanesbrands and Berkshire Hathaway leverage North American distribution density. Fashion enthusiasts and medical compression buyers exhibit lowest price sensitivity; replenishment-driven professional wear segments show highest elasticity.
Supply Chain Analysis
Knitwear technician scarcity across Italy and Portugal constrains capacity expansion for 400-600 needle gauge sheer production, creating bottlenecks that favor vertically integrated Austrian and German manufacturers. Raw material flows draw from China for spandex polymerization, Belgium for caprolactam, and Italy for circular knitting machinery. Single-source vulnerability concentrates in specialized elastane supply from European chemical groups undergoing REACH-mandated retooling. Distribution runs through direct-to-consumer platforms in Germany and the UK, with residual wholesale layers serving Southern European retail density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct-to-consumer platform consolidation, with subscription models and quick-commerce aggregators extracting terms from fragmented manufacturing bases.
For Market Incumbents: Secure backward integration into certified nylon recycling streams to defend margin position against feedstock volatility. Lock in circular knitting machine operator pipelines through apprenticeship partnerships with Tuscan and Lombard vocational institutes. Channel control through exclusive e-commerce platform development offers defensive positioning against aggregator intermediation. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for graduated compression stockings open white-space penetration into men's medical hosiery, a segment underserved by incumbent fashion-focused portfolios. Target India's tier-2 organized retail corridors where branded hosiery remains underdeveloped. A sustainability-first go-to-market angle—blockchain-tracked fiber provenance—differentiates against legacy supply opacity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive recycling infrastructure and direct retail presence. Long-term viability hinges on EU CSRD compliance readiness and digital product passport implementation capability. Watch for REACH NMP solvent restriction enforcement timelines as inflection indicators for European capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captive certified nylon supply insulates Wolford and Calzedonia from petrochemical volatility and REACH compliance costs. |
| Direct-to-Consumer Platform Launch | German and UK subscription models compress wholesale layers while capturing repeat purchase data for predictive inventory. |
| Medical-Grade Certification Investment | FDA 510(k) and CE marking pathways unlock clinical channel placement for compression therapy expansion into men's segments. |
| Sustainability Repositioning | Blockchain-tracked recycled nylon and carbon-footprint labeling differentiate early EU CSRD adopters in premium tiers. |
| Distribution Channel Expansion | India's quick-commerce platforms in tier-2 cities present whitespace for branded hosiery where unorganized sector dominates. |
Study Parameters
Operator-level perspectives from knitwear technicians, circular knitting machine operators, procurement leads at Italian and Portuguese mills, direct-to-consumer platform merchandisers, and compression therapy clinicians anchored the qualitative base. Secondary validation drew from EU ECHA REACH substance databases, FDA 510(k) clearance records, SAMR GB standards filings, and customs trade data for nylon and spandex feedstock flows. Bottom-up capacity modeling across 400-600 needle gauge production lines triangulated with top-down consumption estimates from German and UK e-commerce transaction patterns.
Sensitivity analysis tested forecast robustness across petrochemical price volatility scenarios, REACH enforcement timing variations, and technician pipeline replenishment rates. Segmentation dimensions spanned product type, material certification grade, compression rating classification, and channel structure. CAGRs derived from installed machinery capacity utilization trends and millennial purchase conversion rates through virtual try-on platforms.
Underlying assumptions cover sustained EU Green Deal implementation, stable China-Italy machinery trade flows, and gradual India organized retail penetration, with deviation risk concentrated in REACH NMP restriction timelines and knitwear technician attrition rates. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and bio-based feedstock scale-up curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Dye Sublimated Apparel Market