
 China Flame Retardant Apparel Market | 2026-2036
China Flame Retardant Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
China Flame Retardant Apparel Market Intelligence
Multi-source procurement from domestic textile mills is pivoting toward vertically integrated supply chains as end-users seek faster certification turnaround. Xinxiang Shinco Protective Garments leverages its Henan manufacturing base to control fabric finishing and garment assembly under one roof. DuPont competes through upstream control over aramid fiber supply, while Xinke Protective anchors its position in cotton-based flame retardant treatments for cost-sensitive industrial buyers.
Flame retardant apparel denotes garments engineered with inherent or treated fibers that self-extinguish when exposed to ignition sources, typically achieving limited flame spread indices under GB 5455 test protocols to protect workers in thermal hazard environments. Coveralls and jackets dominate volume shipments due to full-body protection requirements in oil and gas and chemical manufacturing settings, while Nomex and Kevlar segments command premium positioning where arc flash and molten metal risks elevate performance specifications. Cotton blends retain share in construction and general manufacturing through lower unit costs and easier laundering cycles.
China's SAMR enforces GB standards for protective clothing, while MEE regulations tie flame retardant procurement to workplace safety audits in hazardous industries, and the dual carbon goals pressure manufacturers to reduce perfluorinated chemical treatments in favor of phosphorus-based alternatives. Buyers should track how provincial environmental bureaus interpret MEE discharge rules for textile finishers, as compliance cost dispersion will reshape supplier viability ahead of the next regulatory cycle.
Market Dynamics
China's flame retardant apparel sector is compressing under the weight of MEE discharge rules for textile finishers, forcing mills to abandon perfluorinated chemistries ahead of the next compliance cycle while petrochemical buyers accelerate certified workwear procurement.
Growth Catalysts
- GB 12014 Anti-Static Mandates:State-owned oil and gas operators across drilling platforms and refineries are expanding certified workwear procurement to meet tightened fire safety codes for industrial facilities.
- Jiangsu-Shandong Cluster Density:Petrochemical manufacturing bases overlapping with textile production hubs in these provinces create localized supply-demand matching that reduces logistics friction for bulk buyers.
- Dual Carbon Policy Pressure:National emissions targets are redirecting state procurement toward phosphorus-based flame retardant treatments, opening volume contracts for compliant domestic suppliers.
Market Restraints
- Aramid Fiber Import Dependency:Domestic weavers remain captive to foreign para-aramid supply for arc-rated garments, exposing margins to currency volatility and export control risk.
- Henan-Xinjiang Supply Concentration:Fabric finishing capacity clusters in central and western provinces, creating single-point vulnerability to provincial environmental bureau enforcement actions.
- Cotton Blend Performance Ceiling:Treated natural fiber garments fail GB 5455 limited flame spread indices above specific thermal thresholds, restricting their deployment in molten metal exposure environments.
Strategic Opportunities
- Sichuan-Shaanxi Energy Corridor:Natural gas extraction expansion in these southwestern provinces lacks established protective apparel supply chains, creating first-mover territory for certified distributors.
- Phosphorus-Nitrogen Synergist Convergence:Hybrid intumescent coating systems are opening technical pathways to halogen-free compliance without sacrificing wash durability.
- SAMR Fast-Track Certification:Streamlined GB standard approval processes for recycled fiber content are enabling circular economy positioning ahead of competing import brands.
Industry Challenges
- GB 5455 Testing Bottleneck:Accredited third-party laboratories face capacity constraints, stretching certification timelines to twelve weeks and delaying seasonal contract deliveries.
- Multi-Tier Supplier Auditing Burden:Oil and gas majors now require chain-of-custody documentation through three supplier tiers, forcing mid-size garment assemblers to invest in traceability software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Flame Retardant Apparel Market |
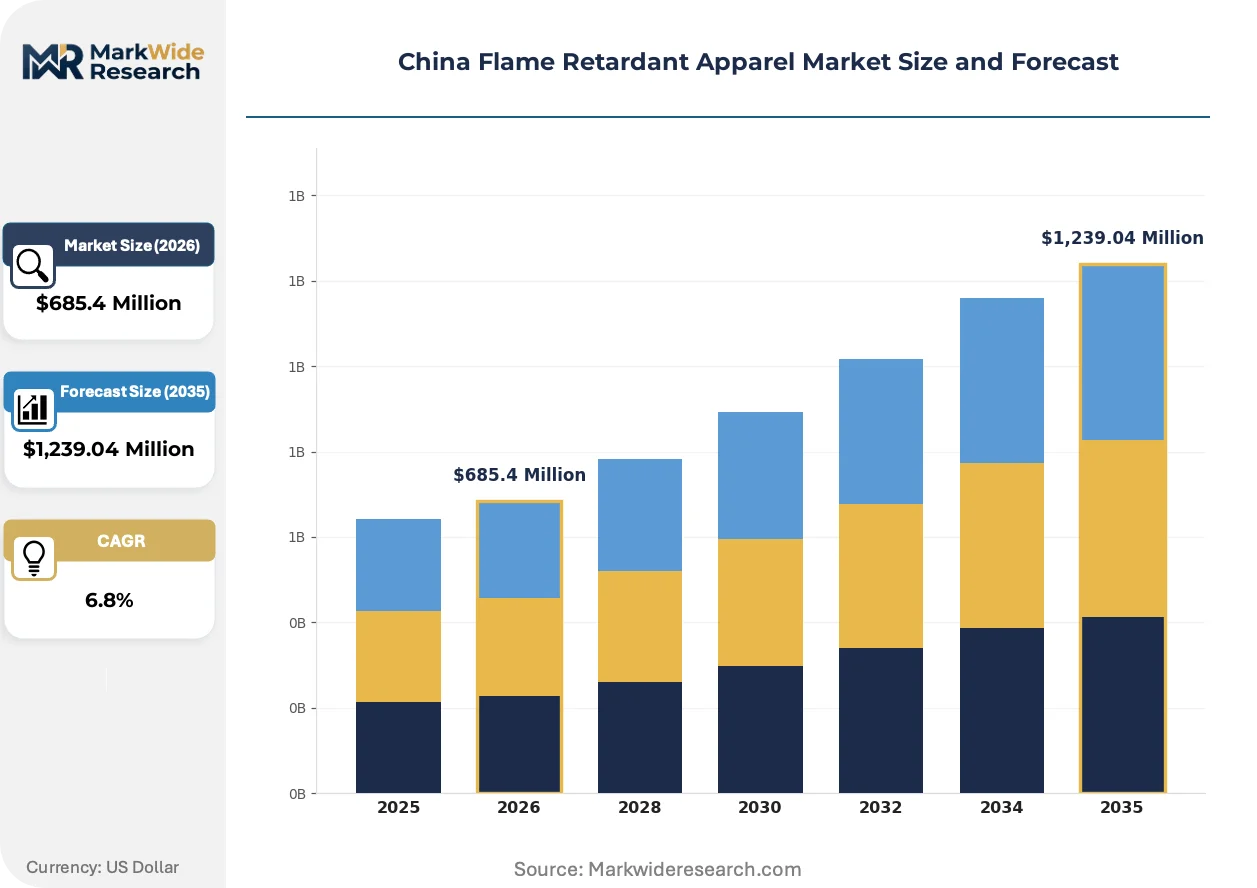
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Shirts, Trousers, Jackets Material: Cotton, Polyester, Nomex, Kevlar End User: Manufacturing, Oil & Gas, Construction, Firefighting Grade: Industrial, Commercial, Military, Others |
| Companies Covered | DuPont, 3M, Cintas Corporation, Xinxiang Shinco Protective Garments, Xinke Protective, TenCate Protective Fabrics, Ansell Limited, Kimberly-Clark Corporation, Clariant, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Flame Retardant Apparel Market Strategic Shifts & Innovations
Technical fiber engineering and procurement digitization are restructuring how protective garments move from mill to end-user, with compliance automation and material substitution commanding capital allocation.
Phosphorus-based intumescent finishing is absorbing market share from legacy halogenated treatments as MEE discharge rules tighten around perfluorinated chemical runoff. Petrochemical procurement departments in Shandong are specifying these chemistries in three-year framework agreements. The technology is absorbing price premiums previously captured by imported inherent-FR fabrics, compressing the standard-performance tier toward domestic supply.
MEE regulations now tie flame retardant procurement to mandatory workplace safety audits in hazardous industries, with provincial environmental bureaus interpreting discharge rules unevenly across textile finishers. Jiangsu-based mills face stricter effluent monitoring than Henan counterparts, creating compliance cost dispersion that reshapes supplier viability. Chemical manufacturing buyers are responding by consolidating vendor lists to those with multi-province certification coverage.
State oil and gas operators are compressing supplier qualification cycles from annual to quarterly reviews, with procurement teams prioritizing vertically integrated mills that control fabric finishing and garment assembly. This pattern concentrates contract awards in Henan and Shandong manufacturing bases where single-facility certification covers the full production chain. The shift is most visible in Sinopec and PetroChina drilling platform supply agreements, where turnaround speed now outweighs unit price in award criteria.
China Flame Retardant Apparel Market Segmentation
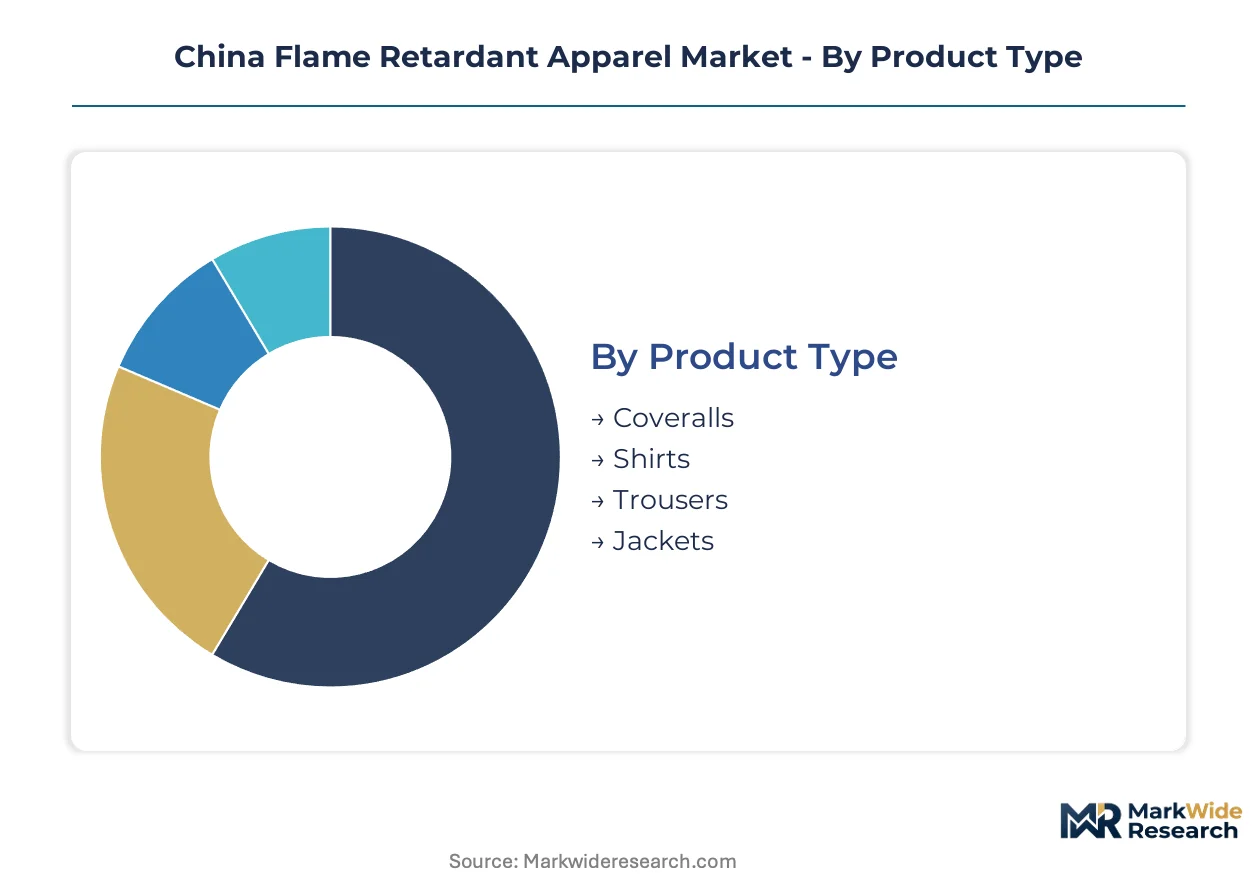
Segmentation in China's flame retardant apparel market tracks how procurement priorities diverge between state-owned energy majors and private industrial buyers. Material chemistry and certification grade determine supplier qualification tiers, while product architecture shapes replacement cycles and bulk contract structures.
Product Type:
Buyers differentiate by body coverage requirements and thermal exposure duration, with full-body garments commanding longer procurement cycles and stricter GB 5455 testing protocols than partial coverage items.
- Coveralls:One-piece designs integrating torso and leg protection dominate Sinopec and PetroChina drilling platform contracts. Jiangsu-based assemblers report these garments absorb the majority of state procurement spend due to mandatory full-body coverage in hydrocarbon processing zones.
- Jackets:Upper-body protection with detachable configurations allows layering flexibility in variable-temperature refinery environments. Shandong petrochemical clusters specify these for maintenance crews requiring mobility during intermittent thermal exposure.
- Shirts:Upper-torso garments with limited sleeve coverage serve construction and general manufacturing where thermal hazard intensity remains below molten metal thresholds.
- Trousers:Lower-body protection typically procured as companion pieces to shirts in cost-sensitive industrial settings, with shorter replacement cycles than full coveralls.
Coveralls lead volumes today; jackets are gaining share fastest as refineries prioritize modular protection systems.
Material:
Cost-performance tradeoffs separate procurement tiers, with inherent fiber garments requiring higher upfront investment but delivering extended wash durability versus treated natural fibers.
- Nomex:Meta-aramid inherent-FR fiber maintains protective properties through industrial laundering cycles without chemical replenishment. State oil and gas operators specify these for offshore platforms where garment replacement logistics prove costly.
- Cotton:Treated natural fiber with phosphorus-based finishing retains cost advantage for construction and general manufacturing buyers in Henan and Shandong provinces. Dual carbon policy pressures are redirecting state procurement away from perfluorinated treatments toward these chemistries.
- Kevlar:Para-aramid fiber delivers arc flash and cut resistance for electrical utility and molten metal exposure applications, though import dependency constrains domestic supply security.
- Polyester:Synthetic base fabrics with FR finishing occupy economy-tier positioning where thermal exposure duration remains limited and replacement frequency justifies lower unit costs.
Cotton leads volumes today; Nomex is climbing the fastest as MEE discharge rules tighten around treated-fabric effluent.
End User:
Industry-specific hazard profiles dictate certification grade requirements, with hydrocarbon processing environments demanding higher arc ratings than construction or general manufacturing settings.
- Oil & Gas:Exploration, drilling, and refining operations across Sinopec and PetroChina facilities drive premium-tier procurement with mandatory anti-static and flame spread compliance under GB 12014.
- Manufacturing:Chemical processing and metal fabrication facilities in Jiangsu and Shandong provinces require intermediate protection levels, with procurement consolidating toward vertically integrated domestic suppliers.
- Construction:Building and infrastructure projects deploy treated cotton blends where thermal hazard intensity and exposure duration remain below industrial thresholds.
- Firefighting:Emergency response services require specialized structural and proximity gear with thermal insulation layers distinct from industrial workwear specifications.
Oil & Gas leads volumes today; Manufacturing is expanding most quickly as MEE workplace safety audits broaden compliance requirements.
Grade:
Certification tier determines acceptable thermal exposure limits and laundering durability, with industrial grade absorbing volume share while military specifications concentrate in specialized defense procurement channels.
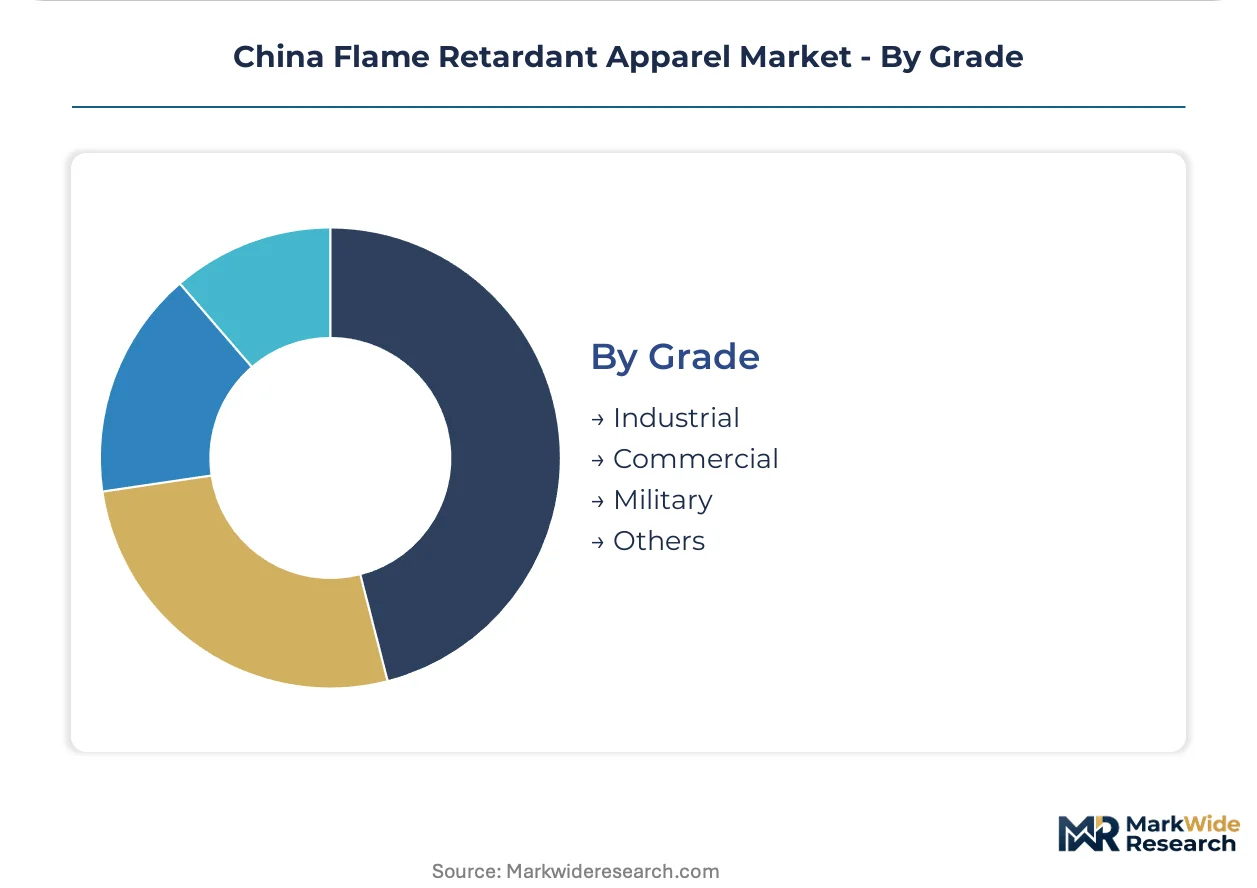
- Industrial:GB 5455 certified garments for thermal hazard environments in petrochemical, chemical, and heavy manufacturing facilities represent the core procurement category for state-owned enterprise buyers.
- Military:Defense procurement with enhanced durability and camouflage requirements operates through separate qualification channels with distinct testing protocols from civilian industrial standards.
- Commercial:Lower-tier protection for hospitality, transportation, and light industrial settings where regulatory compliance remains voluntary or minimal.
- Others:Specialized certifications for electrical utilities, welding operations, and laboratory environments with hazard-specific performance requirements outside standard industrial grades.
Industrial grade leads volumes today; Military is gaining share fastest as defense modernization programs expand technical textile procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong provinces anchor China's flame retardant apparel demand through overlapping petrochemical clusters and textile manufacturing bases. Provincial environmental bureaus under MEE jurisdiction interpret discharge rules unevenly, creating compliance cost dispersion that redirects procurement flows across manufacturing regions.
Jiangsu Province
Sinopec refining complexes in Nanjing and Nantong drive certified workwear procurement for hydrocarbon processing crews. SAMR enforcement of GB 12014 anti-static mandates tightens qualification thresholds for suppliers serving these facilities. Wuxi and Suzhou textile finishers face stricter MEE effluent monitoring than central China counterparts, compressing margins for treated-fabric specialists.
Shandong Province
Petrochemical manufacturing bases in Qingdao and Zibo generate concentrated demand for full-body protective garments under updated fire safety codes. Provincial workplace safety audits tie flame retardant procurement to MEE compliance documentation. Dongying oilfield service contractors are consolidating vendor lists toward vertically integrated mills with multi-province certification coverage.
Henan Province
Xinxiang garment assemblers leverage captive fabric finishing capacity to shorten certification turnaround for state oil and gas contracts. Dual carbon policy pressures redirect procurement toward phosphorus-based treatments away from perfluorinated chemistries. Zhengzhou logistics hubs enable rapid distribution to Sichuan-Shaanxi energy corridor developments.
Sichuan Province
Natural gas extraction expansion in the Sichuan Basin lacks established protective apparel supply chains, creating first-mover opportunities for certified distributors. MEE workplace safety audits extend compliance requirements to southwestern energy developments. Chengdu-based procurement offices are qualifying new suppliers to serve drilling platform operators.
Shaanxi Province
Yanchang Petroleum and extended natural gas pipeline networks generate emerging demand for arc-rated garments in electrical maintenance roles. GB 5455 testing capacity constraints stretch supplier qualification timelines. Xi'an industrial distributors are building inventory positions to capture infrastructure-driven replacement cycles.
China Flame Retardant Apparel Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue phosphorus-based chemistry transitions and recycled fiber certifications. Market structure concentrates around vertically integrated domestic mills and import-dependent aramid fiber suppliers. Three archetypes dominate: captive-fabric finishers controlling full production chains, treated-cotton specialists serving cost-sensitive construction buyers, and inherent-fiber importers targeting offshore platform specifications. Competitive moves center on backward integration into fabric finishing and accelerated SAMR certification timelines.
Within the domestic integrated tier, Xinxiang Shinco Protective Garments and Xinke Protective exemplify archetypes anchored in central China manufacturing bases. DuPont occupies a position representing upstream aramid fiber control for premium thermal protection applications. These three entities illustrate how supplier qualification is compressing toward entities with single-facility certification coverage spanning fabric finishing through garment assembly.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| Cintas Corporation |
| Xinxiang Shinco Protective Garments |
| Xinke Protective |
| TenCate Protective Fabrics |
| Ansell Limited |
| Kimberly-Clark Corporation |
| Clariant |
| Others |
Cost & Logistics Intelligence
Captive fabric finishing within Henan and Shandong manufacturing bases anchors both supply security and pricing power for domestic flame retardant apparel producers serving state oil and gas operators. This integration pattern compresses certification timelines and insulates margin structures from MEE discharge rule volatility that fragments treated-cotton specialists.
Pricing Analysis
Input-cost pass-through from para-aramid fiber imports and phosphorus-based chemical treatments shapes tiered pricing across the market. Three-tier pricing structure across premium, standard, and economy levels separates Nomex-based offshore platform specifications from cotton-blend construction garments and polyester economy tiers. Pricing pressure stems from currency volatility in aramid fiber sourcing and uneven MEE compliance costs across provincial environmental bureaus. Construction buyers in Henan exhibit highest price sensitivity, while Sinopec drilling platform procurement prioritizes turnaround speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with foreign para-aramid fiber supply for arc-rated garments, constraining domestic weavers serving electrical utility and molten metal exposure applications. Manufacturing concentration clusters in China, with secondary fabric finishing capacity in Vietnam and Bangladesh for basic treated-cotton exports. Raw material dependencies center on imported meta-aramid and para-aramid fibers, phosphorus-based flame retardant chemistries, and cotton feedstock from Xinjiang. Tariff exposure on specialty fiber imports presents structural risk. Distribution runs through vertically integrated mills with direct state enterprise contracts, supplemented by industrial distributors in Chengdu and Xi'an for southwestern energy corridor penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MEE workplace safety audit mandates and GB 12014 anti-static compliance cycles continuously refresh procurement volumes across petrochemical and energy infrastructure.
For Market Incumbents: Anticipate phosphorus-nitrogen synergist coating adoption by consolidating multi-province certification coverage ahead of provincial environmental bureau enforcement divergence. Defensive moves require backward integration into fabric finishing to capture Sinopec quarterly supplier review cycles, and investment in SAMR fast-track certification pathways for recycled fiber content to offset import-brand positioning. For New Entrants and Emerging Players: Enter via Sichuan-Shaanxi energy corridor distribution partnerships where natural gas extraction expansion lacks established protective apparel supply chains. White-space targets include Chengdu-based procurement office qualification for drilling platform operators and arc-rated garment inventory positioning for Yanchang Petroleum electrical maintenance roles. Go-to-market execution should leverage Zhengzhou logistics hub connectivity for rapid southwestern fulfillment. For Investors and Strategic Acquirers: Roll-up economics work for captive-fabric finishing specialists because provincial MEE discharge rule interpretation variance is fragmenting treated-cotton assemblers without multi-region compliance coverage. Long-term viability centers on five-to-ten year state energy infrastructure procurement cycles. Acquisition targets should demonstrate single-facility certification spanning fabric finishing through garment assembly. The signal to watch is SAMR streamlined approval timeline expansion for recycled fiber content, indicating circular economy positioning value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fabric Finishing | Captive phosphorus-based treatment capacity secures Sinopec quarterly contract awards against fragmented competitors. |
| SAMR Fast-Track Certification Investment | Streamlined GB standard approval for recycled fiber content enables circular economy positioning ahead of import brands. |
| Sichuan-Shaanxi Corridor Distribution Buildout | First-mover inventory positioning captures natural gas extraction procurement from Chengdu-based drilling operators. |
| Phosphorus-Nitrogen Synergist R&D Partnership | Hybrid intumescent coating development unlocks halogen-free compliance without sacrificing wash durability thresholds. |
| Multi-Province Environmental Compliance Coverage | Cross-regional MEE certification insulates vendor viability against provincial bureau enforcement divergence. |
Research Approach
Multiple input streams — primary interviews with plant managers at Jiangsu textile finishers, procurement leads at Sinopec and PetroChina facilities, distribution channel partners in Henan and Shandong, and technical R&D directors at phosphorus-based chemical suppliers — were reconciled against secondary validation from SAMR GB standard filings, MEE discharge rule documentation, customs trade data on aramid fiber imports, and provincial workplace safety audit records. Bottom-up demand modeling across end-use segments was triangulated with top-down market sizing from production capacity assessments.
Data-stream reconciliation applied analytical framework segmentation across material chemistry tiers, product architecture categories, end-use industry hazard profiles, and certification grade specifications throughout the forecast period. CAGRs were derived from volume shipment trajectories mapped against state energy infrastructure investment cycles and dual carbon policy implementation timelines. Industry-specific forecast inputs incorporated GB 5455 testing laboratory capacity constraints and provincial environmental bureau enforcement pattern probabilities.
Inputs from primary stakeholder interviews and documented regulatory filings were available through the study window; gaps in real-time provincial MEE discharge rule interpretation variance introduce uncertainty bands around supplier viability assessments. Forecasts reflect documented assumptions regarding state procurement cycle acceleration and phosphorus-based chemistry substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Denim Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
South America Lingerie Market