
 Asia-Pacific Footwear Sole Material Market | 2026-2036
Asia-Pacific Footwear Sole Material Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Footwear Sole Material Market Outlook
Aftermarket recycling and regrind material programs is tilting margin pools away from virgin compound sales toward closed-loop supply services. Yue Yuen Industrial Holdings Limited leverages its integrated manufacturing footprint across China and Vietnam to control costs from resin to finished sole. Toray Industries anchors premium positioning through high-performance carbon fiber-reinforced midsole plates for athletic applications. Kumho Petrochemical competes on synthetic rubber scale, supplying major Korean and Chinese footwear brands with consistent compound quality.
Footwear sole material encompasses the structural bottom layer of shoes, typically formulated from rubber, ethylene-vinyl acetate (EVA), thermoplastic polyurethane (TPU), or leather, with densities ranging from 0.15 g/cm³ for ultralight EVA foams to 1.2 g/cm³ for full-grain leather outsoles, manufactured through injection molding, compression molding, or direct attach processes to provide traction, cushioning, and durability. EVA dominates volume across casual and sports categories due to its superior energy return and weight reduction, while TPU captures expanding share in performance athletic segments where abrasion resistance and flex fatigue life determine product lifespan. Rubber retains structural importance in formal and industrial safety footwear where slip resistance standards mandate specific coefficient-of-friction thresholds. The men's end-user segment sustains higher absolute volume, though women's athletic and lifestyle categories show faster product refresh cycles.
China's SAMR enforces GB standards for footwear physical performance including sole adhesion and wear resistance, while India's BIS mandates ISI certification for rubber and plastic footwear components entering domestic distribution. Japan's METI oversees JIS standards that classify sole materials by specific gravity and tensile elongation for industrial safety applications. REACH-compliant formulations from South Korean and Japanese suppliers gain preferential access to export-oriented Vietnamese and Indonesian factories serving EU-bound brands. Stakeholders must monitor how EUDR deforestation traceability requirements and evolving EU Green Deal carbon border adjustments reshape material sourcing qualifications for Asia-Pacific sole compound exporters.
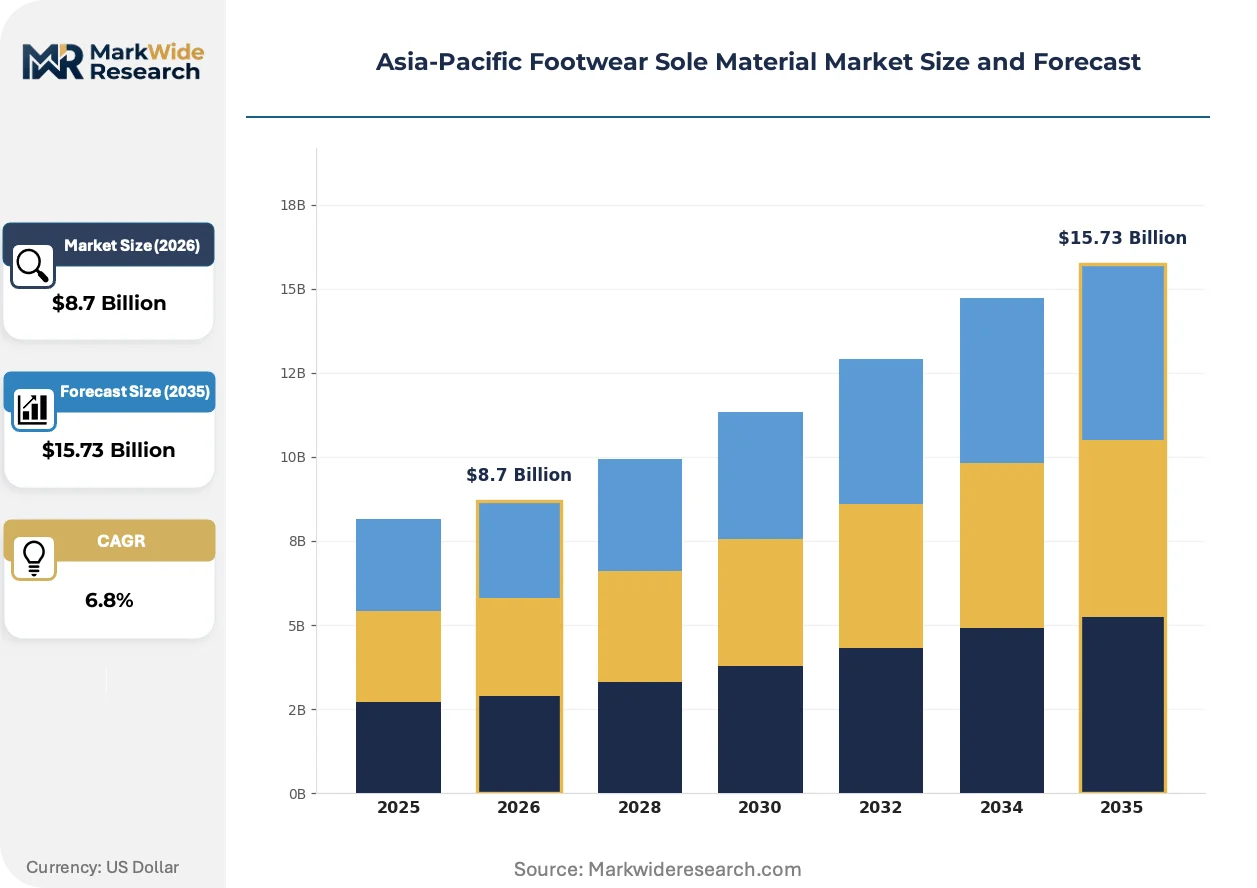
Market Dynamics
China's dual carbon goals and India's BIS quality mandates are compressing virgin compound margins while redirecting capital toward bio-based polyurethane alternatives and closed-loop recycling infrastructure across Vietnam's export zones and Indonesia's industrial corridors.
Growth Catalysts
- EVA and TPU compound demand:Athletic footwear brands in China and Vietnam are expanding orders for lightweight formulations to meet performance specifications in running and basketball categories.
- GB standards enforcement:China's SAMR mandates for sole adhesion and wear resistance are forcing quality upgrades that favor certified compound suppliers over informal producers.
- Bio-based polyurethane alternatives:Manufacturers are pivoting feedstock sourcing toward renewable polyols to align with procurement criteria from EU-bound brands operating in Ho Chi Minh City and Jakarta.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress EVA and TPU compound margins, particularly for mid-scale processors lacking long-term supply contracts.
- Vietnam supply concentration:Overreliance on export manufacturing zones around Ho Chi Minh City and Binh Duong creates geographic vulnerability to port congestion and power rationing events.
- REACH compliance costs:South Korean and Japanese suppliers face elevated formulation testing expenses to maintain access to EU-bound Vietnamese and Indonesian factories.
Strategic Opportunities
- Indonesia industrial corridor expansion:Underpenetrated sole compound demand in Java's emerging footwear clusters offers first-mover positioning for integrated resin-to-sole producers.
- Aftermarket regrind programs:Closed-loop supply services for end-of-life sole recovery are capturing margin pools previously held by virgin compound sales in China's Pearl River Delta.
- EUDR traceability alignment:Early certification against EU deforestation requirements creates preferential supplier status for Asia-Pacific exporters serving premium athletic brands.
Industry Challenges
- Polyurethane formulation expertise gap:Shortage of polymer chemists capable of tuning bio-based polyol reactivity is slowing product qualification timelines at Indonesian and Vietnamese compounders.
- Injection molding capex intensity:Direct-attach process equipment for TPU midsole integration requires capital outlays that strain balance sheets of mid-tier sole manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Footwear Sole Material Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, EVA, TPU, Leather Footwear Type: Casual, Sports, Formal, Slippers End User: Men, Women, Children, Unisex Market Channel: Online, Retail, Wholesale, Distributor |
| Companies Covered | Asics Corporation, Yue Yuen Industrial Holdings Limited, Toray Industries, Teijin Limited, LG Chem, Mitsui Chemicals, Formosa Plastics Corporation, Kumho Petrochemical, Wanhua Chemical Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Footwear Sole Material Market Strategic Shifts
Digital material selection platforms and predictive wear-modeling tools are compressing traditional compound qualification cycles while reshaping how athletic brands specify sole formulations across Asia-Pacific supply chains.
Expanded thermoplastic polyurethane foaming is virtualizing the midsole design-to-production pipeline. Brands including Chinese and Korean athletic labels are adopting supercritical CO2 foaming for density gradient control. This technology is virtualizing the role of physical mold iteration and reducing time-to-market for performance footwear launches.
India's BIS ISI certification mandate for rubber and plastic footwear components is forcing domestic compounders to upgrade testing infrastructure. The regulation eliminates uncertified suppliers from formal distribution channels. Small-scale Gujarat and Tamil Nadu processors are consolidating or exiting as compliance costs concentrate volume with certified compound manufacturers.
Brand technical teams are embedding material scientists within Vietnam and Indonesia factory operations to compress formulation feedback loops. This co-location model replaces arm's-length specification handoffs with real-time density and hardness adjustments during production ramp. Korean and Japanese athletic brands have deployed the most aggressive embedded technical teams in Ho Chi Minh City manufacturing zones.
Asia-Pacific Footwear Sole Material Market Segmentation
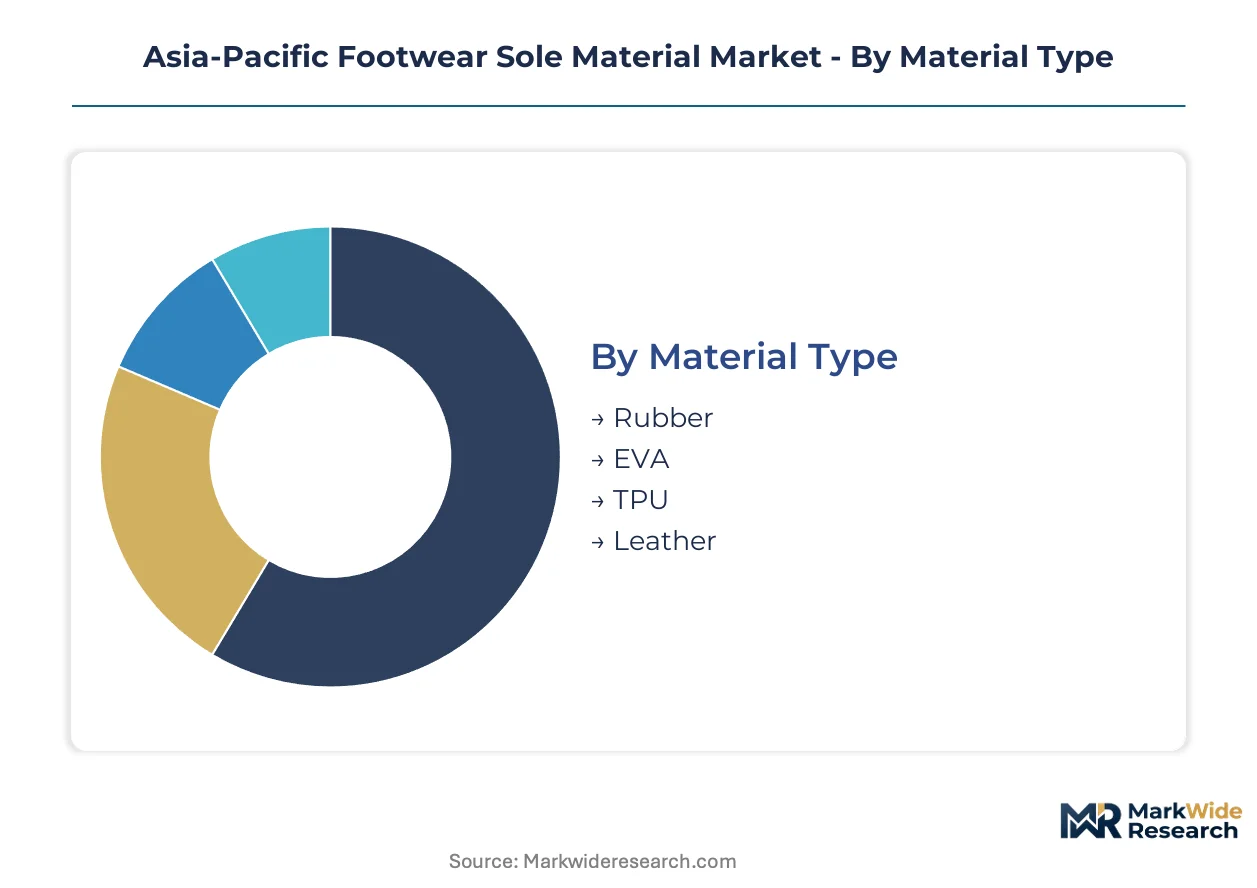
Material composition determines performance specifications and margin structures across Asia-Pacific sole manufacturing. Segmentation reveals how EVA and TPU formulations command premium positioning while rubber and leather serve distinct durability and aesthetic requirements in regional supply chains.
Material Type:
Mature rubber formulations coexist with emerging bio-based alternatives across the maturity spectrum, creating tiered supplier positioning from commodity compounders to specialty polymer developers.
- EVA:Ethylene-vinyl acetate foam compounds deliver densities from 0.15 g/cm³ for ultralight running midsoles, with Chinese and Vietnamese athletic brands expanding orders for energy-return formulations in basketball and marathon categories. SAMR GB standards for wear resistance are compressing informal supplier participation.
- TPU:Thermoplastic polyurethane offers superior abrasion resistance and flex fatigue life for performance athletic segments. Supercritical CO2 foaming adoption by Korean and Chinese brands is virtualizing mold iteration cycles in Ho Chi Minh City production zones.
- Rubber:Natural and synthetic rubber compounds retain structural importance in industrial safety footwear where JIS coefficient-of-friction thresholds mandate specific formulations. Kumho Petrochemical supplies consistent compound quality to major Korean and Chinese brands.
- Leather:Full-grain and bonded leather outsoles serve formal footwear categories with densities reaching 1.2 g/cm³, concentrated in Indian and Italian-influenced manufacturing clusters serving premium export markets.
EVA handles the majority of throughput across casual and sports categories; TPU is the fastest mover on share as performance athletic specifications tighten.
Footwear Type:
Application-driven segmentation separates high-refresh athletic cycles from durable formal footwear procurement patterns, with channel economics diverging sharply between direct-to-consumer sports launches and wholesale formal distribution.
- Sports:Running, basketball, and training categories demand lightweight EVA and TPU compounds with calibrated density gradients. Embedded material scientists from Korean and Japanese brands compress formulation feedback loops in Vietnam's manufacturing zones.
- Casual:Lifestyle sneakers and everyday footwear balance cost efficiency with aesthetic flexibility, sourcing standardized EVA formulations from Indonesia's emerging Java clusters and China's Pearl River Delta processors.
- Formal:Leather and rubber outsoles dominate where durability and slip resistance standards apply. India's BIS ISI certification mandates are consolidating volume with certified compound manufacturers as small-scale Gujarat processors exit.
- Slippers:Injection-molded EVA and compressed rubber serve high-volume, low-margin domestic markets across India and Southeast Asia with minimal performance specification overhead.
Sports footwear commands the steepest expansion trajectory as athletic brand technical requirements intensify; formal categories maintain stable procurement volumes through established wholesale channels.
End User:
Customer-type segmentation aligns product refresh velocity with gendered purchasing patterns, where women's athletic categories show faster design turnover despite men's higher absolute volume throughput.
- Men:Higher absolute volume concentration in work safety, formal, and athletic categories. Industrial safety mandates from Japan's METI and China's SAMR drive specification compliance for rubber and TPU compounds.
- Women:Faster product refresh cycles in lifestyle and performance athletic segments. Korean and Chinese brands prioritize colorway and density variation for women's lines in Vietnam export zones.
- Children:Growth-calibrated sizing and safety-focused material selection dominate, with BIS quality mandates in India affecting domestic distribution requirements for rubber and plastic components.
- Unisex:Standardized sizing and neutral aesthetics reduce SKU complexity, favored by direct-to-consumer online channels and wholesale distributors seeking inventory efficiency.
Men's segments absorb the largest compound tonnage; women's athletic and lifestyle categories are expanding most quickly on design refresh frequency.
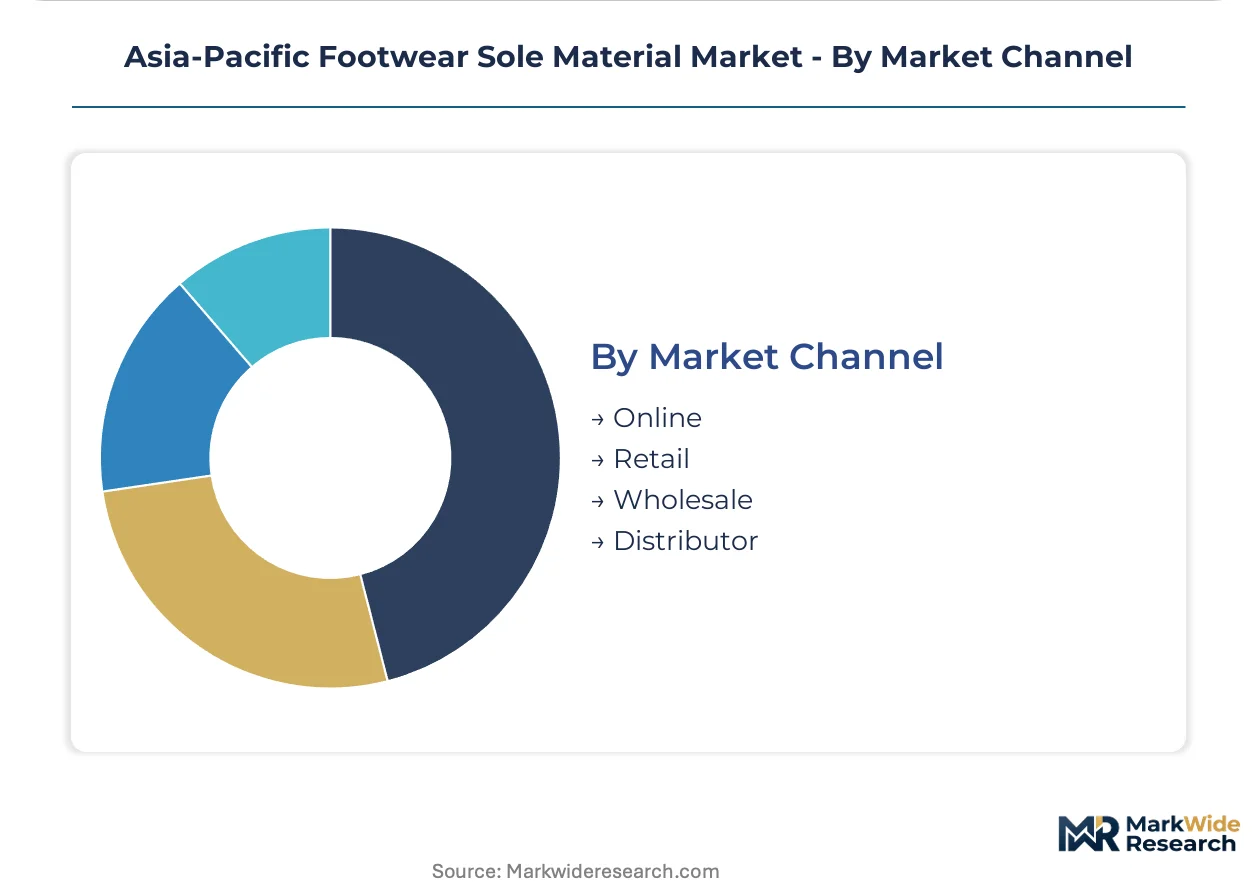
Market Channel:
Channel segmentation reflects supply chain configuration differences between inventory-light digital platforms and working-capital-intensive wholesale distribution, with geographic concentration shaping route-to-market economics.
- Retail:Branded storefronts and multi-brand outlets in Jakarta, Ho Chi Minh City, and Shanghai drive specification visibility for premium TPU and bio-based formulations. REACH-compliant compounds from Japanese suppliers gain preferential placement.
- Online:Direct-to-consumer platforms compress lead times and enable rapid SKU testing. Digital material selection tools are reshaping how athletic brands specify sole formulations without physical mold iteration.
- Wholesale:Bulk procurement for private-label and regional brands concentrates in Indonesia's industrial corridors and India's Tamil Nadu clusters, favoring standardized EVA and rubber compounds.
- Distributor:Third-party logistics networks serve fragmented domestic markets across the Philippines, Malaysia, and secondary Indian cities with inventory pooling for mid-tier compound specifications.
Retail channels maintain the deepest compound specification engagement; online distribution is climbing the fastest as direct-to-consumer athletic brands expand Asia-Pacific fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Indonesia exhibit high price elasticity, squeezing mid-scale compounders on EVA margins, while Japanese and South Korean athletic brands absorb premium TPU formulations with minimal volume sensitivity. China's dual carbon enforcement compresses virgin material demand curves differently across coastal export zones versus inland wholesale corridors.
China
Domestic athletic brands and export contract manufacturers drive differentiated demand for lightweight EVA and bio-based polyurethane alternatives. SAMR's GB standards for sole adhesion and wear resistance eliminate uncertified compound suppliers from formal channels. Pearl River Delta processors pivot toward closed-loop recycling infrastructure to align with MEE enforcement of dual carbon targets.
Vietnam
Korean and Japanese athletic brands concentrate procurement for performance TPU midsoles in Ho Chi Minh City and Binh Duong export zones. REACH compliance costs elevate formulation testing expenses for compounders serving EU-bound factory orders. Supercritical CO2 foaming adoption accelerates as embedded technical teams compress mold iteration cycles.
India
Domestic formal footwear and industrial safety categories sustain rubber compound demand despite EVA penetration in casual segments. BIS ISI certification mandates for rubber and plastic components consolidate volume with certified manufacturers. Gujarat and Tamil Nadu processors face exit pressure as compliance costs concentrate procurement with qualified compound suppliers.
South Korea
Domestic athletic brands and petrochemical-backed compounders anchor premium TPU formulation development for export markets. MFDS-aligned material safety documentation supports seamless access to Vietnamese manufacturing partnerships. Seoul-based technical teams deploy embedded material scientists in Ho Chi Minh City production zones.
Indonesia
Emerging Java footwear clusters generate underpenetrated demand for standardized EVA compounds as export manufacturing expands. Domestic wholesale channels favor cost-efficient rubber formulations for local distribution. Industrial corridor development in Greater Jakarta attracts first-mover positioning from integrated resin-to-sole producers.
Asia-Pacific Footwear Sole Material Market Competitive Environment
Integrated petrochemical-compounders and specialized footwear material developers split the market between scale-driven commodity supply and performance-tier formulation expertise. Structure consolidates around three archetypes: captive petrochemical producers with backward integration into resin supply, independent compounders serving branded athletic technical specifications, and integrated sole manufacturers controlling cost from polymer to finished component. Dominant competitive moves include capacity expansion in Vietnam's export zones and strategic partnerships embedding technical teams within factory operations.
Among integrated sole manufacturers, Yue Yuen Industrial Holdings Limited exemplifies the captive-production archetype with manufacturing footprint spanning China and Vietnam. Toray Industries and Kumho Petrochemical represent petrochemical-backed compounders supplying consistent quality to major regional athletic brands. These three anchors illustrate how scale, technical integration, and geographic positioning define competitive differentiation in Asia-Pacific sole material supply.
| Leading Market Players |
|---|
| Asics Corporation |
| Yue Yuen Industrial Holdings Limited |
| Toray Industries |
| Teijin Limited |
| LG Chem |
| Mitsui Chemicals |
| Formosa Plastics Corporation |
| Kumho Petrochemical |
| Wanhua Chemical Group |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo port freight corridors transmit volatile bunker fuel costs downstream, compressing EVA compound margins for mid-scale Vietnamese processors while amplifying price spreads between certified bio-based formulations and commodity alternatives across Ho Chi Minh City export zones.
Pricing Analysis
Aftermarket regrind and closed-loop recovery services now capture lifetime value previously locked in virgin compound sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH compliance certification and embedded technical support, with EU-bound athletic brands absorbing premium TPU formulations while Indian wholesale channels squeeze EVA suppliers on volume scale. Cost compression in mid-grade EVA runs through petrochemical feedstock volatility and informal supplier exit. Price-sensitive buyers concentrate in Indonesia's domestic wholesale corridors; least sensitive demand anchors in Korean and Japanese athletic brand technical specifications.
Supply Chain Analysis
Ethylene and propylene feedstock sourcing draws from integrated petrochemical complexes in China, South Korea, and Thailand, with resin supply concentrating around Yeosu, Ulsan, and Ningbo production hubs. TPU pellet and EVA compound manufacturing rests on phthalate-free plasticizer availability and supercritical CO2 blowing agent supply chains. Single-source vulnerability intensifies around specialized bio-based polyol producers serving EU-bound Vietnamese factories. Distribution runs through Ho Chi Minh City and Jakarta industrial corridors for export manufacturing, with Pearl River Delta processors serving domestic Chinese wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as dual carbon enforcement and BIS quality mandates displace informal compounders, creating acquisition targets and white-space entry points across certified supplier tiers.
For Market Incumbents: Insulate margin pools by accelerating backward integration into bio-based polyol supply and embedding technical teams within Vietnam's Ho Chi Minh City manufacturing zones to compress formulation feedback loops. Threat substitution from supercritical CO2 foaming virtualization demands captive R&D investment in density gradient control. Certification investment in EUDR traceability systems anchors preferential supplier status against emerging Indonesian compounders. For New Entrants and Emerging Players: Pursue underpenetrated Java industrial corridors for standardized EVA supply to emerging footwear clusters, leveraging lower compliance overhead against established Vietnamese exporters. Target India's certified compounder gap as BIS ISI mandates consolidate Gujarat and Tamil Nadu volume. Go-to-market through direct technical partnership with Korean athletic brand procurement teams seeking second-source TPU qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with demonstrated supercritical foaming capability and embedded factory technical presence over pure resin suppliers. Long-term viability across the analysis window hinges on bio-based feedstock transition completion and EUDR certification infrastructure. Acquisition target archetype: mid-scale Vietnamese or Indonesian compounders with SAMR or BIS compliance and latent capacity for TPU formulation expansion. Signal to watch: embedded material scientist deployment rates by Korean and Japanese brands as proxy for technical integration intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyols | Captures margin from renewable feedstock transition mandated by EU Green Deal procurement criteria. |
| Supercritical CO2 Foaming Capacity Addition | Virtualizes mold iteration cycles for Korean and Chinese athletic brands in Vietnam export zones. |
| EUDR Traceability Certification Program | Secures preferential supplier status for EU-bound factory orders against uncertified competitors. |
| Embedded Technical Team Deployment | Compresses real-time density and hardness adjustments during production ramp in Ho Chi Minh City. |
| Closed-Loop Regrind Infrastructure | Captures aftermarket margin pools from end-of-life sole recovery in China's Pearl River Delta. |
Study Parameters
Initial hypotheses were tested against primary input from compound procurement managers at athletic brand technical offices, plant managers at Vietnamese and Indonesian sole manufacturers, petrochemical R&D directors, and BIS certification auditors, and refined through secondary validation against customs trade data, SAMR GB standard filings, SEC 10-K disclosures from integrated sole manufacturers, and REACH compliance registries. Bottom-up volume modeling from individual factory capacity and top-down demand triangulation from brand procurement forecasts were cross-referenced for convergence.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning material type, footwear application, end-user gender, and channel configuration. CAGRs were derived from slope analysis of fitted trend lines against historical volume trajectories, incorporating input from ethylene price elasticity models and athletic brand order pipeline disclosures.
Macroeconomic conditions sit as an overlay; deviation in bunker fuel indices, ethylene spot pricing, or RMB-VND exchange rates would shift the trajectory for export manufacturing margins. Forecasts reflect documented assumptions regarding regulatory enforcement timing and brand technical specification evolution. Cross-checking against IHS Markit petrochemical demand indices and athletic footwear production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Global Socks Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Denim Market
Apparel Textiles
Rolle Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Knitwear Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Automotive Textiles Market