
 North America Textile Garment Market | 2026-2036
North America Textile Garment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Textile Garment Market Analytics
Software-defined sizing and digital fit customization is recalibrating how textile garments move from factory to consumer. Nike Inc. leverages biomechanical data and 3D knitting platforms to reduce return rates in its direct channels. Levi Strauss & Co. anchors its competitive position through controlled denim finishing operations in Mexico that preserve proprietary wash chemistry. Hanesbrands Inc. dominates mass-market basics distribution through captive wholesale relationships with US big-box retailers.
Textile garments encompass woven, knitted, and non-woven apparel constructed from natural or synthetic fibers, typically measured by fabric weight in grams per square meter and seam strength in Newtons per centimeter, serving functional, protective, and fashion purposes across consumer and institutional buyers. Cotton retains the largest volume share in the North American material mix due to regional spinning infrastructure and consumer tactile preference, though polyester gains ground in athletic applications for moisture-wicking performance. Jeans and jackets command higher unit margins than T-shirts because of complex construction, hardware requirements, and brand premiumization potential in the premium denim and outerwear segments.
The US EPA oversees chemical discharge limits under the Clean Water Act that constrain textile dyeing operations, while California's Safer Consumer Products regulations force reformulation of flame retardants and formaldehyde-based finishes. OSHA workplace standards govern cotton dust exposure in spinning mills, particularly affecting operations in the southeastern US states. Stakeholders must track how state-level extended producer responsibility legislation evolves, since apparel take-back mandates will reshape reverse logistics costs and material recovery economics across the value chain.
Market Dynamics
Extended producer responsibility mandates in California and chemical safety reviews by the US EPA are forcing apparel brands to reconfigure material sourcing and reverse logistics infrastructure across the value chain.
Growth Catalysts
- Activewear Performance Fabrics:Athletes and fitness consumers drive preference for moisture-wicking synthetic blends in training and competition apparel. Polyester-spandex constructions now dominate team sports and recreational athletic segments.
- EPA Clean Water Act Enforcement:Stricter discharge limits on textile dyeing operations accelerate investment in closed-loop water systems and low-impact finishing chemistry across US manufacturing zones.
- Mexico-Border Manufacturing Clusters:Assembly operations in Baja California and Chihuahua shorten lead times for cotton and polyester apparel destined for US Southwest distribution hubs.
Market Restraints
- Cotton Price Volatility:Weather-driven supply fluctuations in Texas and Mississippi Delta growing regions compress margins for basics manufacturers dependent on domestic fiber sourcing.
- California Safer Consumer Products Rules:Flame retardant and formaldehyde-based finish reformulations force costly R&D cycles and inventory write-downs for legacy product lines.
- Technical Limitations in Mechanical Recycling:Fiber length degradation in post-consumer cotton recovery constrains closed-loop garment-to-garment production at commercial scale.
Strategic Opportunities
- Software-Defined Sizing:Biomechanical data platforms and 3D knitting enable mass customization in direct-to-consumer channels, reducing return processing costs.
- Canadian Apparel Take-Back Expansion:Provincial extended producer responsibility frameworks in British Columbia and Ontario create first-mover advantage for brands building North American reverse logistics networks.
- Digital-Physical Convergence:Virtual try-on technologies integrated with e-commerce platforms compress the purchase decision cycle in online denim and outerwear segments.
Industry Challenges
- OSHA Cotton Dust Compliance:Workplace exposure limits in southeastern US spinning mills require capital-intensive ventilation upgrades and medical monitoring programs.
- Legacy ERP Integration:Enterprise resource planning systems at established wholesalers struggle to synchronize with real-time inventory visibility demands from big-box retail partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Textile Garment Market |
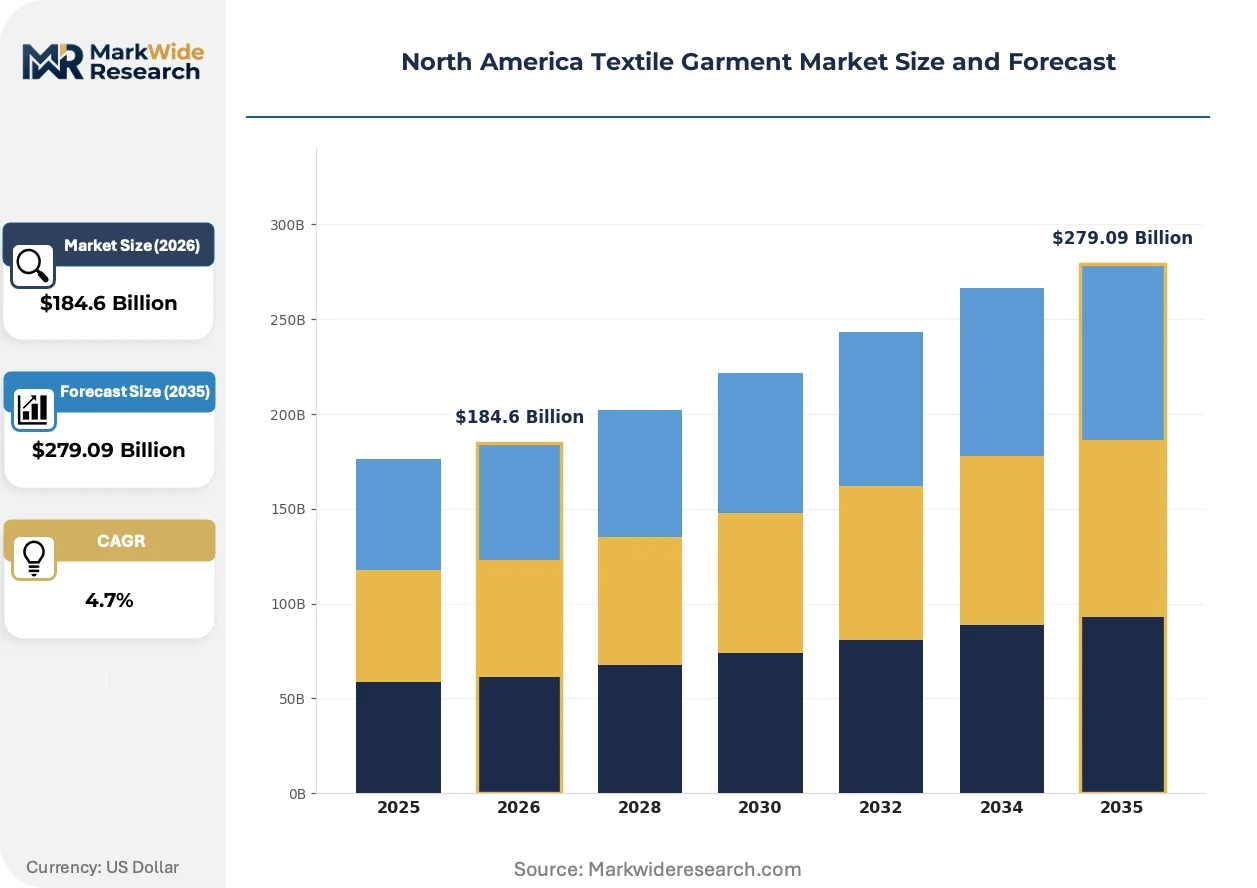
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $279.09 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shirts, Jeans, Jackets, Dresses Material: Cotton, Polyester, Wool, Nylon End User: Men, Women, Children, Athletes Distribution Channel: Online, Retail Stores, Wholesalers, Boutiques |
| Companies Covered | Nike Inc., VF Corporation, Levi Strauss & Co., Hanesbrands Inc., PVH Corp., Milliken & Company, Parkdale Mills, Mohawk Industries Inc., Elevate Textiles Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Textile Garment Market Evolving Landscape
Digital fit technologies and low-impact finishing chemistry are compressing traditional garment development timelines while regulatory pressure on chemical inputs intensifies reformulation investments.
3D knitting platforms are expanding into made-to-measure activewear production. Direct-to-consumer athletic brands deploy these systems for on-demand manufacturing of compression garments and performance tops. The technology is expanding into mid-market basics by enabling single-unit production economics previously reserved for artisanal operations.
California's Safer Consumer Products regulations now mandate alternative assessment for formaldehyde-based wrinkle-resistant finishes in children's sleepwear and occupational uniforms. Apparel finishers in Los Angeles and San Francisco garment districts face reformulation deadlines that compress product development cycles. Brands with captive finishing operations in Mexico preserve proprietary chemistry through geographic separation from state-level enforcement.
Buyers increasingly demand supply chain transparency documentation as a prerequisite for wholesale procurement. Mass-market retailers now require tier-1 suppliers to disclose fiber origin, dyehouse location, and wage compliance certification. This behavioral shift concentrates sourcing relationships with vertically integrated manufacturers capable of end-to-end traceability, particularly visible in US Southwest distribution corridors serving Texas and Arizona retail networks.
North America Textile Garment Market Segmentation
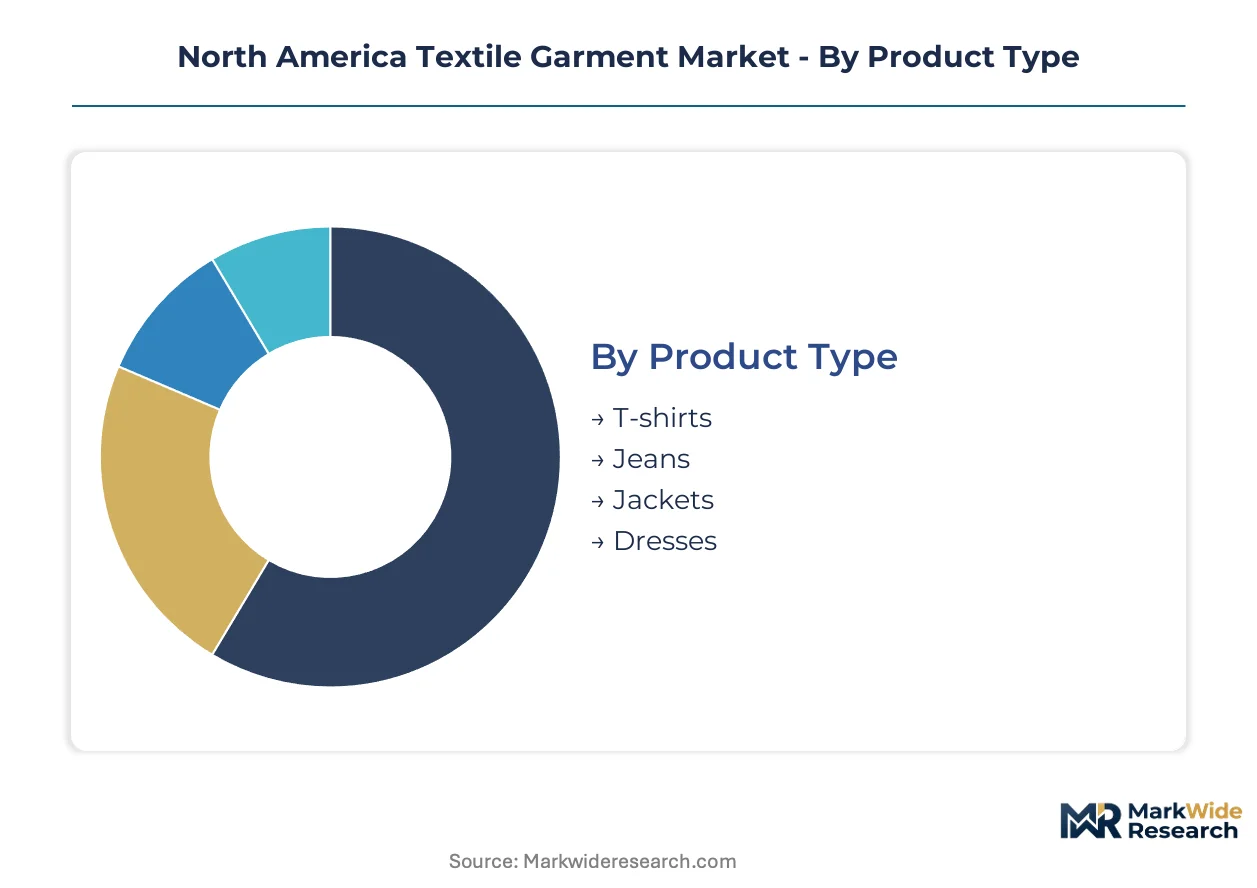
Segmentation in the North America Textile Garment Market reveals divergent margin structures and sourcing requirements. Product type and material selection dictate capital intensity, while end-user targeting shapes channel strategy and geographic fulfillment priorities.
Product Type:
Volume concentration sits with basic apparel, while premium margins concentrate in complex construction categories.
- T-shirts:Lightweight knit constructions in cotton or cotton-poly blends dominate unit volume across mass-market distribution. Demand concentrates in the US Southwest, where Mexico-border assembly clusters and Texas distribution hubs compress lead times for replenishment programs serving big-box retailers.
- Jeans:Heavyweight denim with proprietary wash chemistry and hardware requirements commands higher unit margins than basics. California's Safer Consumer Products regulations on flame retardants and formaldehyde-based finishes force reformulation of legacy finishing processes, elevating compliance costs for domestic finishers.
- Jackets:Multi-component outerwear with insulation, lining, and weatherproofing layers requires specialized sewing equipment and longer production cycles.
- Dresses:Varied silhouette constructions span fast-fashion seasonal turnover and occasion-wear premium positioning.
Mature deployment sits with T-shirts. Newer deployment is concentrated in technical outerwear and performance-oriented jacket constructions.
Material:
Natural fiber infrastructure anchors regional spinning capacity, while synthetics capture athletic performance applications.
- Cotton:Regional spinning infrastructure in the southeastern US preserves volume leadership despite weather-driven price volatility in Texas and Mississippi Delta growing regions. OSHA cotton dust exposure limits in these mills require capital-intensive ventilation upgrades and medical monitoring programs.
- Polyester:Moisture-wicking synthetic constructions now dominate team sports and recreational athletic segments. Demand concentrates among athletes and fitness consumers in the US Southwest, where performance fabric preferences align with active outdoor lifestyles.
- Wool:Thermal regulation and natural flame resistance sustain niche positioning in cold-weather outerwear and occupational uniforms.
- Nylon:High tenacity-to-weight ratios enable lightweight durability in technical jackets and compression activewear.
Established fiber processing dominates cotton. The steepest expansion trajectory belongs to polyester-spandex blends in athletic applications.
End User:
Gender-based segmentation aligns with sizing complexity and replenishment frequency, while athletic specialization demands technical performance specifications.
- Men:Standardized sizing grids and predictable style rotation support high-volume, low-complexity production economics in basics and denim.
- Women:Greater silhouette variety and seasonal trend velocity require flexible manufacturing systems and higher SKU counts.
- Children:Rapid size turnover and safety regulations on flame retardants in sleepwear elevate compliance burdens for California-facing suppliers.
- Athletes:Biomechanical data integration and 3D knitting platforms enable mass customization of compression garments and performance tops. Demand concentrates in direct-to-consumer channels where software-defined sizing reduces return processing costs.
Conventional gender segmentation maintains volume leadership. Athlete-specific technical apparel represents the fastest-climbing customization tier.
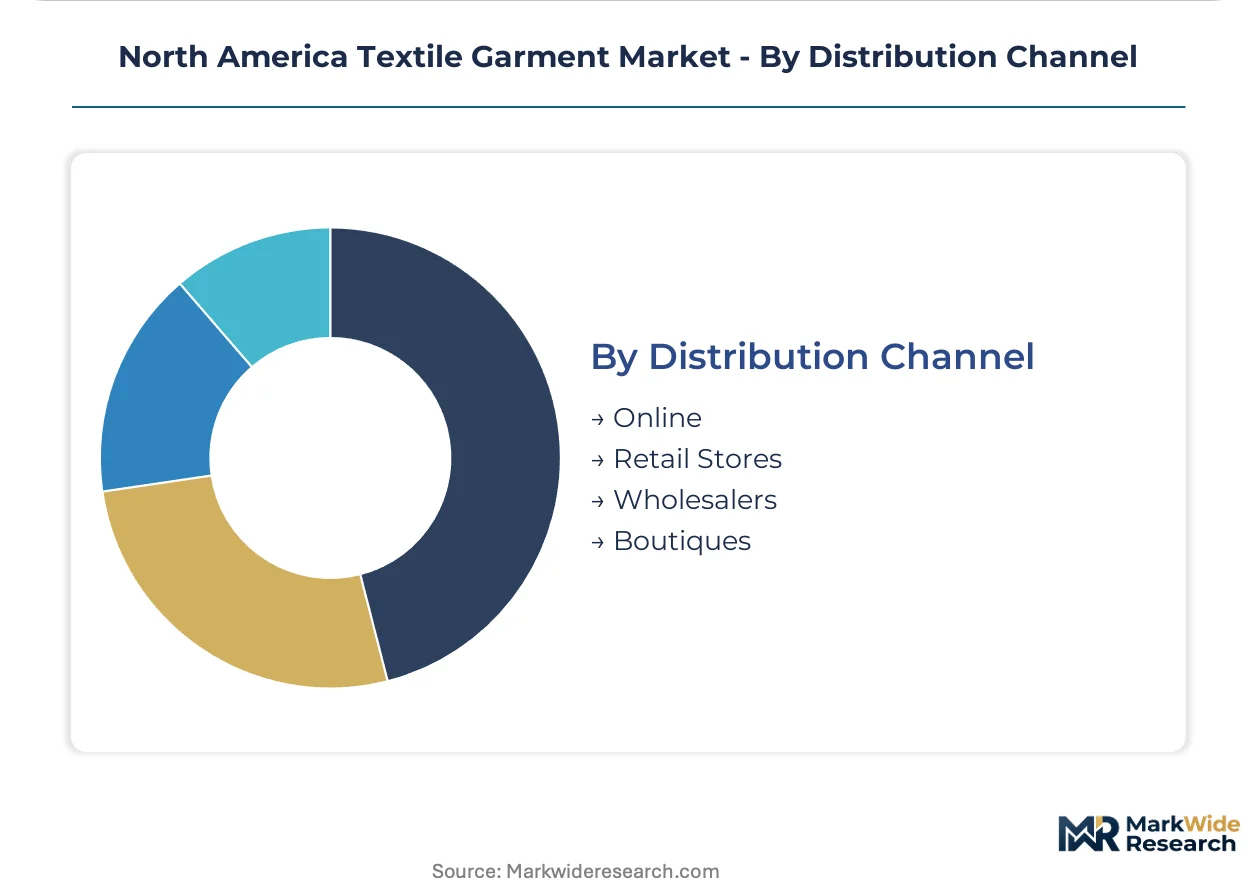
Distribution Channel:
Channel selection determines inventory risk allocation and margin capture, with digital integration reshaping traditional wholesale relationships.
- Online:Direct-to-consumer platforms leverage virtual try-on technologies and biomechanical sizing data to compress purchase decision cycles. Brands building proprietary e-commerce infrastructure capture margin otherwise surrendered to retail intermediaries.
- Retail Stores:Big-box partnerships in the US Southwest concentrate replenishment volume through Texas distribution hubs, though legacy ERP systems at established wholesalers struggle with real-time inventory visibility demands.
- Wholesalers:Captive relationships with vertically integrated manufacturers capable of end-to-end traceability are increasingly mandatory for mass-market procurement.
- Boutiques:Curated assortment and premium positioning sustain higher unit economics despite lower volume throughput.
Wholesale relationships retain volume concentration. Digital-native channels are gaining share fastest through software-defined sizing and on-demand production integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumption outpaces domestic production capacity, creating import dependency for finished apparel while Mexico and Canada specialize in upstream textile processing and nearshoring assembly.
United States
Athletic wear demand from fitness consumers and professional sports leagues drives polyester-spandex consumption. The EPA enforces Clean Water Act discharge limits on domestic dyeing operations. Los Angeles and New York garment districts concentrate finishing capacity for premium denim and outerwear brands.
Mexico
Nearshoring investments from US retailers accelerate assembly operations for time-sensitive fashion cycles. Mexican environmental regulations align with USMCA sustainability provisions for cross-border trade. Baja California and Chihuahua manufacturing clusters shorten lead times for cotton basics destined for Texas distribution hubs.
Canada
Provincial extended producer responsibility frameworks in British Columbia and Ontario mandate apparel take-back programs. Health Canada regulates chemical safety in children's sleepwear through flammability standards. Montreal and Toronto house technical design centers serving North American outerwear brands.
North America Textile Garment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure. Vertically integrated manufacturers with captive spinning and finishing operations command margin advantages in basics and denim. The market fragments across three archetypes: multinational athletic brands with direct-to-consumer platforms, heritage denim houses with proprietary wash chemistry, and mass-market wholesalers with big-box retail captivity. Competitive intensity centers on geographic diversification into Mexico-border assembly zones and software-defined sizing investments that compress return rates.
Among US-incorporated athletic specialists, Nike Inc. exemplifies the biomechanical data and 3D knitting archetype. Levi Strauss & Co. and Hanesbrands Inc. represent contrasting positioning strategies—one anchored in controlled Mexico finishing for premium denim, the other in mass-market basics distribution through wholesale retail partnerships. These three entities illustrate how scale, vertical control, and channel selection separate winners in distinct garment segments.
| Leading Market Players |
|---|
| Nike Inc. |
| VF Corporation |
| Levi Strauss & Co. |
| Hanesbrands Inc. |
| PVH Corp. |
| Milliken & Company |
| Parkdale Mills |
| Mohawk Industries Inc. |
| Elevate Textiles Inc. |
| Others |
Value Network & Pricing Analysis
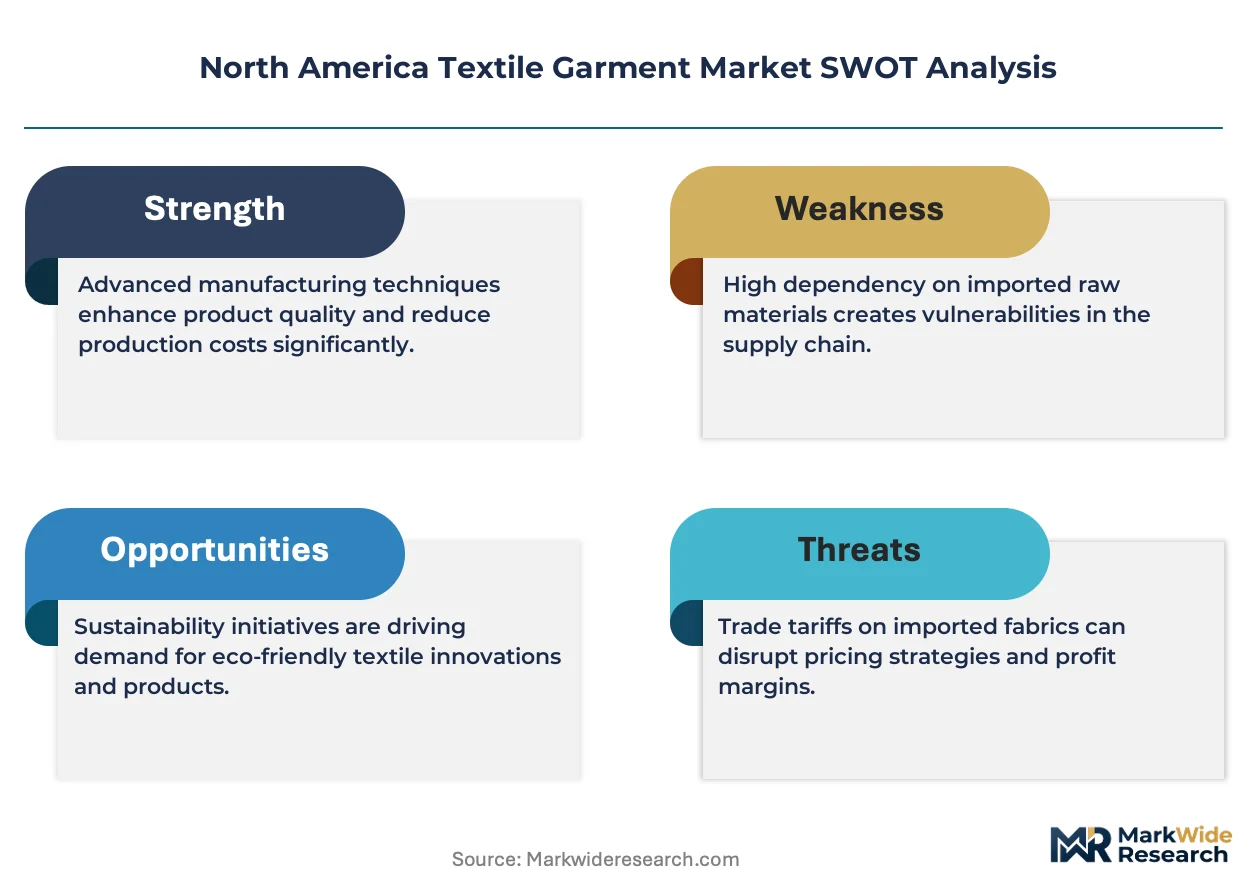
Captive finishing operations in Mexico anchor margin preservation for denim specialists while California's chemical safety mandates force domestic competitors into costly reformulation cycles. This geographic bifurcation of compliance costs creates pricing power asymmetries that favor vertically integrated players with cross-border production footprints.
Pricing Analysis
Margin tightening in mass-market basics reflects cotton price volatility from Texas and Mississippi Delta weather disruptions. Three-tier pricing structure across premium, standard, and economy levels separates proprietary-wash denim from commodity basics. Price differentiation hinges on certification tier for chemical compliance and captive supply of spinning capacity. Cost-down pressure on polyester activewear accelerates because athletes demand moisture-wicking performance at competitive price points. Big-box retail buyers exhibit highest price sensitivity; premium outerwear purchasers show lowest.
Supply Chain Analysis
USMCA domestic-content provisions reshape sourcing toward Mexico-border assembly clusters in Baja California and Chihuahua. Geographic supply concentration spans Mexico, the United States, and Canada. Raw material dependencies draw from Texas cotton, Southeast Asian polyester fiber, and proprietary dye chemistry. Tariff exposure on cross-border textile shipments constitutes the dominant supply chain risk. Distribution runs through Texas hubs serving Southwest retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Safer Consumer Products regulations erect compliance moats that protect incumbent finishers with reformulation capabilities while screening out undercapitalized entrants. This cost-of-compliance dynamic concentrates competitive advantage among players with captive chemistry expertise.
For Market Incumbents: Extend controlled finishing operations in Mexico to preserve proprietary wash chemistry outside California enforcement jurisdiction. Deepen backward integration into Southeast US spinning capacity to hedge cotton price volatility. Defensive priority centers on OSHA-compliant ventilation upgrades in legacy mills facing dust exposure mandates.
For New Entrants and Emerging Players: Direct-to-consumer platforms with biomechanical sizing data offer the most penetrable entry route. White-space targets include athlete-specific compression garments and Canadian provincial take-back program logistics. Go-to-market angle emphasizes software-defined customization to compress return rates below wholesale benchmarks.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by athletic brands seeking captive finishing capacity. Long-term viability favors vertically integrated manufacturers with cross-border footprints and chemical compliance certification. Watch EPA Clean Water Act enforcement intensity as inflection indicator for domestic dyeing asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Mexico Finishing Expansion | Preserved proprietary chemistry outside California Safer Consumer Products jurisdiction protects margin structure. |
| 3D Knitting Platform Deployment | On-demand compression garment production reduces inventory risk in athlete direct-to-consumer channels. |
| Closed-Loop Water System Investment | EPA Clean Water Act compliance in domestic dyeing operations avoids discharge limit penalties. |
| Canadian Take-Back Network Buildout | British Columbia and Ontario EPR frameworks create first-mover reverse logistics advantage. |
| Biomechanical Data Platform Integration | Software-defined sizing reduces return processing costs below traditional wholesale economics. |
Research Methodology
Independent corroboration across brand supply chain executives, textile mill operations directors, and retail procurement managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through US EPA enforcement records, USMCA trade documentation, and OSHA compliance filings. Bottom-up capacity assessments triangulated against top-down consumption estimates from customs data and retail audit channels.
Comparable-period anchoring used historical volume trajectories across cotton basics, denim, and activewear segments to calibrate projection assumptions. The analytical framework modeled product type, material composition, end-user gender, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific inputs included cotton futures volatility patterns and EPA enforcement intensity indices.
Inputs from state regulatory filings and trade association surveys were available through the study window; gaps in real-time inventory velocity data from private wholesalers introduce uncertainty bands. Forecasts reflect documented assumptions on USMCA stability and chemical regulatory trajectory. Cotton weather shocks or accelerated EPA rulemaking could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Stockings Market
Apparel Textiles
Denim Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Japan Denim Jeans Market