
 Non Woven Converting Machine Market | 2026-2036
Non Woven Converting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Non Woven Converting Machine Market Insights
The split between premium precision systems and commodity converting lines is hardening as hygiene brand owners demand servo-driven tension control and inline defect detection while budget buyers prioritize throughput over flexibility. DiloGroup leverages its needle punching specialization to anchor high-performance industrial fabric contracts across European technical textile clusters. Freudenberg Group sustains captive machine customization through backward integration into filtration and automotive component supply chains.
Non woven converting machines transform continuous rolls of bonded fibrous webs into finished or intermediate products through slitting, folding, laminating, or rewinding operations, typically processing webs from 15 to 400 gsm at line speeds exceeding 600 meters per minute for hygiene applications. The equipment serves medical, filtration, geotextile, and absorbent product supply chains where web integrity and edge uniformity determine downstream performance. Slitting machines dominate installed base value due to their ubiquity across every end-use vertical, while hydroentangling technology lines command premium pricing as spunlace demand expands in flushable wipes and medical gauze segments. Fully automatic systems with programmable logic control are displacing semi-automatic configurations in new capacity investments as labor costs and changeover frequency rise.
FDA device manufacturing regulations and EU MDR conformity requirements shape machine design for medical nonwoven processing, mandating validated cleaning protocols and traceable change parts. REACH chemical restrictions and California's Proposition 65 influence adhesive selection in laminating stations, pushing OEMs toward hot-melt platforms with reduced hazardous substance profiles. Stakeholders must monitor how Ecodesign Directive expansion and emerging state-level extended producer responsibility laws in the US reshape material handling specifications and retrofit obligations across installed equipment fleets.
Market Dynamics
The Non Woven Converting Machine Market faces a structural squeeze between hygiene brand demands for servo-driven precision systems and commodity buyers prioritizing raw throughput, forcing OEMs to bifurcate R&D roadmaps and production lines.
Growth Catalysts
- EU Green Deal mandates:Biodegradable substrate handling capabilities are becoming mandatory specifications in European tender documents, pulling converters toward equipment with certified compostable web processing.
- Spunlace medical gauze demand:Hydroentangling technology lines command premium positioning as hospital procurement shifts toward single-use sterile products with validated supply chains.
- China-India-Germany production clusters:Regional nonwoven output scaling in these three markets concentrates new machine orders, creating localized service ecosystems and faster spare parts availability.
Market Restraints
- Specialized steel and servo motor costs:Input material volatility for precision tension control components compresses margins on mid-tier equipment configurations.
- German-Italian component supplier concentration:Critical web handling subsystems rely on a narrow base of European precision engineering houses, exposing buyers to extended lead times.
- REACH chemical restrictions:Adhesive formulation constraints in laminating stations limit hot-melt platform options and complicate multi-region equipment certification.
Strategic Opportunities
- Flushable wipes regulatory tailwind:EDANA/INDA flushability guidelines in North America and Europe are creating certified equipment demand for dispersible substrate converting lines.
- India technical textile expansion:Underpenetrated geotextile and automotive interior markets offer whitespace for needle punching and thermal bonding system suppliers.
- Digital twin convergence:Virtual commissioning and predictive maintenance modules are converging with traditional PLC architectures, enabling remote diagnostics and reduced commissioning time.
Industry Challenges
- Validated cleaning protocol engineering:FDA device manufacturing regulations and EU MDR conformity requirements demand specialized mechanical design talent that OEMs struggle to recruit.
- Legacy semi-automatic fleet retrofit complexity:Installed base upgrades to programmable logic control face mechanical-electrical integration friction and undocumented change part histories.
- Extended producer responsibility compliance:Emerging state-level EPR laws in the US reshape material handling specifications with uncertain retrofit obligations across existing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Woven Converting Machine Market |
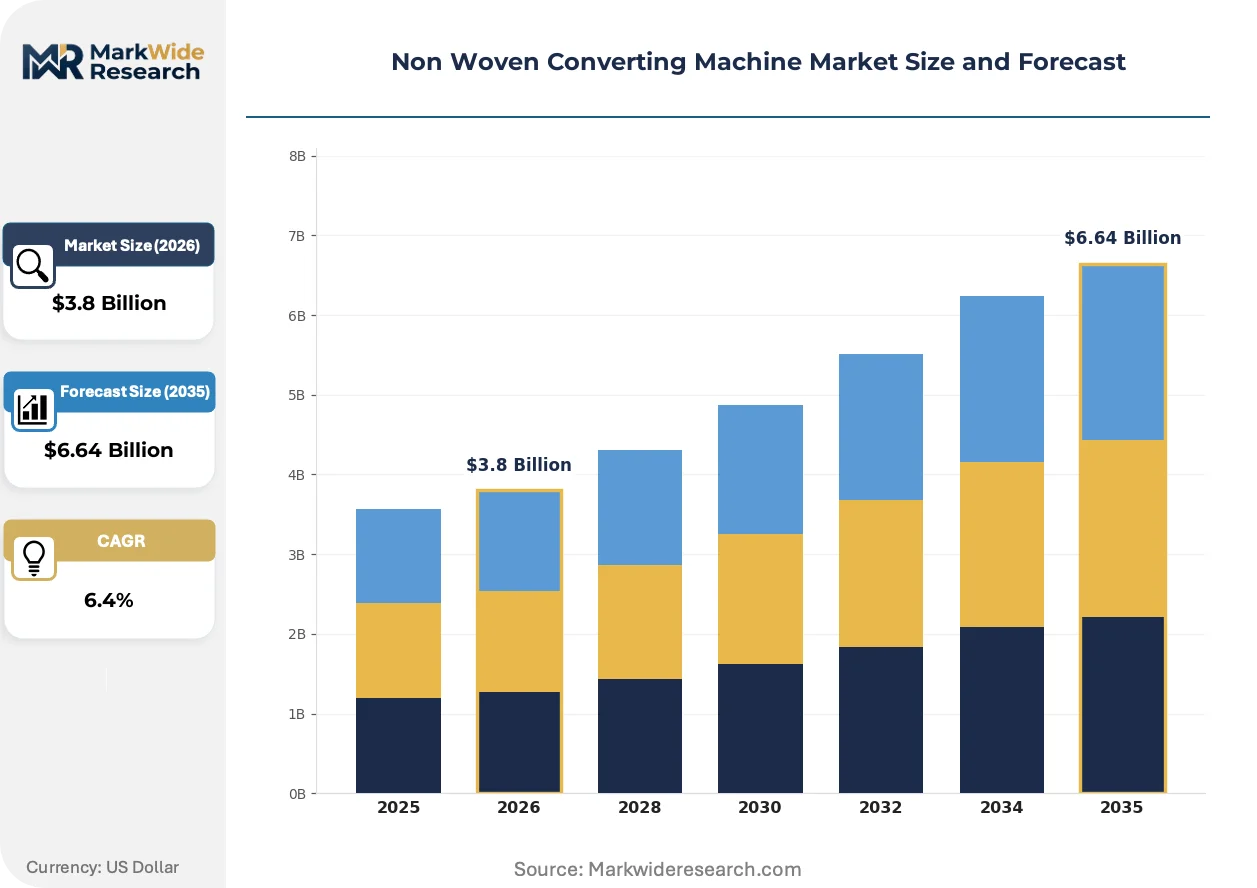
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Slitting Machines, Laminating Machines, Folding Machines, Rewinding Machines, Sheeting Machines Technology: Thermal Bonding, Ultrasonic Bonding, Needle Punching, Chemical Bonding, Hydroentangling End User Industry: Hygiene Products, Automotive Components, Filtration Systems, Agricultural Fabrics, Construction Materials Automation Level: Manual, Semi-Automatic, Fully Automatic, CNC Controlled, Programmable Logic Control |
| Companies Covered | Paper Converting Machine Company, DiloGroup, Celli Group, C.G. Bretting Manufacturing Co., Freudenberg Group, Berry Global Inc., Johns Manville Corporation, Ahlstrom, Glatfelter Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Woven Converting Machine Market Trends and Innovations
Machine intelligence and substrate sustainability requirements are actively reconfiguring equipment specifications, with inline quality systems and biodegradable processing capabilities now baseline expectations rather than premium options.
Artificial vision defect detection is converging with servo-driven tension control to enable real-time web quality management at line speeds exceeding 600 meters per minute. Hygiene product manufacturers in Germany and the US are adopting these integrated platforms fastest, compressing the acceptable defect threshold from visible flaws to micron-level basis weight variation. This convergence is forcing smaller OEMs into technology partnerships or niche specialization to remain specification-relevant.
REACH chemical restrictions and California Proposition 65 are eliminating solvent-based adhesive platforms from laminating station designs, mandating hot-melt systems with reduced hazardous substance profiles. Equipment buyers in the EU and US West Coast now require validated material safety documentation as a precondition for purchase approval. Medical nonwoven processors face the tightest compliance windows, with FDA device manufacturing regulations layering onto chemical safety protocols.
Service contract unbundling is fragmenting the traditional bundled maintenance model, with large hygiene converters in China and India negotiating à la carte spare parts and remote support separately from installation. This procurement pattern shift is compressing OEM service margins while opening independent technical service provider markets. The trend is most visible in high-volume diaper and sanitary pad production facilities where internal maintenance capabilities have matured.
Non Woven Converting Machine Market Segmentation
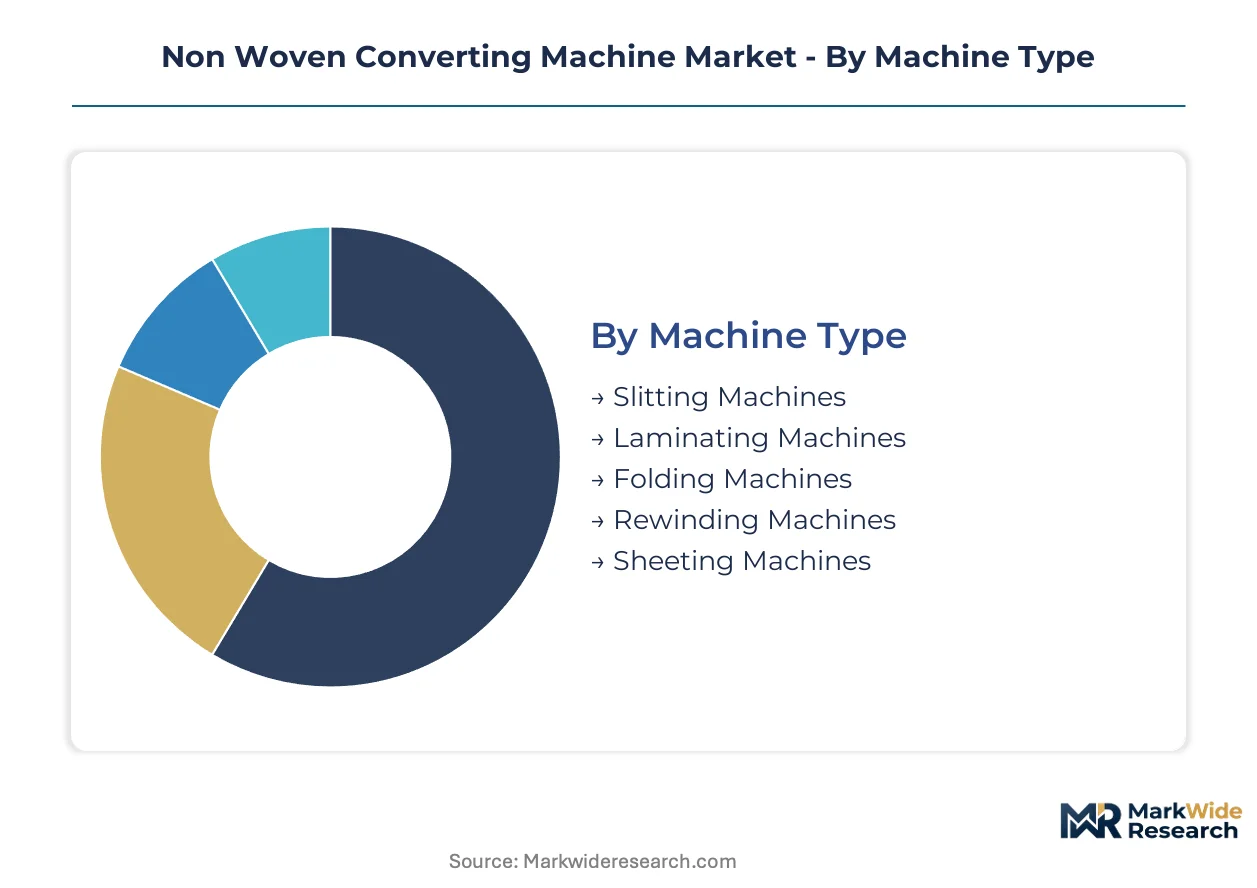
Non woven converting machine segmentation reveals distinct procurement patterns across equipment types and automation tiers. Buyers in hygiene and medical verticals prioritize integrated servo-driven systems, while commodity processors favor standalone units with lower capital thresholds.
Machine Type:
Standalone slitting and sheeting systems serve entry-level converters with limited integration requirements, while laminating and folding modules increasingly embed within continuous production lines for hygiene manufacturers.
- Slitting Machines:These units divide continuous nonwoven webs into precise widths using rotary or shear blade configurations, processing materials from 15 to 400 gsm. Demand concentrates in China and India where regional nonwoven output scaling drives replacement cycles for aging mechanical-tension equipment. The installed base dominance stems from universal applicability across every end-use vertical.
- Laminating Machines:Multi-layer bonding systems combine webs, films, and absorbent cores through hot-melt or ultrasonic welding stations. European hygiene brand owners specify these for diaper and sanitary pad lines to meet EU Green Deal biodegradable substrate handling mandates. REACH chemical restrictions are eliminating solvent-based adhesive platforms from new equipment designs.
- Folding Machines:Z-fold, C-fold, and interfold configurations produce finished wipe and medical drape formats. German technical textile clusters favor high-speed units with inline quality verification.
- Rewinding Machines:Tension-controlled roll finishing systems prepare intermediate products for downstream converting or direct shipment. Indian agricultural fabric processors prioritize robust mechanical designs over precision servo control.
- Sheeting Machines:Cut-to-length systems produce flat-packed nonwoven sheets for medical drapes and industrial wipes. Budget buyers in construction materials favor semi-automatic configurations.
Volume placements concentrate in slitting machines; the faster expansion belongs to laminating machines.
Technology:
Cost tiers separate thermal and chemical bonding as commodity platforms from hydroentangling and ultrasonic systems commanding premium positioning in medical and flushable wipe applications.
- Thermal Bonding:Calendar-based consolidation using heat and pressure suits high-volume hygiene substrates with lower structural demands. Chinese diaper manufacturers deploy these lines for cost-optimized throughput.
- Ultrasonic Bonding:High-frequency mechanical vibration creates molecular friction bonds without thermal degradation. Medical nonwoven processors in Germany adopt these for FDA device manufacturing compliance where validated cleaning protocols are mandatory. The technology eliminates adhesive contamination risks in sterile product supply chains.
- Needle Punching:Barbed needle arrays mechanically entangle fibers for geotextile and automotive interior applications. DiloGroup anchors European technical textile contracts through specialized high-performance industrial fabric systems.
- Chemical Bonding:Latex or resin saturation provides dimensional stability for disposable wipes and filtration media. California Proposition 65 restrictions are constraining formulation options in US West Coast equipment specifications.
- Hydroentangling:High-pressure water jets entangle fibers without mechanical stress, producing soft, absorbent structures. Spunlace medical gauze demand is climbing the fastest as hospital procurement shifts toward single-use sterile products with validated supply chains.
Procurement is shifting toward hydroentangling for premium medical applications; thermal bonding retains the largest installed base.
End User Industry:
Customer type differentiation separates hygiene product manufacturers demanding servo-driven precision from agricultural and construction buyers prioritizing equipment durability over changeover flexibility.
- Hygiene Products:Diaper, sanitary pad, and adult incontinence producers require line speeds exceeding 600 meters per minute with micron-level basis weight control. Freudenberg Group sustains captive machine customization through backward integration into filtration and automotive component supply chains.
- Automotive Components:Headliner, trunk liner, and insulation fabric converters need thermal and acoustic performance validation. German OEMs specify needle punching and thermal bonding combinations for interior trim applications.
- Filtration Systems:HVAC, liquid, and industrial air filtration demands precise pleating and media handling. EU MDR conformity requirements shape machine design for medical filtration processors.
- Agricultural Fabrics:Crop cover, mulch mat, and greenhouse shading applications favor robust mechanical designs with lower automation levels. Indian technical textile expansion offers whitespace for needle punching system suppliers.
- Construction Materials:Geotextile, housewrap, and roofing underlayment processors prioritize throughput over precision. Chinese infrastructure investment drives regional equipment demand.
Equipment shipments concentrate in hygiene products; automotive components are gaining share fastest as lightweighting trends expand nonwoven interior applications.
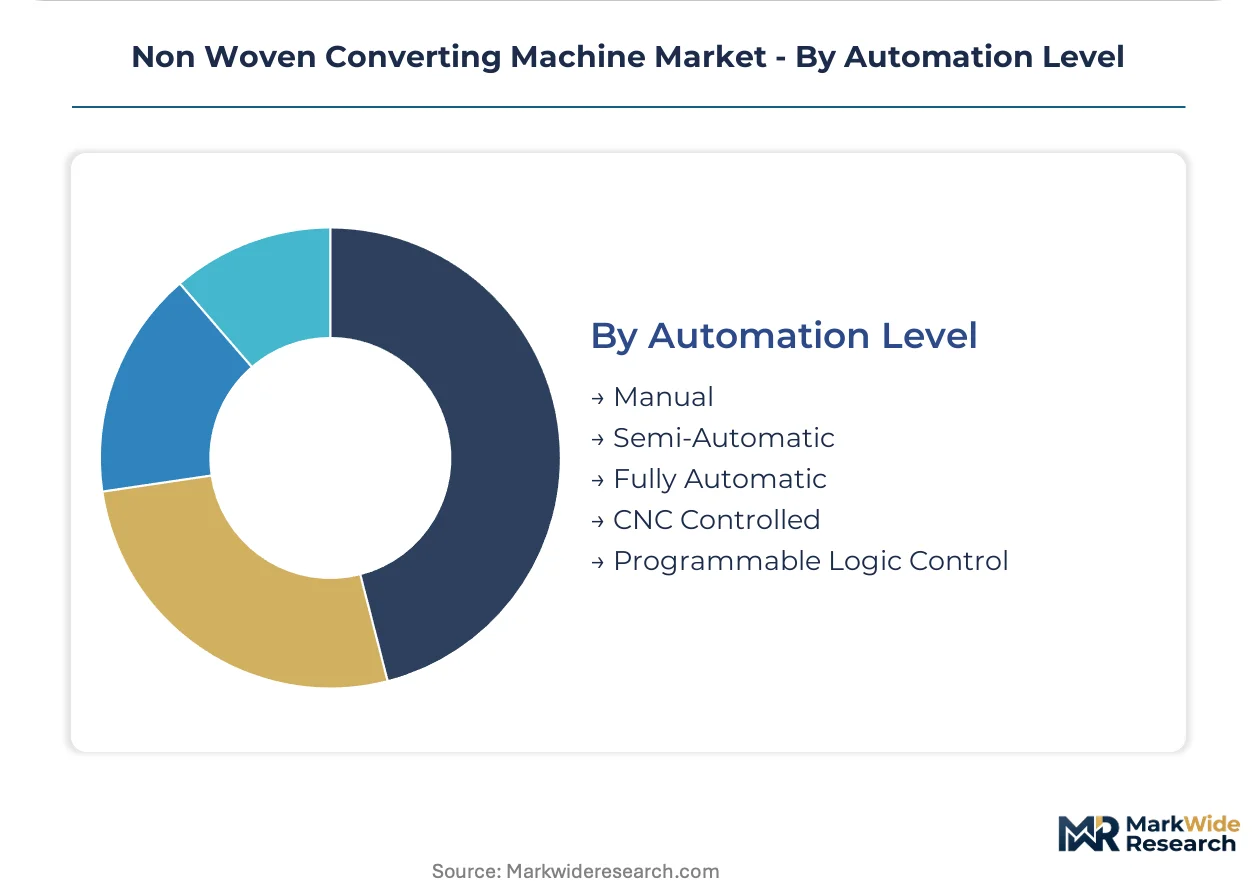
Automation Level:
Maturity gradients separate legacy manual and semi-automatic fleets from programmable logic control investments in new capacity, with CNC and fully automatic systems capturing premium positioning in high-labor-cost geographies.
- Manual:Operator-dependent setups persist in emerging market small-batch operations with limited capital availability. These configurations face obsolescence pressure as labor costs rise.
- Semi-Automatic:Partial mechanization with manual loading and quality inspection dominates mid-tier agricultural and construction fabric processors. Legacy fleet retrofit complexity impedes upgrades to programmable logic control due to undocumented change part histories.
- Fully Automatic:Integrated material handling and quality systems minimize operator intervention. Large hygiene converters in China and India negotiate à la carte service contracts separately from installation, fragmenting traditional bundled maintenance models.
- CNC Controlled:Computer numerical precision enables rapid format changeover for contract converters serving multiple end-use verticals. Digital twin convergence with virtual commissioning reduces deployment timelines.
- Programmable Logic Control:PLC architectures with artificial vision defect detection and servo-driven tension control enable real-time web quality management. These systems are displacing semi-automatic configurations in new capacity investments as labor costs and changeover frequency rise.
New order intake concentrates in programmable logic control systems; CNC controlled units are expanding most quickly among contract converters seeking format flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta corridor concentrates the densest cluster of nonwoven converting machinery procurement, with Chinese diaper manufacturers driving replacement cycles for aging mechanical-tension equipment across the region.
China
Domestic hygiene brands in Fujian and Guangdong provinces are scaling spunlace capacity for flushable wipes compliant with EDANA/INDA guidelines. The Ministry of Ecology and Environment's dual carbon goals are accelerating biodegradable substrate handling retrofits. Zhejiang's technical textile belt is absorbing needle punching systems for automotive interior contracts.
Germany
Freudenberg's captive machine customization anchors demand in Baden-Württemberg for filtration and automotive component supply chains. The EU Green Deal mandates certified compostable web processing capabilities in European tender documents. The Rhine-Ruhr industrial corridor hosts specialized service ecosystems for precision tension control component maintenance.
India
Maharashtra's technical textile expansion offers whitespace for needle punching and thermal bonding system suppliers targeting geotextile applications. The Bureau of Indian Standards is tightening quality protocols for medical nonwoven exports. Gujarat's petrochemical corridor is spawning localized spare parts availability for high-volume diaper converters.
United States
California's Proposition 65 restrictions are eliminating solvent-based adhesive platforms from laminating station designs on the West Coast. The FDA's device manufacturing regulations mandate validated cleaning protocols for medical nonwoven processors in the Boston-Cambridge cluster. Southeast hygiene manufacturers in Georgia and South Carolina are negotiating à la carte service contracts separately from installation.
Japan
Tokyo-Osaka medical nonwoven processors are adopting ultrasonic bonding systems for sterile product supply chains to eliminate adhesive contamination risks. The Ministry of Economy, Trade and Industry is promoting digital twin convergence for virtual commissioning. Kyushu's automotive interior fabricators are specifying thermal and acoustic performance validation equipment.
Non Woven Converting Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where premium precision systems and commodity converting lines harden into separate procurement tiers. The vendor base spans European precision engineering houses, Asian fabricators, and North American integrated hygiene conglomerates. Three archetypes dominate: integrated hygiene brands with captive machine customization, specialized needle punching and hydroentangling OEMs, and modular component suppliers serving retrofit markets. Competitive moves concentrate on backward integration into filtration supply chains and technology partnerships for artificial vision defect detection.
Among European precision specialists, DiloGroup and Freudenberg Group exemplify contrasting strategic positions. DiloGroup anchors high-performance industrial fabric contracts through specialized needle punching capabilities. Freudenberg Group occupies a position defined by backward integration into automotive and filtration component supply chains. Paper Converting Machine Company represents the North American fabrication tier serving hygiene converters with standalone slitting and laminating configurations.
| Leading Market Players |
|---|
| Paper Converting Machine Company |
| DiloGroup |
| Celli Group |
| C.G. Bretting Manufacturing Co. |
| Freudenberg Group |
| Berry Global Inc. |
| Johns Manville Corporation |
| Ahlstrom |
| Glatfelter Corporation |
| Others |
Pricing and Supply Chain Analysis
Hygiene product manufacturers in China and Germany command disproportionate pricing leverage through consolidated volume procurement, compressing OEM margins while rewarding certified compostable web processing capabilities with modest premiums. This buyer concentration forces equipment vendors into outcome-based contracting where line speed guarantees and uptime commitments displace traditional hardware-plus-installation quotations.
Pricing Analysis
Value-based pricing anchored to validated throughput outcomes dominates premium tier negotiations, with servo-driven precision systems commanding premiums tied to defect reduction guarantees rather than capital cost alone. Price differentiation hinges on EU MDR certification tier and after-sales service bundling, with unbundled à la carte procurement gaining traction among large Indian and Chinese converters. Cost compression in mid-tier thermal bonding equipment is intensifying because specialized steel and servo motor input volatility erodes margin buffers. Agricultural fabric processors in India exhibit highest price sensitivity, while German medical nonwoven buyers prioritize compliance documentation over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Mumbai orchestrate hub-and-spoke spare parts logistics, with localized inventory positioning determining aftermarket service responsiveness. Manufacturing concentration rests on German and Italian precision engineering houses for critical web handling subsystems, Chinese fabricators for structural frames, and Japanese suppliers for artificial vision components. Single-source vulnerability in specialized tension control servo motors exposes buyers to extended lead time risk. Distribution runs through OEM-direct channels for large hygiene converters and independent technical service providers for mid-tier retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR and FDA device manufacturing regulations erect formidable barrier-to-entry moats, advantaging incumbents with validated cleaning protocol engineering capabilities and documented change part histories.
For Market Incumbents: Anchor defensive positioning through captive backward integration into filtration and automotive component supply chains, mirroring Freudenberg Group's model. Deepen certification investment in biodegradable substrate handling capabilities ahead of Ecodesign Directive expansion. Prioritize digital twin convergence for predictive maintenance modules to counter independent technical service provider encroachment in China and India. For New Entrants and Emerging Players: Capture whitespace in India's underpenetrated geotextile and automotive interior markets where needle punching and thermal bonding system demand outstrips specialized supplier presence. Target Maharashtra and Gujarat technical textile clusters with localized spare parts availability partnerships. Pursue flushable wipes regulatory tailwind through EDANA/INDA guideline-certified equipment positioning. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive servo-driven tension control technology and established European regulatory compliance track records. Long-term viability hinges on acquisition targets possessing artificial vision defect detection partnerships and validated medical nonwoven processing credentials. Monitor FDA enforcement patterns on validated cleaning protocols as inflection indicator for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Supply Chains | Freudenberg Group's captive machine customization secures automotive component contract lock-in. |
| Digital Twin Convergence for Virtual Commissioning | Japan's METI promotion accelerates remote diagnostics adoption among Tokyo-Osaka medical processors. |
| Biodegradable Substrate Handling Certification | EU Green Deal mandates pull converters toward compostable web processing capabilities. |
| Needle Punching Specialization for Technical Textiles | DiloGroup anchors European industrial fabric contracts through high-performance system focus. |
| Service Contract Unbundling and À La Carte Pricing | Large Chinese and Indian hygiene converters fragment traditional bundled maintenance models. |
Research Methodology
Multi-period observation of machine order backlogs, regulatory filing timelines, and regional nonwoven output scaling anchored the trend analysis, supplemented by interviews with OEM engineering directors, hygiene product manufacturing executives, aftermarket service heads, and precision component procurement leads. Secondary validation drew from EU MDR conformity documentation, FDA device manufacturing regulation filings, EDANA/INDA flushability guideline submissions, and trade customs data for specialized steel and servo motor imports. Bottom-up equipment shipment tallies triangulated against top-down regional nonwoven capacity expansion estimates.
Segment-weighting across machine type, bonding technology, end-use vertical, and automation tier informed volume and value distribution modeling throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles, capacity utilization rates, and regional labor cost trajectories. Industry-specific inputs incorporated REACH chemical restriction compliance costs and extended producer responsibility law adoption patterns across US state legislatures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Ecodesign Directive expansion timing and emerging state-level EPR retrofit obligation clarity. Forecasts reflect documented assumptions on regional nonwoven output scaling, regulatory enforcement intensity, and input material cost stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market