
 Hosiery Market | 2026-2036
Hosiery Market Size, Share, and Industry Trends Forecast 2026-2036
Hosiery Market Intelligence
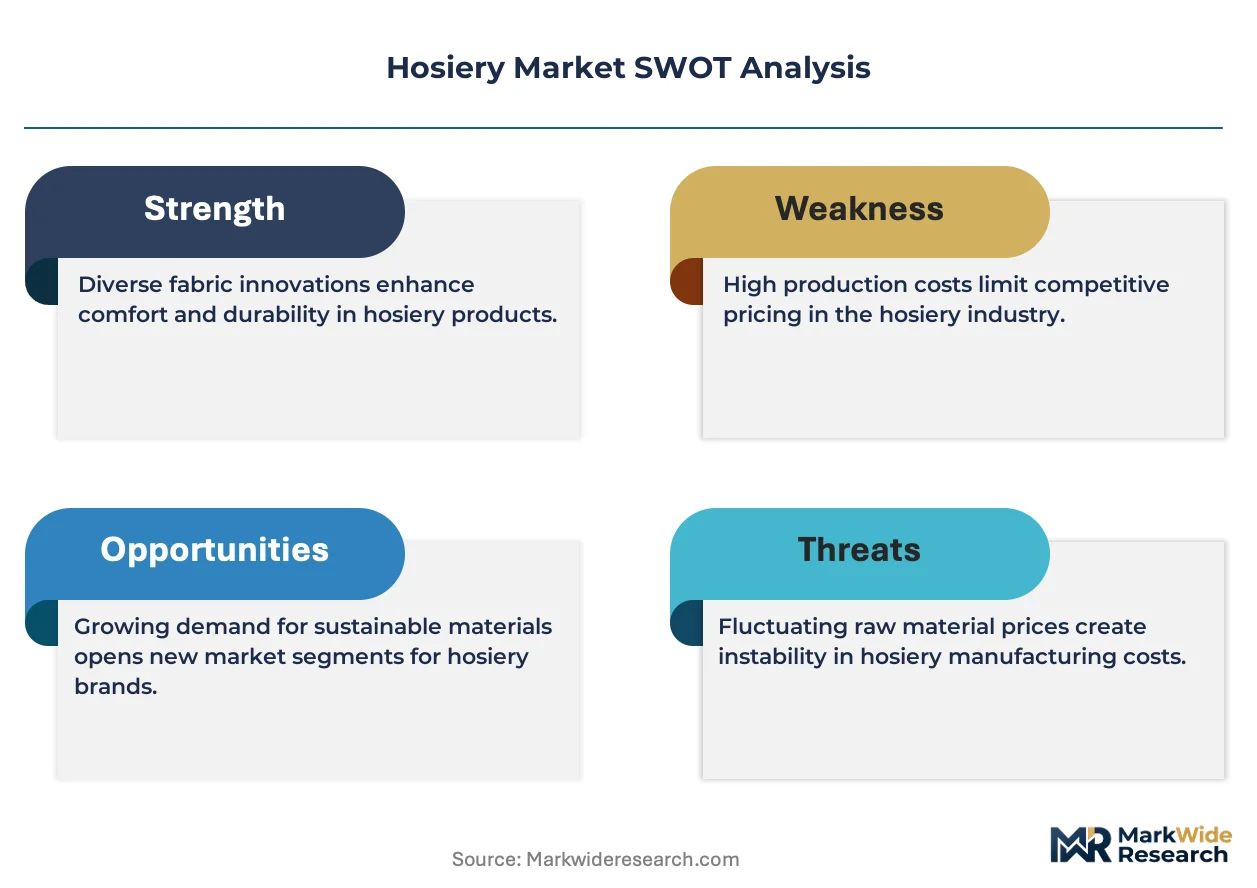
The OEKO-TEX STANDARD 100 certification is bifurcating the competitive landscape, separating premium brands from mass-market producers based on material safety and quality. Premium player Wolford AG specializes in luxury materials and innovative designs for a high-margin niche. In contrast, Hanesbrands Inc. leverages its extensive distribution network and manufacturing scale to serve the high-volume, price-sensitive segment. Calzedonia S.p.A. occupies a middle ground, focusing on fast-fashion trends and broad accessibility through its specialty stores.
Hosiery encompasses a range of garments worn directly on the legs and feet, defined by fabric weight measured in denier. These products are typically manufactured using circular knitting machines and incorporate materials like nylon blended with spandex to provide elasticity and a close fit. While tights and pantyhose for women remain the largest product categories, knee highs are seeing renewed interest. The material segment shows a clear preference for nylon blends, and online retail is rapidly gaining share from traditional department stores.
Regulatory oversight from bodies like the European Chemicals Agency (ECHA) under REACH and the U.S. Federal Trade Commission (FTC) governs the use of dyes and chemicals, and mandates accurate fiber content labeling. In China, compliance with national GB standards for textiles is essential for market access. Navigating the shift toward circular economy principles and managing material sourcing transparency will be critical for maintaining brand reputation and market position.
Market Dynamics
A central dynamic within the hosiery market is the bifurcation caused by sustainability certifications and material science. This splits the market between premium brands investing in certified, recycled materials and mass-market producers competing on volume and price with conventional nylon blends.
Growth Catalysts
- Evolving Fashion Norms:The integration of hosiery into mainstream professional and casual wear, particularly in high-growth economies like India, expands the consumer base beyond traditional occasional use.
- Sustainable Materials:Consumer and regulatory pressure for circularity is promoting the adoption of materials like recycled nylon and bio-derived spandex, creating value-added product categories.
- Online Channel Expansion:The proliferation of e-commerce platforms and direct-to-consumer brands enhances market access and product visibility, especially for specialty and niche hosiery products.
Market Restraints
- Input Price Volatility:Nylon and spandex, primary petroleum derivatives, face significant price volatility tied to crude oil markets, creating margin pressure for manufacturers.
- Substitution from Athleisure:The widespread adoption of leggings and other athleisure bottoms as everyday wear presents a direct substitute for traditional pantyhose and tights in many casual contexts.
- Chemical Regulation Compliance:Adherence to stringent chemical regulations, such as REACH in Europe, adds significant cost and complexity to the dyeing and finishing processes for hosiery.
Strategic Opportunities
- Performance and Wellness Segments:Performance hosiery with targeted compression and moisture-wicking opens new avenues in niche sports and medical wellness, commanding higher price points.
- Smart Textile Integration:Incorporating micro-sensors and conductive yarns into hosiery presents an opportunity to develop garments for health monitoring and connected fitness applications.
- Subscription-Based Models:Direct-to-consumer brands can cultivate customer loyalty and create predictable revenue streams by offering curated hosiery subscription box services.
Industry Challenges
- Global Compliance Patchwork:Manufacturers face the operational challenge of ensuring products comply with a fragmented set of international rules, including FTC labeling in the U.S. and GB standards in China.
- Supply Chain Transparency:Verifying the authenticity of recycled materials and ensuring ethical labor practices across a multi-tiered, global supply chain remains a significant hurdle for brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hosiery Market |
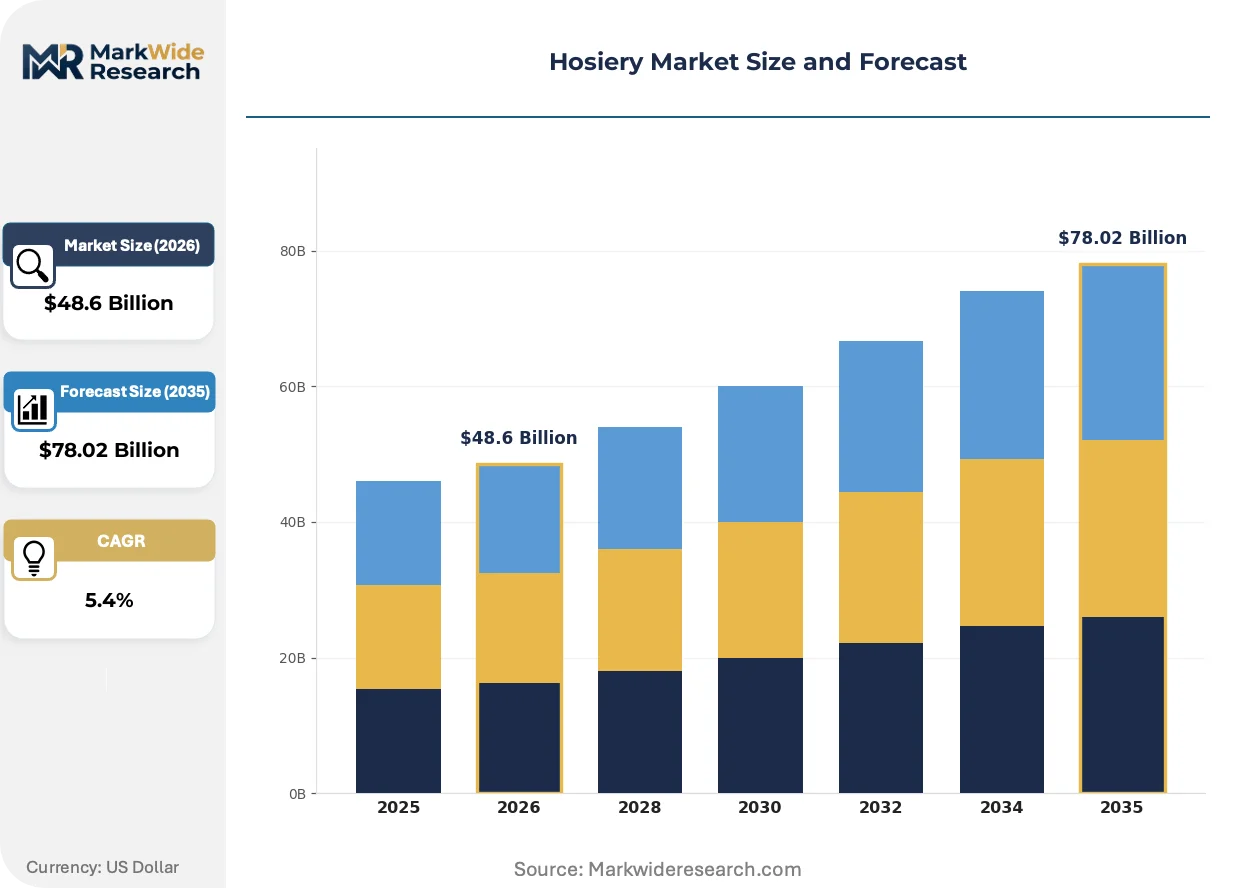
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tights, Stockings, Pantyhose, Knee Highs Material: Nylon, Cotton, Spandex, Wool End User: Women, Men, Children, Unisex Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Department Stores |
| Companies Covered | Falke KGaA, Spanx, Inc., Hanesbrands Inc, Golden Lady Company S.p.A., Calzedonia S.p.A., Jockey International, Inc., Gildan Activewear Inc, Renfro Corp., Wolford AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hosiery Market Strategic Shifts & Innovations
Material science and circular economy principles are transforming hosiery from a disposable commodity into a product category defined by performance and sustainability. This shift is evident in fabric innovation, regulatory pressures, and evolving consumer purchasing habits.
Advanced circular knitting machinery is a key technological driver. These machines use finer gauge needles to create complex, seamless garments with high-definition patterns previously unachievable at scale. Premium and luxury segments are rapidly adopting this technology for superior fit and aesthetic appeal. This advanced knitting capability is miniaturizing yarn filaments, enabling the creation of ultra-sheer yet highly durable fabrics.
Regulations focused on sustainability are impacting material choices. The European Union’s Ecodesign for Sustainable Products Regulation (ESPR) mandates improved durability and recyclability for textiles. This policy is forcing manufacturers to move away from complex, inseparable blends of fibers. The tights and legwear category is most affected, prompting research into mono-material designs and new recycling-friendly elastomers.
Subscription-based purchasing is altering distribution channels. This model disrupts the traditional retail cycle of seasonal, in-store purchasing by offering regular replenishment directly to the consumer. Direct-to-consumer brands that leverage this model for convenience are gaining traction over incumbent store-based retailers. This trend is most prominent in urban centers across North America and Europe, driven by digitally native consumers.
Hosiery Market Segmentation
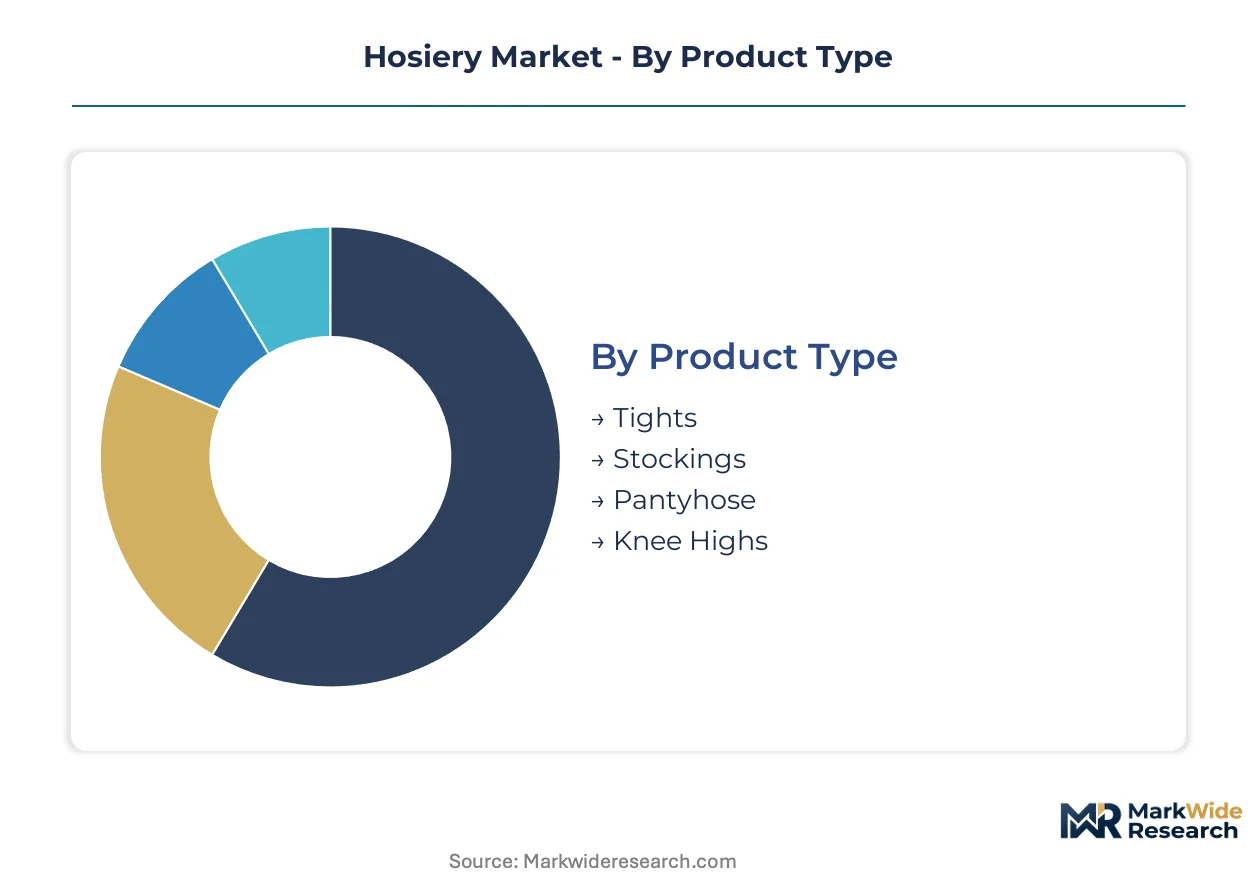
Hosiery market segmentation provides a granular view of consumer preferences and operational dynamics, revealing distinct pathways for product development and market penetration. Understanding these divisions helps manufacturers align production with specific demand patterns and distribution efficiencies. This detailed breakdown highlights areas of concentrated growth and competitive intensity across various product types, materials, end-users, and distribution channels.
Product Type:
Segments within hosiery product types exhibit varying degrees of substitution pressure from alternative apparel categories.
- Tights:Tights are close-fitting garments covering the body from the waist to the feet, typically made from nylon-spandex blends in various deniers. Demand for tights concentrates in European and North American markets, driven by evolving fashion norms integrating hosiery into professional and casual wear.
- Pantyhose:Pantyhose are sheer, form-fitting garments covering the lower torso and legs, designed for a smooth aesthetic under dresses and skirts. Their demand remains strong in established markets like the United States and Japan, particularly for formal and office settings.
- Stockings:Stockings are individual leg coverings, often held up by garters, catering to specific fashion preferences and intimate apparel segments.
- Knee Highs:Knee highs are shorter hosiery items extending to just below the knee, experiencing renewed interest for comfort and versatility in countries like Germany and France.
Tights anchor the volume base while Knee Highs gain share at the steepest rate.
Material:
Material choices in hosiery reflect a tiered cost structure, balancing performance attributes with raw material expenses.
- Nylon:Nylon is a synthetic polymer prized for its strength, elasticity, and ability to be knitted into sheer fabrics, often blended with other fibers for enhanced properties. Demand for nylon blends is pervasive across all hosiery categories, with significant adoption in Asian manufacturing hubs like China and India due to cost-effectiveness and versatility.
- Spandex:Spandex, also known as elastane, is a highly elastic synthetic fiber providing stretch and shape retention crucial for a comfortable, close fit in hosiery. Its integration is critical for performance hosiery and premium products, particularly in markets like the United States where consumers prioritize comfort and durability.
- Cotton:Cotton offers breathability and softness, primarily used in comfort-focused socks and some casual hosiery, favored in colder climates.
- Wool:Wool provides natural insulation and moisture-wicking properties, serving premium and cold-weather hosiery segments, especially in Scandinavian countries and Canada.
Nylon blends represent the foundational material choice, while sustainable variations of Spandex are experiencing rapid expansion.
End User:
Hosiery end-user segments are defined by distinct application requirements and fashion sensibilities.
- Women:The women's segment encompasses the broadest range of hosiery products, from sheer pantyhose for professional wear to fashion tights and performance legwear. Demand in this segment is robust in markets like India and Brazil, driven by evolving fashion trends and increased participation in professional workforces.
- Men:The men's segment primarily includes dress socks, athletic socks, and some specialized compression hosiery, focusing on comfort, durability, and functional performance. Growth in this segment is notable in developed economies such as the United Kingdom and Australia, influenced by athleisure trends and specialized performance needs.
- Children:Children's hosiery focuses on comfort, durability, and playful designs, catering to everyday wear and special occasions.
- Unisex:Unisex hosiery often includes basic socks, athletic wear, and some casual legwear, emphasizing functional attributes over gender-specific styling.
Women's hosiery constitutes the largest consumer base, with the men's segment showing accelerated growth in specialized product categories.
Distribution Channel:
The volume distribution of hosiery is undergoing a significant transformation, driven by shifts in consumer purchasing habits.
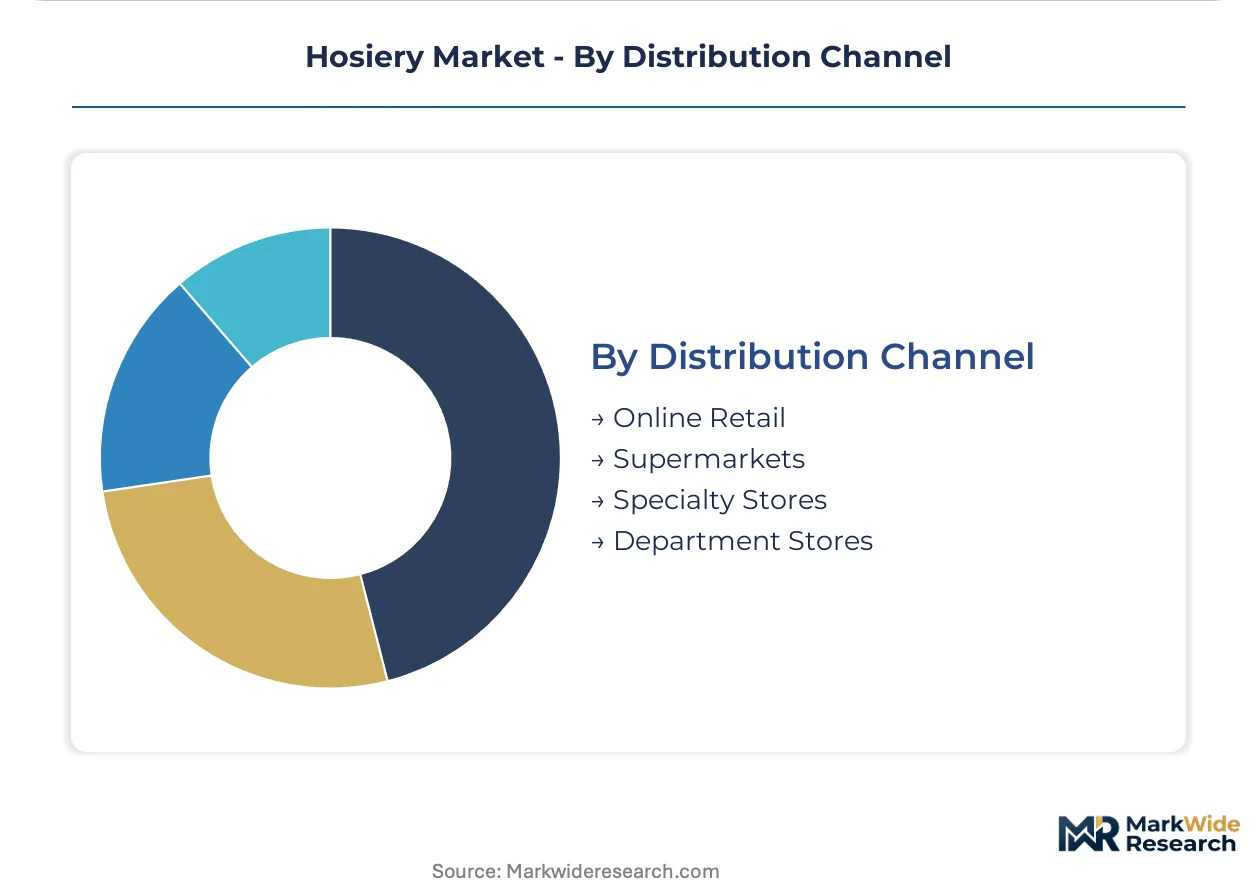
- Online Retail:Online retail platforms provide extensive product selection, competitive pricing, and convenience, enabling direct-to-consumer models and niche brand access. This channel is rapidly gaining share in North America and Europe, supported by digitally native consumers and subscription-based models.
- Supermarkets:Supermarkets and hypermarkets offer everyday hosiery essentials at accessible price points, leveraging high foot traffic and convenience for impulse purchases. This channel maintains significant volume in mass-market segments across countries like Germany and France.
- Specialty Stores:Specialty stores focus on curated collections, premium brands, and personalized service, catering to fashion-conscious consumers seeking unique or luxury items.
- Department Stores:Department stores traditionally offered a wide range of hosiery brands but are experiencing declining share due to competition from online and specialty retailers, particularly in the United States and Canada.
Online Retail is expanding most quickly, while Supermarkets continue to manage substantial sales volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration influences regional hosiery market dynamics, with diverse fashion sensibilities and economic development driving demand across continents. Evolving consumer preferences for comfort and sustainability shape product adoption in specific countries. Regulatory frameworks also guide material innovation and market access for manufacturers.
India
Demand for hosiery in India expands with evolving fashion norms, integrating legwear into professional and casual attire for women. The PLI scheme supports domestic textile manufacturing, encouraging local production capabilities. Delhi-NCR leads in fashion trends and online retail adoption, facilitating broader market access for hosiery brands.
United States
The United States market sustains strong demand for pantyhose in formal settings and experiences growth in performance hosiery segments. The U.S. Federal Trade Commission (FTC) mandates accurate fiber content labeling, ensuring consumer trust and product quality. New York City remains a hub for fashion innovation and specialty retail, influencing hosiery trends.
Germany
Germany shows renewed interest in knee highs, valued for comfort and versatility, alongside robust supermarket sales of everyday hosiery essentials. The European Union’s Ecodesign for Sustainable Products Regulation (ESPR) is pushing for improved durability and recyclability in textile products. North Rhine-Westphalia serves as a significant textile manufacturing and retail distribution center.
China
China represents a critical manufacturing hub for cost-effective nylon blends, serving both domestic consumption and global export markets. Compliance with national GB standards for textiles is essential for market entry and product safety. The Yangtze River Delta region concentrates textile production capabilities, driving innovation in hosiery manufacturing processes.
Hosiery Market Key Industry Players
Player mix skews toward established global brands alongside agile niche specialists, reflecting a tiered market structure. The competitive landscape bifurcates between premium innovators and high-volume mass-market producers. Strategic partnerships and portfolio diversification represent dominant competitive moves among market participants.
On the premium-tier vector, Wolford AG exemplifies a focus on luxury materials and innovative designs for a high-margin niche. Calzedonia S.p.A. occupies a middle ground, anchoring its position through fast-fashion trends and broad accessibility via specialty stores. At the scale-driven end, Hanesbrands Inc. leverages its extensive distribution network and manufacturing scale to serve the price-sensitive segment.
| Leading Market Players |
|---|
| Falke KGaA |
| Spanx, Inc. |
| Hanesbrands Inc |
| Golden Lady Company S.p.A. |
| Calzedonia S.p.A. |
| Jockey International, Inc. |
| Gildan Activewear Inc |
| Renfro Corp. |
| Wolford AG |
Cost & Logistics Intelligence
Substitution of athleisure wear for traditional hosiery reshapes consumer demand patterns and influences pricing strategies across the market. This dynamic affects manufacturing locations and material procurement, especially for mass-market producers.
Pricing Analysis
Cost-plus contracts, often indexed to petroleum derivatives like nylon and spandex, underpin pricing for high-volume hosiery manufacturers. Price differentiation stems from material safety certifications like OEKO-TEX STANDARD 100 and brand premium for luxury items. Pricing pressure intensifies due to raw material volatility and competition from athleisure alternatives. Mass-market consumers exhibit high price sensitivity, while premium buyers prioritize quality and design.
Supply Chain Analysis
Compliance with national GB standards for textiles in China represents a critical chokepoint for market access and product safety for global hosiery brands. Supply concentrates in manufacturing hubs like China and India, drawing from petroleum-derived nylon and spandex. Commodity price volatility for these raw materials poses a structural risk for manufacturers. Downstream distribution runs through rapidly expanding online retail platforms and high-volume supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hosiery market reveals a scarcity in advanced material science and circular economy expertise. This capability gap limits widespread adoption of sustainable materials and innovative product designs.
For Market Incumbents:Compound investment in advanced circular knitting machinery to enhance product durability and aesthetic appeal. This defends against athleisure substitution and enables premium-tier differentiation. Reinforce supply chain transparency and OEKO-TEX certification to meet stringent chemical regulations from bodies like ECHA. Develop mono-material designs to align with Ecodesign for Sustainable Products Regulation (ESPR).
For New Entrants and Emerging Players:Differentiate on performance and wellness attributes, targeting niche sports and medical applications with specialized hosiery. Focus on smart textile integration, incorporating micro-sensors for health monitoring to create unique value propositions. The most penetrable segment lies within digitally native consumers in urban centers across North America and Europe. Leverage subscription-based direct-to-consumer models for predictable revenue streams and customer loyalty.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors agile niche specialists with strong sustainability credentials and digital distribution. Long-term viability remains strong, driven by evolving fashion norms and consumer demand for eco-friendly products. Target acquisition profiles should include direct-to-consumer brands leveraging subscription models or innovators in smart textile integration. Watch for accelerated adoption rates of recycled nylon and bio-derived spandex as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | Aligns brands with consumer and regulatory pressure for circular economy principles. |
| Direct-to-Consumer Model Adoption | Cultivates customer loyalty and expands market access for niche hosiery products. |
| Advanced Knitting Technology Integration | Enables production of ultra-sheer, durable, and complex seamless garments. |
| Smart Textile Product Launch | Opens new revenue streams in health monitoring and connected fitness applications. |
| Bio-derived Material Sourcing | Reduces reliance on petroleum derivatives and enhances environmental compliance. |
Research Approach
The analysis maps hosiery product types, end-user segments, and material categories, each validated through extensive primary interviews. Industry stakeholders included hosiery manufacturers, material suppliers, retail buyers, and regulatory compliance officers. Secondary validation drew from trade association reports, national GB standards for textiles, ECHA reports, and customs data. This approach utilized both bottom-up and top-down triangulation to ensure data accuracy.
Forecast outputs underwent rigorous consistency checks against external benchmarks and historical market performance across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, end-user, and distribution channel, alongside regional regulatory frameworks. Compound annual growth rates were derived from a multi-variable regression analysis. Industry-specific inputs included denier weight trends and sustainable material adoption rates.
Material uncertainties — including geopolitical shifts affecting trade and unforeseen material science breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding current regulatory trajectories and consumer preference evolution. Practitioners should keep alternative scenarios live as supply chain stability and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Zipper Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Stockings Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Cooling Apparel Market