
 Hunting Apparel Market | 2026-2036
Hunting Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Hunting Apparel Market Intelligence
Subscription-based scent-control replenishment programs is pivoting how manufacturers monetize repeat purchases. Sitka Gear leverages direct-to-consumer digital channels to sustain premium positioning across technical outerwear tiers. Kuiu anchors its growth in ultralight mountain hunting specialization with vertically controlled fabric sourcing. First Lite differentiates through proprietary merino wool blends and pattern ecosystems that command outfitter loyalty.
Hunting apparel denotes purpose-engineered garments designed for concealment, thermoregulation, and scent suppression during pursuit of wild game, typically incorporating waterproof-breathable membranes rated to 20,000mm hydrostatic head and activated-carbon odor-adsorption layers. Polyester and synthetic material segments lead volume as hunters prioritize quick-dry performance over traditional cotton in variable conditions. Application demand concentrates in big game and waterfowl categories where seasonal exposure severity justifies technical investment and replacement cycles compress.
Federal land access policies administered by the US Forest Service and Bureau of Land Management shape hunter participation rates and regional demand distribution across American public lands. EPA regulations on perfluorinated chemical treatments in durable water repellent finishes are forcing reformulation of waterproofing chemistries throughout synthetic outerwear supply chains. State wildlife agencies set tag allocations and season structures that directly determine replacement gear timing for resident and non-resident hunters. Stakeholders must monitor evolving PFAS restriction timelines and land-use designations that alter hunter density and apparel wear rates.
Market Dynamics
PFAS phase-out mandates from the EPA are forcing waterproofing chemistry reformulation across synthetic outerwear supply chains, compressing product development timelines while elevating R&D costs for manufacturers dependent on legacy durable water repellent treatments.
Growth Catalysts
- Merino wool technical blends:Proprietary fiber combinations from New Zealand and Australian suppliers deliver odor resistance and thermoregulation that synthetic alternatives struggle to match in backcountry conditions.
- Rocky Mountain West hunter density:Colorado, Idaho, and Montana tag allocations sustain replacement gear cycles among resident and non-resident big game hunters.
- USDA Forest Service access maintenance:Trailhead infrastructure investments and seasonal road openings preserve hunter participation rates on federal lands.
Market Restraints
- Activated-carbon sourcing concentration:Specialized odor-adsorption media production concentrates among limited North American suppliers, creating input vulnerability.
- EPA PFAS restriction timeline uncertainty:Evolving state-level bans ahead of federal harmonization force parallel compliance pathways and inventory obsolescence risk.
- Technical skill gaps in domestic cut-and-sew:Apparel manufacturing labor pools in the Upper Midwest have not rebounded to support reshoring initiatives.
Strategic Opportunities
- Direct-to-consumer scent-control subscriptions:Replenishment programs for carbon-filter garments and laundry additives capture lifetime value beyond initial outerwear sales.
- Waterfowl category thermal innovation:Late-season marsh exposure severity justifies premium insulation investment among duck and goose hunters in the Prairie Pothole Region.
- State wildlife agency digital tag systems:Real-time draw result notifications compress gear purchase timing and enable predictive inventory positioning.
Industry Challenges
- 20,000mm hydrostatic head certification backlog:Third-party waterproof-breathable membrane testing capacity constraints delay new product launches.
- Legacy retailer inventory reconciliation:Wholesale channel partners struggle to align preseason orders with compressed consumer demand signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hunting Apparel Market |
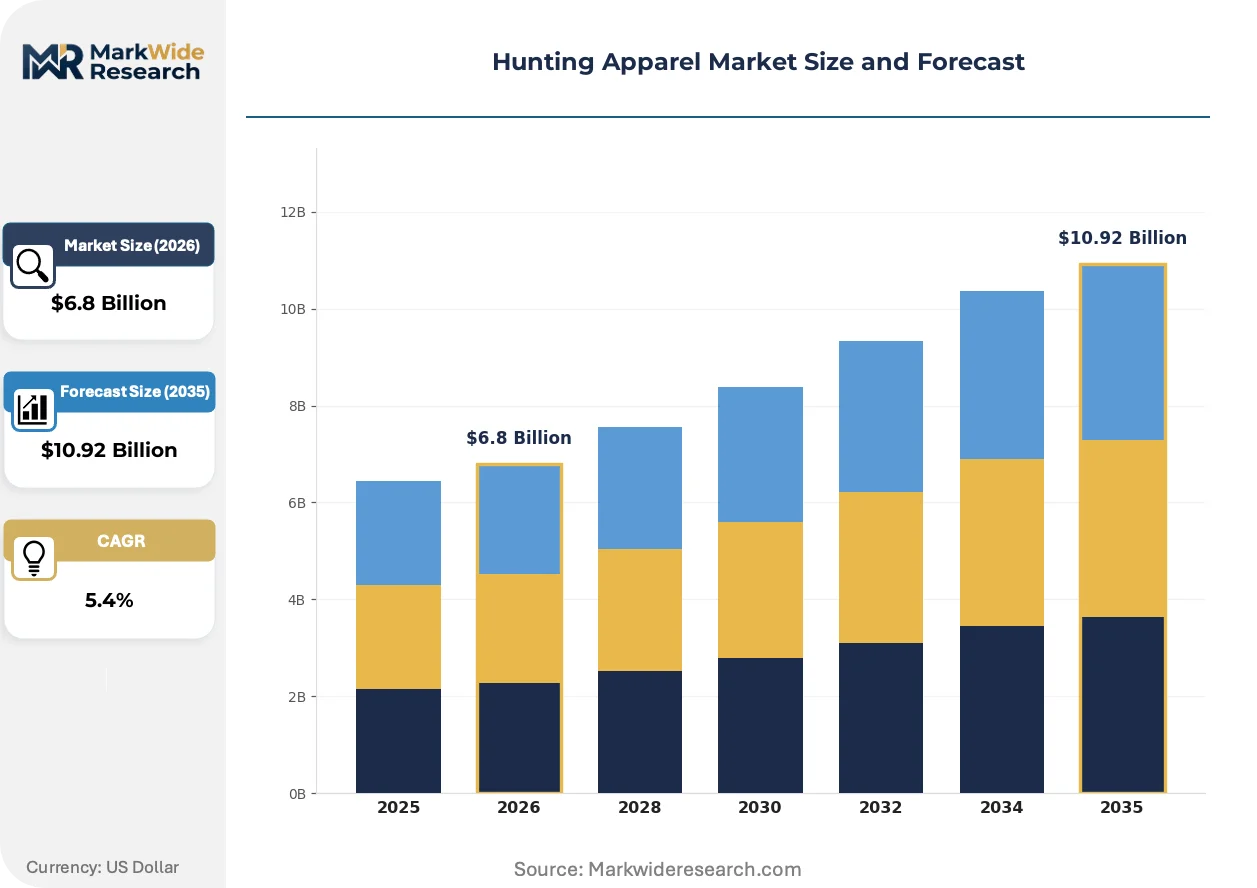
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Jackets, Pants, Base Layers, Headwear Material: Cotton, Polyester, Wool, Synthetic Application: Waterfowl, Big Game, Upland Game, Turkey Customer Type: Professional Hunters, Recreational Hunters, Outfitters, Collectors |
| Companies Covered | Sitka Gear, Danner, Cabela's (Bass Pro Shops), 5.11 Tactical, Ariat International, Under Armour, First Lite, ScentLok Technologies, Kuiu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hunting Apparel Market Strategic Shifts & Innovations
Synthetic fabric innovation, regulatory chemistry reformulation, and subscription-based replenishment models are converging to reshape how technical hunting apparel reaches end users and retains them over multi-year ownership cycles.
Graphene-infused membrane technologies are electrifying thermal management capabilities in base and mid-layer constructions. Backcountry hunters in the Intermountain West are adopting these conductive fabrics at accelerating rates. This electrification is compressing the performance gap between ultralight synthetic systems and traditional heavyweight insulation, enabling single-jacket solutions across broader temperature ranges.
EPA restrictions on perfluorinated chemicals in durable water repellent finishes are forcing chemistry suppliers to accelerate silicone and hydrocarbon-based alternatives. The industrial consequence is a 12-18 month product recertification burden for outerwear manufacturers. Big game synthetic shell producers in the United States are responding with accelerated in-house testing protocols and supply chain dual-sourcing to maintain seasonal launch windows.
Subscription scent-control replenishment is displacing traditional retail repurchase patterns among dedicated hunters. Digital-native brands are capturing outfitter loyalty through automated carbon-filter replacement and specialized laundry additive programs. This behavioral shift concentrates most visibly among Rocky Mountain elk hunters who prioritize odor suppression over pattern concealment in high-pressure hunting units.
Hunting Apparel Market Segmentation
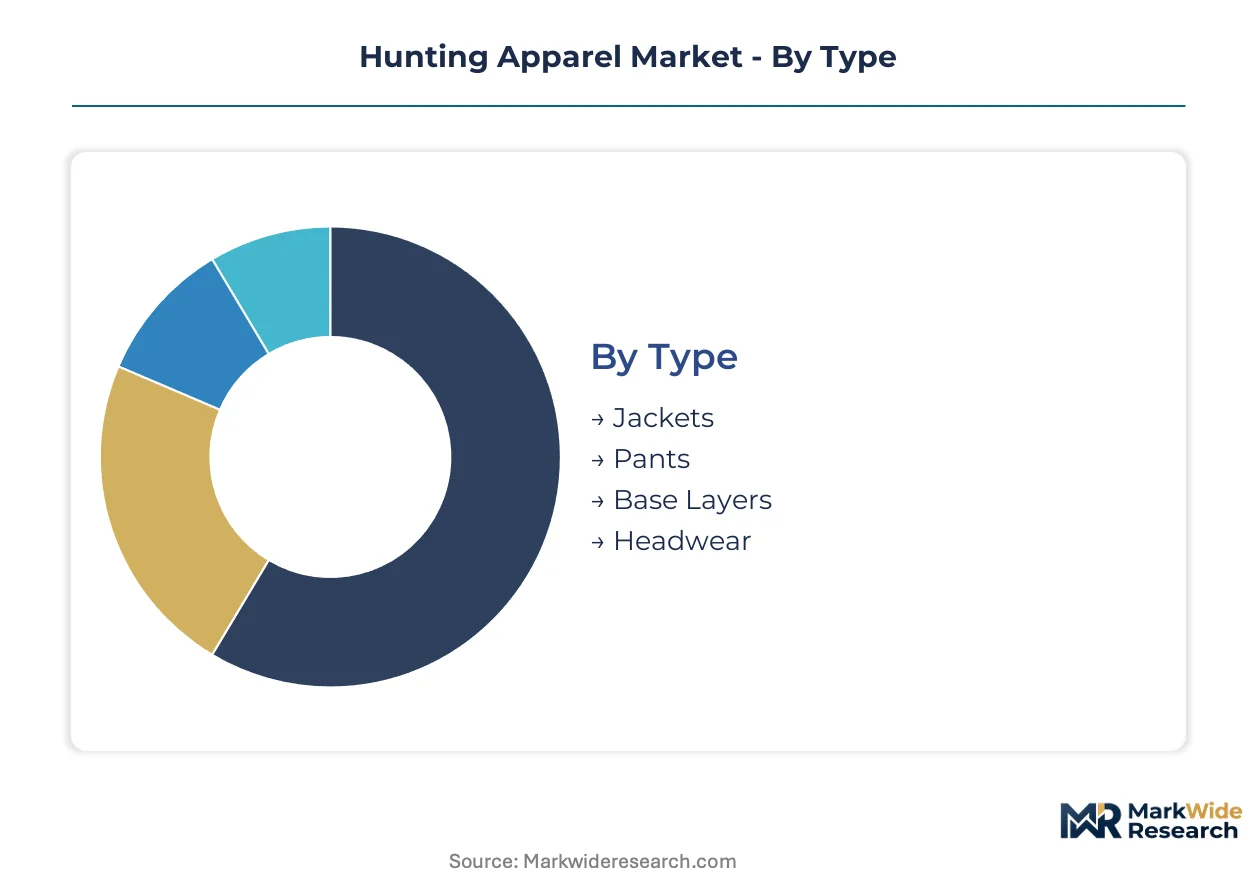
Hunting apparel purchasing hinges on matching technical performance to specific environmental exposure and game pursuit patterns. Segmentation reveals how material innovation, application severity, and customer expertise tier combine to determine price realization and replacement frequency across the category.
Type:
Layering system architecture drives purchase sequencing, with outer shell investment preceding mid-layer and base layer additions.
- Jackets:Waterproof-breathable shells rated to 20,000mm hydrostatic head anchor system investment. Demand concentrates in the Rocky Mountain West where late-season elk exposure justifies premium membrane technology and replacement cycles compress to three-year intervals.
- Base Layers:Merino wool and synthetic moisture-wicking constructions manage thermoregulation during high-exertion spot-and-stalk pursuits. Recreational hunters in the Upper Midwest drive volume through seasonal layering system builds preceding whitetail firearm seasons.
- Pants:Reinforced knee and seat panels accommodate brush penetration and seated glassing positions across varied terrain.
- Headwear:Facemasks and beanies complete concealment systems with scent-control integration for close-quarter archery engagements.
Jackets lead on scale; base layers lead on momentum.
Material:
Performance requirements in wet climates have reordered material preference hierarchies away from traditional natural fibers.
- Synthetic:Polyester and nylon blends deliver quick-dry performance and durability in variable precipitation. Waterfowl hunters in the Prairie Pothole Region prioritize synthetic insulation retention when submerged in marsh environments.
- Polyester:Engineered filament constructions dominate volume through cost-accessible moisture management and odor-resistant finishing treatments.
- Wool:Merino fiber blends from New Zealand and Australian suppliers provide odor resistance and temperature modulation in backcountry conditions where washing access is limited.
- Cotton:Traditional duck canvas and flannel constructions persist in casual hunting contexts and heritage aesthetic segments despite technical limitations in wet conditions.
Polyester dominates absolute volume; synthetic climbs the fastest as performance demands intensify.
Application:
Exposure severity and season length determine technical investment depth across game pursuit categories.
- Big Game:Extended backcountry expeditions require complete layering systems with packable insulation and weather protection. Colorado, Idaho, and Montana tag allocations sustain replacement gear cycles among resident and non-resident hunters pursuing elk and mule deer.
- Waterfowl:Late-season marsh hunting demands waterproof insulation and specialized concealment patterns for open-water environments. The Prairie Pothole Region from North Dakota through Iowa generates concentrated demand for thermal innovation in wader-compatible outerwear.
- Upland Game:High-activity bird hunting over dogs prioritizes breathability and brush resistance in milder conditions.
- Turkey:Spring woodland pursuits emphasize complete concealment and minimal movement signature in close-range engagements.
Big game commands highest per-hunter spend; waterfowl shows steepest expansion trajectory.
Customer Type:
Expertise level and economic dependence on hunting outcomes segment purchasing behavior and brand loyalty patterns.
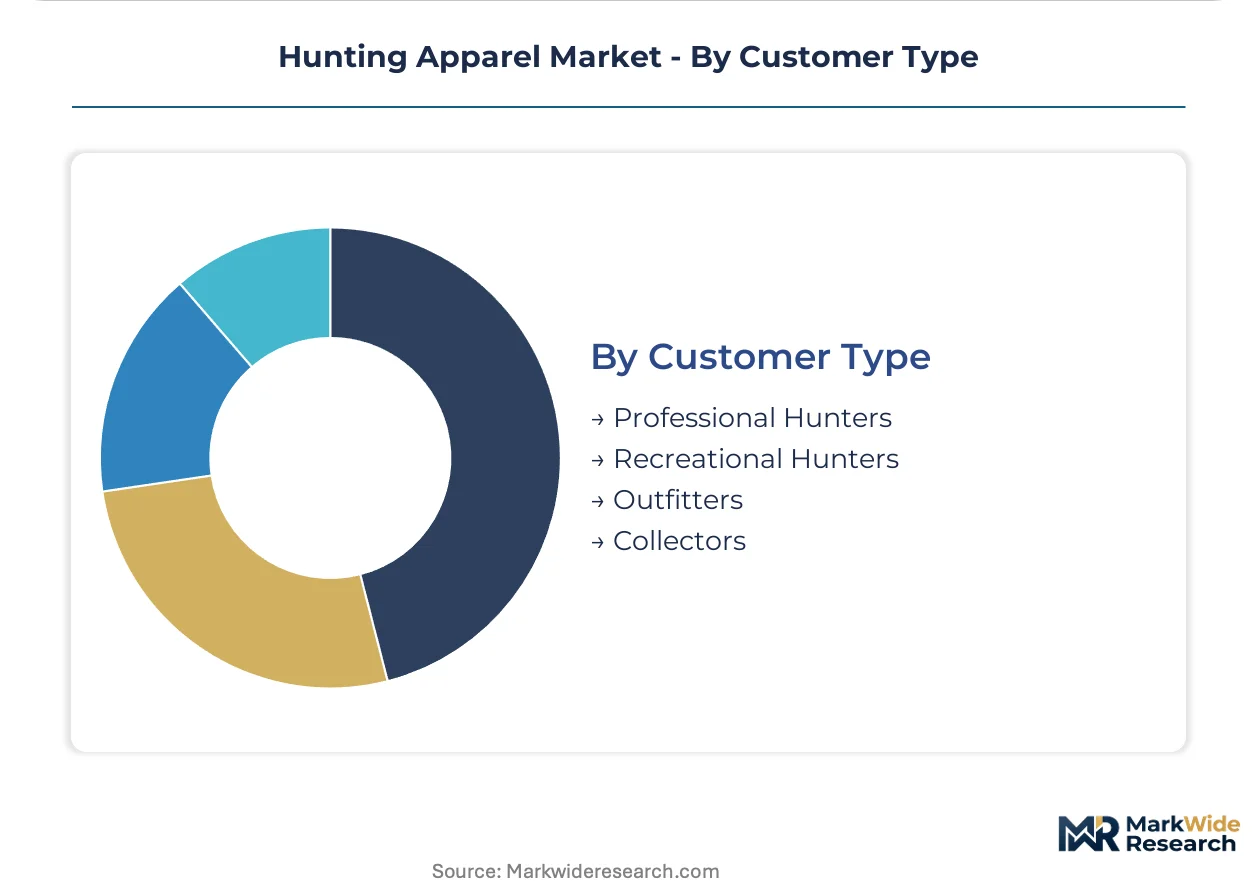
- Recreational Hunters:Weekend and vacation hunters build systems progressively, prioritizing versatility across multiple species and seasons. This segment drives volume through entry-to-mid-tier product adoption and seasonal pre-purchase timing aligned with state wildlife agency tag drawings.
- Professional Hunters:Guides and outfitters require redundant systems for client use and personal durability under daily field conditions.
- Outfitters:Commercial operations standardize client apparel to ensure consistent field performance and brand presentation.
- Collectors:Limited-edition pattern releases and heritage brand collaborations attract non-field purchasing for display and archival purposes.
Recreational hunters anchor volume scale; professional hunters concentrate margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hunter participation rates substantially exceed Canadian levels, though both markets concentrate demand in distinct geographic clusters shaped by federal land access and provincial licensing frameworks.
United States
Colorado, Idaho, and Montana tag allocations sustain replacement gear cycles among resident and non-resident big game hunters. EPA regulations on perfluorinated chemical treatments in durable water repellent finishes are forcing reformulation of waterproofing chemistries throughout synthetic outerwear supply chains. Manufacturing clusters in the Upper Midwest and Pacific Northwest concentrate technical fabric finishing and cut-and-sew operations serving domestic brands.
Canada
Prairie provinces and British Columbia generate concentrated demand for thermal innovation in late-season waterfowl and big game pursuits. Health Canada and PMRA coordinate pesticide and chemical treatment standards affecting scent-control garment formulations. Toronto and Vancouver serve as distribution hubs for technical outerwear reaching outfitters across the Canadian Shield and Rocky Mountain regions.
Germany
Recreational hunting traditions in Bavaria and Baden-Württemberg sustain steady demand for premium concealment systems and weather protection. ECHA REACH regulations govern chemical treatments in textile finishes, creating compliance requirements for imported technical apparel. Industrial clusters around Stuttgart and Munich host specialized textile finishing operations serving Central European hunting markets.
Australia
Victoria and New South Wales generate demand for lightweight, breathable systems suited to variable climate conditions across diverse terrain. The Therapeutic Goods Administration (TGA) and national chemical regulator oversee treatment standards affecting odor-adsorption technologies. Melbourne-based distributors anchor supply chains reaching hunting operators across the southeastern states and Tasmania.
United Kingdom
Scotland and rural England sustain heritage-driven demand for traditional wool constructions alongside technical synthetic adoption. DEFRA and the Environment Agency coordinate land access and wildlife management policies affecting hunter participation rates. Manchester and Leeds textile centers maintain finishing capabilities for weatherproof membrane applications serving domestic and export markets.
Hunting Apparel Market Key Industry Players
Top-tier vendors anchor premium technical positioning, while mid-market specialists and heritage retailers occupy differentiated tiers. The vendor base stratifies across direct-to-consumer digital natives, vertically integrated specialists, and multi-channel outdoor retailers. Three archetypes dominate: ultralight mountain specialists, merino wool innovators, and scent-control technology integrators. Competitive moves concentrate on direct-to-consumer channel expansion and proprietary fabric sourcing partnerships.
Among direct-to-consumer specialists, Sitka Gear, Kuiu, and First Lite exemplify distinct strategic positioning within technical hunting apparel. Sitka Gear occupies a position emphasizing digital channel control and premium outerwear tiering. Kuiu represents the ultralight mountain specialization archetype with emphasis on controlled fabric sourcing. First Lite anchors the merino wool innovation segment through proprietary fiber blends. These three companies collectively illustrate how technical specialization, supply chain control, and pattern ecosystem development differentiate positioning in a market where recreational hunters drive volume and professional users concentrate margin capture.
| Leading Market Players |
|---|
| Sitka Gear |
| Danner |
| Cabela's (Bass Pro Shops) |
| 5.11 Tactical |
| Ariat International |
| Under Armour |
| First Lite |
| ScentLok Technologies |
| Kuiu |
| Others |
Cost & Logistics Intelligence
Recreational hunter demand for PFAS-free waterproofing in the Rocky Mountain West is forcing chemistry suppliers to retool production lines and absorb certification costs, which manufacturers pass through as tiered premiums on technical outerwear.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for synthetic base layer production, compressing margins on entry-tier polyester garments while insulating premium membrane-equipped shells. Three-tier pricing structure across premium, standard, and economy levels separates Sitka Gear's direct-to-consumer positioning from wholesale-dependent heritage brands. Cost compression in mid-tier waterproof-breathable shells is intensifying because EPA-mandated chemistry reformulation demands parallel R&D investment. Recreational hunters in the Upper Midwest exhibit highest price sensitivity, while professional outfitters in Colorado and Idaho demonstrate lowest sensitivity due to client-facing durability requirements.
Supply Chain Analysis
Merino fiber supply rests on New Zealand and Australian wool processors, with activated-carbon odor-adsorption media production concentrating among limited North American suppliers. Synthetic fabric mills in Vietnam, China, and Bangladesh feed cut-and-sew operations in the Upper Midwest and Pacific Northwest. Single-source vulnerability in specialized membrane laminates creates bottlenecks when third-party hydrostatic head certification backlogs delay seasonal launches. Distribution runs through direct-to-consumer digital channels for premium specialists and multi-channel outdoor retailers for volume brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hunting apparel market functions as a stable compounder, with recreational hunter participation in North America generating predictable replacement cycles tied to state wildlife agency tag allocations.
For Market Incumbents: Hedge against EPA PFAS restriction timeline uncertainty by dual-sourcing silicone and hydrocarbon-based water repellent chemistries from multiple suppliers. Secure backward integration into merino wool fiber processing to insulate margin capture from New Zealand and Australian supply concentration. Channel control through direct-to-consumer platforms preserves pricing power against wholesale inventory reconciliation risks. For New Entrants and Emerging Players: Begin with waterfowl category thermal innovation in the Prairie Pothole Region, where late-season marsh exposure severity justifies premium insulation investment and incumbent penetration remains fragmented. Target subscription-based scent-control replenishment programs to capture lifetime value beyond initial outerwear sales. Outfitter loyalty programs anchored in automated carbon-filter replacement offer a defensible go-to-market angle against established pattern ecosystems. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically controlled fabric sourcing specialists who have secured proprietary merino wool blends or graphene-infused membrane partnerships. Long-term viability hinges on multi-year ownership cycle retention through replenishment models rather than transactional seasonal purchases. Watch state wildlife agency digital tag system adoption as an inflection indicator compressing gear purchase timing and enabling predictive inventory positioning.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Reformulation | EPA mandates force 12-18 month product recertification timelines across synthetic outerwear supply chains. |
| Direct-to-Consumer Channel Expansion | Sitka Gear's digital-native model captures outfitter loyalty through controlled pricing and pattern ecosystem development. |
| Subscription Scent-Control Programs | Automated carbon-filter replacement displaces traditional retail repurchase patterns among dedicated Rocky Mountain elk hunters. |
| Proprietary Merino Wool Sourcing | First Lite's New Zealand and Australian fiber partnerships create input security that synthetic competitors cannot replicate. |
| Graphene-Infused Membrane Development | Conductive fabric electrification compresses the performance gap between ultralight synthetics and heavyweight insulation systems. |
Research Approach
Multiple input streams — primary interviews with brand product directors, state wildlife agency licensing administrators, and outfitter operations managers; secondary synthesis of EPA chemical restriction filings, USDA Forest Service access reports, and state tag allocation databases; plus customs records tracking synthetic fabric imports — were reconciled through bottom-up demand modeling and top-down market sizing triangulation.
Historical participation rates across the analysis window were cross-referenced against panel input from procurement leads at multi-channel outdoor retailers and technical R&D directors at membrane suppliers. Segmentation dimensions modeled include layering system architecture, material performance tier, game pursuit category, and customer expertise level. CAGRs were derived from replacement cycle compression analysis and geographic hunter density projections, with federal land access policy shifts and PFAS regulatory timelines serving as key scenario inputs.
Caveats apply where EPA PFAS restriction acceleration or state-level ban harmonization could materially shift the outlook for waterproof-breathable membrane availability and pricing. A small set of named triggers — federal land access designation changes, activated-carbon supply disruptions, and digital tag system adoption rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Maternity Leggings Market