
 Asia-Pacific Digital Clothing Market | 2026-2036
Asia-Pacific Digital Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Clothing Market Analytics
Buyer concentration across Asia-Pacific gaming ecosystems is rebalancing as platform operators fragment into specialized metaverse environments while consolidated fashion houses deepen direct-to-avatar relationships. Nike, Inc. leverages its SNKRS digital infrastructure to anchor virtual sneaker drops across Japanese and South Korean mobile ecosystems. The Fabricant Agency B.V. competes through open-source 3D garment protocols that extend designer access to blockchain-verified ownership layers. Guccio Gucci S.p.A. (Kering Group) dominates luxury digital collectible drops, positioning its Vault platform as a curated gateway for scarce virtual fashion assets.
Asia-Pacific digital clothing encompasses computer-generated garments rendered through 3D modeling engines, composed of polygon mesh structures with physics-based shading for drape simulation and real-time display across virtual environments; these assets serve commercial purposes spanning avatar customization, virtual runway presentations, and blockchain-authenticated ownership transfer. Virtual garments currently lead transaction volume across online marketplaces, though augmented reality outfits for social media platforms represent the fastest-expanding margin pool as camera-native commerce proliferates in China and India. Blockchain-backed provenance systems for digital accessories command premium pricing, while artificial intelligence-driven sizing algorithms reduce return friction for retailers experimenting with virtual try-on workflows.
China's SAMR enforces digital asset classification standards that determine whether virtual garments qualify as securities, while South Korea's financial regulators scrutinize blockchain-based fashion NFTs under evolving virtual asset frameworks. Japan's consumer protection agencies monitor AR outfit transactions for misleading representation, particularly where digital-physical equivalence claims circulate on social media platforms. Stakeholders must track how divergent national treatments of digital ownership reshape cross-border marketplace architecture and designer royalty enforcement mechanisms.
Market Dynamics
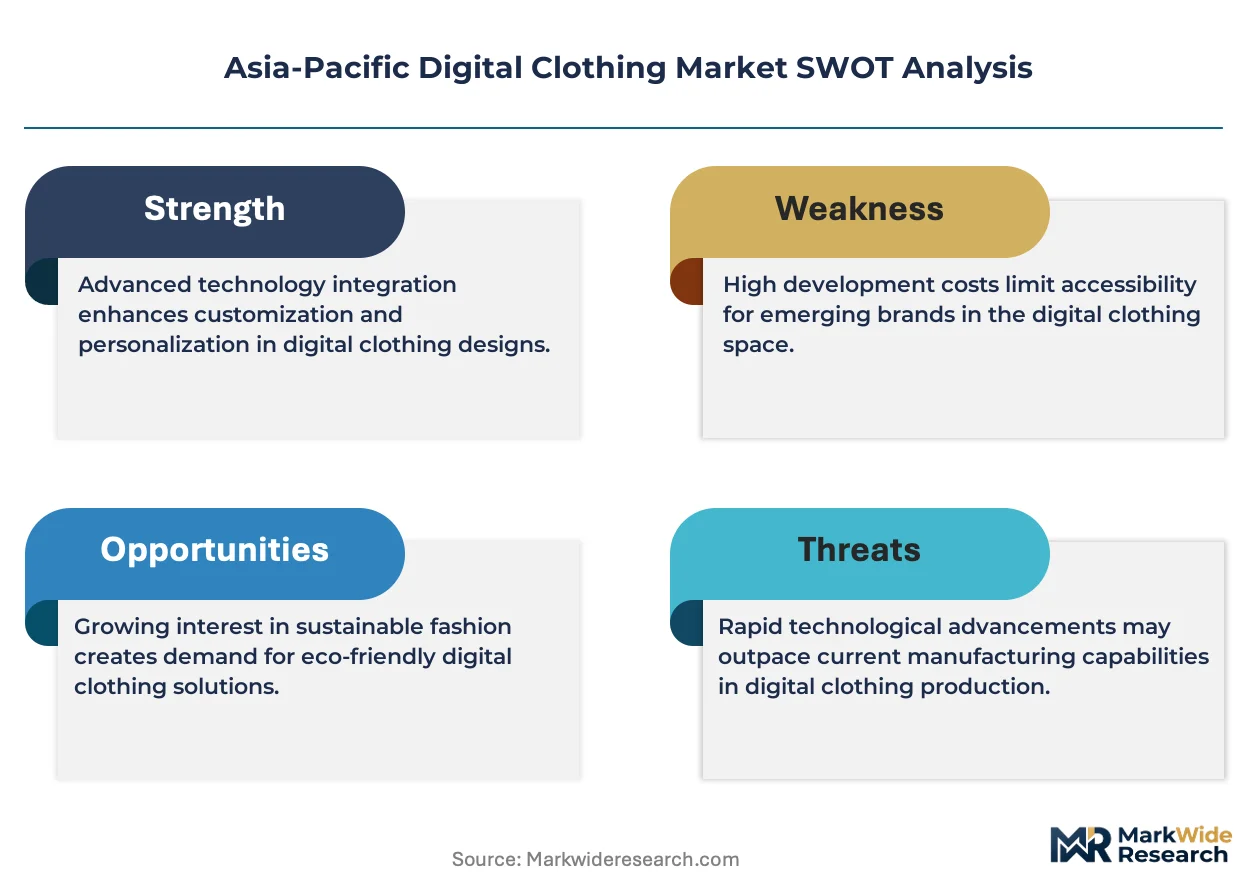
Platform fragmentation across Southeast Asian gaming ecosystems is compressing margins for middleware providers while concentrating buyer power among avatar-customization aggregators. China's SAMR digital asset classification and South Korea's metaverse investment frameworks are forcing compliance recalibration across blockchain-backed garment provenance systems.
Growth Catalysts
- VTuber Culture Expansion:Japan's creator economy sustains demand for AR outfits and digital accessories through virtual influencer monetization pipelines.
- MIIT Asset Guidelines:China's Ministry of Industry and Information Technology standards clarify virtual garment classification, reducing legal uncertainty for domestic platforms.
- Physics-Based Rendering:Real-time cloth simulation engines enable drape-accurate virtual try-on workflows for mobile-first fashion retailers.
Market Restraints
- Blockchain Energy Costs:Proof-of-work consensus mechanisms for NFT garment minting face input cost volatility as regional electricity tariffs fluctuate.
- Platform Dependency Risk:Avatar customization revenue concentrates within three dominant Southeast Asian gaming ecosystems, creating supplier concentration exposure.
- Cross-Border Royalty Enforcement:Divergent national treatments of digital ownership fragment designer compensation mechanisms across Asia-Pacific jurisdictions.
Strategic Opportunities
- India's Camera-Native Commerce:Social media platform AR filters for digital clothing remain underpenetrated relative to China, presenting first-mover expansion potential.
- AI-Generated Pattern Design:Machine learning diffusion models trained on textile archives converge with 3D garment pipelines, accelerating designer prototyping cycles.
- South Korea's Metaverse Tax Incentives:The country's virtual asset investment frameworks subsidize domestic platform development for blockchain-verified fashion marketplaces.
Industry Challenges
- 3D Technical Artist Scarcity:Specialized talent capable of polygon optimization and physics-based shading for real-time engines commands premium compensation, constraining studio scaling.
- Interoperability Standard Delays:Absence of unified avatar format protocols forces redundant asset creation across incompatible metaverse environments.
- SAMR Compliance Timelines:China's digital asset security classification reviews extend platform launch schedules, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Clothing Market |
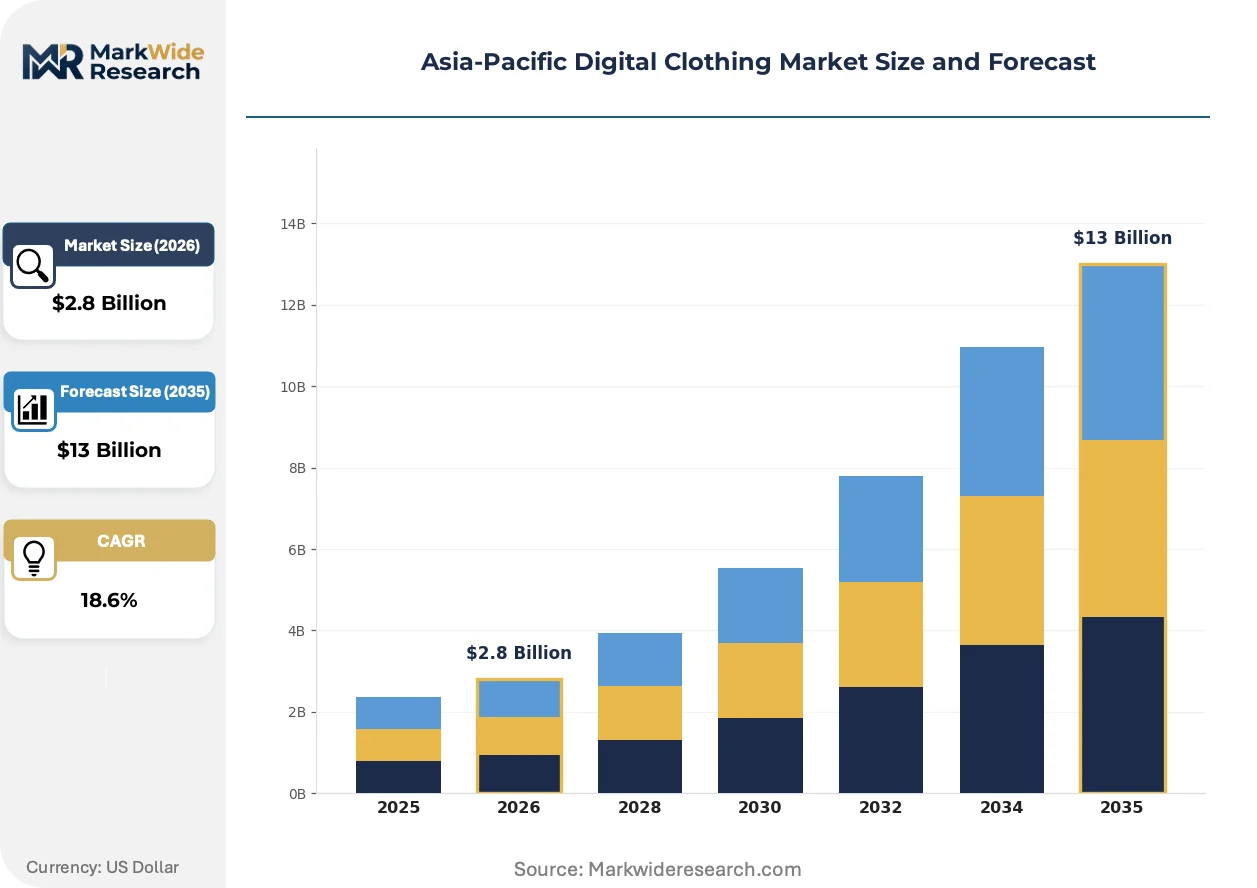
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Garments, Augmented Reality Outfits, 3D Printed Apparel, Digital Accessories Customer Type: Fashion Enthusiasts, Gamers, Designers, Retailers Distribution Channel: Online Marketplaces, Mobile Apps, Brand Websites, Social Media Platforms Technology: 3D Modeling, Virtual Reality, Blockchain, Artificial Intelligence |
| Companies Covered | Adidas AG, Nike, Inc., LVMH SE, H&M Group, The Fabricant Agency B.V., More Dash, Inc. (DressX), Auroboros Ltd., Guccio Gucci S.p.A. (Kering Group), Dolce & Gabbana S.r.l., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Clothing Market Evolving Landscape
Generative artificial intelligence is compressing garment design cycles while fragmenting creator tool access across amateur and professional segments. Physics simulation fidelity improvements enable real-time drape behavior previously restricted to offline rendering pipelines.
Blockchain-based provenance infrastructure is decentralizing ownership verification for digital fashion assets. Japanese VTuber agencies and South Korean idol management firms adopt these systems for limited-edition virtual merchandise drops. The shift compresses reliance on centralized platform authentication, enabling peer-to-peer secondary markets for avatar accessories.
South Korea's financial regulators scrutinize blockchain-based fashion NFTs under evolving virtual asset frameworks established by the Financial Services Commission. The industrial consequence elevates compliance costs for domestic platforms while creating competitive moats for firms with established legal infrastructure. Domestic metaverse operators respond by segregating NFT functionality into regulated subsidiaries.
Social media platforms in China and India displace dedicated virtual fashion marketplaces as primary discovery channels for AR outfit acquisition. ByteDance and Kuaishou integrate camera-native commerce workflows that bypass standalone app downloads. This channel shift concentrates transaction volume where user attention already aggregates, marginalizing independent marketplace operators.
Asia-Pacific Digital Clothing Market Segmentation
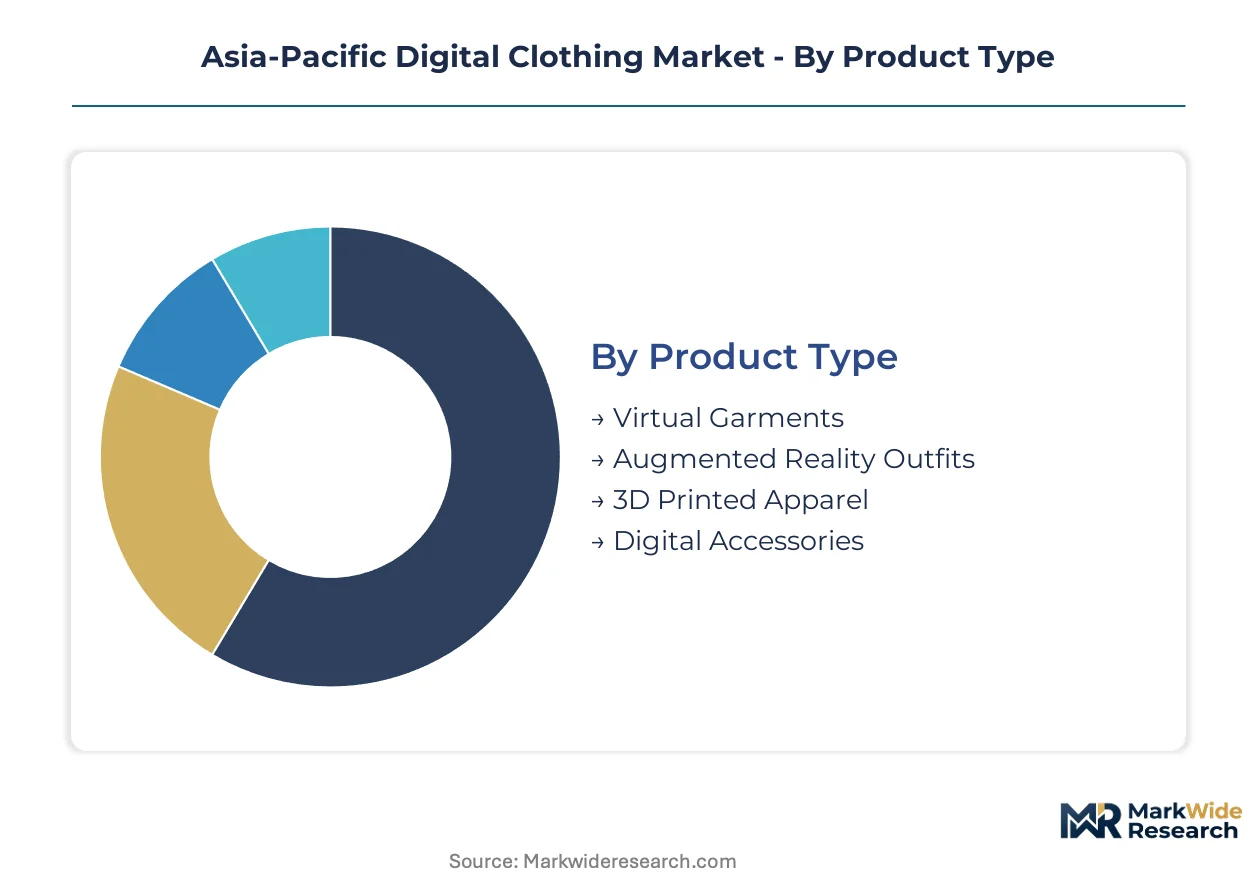
Asia-Pacific digital clothing segments reflect divergent technical maturity and buyer sophistication. Virtual garment pipelines serve gaming ecosystems with established monetization, while AR outfit adoption tracks social media platform expansion across emerging economies.
Product Type:
Cost tier differentiation separates mass-market avatar customization from premium digital collectible markets.
- Virtual Garments:Polygon mesh structures with physics-based shading enable real-time drape simulation across gaming engines. Demand concentrates in Japan's VTuber agencies and South Korean idol management firms where avatar customization drives recurring merchandise revenue.
- Augmented Reality Outfits:Camera-native overlays integrate with social media platform filters for instant try-on sharing. China's ByteDance and India's emerging short-video ecosystems expand adoption fastest as mobile-first consumers bypass dedicated marketplace apps.
- 3D Printed Apparel:Digital-to-physical workflows connect virtual design files with additive manufacturing services.
- Digital Accessories:Blockchain-verified ownership layers command premium pricing for scarce virtual items.
Volume sits with Virtual Garments; growth tilts toward Augmented Reality Outfits.
Customer Type:
Application focus varies from creator monetization to enterprise workflow integration.
- Gamers:Avatar customization spending concentrates within three dominant Southeast Asian gaming ecosystems where platform operators fragment into specialized metaverse environments. China's MIIT guidelines on digital asset classification reshape compliance requirements for blockchain-backed inventory.
- Fashion Enthusiasts:Collector demand for scarce digital assets drives premium pricing on curated marketplace platforms. Japan's creator economy sustains purchasing through virtual influencer monetization pipelines.
- Designers:Prototyping tool adoption accelerates as AI-generated pattern design converges with 3D garment pipelines.
- Retailers:Virtual try-on workflows reduce return friction for mobile-first fashion commerce.
Revenue concentrates with Gamers; margin expansion favors Fashion Enthusiasts.
Distribution Channel:
Geography determines platform preference between integrated social commerce and standalone marketplace discovery.
- Social Media Platforms:ByteDance and Kuaishou displace dedicated marketplaces as primary AR outfit discovery channels in China. Camera-native commerce workflows bypass standalone app downloads, concentrating transaction volume where user attention already aggregates.
- Mobile Apps:Nike's SNKRS infrastructure anchors virtual sneaker drops across Japanese and South Korean mobile ecosystems. Platform-specific loyalty programs deepen direct-to-avatar relationships.
- Online Marketplaces:Open-source 3D garment protocols extend designer access to blockchain-verified ownership layers.
- Brand Websites:Curated drops for luxury digital collectibles leverage scarcity mechanics and gated access.
Transaction volume flows through Social Media Platforms; brand control strengthens via Mobile Apps.
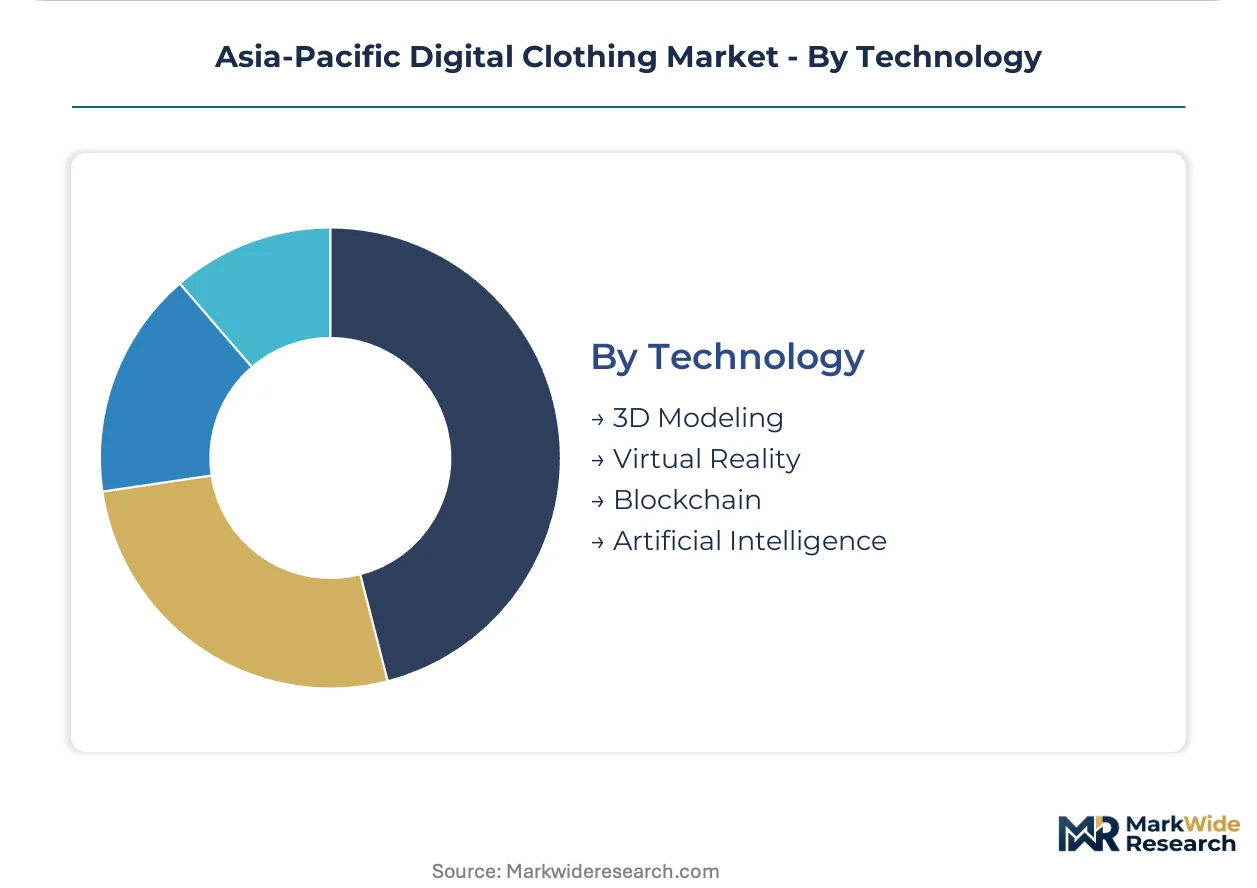
Technology:
Maturity gaps separate proven rendering pipelines from emerging infrastructure layers.
- 3D Modeling:Polygon optimization and physics-based shading for real-time engines commands premium compensation for specialized technical artists. Studio scaling constraints persist as talent scarcity limits production capacity expansion.
- Blockchain:Decentralized ownership verification compresses reliance on centralized platform authentication. South Korea's Financial Services Commission scrutinizes fashion NFTs under evolving virtual asset frameworks, elevating compliance costs for domestic operators.
- Virtual Reality:Hardware penetration limitations restrict immersive fashion presentation to early adopter segments.
- Artificial Intelligence:Machine learning diffusion models trained on textile archives accelerate designer prototyping cycles.
Production depends on 3D Modeling; infrastructure investment targets Blockchain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific digital clothing demand concentrates in Japan's VTuber economy, China's social commerce ecosystems, and South Korea's idol management pipelines, with regulatory divergence across these markets fragmenting cross-border ownership enforcement.
China
ByteDance and Kuaishou drive AR outfit adoption through camera-native commerce workflows that bypass standalone marketplace apps. SAMR's digital asset classification standards determine whether virtual garments qualify as securities, extending platform launch timelines. Shanghai and Hangzhou host the dominant domestic metaverse development clusters where fashion-tech startups navigate MIIT compliance requirements.
Japan
VTuber agencies sustain recurring demand for avatar customization through virtual influencer monetization pipelines. METI monitors consumer protection in AR outfit transactions where digital-physical equivalence claims circulate on social platforms. Tokyo's creator economy anchors specialized 3D technical artist talent pools that command premium compensation.
South Korea
Idol management firms adopt blockchain-verified ownership systems for limited-edition virtual merchandise drops. The Financial Services Commission scrutinizes fashion NFTs under evolving virtual asset frameworks, elevating compliance costs for domestic operators. Seoul's metaverse investment frameworks subsidize platform development for blockchain-backed fashion marketplaces.
India
Social media AR filters for digital clothing remain underpenetrated relative to China, presenting first-mover expansion potential for camera-native commerce. TRAI guidelines on digital content classification shape platform liability for virtual asset transactions. Mumbai and Bangalore concentrate emerging fashion-tech ventures targeting mobile-first consumers.
Australia
Gaming platform operators fragment into specialized metaverse environments, compressing margins for middleware providers serving avatar customization markets. TGA-equivalent digital asset oversight remains less prescriptive than Asian counterparts, attracting regional headquarters for blockchain fashion ventures. Sydney hosts experimental retail pilots integrating virtual try-on workflows with physical store networks.
Asia-Pacific Digital Clothing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue creator-tool specialization and blockchain infrastructure layers. The market structures around three archetypes: sportswear houses with direct-to-avatar mobile infrastructure, luxury conglomerates curating scarce digital collectible drops, and open-source protocol agencies democratizing 3D garment access. Competitive moves concentrate on strategic partnerships with gaming platforms and portfolio diversification into AI-generated design tools.
Within the sportswear-digital convergence tier, Nike, Inc. anchors virtual sneaker drop infrastructure across Japanese and South Korean mobile ecosystems. The Fabricant Agency B.V. exemplifies the open-source protocol archetype, extending designer access to blockchain-verified ownership layers. Guccio Gucci S.p.A. (Kering Group) occupies the luxury scarcity position, positioning its Vault platform as a curated gateway for limited virtual fashion assets.
| Leading Market Players |
|---|
| Adidas AG |
| Nike, Inc. |
| LVMH SE |
| H&M Group |
| The Fabricant Agency B.V. |
| More Dash, Inc. (DressX) |
| Auroboros Ltd. |
| Guccio Gucci S.p.A. (Kering Group) |
| Dolce & Gabbana S.r.l. |
| Others |
Value Network & Pricing Analysis
GPU compute pricing indices cascade through Asia-Pacific digital clothing pipelines, compressing margins for blockchain-verified garment minting while elevating subscription-tier premiums for real-time rendering services. This input-cost volatility stratifies platform operators into three distinct pricing bands based on infrastructure ownership depth.
Pricing Analysis
Volume concentrates in mass-market avatar customization transactions while margin pools concentrate in blockchain-authenticated digital collectibles. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—premium tiers carry verified provenance layers, standard tiers rely on platform-native authentication, and economy tiers offer limited-use licenses without transfer rights. Pricing pressure stems from GPU rental cost volatility in Singapore and Hong Kong data center markets. Fashion enthusiasts demonstrate lowest price sensitivity for scarce drops, while casual gamers in Southeast Asian markets drive volume at economy price points.
Supply Chain Analysis
China's MIIT data-localization requirements and South Korea's cloud-sovereignty frameworks are forcing platform operators to establish domestic rendering infrastructure rather than rely on regional hyperscaler nodes. Supply concentration centers on China for 3D modeling talent pipelines, Japan for specialized technical artist pools, and South Korea for blockchain infrastructure layers. Raw material dependencies include GPU compute clusters, motion-capture studio access, and textile archive training data for AI diffusion models. Single-source vulnerability runs through NVIDIA's datacenter GPU allocation systems for real-time cloth simulation. Distribution runs through social media platform APIs that aggregate transaction volume where user attention already concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI pattern-generation tools are displacing manual 3D garment prototyping workflows, compressing design-cycle timelines from weeks to hours and fragmenting creator-tool market access.
For Market Incumbents: To counter open-source protocol agencies democratizing blockchain-verified ownership layers, established sportswear houses should deepen direct-to-avatar mobile infrastructure investments in Japanese and South Korean ecosystems. Certification investment in MIIT-compliant domestic rendering nodes preserves platform launch timelines against SAMR review extensions. Channel control through exclusive gaming platform partnerships defends against middleware margin compression.
For New Entrants and Emerging Players: VTuber management agencies in Japan represent the most penetrable buyer segment for specialized AR outfit tooling. India's camera-native commerce workflows offer white-space expansion potential relative to China's saturated social commerce channels. First-mover positioning requires integration with ByteDance or Kuaishou API ecosystems rather than standalone marketplace development.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated studios with captive 3D technical artist talent in Tokyo or Seoul, where capability scarcity commands premium compensation and creates defensive moats. Long-term viability over the next decade hinges on interoperability protocol adoption rather than platform-specific asset creation. The signal to watch is Financial Services Commission guidance evolution on fashion NFT securities classification, which would trigger regulatory-compliance infrastructure buildout demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ByteDance API partnerships concentrate transaction volume within China's dominant social commerce ecosystem. |
| Strategic Partnership | Exclusive drops with South Korean idol management firms leverage blockchain-verified scarcity mechanics. |
| Acquisition of Specialist Firm | Tokyo-based 3D technical artist studios command irreplaceable real-time cloth simulation expertise. |
| Geographic Expansion | India's underpenetrated AR filter market offers first-mover advantage in camera-native commerce. |
| Product Launch | AI-generated pattern design tools compress prototyping cycles for Japan's VTuber agency clients. |
Research Methodology
Independent corroboration across platform operator financial disclosures, VTuber agency merchandise revenue filings, and SAMR regulatory guidance documents underwrites the qualitative findings. Primary interviews with metaverse platform executives, 3D technical artist studio heads, blockchain infrastructure engineers, and idol management firm licensing directors combined with secondary validation from MIIT policy circulars, Financial Services Commission virtual asset frameworks, and METI consumer protection bulletins. Bottom-up transaction volume modeling and top-down addressable market sizing triangulate across the analysis window.
Comparable-period anchoring to historical avatar-customization spending patterns and social commerce transaction growth rates established the forecast baseline. Segmentation dimensions span product type, customer archetype, distribution channel, and technology maturity tier. CAGRs derive from fitted growth curves calibrated to platform adoption S-cycles and regulatory milestone timelines. Industry-specific inputs include GPU compute cost trajectories and VTuber agency merchandise pipeline expansion rates.
Caveats apply where SAMR security classification review extensions, Financial Services Commission NFT guidance reversals, or GPU supply allocation disruptions could materially shift the outlook. Forecasts reflect assumptions regarding interoperability protocol adoption velocity and social media platform API access continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Knitwear Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Global Socks Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Automotive Textiles Market