
 Clothing Manufacturing Service Market | 2026-2036
Clothing Manufacturing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Clothing Manufacturing Service Market Insights
Premium-grade fabric sourcing is rotating toward certified organic and recycled material tiers. Tack Apparel leverages its vertical knitting and dyeing infrastructure to control quality from fiber to finished garment. Affix Apparel anchors its competitive stance through specialized small-batch production for emerging direct-to-consumer labels. Lefty Production Co. differentiates via Los Angeles-based manufacturing that emphasizes speed-to-market and ethical labor compliance.
Clothing manufacturing service encompasses the outsourced production of finished garments from raw textiles through cutting, sewing, finishing, and quality verification, typically governed by specifications for stitch density, fabric weight, and colorfastness. The primary commercial purpose centers on enabling brands and designers to scale production without owning fixed factory assets. Within product type segmentation, T-shirts and jeans constitute mature volume categories with compressed margins, while jackets command premium pricing due to complex construction requirements. The end-user dimension shows retail brands and private labels capturing the largest contract volumes, though fashion designers represent the fastest-growing segment as independent label formation accelerates.
REACH in Europe and OEKO-TEX standards globally constrain chemical inputs in dyeing and finishing processes, directly elevating compliance costs for manufacturers serving export markets. The US Consumer Product Safety Commission enforces flammability and labeling rules that shape product specifications for children's wear and sleepwear categories. Stakeholders must monitor how evolving extended producer responsibility frameworks in the EU and emerging state-level textile recycling mandates in California reshape cost structures and supplier qualification criteria.
Market Dynamics
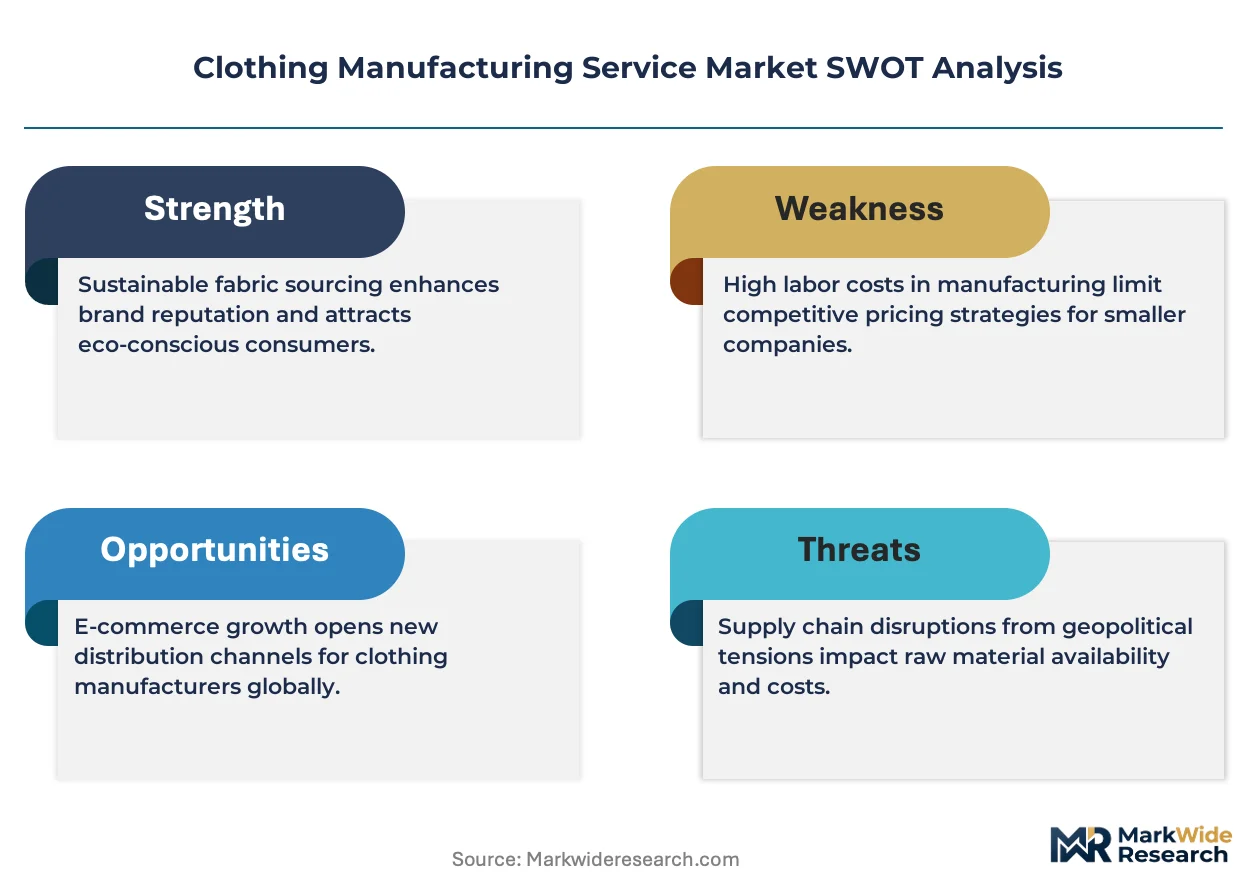
Nearshoring momentum is compressing lead times as retail brands exit China-dependent supply chains, redirecting contract flows toward Vietnam and Bangladesh while REACH compliance costs restructure European sourcing economics.
Growth Catalysts
- REACH chemical restrictions:European ECHA enforcement is filtering out low-compliance dye houses, concentrating contract volumes among certified manufacturers with captive finishing capabilities.
- Small-batch direct-to-consumer labels:Independent brand formation is accelerating demand for flexible minimum-order-quantity production that legacy mass-market factories cannot accommodate.
- Recycled fiber technology:Mechanical and chemical recycling of post-consumer polyester is scaling, enabling brands to meet circularity pledges without virgin material premiums.
Market Restraints
- Cotton price volatility:Climate-driven supply fluctuations in India and the United States are compressing margins for mid-tier manufacturers locked into fixed-price contracts.
- Single-country dye chemical dependency:Concentration of specialty dye intermediate production in China creates input fragility for export-oriented finishing houses in Bangladesh and Vietnam.
- Skilled pattern-making scarcity:Technical pattern engineering expertise is aging out in traditional manufacturing clusters without structured apprenticeship pipelines.
Strategic Opportunities
- California textile recycling mandates:Emerging extended producer responsibility frameworks will create first-mover advantage for manufacturers with closed-loop collection infrastructure.
- On-demand micro-factories:Digital printing and automated cutting convergence enables urban production nodes serving same-week delivery requirements for e-commerce brands.
- Medical-grade garment crossover:Antimicrobial finishing capabilities developed for healthcare textiles are transferable to premium activewear segments demanding hygiene certification.
Industry Challenges
- OEKO-TEX certification timelines:Multi-month laboratory testing queues for Standard 100 and STeP approvals are delaying new supplier qualification for time-sensitive brand launches.
- Legacy ERP integration:Established manufacturers with on-premise production management systems face friction connecting to cloud-based brand procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothing Manufacturing Service Market |
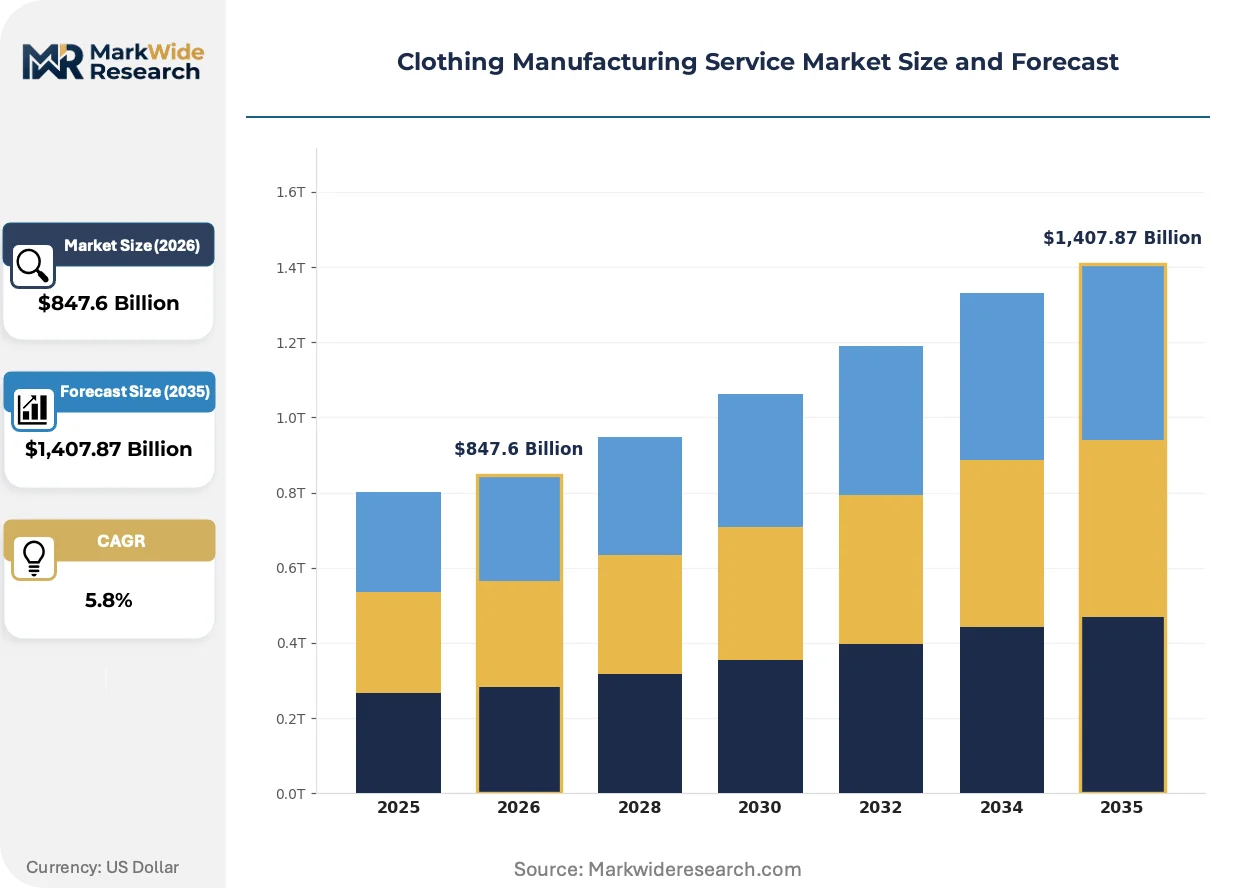
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,407.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shirts, Dresses, Jeans, Jackets End User: Retail Brands, Fashion Designers, Wholesalers, Private Labels Manufacturing Stage: Cuts & Sew, Prototype Development, Bulk Production, Finishing Service Type: Design Services, Sourcing, Quality Control, Logistics |
| Companies Covered | Tack Apparel, Affix Apparel, Apparel Production, Lefty Production Co., Zega Apparel, Los Angeles Apparel, Royal Apparel, Appareify, Billoomi Fashion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothing Manufacturing Service Market Trends and Innovations
Digital workflow tools and automated quality verification are compressing traditional sampling cycles while regulatory chemical transparency requirements force material traceability investments across supplier tiers.
3D virtual sampling software is bifurcating the prototype development phase. Direct-to-consumer brands and mid-size retail labels are adopting digital garment simulation to eliminate physical sample rounds. This compression of pre-production timelines is enabling faster seasonal turnaround and reducing air freight dependency for last-minute corrections.
EU Green Deal textile sustainability requirements are mandating fiber composition disclosure and durability testing. The European Commission's forthcoming eco-design regulations will impose repairability standards and recycled content minimums. Children's wear and outerwear categories face the steepest compliance ramps given stricter chemical and mechanical safety baselines.
Brand procurement departments are consolidating vendor rosters to deepen supplier relationships and improve compliance audit coverage. Multi-brand retail groups are deploying shared supplier scorecards that weight environmental certification alongside traditional cost and delivery metrics. This concentration is most pronounced among European and North American apparel companies with public sustainability commitments.
Clothing Manufacturing Service Market Segmentation
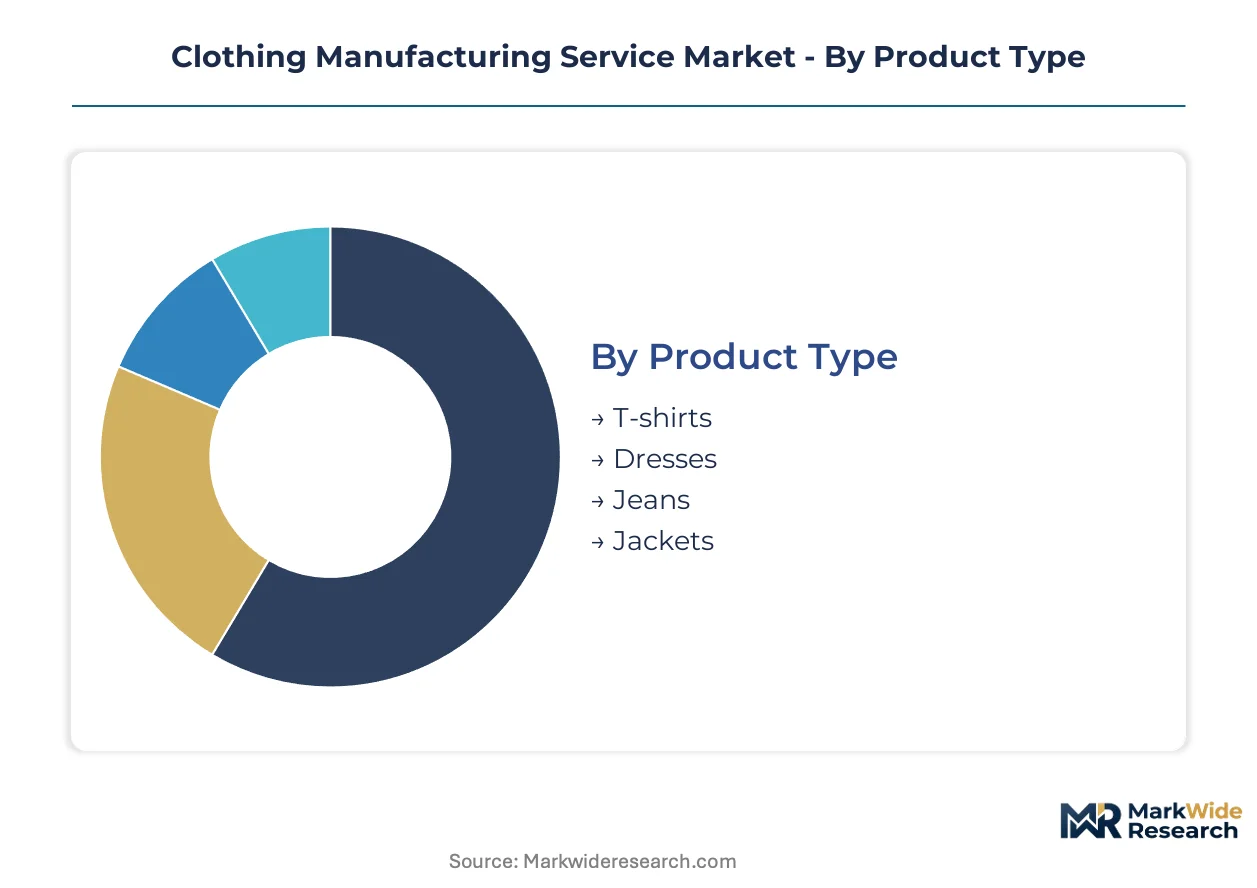
Segmentation in clothing manufacturing services reveals how contract flows concentrate around garment complexity tiers and buyer sophistication levels. Manufacturers configure equipment and labor pools differently to serve commodity volume versus specialized design-led production.
Product Type:
Domestic-market T-shirt and jeans production clusters in Vietnam and Bangladesh serve regional retail chains, while jacket manufacturing concentrates in export-oriented facilities with technical outerwear expertise.
- T-shirts:Circular knitting machines produce tubular bodies with automated cutting for high-volume basics. Demand clusters with fast-fashion retail brands in Bangladesh seeking OEKO-TEX certified dye houses for export compliance.
- Jeans:Heavy twill construction requires specialized chain-stitch and bar-tack machinery with ozone finishing for distressed effects. Italian and Turkish mills dominate premium selvedge sourcing for designer labels.
- Dresses:Varied silhouettes demand flexible line setups with skilled operators for pleating and draping.
- Jackets:Complex pattern engineering with interlinings, welt pockets, and weatherproof seam sealing.
T-shirts command the established base. The steepest expansion runs through jackets as technical outerwear premiums attract upgrading manufacturers.
End User:
Cost tier differentiation separates price-sensitive volume buyers from premium design-led accounts willing to pay for sampling agility and small-batch flexibility.
- Retail Brands:Multi-store chains with seasonal line planning requiring predictable capacity allocation and compliance documentation. Vietnam-based manufacturers capture expanding contract volumes as European retail brands exit China-dependent sourcing.
- Fashion Designers:Independent labels with irregular order patterns and rapid style turnover. Los Angeles micro-factories and Portugal's northern textile cluster specialize in sub-500-unit production with digital sampling support.
- Wholesalers:Price-driven volume buyers with standardized specifications and extended lead-time tolerance.
- Private Labels:Retailer-owned brands requiring white-label production with strict exclusivity and packaging protocols.
Retail brands anchor contract volumes. Fashion designers are gaining share fastest as direct-to-consumer formation accelerates.
Manufacturing Stage:
Application focus separates material-preparation specialists from full-package providers integrating design-to-delivery workflows.
- Cuts & Sew:CMT (cut-make-trim) operations executing client-provided patterns and materials. Bangladesh's Dhaka-Chittagong corridor dominates this tier with competitive labor rates and expanding LEED-certified factory construction.
- Prototype Development:Sampling and fit-validation services with 3D virtual simulation capabilities. Portugal's Porto region and New York's Garment District maintain pattern engineering density for rapid iteration cycles.
- Bulk Production:Scaled assembly line operations with capacity commitments.
- Finishing:Pressing, packaging, and quality verification with specialized treatments.
Bulk production commands the established base. Prototype development is expanding most quickly as digital sampling compresses pre-production timelines.
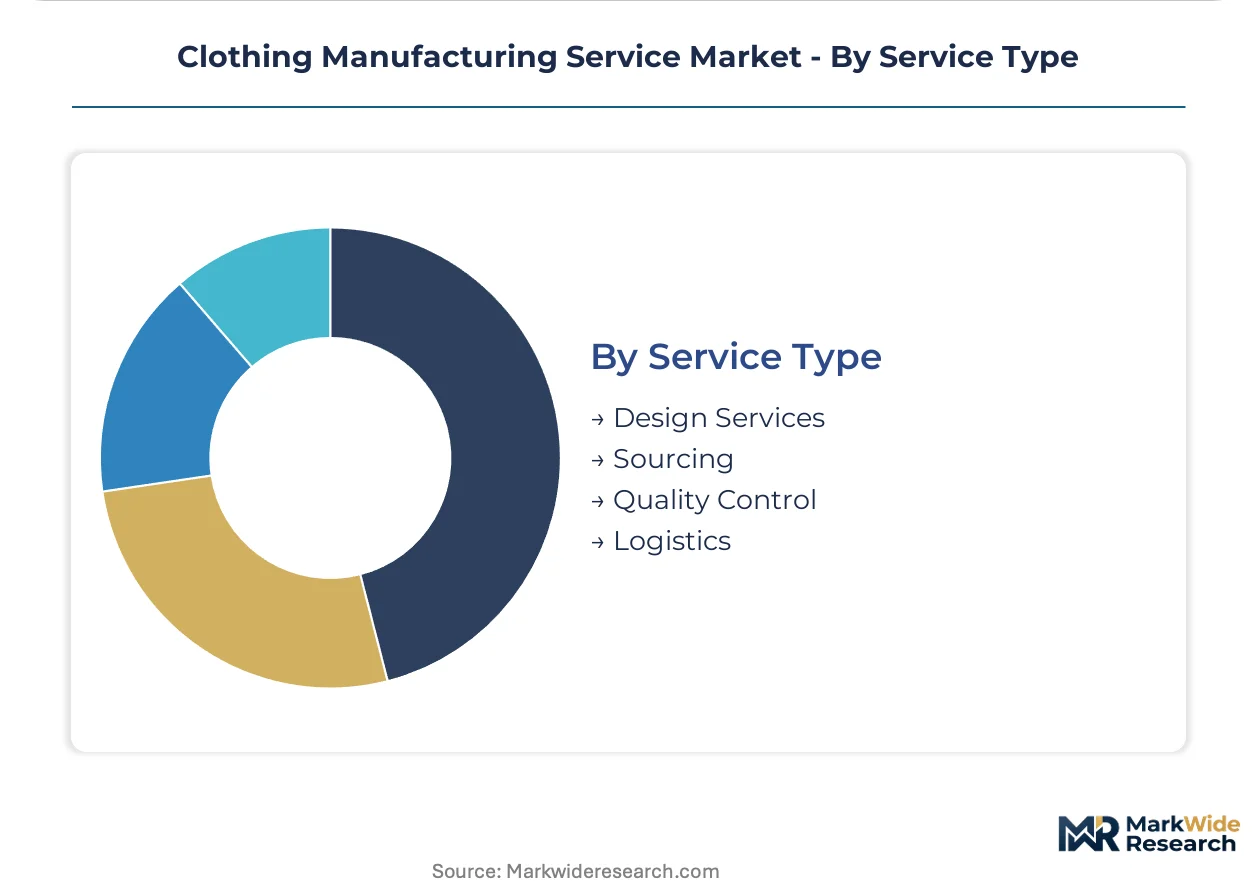
Service Type:
Customer type orientation distinguishes creative partners from execution-only providers, with margin concentration in advisory and compliance functions.
- Design Services:Technical pattern making, fabric selection, and trend interpretation. Italian full-package manufacturers in Tuscany and Emilia-Romagna integrate design studios with production for luxury brand partnerships.
- Sourcing:Raw material procurement with fiber traceability documentation. REACH compliance requirements are elevating European-based sourcing agents who manage chemical certification across supplier tiers.
- Quality Control:Inline inspection and final audit protocols.
- Logistics:Consolidation, customs documentation, and freight coordination.
Sourcing commands the established base. Design services are climbing the fastest as brands seek upstream creative partnership differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Bangladesh and Vietnam exhibit acute price elasticity for commodity basics, while Italian and Portuguese contract manufacturers command premium tolerance for design-intensive production with compliance documentation.
Bangladesh
European fast-fashion retail brands are redirecting volume contracts from China to Dhaka-Chittagong corridor factories seeking REACH-compliant dye house partnerships. The country's national export promotion bureau incentivizes LEED-certified green factory construction through tax holidays. Gazipur and Narayanganj industrial zones concentrate garment assembly operations with expanding OEKO-TEX certified finishing capacity.
Vietnam
US retail chains favor Vietnamese manufacturers for tariff-advantaged access and shorter ocean freight lanes to West Coast ports. The Ministry of Industry and Trade administers preferential certificate-of-origin protocols under bilateral trade agreements. Ho Chi Minh City and Binh Duong province host vertically integrated knitting-dyeing-sewing clusters serving technical outerwear and activewear segments.
Italy
Luxury heritage houses and emerging direct-to-consumer labels source full-package production from Tuscan and Emilia-Romagna ateliers for sampling agility and artisan craft positioning. EU Green Deal textile sustainability requirements mandate fiber traceability documentation that Italian manufacturers embed through captive spinning operations. Prato's regenerated wool district and Como silk finishing valley anchor circular material innovation for premium brand partnerships.
Portugal
Northern European sustainable fashion brands concentrate small-batch orders in Porto and Braga textile clusters for sub-500-unit minimums with digital sampling support. Portugal's national innovation agency co-funds Industry 4.0 automation retrofits for family-owned cut-and-sew operations. Guimarães and Vila Nova de Famalicão municipalities specialize in rapid-prototype development with 3D virtual simulation capabilities.
United States
Direct-to-consumer labels and celebrity-founded brands prioritize Los Angeles micro-factories for same-week sampling turnaround and domestic-made marketing claims. California's emerging extended producer responsibility framework for textile recycling mandates closed-loop collection infrastructure investment. Downtown Los Angeles Fashion District and South Bay industrial pockets concentrate automated cutting and digital printing nodes serving e-commerce velocity requirements.
Clothing Manufacturing Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated Asian manufacturers optimizing unit economics while Western specialists capture margin through compliance and speed-to-market services. The vendor base stratifies across three tiers: mass-volume CMT operators, mid-scale full-package providers, and boutique ateliers serving luxury houses. Dominant competitive moves include geographic diversification of production footprints and strategic partnerships with fiber innovators for recycled material pipelines.
Among Los Angeles-based manufacturers, Lefty Production Co. and Los Angeles Apparel occupy positions emphasizing ethical labor compliance and rapid domestic turnaround for direct-to-consumer brands. Tack Apparel exemplifies the vertically integrated archetype with captive knitting and dyeing infrastructure controlling quality from fiber to finished garment. Affix Apparel sits within the flexible-production tier, specializing in small-batch runs for emerging labels that mass-market factories cannot accommodate.
| Leading Market Players |
|---|
| Tack Apparel |
| Affix Apparel |
| Apparel Production |
| Lefty Production Co. |
| Zega Apparel |
| Los Angeles Apparel |
| Royal Apparel |
| Appareify |
| Billoomi Fashion |
| Others |
Pricing and Supply Chain Analysis
Recycled polyester substitution for virgin fiber is compressing raw material premiums while redrawing supplier maps toward mechanical recycling clusters in Italy and chemical recycling facilities in Turkey. REACH-compliant dye house scarcity in Europe simultaneously elevates finishing costs and concentrates contract volumes among certified manufacturers with captive chemical management systems.
Pricing Analysis
After-sales compliance documentation and extended certification maintenance contracts now drive lifetime value capture for full-package manufacturers serving export markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by OEKO-TEX certification tier and fiber traceability depth. Price erosion runs through commodity T-shirt and jeans production as Bangladeshi CMT operators absorb cotton volatility without contract renegotiation mechanisms. Fashion designers and direct-to-consumer labels show least price sensitivity, prioritizing sampling agility and small-batch flexibility over unit cost minimization.
Supply Chain Analysis
Strategic stockpiling of specialty dye intermediates dominates inventory strategy as Bangladeshi and Vietnamese finishing houses buffer against Chinese chemical supply disruptions. Raw material sourcing draws from Indian cotton, Chinese polyester intermediates, and Italian regenerated wool. Single-country dependency on Chinese specialty dye production creates acute input fragility. Distribution runs through consolidated vendor rosters with shared supplier scorecards weighting environmental certification alongside traditional delivery metrics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clothing manufacturing services are entering a cyclical recovery phase as inventory destocking concludes and retail brands rebuild order books. Cotton price stabilization and nearshoring contract redirection toward Vietnam and Bangladesh provide the cyclical foundation.
For Market Incumbents: Shield margin position by deepening captive finishing capabilities ahead of EU Green Deal durability testing mandates. Accelerate LEED-certified factory construction in Gazipur and Narayanganj industrial zones to capture European fast-fashion contract flows exiting China. Certification investment represents the critical defensive lever against low-cost CMT operators without compliance infrastructure.
For New Entrants and Emerging Players: Lead with on-demand micro-factory positioning in Los Angeles or Porto textile clusters serving same-week sampling requirements for direct-to-consumer labels. Target sub-500-unit minimum production segments that legacy mass-market factories cannot accommodate. Digital sampling integration with automated cutting nodes provides the differentiated go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertically integrated manufacturers in Vietnam's Binh Duong province with knitting-dyeing-sewing clusters and activewear technical expertise. Five-to-ten year viability hinges on recycled fiber pipeline partnerships and closed-loop collection infrastructure readiness. Watch California extended producer responsibility framework implementation as the inflection signal for textile recycling mandate adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye House Operations | Captive REACH-compliant finishing secures European retail contract eligibility against certified competitors. |
| Digital Sampling Platform Deployment | 3D virtual simulation compresses pre-production timelines for fashion designer client acquisition. |
| Recycled Fiber Pipeline Partnership | Mechanical and chemical recycling alliances enable circularity pledge fulfillment without virgin material premiums. |
| Micro-Factory Network Expansion | Urban production nodes in Los Angeles and Porto serve same-week delivery requirements for e-commerce velocity. |
| Closed-Loop Collection Infrastructure | California textile recycling mandate compliance creates first-mover positioning for extended producer responsibility frameworks. |
Research Methodology
A standing panel of garment production managers, brand procurement directors, dye house technical leads, and logistics coordinators provided ongoing calibration across the research phase. Primary fieldwork combined structured interviews with secondary validation against customs records, OEKO-TEX certification databases, and LEED factory registries. Bottom-up capacity modeling and top-down trade flow analysis were triangulated for consistency.
External benchmark validation against customs export data and industry association capacity surveys confirmed output consistency across the projection horizon. Segmentation dimensions modeled include garment complexity tier, buyer sophistication level, manufacturing stage depth, and regional regulatory cluster. CAGRs were derived from capacity expansion pipelines and contract flow redirection patterns, with cotton price volatility and dye chemical supply concentration as key forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained nearshoring momentum or abrupt REACH enforcement escalation would require recalibration. Forecasts reflect assumptions regarding certification adoption timelines and recycled fiber technology scaling. Revision becomes warranted when EU Green Deal textile sustainability requirements cross implementation thresholds ahead of supplier readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Zipper Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Knitwear Market