
 Egypt Textile Manufacturing Market | 2026-2036
Egypt Textile Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Textile Manufacturing Market Foresight
Buyer concentration across Egypt's textile sector is broadening as European fast-fashion retailers diversify sourcing away from Asian suppliers while domestic garment exporters fragment into specialized subcontracting clusters. Oriental Weavers leverages its integrated dyeing and finishing infrastructure to supply European home textile chains. Misr Spinning & Weaving (El Mahalla) sustains Egypt's largest cotton yarn output through state-supported modernization of its Delta facilities. Cotton & Textile Industries Holding Co. anchors public-sector production across multiple governorates with vertically integrated gin-to-garment operations.
Egypt textile manufacturing encompasses the conversion of raw fibers into finished fabrics through mechanical and chemical processes including spinning, weaving, knitting, and wet-processing treatments such as mercerization and reactive dyeing, primarily serving apparel, home furnishing, and industrial end-uses requiring specific tensile strength and colorfastness specifications. Apparel commands the largest output volume given Egypt's duty-free access to EU and US markets under qualifying origin rules, while technical textiles for automotive upholstery represent the fastest-expanding margin pool as Egyptian suppliers qualify for Tier 2 supplier status with European automakers. Cotton retains structural dominance in raw material sourcing due to long-staple Giza varietals, though polyester blending is accelerating in knitting operations serving price-sensitive export segments.
Egypt's Ministry of Trade and Industry enforces quality benchmarks through the Egyptian Organization for Standardization and Quality (EOS), while export-oriented producers must comply with EU REACH chemical restrictions and OEKO-TEX certification requirements to maintain European market access. The Industrial Development Authority coordinates land and energy allocations for textile zones in Sharqia and Damietta governorates, shaping where capacity expansion occurs. Stakeholders must monitor how Egypt's accession negotiations with the African Continental Free Trade Area reshape rules-of-origin advantages against competing Maghreb suppliers.
Market Dynamics
EU REACH chemical restrictions are compressing wet-processing capacity among Nile Delta dye houses while Egyptian spinners absorb higher Egyptian Electricity Holding Company tariffs that reshape cost structures against Turkish competitors.
Growth Catalysts
- EU-Egypt Association Agreement tariff preferences:Apparel exporters secure duty-free access to European fast-fashion retailers by meeting qualifying origin rules on yarn-forward production.
- Automotive technical textiles:Egyptian suppliers achieve Tier 2 supplier status with European automakers for upholstery and interior components, opening margin-rich industrial end-uses.
- Long-staple Giza cotton varietals:Spinners command premium positioning in fine-count yarn segments where Egyptian cotton retains structural sourcing advantages over Pakistani and Indian competitors.
Market Restraints
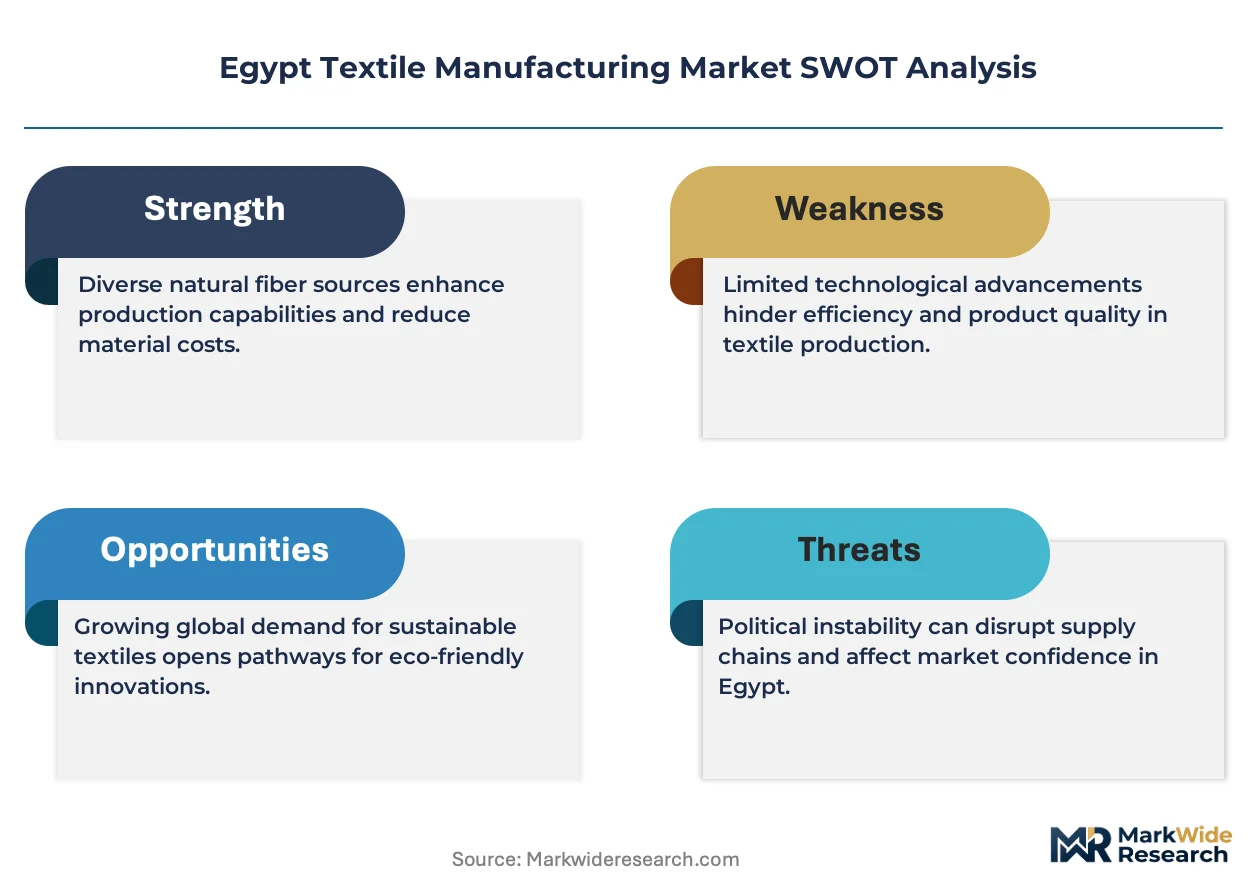
- Natural gas price volatility:Steam generation for mercerization and continuous dyeing ranges consumes 40-45% of wet-processing energy costs, exposing margins to Egyptian General Petroleum Corporation pricing adjustments.
- Imported polyester staple fiber dependence:Knitting operations serving price-sensitive export segments rely on Saudi Arabian and Chinese petrochemical suppliers, creating forex exposure and inventory risk.
- Water scarcity in Delta governorates:Nile water allocation constraints limit expansion of water-intensive finishing operations in Sharqia and Damietta textile zones.
Strategic Opportunities
- African Continental Free Trade Area accession:Egyptian negotiators seek rules-of-origin advantages that would displace Moroccan and Tunisian suppliers in intra-African apparel trade.
- Digital textile printing convergence:Reactive inkjet systems paired with AI-driven color matching enable short-run customization for European independent fashion labels.
- Industrial Development Authority land allocations:New textile zones in 10th of Ramadan City offer subsidized utility tariffs for export-oriented garment assembly operations.
Industry Challenges
- Reactive dye chemist shortage:Wet-processing facilities struggle to recruit technicians capable of formulating shade recipes compliant with EU REACH restricted substance lists.
- OEKO-TEX certification timelines:Six-to-nine-month approval cycles for Standard 100 certification delay market entry for new finishing entrants targeting European home textile chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Textile Manufacturing Market |
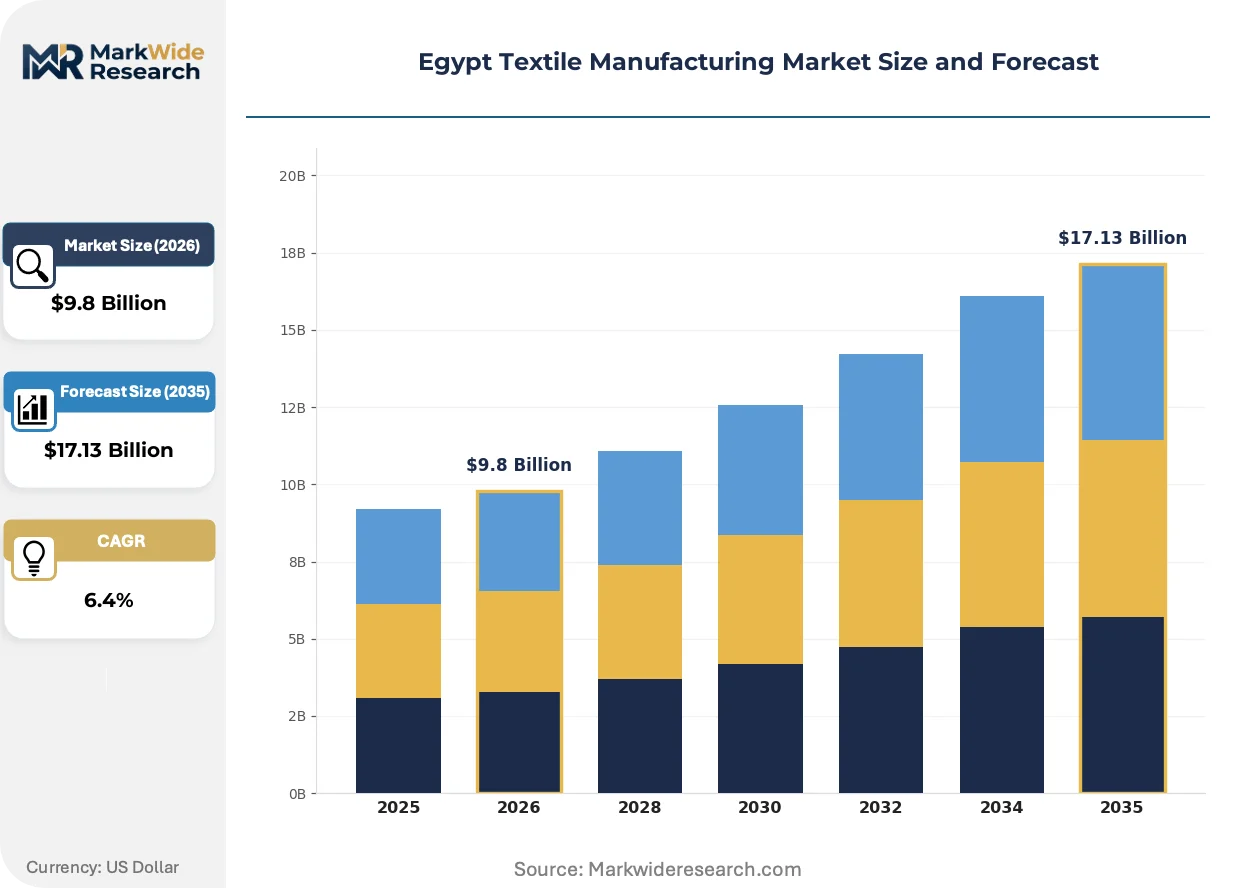
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Home Textiles, Technical Textiles, Floor Coverings Material: Cotton, Polyester, Nylon, Wool Process Type: Weaving, Knitting, Dyeing, Finishing End User: Fashion Retailers, Automotive, Upholstery, Industrial |
| Companies Covered | Cotton & Textile Industries Holding Co., Misr Spinning & Weaving (El Mahalla), Oriental Weavers, Arafa Holding, Alexandria Spinning & Weaving (SPINALEX), Giza Spinning, Kazareen Textile Company, Al Hesn Textiles, Nile Linen Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Textile Manufacturing Market Shifts & Advancements
Digital workflow integration across spinning, weaving, and finishing operations is compressing lead times for made-to-order apparel while Egyptian regulators accelerate chemical compliance frameworks to maintain European market access.
AI-driven predictive maintenance systems are electrifying ring-spinning operations by reducing downtime on high-speed frames above 25,000 rpm. El Mahalla-based mills deploy vibration sensors and machine-learning algorithms to anticipate spindle failures before yarn breaks occur. This convergence of IoT hardware and cloud analytics is enabling 24/7 continuous production runs that were previously interrupted by unplanned maintenance windows.
EU REACH Annex XVII restrictions on azo dyes and nickel-release compounds are forcing Delta dye houses to reformulate chemical inventories and invest in effluent treatment upgrades. The Egyptian Organization for Standardization and Quality has aligned national technical regulations with European chemical safety benchmarks to preserve preferential trade status. Home textile exporters targeting German and Dutch retail chains now face mandatory proof of compliance with updated restricted substance lists before purchase order confirmation.
Nearshoring procurement patterns among European fashion retailers are shortening order cycles from 90-day to 45-day turnaround requirements. Egyptian garment exporters are responding by fragmenting into specialized subcontracting clusters—cut-make-trim specialists, dedicated sampling studios, and logistics consolida tors—rather than maintaining full-package vertical operations. This restructuring is most visible in Damietta governorate, where Italian-owned buying offices now coordinate multi-supplier production programs for mid-market apparel brands.
Egypt Textile Manufacturing Market Segmentation
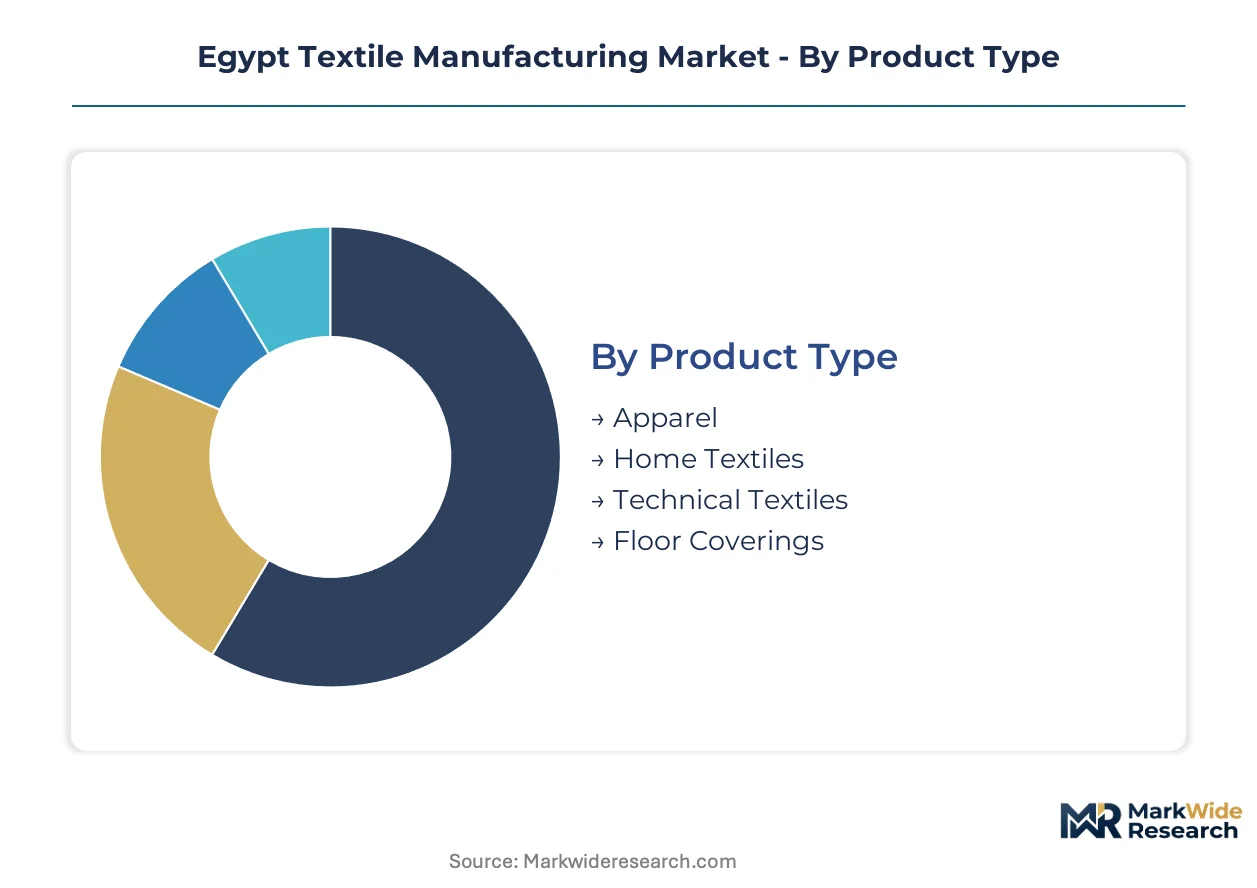
Egypt's textile manufacturing structure fragments across four distinct dimensions that govern investment allocation and margin capture. Each segmentation axis reveals where capacity concentrates and which customer requirements reshape production economics.
Product Type:
Supply concentration in Nile Delta governorates favors high-volume, export-oriented categories with established logistics corridors to European ports.
- Apparel:Cut-make-trim operations and full-package garment assembly dominate employment and export revenue. European fast-fashion retailers source knit tops and woven bottoms from Damietta and Sharqia clusters under EU-Egypt Association Agreement tariff preferences.
- Technical Textiles:Automotive upholstery and industrial filtration fabrics command premium pricing. Egyptian suppliers achieve Tier 2 certification with European automakers, opening margin pools that apparel cannot match.
- Home Textiles:Bed linens and terry towels serve Middle Eastern and European retail chains. Integrated dyeing and finishing infrastructure in 10th of Ramadan City supports quick-turn replenishment programs.
- Floor Coverings:Machine-woven carpets and rugs leverage long-staple Giza cotton for luxury positioning in German and Benelux markets.
Apparel absorbs the bulk of installed capacity; technical textiles is expanding most quickly.
Material:
Raw material sourcing patterns reflect Egypt's structural advantages in natural fibers versus import dependence for synthetic feedstocks.
- Cotton:Long-staple Giza varietals anchor fine-count yarn production. El Mahalla spinners command premium positioning in European shirting and luxury bed linen segments where Egyptian cotton retains sourcing advantages over Pakistani and Indian competitors.
- Polyester:Petrochemical-derived staple fiber dominates knitting operations serving price-sensitive export segments. Reliance on Saudi Arabian and Chinese suppliers creates foreign exchange exposure and inventory risk.
- Nylon:Industrial applications including tire cord and technical filtration drive modest consumption through specialized extrusion facilities.
- Wool:Limited domestic availability restricts processing to small-scale worsted spinning for winter outerwear and uniform contracts.
Cotton commands the highest value per kilogram processed; polyester handles the greatest throughput volume.
Process Type:
Capital intensity and energy consumption separate process stages, with wet-processing bottlenecks constraining overall system throughput.
- Weaving:Air-jet and rapier looms in Delta mills produce greige fabric for apparel and home textile finishing. State-supported modernization programs upgrade loom speeds above 800 picks per minute.
- Knitting:Circular and flat-bed machines serve fast-fashion knitwear demand with shorter lead times than woven alternatives. Polyester-cotton blends dominate substrate selection.
- Dyeing:Continuous and batch dyeing ranges consume 40-45% of wet-processing energy costs. REACH compliance requirements force chemical inventory reformulation and effluent treatment upgrades.
- Finishing:Mercerization, calendering, and softening treatments deliver final fabric specifications. Water scarcity in Sharqia and Damietta zones limits expansion of water-intensive finishing capacity.
Weaving holds the deepest installed base; finishing represents the tightest capacity constraint.
End User:
Customer concentration and certification requirements segment the market into distinct procurement channels with diverging margin structures.
- Fashion Retailers:European fast-fashion and mid-market brands drive order fragmentation into specialized subcontracting clusters. Forty-five-day turnaround requirements compress traditional ninety-day production cycles.
- Automotive:Tier 2 supplier status with European OEMs demands IATF 16949 quality systems and OEKO-TEX certification. Upholstery and interior component contracts offer multi-year visibility.
- Upholstery:Furniture manufacturers in Italy and Turkey source Egyptian fabrics for residential and contract seating applications.
- Industrial:Filtration, geotextile, and reinforcement applications serve construction and environmental infrastructure projects across Africa and the Middle East.
Fashion retailers generate the highest order frequency; automotive delivers the most stable margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long-staple Giza cotton cultivation in the Nile Delta anchors Egypt's textile geography, concentrating spinning capacity in governorates with direct access to raw fiber and Mediterranean port infrastructure.
Sharqia Governorate
Cut-make-trim operations for European fast-fashion retailers drive employment growth in Zagazig industrial zones. The Industrial Development Authority allocates subsidized land parcels to export-oriented garment assemblers under the textile modernization program. Water scarcity constraints limit expansion of dyeing capacity despite strong order inflows from Italian buying offices.
Damietta Governorate
Home textile finishing clusters serve German and Dutch retail chains with integrated dyeing infrastructure. EU REACH compliance requirements force chemical inventory reformulation at wet-processing facilities along the Damietta branch of the Nile. Italian-owned buying offices coordinate multi-supplier production programs for mid-market apparel brands from port-adjacent industrial zones.
Gharbia Governorate
El Mahalla-based spinners sustain Egypt's largest cotton yarn output through state-supported equipment upgrades. The Egyptian Electricity Holding Company tariff structure reshapes cost competitiveness against Turkish rivals for fine-count yarn exports. High-speed ring-spinning frames above 25,000 rpm deploy AI-driven predictive maintenance systems across mill floors.
10th of Ramadan City
Subsidized utility tariffs attract export-oriented garment assembly operations to this planned industrial satellite of Greater Cairo. New textile zones offer dedicated logistics corridors to Alexandria and Damietta ports for EU-bound container shipments. Quick-turn replenishment programs for bed linens and terry towels leverage proximity to integrated dyeing and finishing infrastructure.
Egypt Textile Manufacturing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technical textile certification for automotive supply chains. The market exhibits moderate concentration with public-sector holding companies anchoring upstream spinning capacity while private specialists dominate downstream garment assembly. Three archetypes prevail: vertically integrated gin-to-garment operators, specialized cut-make-trim subcontractors, and technical textile qualifiers targeting Tier 2 automotive status. Competitive moves center on capacity expansion in subsidized industrial zones and strategic partnerships with European buying offices to secure purchase order visibility.
Among Egyptian textile conglomerates, Cotton & Textile Industries Holding Co. and Misr Spinning & Weaving (El Mahalla) exemplify the public-sector integrated archetype with Delta-based spinning assets, while Oriental Weavers occupies a position within the specialized home textile tier serving European retail chains.
| Leading Market Players |
|---|
| Cotton & Textile Industries Holding Co. |
| Misr Spinning & Weaving (El Mahalla) |
| Oriental Weavers |
| Arafa Holding |
| Alexandria Spinning & Weaving (SPINALEX) |
| Giza Spinning |
| Kazareen Textile Company |
| Al Hesn Textiles |
| Nile Linen Group |
| Others |
Supply & Pricing Matrix
Cotton price benchmarks at Alexandria Cotton Exporters Association (ALCOTEX) cascade through Egyptian textile supply chains into three distinct pricing tiers based on yarn count fineness and OEKO-TEX certification status. Giza long-staple varietals anchor premium positioning for European luxury home textile contracts, while polyester-blend knits compete on volume against Turkish and Bangladeshi alternatives.
Pricing Analysis
After-sales technical support and REACH compliance documentation are bundled into premium tier quotations for automotive upholstery contracts, while standard apparel exports carry unbundled dye-lab matching fees. Pricing stratifies across premium Giza cotton shirting, mid-tier polyester-cotton knits, and economy-grade open-end yarn for domestic uniform contracts. Cost compression in wet-processing stems from Egyptian Electricity Holding Company tariff adjustments that narrow margins against Turkish competitors. European fast-fashion retailers exhibit highest price sensitivity due to 45-day turnaround requirements, while automotive Tier 2 suppliers accept longer payment terms for multi-year contract stability.
Supply Chain Analysis
Direct-to-garment-assembler channels handle European retailer demand through Italian buying offices in Damietta and Sharqia industrial zones. Raw cotton sourcing concentrates in Nile Delta governorates with ginning infrastructure in Gharbia and Kafr El Sheikh, while polyester staple fiber draws from Saudi Arabian and Chinese petrochemical suppliers. Steam generation for mercerization and continuous dyeing ranges creates single-source vulnerability to Egyptian General Petroleum Corporation natural gas pricing. Distribution runs through Alexandria and Damietta ports for EU-bound container shipments under preferential tariff arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egyptian textile manufacturing is transitioning from conventional wet-processing to digital inkjet printing and AI-driven color matching, displacing legacy batch-dyeing infrastructure that struggles with REACH compliance timelines.
For Market Incumbents: Deepen backward integration into captive ginning operations to secure Giza cotton supply against export quota competition from Indian spinners. Invest in OEKO-TEX Standard 100 certification infrastructure to reduce six-to-nine-month approval cycles that delay European home textile purchase orders. Add ring-spinning capacity in 10th of Ramadan City textile zones where Industrial Development Authority subsidized utility tariffs offset Egyptian Electricity Holding Company cost pressures. For New Entrants and Emerging Players: Begin with technical textile qualification for automotive upholstery applications where Tier 2 supplier status offers multi-year contract visibility absent from fast-fashion apparel. Target Damietta governorate home textile finishing clusters where water scarcity constraints limit incumbent expansion of dyeing capacity. Pursue digital textile printing convergence with reactive inkjet systems to serve short-run customization demand from European independent fashion labels. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cut-make-trim subcontractors in Sharqia Governorate where Zagazig industrial zones offer subsidized land parcels under textile modernization programs. Long-term viability across the projection horizon rests on qualifying for African Continental Free Trade Area rules-of-origin advantages that would displace Moroccan and Tunisian suppliers. Monitor Egypt's accession negotiation timelines as the inflection indicator for intra-African apparel trade repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Ginning | Captive supply of Giza long-staple varietals secures premium yarn positioning against Pakistani and Indian competitors. |
| Digital Textile Printing Adoption | Reactive inkjet systems paired with AI color matching enable 45-day turnaround compliance for European fast-fashion retailers. |
| OEKO-TEX Certification Investment | Standard 100 approval infrastructure reduces six-to-nine-month delays blocking German and Dutch retail chain entry. |
| Automotive Tier 2 Qualification | IATF 16949 quality systems open margin-rich upholstery contracts with multi-year visibility from European OEMs. |
| AfCFTA Rules-of-Origin Positioning | Egyptian negotiator progress on accession terms determines competitive displacement of Maghreb suppliers in intra-African trade. |
Research Methodology
Multi-period observation of Alexandria Cotton Exporters Association pricing benchmarks, Industrial Development Authority land allocation records, and EU REACH regulatory amendment timelines anchored the trend analysis, supplemented by interviews with plant managers at Delta-based spinning mills, procurement leads at European fast-fashion retailers, wet-processing technical directors, and automotive Tier 1 supplier quality engineers. Secondary validation drew from Egyptian Organization for Standardization and Quality technical regulations, Egyptian Electricity Holding Company tariff filings, customs and trade data through General Authority for Supply Commodities, and SEC filings of publicly listed textile conglomerates. Bottom-up capacity assessments across Sharqia, Damietta, and Gharbia governorates were triangulated against top-down export value estimates.
Segment-weighting approaches modeled product type, material composition, process stage, and end-user industry across the analysis window, with apparel, technical textiles, home textiles, and floor coverings receiving distinct volume and value coefficients. CAGRs were derived from trend extrapolation of installed capacity expansion in 10th of Ramadan City textile zones and qualification timelines for automotive supplier status. Forecast inputs included Nile water allocation constraints affecting finishing capacity expansion and Egyptian General Petroleum Corporation natural gas pricing volatility impacting wet-processing economics.
Underlying measurement precision varies by segment; technical textiles and automotive upholstery carry tighter precision than fragmented apparel subcontracting due to concentrated buyer visibility. Forecasts reflect assumptions regarding EU-Egypt Association Agreement tariff preference continuity and African Continental Free Trade Area accession progress. Periodic stress-testing of base assumptions against regulatory amendment timelines and commodity price benchmark movements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Global Cashmere Yarn Market