
 Welding Apparels Market | 2026-2036
Welding Apparels Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Apparels Market Analytics
Flame-resistant synthetic fabrics is realigning traditional leather-dominated welding apparel economics, reducing weight while improving thermal protection ratings. ESAB leverages its integrated PPE portfolio to sustain channel control across European distribution networks. MSA Safety anchors its position through R&D intensity in respiratory-integrated helmet systems. Portwest Clothing competes on manufacturing scale, dominating private-label supply to industrial distributors in the United Kingdom and Ireland.
Welding apparels encompass protective garments and accessories engineered to shield operators from radiant heat, molten metal spatter, ultraviolet radiation, and electric arc flash, typically constructed with leather hides, treated cotton duck, para-aramid fibers, or multilayer synthetic composites rated to ASTM F1506 and ISO 11611 standards. The primary industrial purpose centers on preventing burn injuries and occupational illnesses in fusion welding, cutting, and allied thermal processes. Helmets and gloves command the largest margin pools due to mandatory replacement cycles and technological integration, while synthetic material segments grow fastest as fabric breathability improves. Professional end users represent the mature core, yet hobbyist channels expand through e-commerce penetration and DIY welding equipment sales.
OSHA 29 CFR 1910.132 mandates hazard assessment protocols that directly expand employer expenditure on certified welding PPE, while EU Regulation 2016/425 enforces CE marking and third-party conformity assessment for flame-resistant garments entering European markets. China's GB 8965.1 standard for protective clothing creates parallel compliance obligations for suppliers targeting domestic heavy industry procurement. Stakeholders must monitor evolving arc-rating thresholds and cross-border harmonization between NFPA 70E and IEC 61482 test methods to anticipate certification-driven product obsolescence.
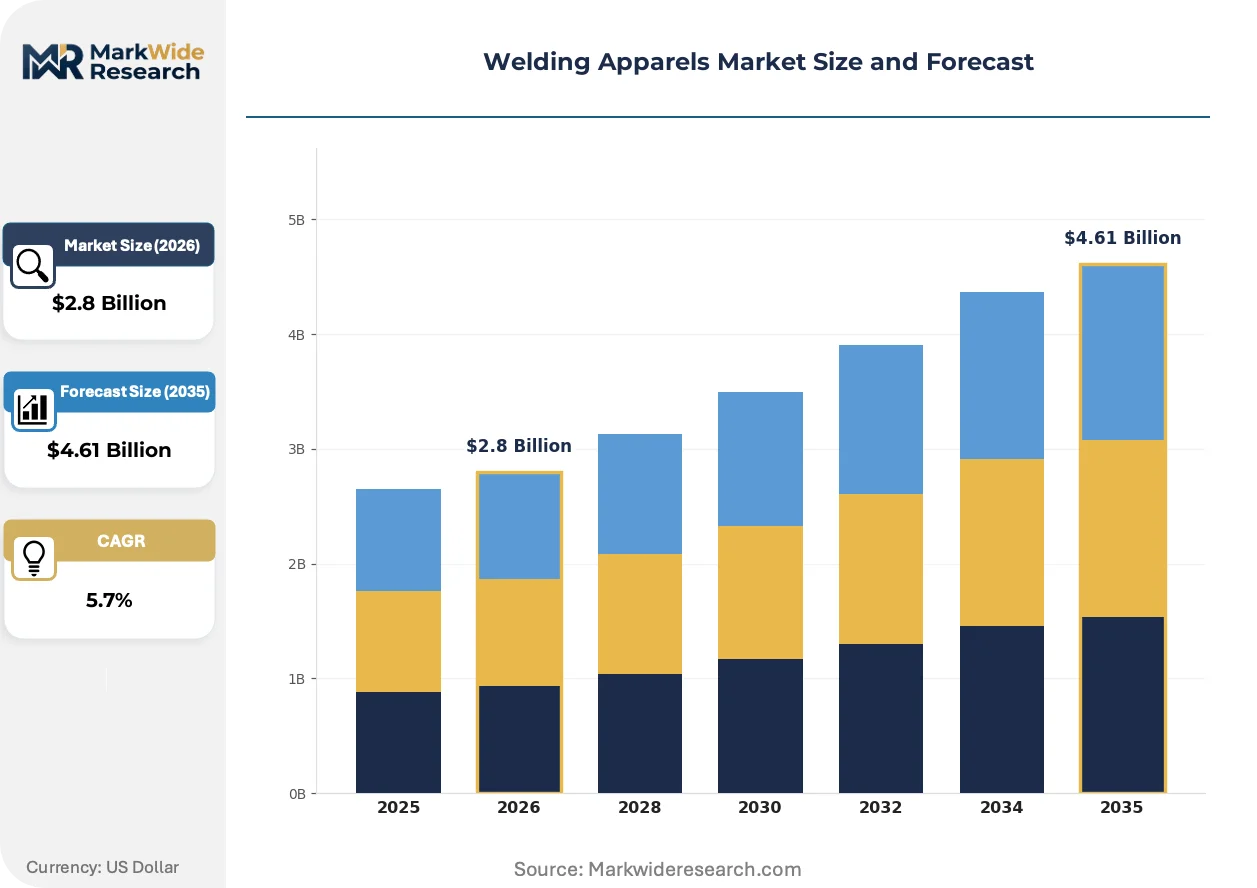
Market Dynamics
Flame-resistant synthetic fabrics are compressing traditional leather economics across welding apparel supply chains, forcing material suppliers to retool production lines or cede share to para-aramid and multilayer composite alternatives.
Growth Catalysts
- OSHA 29 CFR 1910.132 enforcement:Mandatory hazard assessment protocols in US fabrication shops expand employer expenditure on certified welding PPE, particularly arc-rated garments and respiratory-integrated helmet systems.
- Shipbuilding concentration in South Korea:Hyundai Heavy Industries and DSME procurement drives adoption of advanced protective gear with integrated cooling and communication features for yard welders.
- Para-aramid fiber breathability improvements:Next-generation fabric constructions reduce heat stress incidents while maintaining ISO 11611 compliance, accelerating substitution away from leather in high-temperature environments.
Market Restraints
- Raw material volatility:Chrome-tanned leather prices fluctuate with Brazilian hide supply and chemical input costs, squeezing margin stability for traditional garment producers.
- Supply concentration in Zhejiang province:Synthetic fabric weaving and coating capacity clusters along China's eastern seaboard, creating geographic vulnerability to port congestion and energy rationing.
- Technical limitation in arc-rating harmonization:Divergent test methods between NFPA 70E and IEC 61482 force dual certification costs for suppliers targeting both North American and European industrial buyers.
Strategic Opportunities
- Underpenetrated GCC industrial zones:Saudi Arabia's giga-project construction and UAE ship repair yards lack established welding PPE distribution, creating first-mover channel openings for certified suppliers.
- E-commerce hobbyist channels:DIY welding equipment sales through Amazon and specialty retailers expose amateur users to professional-grade protective gear previously restricted to industrial procurement.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for textile waste incentivize rental and refurbishment models for high-turnover welding gloves and jackets.
Industry Challenges
- Certification timeline compression:Accelerated revision cycles for ASTM F1506 and ISO 11611 standards force R&D teams to validate new material constructions before existing inventory faces obsolescence.
- Skill gap in composite fabrication:Shortage of technicians trained in multilayer synthetic assembly limits domestic production capacity expansion outside established Asian manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Apparels Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Helmets, Jackets, Aprons Material: Leather, Cotton, Synthetic, Kevlar Application: Construction, Manufacturing, Automotive, Shipbuilding End User: Professionals, Hobbyists, Maintenance Staff, Industrial Workers |
| Companies Covered | MSA Safety, ESAB, Honeywell Safety Products, 3M, Portwest Clothing, John Tillman, Magid Glove & Safety, Steiner Industries, Chicago Protective Apparel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Apparels Market Evolving Landscape
Active cooling and sensor-integrated helmet systems are redefining operator protection economics, shifting value capture from passive garments to intelligent equipment with embedded diagnostics and connectivity.
Photovoltaic-darkening filter technology is electrifying helmet visor performance. These liquid-crystal systems replace fixed-shade passive filters, enabling instant arc detection and adjustable darkness levels. Automotive and aerospace fabrication shops in Germany and Japan are standardizing these units for precision welding tasks. The technology is electrifying competition among helmet suppliers, compressing replacement cycles and expanding attach rates for respiratory and communication modules.
EU Regulation 2016/425 conformity assessment tightening is reshaping market access requirements. Third-party notified body involvement for flame-resistant garment CE marking has extended approval timelines and raised documentation burdens. Suppliers targeting European industrial distributors must now maintain technical files beyond previous self-certification norms. German and French metalworking clusters are prioritizing suppliers with established EU-based testing partnerships to mitigate procurement delays.
Industrial buyers are consolidating welding PPE procurement through integrated safety distributors rather than fragmented specialty suppliers. Large fabrication contractors in China's Guangdong and Jiangsu provinces now specify single-source contracts covering helmets, gloves, and respiratory protection. This concentration favors suppliers with breadth across ASTM and GB standard portfolios. The shift is most visible in state-owned shipyard and infrastructure procurement, where bundle pricing and unified compliance documentation reduce administrative overhead.
Welding Apparels Market Segmentation
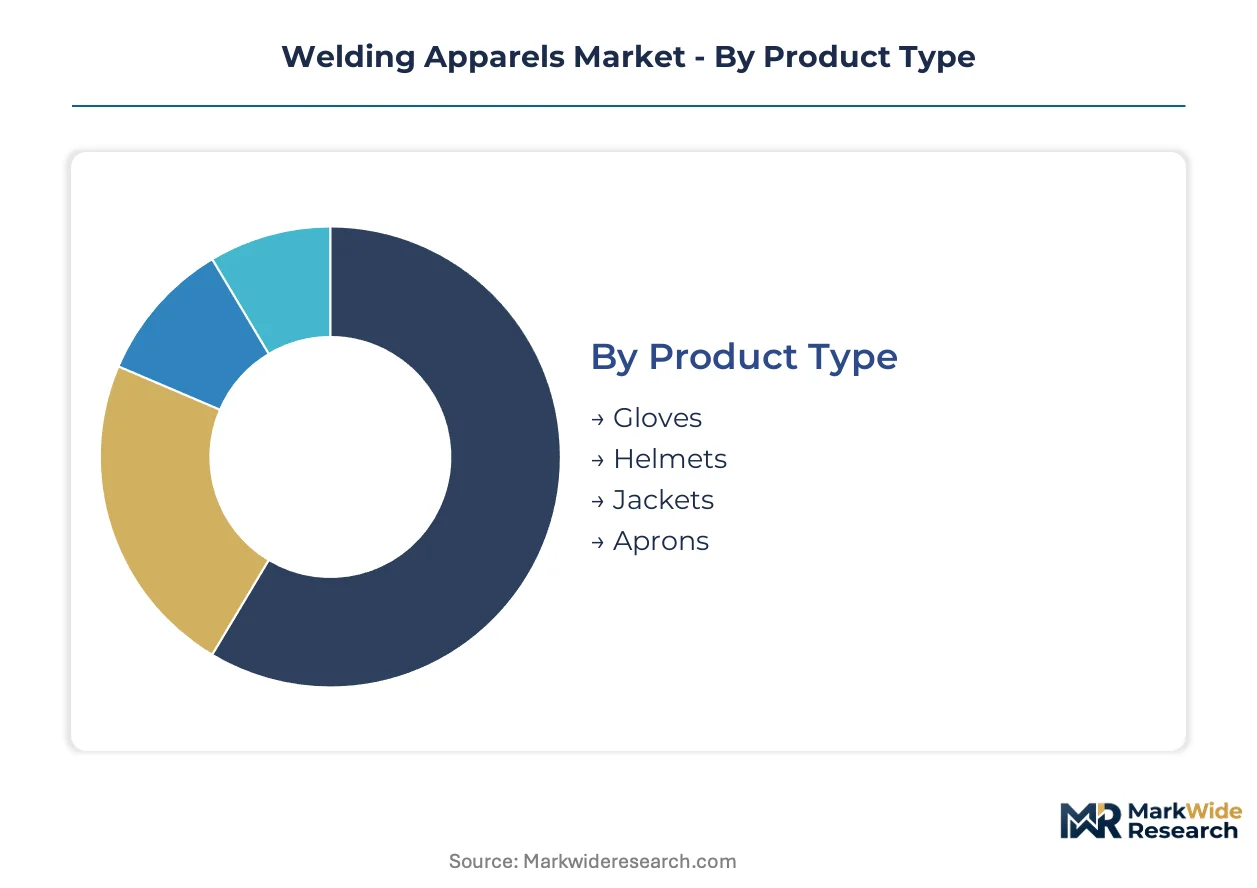
Welding apparel segmentation reveals how procurement priorities diverge between heavy industrial buyers and specialized trade users. Product architecture, material specifications, and end-user sophistication create distinct margin profiles across each dimension.
Product Type:
Helmets and gloves function as standalone replacement-cycle products, while jackets and aprons embed into broader PPE systems with longer service intervals.
- Helmets:Auto-darkening filter technology dominates specification sheets, with photovoltaic liquid-crystal systems displacing fixed-shade passive filters in precision fabrication environments. German automotive assembly plants and Japanese aerospace contractors now mandate adjustable darkness levels for TIG welding operations, compressing replacement cycles to 18-24 months.
- Gloves:Multilayer constructions combining grain leather palms with para-aramid backs deliver dexterity without sacrificing ISO 11611 compliance. South Korean shipyards specify integrated cooling liners for yard welders exposed to prolonged radiant heat exposure.
- Jackets:Full-torso protection rated to ASTM F1506 commands premium positioning in electrical utility maintenance.
- Aprons:Bib-style designs persist in maintenance workshops where mobility requirements exceed thermal coverage needs.
Volume placements concentrate in gloves; the faster expansion belongs to helmets.
Material:
Cost tiers separate commodity leather from engineered synthetics, with breathability improvements driving substitution economics in high-temperature environments.
- Synthetic:Multilayer para-aramid composites reduce garment weight by 40% versus traditional leather while maintaining equivalent arc ratings. China's Guangdong province fabrication clusters now specify synthetic jackets for summer production cycles to mitigate heat stress liability.
- Leather:Chrome-tanned hides from Brazilian supply chains retain cost advantage in commodity glove production. Price volatility in chemical tanning inputs squeezes margin stability for traditional garment producers serving price-sensitive maintenance channels.
- Kevlar:Cut-resistant thread reinforcements extend glove service life in heavy plate welding.
- Cotton:Treated duck fabric occupies entry-level positioning for hobbyist and light-duty maintenance applications.
Leather retains the largest installed base; engineered synthetics are climbing the fastest.
Application:
Application segmentation tracks end-use intensity, with continuous production environments demanding higher-specification protection than intermittent maintenance tasks.
- Shipbuilding:Hyundai Heavy Industries and DSME procurement drives adoption of integrated cooling and communication-enabled helmet systems for yard welders. Korean maritime construction specifications now exceed baseline ISO 11611 requirements for overhead welding positions.
- Manufacturing:Automotive stamping and frame welding operations in Germany prioritize respiratory-integrated helmet configurations to address manganese fume exposure. OEM tier-one suppliers bundle PPE procurement through single-source distributor contracts.
- Construction:Infrastructure steel erection combines fall protection with welding PPE in unified harness configurations.
- Automotive:Precision TIG applications in battery enclosure fabrication favor lightweight synthetic materials.
Manufacturing generates the highest unit volumes; shipbuilding commands the steepest specification escalation.
End User:
Customer type determines channel structure, with professional procurement flowing through industrial distributors and hobbyist demand fragmenting across e-commerce platforms.
- Professionals:Certified welders in unionized trades require documented compliance with employer hazard assessment protocols under OSHA 29 CFR 1910.132. US fabrication shops maintain replacement schedules tied to visible wear indicators rather than calendar cycles.
- Industrial Workers:Maintenance technicians performing intermittent welding tasks drive demand for multi-function PPE combining cut, flame, and arc protection. Saudi Aramco contractor specifications now require dual-certified garments for turnaround maintenance crews.
- Hobbyists:DIY equipment sales through Amazon expose amateur users to professional-grade protection previously restricted to industrial procurement channels.
- Maintenance Staff:Facility technicians prioritize versatility over specialization in protective garment selection.
Industrial workers represent the core revenue base; hobbyist channels are gaining share fastest through e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's coastal manufacturing provinces where heavy industrial output dominates procurement volumes, while South Korean shipbuilding yards drive adoption of advanced protective gear with integrated cooling systems.
United States
OSHA 29 CFR 1910.132 enforcement expands employer expenditure on certified welding PPE across fabrication shops and construction sites. The Department of Labor mandates hazard assessment protocols that directly elevate arc-rated garment procurement. Texas and Louisiana petrochemical maintenance corridors drive specification escalation for dual-certified flame and arc protection.
Germany
Automotive stamping and frame welding operations prioritize respiratory-integrated helmet configurations under EU Regulation 2016/425 conformity assessment. The ECHA framework enforces CE marking with third-party notified body involvement for flame-resistant garments. Bavarian automotive clusters standardize adjustable-darkness helmet systems for precision TIG welding in battery enclosure fabrication.
China
GB 8965.1 standard compliance creates parallel obligations for suppliers targeting domestic heavy industry procurement. The MIIT oversees protective clothing certification for state-owned shipyard and infrastructure tenders. Guangdong and Jiangsu province fabrication clusters now specify synthetic jackets for summer production cycles to mitigate heat stress liability.
South Korea
Hyundai Heavy Industries and DSME procurement drives adoption of integrated cooling and communication-enabled helmet systems for yard welders. The MFDS aligns with international standards while maritime construction specifications exceed baseline ISO 11611 requirements. Busan-Ulsan shipbuilding corridors command the steepest specification escalation for overhead welding positions.
Saudi Arabia
Giga-project construction and ship repair yards lack established welding PPE distribution, creating first-mover channel openings for certified suppliers. The SFDA and national procurement frameworks emphasize worker safety in industrial zones. Eastern Province industrial cities and NEOM construction sites represent underpenetrated demand for professional-grade protective gear.
Welding Apparels Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated safety distributors consolidating procurement for large fabrication contractors. The vendor base organizes around three archetypes: diversified industrial conglomerates with PPE divisions, pure-play protective equipment specialists, and regional contract manufacturers serving private-label channels. Competitive moves center on portfolio breadth expansion across helmet-glove-jacket systems and geographic penetration into underpenetrated industrial zones.
Among diversified safety equipment providers, MSA Safety and Honeywell Safety Products exemplify the integrated-systems archetype, while ESAB represents the welding-specialist vector with captive channel control. Portwest Clothing occupies a position in the scale-driven manufacturing tier, anchoring private-label supply to industrial distributors. These three company structures illustrate how competitive positioning diverges between technology-integrated helmet systems and manufacturing-scale garment production.
| Leading Market Players |
|---|
| MSA Safety |
| ESAB |
| Honeywell Safety Products |
| 3M |
| Portwest Clothing |
| John Tillman |
| Magid Glove & Safety |
| Steiner Industries |
| Chicago Protective Apparel |
| Others |
Value Network & Pricing Analysis
Captive synthetic fabric production in China's Zhejiang province anchors both supply security and margin control for welding apparel manufacturers serving ASTM F1506 and ISO 11611 certification tiers. In-house para-aramid weaving and multilayer composite coating capabilities insulate integrated suppliers from Brazilian hide price volatility while compressing lead times for European and North American distributor contracts.
Pricing Analysis
Volume placements in leather gloves trade at thin margins while helmet systems with photovoltaic-darkening filters capture premium positioning. Pricing stratifies across certified arc-rated garments, standard synthetic jackets, and economy cotton duck alternatives based on thermal protection ratings and replacement cycle bundling. Cost compression in commodity leather tiers intensifies as chrome tanning input volatility squeezes traditional garment producers. Hobbyist e-commerce buyers exhibit highest price sensitivity; shipyard procurement officers in South Korea prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's state-owned shipyard tenders reshape sourcing patterns toward GB 8965.1-certified local suppliers. Manufacturing gravity centers on China, Vietnam, and Bangladesh for synthetic weaving and garment assembly, with Brazilian tanneries feeding leather glove producers. Raw material dependencies span para-aramid fibers, liquid-crystal display components for helmet filters, and chrome-tanned hides. Single-source vulnerability concentrates in Zhejiang province coating capacity. Distribution runs through integrated safety distributors consolidating multi-product PPE procurement for large fabrication contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The welding apparel sector is becoming a vertical-integration race where captive synthetic fabric production and in-house certification testing capabilities determine who captures margin from material substitution trends. Players without upstream para-aramid weaving or downstream distributor relationships face displacement.
For Market Incumbents: Extend certification testing infrastructure to compress ISO 11611 and ASTM F1506 approval timelines before inventory obsolescence accelerates. Deepen backward integration into para-aramid fiber sourcing to offset Brazilian hide price volatility threatening leather glove margins. Anchor channel control through exclusive distributor partnerships covering helmet-glove-jacket bundles. For New Entrants and Emerging Players: Hobbyist welders purchasing through Amazon and specialty DIY retailers represent an underserved buyer archetype with lower certification barriers than industrial procurement. Target Saudi Arabia's Eastern Province giga-project sites and UAE ship repair yards lacking established welding PPE distribution. Lead with e-commerce direct-to-consumer positioning before scaling into contractor channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified safety conglomerates seeking welding-specialist capabilities. Long-term viability hinges on synthetic material R&D intensity and EU-based testing partnerships for CE marking efficiency. Watch for accelerated revision cycles in NFPA 70E and IEC 61482 arc-rating harmonization as inflection signals for certification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Para-Aramid Fiber | Captive synthetic supply insulates margin from Brazilian hide volatility and Zhejiang energy rationing. |
| EU-Based Testing Partnership | Notified body relationships compress CE marking timelines under EU Regulation 2016/425 conformity assessment. |
| Respiratory-Integrated Helmet Launch | MSA Safety and Honeywell anchor positioning in German automotive stamping operations addressing manganese fume exposure. |
| E-Commerce Hobbyist Channel Entry | Amazon and specialty DIY retailers expose amateur welders to professional-grade protection previously restricted to industrial procurement. |
| GCC Distribution Network Buildout | Saudi Aramco contractor specifications and NEOM construction sites lack established welding PPE supply infrastructure. |
Research Methodology
Trade customs databases, OSHA enforcement records, and EU notified body certification registries formed the secondary backbone for demand quantification and regulatory mapping. Primary interviews with safety directors at Hyundai Heavy Industries and DSME, procurement leads at German automotive OEMs, and channel managers at UK industrial distributors validated replacement cycle assumptions and specification escalation trends. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against national PPE expenditure data anchored market sizing integrity.
Bottom-up modeling segmented the market by helmet, glove, jacket, and apron categories with material-grade disaggregation across synthetic, leather, and cotton tiers. The analytical framework incorporated end-use intensity differentials between continuous shipyard welding and intermittent maintenance tasks. CAGRs were derived from regression analysis of historical procurement patterns against regulatory enforcement timelines and synthetic fabric breathability improvement curves. Forecast inputs included OSHA 29 CFR 1910.132 compliance cost estimates and EU Green Deal circularity mandate implementation trajectories.
Revisions become necessary when arc-rating harmonization between NFPA 70E and IEC 61482 accelerates beyond modeled timelines or when Zhejiang province energy rationing disrupts synthetic fabric coating capacity. Forecasts reflect documented assumptions regarding certification timeline compression and para-aramid fiber substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Denim Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Asia-Pacific Digital Clothing Market