
 Europe Footwear Sole Material Market | 2026-2036
Europe Footwear Sole Material Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Footwear Sole Material Market Foresight
Bio-based polyurethane chemistry is fragmenting the traditional petrochemical supply chain for performance outsoles. BASF SE leverages its Ludwigshafen R&D campus to scale renewable carbon content in elastomer formulations. Covestro AG anchors its European position through dedicated TPU lines at its Dormagen site. Vibram S.p.A. differentiates via compound specialization for mountaineering and trail-running segments.
Footwear sole material encompasses elastomeric and polymeric compounds engineered to provide abrasion resistance, energy return, and ground contact stability across diverse terrain and gait conditions. TPU grades deliver Shore A hardness values from 70 to 95 alongside hydrolysis resistance for athletic applications. Rubber compounds dominate industrial safety and outdoor categories where oil resistance and cold-flex performance command premium positioning. EVA formulations lead volume in casual and children's segments where lightweight cushioning at lower unit economics drives procurement decisions.
REACH registration requirements and the EU Green Deal's chemical sustainability framework constrain feedstock choices while opening reformulation contracts for compliant compounders. ECHA substance evaluation pushes phthalate and heavy-metal restrictions deeper into the supply chain, forcing finished-goods brands to audit tier-two material sources. Stakeholders must monitor how the F-Gas Regulation's phase-down timelines affect blowing-agent availability for midsole foaming operations.
Market Dynamics
Bio-based polyurethane chemistry is fragmenting Europe's petrochemical supply chain for performance outsoles, with compounders reformulating feedstocks to meet EU Green Deal targets while athletic brands accelerate renewable carbon procurement.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Compounders across Germany and Italy are securing reformulation contracts as brands face mandatory renewable content thresholds. Portugal's Porto rubber cluster attracts bio-based TPU investment.
- Performance outsole demand from trail-running segments:Mountaineering and technical footwear manufacturers prioritize hydrolysis-resistant elastomers. Italy's Arzignano leather district integrates advanced rubber compounds into hybrid construction.
- ECHA substance evaluation enforcement:Phthalate and heavy-metal restrictions cascade through tier-two audits. Compliant compounders capture market position from legacy petrochemical suppliers.
Market Restraints
- Petrochemical feedstock price volatility:Crude-derived polyol costs swing with energy markets, compressing margins for non-integrated compounders serving mid-tier athletic brands.
- Blowing-agent supply concentration:The F-Gas Regulation's phase-down timeline constrains hydrofluorocarbon availability for midsole foaming operations, particularly affecting Portugal's EVA processors.
- Technical performance gaps in bio-based grades:Renewable polyurethane elastomers still trail petrochemical equivalents in cold-flex performance below minus twenty degrees Celsius, limiting adoption in Nordic safety footwear.
Strategic Opportunities
- Underpenetrated circular material flows:Chemical recycling infrastructure for end-of-life TPU outsoles remains sparse across Eastern Europe, creating first-mover positioning for compounders building pyrolysis partnerships.
- Emerging orthopedic and diabetic footwear applications:Pressure-mapping integration with custom-molded sole units opens medical-grade pricing tiers. German rehabilitation device manufacturers seek Shore A 40-60 formulations.
- CSRD-mandated supply chain disclosure:Corporate sustainability reporting requirements push finished-goods brands toward auditable bio-based content certificates, rewarding compounders with mass-balance certification.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in renewable carbon integration concentrates at BASF's Ludwigshafen campus and select Italian research institutes, constraining scaling capacity for mid-size compounders.
- REACH registration timeline compression:Novel bio-based intermediates face eighteen-to-thirty-six-month authorization windows, delaying product launches for reformulated elastomer grades.
- Legacy compounding equipment retrofit costs:Bio-based polyols require modified reactor temperature profiles and moisture control systems, demanding capital deployment that fragments producer economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Footwear Sole Material Market |
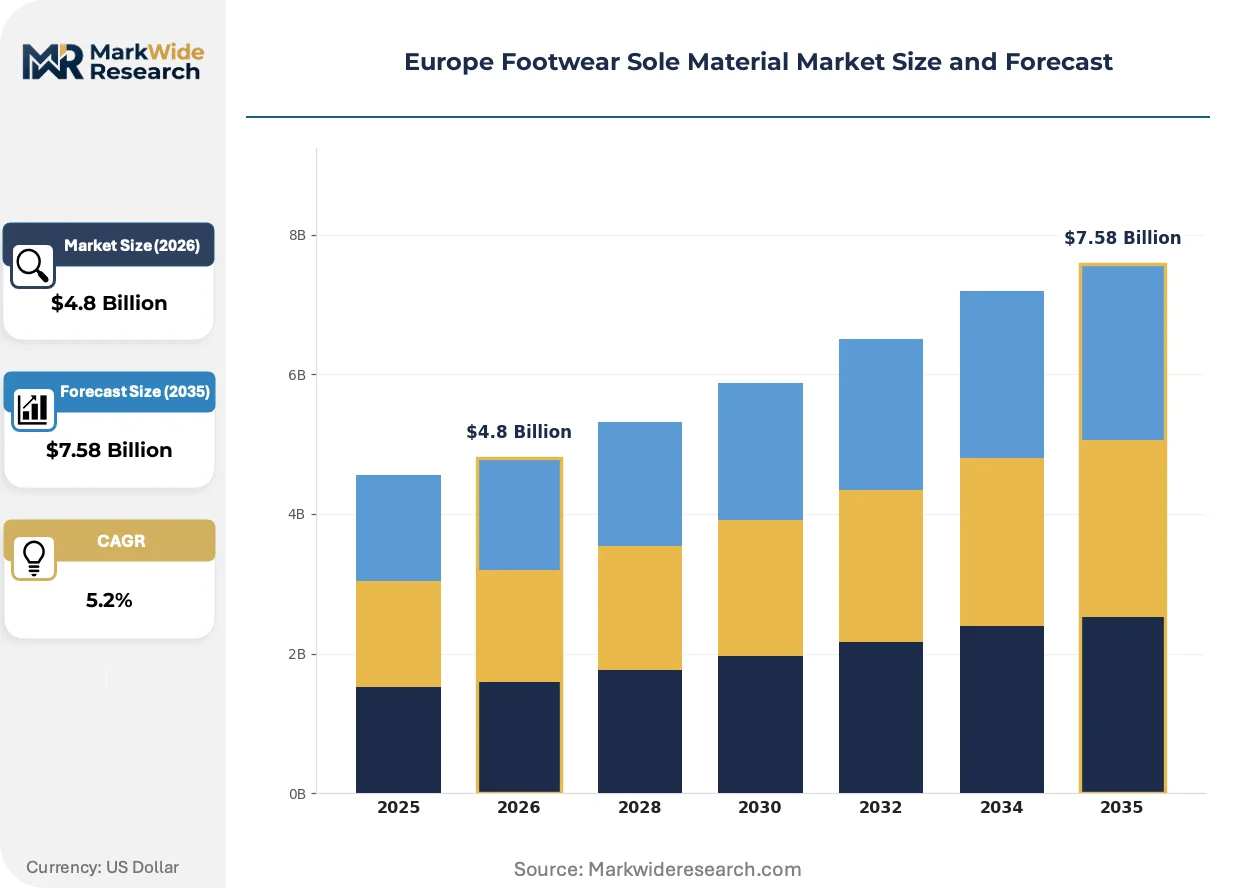
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, EVA, TPU, Leather Footwear Type: Sports Shoes, Casual Footwear, Formal Shoes, Sandals End User: Men, Women, Children, Athletes Production Stage: Raw Material, Processing, Finishing, Quality Control |
| Companies Covered | Vibram S.p.A., BASF SE, Covestro AG, INEOS Group Limited, Hexpol AB, Solvay S.A., Arkema S.A., Lanxess AG, Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Footwear Sole Material Market Shifts & Advancements
Digital process control and closed-loop material tracking are reconfiguring how European compounders validate bio-based content claims and optimize elastomer performance across heterogeneous production runs.
Mass spectrometry-based carbon fingerprinting is digitizing supply chain verification for renewable content claims. Third-party certification bodies in Germany and the Netherlands now mandate isotope analysis for mass-balance certificates. This technology is compressing audit timelines from months to weeks while exposing greenwashing risks for non-compliant compounders.
REACH authorization timelines for novel bio-based intermediates are tightening compounder R&D planning horizons. The European Chemicals Agency's 2024 substance evaluation work program prioritizes phthalate alternatives in polymer formulations. Athletic footwear brands sourcing from Italy and Portugal now require pre-registration documentation before contract award.
Direct compounder-to-brand procurement is displacing traditional distributor channels for specialized TPU grades. German and French athletic footwear manufacturers now negotiate formulation exclusivity directly with Dormagen and Antwerp production sites. This pattern concentrates volume with integrated petrochemical players while marginalizing regional compounders lacking technical service depth.
Europe Footwear Sole Material Market Segmentation
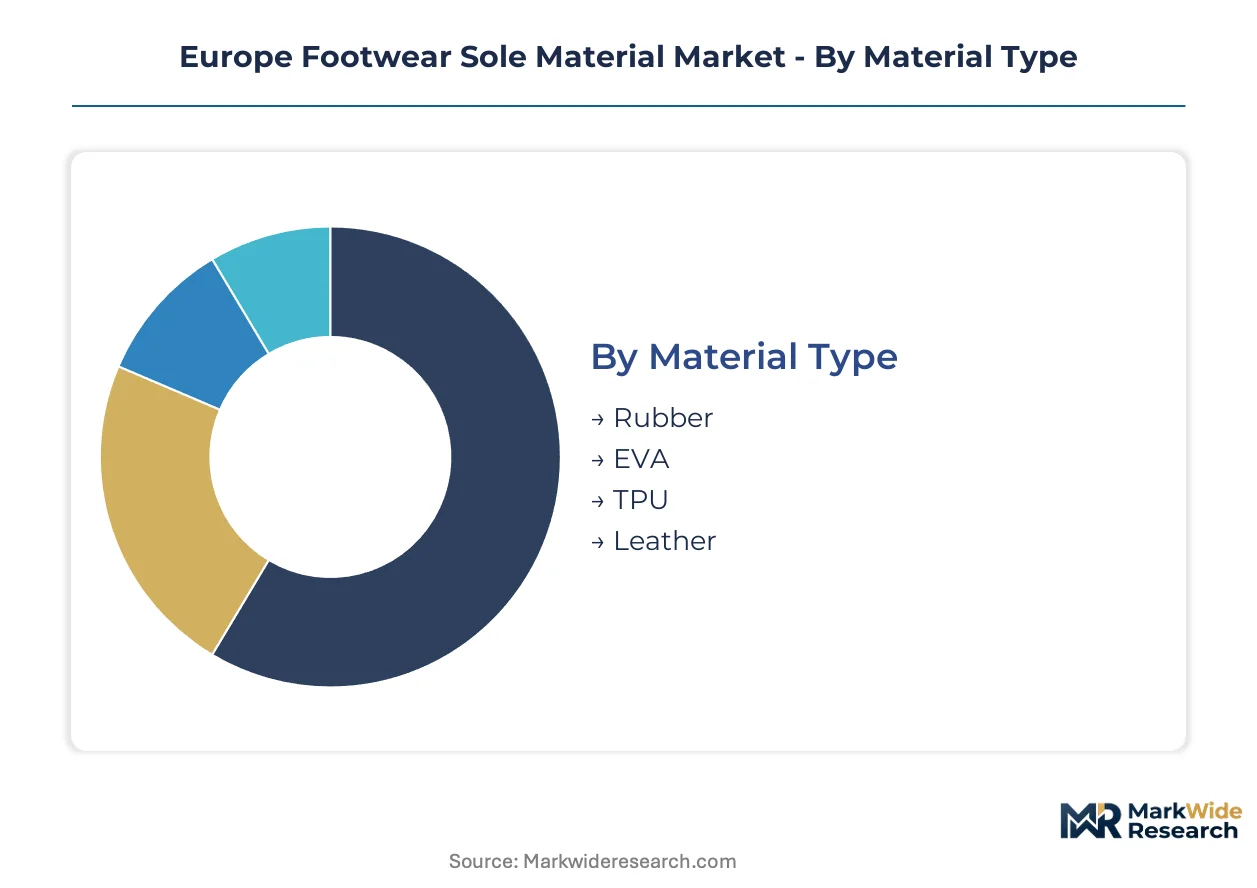
Material chemistry and end-use performance requirements fragment procurement patterns across European footwear manufacturing. Compounders must align formulation portfolios with distinct abrasion, cushioning, and regulatory demands that vary by application and customer segment.
Material Type:
Cost tier differentiation separates commodity volume plays from specialty elastomer premiums in sole compound procurement.
- Rubber:Natural and synthetic rubber compounds deliver Shore A hardness from 50 to 90 with superior oil resistance and cold-flex performance. Italy's Arzignano leather district and Portugal's Porto rubber cluster concentrate demand for industrial safety and mountaineering outsoles where REACH-compliant formulations command premium positioning.
- TPU:Thermoplastic polyurethane grades span Shore A 70 to 95 with hydrolysis resistance critical for athletic applications. Covestro AG's Dormagen site and BASF SE's Ludwigshafen campus anchor European supply as trail-running brands accelerate renewable carbon procurement under EU Green Deal thresholds.
- EVA:Ethylene-vinyl acetate foams dominate casual and children's segments through lightweight cushioning at lower unit economics. Portugal's EVA processors face F-Gas Regulation constraints on blowing-agent availability for midsole expansion.
- Leather:Vegetable-tanned and chrome-free leather soles persist in formal footwear and heritage craft segments. Italian tanneries in Tuscany supply certified grades meeting ECHA substance evaluation for restricted heavy-metal content.
Rubber commands the established base. The steepest expansion runs through TPU as athletic brands reformulate for bio-based content compliance.
Footwear Type:
Application-driven performance specifications reshape compounder R&D priorities and direct procurement relationships with finished-goods manufacturers.
- Sports Shoes:Energy return and abrasion resistance specifications from German and French athletic manufacturers push TPU and advanced rubber formulations. Direct compounder-to-brand procurement displaces distributor channels for specialized grades with formulation exclusivity clauses.
- Casual Footwear:EVA and blended polyurethane compounds balance lightweight comfort with cost efficiency at volume scale. Mass-market brands prioritize Shore A 50-65 formulations with simplified processing requirements.
- Formal Shoes:Leather soles and thin rubber injection units dominate construction where aesthetic finish and acoustic properties matter. Italian manufacturers in Milan's design corridor specify chrome-free tanning for EU Green Deal alignment.
- Sandals:Molded EVA and compressed rubber compounds address open-weather durability with minimal material weight. Portuguese compounders supply Iberian and Mediterranean markets with UV-stabilized grades.
Sports shoes concentrate the highest compounder engagement intensity. Casual footwear delivers the broadest volume base across European production.
End User:
Customer type determines sizing complexity, performance certification requirements, and distribution channel configuration for sole material suppliers.
- Men:Industrial safety and formal segments drive demand for wider lasts with reinforced heel counters. German safety footwear manufacturers specify oil-resistant rubber compounds for automotive and construction end-uses.
- Women:Fashion-forward athletic and casual categories prioritize color-stable TPU and lightweight EVA with aesthetic finish requirements. French and Italian brands lead specification setting for women's performance footwear.
- Children:Rapid size turnover and cost sensitivity favor simplified EVA formulations with basic abrasion resistance. Portuguese processors capture volume through efficient mold-change capabilities.
- Athletes:Technical trail-running and mountaineering segments demand hydrolysis-resistant elastomers with terrain-specific lug geometries. Vibram S.p.A. and specialized Italian compounders serve this premium niche with custom formulation partnerships.
Men's industrial and safety applications anchor rubber compound volumes. The athlete segment generates the fastest formulation innovation cycles and direct technical service relationships.
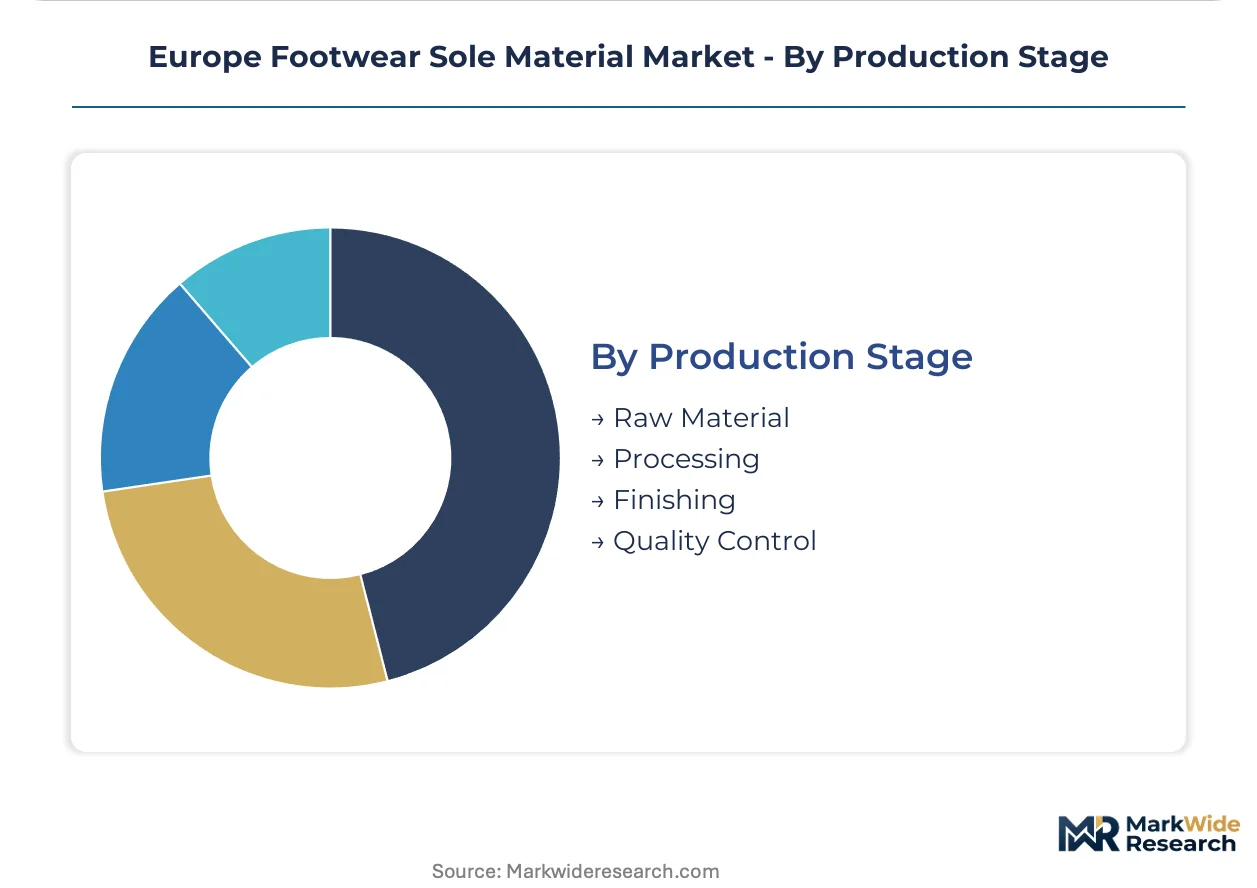
Production Stage:
Supply concentration varies across upstream petrochemical integration, midstream compounding, and downstream quality verification layers.
- Raw Material:Bio-based polyol and renewable carbon feedstock sourcing concentrates at BASF's Ludwigshafen and select Italian research institutes. Polymer chemist talent scarcity constrains scaling capacity for novel bio-intermediate development.
- Processing:Compounding operations require modified reactor temperature profiles and moisture control systems for bio-based polyols. Legacy equipment retrofit costs fragment economics for mid-size European compounders.
- Finishing:Surface treatment and multi-density bonding operations cluster in Portugal's Porto rubber cluster and Italy's Arzignano district. CSRD-mandated supply chain disclosure pushes brands toward auditable mass-balance certification.
- Quality Control:Mass spectrometry-based carbon fingerprinting compresses audit timelines for renewable content claims. German and Dutch certification bodies now mandate isotope analysis for bio-based verification.
Processing commands the deepest capital deployment and margin compression risk. Quality control represents the fastest-expanding service layer as disclosure requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export bio-based TPU formulations to French and Italian athletic footwear manufacturers, establishing a north-south trade corridor that channels renewable carbon chemistry toward premium outsole production.
Germany
BASF SE's Ludwigshafen campus anchors bio-based polyol development for athletic brands demanding renewable carbon thresholds. REACH registration timelines for novel intermediates compress R&D planning horizons at the Ludwigshafen and Dormagen chemical corridors. Bavaria's industrial safety footwear manufacturers specify oil-resistant rubber compounds for automotive sector procurement.
Italy
Vibram S.p.A. drives mountaineering and trail-running compound specialization from its northern Italian base. ECHA substance evaluation enforcement cascades phthalate restrictions through tier-two audits affecting Tuscany's chrome-free tanneries. Arzignano's leather district integrates advanced rubber compounds into hybrid sole construction for heritage craft segments.
Portugal
Porto's rubber cluster attracts bio-based TPU investment as compounders reformulate for EU Green Deal compliance. The F-Gas Regulation's phase-down timeline constrains hydrofluorocarbon availability for EVA midsole processors along the northern coast. Portuguese molders capture children's footwear volume through efficient mold-change capabilities serving Iberian mass-market brands.
France
French athletic manufacturers negotiate formulation exclusivity directly with German petrochemical production sites. CSRD-mandated supply chain disclosure pushes Paris-based finished-goods brands toward auditable mass-balance certification. The Auvergne-Rhône-Alpes region concentrates pressure-mapping integration for emerging orthopedic sole applications.
Netherlands
Dutch certification bodies mandate isotope analysis for mass-balance certificates, compressing audit timelines for renewable content claims. Rotterdam's port infrastructure handles bio-based feedstock imports serving compounders across the Rhine corridor. Mass spectrometry-based carbon fingerprinting laboratories in the Randstad region digitize supply chain verification protocols.
Europe Footwear Sole Material Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure where integrated petrochemical groups capture volume through direct brand relationships while regional compounders defend position via technical service depth. The vendor base organizes around three archetypes: multinational chemical conglomerates with upstream polyol integration, specialized elastomer compounders serving niche performance segments, and regional processors optimizing mold efficiency for mass-market tiers. Dominant competitive moves include backward integration into renewable carbon feedstocks and exclusive formulation partnerships with finished-goods brands.
Among integrated chemical groups, BASF SE and Covestro AG exemplify the upstream-control archetype through their Ludwigshafen and Dormagen production sites. Vibram S.p.A. occupies a distinct position as a compound specialist anchored in Italy's performance footwear corridor. These three entities represent the competitive spectrum from petrochemical-scale operations to formulation-focused technical service models.
| Leading Market Players |
|---|
| Vibram S.p.A. |
| BASF SE |
| Covestro AG |
| INEOS Group Limited |
| Hexpol AB |
| Solvay S.A. |
| Arkema S.A. |
| Lanxess AG |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Porto's rubber cluster channels bio-based TPU capacity toward premium athletic outsoles, concentrating formulation expertise that commands pricing power over mid-tier compounders lacking mass-balance certification. REACH authorization timelines and F-Gas Regulation compliance costs cascade downstream, compressing margins for processors without integrated polyol supply.
Pricing Analysis
Petrochemical-grade TPU, first-generation bio-based elastomers, and next-generation renewable carbon formulations stratify across premium, standard, and economy tiers. Price differentiation rests on mass-balance certification grade and direct brand procurement relationships versus distributor-mediated supply. Cost compression in standard-grade EVA runs through F-Gas Regulation constraints on blowing-agent availability. Mass-market children's footwear buyers exhibit highest price sensitivity; technical trail-running brands prioritize performance over unit cost.
Supply Chain Analysis
REACH substance evaluation and EU Green Deal chemical sustainability targets constrain feedstock flows without blocking trade, pushing compounders toward pre-registered bio-intermediate sourcing. Supply concentrates in Germany, Italy, and Portugal. Raw material dependencies span crude-derived polyols, renewable carbon feedstocks, and hydrofluorocarbon blowing agents. Single-source vulnerability sits with Ludwigshafen-centered polymer chemist talent for novel bio-based formulation. Distribution runs through direct compounder-to-brand procurement channels displacing traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polyurethane chemistry threatens incumbent petrochemical compounders with demand substitution as EU Green Deal thresholds harden. Incumbents must navigate this transition while defending formulation expertise advantages.
For Market Incumbents: Harden technical service depth around renewable carbon integration to retain direct brand procurement relationships against emerging bio-specialist compounders. Prioritize backward integration into certified bio-polyol supply at Dormagen or Ludwigshafen corridor sites. Lock formulation exclusivity clauses with French and Italian athletic manufacturers before REACH authorization timelines compress further. For New Entrants and Emerging Players: Build out chemical recycling infrastructure partnerships in Eastern Europe where end-of-life TPU collection remains underdeveloped. Target orthopedic and diabetic footwear applications in Germany's rehabilitation device corridor where Shore A 40-60 specification gaps persist. Lead with mass-balance certification and isotope-analysis documentation to satisfy CSRD-mandated supply chain disclosure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because formulation expertise concentrates at integrated petrochemical campuses while mid-size compounders face capital constraints on bio-polyol reactor retrofits. Watch for inflection when REACH authorization backlogs clear for novel bio-intermediates, signaling scalable supply of next-generation renewable carbon grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Supply | BASF SE's Ludwigshafen campus secures renewable carbon feedstock for compliant elastomer formulations. |
| Mass-Balance Certification Investment | German and Dutch certification bodies mandate isotope analysis for auditable bio-based content claims. |
| Direct Compounder-to-Brand Procurement | French athletic manufacturers negotiate formulation exclusivity, displacing traditional distributor channels. |
| Chemical Recycling Infrastructure Partnership | End-of-life TPU pyrolysis capacity in Eastern Europe creates first-mover positioning for circular material flows. |
| REACH Pre-Registration Documentation | Italian and Portuguese compounders secure contract eligibility before ECHA substance evaluation tightens. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance evaluation databases, EU customs trade records, and SEC filings from integrated chemical groups. Primary interviews engaged polymer chemists at compounding facilities, procurement leads at German and French athletic footwear manufacturers, and technical directors at certification bodies in Germany and the Netherlands. Bottom-up volume estimates from material-grade consumption patterns were triangulated against top-down market sizing from petrochemical production disclosures.
Forecast inputs span material chemistry segmentation, end-use performance tier, and regional production cluster concentration across the modeling period. CAGRs were derived from elasticity-adjusted demand projections for bio-based content thresholds and F-Gas Regulation phase-down timelines. Industry-specific inputs include REACH authorization pipeline status for novel bio-intermediates and CSRD implementation schedules affecting supply chain disclosure requirements.
Stress conditions across crude-derived polyol cost volatility, REACH registration timeline compression, and bio-based grade technical performance gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity and athletic brand renewable procurement commitments. Material shifts in ECHA substance evaluation prioritization or F-Gas Regulation acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Stockings Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Rolle Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Asia Pacific Garment Steamers Market