
 Breathing Disorders Treatment Market | 2026-2036
Breathing Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Breathing Disorders Treatment Market Analysis
Asset-light leasing models for nebulizers and CPAP machines are reshaping competitive dynamics in respiratory care. GlaxoSmithKline leverages extensive R&D pipelines to sustain leadership across asthma and COPD portfolios. AstraZeneca anchors its position through biologics specialization in severe eosinophilic asthma. Boehringer Ingelheim competes via dominance in LAMA-LABA combination therapies for chronic obstructive pulmonary disease.
Breathing disorders treatment encompasses pharmaceutical agents, mechanical devices, and digital therapeutics designed to restore or maintain pulmonary function through bronchodilation, anti-inflammatory action, oxygen supplementation, or airway pressure management. Metered-dose inhalers incorporate hydrofluoroalkane propellants at specific particle size distributions to achieve deep lung deposition. Inhalers command the largest product-type revenue pool due to chronic prescription volumes, while oxygen therapy devices capture expanding margins as home-based reimbursement broadens. The sleep apnea segment within therapy areas is accelerating fastest, driven by diagnostic access improvements and wearable screening technologies.
The FDA oversees device clearance and combination-product classification, while the EPA regulates hydrofluoroalkane propellant transitions under environmental mandates. The EU MDR imposes stricter clinical-evidence requirements on nebulizers and CPAP systems entering European markets. Stakeholders must monitor how propellant-phase regulations intersect with device redesign timelines to preserve portfolio viability.
Market Dynamics
The transition from hydrofluoroalkane to low-global-warming-potential propellants is forcing simultaneous reformulation of metered-dose inhalers and redesign of device architectures, compressing development timelines across pharmaceutical portfolios.
Growth Catalysts
- Connected inhaler mandates:The FDA's evolving guidance on digital therapeutics integration accelerates sensor-enabled adherence monitoring in the United States. Device manufacturers are embedding Bluetooth modules to capture real-world usage data.
- Homecare reimbursement expansion:Germany's statutory health insurance framework now covers portable oxygen concentrators and CPAP machines for outpatient chronic obstructive pulmonary disease management. This shifts treatment volume from acute facilities to domestic settings.
- Biologics pipeline maturation:Anti-interleukin-5 and anti-IgE monoclonal antibodies are penetrating severe eosinophilic asthma populations previously managed with corticosteroids alone. Pulmonologists are expanding specialty referral networks to administer these therapies.
Market Restraints
- Propellant supply concentration:HFA-152a and HFO-1234ze manufacturing capacity concentrates among three chemical suppliers in China and the United States. Any disruption to this concentrated base stalls inhaler production globally.
- EU MDR clinical evidence burdens:Nebulizers and positive airway pressure devices now require expanded clinical investigations for CE marking renewal. Smaller device manufacturers lack capital to generate this evidence.
- Generic bronchodilator substitution:Patent expirations on long-acting beta-agonist monotherapies enable rapid commoditization of salmeterol and formoterol inhalers. Price erosion compresses margins for originator portfolios.
Strategic Opportunities
- Rural diagnostic penetration:Wearable pulse oximetry and smartphone-integrated spirometry are reaching undiagnosed sleep apnea populations in India. Screening technology is bypassing traditional polysomnography bottlenecks.
- Propellant transition incentives:The EPA's Significant New Alternatives Policy program offers streamlined review pathways for HFA-free inhaler submissions. First movers capture regulatory preference and shelf positioning.
- Digital therapeutic bundling:Cognitive behavioral therapy modules for anxiety-driven dyspnea are integrating with prescribed bronchodilator regimens. Payers in the United Kingdom are piloting bundled reimbursement for these combinations.
Industry Challenges
- Combination product expertise scarcity:Inhaler development now demands simultaneous mastery of pharmaceutical formulation, electronic sensor engineering, and software validation. Firms struggle to recruit cross-functional teams fluent in FDA's combination product regulations.
- Legacy device interoperability:Health systems in the United States have accumulated incompatible positive airway pressure machines across multiple vendors. Replacing these with connected platforms requires costly infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathing Disorders Treatment Market |
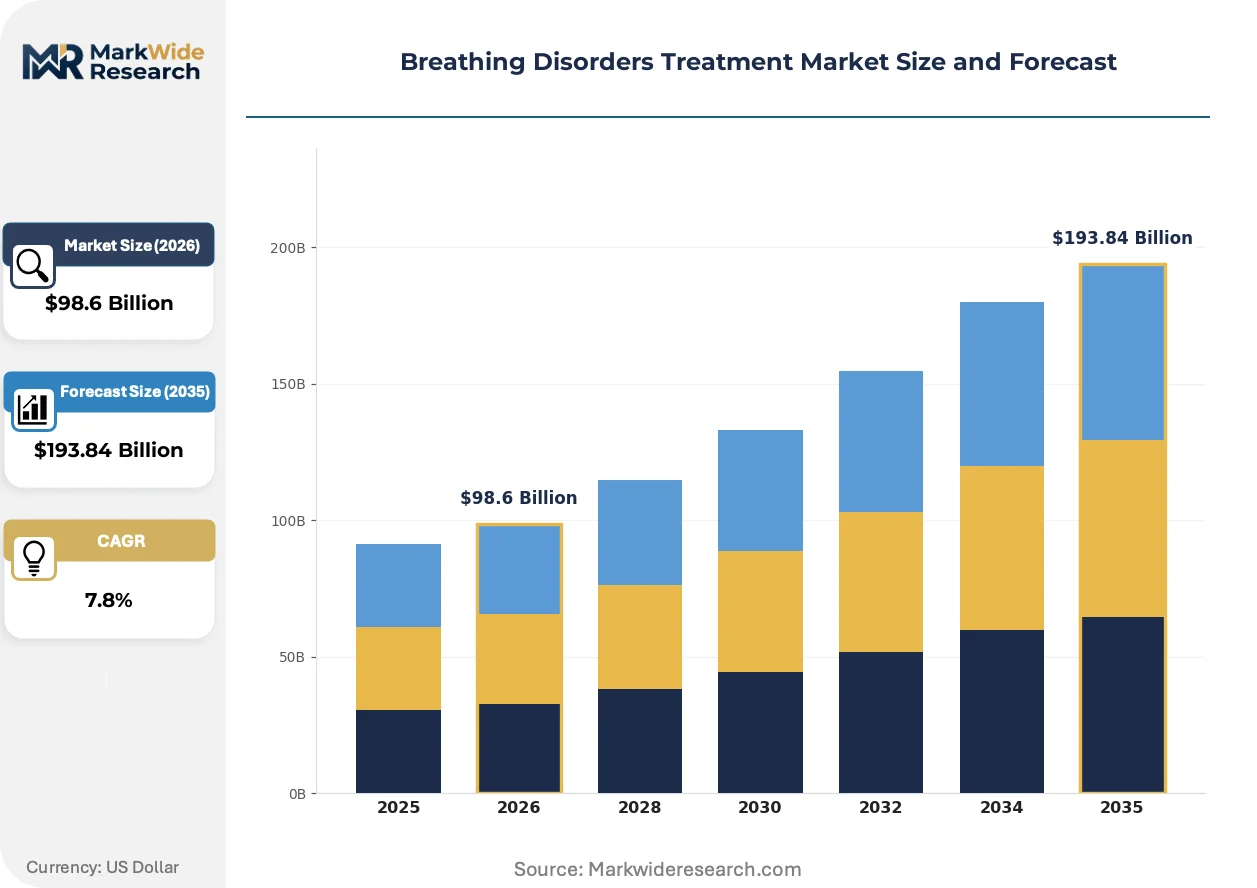
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $193.84 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Therapy Devices, CPAP Machines Therapy Area: Asthma, COPD, Sleep Apnea, Pulmonary Fibrosis End User: Hospitals, Homecare Settings, Clinics, Rehabilitation Centers Delivery Mode: Oral, Inhalation, Subcutaneous, Intravenous |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Novartis, Boehringer Ingelheim, Teva Pharmaceutical Industries, Merck & Co., Sanofi, Pfizer, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathing Disorders Treatment Market Emerging Trajectories
Digital biomarker capture and algorithmic dosing adjustment are converging to transform chronic respiratory disease from episodic crisis management into continuous, data-driven care optimization.
Artificial intelligence-enabled auscultation platforms are virtualizing the traditional stethoscope examination for wheeze and crackle detection. Primary care networks in the United Kingdom are deploying these smartphone-connected acoustic sensors to triage asthma exacerbations before emergency presentation. The technology is compressing specialist referral timelines while expanding diagnostic access to underserved regions.
The EU F-Gas Regulation's phasedown schedule is mandating transition away from hydrofluoroalkane propellants in all metered-dose inhalers by 2036. Pharmaceutical manufacturers are accelerating dry powder inhaler development and novel liquid propellant formulations to preserve portfolio continuity. German and French regulators are coordinating early approval pathways for these redesigned devices to prevent supply interruptions.
Patient-initiated therapy adjustments based on fractional exhaled nitric oxide readings are displacing rigid physician-directed dosing schedules. Severe asthma populations in Australia and Canada are adopting handheld FeNO monitors to personalize corticosteroid stepping. This behavioral shift is reducing oral steroid exposure while demanding new reimbursement frameworks for self-monitoring consumables.
Breathing Disorders Treatment Market Segmentation
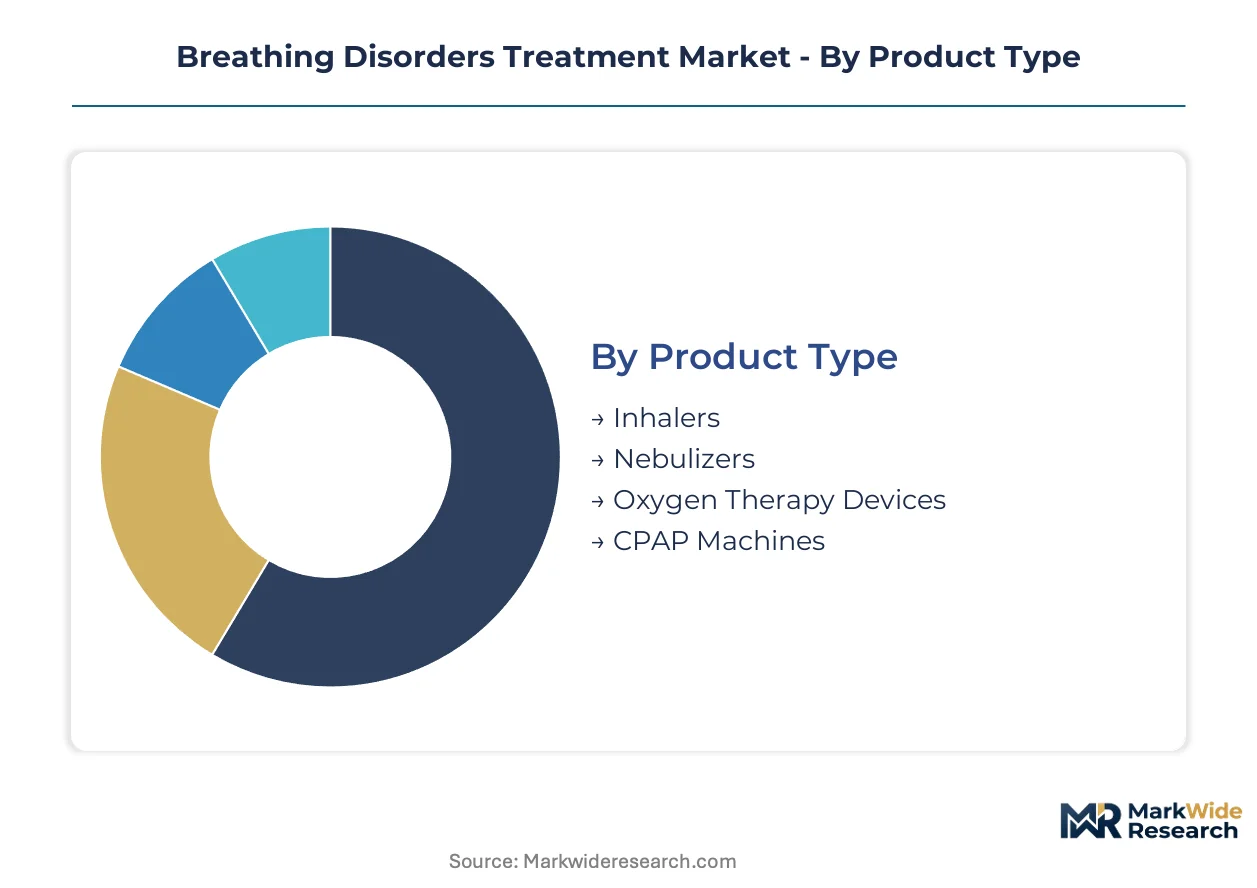
Segmentation in respiratory care reveals distinct procurement patterns across device categories, therapy areas, and care settings. Pharmaceutical manufacturers and device suppliers calibrate portfolio investments differently for chronic maintenance versus acute intervention segments.
Product Type:
Mature inhaler technologies coexist with emerging connected device platforms across this category.
- Inhalers:Metered-dose and dry powder variants deliver bronchodilators and corticosteroids through hydrofluoroalkane or breath-actuated mechanisms. Demand concentrates in Germany and the United States where prescription volumes for asthma and COPD maintenance therapy drive recurring revenue pools; the EPA's propellant transition mandates are forcing simultaneous reformulation and device redesign.
- Oxygen Therapy Devices:Portable concentrators and stationary systems extract and deliver medical-grade oxygen through pressure swing adsorption or membrane separation. Homecare settings in Germany are expanding fastest under statutory reimbursement expansion for outpatient COPD management.
- Nebulizers:Compressor and mesh technologies aerosolize liquid medications for patients unable to coordinate breath-actuated delivery.
- CPAP Machines:Continuous positive airway pressure devices maintain patent airways during sleep through motorized blower systems and humidification circuits.
Inhalers retain volume leadership; oxygen therapy devices hold the steepest expansion curve.
Therapy Area:
Application intensity varies sharply between episodic crisis management and continuous chronic disease control.
- COPD:Chronic obstructive pulmonary disease demands combined bronchodilator therapy, oxygen supplementation, and pulmonary rehabilitation. Germany's statutory health insurance framework now covers portable oxygen concentrators for outpatient management.
- Sleep Apnea:Obstructive sleep apnea treatment centers on positive airway pressure therapy and mandibular advancement devices. Wearable screening technologies in India are bypassing traditional polysomnography bottlenecks to reach undiagnosed rural populations.
- Asthma:Inflammatory airway disease managed through inhaled corticosteroids, long-acting beta-agonists, and biologic modifiers for severe eosinophilic phenotypes.
- Pulmonary Fibrosis:Interstitial lung disease with limited pharmaceutical options, focusing on antifibrotic agents and supplemental oxygen for hypoxemic patients.
COPD commands the largest installed device base; sleep apnea is climbing the fastest.
End User:
Customer type determines reimbursement pathway complexity and device specification requirements.
- Homecare Settings:Domestic environments where patients self-administer oxygen therapy, CPAP, or nebulized medications. Germany's statutory health insurance framework has shifted treatment volume from acute facilities to domestic settings through expanded portable device coverage.
- Hospitals:Acute care facilities managing respiratory failure, exacerbations, and perioperative support through high-flow oxygen and mechanical ventilation.
- Clinics:Outpatient pulmonary practices delivering spirometry, biologic infusions, and device fitting services.
- Rehabilitation Centers:Post-acute facilities providing pulmonary rehabilitation, oxygen weaning protocols, and sleep therapy adherence coaching.
Homecare settings are gaining share fastest; hospitals retain the highest device specification thresholds.
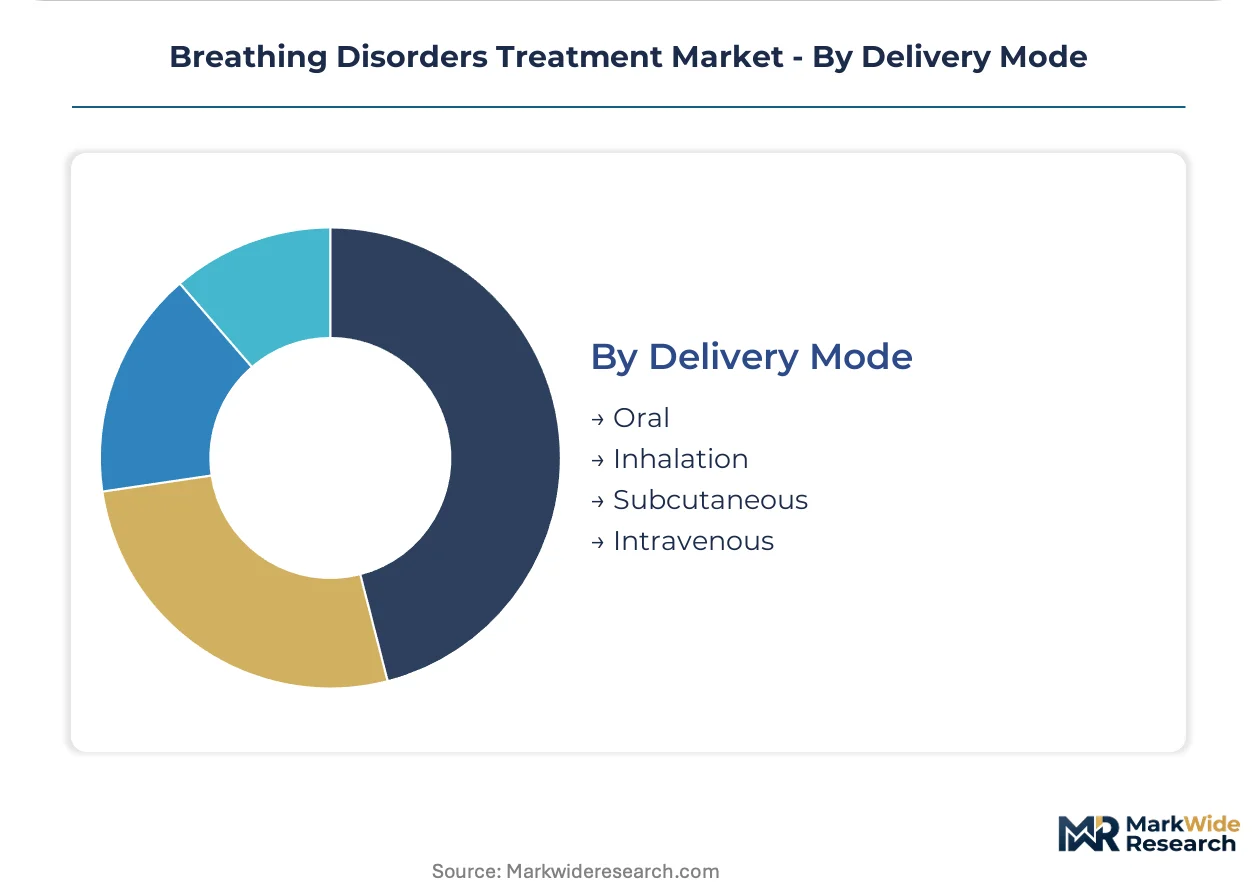
Delivery Mode:
Route of administration selection depends on drug physicochemical properties and patient coordination capacity.
- Inhalation:Direct pulmonary deposition through pressurized or breath-actuated aerosol systems. The FDA's evolving guidance on connected inhaler devices is accelerating Bluetooth-enabled adherence monitoring in the United States.
- Oral:Systemic absorption through gastrointestinal tract for maintenance corticosteroids and phosphodiesterase inhibitors.
- Subcutaneous:Biologic monoclonal antibodies targeting interleukin-5 and IgE pathways in severe eosinophilic asthma.
- Intravenous:Hospital-administered acute rescue therapies and perioperative bronchodilation.
Inhalation dominates chronic prescription volumes; subcutaneous biologics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's Significant New Alternatives Policy program is accelerating propellant transition timelines for inhaler manufacturers in the United States. Germany's statutory health insurance framework has created reimbursement clarity for home-based oxygen therapy and CPAP devices. India's wearable screening technologies are bypassing traditional diagnostic bottlenecks to reach undiagnosed rural sleep apnea populations.
United States
FDA guidance on connected inhaler devices is embedding Bluetooth-enabled adherence monitoring into commercial respiratory portfolios. The EPA regulates hydrofluoroalkane propellant transitions under environmental mandates that compress device redesign timelines. Boston's medical device cluster hosts development operations for sensor-integrated inhaler platforms targeting digital therapeutic integration.
Germany
COPD prevalence and statutory reimbursement clarity sustain sustained adoption of portable oxygen concentrators and CPAP machines. The EU MDR imposes stricter clinical-evidence requirements on nebulizers and positive airway pressure systems entering domestic markets. North Rhine-Westphalia's industrial base concentrates manufacturing operations for precision-engineered respiratory device components.
India
Wearable pulse oximetry and smartphone-integrated spirometry are reaching undiagnosed sleep apnea populations in rural districts. The country's national pharmaceutical regulator oversees device clearance pathways for imported respiratory equipment. Maharashtra's Mumbai-Pune corridor anchors distribution networks for both imported and domestically assembled nebulizer and oxygen concentrator systems.
United Kingdom
Payers are piloting bundled reimbursement for cognitive behavioral therapy modules integrated with prescribed bronchodilator regimens. MHRA alignment with EU MDR transitional provisions affects CE marking renewal timelines for legacy device portfolios. London's healthcare procurement networks are deploying AI-enabled auscultation platforms to primary care triage for asthma exacerbations.
China
NMPA oversight of combination product classification intersects with domestic manufacturing scale for compressor nebulizers and oxygen concentrators. The country's dual carbon goals pressure propellant-intensive inhaler supply chains toward dry powder alternatives. Yangtze River Delta medical device clusters are expanding production capacity for export-oriented respiratory equipment.
Breathing Disorders Treatment Market Vendor Landscape
On the supply side, the industry is consolidating around pharmaceutical-device combination expertise and biologics specialization. Tiered competitive positioning separates large-cap diversified portfolios from mid-cap device specialists and generic bronchodilator manufacturers. Three archetypes dominate: R&D-intensive biologics developers, precision device engineers, and scale-driven generic inhaler suppliers. Strategic moves concentrate on M&A for digital therapeutic capabilities and vertical integration into propellant supply chains.
Within the biologics-specialist tier, AstraZeneca and GlaxoSmithKline exemplify divergent positioning strategies. AstraZeneca anchors its competitive stance through monoclonal antibody development for severe eosinophilic asthma phenotypes. GlaxoSmithKline occupies a position spanning both pharmaceutical formulation and connected device platform integration. Boehringer Ingelheim represents the LAMA-LABA combination therapy archetype within chronic obstructive pulmonary disease maintenance portfolios.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Novartis |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries |
| Merck & Co. |
| Sanofi |
| Pfizer |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries nebulizer components and HFA propellant precursors at freight rates that directly compress margins for European device manufacturers while amplifying price spreads between CE-marked premium systems and unbranded economy alternatives. This logistics cost dynamic reinforces how supply concentration upstream translates into tiered downstream pricing power.
Pricing Analysis
Certification level creates the primary spread between FDA-cleared connected inhalers and basic compressor nebulizers lacking CE marking. Three-tier pricing structure across premium, standard, and economy levels dominates the market, with ISO 13485-certified manufacturers commanding substantial premiums over non-certified competitors. Cost compression in the generic bronchodilator segment is intensifying because patent expirations on long-acting beta-agonist monotherapies enable rapid substitution. Homecare procurement managers in Germany exhibit the highest price sensitivity, while hospital purchasing committees prioritize device interoperability over unit cost.
Supply Chain Analysis
Hydrofluoroalkane propellant precursors and specialized polymer housings feed from concentrated chemical manufacturing bases in China and the United States. Mesh nebulizer piezoelectric elements and CPAP blower motors draw from Taiwanese and South Korean electronics suppliers. Single-source vulnerability around HFA-152a manufacturing capacity in China stalls inhaler production globally during any disruption. Distribution runs through medical device distributors in Germany, direct hospital contracts in the United States, and pharmacy retail chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breathing disorders treatment market sits in early-cycle expansion as homecare reimbursement frameworks in Germany and wearable diagnostic penetration in India accelerate adoption beyond traditional clinical settings.
For Market Incumbents: Pre-empt generic bronchodilator commoditization by accelerating backward integration into propellant supply chains and securing exclusive sensor-technology licensing for connected inhaler platforms. GlaxoSmithKline and AstraZeneca must defend against emerging biologics specialists by expanding pulmonologist referral networks for severe eosinophilic asthma administration.
For New Entrants and Emerging Players: Rural diagnostic penetration in India represents the most penetrable entry point, where smartphone-integrated spirometry and wearable pulse oximetry bypass traditional polysomnography bottlenecks. Portable oxygen concentrator leasing models for outpatient COPD management in Germany offer a second white-space target. A direct-to-patient subscription model with statutory insurance pre-authorization support provides the optimal go-to-market angle.
For Investors and Strategic Acquirers: Digital therapeutic developers with FDA-cleared cognitive behavioral therapy modules for anxiety-driven dyspnea command premium valuations as bundled reimbursement pilots expand in the United Kingdom. Long-term viability hinges on capturing regulatory preference through early EPA Significant New Alternatives Policy submissions for HFA-free inhaler platforms. Watch for MHRA alignment decisions with EU MDR transitional provisions as the inflection signal for European device portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Transition Acceleration | EPA streamlined review pathways for HFA-free submissions capture regulatory preference and shelf positioning. |
| Connected Inhaler Platform Integration | FDA guidance on Bluetooth-enabled adherence monitoring embeds sensor technology into commercial respiratory portfolios. |
| Biologics Pipeline Diversification | Anti-interleukin-5 monoclonal antibodies penetrate severe eosinophilic asthma populations previously managed with corticosteroids alone. |
| Homecare Reimbursement Strategy | Germany's statutory health insurance framework shifts treatment volume from acute facilities to domestic settings through portable device coverage. |
| Digital Therapeutic Bundling | United Kingdom payer pilots for cognitive behavioral therapy modules integrated with bronchodilator regimens create new revenue pools. |
Methodological Framework
A standing panel of respiratory device product managers, hospital GPO contracts specialists, pulmonologists managing severe asthma referrals, and statutory health insurance reimbursement officers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA combination product assessments, ClinicalTrials.gov biologics entries, and German statutory insurance reimbursement bulletins. Bottom-up demand modeling for inhaler prescription volumes and top-down macroeconomic triangulation anchored the analytical framework.
Scenario-bracketing around propellant transition timelines and EU MDR implementation phases shaped the projection horizon across therapy areas and delivery modes. Segmentation dimensions modeled include product type, therapy area, end-user setting, and regional regulatory cluster. CAGRs derived from historical prescription volume trajectories, device shipment data, and reimbursement expansion schedules. Forecast inputs incorporated FeNO self-monitoring adoption curves in Australia and Canada alongside wearable screening penetration rates in India.
Practitioners should monitor EPA Significant New Alternatives Policy submission volumes and EU F-Gas Regulation phasedown enforcement for early signals of portfolio disruption. Forecasts reflect assumptions around propellant manufacturing capacity expansion and MDR clinical evidence generation timelines. Cross-checking against CMS Medicare oxygen therapy reimbursement data and German GKV outpatient device expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Respiratory Disorders Treatment Market