
 Viral Pneumonia Treatment Market | 2026-2036
Viral Pneumonia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Pneumonia Treatment Market Analytics
Combination therapy bundling is rebalancing procurement decisions across hospital formularies, as institutions seek to consolidate vendor relationships and streamline inventory management. Pfizer Inc. leverages its broad infectious disease portfolio to anchor long-term supply agreements with integrated delivery networks. Gilead Sciences, Inc. specializes in antiviral development pipelines that differentiate its positioning among academic medical centers. Merck & Co., Inc. competes through manufacturing scale that sustains reliable supply during seasonal demand surges.
Viral pneumonia treatment encompasses pharmaceutical and supportive interventions targeting viral pathogens infecting lung parenchyma, with antiviral agents typically requiring specific viral identification or empiric coverage against influenza, respiratory syncytial virus, or SARS-CoV-2 based on polymerase chain reaction diagnostics and clinical severity scoring. The primary purpose centers on reducing mortality, shortening hospitalization duration, and preventing progression to acute respiratory distress syndrome through pathogen-directed therapy and adjunctive corticosteroid modulation. Antivirals and monoclonal antibodies represent the leading margin pool where novel mechanisms command premium positioning, while intravenous administration dominates inpatient revenue capture though inhalation routes are gaining traction in early-stage outpatient protocols. Hospitals remain the dominant end-user channel, yet home care segments are expanding as oral antiviral bioavailability improves and remote monitoring technologies mature.
The FDA's infectious disease guidance and the EMA's antiviral efficacy standards shape clinical trial endpoints and label expansions, directly influencing which therapeutic classes achieve formulary placement. The WHO's essential medicines list and national treatment guidelines from China's NMPA further constrain or enable market access depending on local epidemiological prioritization. Stakeholders must monitor resistance surveillance networks and regulatory science initiatives that redefine combination therapy requirements before committing to manufacturing capacity expansions.
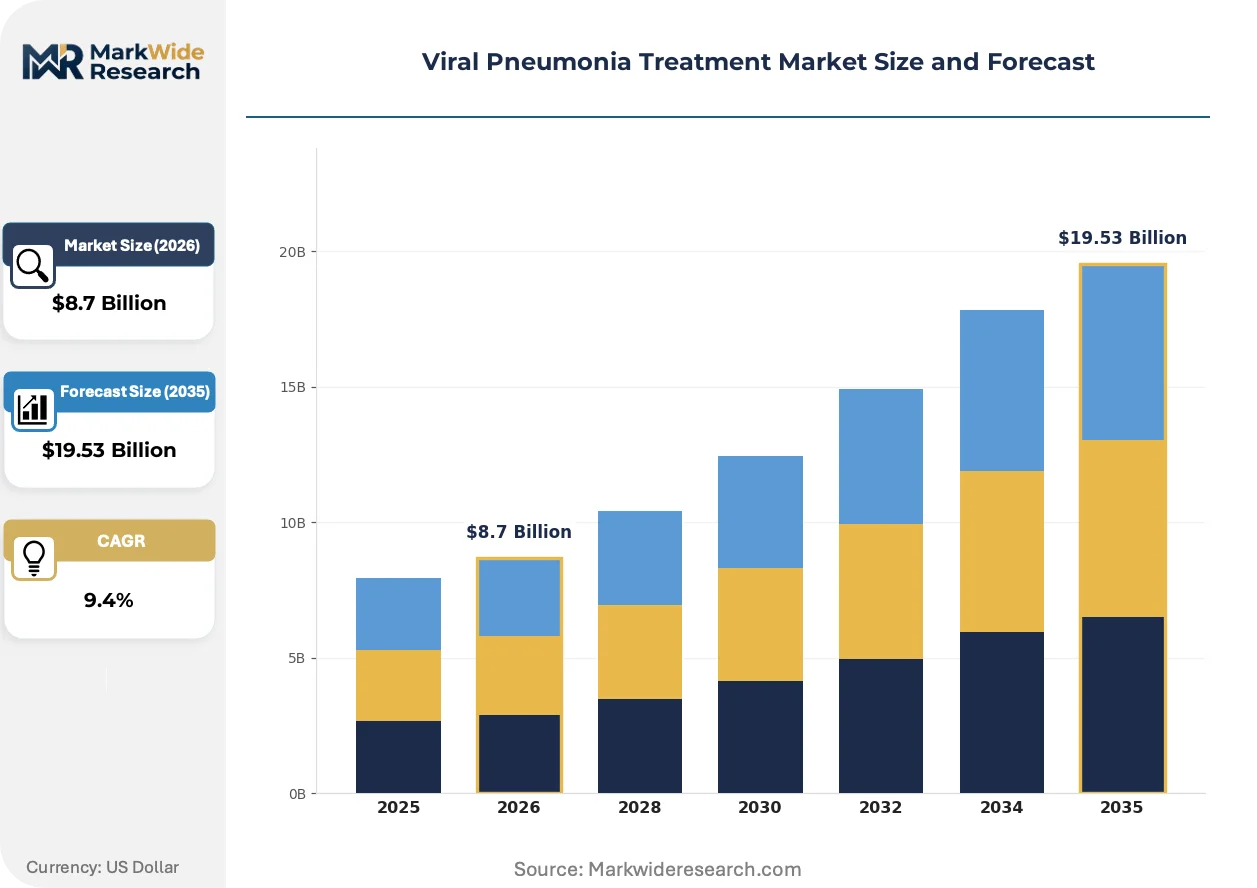
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing antiviral manufacturers to bundle diagnostics with therapeutics in single-source contracts. This structural pressure favors portfolios spanning polymerase chain reaction platforms through monoclonal antibody infusions.
Growth Catalysts
- Accelerated FDA Approval Pathways:The FDA's infectious disease fast-track designation compresses Phase III timelines from 48 to 24 months for novel antiviral mechanisms. Academic medical centers gain earlier access to mechanism-of-action data, driving formulary pre-positioning.
- Respiratory Syncytial Virus Co-Infection Protocols:Pediatric intensive care units in the United States are standardizing empiric antiviral coverage for RSV-influenza overlap. This protocol expansion pulls neuraminidase inhibitors and fusion inhibitors into bundled order sets.
- Point-of-Care Molecular Diagnostics:Cepheid and BioFire platforms now return viral identification within 45 minutes at bedside. Emergency departments are rewriting admission algorithms around rapid pathogen confirmation.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70 percent of antiviral raw material synthesis concentrates in Zhejiang and Jiangsu provinces. Geopolitical friction or environmental enforcement surges in China disrupt global supply continuity.
- Antiviral Resistance Surveillance Gaps:The WHO's Global Influenza Surveillance and Response System lacks real-time resistance reporting from outpatient settings. Empiric prescribing continues despite circulating resistant strains.
- Reimbursement Compression for Supportive Care:Medicare's hospital-acquired condition reduction program penalizes extended mechanical ventilation. This creates perverse incentives to discharge before optimal antiviral course completion.
Strategic Opportunities
- Inhalation Route Development:Nebulized antiviral formulations bypass first-pass metabolism and enable outpatient administration. Pulmonary delivery technology from United Kingdom-based specialist firms is attracting licensing interest from large-cap manufacturers.
- EMA's Adaptive Pathway Pilot:The European Medicines Agency's rolling review mechanism allows conditional approval based on surrogate endpoints. This regulatory tailwind accelerates market entry for novel host-directed therapies targeting acute respiratory distress syndrome prevention.
- Home Infusion Services Expansion:Monoclonal antibody administration is migrating from infusion centers to home health nursing. This channel innovation captures margin previously absorbed by hospital facility fees.
Industry Challenges
- Clinical Pharmacology Talent Scarcity:Antiviral pharmacokinetic modeling for special populations requires expertise in physiologically-based pharmacokinetic simulation. Contract research organizations report 18-month backlogs for qualified modelers.
- Cold Chain Integrity for Biologics:Temperature excursions during last-mile distribution to rural hospitals compromise monoclonal antibody stability. Capital deployment into validated packaging and real-time monitoring systems strains mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Pneumonia Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Corticosteroids, Monoclonal Antibodies, Supportive Care Administration Route: Intravenous, Oral, Inhalation, Subcutaneous End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Treatment Protocol: Outpatient Care, Inpatient Care, Intensive Care Unit, Preventive Treatment |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Merck & Co., Inc., Gilead Sciences, Inc., AstraZeneca, Novartis AG, F. Hoffmann-La Roche Ltd., Sanofi, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Pneumonia Treatment Market Evolving Landscape
Artificial intelligence is compressing antiviral lead identification timelines while regulatory science redefines acceptable evidence standards for combination therapy approvals. These forces are reshaping how manufacturers prioritize pipeline investments and clinical trial design.
Machine learning platforms trained on viral protease structural data are automating candidate prioritization for medicinal chemistry teams. Large-cap manufacturers have embedded these tools into early-stage discovery, reducing hit-to-lead cycles from 18 months to 7 months. This acceleration is concentrating early-phase investment in computational biology capabilities.
The EMA's platform technology designation allows extrapolation of safety data across viral serotypes, reducing the patient exposure required for label expansion. Vaccine-adjacent antiviral developers are restructuring regulatory strategies around this pathway. European submissions for respiratory syncytial virus prophylaxis now lead US filings to exploit this framework.
Integrated delivery networks are unbundling antiviral procurement from diagnostic equipment leases, reversing decade-old bundled contracting conventions. Hospital pharmacy and therapeutics committees now negotiate antiviral formularies separately from molecular platform acquisitions. This disintermediation is most visible in the United States, where three large systems have completed such separations since 2023.
Viral Pneumonia Treatment Market Segmentation
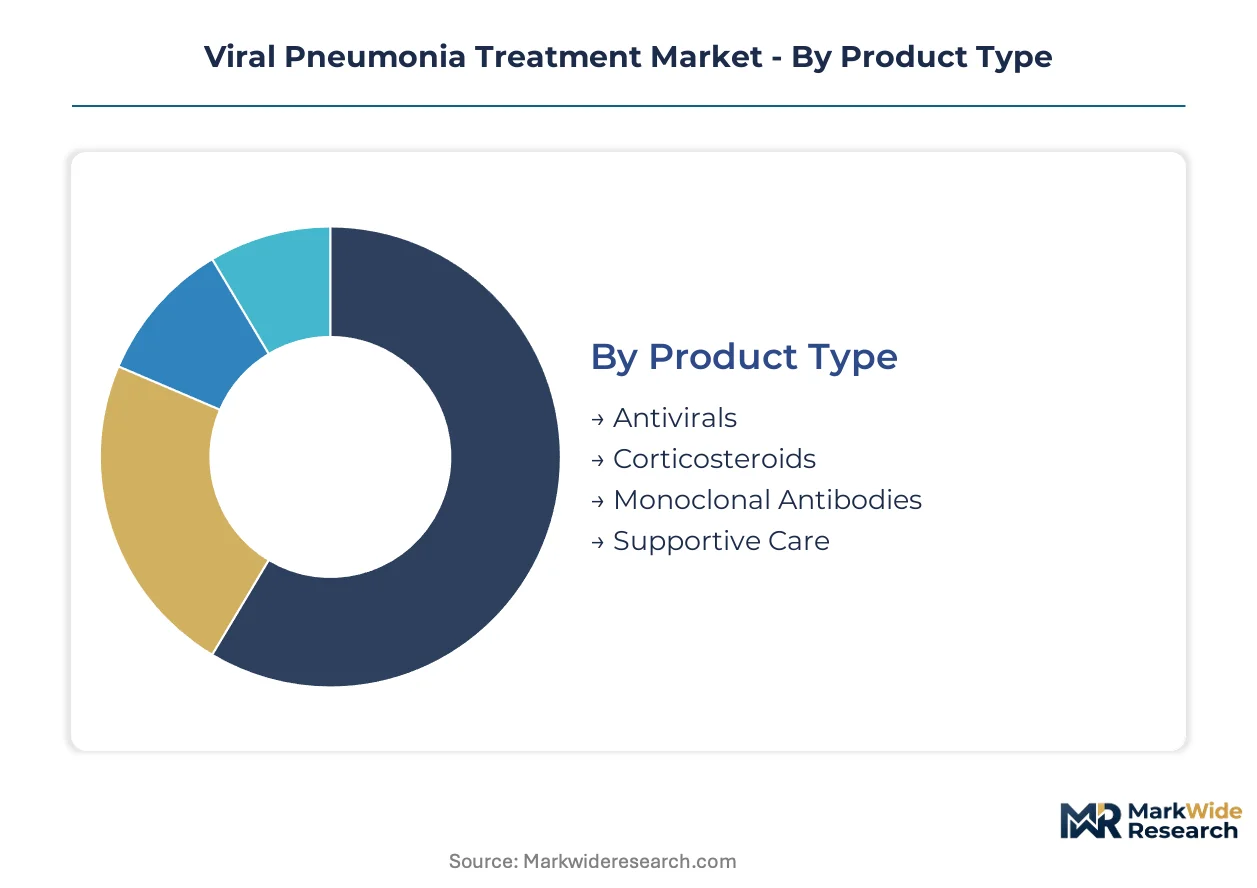
Antiviral manufacturers configure R&D pipelines and manufacturing capacity around distinct product-performance tiers and delivery modalities. Segmentation clarity enables targeted positioning against hospital formulary committees and emerging home infusion channels.
Product Type:
Mechanism of action defines reimbursement tiers and manufacturing complexity across the therapeutic landscape.
- Antivirals:Direct-acting agents targeting neuraminidase, RNA polymerase, or viral entry mechanisms command premium formulary placement. Demand clusters in United States academic medical centers where rapid pathogen identification enables pathogen-directed therapy.
- Monoclonal Antibodies:Engineered immunoglobulins deliver passive immunity with extended half-lives requiring single-dose administration. Pediatric intensive care units in tertiary hospitals drive adoption for respiratory syncytial virus prophylaxis in high-risk infants.
- Corticosteroids:Adjunctive immunomodulators reduce inflammatory lung injury in severe disease.
- Supportive Care:Oxygen delivery, fluid management, and mechanical ventilation protocols.
Antivirals lead on scale; monoclonal antibodies lead on momentum.
Administration Route:
Delivery modality determines care setting economics and patient throughput capacity.
- Intravenous:Hospital-based infusion enables rapid bioavailability in critical illness. United States emergency departments anchor demand where admission algorithms prioritize immediate therapeutic intervention.
- Inhalation:Nebulized formulations bypass hepatic first-pass metabolism for direct pulmonary deposition. United Kingdom pulmonary delivery specialists are licensing technology to large-cap manufacturers seeking outpatient expansion.
- Oral:Tablet and capsule formulations support discharge planning and home completion of therapy courses.
- Subcutaneous:Depot injections enable extended-release pharmacokinetics for prophylactic indications.
Intravenous dominates current revenue capture; inhalation is climbing the fastest toward outpatient protocols.
End User:
Channel structure is fragmenting as bioavailability improvements enable site-of-care migration.
- Hospitals:Inpatient wards and emergency departments concentrate acute antiviral administration. Integrated delivery networks in the United States negotiate bundled contracts spanning diagnostics through therapeutics.
- Home Care:Nursing services and remote monitoring platforms enable post-discharge monoclonal antibody completion. Medicare reimbursement shifts are accelerating channel investment by specialty pharmacy providers.
- Clinics:Urgent care and outpatient infusion centers handle stable patients requiring parenteral therapy.
- Long-term Care Facilities:Skilled nursing environments manage prophylaxis in immunocompromised resident populations.
Hospitals retain volume concentration; home care shows steepest expansion trajectory.
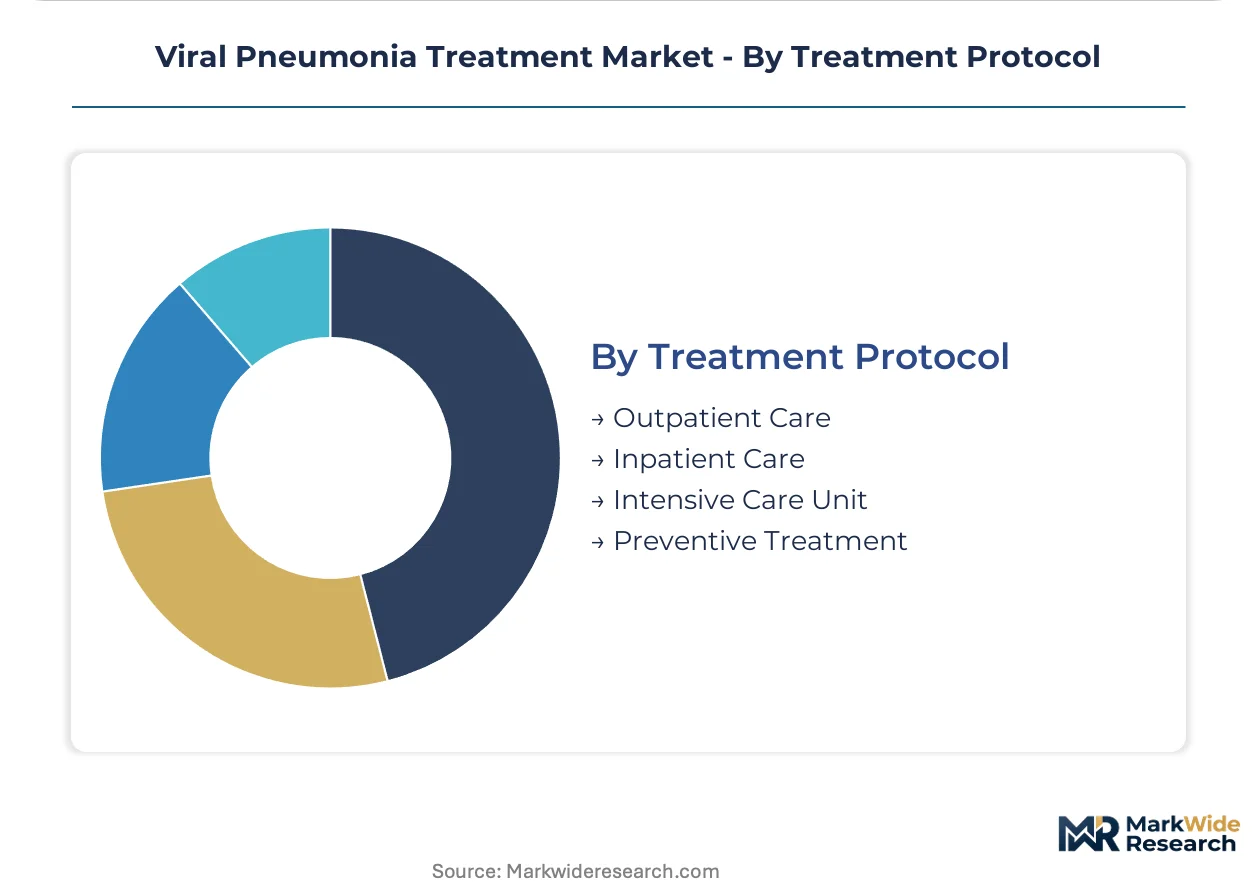
Treatment Protocol:
Clinical severity stratification determines therapeutic intensity and monitoring requirements.
- Inpatient Care:Standard hospital admission protocols manage moderate respiratory compromise requiring supplemental oxygen. General medical floors in United States community hospitals generate consistent antiviral utilization.
- Intensive Care Unit:Mechanical ventilation and extracorporeal support for acute respiratory distress syndrome. Academic medical centers concentrate specialized antiviral-corticosteroid combination protocols.
- Outpatient Care:Early oral antiviral initiation within 48 hours of symptom onset.
- Preventive Treatment:Pre-exposure prophylaxis for high-risk immunocompromised populations.
Inpatient care anchors utilization; intensive care unit protocols gain share fastest through severity-based triage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Viral pneumonia therapeutics first achieved commercial scale in the United States during the post-war expansion of academic medical centers, with subsequent diffusion into European and Asian hospital systems following regulatory harmonization efforts in the 1990s.
United States
Respiratory syncytial virus and influenza co-infection management drives protocol adoption across pediatric intensive care units. The FDA's accelerated approval pathways for infectious disease therapies compress development timelines from 48 to 24 months. Boston and San Francisco anchor antiviral clinical trial networks where academic medical centers gain early access to mechanism-of-action data.
Germany
Integrated delivery networks standardize empiric antiviral coverage for severe respiratory infections in tertiary hospitals. The EMA's adaptive pathway pilot enables conditional approval based on surrogate endpoints, accelerating market entry for novel host-directed therapies. Baden-Württemberg concentrates pharmaceutical manufacturing infrastructure supporting European supply continuity.
China
Active pharmaceutical ingredient synthesis concentrates in Zhejiang and Jiangsu provinces, supplying over 70 percent of global antiviral raw materials. The NMPA's national treatment guidelines constrain or enable market access depending on local epidemiological prioritization. Shanghai hosts regulatory science initiatives that redefine combination therapy requirements for manufacturers.
United Kingdom
Pulmonary delivery specialists license nebulized antiviral technology to large-cap manufacturers seeking outpatient expansion. The MHRA's post-Brexit regulatory autonomy enables faster pathway negotiations for novel inhalation routes. London and Cambridge concentrate biotech R&D clusters focused on host-directed acute respiratory distress syndrome prevention.
Japan
Rapid pathogen identification platforms from domestic manufacturers reshape emergency department admission algorithms. The PMDA's infectious disease priority review vouchers compress regulatory review periods for novel mechanisms. Osaka and Tokyo anchor monoclonal antibody manufacturing scale serving Asia-Pacific seasonal demand surges.
Viral Pneumonia Treatment Market Competitive Landscape
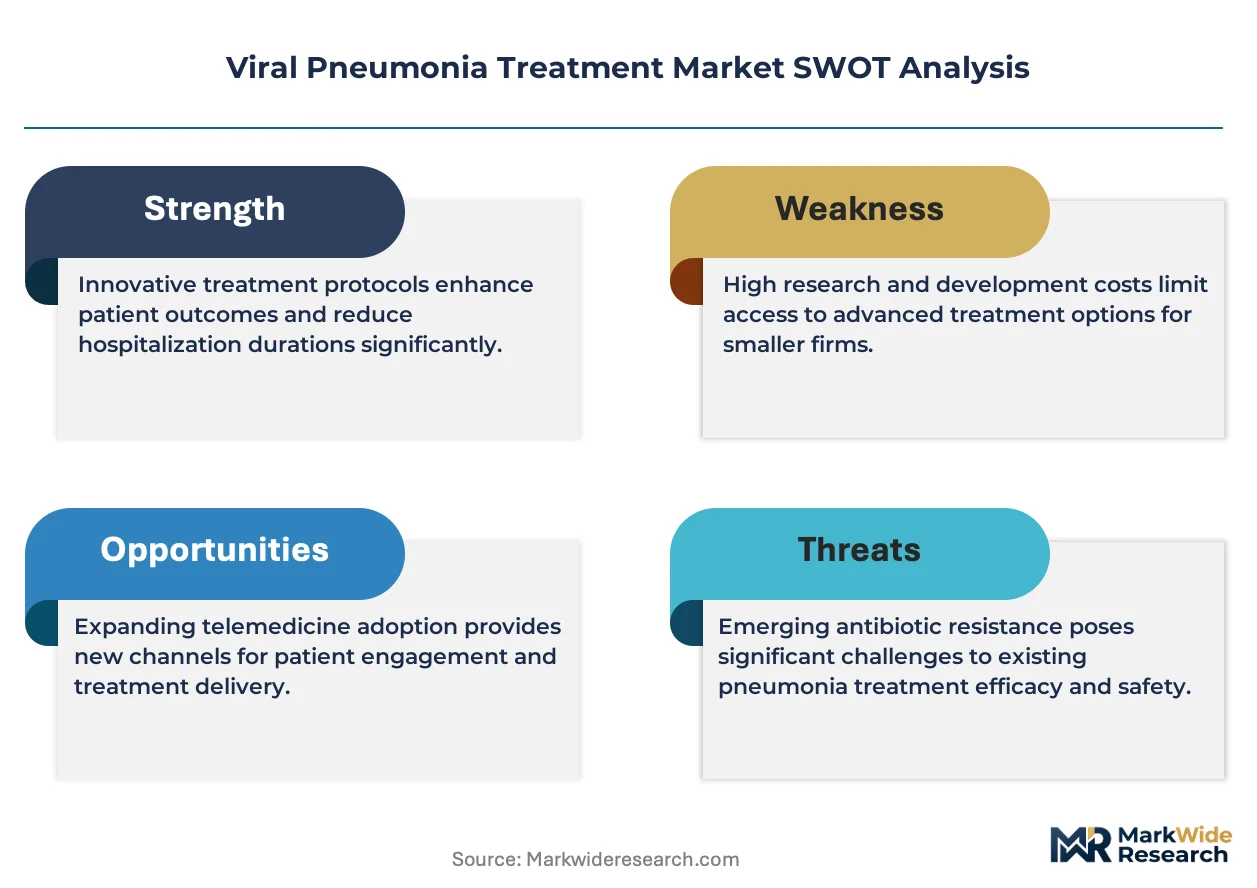
Premium-margin players sit above commodity-margin players across mechanism-of-action differentiation, with direct-acting antivirals and engineered immunoglobulins commanding formulary preference over generic corticosteroid adjuncts. Large-cap pharmaceutical conglomerates with broad infectious disease portfolios anchor long-term supply agreements, while mid-cap antiviral specialists compete through manufacturing reliability during seasonal peaks. Three archetypes dominate: diversified conglomerates spanning diagnostics through therapeutics, antiviral-focused developers with deep pipeline specialization, and manufacturing-scale operators sustaining supply continuity. Competitive intensity concentrates on bundled contracting with integrated delivery networks and licensing partnerships for pulmonary delivery technology.
Within the diversified conglomerate tier, Pfizer Inc. and GlaxoSmithKline plc exemplify portfolio breadth that enables single-source hospital procurement relationships. Merck & Co., Inc. occupies a position among manufacturing-scale operators whose reliable supply during demand surges sustains formulary placement. Gilead Sciences, Inc. anchors the antiviral-specialist archetype with concentrated expertise in RNA-targeting mechanisms. These three patterns—portfolio breadth, manufacturing reliability, and mechanism specialization—represent the dominant competitive positions manufacturers must occupy to secure procurement contracts across United States and European hospital systems.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Gilead Sciences, Inc. |
| AstraZeneca |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Sanofi |
| AbbVie Inc. |
| Others |
Value Network & Pricing Analysis
Premium antiviral-monoclonal antibody bundles versus generic corticosteroid adjuncts create a sharp mechanism-of-action divergence that manifests in both hospital formulary pricing tiers and API sourcing strategies. United States academic medical centers pay mechanism premiums for direct-acting agents while procurement managers extract volume discounts from concentrated Zhejiang and Jiangsu supply bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs hospital formulary placement, with direct-acting antivirals and engineered immunoglobulins commanding mechanism premiums over generic corticosteroids. Price differentiation hinges on FDA fast-track certification status and manufacturing scale reliability during seasonal demand surges. Cost compression in the corticosteroid adjunct tier is intensifying because integrated delivery networks unbundle diagnostic equipment from therapeutic procurement. Pediatric intensive care units show least price sensitivity for RSV prophylaxis, while community hospital general medical floors face strict reimbursement caps.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised monoclonal antibodies remain underdeveloped, forcing write-offs when cold chain integrity fails during last-mile rural distribution. Active pharmaceutical ingredient synthesis concentrates in China, India, and Switzerland, with Zhejiang and Jiangsu provinces anchoring neuraminidase inhibitor raw material production. Supply chain risk centers on single-source vulnerability for RNA polymerase inhibitor intermediates. Distribution runs through integrated delivery network central warehouses to hospital pharmacies, with home infusion services emerging as a direct-to-patient channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital formulary committees now prioritize mechanism-of-action differentiation over procurement cost minimization. Demand is shifting toward premium specifications for host-directed therapies that prevent acute respiratory distress syndrome progression.
For Market Incumbents: Lock in long-term supply agreements with integrated delivery networks before EMA adaptive pathway approvals flood European markets with novel mechanisms. Anchor manufacturing capacity in Baden-Württemberg to exploit EMA rolling review advantages. Defend against mid-cap pulmonary delivery specialists by licensing nebulized formulation technology from United Kingdom biotech clusters. For New Entrants and Emerging Players: Enter via the home infusion services channel where Medicare reimbursement shifts are decoupling monoclonal antibody administration from hospital facility fees. Target urgent care clinic networks in United States metropolitan corridors for oral antiviral distribution partnerships. Pursue platform technology designation with EMA to extrapolate safety data across viral serotypes and compress regulatory exposure requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with antiviral-focused developers possessing deep RNA-targeting pipelines and existing FDA fast-track designations. Long-term viability across the analysis window favors manufacturers with captive API supply or backward integration into Zhejiang synthesis partnerships. Watch FDA infectious disease guidance revisions on combination therapy requirements as the inflection signal for manufacturing capacity commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Adaptive Pathway Submission | Accelerates conditional approval for host-directed therapies targeting ARDS prevention in European markets. |
| Pulmonary Delivery Technology Licensing | Enables outpatient nebulized antiviral expansion through United Kingdom specialist firm partnerships. |
| Integrated Delivery Network Contracting | Secures bundled formulary placement spanning PCR diagnostics through monoclonal antibody infusions. |
| API Manufacturing Scale-Up | Buffers against Zhejiang supply disruption risks through Baden-Württemberg production redundancy. |
| Home Infusion Channel Development | Captures margin previously absorbed by hospital facility fees via Medicare reimbursement shifts. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors grounded qualitative insights in operational reality. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down epidemiological projections were cross-referenced to anchor volume estimates.
Bottom-up demand modeling segmented the market by product mechanism, administration route, end-user channel, and treatment protocol severity. Top-down epidemiological triangulation incorporated respiratory syncytial virus and influenza co-infection surveillance data across the projection horizon. CAGR derivation integrated historical approval-to-adoption curves for antiviral therapies with regulatory pathway acceleration factors.
Inputs from FDA fast-track designation records and EMA adaptive pathway pilot documentation were available through the study window; gaps in real-time antiviral resistance surveillance from outpatient settings introduce uncertainty bands around empiric prescribing volume assumptions. Practitioners should monitor WHO Global Influenza Surveillance resistance reporting delays and Medicare hospital-acquired condition penalty program revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market