
 Pediatric Respiratory Disease Therapeutics Market | 2026-2036
Pediatric Respiratory Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Respiratory Disease Therapeutics Market Analytics
The divergence between premium biologic therapies and commodity bronchodilators is hardening as payers impose stricter prior authorization on high-cost monoclonal antibodies while generic albuterol margins compress. Regeneron Pharmaceuticals leverages its Dupixent franchise to sustain pricing power in severe pediatric asthma. GlaxoSmithKline plc anchors the maintenance segment with inhaled corticosteroid combinations that dominate hospital formularies.
Pediatric respiratory disease therapeutics comprise pharmaceutical and device-based interventions engineered to achieve lung deposition rates exceeding 30% in children under five, utilizing particle sizes of one to five microns and breath-actuated mechanisms to overcome developmental limitations in inhalation technique. These therapeutics primarily aim to prevent exacerbations, preserve lung function, and reduce emergency department utilization in chronically ill pediatric populations. Inhalers lead product type revenue due to established reimbursement, while antiviral therapies represent the fastest-expanding category as respiratory syncytial virus prophylaxis broadens. The home care end user segment captures widening margin pools as remote monitoring technologies enable hospital-at-home models for cystic fibrosis management.
The FDA's Rare Pediatric Disease Priority Review Voucher program and the EMA's Paediatric Investigation Plans collectively shape development pipelines by mandating age-appropriate formulations and extending exclusivity incentives. ISO 18562 biocompatibility standards for breathing gas pathways constrain device material selection, elevating compliance costs for nebulizer manufacturers. Stakeholders must monitor how CMS pediatric supplemental rebate negotiations and EU Health Technology Assessment convergence alter commercial access for novel biologics.
Market Dynamics
Medicaid reimbursement reforms in the United States are accelerating hospital-at-home transitions for pediatric asthma and cystic fibrosis patients, compressing traditional inpatient revenue models while expanding device-based maintenance therapy volumes.
Growth Catalysts
- FDA Rare Pediatric Disease Priority Review Vouchers:These incentives compress regulatory timelines for novel biologics targeting severe asthma phenotypes, attracting venture investment into pediatric-specific formulations.
- Home care infrastructure:Remote monitoring platforms for cystic fibrosis management enable continuous lung function tracking, reducing emergency department utilization and capturing margin pools previously retained by hospitals.
- Respiratory syncytial virus prophylaxis expansion:Antiviral therapy demand accelerates as neonatal intensive care units in the United States and Germany broaden preventive treatment protocols for high-risk infants.
Market Restraints
- Prior authorization friction:United States commercial payers impose stricter utilization management on monoclonal antibody therapies, creating reimbursement delays that compress prescribing velocity for severe pediatric asthma.
- Generic albuterol margin compression:Commodity bronchodilator manufacturing concentrates in Indian and Chinese active pharmaceutical ingredient suppliers, eroding profitability for finished dose producers.
- ISO 18562 biocompatibility compliance:Breathing gas pathway testing requirements for nebulizers elevate material selection costs and extend device development timelines.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Diagnostic infrastructure gaps in Nigeria and Kenya leave severe asthma and cystic fibrosis undetected, creating first-mover advantage for portable spirometry and telemedicine-enabled screening.
- EMA Paediatric Investigation Plans:Mandated age-appropriate formulation development extends market exclusivity periods, incentivizing pediatric-specific clinical trials that adult-focused portfolios previously neglected.
- Smart inhaler-nebulizer convergence:Bluetooth-enabled dose counters integrated with cloud-based adherence platforms enable outcome-based contracting with United States Medicaid managed care organizations.
Industry Challenges
- Pediatric pulmonology workforce scarcity:Fellowship training programs in the United States and Germany produce insufficient specialists to match expanding hospital network capacity, creating patient access bottlenecks.
- Legacy nebulizer integration complexity:Hospital procurement departments struggle to reconcile breath-actuated devices with existing compressor infrastructure, delaying formulary adoption despite superior lung deposition rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Respiratory Disease Therapeutics Market |
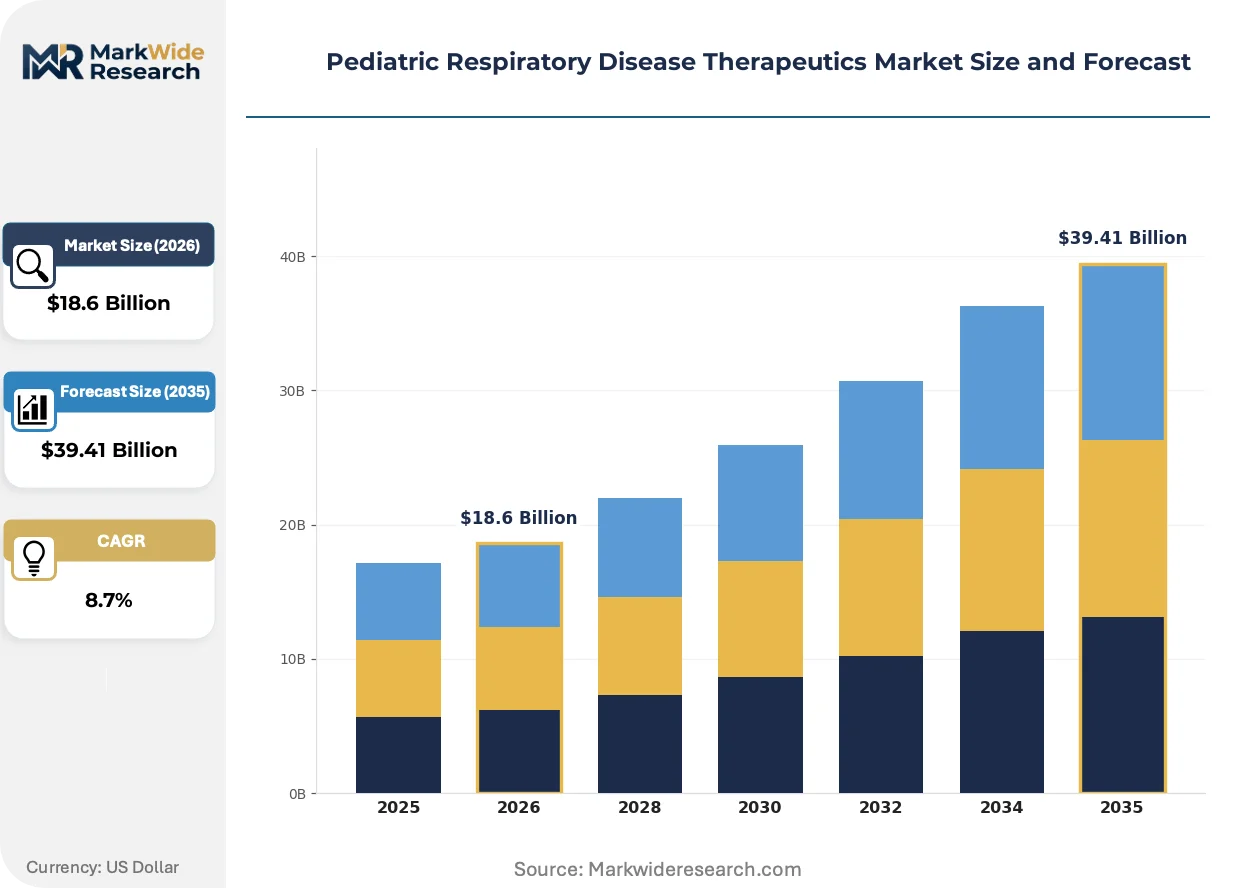
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oral Medications, Antiviral Therapies Delivery Mode: Inhalation, Oral, Intravenous, Transdermal End User: Pediatrics, Hospitals, Clinics, Home Care Therapy Area: Asthma, Cystic Fibrosis, Bronchitis, Allergies |
| Companies Covered | Regeneron Pharmaceuticals, F. Hoffmann-La Roche AG, Novartis AG, GlaxoSmithKline plc, Boehringer Ingelheim GmbH, AstraZeneca plc, Merck & Co, Bayer AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Respiratory Disease Therapeutics Market Evolving Landscape
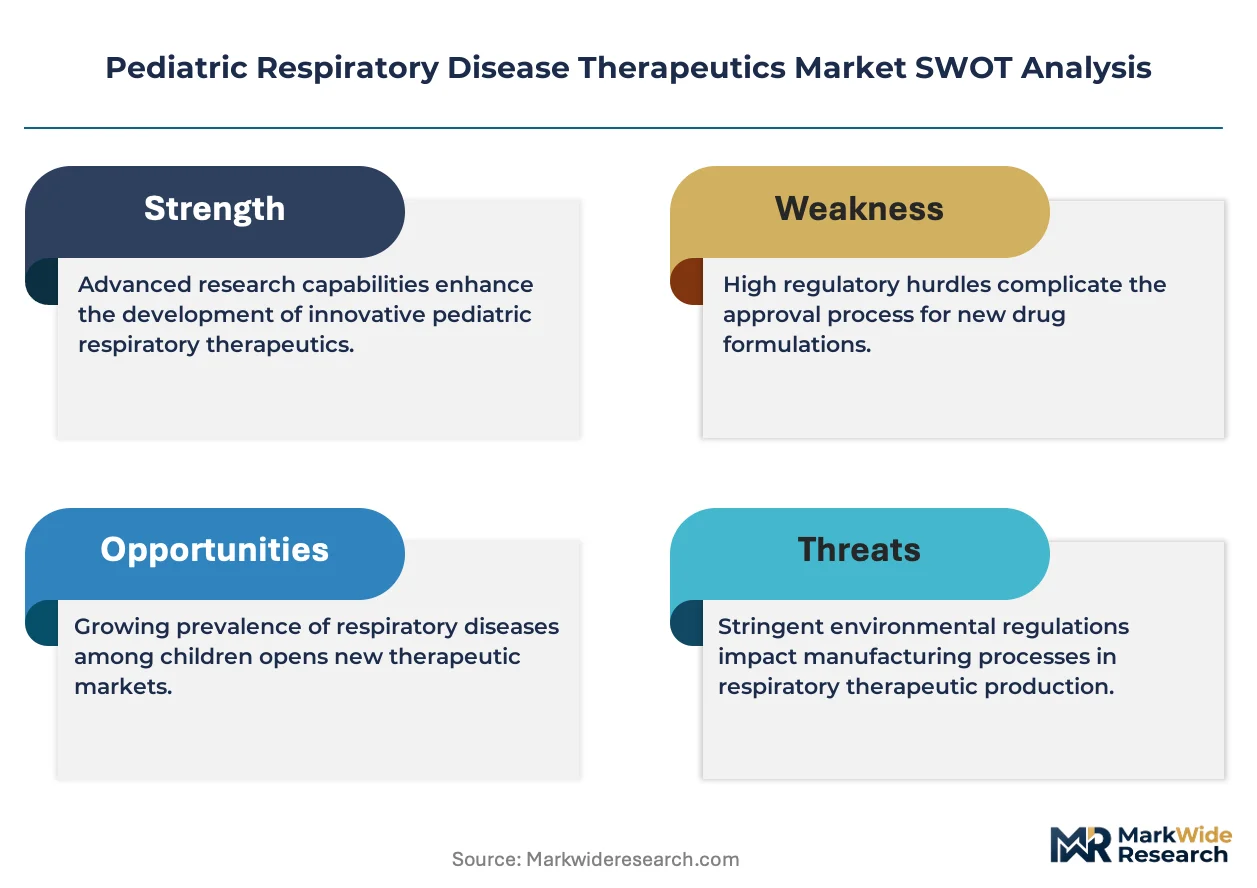
Particle engineering and connectivity technologies are converging to overcome developmental limitations in pediatric inhalation technique, while regulatory mandates force age-appropriate formulation investment that adult-centric pipelines previously avoided.
Mesh nebulizer technology is consolidating market share from traditional jet compressors by achieving consistent one-to-three micron particle size distribution regardless of patient breathing pattern. Pediatric hospitals in the United States and Germany are replacing legacy fleet equipment at accelerated procurement cycles. The structural consequence is compressing aftermarket compressor revenue while shifting margin capture toward disposable mesh components and connected adherence platforms.
EMA Paediatric Investigation Plans now mandate age-appropriate formulation development for all new molecular entities seeking European approval, forcing sponsors to invest in pediatric pharmacokinetic studies that were historically deferred. This regulatory friction extends development timelines by twelve to twenty-four months but creates exclusivity extensions that reward first movers. Inhaled corticosteroid combination products face the steepest compliance burden due to existing adult-dominant portfolios.
Hospital procurement departments increasingly unbundle device acquisition from pharmaceutical supply contracts, enabling standalone nebulizer and smart inhaler vendor selection based on ISO 18562 certification status rather than bundled pricing. This pattern concentrates purchasing authority within biomedical engineering functions that previously deferred to pharmacy committees. The United States exhibits the most pronounced shift, with children's hospital networks in Texas and California leading contract separation.
Pediatric Respiratory Disease Therapeutics Market Segmentation
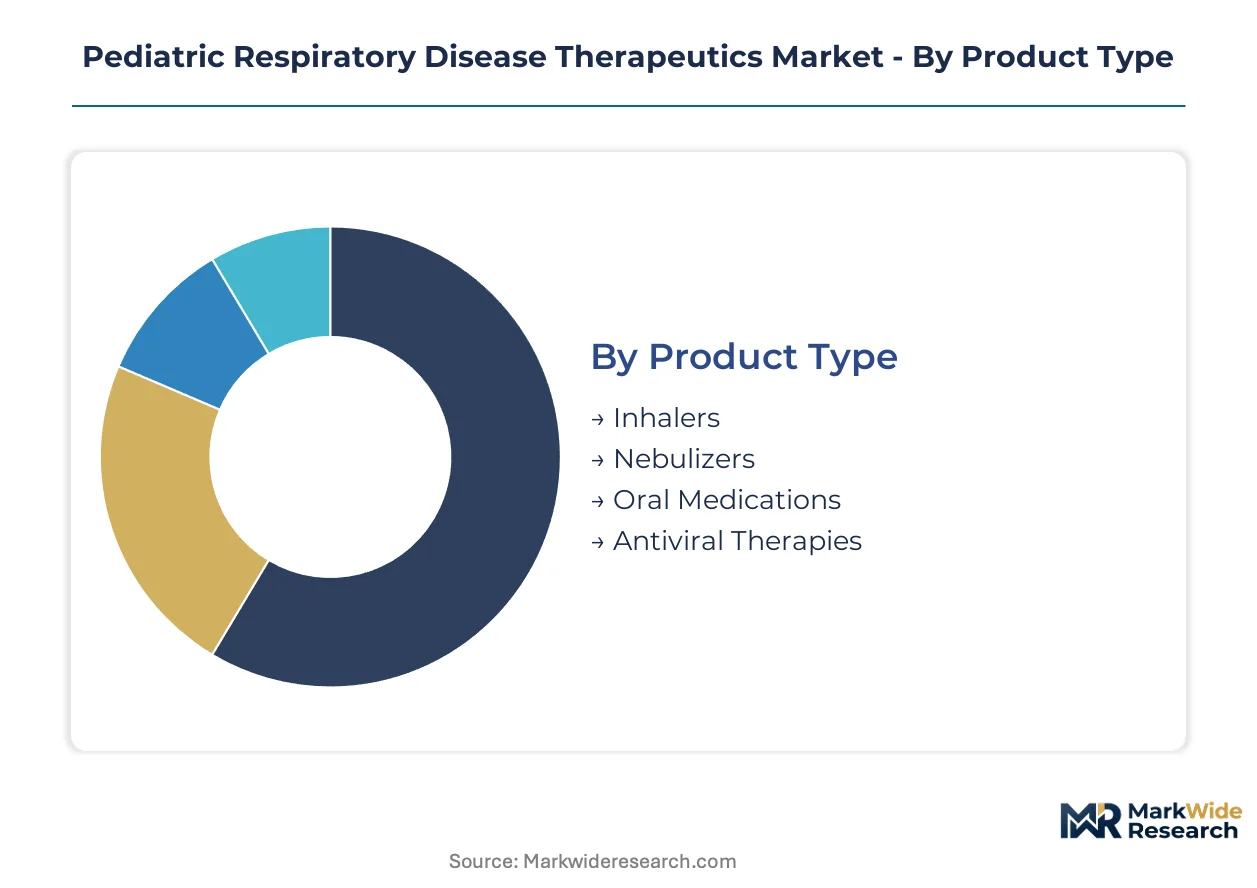
Pediatric respiratory therapeutics fragment across device technology, delivery physics, care setting, and disease phenotype. Each dimension carries distinct reimbursement logic and regulatory burden that shapes commercial strategy.
Product Type:
Volume concentrates in legacy inhalation devices while premium biologics capture margin expansion.
- Inhalers:Metered-dose and dry-powder platforms dominate hospital formularies through established CPT reimbursement codes. United States Medicaid managed care organizations favor breath-actuated variants to reduce technique-dependent dosing errors in children under twelve.
- Antiviral Therapies:Monoclonal antibody prophylaxis for respiratory syncytial virus commands prior authorization tiers but delivers superior outcomes in neonatal intensive care units across Texas and California. FDA accelerated approval pathways compress development timelines for this category.
- Nebulizers:Mesh technology displaces jet compressors in pediatric pulmonology units seeking consistent sub-three-micron particle distribution.
- Oral Medications:Leukotriene inhibitors and systemic corticosteroids serve maintenance protocols where inhalation technique remains undeveloped.
Today's leader: Inhalers. Tomorrow's challenger: Antiviral Therapies.
Delivery Mode:
Application context determines modality selection — acute rescue versus chronic maintenance versus prophylactic prevention.
- Inhalation:Direct lung deposition minimizes systemic exposure, critical for developing endocrine systems. Particle engineering targets one-to-five micron distribution to overcome shallow breathing patterns in infants.
- Oral:Systemic absorption serves patients with cognitive or motor barriers to coordinated inhalation. Palatability formulations drive compliance in the two-to-six age bracket.
- Intravenous:Reserved for acute exacerbations requiring rapid bronchodilation in emergency department settings.
- Transdermal:Emerging patch-based delivery for anticholinergics addresses adherence gaps in adolescent populations.
Inhalation retains clinical preference. Oral expands where technique fails.
End User:
Customer type stratifies across institutional procurement versus consumer-direct acquisition channels.
- Home Care:Remote monitoring platforms for cystic fibrosis management enable continuous lung function tracking, capturing margin pools previously retained by inpatient facilities. Bluetooth-enabled nebulizers with cloud adherence tracking dominate this segment.
- Hospitals:Pediatric pulmonology units in the United States anchor volume through formulary committees that prioritize ISO 18562-certified devices. Procurement departments increasingly unbundle device acquisition from pharmaceutical supply contracts.
- Clinics:Outpatient settings concentrate asthma maintenance prescriptions with tighter generic substitution protocols.
- Pediatrics:Specialist referral networks in Germany and the United States create access bottlenecks due to fellowship training scarcity.
Home Care gains share fastest. Hospitals defend volume through formulary control.
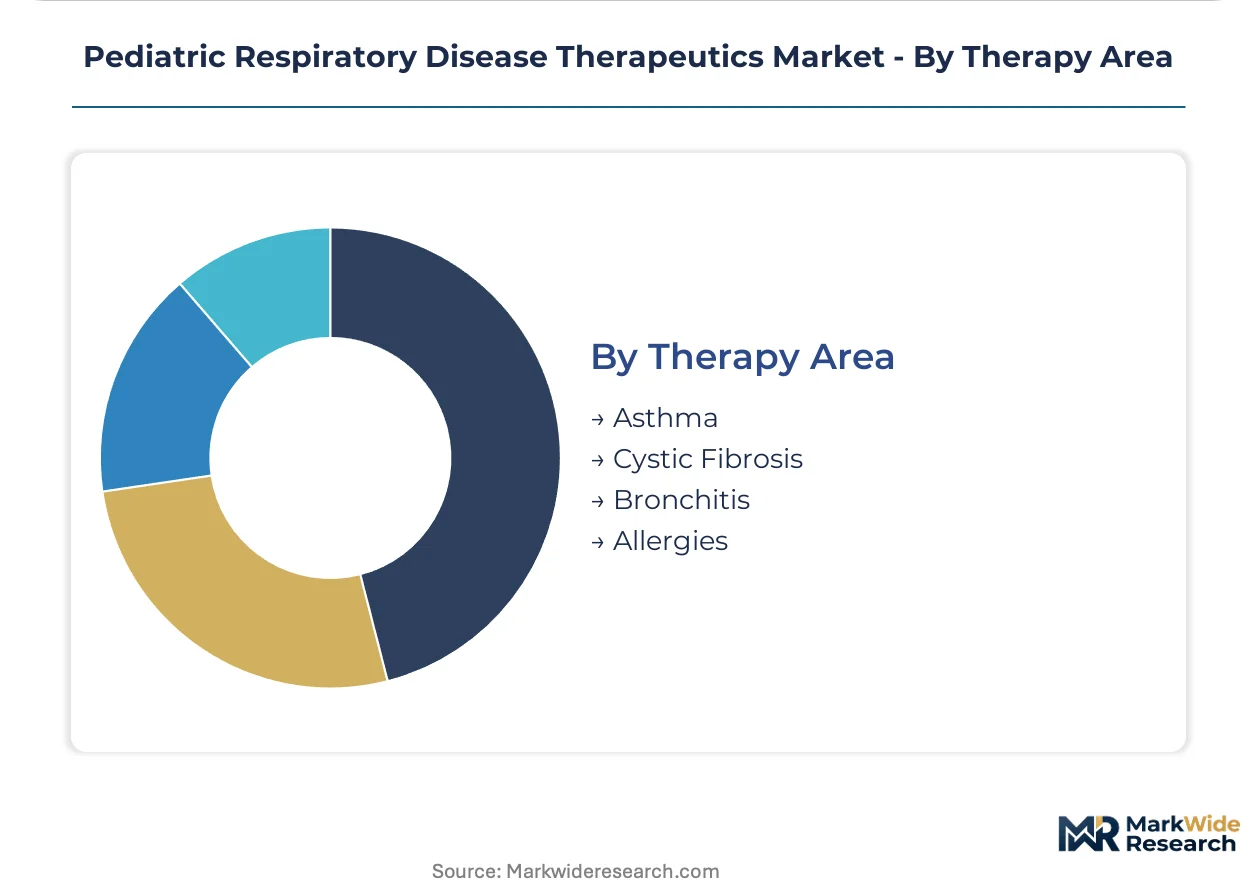
Therapy Area:
Disease severity and chronicity determine therapy intensity and device sophistication requirements.
- Asthma:The most prevalent indication drives inhaled corticosteroid combination volume. Severe phenotypes qualify for biologic add-on therapy under strict prior authorization.
- Cystic Fibrosis:Mutation-specific modulators transform survival curves, requiring coordinated airway clearance device protocols. United States CF Foundation care centers standardize nebulizer specifications.
- Bronchitis:Acute viral presentations concentrate in urgent care settings with commodity bronchodilator deployment.
- Allergies:Comorbid allergic rhinitis expands intranasal corticosteroid co-prescribing with asthma maintenance regimens.
Asthma anchors revenue scale. Cystic Fibrosis commands premium pricing per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cystic fibrosis care networks standardize nebulizer specifications more aggressively than Brazil's fragmented diagnostic infrastructure, yet both face pediatric pulmonology workforce scarcity. The United States concentrates biologic therapy development through FDA accelerated pathways. China scales domestic mesh nebulizer manufacturing. India confronts severe asthma underdiagnosis. The United Kingdom leverages NHS England procurement to reshape device formularies.
United States
Texas and California children's hospital networks unbundle device procurement from pharmaceutical contracts, shifting purchasing authority to biomedical engineering committees. FDA Rare Pediatric Disease Priority Review Vouchers compress development timelines for severe asthma biologics. Medicaid managed care organizations in Florida and Ohio favor breath-actuated inhalers to reduce dosing errors in patients under twelve.
Germany
Bavarian and North Rhine-Westphalian pediatric pulmonology units replace legacy jet compressor fleets with mesh nebulizers achieving consistent sub-three-micron particle distribution. EMA Paediatric Investigation Plans mandate age-appropriate formulation development, extending exclusivity periods for sponsors investing in pediatric pharmacokinetic studies. Berlin-Brandenburg hospital networks anchor procurement standardization for ISO 18562-certified breathing gas pathway devices.
China
Yangtze River Delta and Pearl River Delta manufacturing clusters scale domestic mesh nebulizer component production, displacing imported compressor equipment in provincial hospital tenders. NMPA pediatric formulation guidelines align with international lung deposition standards. Beijing-Tianjin-Hebei medical device parks concentrate connected inhaler-nebulizer assembly for Bluetooth-enabled adherence platforms.
India
Maharashtra and Karnataka diagnostic infrastructure gaps leave severe pediatric asthma phenotypes undetected, creating first-mover opportunity for portable spirometry and telemedicine-enabled screening. CDSCO pediatric drug approval pathways remain underdeveloped relative to adult therapeutic categories. Delhi-NCR specialist referral networks face acute pulmonology fellowship training bottlenecks.
United Kingdom
NHS England procurement frameworks in London and the Midlands prioritize ISO 18562-certified nebulizers over bundled pharmaceutical-device contracts. MHRA pediatric investigation plan enforcement mirrors EMA mandates for age-appropriate formulation development. Scotland and Wales regional health boards lag England in remote monitoring platform deployment for cystic fibrosis home care.
Pediatric Respiratory Disease Therapeutics Market Competitive Landscape
Top-tier vendors anchor biologic therapy development, while mid-tier device manufacturers and generic bronchodilator suppliers occupy commoditized segments. The vendor base stratifies across three strategic archetypes: monoclonal antibody developers capturing prior-authorized premium pricing, inhaled corticosteroid combination producers defending hospital formulary positions, and connected device specialists enabling adherence-based contracting. Dominant competitive moves include unbundled device procurement negotiations and backward integration into active pharmaceutical ingredient supply.
Among US-based biologic developers, Regeneron Pharmaceuticals exemplifies the premium-tier monoclonal antibody archetype through its Dupixent franchise positioning. GlaxoSmithKline plc represents the maintenance-segment anchor with inhaled corticosteroid combinations dominating hospital formularies. Swiss-headquartered Novartis AG and Roche AG occupy positions bridging biologic innovation with device-therapy integration, reflecting European pharmaceutical conglomerate structures.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| F. Hoffmann-La Roche AG |
| Novartis AG |
| GlaxoSmithKline plc |
| Boehringer Ingelheim GmbH |
| AstraZeneca plc |
| Merck & Co |
| Bayer AG |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient spot prices for albuterol sulfate and fluticasone propionate cascade through three pricing tiers, compressing margins for commodity bronchodilator manufacturers while insulating biologic developers with prior-authorized premium positioning.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for generic bronchodilators, forcing finished-dose producers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 18562 certification status and breath-actuated mechanism sophistication. Cost compression in the economy tier intensifies because Indian API suppliers consolidated production share. Medicaid managed care organizations exhibit highest price sensitivity; neonatal intensive care units demonstrate lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese mesh nebulizer component manufacturers supplying Yangtze River Delta assembly parks. Finished device production draws from China, Germany, and the United States, while API synthesis feeds from India and China. Supply chain risk centers on NMPA pediatric formulation guideline alignment delays disrupting cross-border component flows. Distribution runs through hospital procurement committees unbundling device acquisition from pharmaceutical contracts, with GPO contracts managers gaining authority over standalone nebulizer selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pediatric respiratory therapeutics market represents a late-cycle quality story as cystic fibrosis home care demand shifts toward Bluetooth-enabled adherence platforms and ISO 18562-certified breathing gas pathway devices.
For Market Incumbents: Extend formulary anchoring through backward integration into mesh nebulizer component supply, countering unbundled procurement threats from biomedical engineering committees. Deepen hospital-at-home infrastructure partnerships to capture margin pools shifting from inpatient facilities, while investing in pediatric pharmacokinetic studies to secure EMA exclusivity extensions.
For New Entrants and Emerging Players: Connected inhaler-nebulizer convergence offers technology-first wedge into Medicaid managed care outcome-based contracting, where incumbent device-therapy bundles face procurement separation. Target Sub-Saharan Africa diagnostic infrastructure gaps in Nigeria and Kenya with portable spirometry and telemedicine-enabled screening. Deploy direct-to-clinic go-to-market models bypassing specialist referral bottlenecks.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap connected device specialists possessing ISO 18562 certification and cloud adherence platform integration. Five-to-ten year viability favors vendors with captive supply of sub-three-micron particle engineering capability and hospital-at-home reimbursement pathway expertise. Monitor FDA Rare Pediatric Disease Priority Review Voucher issuance velocity as inflection indicator for biologic development pipeline momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Paediatric Investigation Plan Compliance | Exclusivity extensions reward sponsors investing in age-appropriate formulation development. |
| ISO 18562 Certification Investment | Breathing gas pathway biocompatibility standards elevate device material selection barriers for competitors. |
| Hospital-at-Home Infrastructure Partnership | Remote monitoring platforms capture cystic fibrosis margin pools from traditional inpatient facilities. |
| Backward Integration into API Supply | Captive albuterol sulfate production defends against Indian and Chinese supplier consolidation. |
| Bluetooth-Enabled Adherence Platform Development | Cloud-based dose counters enable outcome-based contracting with Medicaid managed care organizations. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement records, and API trade flow customs data — were reconciled through primary interviews with pediatric pulmonologists, formulary directors, biomedical engineering procurement leads, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearances, EMA Paediatric Investigation Plan submissions, CMS Medicare reimbursement schedules, and ISO 18562 certification registries. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical prescription volume trends cross-referenced against expert panel assessments of prior authorization friction and mesh nebulizer replacement cycles across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end user, and therapy area, with regional regulatory clusters capturing FDA, EMA, NMPA, and CDSCO pathway divergence. CAGRs derived from log-linear trend fitting adjusted for Medicaid managed care penetration curves and cystic fibrosis mutation-specific modulator adoption trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA Rare Pediatric Disease Priority Review Voucher policy continuity, pediatric pulmonology fellowship training expansion rates, and sub-three-micron particle engineering patent cliff timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Global Dyspnea Treatment Market