
 Interventional Pulmonology Market | 2026-2036
Interventional Pulmonology Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Pulmonology Market Intelligence
The shift towards equipment leasing and managed service contracts for high-cost imaging systems is reconfiguring competitive positioning. Olympus Corporation leverages its strong brand and extensive service network in the endoscope segment. Boston Scientific Corporation differentiates through its focus on minimally invasive devices for airway stenosis. Medtronic sustains a broad portfolio, including its electromagnetic navigation bronchoscopy systems for complex diagnostic procedures.
Interventional pulmonology involves the use of endoscopic and other minimally invasive techniques to diagnose and treat diseases of the airways, lungs, and pleura. These procedures utilize devices like bronchoscopes, which provide direct visualization of the tracheobronchial tree with working channels for tools. Bronchoscopes and endobronchial ultrasound systems represent mature, high-volume product categories. The therapy area of lung cancer diagnosis and staging drives a significant portion of procedural volume, particularly within academic hospitals.
Device approval pathways are governed by agencies such as the US FDA, Europe's EMA under the Medical Device Regulation (MDR), and China's NMPA. These regulations mandate stringent clinical evidence for safety and efficacy, directly influencing market entry timelines and R&D costs. Success for device manufacturers depends on navigating these complex regulatory environments while adapting to technological innovation in robotic and image-guided interventions.
Market Dynamics
The central structural force in interventional pulmonology is the convergence of robotic assistance and advanced imaging. This fusion enables more precise access to peripheral lung nodules, driving a shift toward earlier diagnosis and treatment within specialized academic hospital settings.
Growth Catalysts
- Robotic-Assisted Platforms:The proliferation of robotic bronchoscopy systems enhances precision and control in reaching small, peripheral pulmonary nodules, directly improving diagnostic yield for early-stage lung cancer detection and staging.
- Government Healthcare Modernization:National health strategies, particularly in China, are channeling significant investment into upgrading hospital infrastructure and acquiring advanced diagnostic equipment, creating concentrated demand for interventional pulmonology systems.
- Aging Demographics:A rising incidence of chronic obstructive pulmonary disease (COPD) and lung cancer in aging populations across developed economies like Japan and Germany sustains high procedural volumes for diagnostic and therapeutic interventions.
Market Restraints
- High Capital Expenditure:The substantial upfront cost of robotic bronchoscopy platforms and integrated imaging suites restricts their acquisition primarily to large, well-funded academic medical centers and hospital systems.
- Stringent Regulatory Pathways:Europe's Medical Device Regulation (MDR) mandates extensive clinical evidence for device approval, which extends market entry timelines and elevates research and development costs for manufacturers.
- Specialized Skill Requirements:Performing complex robotic-assisted procedures requires extensive, specialized training, creating a bottleneck in the number of qualified interventional pulmonologists available to operate the systems.
Strategic Opportunities
- Expansion into Therapeutics:Moving beyond diagnostics to deliver localized therapies, such as bronchoscopic tumor ablation and targeted drug delivery, presents a significant opportunity for procedural and device market expansion.
- Simulation and Tele-Proctoring:Developing virtual reality training simulators and remote proctoring capabilities can accelerate the physician learning curve and broaden the adoption of complex techniques in underserved regions.
- Underpenetrated Geographic Markets:Improving healthcare infrastructure and rising disposable incomes in countries like Brazil and India offer long-term growth potential as access to advanced pulmonary care expands.
Industry Challenges
- System Interoperability:Integrating data from disparate systems, including CT scanners, navigation platforms, and endoscopes, into a seamless clinical workflow remains a significant technical hurdle for healthcare providers.
- Reimbursement Uncertainty:Inconsistent and often inadequate reimbursement codes for novel interventional procedures across different healthcare payers, including in the United States, creates economic risk for hospitals adopting new technologies.
- Complex Reprocessing Protocols:The intricate designs of advanced bronchoscopes, particularly robotic-assisted models, complicate cleaning and sterilization processes, posing operational and patient safety challenges for hospital staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Pulmonology Market |
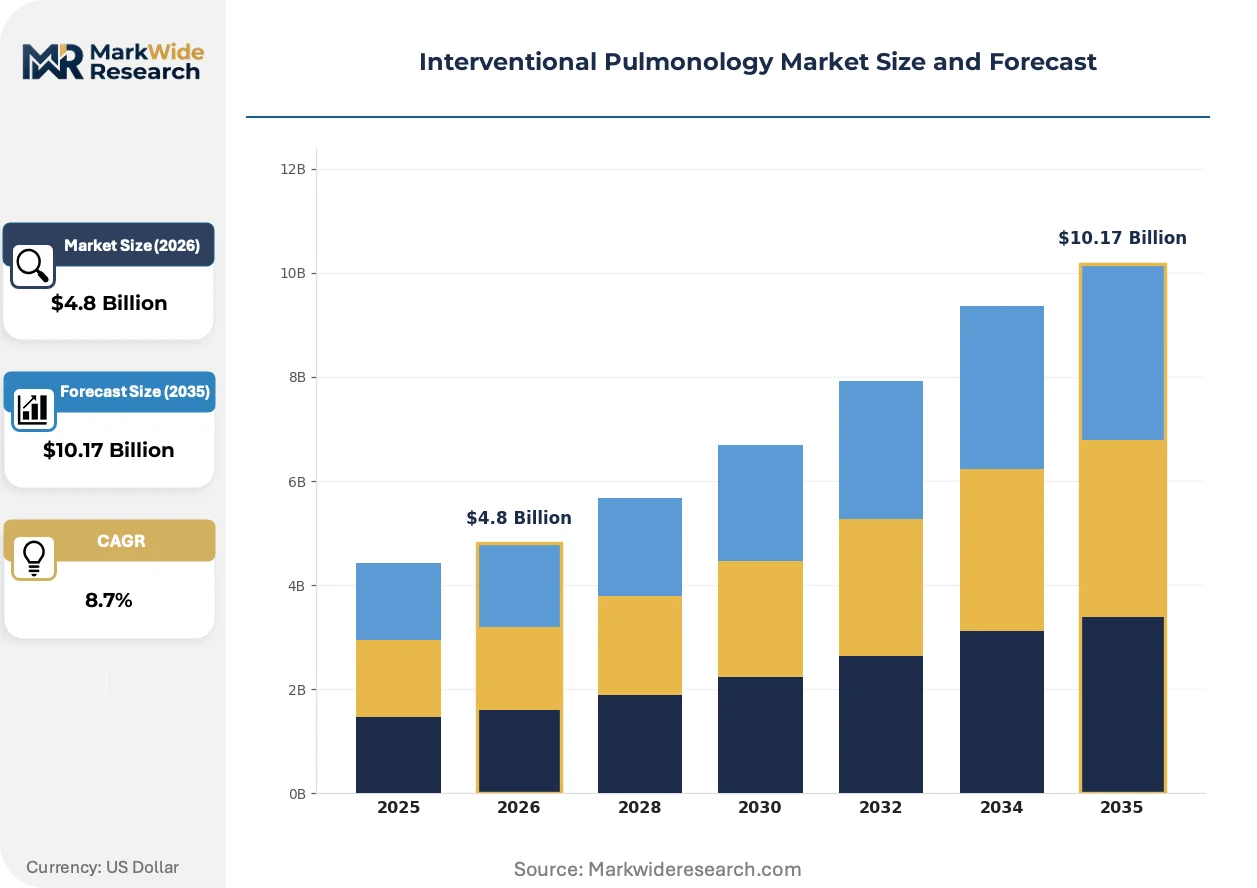
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
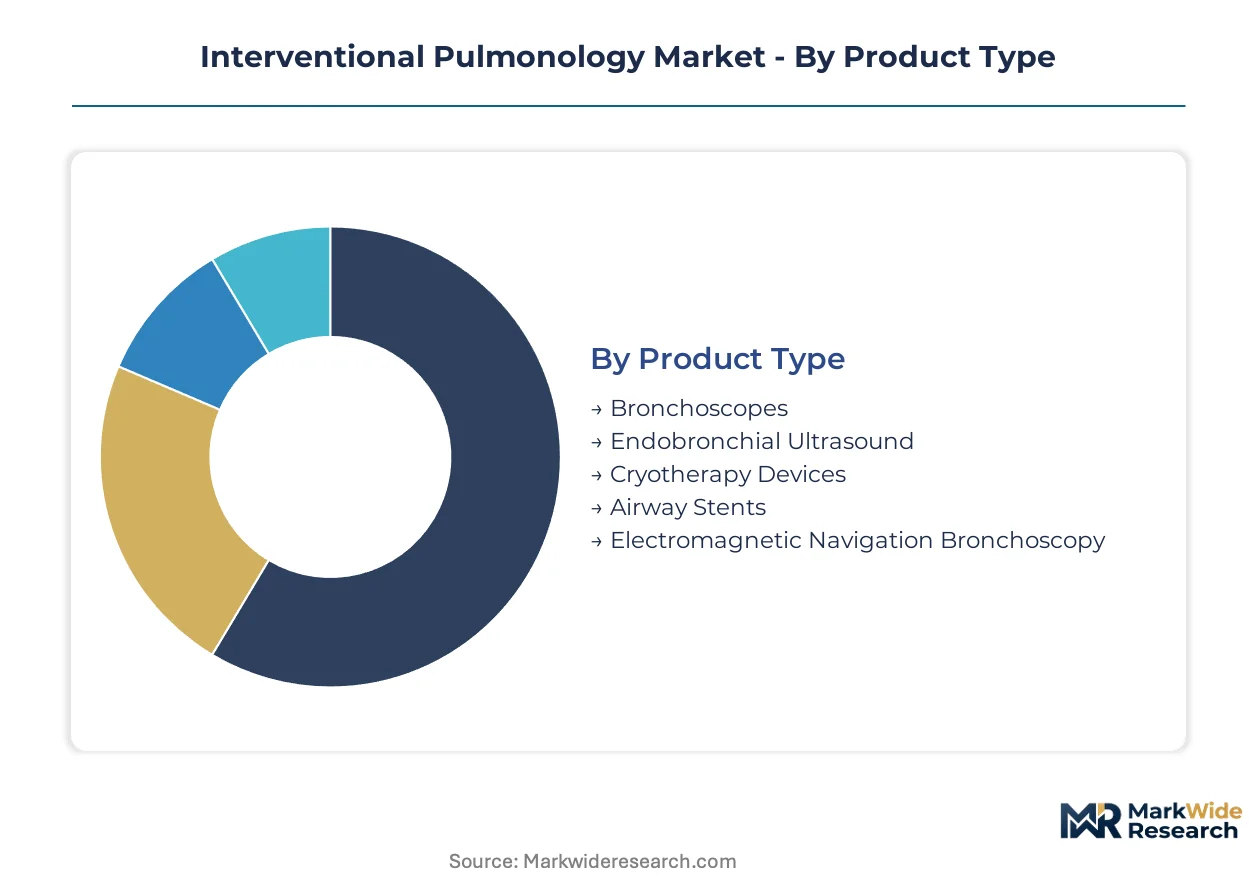
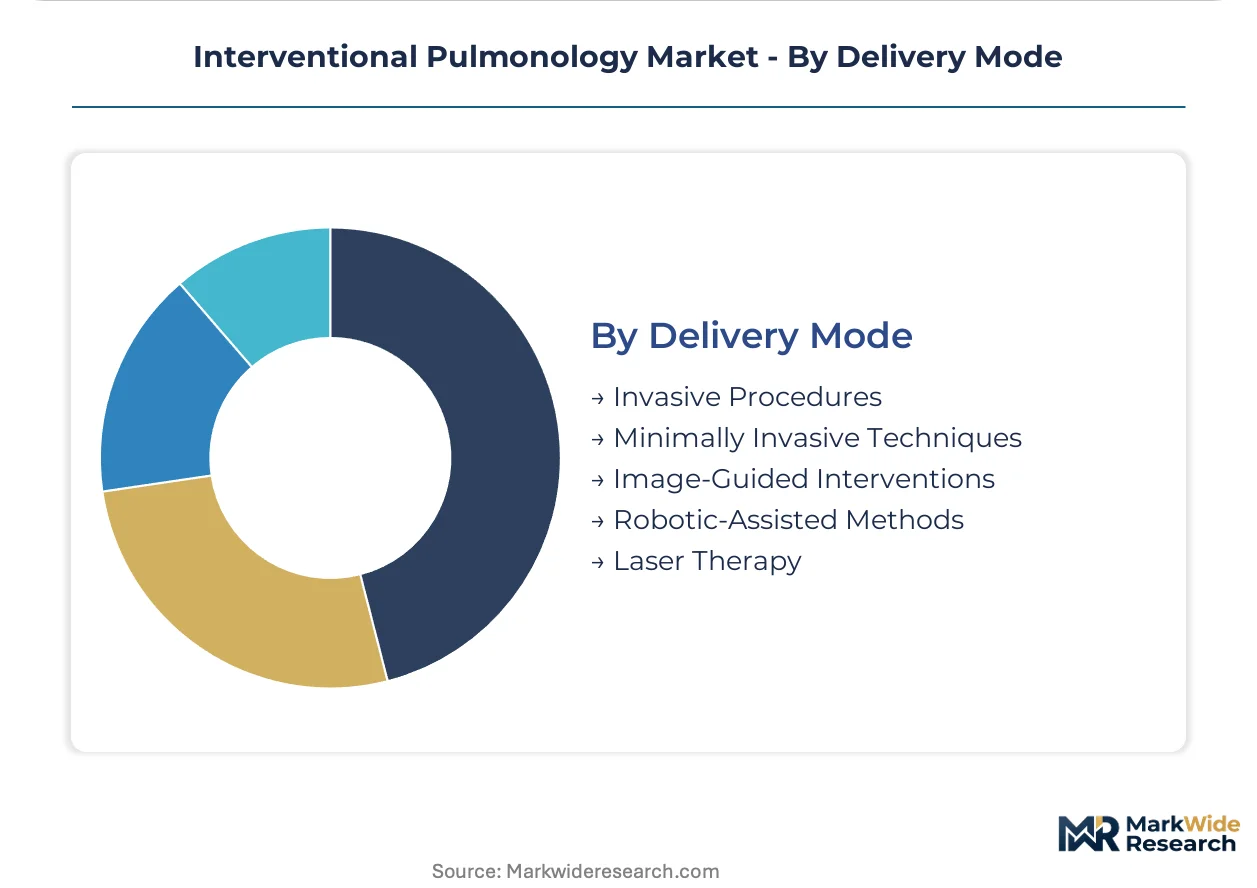
| Segmentation | Product Type: Bronchoscopes, Endobronchial Ultrasound, Cryotherapy Devices, Airway Stents, Electromagnetic Navigation Bronchoscopy Therapy Area: Lung Cancer, Airway Stenosis, Pleural Diseases, Pulmonary Nodules, Tracheomalacia End User: Specialty Clinics, Research Institutes, Diagnostic Centers, Treatment Facilities, Academic Hospitals Delivery Mode: Invasive Procedures, Minimally Invasive Techniques, Image-Guided Interventions, Robotic-Assisted Methods, Laser Therapy |
| Companies Covered | Medtronic, Karl Storz, Boston Scientific Corporation, Becton, Dickinson and Company, Richard Wolf Corporation, Olympus Corporation, Cook Medical, Smiths Group plc, FUJIFILM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Pulmonology Market Strategic Shifts & Innovations
Technological integration is the defining theme, as standalone devices are combined into cohesive procedural platforms. This evolution aims to transform multi-step diagnostic pathways into single-session procedures, improving both clinical efficiency and patient outcomes in lung cancer care.
Electromagnetic navigation bronchoscopy (ENB) provides a virtual, CT-based roadmap to guide tools to peripheral lung lesions. Major academic hospitals and cancer centers are rapidly adopting these systems for difficult-to-reach nodules. This technology is hybridizing diagnostic visualization with real-time navigational guidance, enabling a more direct path for biopsy and potentially future therapeutic delivery in one session.
The US FDA's Safer Technologies Program (STeP) offers an expedited pathway for devices that provide significant safety improvements over existing options. This regulatory framework reduces review timelines by enabling more interactive collaboration between manufacturers and the agency. Device makers developing next-generation robotic systems and AI-driven diagnostic software are most affected, as they can use STeP to accelerate market access.
A transition away from outright capital purchases toward equipment leasing and managed service contracts is gaining traction. This model disrupts the traditional one-time sales cycle, replacing it with long-term partnerships focused on service, software, and consumables. This shift is most prominent within large US integrated delivery networks (IDNs) and European hospital groups seeking predictable costs and protection from technology obsolescence.
Interventional Pulmonology Market Segmentation
Understanding the interventional pulmonology market through its segmentation reveals distinct demand patterns and technological adoption curves. Each category highlights specific areas of innovation and established clinical practice. This granular view assists manufacturers in tailoring product development and market entry strategies.
Product Type:
The range of devices available for interventional pulmonology procedures addresses diverse diagnostic and therapeutic needs across the respiratory system.
- Bronchoscopes:These flexible or rigid tubes provide direct visualization of the tracheobronchial tree, featuring working channels for various tools. Demand for advanced bronchoscopes remains high in academic hospitals for routine diagnostics and complex interventions.
- Electromagnetic Navigation Bronchoscopy:This technology uses a virtual, CT-based roadmap to guide instruments to peripheral lung lesions with enhanced precision. Cancer centers in the United States are rapidly adopting these systems for early lung cancer diagnosis.
- Endobronchial Ultrasound:EBUS systems integrate ultrasound imaging with bronchoscopy, enabling real-time visualization of lymph nodes and lesions adjacent to the airways.
- Cryotherapy Devices:These instruments use extreme cold to destroy abnormal tissue, finding application in airway obstruction and tumor debulking.
- Airway Stents:Implantable devices maintain airway patency in patients suffering from malignant or benign strictures.
Bronchoscopes hold installed capacity. Electromagnetic Navigation Bronchoscopy is rotating up the share rankings.
Therapy Area:
Clinical applications for interventional pulmonology procedures span a broad spectrum of respiratory conditions, with lung cancer diagnosis driving significant volume.
- Lung Cancer:Interventional pulmonology plays a critical role in the diagnosis, staging, and palliation of lung cancer through biopsy and airway management. Academic hospitals globally prioritize this therapy area due to the high incidence and mortality associated with lung malignancies.
- Pulmonary Nodules:Procedures target the precise diagnosis and characterization of suspicious pulmonary nodules, often utilizing advanced navigational tools. Earlier detection of these nodules drives demand for minimally invasive diagnostic techniques in specialized clinics.
- Airway Stenosis:This condition involves the narrowing of airways, requiring interventions such as balloon dilation, stenting, or laser therapy.
- Pleural Diseases:Interventions address conditions affecting the pleura, including effusions and pneumothorax, often involving drainage or pleurodesis.
- Tracheomalacia:Procedures manage the collapse of the trachea, typically involving stenting to maintain airway patency.
Lung cancer diagnosis dominates procedural focus. Airway stenosis treatment shows consistent procedural growth.
End User:
The institutional settings where interventional pulmonology procedures are performed reflect varying levels of complexity and technology adoption.
- Academic Hospitals:These large institutions are primary adopters of advanced robotic-assisted platforms and complex diagnostic systems due to their research focus and high procedural volumes. Academic medical centers in Germany drive significant demand for integrated imaging suites.
- Specialty Clinics:Focused on specific respiratory conditions, these clinics offer tailored interventional pulmonology services, often emphasizing less complex, high-volume procedures. Demand for specialized care in China supports the expansion of these focused facilities.
- Research Institutes:These entities primarily focus on developing new interventional techniques and devices, often in collaboration with academic partners.
- Diagnostic Centers:Facilities dedicated to diagnosing respiratory diseases utilize interventional pulmonology tools for precise tissue sampling.
- Treatment Facilities:Hospitals and clinics providing therapeutic interventions for respiratory conditions constitute a significant end-user segment.
Academic hospitals drive technology adoption. Specialty clinics expand localized patient access.
Delivery Mode:
Procedural approaches in interventional pulmonology range from traditional techniques to highly advanced, technology-driven methods, impacting patient outcomes and operator skill requirements.
- Robotic-Assisted Methods:These systems enhance precision and control for reaching small, peripheral pulmonary nodules, improving diagnostic yield. Specialized training centers in the United States are critical for expanding the adoption of robotic bronchoscopy.
- Minimally Invasive Techniques:These procedures reduce patient trauma and recovery times compared to open surgery, utilizing endoscopic tools through natural orifices. Hospitals across Europe increasingly favor minimally invasive approaches for a wide range of diagnostic and therapeutic interventions.
- Invasive Procedures:Traditional surgical interventions, though less common for primary diagnosis, remain necessary for certain complex cases.
- Image-Guided Interventions:Techniques that use real-time imaging, such as fluoroscopy or ultrasound, to guide instruments during procedures.
- Laser Therapy:The use of laser energy for tissue ablation and debulking within the airways.
Minimally invasive techniques form the procedural baseline. Robotic-assisted methods represent the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic hospitals represent the primary adopter of advanced interventional pulmonology technologies across various geographies. These institutions drive concentrated demand for sophisticated systems due to their research focus and high procedural volumes. National health strategies significantly influence market development by channeling investment into upgrading hospital infrastructure and acquiring advanced diagnostic equipment.
China
Government initiatives to modernize healthcare infrastructure are channeling significant investment into advanced diagnostic equipment. The NMPA's streamlined approval processes for innovative medical devices accelerate market entry. Major urban centers like Shanghai and Beijing are experiencing rapid expansion of specialized pulmonary care facilities.
United States
Academic medical centers are leading the adoption of robotic-assisted bronchoscopy platforms for early lung cancer diagnosis. The FDA's Safer Technologies Program (STeP) offers an expedited pathway for novel diagnostic and therapeutic devices. Specialized training centers in states such as California and Massachusetts are critical for expanding the adoption of complex techniques.
Germany
An aging demographic contributes to a rising incidence of chronic obstructive pulmonary disease and lung cancer, sustaining high procedural volumes. Europe's Medical Device Regulation (MDR) mandates stringent clinical evidence for device approval. Academic medical centers in regions like Bavaria and North Rhine-Westphalia drive significant demand for integrated imaging suites.
Japan
The country's aging population drives consistent demand for diagnostic and therapeutic interventions related to pulmonary conditions. The PMDA regulates medical device approvals, emphasizing safety and efficacy for new technologies. Research and development hubs in Tokyo and Osaka focus on advancing minimally invasive techniques for respiratory diseases.
Brazil
Improving healthcare infrastructure and rising disposable incomes expand access to advanced pulmonary care in major cities. ANVISA oversees medical device registration, ensuring product safety and quality for the national market. São Paulo and Rio de Janeiro are seeing increased investment in specialized clinics and hospital departments.
Interventional Pulmonology Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in interventional pulmonology. The market exhibits a tiered structure, with established medical device giants offering broad portfolios alongside focused innovators specializing in niche technologies. Companies are increasingly engaging in strategic partnerships and R&D investments to drive innovation in robotic and image-guided interventions.
Within the broad portfolio provider archetype, Medtronic sustains a comprehensive product line, including its electromagnetic navigation bronchoscopy systems for complex diagnostic procedures. Olympus Corporation exemplifies established market leaders, leveraging its strong brand and extensive service network in the endoscope segment. Boston Scientific Corporation represents specialized device innovators, differentiating through its focus on minimally invasive devices for airway stenosis.
| Leading Market Players |
|---|
| Medtronic |
| Karl Storz |
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| Richard Wolf Corporation |
| Olympus Corporation |
| Cook Medical |
| Smiths Group plc |
| FUJIFILM Corporation |
| Others |
Cost & Logistics Intelligence
German manufacturing clusters, known for precision engineering, influence downstream pricing power for advanced interventional pulmonology devices through their specialized component capacity. The market's shift towards managed service contracts also reconfigures cost structures for hospitals, emphasizing predictable operational expenditures over large capital outlays.
Pricing Analysis
Long-term contracts for high-cost imaging systems often follow a cost-plus structure with service-level indexation. Price differentiation stems from brand premium, particularly for established players like Olympus Corporation, and the extent of after-sales service bundles. Pricing pressure intensifies for manufacturers due to hospital reimbursement uncertainty for novel procedures. Specialty clinics and smaller hospital groups exhibit higher price sensitivity compared to well-funded academic medical centers.
Supply Chain Analysis
Upstream, specialized micro-optics and robotics components form critical inputs for interventional pulmonology devices. Geographic supply concentration centers on China for base components, with advanced manufacturing and assembly capabilities in Germany and Japan. The supply chain faces single-source vulnerability for specialized micro-optics required in next-generation robotic bronchoscopes. Distribution runs through direct sales teams and long-term managed service partnerships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a growth-through-capability-building story, primarily due to the scarcity of specialized interventional pulmonologists trained in advanced robotic techniques.
For Market Incumbents: Insulate core market share by deepening R&D investments in AI-driven diagnostic software for existing platforms. Leverage extensive service networks to offer comprehensive managed service contracts, bundling equipment and training to counter emerging niche competitors. Strengthen regulatory affairs capabilities to navigate evolving device approval pathways like Europe's MDR.
For New Entrants and Emerging Players: Build out specialized training and simulation programs to address the bottleneck in qualified interventional pulmonologists. Target underpenetrated geographic markets like Brazil and India with cost-effective, minimally invasive diagnostic tools. Partner with academic hospitals to validate novel localized therapeutic delivery systems, gaining early clinical adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a high-growth, innovation-driven play because aging demographics and rising chronic respiratory diseases sustain demand for advanced interventions. Focus on acquiring specialized device innovators with strong intellectual property in robotic-assisted methods or AI-driven diagnostic software. The signal to watch is the expansion of favorable reimbursement codes for novel interventional pulmonology procedures in major healthcare markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Integrates AI for enhanced diagnostic accuracy and procedural guidance in complex cases. |
| Hospital System Partnership | Secures long-term equipment leasing and managed service contracts with predictable revenue streams. |
| Reimbursement Strategy Advocacy | Expands coverage for novel interventional procedures, reducing financial barriers for adoption. |
| FDA STeP Submission | Accelerates market access for innovative devices offering significant safety improvements. |
| Training Program Expansion | Addresses the critical shortage of skilled interventional pulmonologists for advanced systems. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary validation through regulatory filings anchors the qualitative findings. This study engaged interventional pulmonologists, hospital procurement managers, medical device R&D leads, and regulatory affairs specialists. Secondary data sources included US FDA filings, Europe's EMA MDR guidelines, NMPA announcements, and clinical trial registries, contributing to both bottom-up and top-down triangulation.
The analytical framework calibrates market size and growth across the analysis window by modeling segmentation dimensions including product type, therapy area, end user, delivery mode, and geographic region. Compound annual growth rates were derived from historical data, technological adoption rates, and demographic shifts. Key industry-specific forecast inputs included incidence rates of lung cancer and chronic obstructive pulmonary disease, alongside healthcare infrastructure investment trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by established device manufacturers or new robotic system innovators would shift outcomes. Unforeseen regulatory changes, rapid technological disruption, or major shifts in healthcare spending priorities represent risk factors. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Artificial Lung Market