
 Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market | 2026-2036
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market Analysis
CE marking under the EU Medical Device Regulation is unwinding market access for plasma-derived biologics manufacturers seeking European commercialization. Grifols leverages its integrated plasma collection network across the United States and Europe to sustain fractionation capacity for augmentation therapies. CSL Behring anchors its position through control of donor plasma supply chains and specialized cold-chain distribution infrastructure. Kamada competes by specializing in recombinant and plasma-derived protein manufacturing from its Israeli production base.
Alpha-1 antitrypsin deficiency treatment encompasses intravenous augmentation therapy, inhaled formulations, and emerging gene-editing interventions designed to restore functional SERPINA1 protein levels in patients with inherited deficiency states. The standard therapeutic involves weekly intravenous infusions of purified human alpha-1 antitrypsin at doses of 60 mg per kilogram, with the protein sourced from pooled human plasma through Cohn fractionation and viral inactivation protocols. Pulmonary support applications dominate current utilization, as intravenous delivery of Prolastin and Zemaira concentrates generates the largest revenue pool among product types. Subcutaneous and nebulized delivery modes represent the fastest-expanding segments, driven by patient preference for reduced infusion center dependency and emerging bioavailability data for alternative administration routes.
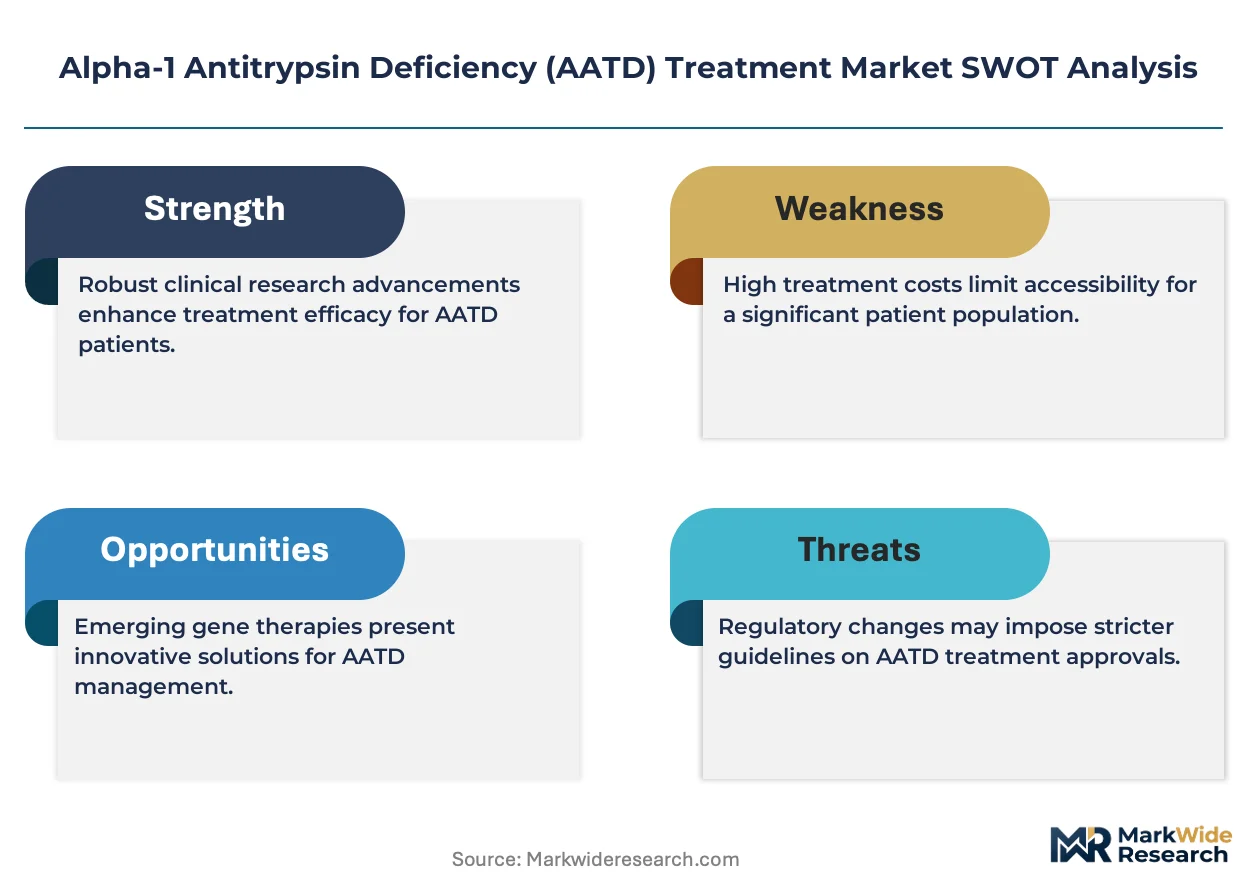
The FDA's orphan drug exclusivity framework and the EMA's priority medicines scheme jointly govern market access incentives for novel AATD therapeutics, with both agencies demanding longitudinal safety data for gene therapy candidates. The European F-Gas Regulation and US EPA guidelines on cold-chain refrigerants impose compliance costs on plasma product logistics, favoring manufacturers with upgraded temperature-controlled distribution systems. Stakeholders must monitor clinical readouts from Arrowhead Pharmaceuticals' RNA interference programs and evolving payer policies on home infusion reimbursement to anticipate shifts in competitive positioning.
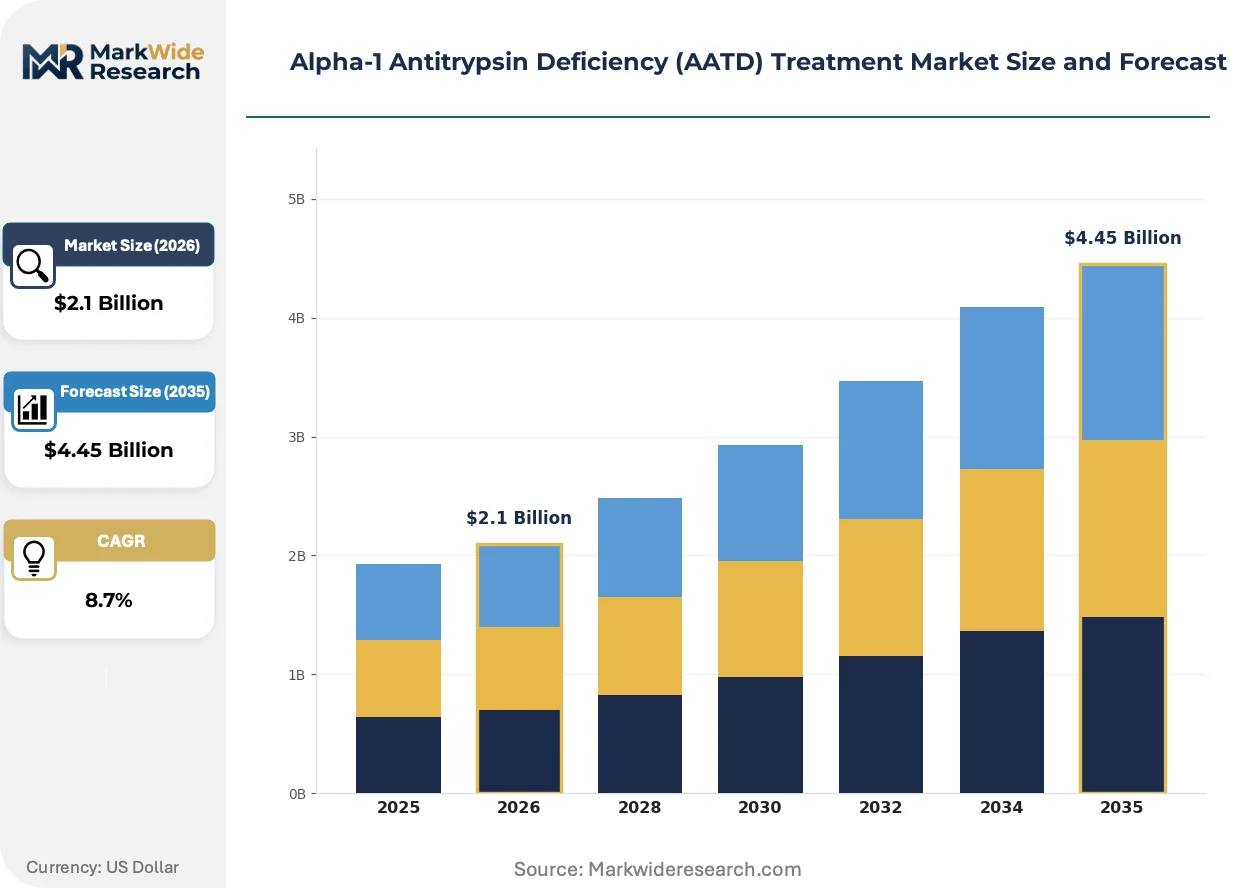
Market Dynamics
Plasma supply scarcity is compressing fractionation economics and accelerating investment in recombinant protein platforms as manufacturers seek supply chain independence from donor-dependent collection networks.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug exclusivity framework and EMA's priority medicines scheme accelerate approval timelines for novel AATD therapeutics, reducing development risk for sponsors targeting small patient populations.
- Home Infusion Expansion:Specialty pharmacies are capturing dispensing volume as payers expand reimbursement for home-based administration, reducing infusion center dependency and improving patient adherence.
- Gene Therapy Pipelines:RNA interference and gene-editing platforms are advancing through clinical stages, promising functional cures that would eliminate chronic augmentation therapy requirements.
Market Restraints
- Plasma Collection Bottlenecks:Fractionators depend on finite donor pools concentrated in the United States and Germany, creating supply vulnerability when collection disruptions occur.
- Cold-Chain Compliance Costs:The EU F-Gas Regulation and US EPA refrigerant guidelines impose escalating logistics expenses on temperature-sensitive plasma product distribution.
- Diagnostic Underdetection:AATD remains widely undiagnosed despite available screening, limiting addressable patient populations and treatment initiation rates.
Strategic Opportunities
- Subcutaneous Formulations:Development of subcutaneous delivery systems would unlock patient self-administration and reduce healthcare system burden compared to intravenous protocols.
- Emerging Market Penetration:Diagnostic expansion in Brazil and Saudi Arabia offers untapped patient identification potential as healthcare infrastructure modernizes.
- Gene Therapy Manufacturing:Viral vector production capacity investments position contract manufacturers to capture value from AATD gene therapy commercialization.
Industry Challenges
- Longitudinal Safety Surveillance:Gene therapy candidates require multi-year follow-up data, extending development timelines and regulatory review periods beyond traditional biologics.
- Plasma Protein Engineering:Recombinant AAT production demands rare expertise in glycosylation pattern replication to match native protein half-life and activity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prolastin, Zemaira, Aralast, Glassia Delivery Mode: Intravenous, Subcutaneous, Inhalation, Nebulized End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Application: Pulmonary Support, Liver Disease Management, Therapeutic Prophylaxis, Symptomatic Relief |
| Companies Covered | Grifols, CSL Behring, Takeda Pharmaceutical Company Limited, Kamada, AstraZeneca, Pfizer, Baxter International, GlaxoSmithKline, Arrowhead Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market Emerging Trajectories
Recombinant manufacturing platforms and alternative delivery modalities are disrupting the decades-old paradigm of plasma-derived intravenous augmentation, forcing incumbents to diversify beyond fractionation economics.
Subcutaneous alpha-1 antitrypsin formulations are supplanting intravenous protocols in development pipelines, offering patients self-administration capability and eliminating infusion center visits. Biotech sponsors are prioritizing bioequivalence studies against established intravenous products. The shift is compressing site-of-care revenue pools while expanding addressable patient populations previously excluded by access barriers.
The EU Medical Device Regulation's CE marking requirements are tightening market access for plasma-derived biologics manufacturers seeking European commercialization. Compliance documentation demands have extended regulatory review timelines. Manufacturers with established quality management systems are absorbing costs more readily than emerging competitors.
Patient advocacy organizations are driving diagnostic screening expansion through direct-to-consumer testing partnerships and physician education campaigns. The Alpha-1 Foundation's registry infrastructure in the United States is being replicated by patient groups in Canada and Australia. This behavioral shift is accelerating case identification rates and expanding treatment-eligible cohorts faster than traditional clinical detection pathways.
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market Segmentation
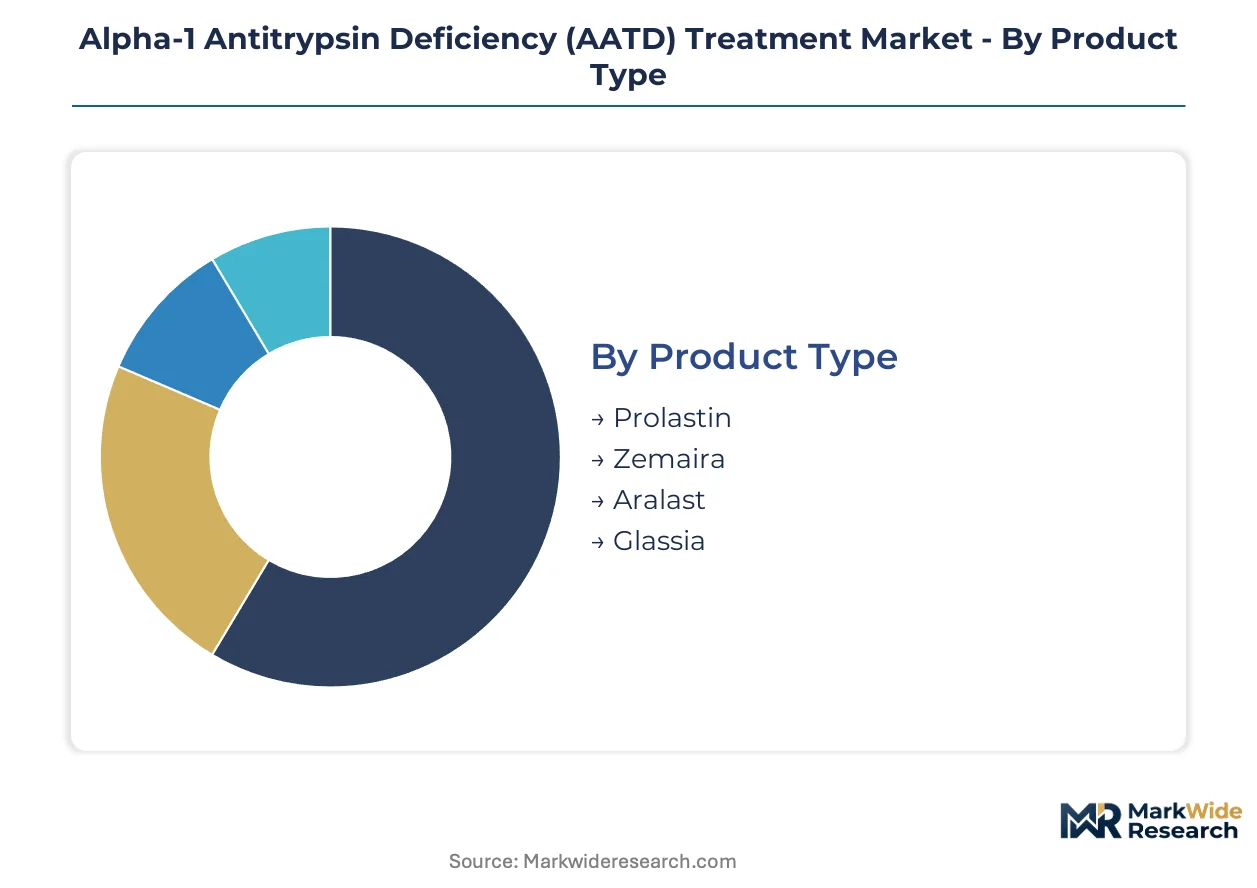
Segmentation in the AATD treatment market reveals how therapeutic modalities compete for patient volume and reimbursement preference. Product origin, delivery convenience, and site-of-care economics determine which configurations capture commercial momentum.
Product Type:
Substitution pressure from recombinant platforms and biosimilar entrants concentrates heaviest on legacy plasma-derived brands with patent cliff exposure.
- Prolastin:The original alpha-1 proteinase inhibitor concentrate, purified through Cohn fractionation with solvent-detergent viral inactivation. Demand concentrates in United States infusion centers where Grifols maintains contractual relationships with pulmonology practices; reimbursement familiarity sustains volume despite newer entrants.
- Zemaira:CSL Behring's purified AAT formulation with documented pharmacokinetic equivalence to Prolastin. United States specialty pharmacies are capturing dispensing volume as payers expand home infusion reimbursement; CSL's captive plasma supply chain insulates against fractionation shortages.
- Aralast:Baxter's plasma-derived augmentation therapy with established cold-chain distribution through hospital outpatient departments.
- Glassia:Kamada's liquid-ready formulation eliminating reconstitution steps, manufactured at its Israeli fractionation facility.
Prolastin retains volume leadership; Glassia holds the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates hospital-based intravenous administration from self-administered alternatives commanding premium pricing for convenience.
- Intravenous:Weekly 60 mg/kg infusions through peripheral venous access remain the standard of care with decades of safety data. United States hospital outpatient departments and infusion centers generate the largest revenue pool; site-of-care reimbursement differentials favor institutional billing over home settings.
- Subcutaneous:Investigational formulations using hyaluronidase-facilitated depot injection promise patient self-administration. Development pipelines at Arrowhead Pharmaceuticals and Intellia Therapeutics are advancing bioequivalence studies; FDA breakthrough therapy designation would accelerate label expansion.
- Inhalation:Nebulized AAT delivery directly to pulmonary epithelium, explored for localized protein replacement with reduced systemic exposure.
- Nebulized:Aerosolized formulations targeting alveolar deposition, requiring specialized compressor systems and patient training protocols.
Intravenous administration dominates current volume; subcutaneous delivery is gaining share fastest.
End User:
Customer type migration from institutional settings to patient-directed channels is redistributing margin capture across the value chain.
- Hospitals:Academic medical centers with dedicated alpha-1 clinics anchor complex case management and clinical trial recruitment.
- Clinics:Pulmonology and hepatology practices with infusion capacity capture stable chronic patient populations.
- Home Care:Nursing-supported residential infusion is expanding as United States Medicare Advantage plans broaden prior authorization for domiciliary services.
- Specialty Pharmacies:CVS Specialty, Accredo, and BioPlus are consolidating dispensing volume through direct-to-patient shipment and reimbursement navigation.
Specialty pharmacies are climbing the fastest in dispensing share; hospitals retain the highest-acuity case concentration.
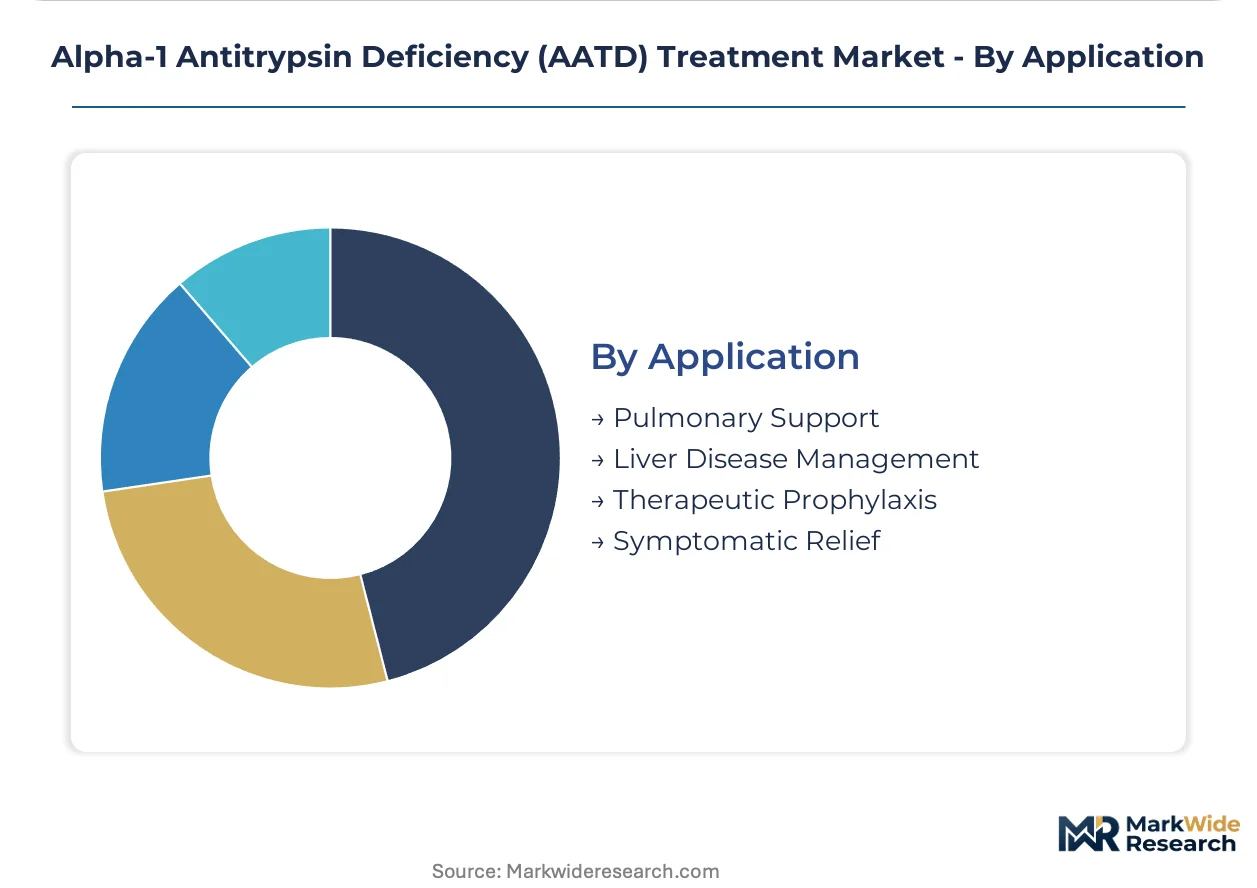
Application:
Maturity differentiation separates well-established pulmonary indications from liver-directed therapies with unmet medical need.
- Pulmonary Support:Emphysema prevention through augmentation therapy represents the approved and reimbursed indication with largest patient eligibility. United States pulmonologists initiate therapy based on Alpha-1 Foundation registry protocols; FEV1 decline reduction provides measurable clinical endpoint.
- Liver Disease Management:Pediatric and adult cholestatic liver disease in PiZZ patients lacks approved pharmacotherapy, creating development opportunity for gene therapy and RNA interference platforms.
- Therapeutic Prophylaxis:Pre-symptomatic intervention in genotype-positive, lung-function-normal individuals remains investigational with contested cost-effectiveness.
- Symptomatic Relief:Adjunctive bronchodilator and anti-inflammatory co-therapy addresses acute exacerbations without modifying underlying deficiency.
Pulmonary support retains volume leadership; liver disease management holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug incentives and patient registry infrastructure are concentrating AATD treatment demand in jurisdictions with established plasma collection networks and specialized reimbursement pathways.
United States
The Alpha-1 Foundation operates the world's largest patient registry with over 100,000 enrolled individuals, driving diagnostic screening expansion across pulmonology practices. FDA orphan drug exclusivity frameworks accelerate approval timelines for novel therapeutics. Grifols maintains fractionation capacity through its integrated plasma collection network spanning Texas, California, and North Carolina collection centers.
Germany
CSL Behring anchors European plasma supply through its Marburg fractionation facility, processing donor material from German and Austrian collection sites. EMA priority medicines schemes reduce regulatory review periods for breakthrough AATD therapies. The Rhine-Main industrial cluster houses specialized cold-chain logistics providers serving hospital outpatient departments across Bavaria and Baden-Württemberg.
United Kingdom
NHS England's specialized commissioning framework governs access to augmentation therapies through designated alpha-1 treatment centers in Manchester and London. MHRA post-Brexit regulatory autonomy permits streamlined approval pathways for plasma-derived biologics. The Cambridge-Oxford biotech corridor hosts gene therapy research programs targeting SERPINA1 deficiency correction.
Canada
Health Canada's orphan drug regulatory pathway mirrors FDA incentives, attracting sponsors to conduct clinical trials in Toronto and Vancouver academic medical centers. Provincial formularies in Ontario and Quebec maintain distinct prior authorization requirements for home infusion reimbursement. Canadian Blood Services plasma collection infrastructure supplies domestic fractionation demand.
Australia
The Therapeutic Goods Administration's orphan drug designation provides fee waivers and priority evaluation for AATD therapeutics entering the Australian market. The Lifeblood plasma collection network concentrates donor recruitment in Sydney, Melbourne, and Brisbane metropolitan areas. Patient advocacy organizations are replicating US registry models to accelerate case identification in Victoria and New South Wales.
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market Vendor Landscape
Listed plasma fractionators compete with private biotechnology specialists across gene therapy development and alternative delivery modality pipelines. Market structure consolidates around three vertically integrated plasma collectors controlling donor supply chains, while emerging RNA interference and gene-editing platforms fragment therapeutic innovation. Strategic archetypes span plasma-dependent incumbents, recombinant protein specialists, and gene therapy platform developers. Dominant competitive moves include plasma collection network expansion and subcutaneous formulation bioequivalence studies.
Among plasma-derived therapy anchors, Grifols and CSL Behring occupy positions sustained by captive donor supply chains and cold-chain distribution infrastructure. Kamada represents the recombinant manufacturing archetype from its Israeli production base, specializing in liquid-ready formulations that eliminate reconstitution steps. Arrowhead Pharmaceuticals exemplifies the RNA interference platform approach, advancing clinical candidates through FDA breakthrough therapy designation pathways.
| Leading Market Players |
|---|
| Grifols |
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Kamada |
| AstraZeneca |
| Pfizer |
| Baxter International |
| GlaxoSmithKline |
| Arrowhead Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Forty-five-day cold-chain inventory cycles govern fractionation economics, binding plasma collection density to pricing power through donor pool scarcity and viral inactivation certification tiers. Grifols and CSL Behring leverage captive United States and German donor networks to command premium positioning against recombinant challengers facing glycosylation validation costs.
Pricing Analysis
Certification level (FDA-grade viral inactivation, CE marking under EU MDR) creates the primary spread between plasma-derived and recombinant offerings. The dominant structure is contract-based long-term offtake between fractionators and hospital systems, with price differentiation driven by cold-chain reliability guarantees and volume scale commitments. Pricing pressure stems from Medicare Advantage home infusion reimbursement expansion compressing site-of-care margins. Academic medical centers show least price sensitivity due to clinical trial infrastructure requirements; independent pulmonology practices exhibit highest sensitivity to per-infusion reimbursement differentials.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Israeli and United States-sourced plasma products entering European hospital networks. Supply concentrates in the United States, Germany, and Israel, drawing from fractionation facilities tethered to donor collection networks in Texas, Bavaria, and the Negev region. Raw material dependencies center on source plasma, chromatography resins, and solvent-detergent viral inactivation reagents. Single-source vulnerability runs through United States donor pool concentration, where CSL Behring and Grifols control over sixty percent of collection infrastructure. Distribution runs through specialty pharmacy direct-to-patient shipment and hospital outpatient department cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AATD treatment market presents a defensive moat sustained by regulatory entrenchment, where FDA orphan drug exclusivity and EMA priority medicines schemes erect multi-year barriers against substitutable entrants.
For Market Incumbents: Fortify plasma collection network density through donor center expansion in Texas and North Carolina, insulating against recombinant protein platform substitution. Deepen backward integration into viral inactivation technology to capture margin from solvent-detergent reagent supply. Prioritize CE marking compliance investments ahead of EU MDR enforcement waves that threaten competitor market access. For New Entrants and Emerging Players: Lead with subcutaneous formulation bioequivalence studies targeting Medicare Advantage home infusion channels, the most penetrable reimbursement pathway for patient self-administration. Target liver disease management applications in pediatric PiZZ populations, where unmet medical need exceeds pulmonary support saturation. Deploy gene therapy platform partnerships with academic medical centers to secure longitudinal safety data infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to divest plasma fractionation units amid recombinant transition pressures. Five-to-ten-year viability favors manufacturers with dual recombinant and plasma-derived pipelines. The signal to watch is Arrowhead Pharmaceuticals RNA interference readout data, which would indicate gene therapy displacement velocity for chronic augmentation therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Patient self-administration unlocks Medicare Advantage home infusion reimbursement expansion. |
| Plasma Collection Network Expansion | Grifols strengthens donor pool control against recombinant protein platform substitution threats. |
| Gene Therapy Clinical Advancement | Arrowhead Pharmaceuticals RNA interference candidates target functional cure elimination of chronic therapy. |
| CE Marking Pathway Investment | Kamada absorbs EU MDR compliance costs that burden emerging competitor European commercialization. |
| Specialty Pharmacy Partnership | CVS Specialty and Accredo consolidate dispensing volume through direct-to-patient cold-chain logistics. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plasma fractionation executives, regulatory affairs leads at EMA and FDA, specialty pharmacy formulary directors, and pulmonology practice administrators; and secondary validation through FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov gene therapy registries, and Medicare Advantage reimbursement policy databases. Bottom-up patient volume modeling triangulated against top-down fractionation capacity estimates across the analysis window.
Across the projection horizon, the analytical framework segmented by product origin (plasma-derived versus recombinant), delivery mode (intravenous, subcutaneous, nebulized), and site-of-care economics (hospital outpatient, specialty pharmacy, home infusion). CAGRs derived from epidemiological prevalence modeling, diagnostic screening expansion rates, and payer policy trajectory assumptions. Forecast inputs incorporated Alpha-1 Foundation registry growth curves and EU F-Gas Regulation cold-chain compliance cost pass-through estimates.
The analysis sits within stated boundaries; outcomes outside sustained orphan drug incentive frameworks, plasma collection network stability, and gene therapy safety profile validation would require recalibration. Forecasts reflect documented assumptions regarding diagnostic detection rates, reimbursement policy continuity, and fractionation capacity utilization. Specific risks that could revise projections include RNA interference platform approval accelerating augmentation therapy obsolescence, or donor pool disruptions from United States collection center regulatory enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Global Pneumonia Therapeutics Market