
 Short-Acting Beta-Agonists Market | 2026-2036
Short-Acting Beta-Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Acting Beta-Agonists Market Analytics
Subscription-based patient monitoring programs is recalibrating how pharmaceutical companies monetize short-acting beta-agonist therapy beyond the initial prescription. Teva Pharmaceutical Industries Ltd leverages its respiratory portfolio breadth to sustain manufacturing scale across multiple dosage forms. GlaxoSmithKline plc anchors brand recognition in emergency bronchodilation through decades of clinical positioning. Cipla Limited competes on cost-engineered inhaler platforms that navigate price-sensitive procurement channels in emerging markets.
Short-acting beta-agonists comprise a class of rapid-onset bronchodilators, typically administered via inhalation within minutes of symptom onset, that selectively stimulate beta-2 adrenergic receptors to relax airway smooth muscle. These agents serve as rescue medication for acute bronchospasm across asthma, chronic obstructive pulmonary disease, and exercise-induced respiratory distress. Albuterol formulations occupy the dominant volume position due to extensive generic availability and established clinical protocols, while metered-dose inhalers concentrate the majority of commercial value through portable convenience and dose-precision engineering. Nebulizer-compatible inhalation solutions capture growing homecare share as reimbursement expands for ambulatory respiratory management.
The FDA enforces bioequivalence requirements for generic inhaled products through increasingly rigorous pharmacokinetic and pharmacodynamic benchmarks that elevate development costs for market entrants. The EPA regulates propellant transitions under Clean Air Act amendments, forcing reformulation investments across chlorofluorocarbon-free delivery platforms. Stakeholders must monitor how evolving bioequivalence standards reshape generic substitution economics and manufacturing compliance burdens.
Market Dynamics
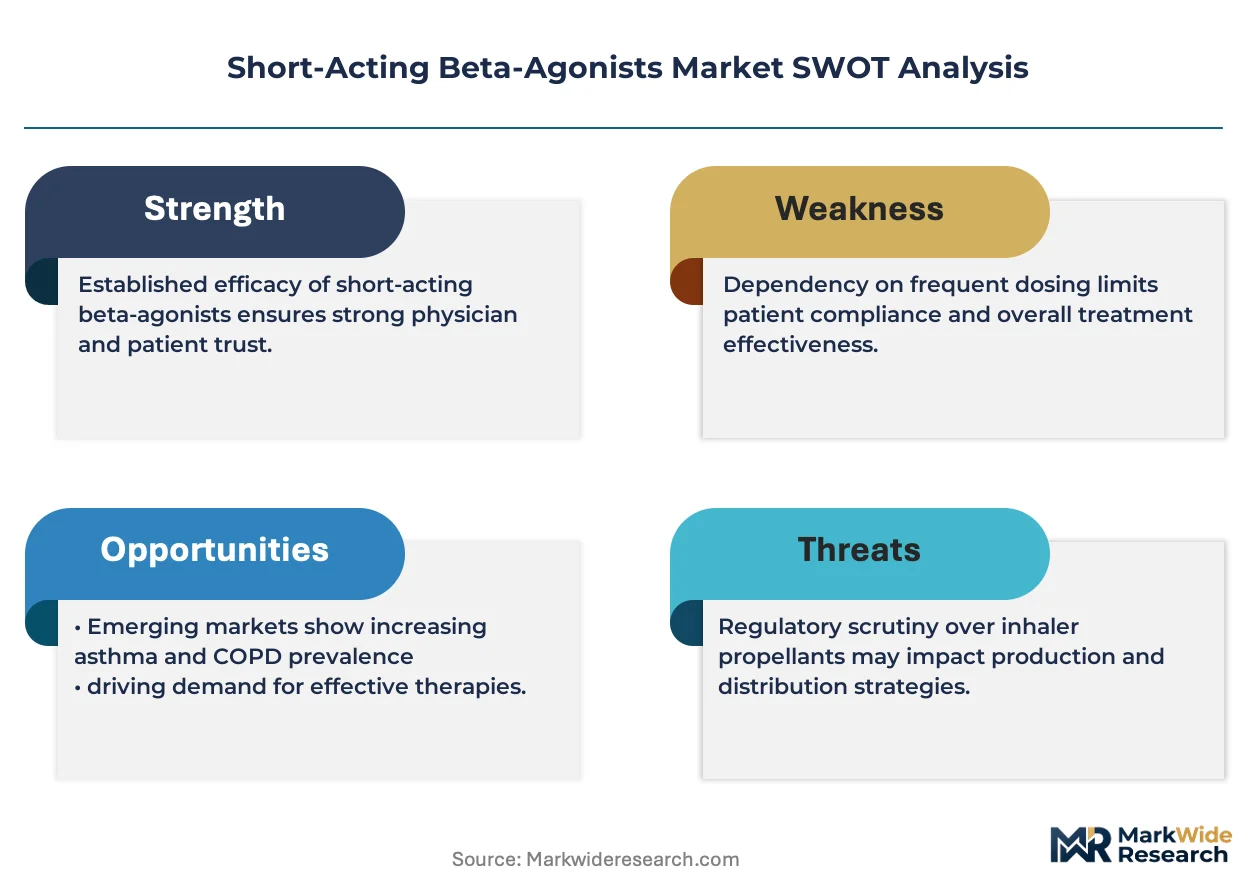
FDA bioequivalence standards for generic inhaled products are compressing development timelines and elevating capital requirements for market entrants, fundamentally restructuring competitive economics across rescue bronchodilator supply.
Growth Catalysts
- Homecare reimbursement expansion:Medicare and private payers in the United States now cover ambulatory nebulizer systems, accelerating patient migration from acute care settings to self-administered rescue therapy.
- REACH propellant mandates:The EU F-Gas Regulation is forcing chlorofluorocarbon-free reformulations, creating replacement demand for hydrofluoroalkane-based metered-dose inhalers across European markets.
- Exercise-induced bronchospasm protocols:Sports medicine guidelines now mandate pre-activity SABA prophylaxis for elite athletic programs, opening institutional procurement channels beyond traditional asthma management.
Market Restraints
- Active pharmaceutical ingredient concentration:Albuterol sulfate manufacturing clusters in India and China, exposing supply chains to export licensing disruptions and geopolitical friction.
- Bioequivalence study costs:FDA pharmacokinetic and pharmacodynamic benchmarks for inhaled generics require specialized clinical infrastructure that excludes smaller development houses.
- Long-acting beta-agonist maintenance therapy:Once-daily LABA controllers reduce rescue inhaler dependence in well-managed asthma populations, constraining volume growth in developed markets.
Strategic Opportunities
- Subscription monitoring platforms:Digital inhaler sensors paired with adherence analytics create recurring revenue streams beyond initial prescription fulfillment in United States homecare markets.
- Environmental sustainability mandates:The EPA Clean Air Act amendments position low-global-warming-potential propellant platforms for preferential procurement in federal and state health systems.
- Pediatric dose-precision engineering:Breath-actuated inhalers with flow-rate compensation address unmet needs in children under twelve, a segment underserved by standard metered-dose designs.
Industry Challenges
- Inhaler device engineering talent:Cross-disciplinary expertise spanning aerosol physics, human factors design, and polymer science remains scarce, extending product development cycles.
- Legacy nebulizer compatibility:New formulation chemistries must demonstrate stability across incompatible compressor technologies, complicating universal labeling claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Acting Beta-Agonists Market |
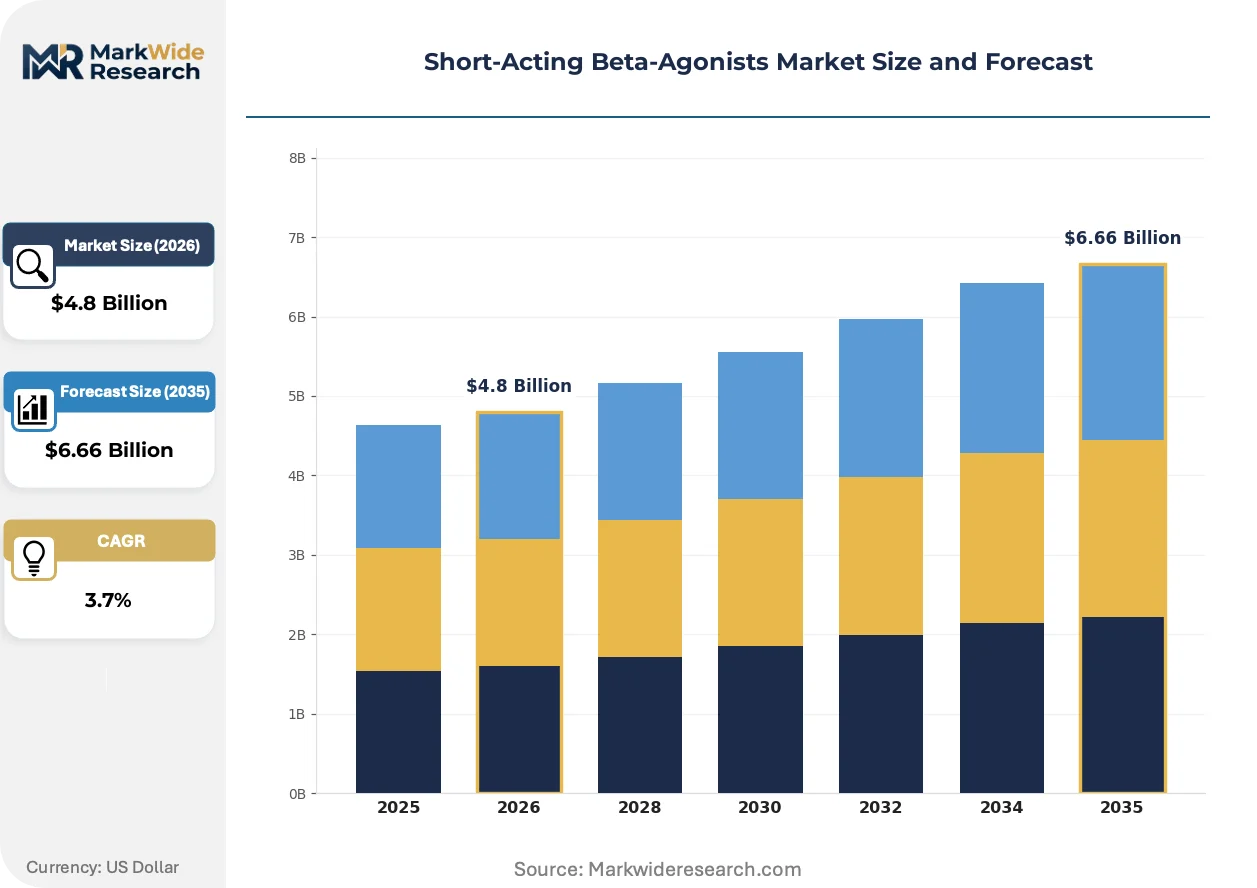
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Albuterol, Levalbuterol, Pirbuterol, Terbutaline Formulation: Inhalation Solution, Metered-Dose Inhalers, Nebulizers, Tablets Application: Asthma, Chronic Obstructive Pulmonary Disease, Exercise-Induced Bronchospasm, Acute Bronchospasm End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Viatris Inc, F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Cipla Limited, Merck & Co., Inc, AstraZeneca plc, Johnson & Johnson Services, Inc, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Acting Beta-Agonists Market Evolving Landscape
Connected inhaler ecosystems are rewiring how rescue therapy is prescribed, monitored, and reimbursed, collapsing the historical separation between pharmaceutical delivery and digital health infrastructure.
Smart inhaler technology is integrating dose-counters, Bluetooth connectivity, and real-time adherence feedback into rescue medication delivery. Pulmonology practices in the United States are deploying these devices to identify poor technique and trigger intervention before emergency escalation. This convergence is integrating pharmaceutical manufacturers into longitudinal patient management contracts that extend far beyond the initial prescription.
The EPA's phasedown of hydrofluoroalkane propellants under Clean Air Act authority is compelling reformulation investments across metered-dose inhaler portfolios. Manufacturers must demonstrate equivalent clinical performance while meeting stringent global warming potential thresholds. Generic entrants face the steepest compliance burden, as their cost-engineered platforms lack capital reserves for dual-track development of legacy and next-generation propellant systems.
Patients are consolidating pharmacy relationships around integrated respiratory management programs that bundle SABA rescue therapy with controller medications and adherence coaching. Retail pharmacy chains in the United States are capturing this shift through disease-state management subscriptions that displace traditional prescription fulfillment. This behavioral pivot concentrates purchasing power among three national pharmacy benefit managers, compressing price negotiation leverage for standalone inhaler suppliers.
Short-Acting Beta-Agonists Market Segmentation
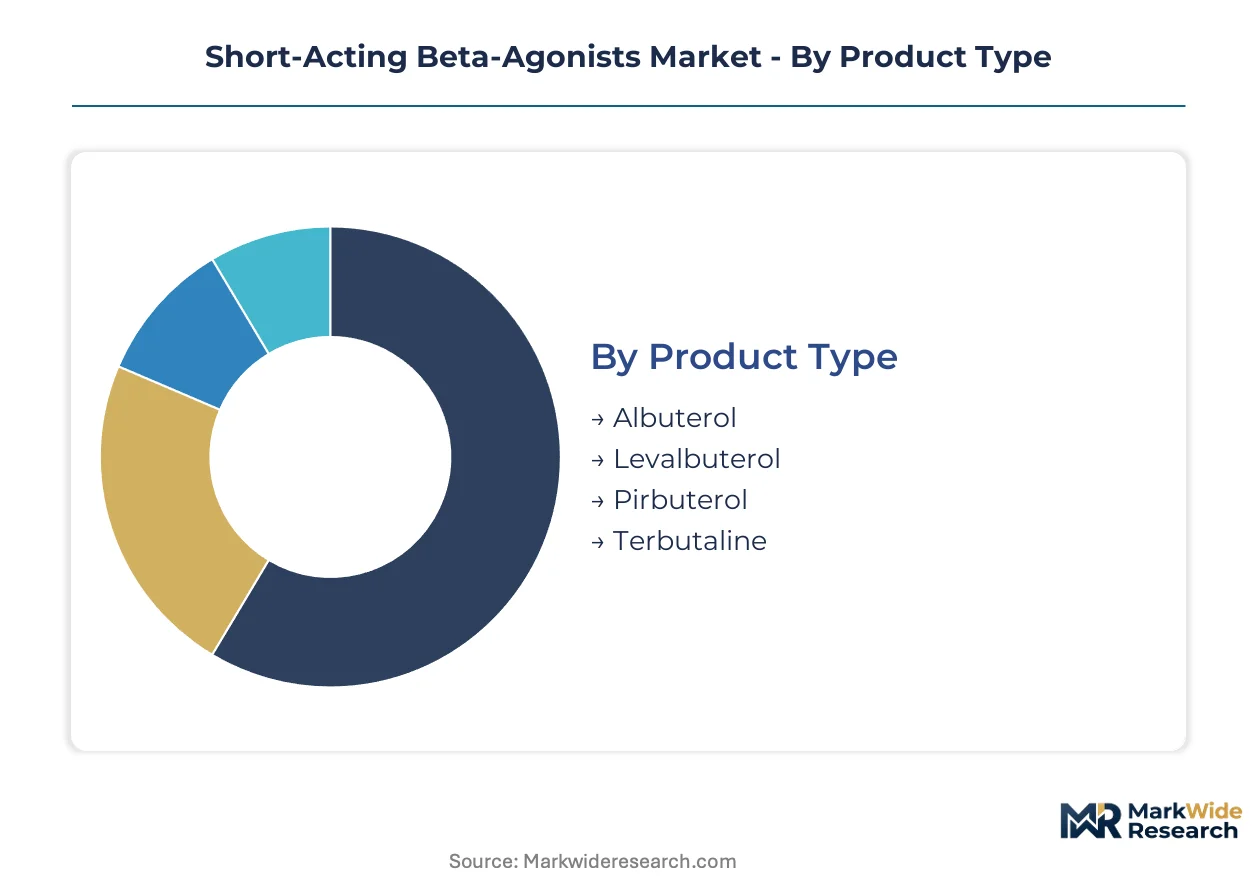
Segmentation in rescue bronchodilator markets reveals distinct procurement patterns across clinical versus self-administered settings. Product chemistry, delivery mechanism, and care venue each shape reimbursement pathways and manufacturing scale requirements differently.
Product Type:
Generic availability and clinical protocol penetration differentiate prescribing behavior across this category.
- Albuterol:The racemic beta-2 agonist dominates volume through extensive generic manufacturing and established emergency department protocols. United States hospital formularies standardize on albuterol sulfate inhalation solution for nebulizer administration, though API concentration in Indian and Chinese manufacturing clusters exposes supply chains to export licensing friction.
- Levalbuterol:The single-enantiomer formulation commands premium positioning in pediatric and cardiac-sensitive populations where reduced beta-1 stimulation matters. Medicare reimbursement for levalbuterol concentrates in academic medical centers with specialized pulmonology units, constrained by higher per-dose cost relative to racemic alternatives.
- Pirbuterol:Breath-activated dry powder systems serve niche exercise-induced bronchospasm prophylaxis in athletic programs.
- Terbutaline:Injectable and oral formulations persist in obstetric and preterm labor applications outside primary respiratory rescue.
Albuterol leads volumes today; levalbuterol is gaining share fastest in pediatric-specialized prescribing networks.
Formulation:
Engineering complexity and patient autonomy requirements determine competitive entry barriers across delivery platforms.
- Metered-Dose Inhalers:Portable dose-precision systems concentrate commercial value through hydrofluoroalkane propellant engineering. The EPA Clean Air Act amendments are forcing reformulation investments across chlorofluorocarbon-free platforms, with generic entrants lacking capital reserves for dual-track legacy and next-generation propellant development.
- Inhalation Solution:Nebulizer-compatible liquid formulations capture expanding homecare share as Medicare and private payers cover ambulatory compressor systems. United States retail pharmacy chains bundle these solutions with disease-state management subscriptions that displace traditional prescription fulfillment.
- Nebulizers:Compressor-based delivery systems require compatibility validation across incompatible legacy technologies.
- Tablets:Oral bronchodilator formats persist in limited acute care and prehospital settings where inhalation is contraindicated.
Metered-dose inhalers anchor revenue concentration; inhalation solutions are expanding most quickly through homecare reimbursement.
Application:
Disease severity and trigger predictability shape rescue medication consumption patterns and adherence monitoring investment.
- Asthma:The primary indication drives rescue inhaler dependence across all age cohorts, with digital sensor integration now standard in United States pulmonology practices for technique identification. Long-acting beta-agonist maintenance therapy in well-managed populations constrains volume growth in developed markets.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation creates sustained rescue medication demand in older populations with higher comorbidity burden. Homecare nebulizer adoption concentrates in COPD given the frequency of acute exacerbations requiring ambulatory management.
- Exercise-Induced Bronchospasm:Pre-activity prophylaxis protocols in elite athletic programs open institutional procurement channels beyond traditional asthma management.
- Acute Bronchospasm:Emergency department and prehospital rescue applications prioritize rapid onset and reliable delivery under stress conditions.
Asthma maintains the steepest volume base; COPD demonstrates the most durable expansion trajectory as populations age.
End User:
Reimbursement infrastructure and purchasing consolidation intensity vary sharply across care settings.
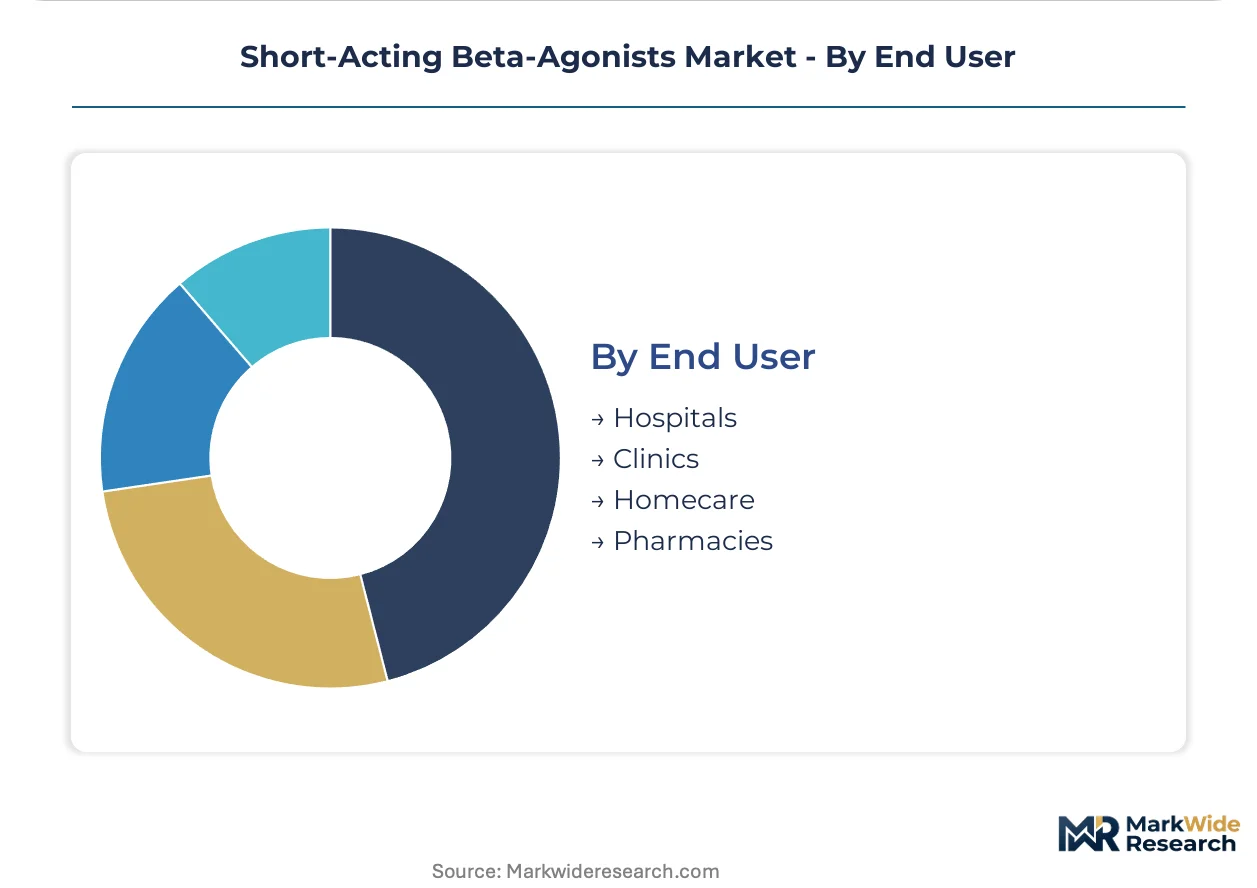
- Homecare:Self-administered rescue therapy is displacing acute care utilization as Medicare coverage expands for ambulatory nebulizer systems. United States patients consolidate pharmacy relationships around integrated respiratory management programs bundling SABA rescue with controller medications and adherence coaching.
- Hospitals:Emergency department and inpatient rescue protocols standardize on albuterol inhalation solution for nebulizer delivery, with formulary decisions concentrating purchasing power among group purchasing organizations.
- Clinics:Outpatient pulmonology practices deploy connected inhaler ecosystems to identify poor technique before emergency escalation.
- Pharmacies:Retail dispensing faces compression as pharmacy benefit managers consolidate purchasing leverage and displace standalone inhaler suppliers.
Homecare settings are climbing the fastest; hospitals retain the largest absolute consumption base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement infrastructure sustains higher per-capita SABA consumption than Germany, where EU F-Gas Regulation compliance costs compress generic manufacturer margins. National regulatory frameworks and care delivery models produce divergent procurement patterns across major markets.
United States
Medicare expansion for ambulatory nebulizer systems accelerates homecare migration from acute settings. FDA bioequivalence standards for generic inhaled products elevate capital requirements for market entrants. North Carolina's Research Triangle hosts clinical trial infrastructure supporting pharmacokinetic studies for rescue bronchodilator approvals.
Germany
EU F-Gas Regulation mandates hydrofluoroalkane propellant transitions, forcing reformulation investments across metered-dose inhaler portfolios. EMA centralized procedures streamline multi-national marketing authorizations for rescue bronchodilators. Baden-Württemberg's pharmaceutical manufacturing corridor concentrates propellant engineering expertise for next-generation inhaler platforms.
India
Price-sensitive procurement in public health programs drives demand for cost-engineered albuterol sulfate API. CDSCO manufacturing facility inspections enforce quality standards for export-oriented production. Gujarat's bulk drug manufacturing clusters supply active pharmaceutical ingredients to generic inhaler formulators across emerging markets.
China
NMPA consistency evaluations for generic inhaled products accelerate domestic substitution of imported rescue bronchodilators. National reimbursement directory updates expand coverage for nebulizer-compatible inhalation solutions. Jiangsu province's pharmaceutical industrial parks scale metered-dose inhaler device manufacturing for regional distribution.
United Kingdom
NHS Integrated Care Systems consolidate respiratory medication procurement around disease-state management contracts. MHRA post-Brexit regulatory autonomy permits tailored bioequivalence requirements for UK-specific labeling. Greater London's hospital formularies standardize connected inhaler deployments for adherence monitoring in severe asthma populations.
Short-Acting Beta-Agonists Market Competitive Landscape
Top-tier vendors anchor brand recognition and manufacturing scale, while mid-tier generic houses compete on cost-engineered platforms and regional regulatory navigation. The vendor base stratifies across three functional tiers: originator pharmaceutical companies with decades of clinical positioning, diversified generic manufacturers with respiratory portfolio breadth, and regional specialists targeting price-sensitive procurement channels. Two dominant competitive moves define current positioning: portfolio diversification into connected inhaler ecosystems with digital adherence monitoring, and backward integration into active pharmaceutical ingredient production to secure supply chain control.
Among Israel-based and UK-based pharmaceutical groups, Teva Pharmaceutical Industries Ltd and GlaxoSmithKline plc exemplify contrasting strategic archetypes. Teva represents the diversified generic manufacturer leveraging respiratory portfolio breadth across multiple dosage forms and geographies. GlaxoSmithKline occupies the originator position, anchoring brand equity in emergency bronchodilation through sustained clinical protocol penetration. Indian pharmaceutical houses including Cipla Limited sit within the regional specialist tier, competing on cost-engineered inhaler platforms that navigate emerging market procurement dynamics. These three anchors illustrate how competitive positioning fragments across regulatory sophistication, manufacturing scale, and geographic focus rather than concentrating around uniform capabilities.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Viatris Inc |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Cipla Limited |
| Merck & Co., Inc |
| AstraZeneca plc |
| Johnson & Johnson Services, Inc |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Aerosol device engineering talent concentration in Germany's Baden-Württemberg pharmaceutical corridor feeds labor-cost differentials that widen pricing spreads between premium hydrofluoroalkane-based metered-dose inhalers and economy-tier nebulizer solutions.
Pricing Analysis
Capacity additions in India's Gujarat bulk drug manufacturing clusters are reshaping price floors for generic albuterol sulfate API, compressing margins for formulators lacking backward integration into active pharmaceutical ingredient production. Pricing stratifies across premium, standard, and economy tiers, with FDA bioequivalence certification and EMA centralized marketing authorization driving differentiation between branded originators and unregistered regional suppliers. Price erosion runs through standard-tier metered-dose inhalers as Chinese NMPA-approved generics enter regional distribution channels. Hospital group purchasing organizations exhibit lowest price sensitivity given formulary standardization protocols, while retail pharmacy chains in United States homecare markets negotiate aggressively on nebulizer-compatible inhalation solutions.
Supply Chain Analysis
Freight cost volatility from Indian and Chinese API manufacturing hubs to European formulation facilities is amplifying working capital requirements for inventory positioning ahead of regulatory inspection windows. Active pharmaceutical ingredient production concentrates in India, China, and selected United States contract manufacturing organizations, with albuterol sulfate and levalbuterol hydrochloride representing critical dependencies. Supply chain risk centers on single-source vulnerability for hydrofluoroalkane propellant engineering expertise tethered to German and United States specialty chemical producers. Distribution runs through three national United States pharmacy benefit managers and consolidated European hospital group purchasing organizations that displace standalone inhaler suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Air Act phasedown mandates for hydrofluoroalkane propellants are forcing replacement demand across metered-dose inhaler portfolios.
For Market Incumbents: Lock in propellant engineering partnerships with German specialty chemical producers before capacity constraints tighten. Secure dual-track development funding for legacy and low-global-warming-potential propellant platforms to outrun generic entrants lacking capital reserves. Backward integration into Indian API manufacturing through contract offtake agreements mitigates export licensing disruption exposure from CDSCO enforcement actions. For New Entrants and Emerging Players: Begin with breath-actuated pediatric inhaler designs that address flow-rate compensation gaps in children under twelve, a segment underserved by standard metered-dose engineering. Target United States pulmonology practices deploying connected inhaler ecosystems for adherence monitoring subscriptions. Partner with retail pharmacy chains bundling disease-state management programs to bypass pharmacy benefit manager purchasing leverage concentration. For Investors and Strategic Acquirers: Diversified generic pharmaceutical houses with respiratory portfolio breadth are the most active acquirer in this space, seeking connected inhaler technology platforms to extend longitudinal patient management contracts. Acquisition target archetypes include digital inhaler sensor developers with FDA-cleared adherence analytics and regional API manufacturers with CDSCO inspection compliance records. Watch for inflection signals in Medicare reimbursement policy for ambulatory nebulizer systems that would accelerate homecare migration.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Global-Warming-Potential Propellant Transition | EPA Clean Air Act compliance positions manufacturers for preferential federal procurement. |
| Connected Inhaler Ecosystem Development | Digital sensor integration captures recurring revenue from United States pulmonology practices. |
| Backward Integration into API Manufacturing | Indian and Chinese bulk drug production secures supply chain control against export licensing friction. |
| Pediatric Dose-Precision Engineering | Breath-actuated designs address unmet needs in children under twelve across European and North American markets. |
| Subscription Monitoring Platform Launch | Adherence analytics bundled with pharmacy disease-state management programs displaces traditional fulfillment. |
Research Methodology
Multiple input streams — regulatory filings, trade flow databases, and stakeholder interviews — were reconciled through bottom-up and top-down triangulation. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed competitive positioning and reimbursement dynamics. Secondary validation drew from FDA bioequivalence guidance documents, EMA centralized procedure submissions, ClinicalTrials.gov rescue bronchodilator protocols, and CMS Medicare coverage determinations for ambulatory nebulizer systems.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product chemistry, delivery mechanism formulation, application indication, and end-user care venue dimensions. CAGRs were derived from patient population epidemiology, protocol penetration rates, and reimbursement expansion timelines specific to asthma, COPD, and exercise-induced bronchospasm indications.
Caveats apply where FDA bioequivalence standard revisions or EPA propellant phasedown acceleration could materially shift the outlook for generic manufacturer economics. Forecasts reflect assumptions regarding Medicare homecare reimbursement stability and Indian API export licensing continuity. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement timelines or NMPA consistency evaluation pace for domestic inhaled generic substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Global Anesthesia Drugs Market