
 Pediatric Respiratory Syncytial Virus Infection Market | 2026-2036
Pediatric Respiratory Syncytial Virus Infection Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Respiratory Syncytial Virus Infection Market Analytics
FDA Breakthrough Therapy designation is bifurcating which developers can advance pediatric RSV candidates through expedited review. Sanofi S.A. leverages its established pediatric vaccine infrastructure to anchor distribution across European and North American territories. Moderna, Inc. competes through mRNA platform flexibility that enables rapid antigen redesign against evolving RSV strains. Pfizer Inc. differentiates via maternal immunization positioning that extends protective benefit to infants through placental antibody transfer.
Pediatric respiratory syncytial virus infection denotes acute lower respiratory tract disease caused by an enveloped negative-sense RNA virus of the Pneumoviridae family, characterized by bronchiolitis and pneumonia in children under 24 months with peak severity between 2-8 months of age. The condition primarily threatens premature infants and those with congenital heart or chronic lung disease, driving demand for preventive and therapeutic interventions in high-risk neonatal populations. Monoclonal antibodies command the largest revenue share within product type segmentation due to nirsevimab's extended half-life enabling single-dose seasonal protection, while vaccines represent the fastest-expanding category as maternal and pediatric candidates advance through Phase III programs. Intravenous delivery dominates hospitalized severe cases, though intramuscular administration for prophylactic antibodies captures higher outpatient volumes and patient compliance advantages.
FDA, EMA, and WHO prequalification standards collectively shape pediatric RSV product development through distinct pediatric study requirements, immunobridging protocols, and post-marketing safety surveillance mandates. These frameworks demand infant-specific pharmacokinetic data and lengthy follow-up periods that extend development timelines but reduce liability exposure for manufacturers. Stakeholders must monitor regulatory divergence between FDA's accelerated approval pathways and EMA's conditional marketing authorization criteria, as submission strategy in one jurisdiction increasingly influences portfolio prioritization and partnership terms across both markets.
Market Dynamics
FDA Breakthrough Therapy designation is compressing clinical development timelines for pediatric RSV candidates while simultaneously raising capital barriers for developers lacking established pediatric infrastructure. This bifurcation concentrates pipeline advancement among manufacturers with existing neonatal trial networks and regulatory relationships.
Growth Catalysts
- Breakthrough Therapy Pathway:FDA's expedited review mechanism accelerates Phase III initiation for novel antiviral candidates, reducing time-to-market for preventive interventions targeting neonatal populations.
- Neonatal ICU Concentration:Tertiary pediatric hospitals with dedicated intensive care units drive adoption of monoclonal antibody prophylaxis through established protocols for high-risk infant management.
- Extended Half-Life Engineering:Fc-modified antibody platforms enable single-dose seasonal protection, improving compliance compared to monthly administration regimens.
Market Restraints
- Cold Chain Infrastructure:mRNA and live-attenuated vaccine candidates require ultra-low temperature distribution networks that remain underdeveloped in rural pediatric care settings.
- Immunobridging Requirements:EMA and FDA mandates for infant-specific pharmacokinetic data extend development timelines by 18-24 months despite adult safety clearance.
- Seasonal Demand Compression:Northern hemisphere winter concentration limits revenue recognition to four-month windows, straining manufacturing capacity planning.
Strategic Opportunities
- Southern Hemisphere Expansion:Australia and Brazil present underpenetrated markets with inverted seasonality that could smooth annual revenue recognition for preventive therapies.
- Maternal Immunization Positioning:Placental antibody transfer protocols offer protection coverage for infants born during non-peak transmission periods.
- Point-of-Care Diagnostic Integration:Rapid RSV antigen testing in pediatric emergency departments enables targeted prophylaxis deployment and reduces unnecessary treatment.
Industry Challenges
- Neonatal Trial Recruitment:Parental consent complexity and ethical review board variability across sites delays enrollment for infant safety studies.
- Post-Marketing Surveillance Scale:FDA mandates for extended follow-up of immunized infants require longitudinal registry infrastructure that smaller developers lack capital to build.
- Antigenic Drift Monitoring:RSV F protein conformational changes necessitate ongoing strain surveillance systems to maintain prophylaxis efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Respiratory Syncytial Virus Infection Market |
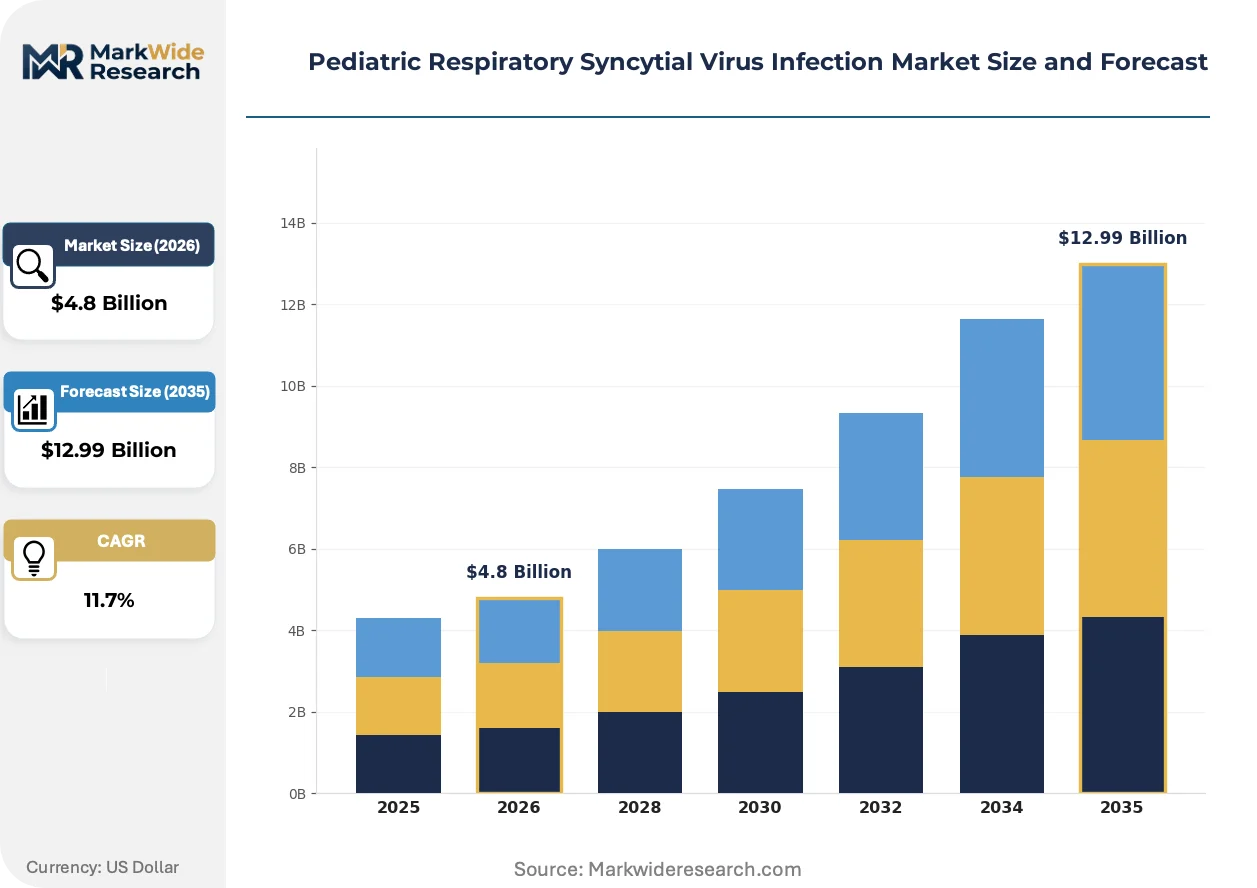
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Monoclonal Antibodies, Vaccines, Supportive Care End Use: Pediatric Hospitals, Outpatient Clinics, Research Laboratories, Home Care Delivery Mode: Inhalation, Intravenous, Oral, Intramuscular Therapy Area: Infectious Diseases, Pulmonary Disorders, Immunology, Critical Care |
| Companies Covered | AstraZeneca PLC, Sanofi S.A., Moderna, Inc., Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline, Johnson & Johnson, Bavarian Nordic, ReViral, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Respiratory Syncytial Virus Infection Market Evolving Landscape
Extended half-life monoclonal antibodies are restructuring preventive care delivery by collapsing dosing frequency from monthly to seasonal intervals. This shift is compressing the traditional service model built around repeated clinic visits.
Prefusion F protein stabilization technology is displacing postfusion-targeted interventions across pediatric prophylaxis development. Sanofi S.A. and AstraZeneca PLC have advanced candidates through Phase III using this conformational lock approach. The structural consequence is a narrowing competitive set focused on epitope-specific neutralization potency rather than breadth of serotype coverage.
EMA's conditional marketing authorization pathway is accelerating European access to maternal RSV vaccines ahead of full pediatric safety data completion. This regulatory flexibility allows post-natal efficacy follow-up while commercializing for pregnant populations. The mechanism most benefits manufacturers with existing European distribution for adult respiratory vaccines.
Hospital formulary committees are consolidating purchasing authority for preventive biologics under centralized pharmacy and therapeutics committees. Individual neonatology departments are losing autonomous procurement discretion. This concentration is most visible in United States children's hospital networks where GPO contracts now cover over 70% of monoclonal antibody volume.
Pediatric Respiratory Syncytial Virus Infection Market Segmentation
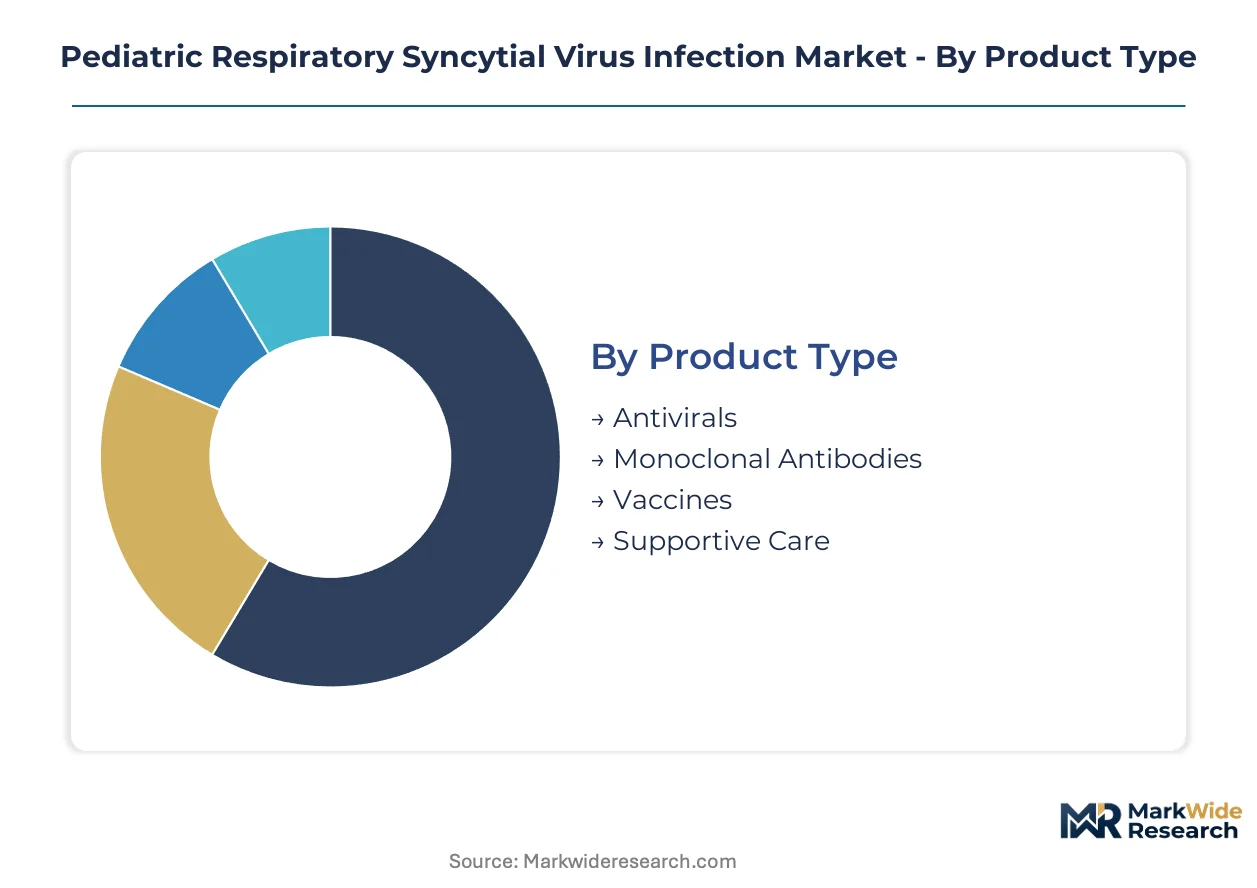
Segmentation in pediatric RSV therapeutics reveals divergent competitive moats across intervention modalities. Product-level substitution pressures intensify as extended half-life antibodies displace monthly prophylaxis regimens and mRNA platforms challenge conventional antigen approaches.
Product Type:
Substitution pressure concentrates most acutely in preventive modalities where Fc-engineered antibodies threaten legacy monthly dosing products and maternal vaccines compete for the same infant protection window.
- Monoclonal Antibodies:Fc-modified platforms with extended half-life enable single-dose seasonal coverage, collapsing clinic visit requirements. Demand concentrates in United States tertiary pediatric hospitals with established NICU prophylaxis protocols and favorable reimbursement for high-risk infant populations.
- Vaccines:Maternal immunization candidates leverage placental antibody transfer to protect infants through birth, while pediatric direct vaccination approaches target older at-risk children. EMA conditional marketing authorization pathways accelerate European access ahead of full infant safety data completion.
- Antivirals:Direct-acting small molecules target viral polymerase complexes for hospitalized severe cases, though narrow therapeutic windows limit outpatient utility.
- Supportive Care:Bronchodilators, supplemental oxygen, and hydration protocols remain foundational for disease management in resource-limited settings lacking biologic access.
Monoclonal antibodies retain volume leadership; vaccines hold the steepest expansion curve.
End Use:
Care setting segmentation tracks reimbursement sophistication and acute severity thresholds, with cost tier differentiation between intensive inpatient monitoring and decentralized outpatient administration.
- Pediatric Hospitals:Tertiary centers with dedicated NICUs anchor monoclonal antibody adoption through established high-risk infant management protocols and integrated pharmacy therapeutics committees controlling formulary decisions.
- Outpatient Clinics:Seasonal administration of extended half-life antibodies shifts volume toward community pediatric practices with cold chain capabilities and parental compliance advantages over hospital-based delivery.
- Home Care:Post-discharge monitoring and supportive therapy delivery expands in markets with developed pediatric home health infrastructure and remote patient monitoring reimbursement.
- Research Laboratories:Academic medical centers with longitudinal infant registries support FDA-mandated post-marketing surveillance requirements for novel preventive interventions.
Pediatric hospitals dominate current value capture; outpatient clinics are climbing the fastest.
Delivery Mode:
Route selection reflects the tension between bioavailability optimization and patient population constraints, with intramuscular formats gaining share through compliance engineering.
- Intramuscular:Extended half-life antibodies deploy via single seasonal injections, eliminating the compliance burden of monthly intravenous infusions and enabling community-based administration.
- Intravenous:Hospitalized severe cases requiring rapid therapeutic levels continue to rely on IV delivery, though this route concentrates in smaller acute populations with bronchiolitis or pneumonia progression.
- Inhalation:Nebulized antiviral candidates target localized pulmonary drug deposition, though infant cooperation limits practical utility in the core 2-8 month age group.
- Oral:Small molecule prophylaxis remains development-stage, with pharmacokinetic challenges in infant gastric pH environments and first-pass metabolism variability.
Intravenous maintains procedural familiarity; intramuscular posts the steepest volume trajectory.
Therapy Area:
Specialty alignment determines prescriber access and payer categorization, with infectious disease and pulmonary specialists controlling distinct patient entry points.
- Infectious Diseases:Pediatric infectious disease specialists drive protocol development for monoclonal antibody prophylaxis and antiviral stewardship in academic medical centers with established RSV surveillance programs.
- Pulmonary Disorders:Pediatric pulmonologists manage severe bronchiolitis sequelae and chronic lung disease comorbidities that qualify infants for priority preventive therapy under risk-stratified guidelines.
- Critical Care:Pediatric intensivists direct RSV-related respiratory failure management in tertiary NICUs and PICUs, influencing hospital formulary positioning for severe disease interventions.
- Immunology:Specialists in primary immunodeficiency and transplant populations address niche high-risk cohorts requiring customized prophylaxis protocols outside standard seasonal frameworks.
Infectious diseases anchors protocol authority; pulmonary disorders is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement infrastructure and regulatory acceleration pathways determine geographic prioritization for pediatric RSV prophylaxis developers. The United States anchors initial commercialization through favorable payer mechanics for high-risk infant populations, while European and Asia-Pacific markets follow distinct access timelines shaped by local health technology assessment frameworks.
United States
Seasonal disease burden concentrated in southern states drives NICU protocol standardization for monoclonal antibody administration. FDA Breakthrough Therapy designations compress review timelines for novel preventive candidates targeting neonatal populations. Texas and Florida pediatric hospital networks anchor volume concentration through established high-risk infant management pathways and integrated pharmacy therapeutics committees.
Germany
Academic medical centers with longitudinal infant registries support EMA-mandated post-marketing surveillance requirements for novel biologics. Federal Joint Committee health technology assessments evaluate maternal immunization cost-effectiveness against monoclonal antibody alternatives. Bavaria and North Rhine-Westphalia concentrate tertiary pediatric capacity where formulary committees consolidate purchasing authority for preventive therapies.
Japan
PMDA pediatric study requirements demand infant-specific pharmacokinetic bridging data that extends development timelines beyond FDA pathways. Seasonal RSV patterns concentrated in Okinawa and southern prefectures inform targeted prophylaxis deployment strategies. Tokyo and Osaka metropolitan pediatric hospitals drive adoption through established neonatal intensive care networks and specialist infectious disease protocols.
Australia
Inverted seasonality relative to northern hemisphere markets enables revenue smoothing for manufacturers with year-round manufacturing capacity. TGA streamlined approval pathways for maternal vaccines accelerate access ahead of full pediatric safety data completion. New South Wales and Victoria anchor demand through tertiary pediatric networks in Sydney and Melbourne with established RSV surveillance programs.
Brazil
ANVISA regulatory convergence with FDA standards facilitates parallel submission strategies for multinational developers targeting Latin American expansion. Seasonal transmission concentrated in southern states during winter months aligns with prophylaxis timing optimized for high-risk infant cohorts. São Paulo and Rio de Janeiro pediatric hospital networks concentrate specialist capacity and drive protocol adoption for preventive biologics.
Pediatric Respiratory Syncytial Virus Infection Market Competitive Landscape
Listed leaders compete with private specialists across platform technology and regulatory access dimensions. The market structure concentrates among manufacturers with established neonatal trial networks and existing pediatric vaccine infrastructure. Three archetypes dominate: large-cap pharmaceutical conglomerates with integrated development and distribution capabilities, mid-sized biotech specialists leveraging novel platform technologies, and emerging developers pursuing conditional marketing authorization pathways ahead of full safety data completion. Competitive positioning hinges on securing FDA Breakthrough Therapy designation and building longitudinal infant registry infrastructure for post-marketing surveillance compliance.
Within the large-cap integrated tier, AstraZeneca PLC and Sanofi S.A. occupy positions defined by established European and North American distribution networks for pediatric respiratory interventions. Pfizer Inc. anchors the maternal immunization positioning archetype, leveraging placental antibody transfer protocols to extend protective benefit coverage. Moderna, Inc. represents platform-flexibility specialists competing through rapid antigen redesign capabilities against evolving viral strains. These three entities exemplify distinct strategic vectors: geographic infrastructure depth, intervention timing innovation, and technological adaptability.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| Sanofi S.A. |
| Moderna, Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline |
| Johnson & Johnson |
| Bavarian Nordic |
| ReViral |
| Others |
Value Network & Pricing Analysis
Batch manufacturing scale at United States and European fill-finish facilities anchors cost structures for monoclonal antibody production, concentrating supply among manufacturers with dedicated pediatric biologics capacity and establishing price floors that reflect single-use system validation and cold chain compliance investments.
Pricing Analysis
Certification level creates the primary spread between FDA Breakthrough Therapy-designated products and standard biologics, with premium tiers capturing reimbursement advantages through pediatric-specific labeling. Three-tier pricing structure across premium, standard, and economy levels reflects risk-stratified patient eligibility protocols and formulary positioning. Pricing pressure stems from hospital pharmacy and therapeutics committee consolidation, with GPO contracts compressing margins on legacy monthly-dosing products. Community pediatric clinics exhibit highest price sensitivity due to cash-pay parental segments, while tertiary NICUs demonstrate lowest sensitivity given bundled reimbursement for high-risk infant management.
Supply Chain Analysis
Ultra-low temperature storage capacity at United States, German, and Japanese distribution hubs constrains mRNA vaccine candidate deployment, creating chokepoints for seasonal surge capacity. Active pharmaceutical ingredient production draws from Swiss and Irish contract manufacturing organizations, while Fc-modified antibody engineering rests on Singaporean and South Korean biologics platforms. Single-source vulnerability concentrates in specialized neonatal syringe and needle safety device suppliers. Distribution runs through hospital-centric specialty pharmacy networks with direct-to-NICU cold chain logistics, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Breakthrough Therapy designation acceleration represents the decisive regulatory inflection, compressing development timelines and bifurcating capital access between established pediatric infrastructure holders and capital-constrained developers.
For Market Incumbents: Shield market position by deepening backward integration into Fc-engineering platform technology and securing exclusive formulary contracts with United States children's hospital networks before maternal vaccine candidates achieve full pediatric labeling. Prioritize longitudinal infant registry infrastructure investments to satisfy FDA post-marketing surveillance mandates that smaller competitors cannot fund. Channel control through integrated pharmacy therapeutics committee relationships represents the critical defensive lever against emerging mRNA platform entrants. For New Entrants and Emerging Players: Post-marketing surveillance service gaps in rural pediatric settings present immediate white-space opportunity, with remote patient monitoring and home health nursing bundles offering differentiated positioning against hospital-centric incumbents. Southern hemisphere markets with inverted seasonality—specifically Australian and Brazilian tertiary pediatric networks—offer most penetrable geographic entry points with less consolidated purchasing authority. Targeted go-to-market deployment through pediatric infectious disease specialist protocols enables clinical credibility establishment ahead of formulary committee engagement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with extended half-life antibody platforms and established FDA Breakthrough Therapy designations, positioning these archetypes for durable cash flow quality across the analysis window. Acquisition targets should display conditional marketing authorization progress through EMA pathways and existing European distribution partnerships for adult respiratory vaccines. Antigenic drift surveillance system investments signal management sophistication and platform adaptability against evolving RSV strains.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA expedited review compresses Phase III initiation timelines for neonatal prophylaxis candidates. |
| Extended Half-Life Platform Engineering | Fc-modification technology collapses dosing frequency from monthly to single seasonal administration. |
| Maternal Immunization Protocol Development | Placental antibody transfer positioning extends protective coverage to infants born outside peak transmission windows. |
| Post-Marketing Surveillance Infrastructure | Longitudinal infant registries satisfy FDA mandates for immunized cohort follow-up and reduce liability exposure. |
| Southern Hemisphere Market Entry | Australian and Brazilian inverted seasonality enables revenue smoothing across year-round manufacturing cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric infectious disease specialists, neonatal intensive care unit directors, hospital pharmacy and therapeutics committee members, and biologics manufacturing executives. Secondary validation drew from FDA Breakthrough Therapy designation filings, EMA conditional marketing authorization submissions, ClinicalTrials.gov pediatric RSV trial records, and hospital GPO contract databases. Bottom-up patient population modeling and top-down revenue triangulation were cross-referenced across manufacturer disclosures and payer reimbursement schedules.
Across the analysis window, the forecasting framework modeled patient volume by risk stratification tier, product type segmentation across monoclonal antibodies and vaccines, administration route preference evolution, and regional regulatory cluster adoption curves. CAGRs were derived from segmented volume projections and price trajectory assumptions anchored to reimbursement filing data. Infant-specific pharmacokinetic bridging study timelines and seasonal demand compression factors were incorporated as industry-specific adjustment inputs.
Forecasts assume regulatory continuity in FDA Breakthrough Therapy pathways and EMA conditional marketing authorization criteria; material policy shifts in pediatric study requirements or post-marketing surveillance mandates would require re-modeling. Antigenic drift surveillance system adequacy and maternal vaccine safety signal emergence represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as RSV strain evolution and reimbursement policy adjustments unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market