

Respiratory Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Biologics Market Insights
ISO 13485 certification for medical device quality management is collapsing as a baseline gate for respiratory biologics manufacturers seeking inhaler-delivery partnerships. AstraZeneca leverages its integrated inhaled-delivery platform to sustain competitive positioning across monoclonal antibody portfolios. GSK anchors European manufacturing capacity for nebulized biologic formulations. Regeneron Pharmaceuticals differentiates through cytokine-targeting R&D intensity in severe asthma indications.
Respiratory biologics comprise engineered protein therapeutics—monoclonal antibodies, cytokine inhibitors, and fusion proteins—manufactured via mammalian cell culture with purity thresholds exceeding 99% and endotoxin limits below 0.25 EU/mL, designed to modulate immune-mediated airway inflammation. Monoclonal antibodies occupy the dominant margin pool due to established reimbursement for severe asthma and COPD biologics. Dry powder inhaler delivery technology is gaining fastest traction as pharmaceutical firms seek patient-administered alternatives to clinic-based injections. Cystic fibrosis indication demand concentrates within specialty clinics equipped for complex biologic handling protocols.
FDA accelerated approval pathways and EMA adaptive licensing frameworks shape product entry timelines, while the EU MDR intensifies post-market surveillance requirements for combination biologic-device products. The EPA regulates propellant chemistry in metered-dose inhalers, forcing reformulation investments that alter cost structures for delivery-technology partnerships. Stakeholders must monitor evolving interchangeability standards for biosimilar respiratory biologics and their impact on payer contracting dynamics.
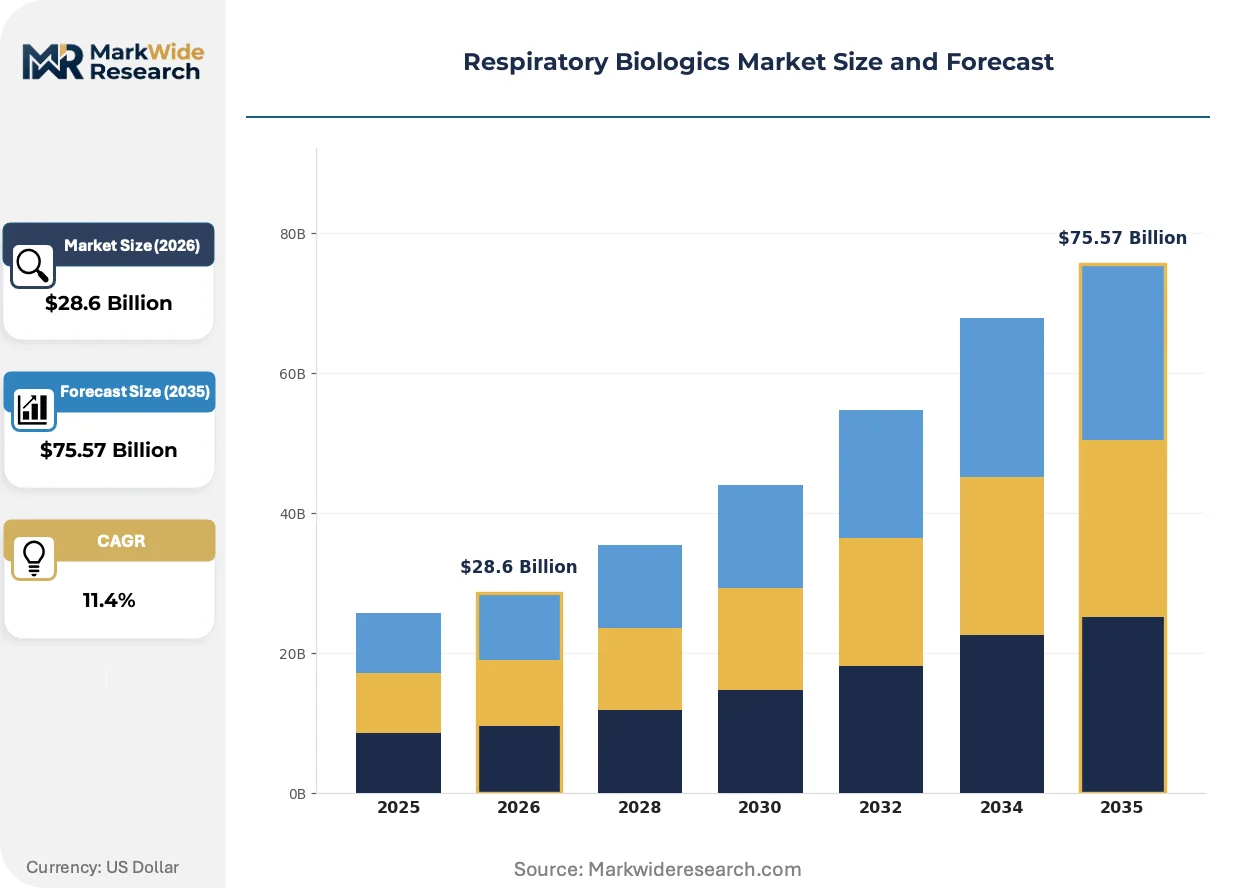
Market Dynamics
Hospital formulary expansion for biologic asthma therapies is compressing purchasing cycles and concentrating procurement authority within integrated delivery networks, fundamentally restructuring how respiratory biologics reach patients.
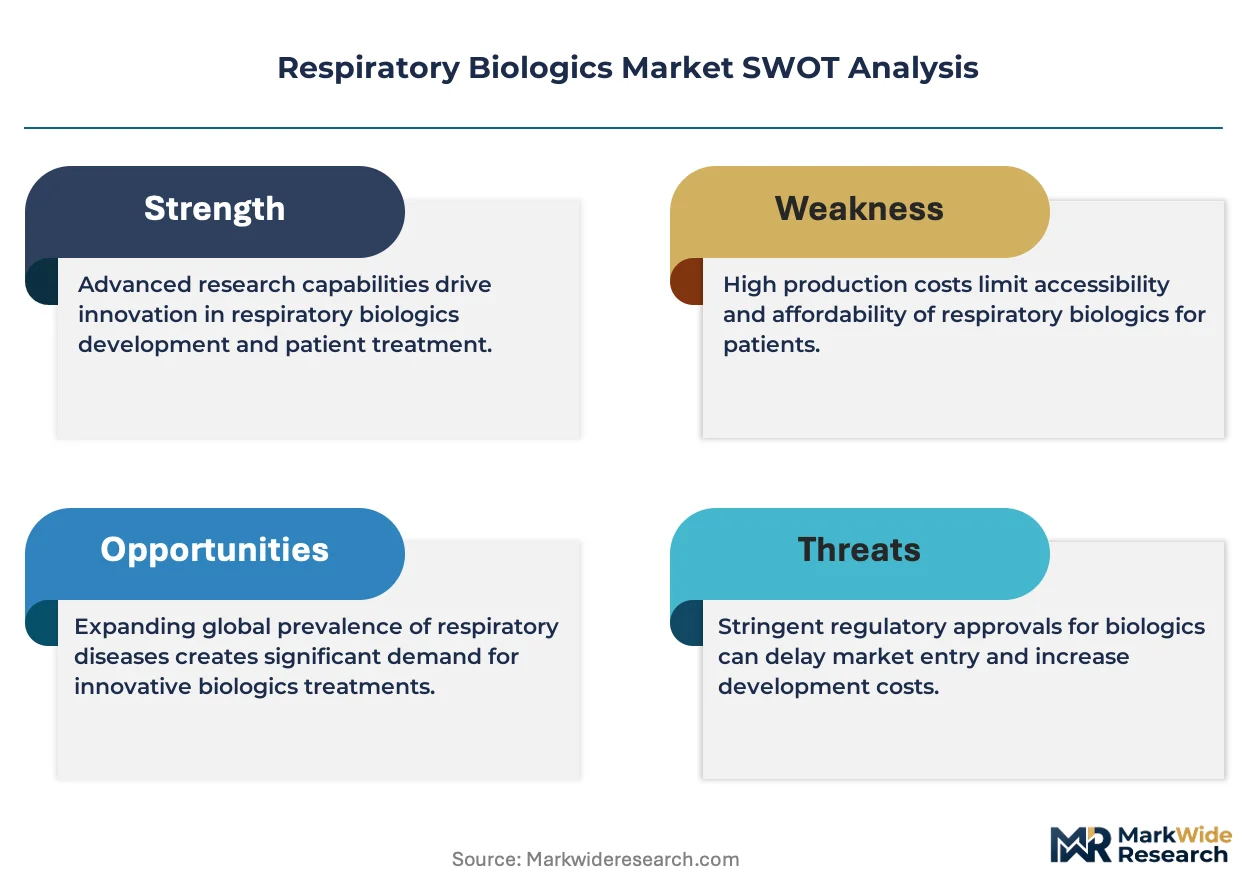
Growth Catalysts
- FDA accelerated approval pathways:Breakthrough therapy designation compresses development timelines for severe asthma biologics, enabling faster patient access.
- Specialty clinic networks:Concentrated purchasing power within United States integrated delivery systems drives volume commitments for nebulized formulations.
- Dry powder inhaler technology:Patient-administered alternatives to clinic-based injections expand addressable populations beyond severe disease segments.
Market Restraints
- Mammalian cell culture input costs:Purity thresholds exceeding 99% and endotoxin limits below 0.25 EU/mL require expensive downstream processing infrastructure.
- European manufacturing concentration:Nebulized biologic formulation capacity clusters in select facilities, creating single-source vulnerability for EU supply.
- EPA propellant chemistry mandates:Forced reformulation investments for metered-dose inhalers alter cost structures for delivery-technology partnerships.
Strategic Opportunities
- Cystic fibrosis specialty clinics:Complex biologic handling protocols create defensible positions for manufacturers with cold-chain expertise.
- Biosimilar interchangeability standards:Evolving FDA guidance on respiratory biologic substitution opens payer contracting flexibility.
- EU MDR adaptive licensing:Post-market surveillance requirements for combination biologic-device products reward early regulatory investment.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management standards for inhaler-delivery partnerships extend partnership negotiation cycles.
- Cytokine-targeting R&D talent scarcity:Severe asthma indication expertise concentrates within limited specialist pools, inflating compensation costs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Biologics Market Trends and Innovations
Delivery technology diversification and regulatory pathway innovation are restructuring competitive entry points, while procurement authority consolidation is reshaping commercial access strategies across patient segments.
Smart nebulizer connectivity is fragmenting the traditional clinic-injection model for severe asthma biologics. Home-based specialty pharmacies are adopting Bluetooth-enabled adherence monitoring within six months of product launch. This technology is fragmenting the historical concentration of biologic administration within hospital infusion centers, compressing site-of-care economics.
EMA adaptive licensing frameworks are accelerating conditional approvals for breakthrough respiratory biologics before full Phase III completion. Manufacturers gain earlier revenue recognition while committing to real-world evidence generation. Severe asthma monoclonal antibodies face the steepest compliance curves as post-authorization study obligations expand.
Integrated delivery networks now mandate outcomes guarantees for biologic asthma therapies exceeding specific exacerbation-reduction thresholds. Traditional fee-for-service reimbursement contracts are yielding to risk-sharing arrangements with specialty pharmacy benefit managers. This behavioral shift is most pronounced in United States markets where Medicare Advantage penetration exceeds forty percent in metropolitan clusters.
Respiratory Biologics Market Segmentation
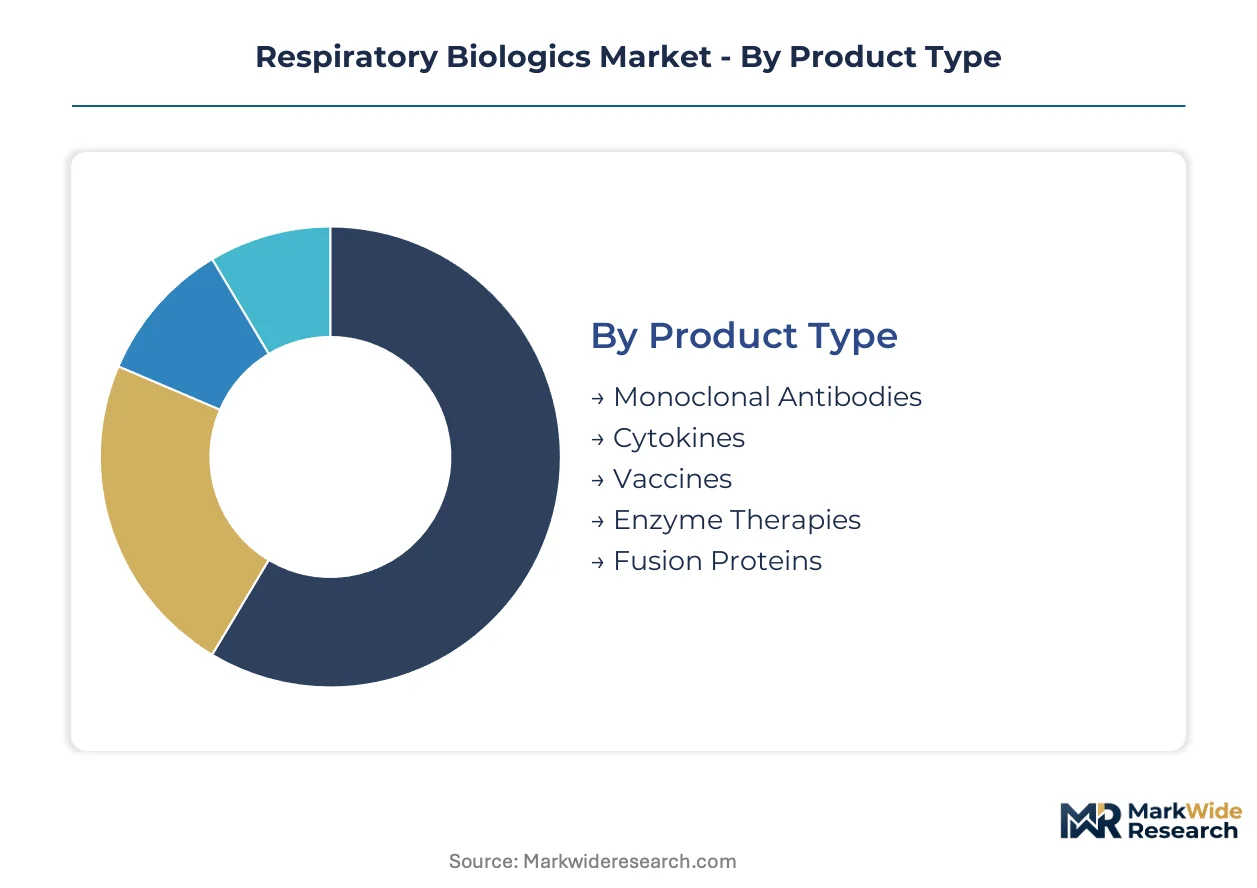
Respiratory biologics segmentation reflects divergent regulatory pathways, manufacturing complexity, and site-of-care economics. Each dimension carries distinct FDA, EMA, and EPA compliance burdens that reshape competitive entry costs and partnership structures across patient populations.
Product Type:
FDA breakthrough therapy designation and EMA adaptive licensing create divergent approval timelines across molecular classes, compressing development cycles for some while extending surveillance obligations for others.
- Monoclonal Antibodies:Engineered immunoglobulins targeting IL-4, IL-5, and IL-13 pathways with established reimbursement for severe eosinophilic asthma. United States integrated delivery networks concentrate purchasing for clinic-administered formulations, while European nebulized capacity clusters in select GSK manufacturing facilities.
- Cytokines:Recombinant signaling proteins modulating Th2 and Th17 inflammatory cascades. Severe asthma indication demand within United States specialty clinic networks drives concentrated procurement authority, though mammalian cell culture purity thresholds above 99% inflate downstream processing infrastructure costs.
- Vaccines:Immunogenic biologics inducing adaptive immunity against respiratory pathogens. FDA accelerated approval pathways compress Phase III timelines for breakthrough candidates targeting COPD exacerbation prevention.
- Enzyme Therapies:Recombinant hydrolases addressing mucus clearance dysfunction in cystic fibrosis. Complex biologic handling protocols within specialty clinics create defensible positions for manufacturers with validated cold-chain logistics.
- Fusion Proteins:Engineered constructs combining receptor domains with antibody Fc regions for extended half-life. EMA post-authorization study obligations expand compliance curves for novel Fc-fusion candidates entering European markets.
Established volume favors monoclonal antibodies; emerging adoption favors cytokine-targeting constructs with expanded indication potential.
Indication:
Cost tier differentiation separates severe disease segments with biologic reimbursement from maintenance populations where small-molecule generics dominate prescribing.
- Asthma:Severe eosinophilic and allergic phenotypes drive biologic eligibility criteria tied to exacerbation frequency and biomarker thresholds. United States Medicare Advantage penetration above forty percent in metropolitan clusters mandates outcomes guarantees from integrated delivery networks.
- Chronic Obstructive Pulmonary Disease:Alpha-1 antitrypsin deficiency and frequent exacerbator phenotypes qualify for biologic intervention. European manufacturing concentration for nebulized formulations creates single-source supply vulnerability across EU markets.
- Cystic Fibrosis:CFTR modulator-resistant genotypes and mucus dysfunction drive enzyme therapy and biologic demand. Specialty clinic networks in the United States require validated cold-chain protocols for complex protein handling.
- Pulmonary Fibrosis:Progressive fibrotic interstitial lung diseases with emerging biologic targets in TGF-beta and integrin pathways. FDA accelerated approval pathways enable conditional entry before full Phase III completion.
- Allergic Rhinitis:Moderate-to-severe allergic phenotypes with biologic eligibility expanding beyond antihistamine failures. Dry powder inhaler technology gains traction as patient-administered alternatives fragment clinic-injection models.
Reimbursement concentration favors asthma; pipeline velocity favors pulmonary fibrosis with adaptive licensing traction.
End User:
Procurement authority is shifting toward integrated delivery networks and specialty pharmacy benefit managers, restructuring site-of-care economics across administration settings.
- Hospitals:Inpatient and infusion center administration of intravenous biologics with formulary committees controlling access. United States hospital systems are expanding biologic asthma therapy access while compressing purchasing cycles.
- Specialty Clinics:Outpatient pulmonology and allergy practices with biomarker testing and biologic prescribing authority. Bluetooth-enabled adherence monitoring adoption within six months of product launch fragments historical infusion center concentration.
- Diagnostic Laboratories:Companion diagnostic testing for eosinophil counts, IgE levels, and FeNO measurements determining biologic eligibility. EPA propellant chemistry mandates force reformulation investments altering metered-dose inhaler cost structures.
- Biotechnology Firms:Contract development and manufacturing organizations producing clinical and commercial biologic supply. ISO 13485 certification for inhaler-delivery partnerships extends negotiation timelines with device manufacturers.
- Research Institutes:Academic medical centers conducting Phase I-III trials and real-world evidence generation for post-authorization commitments. EMA adaptive licensing frameworks reward early regulatory investment with conditional approval pathways.
Volume authority favors hospitals; margin expansion favors specialty clinics with risk-sharing arrangements.
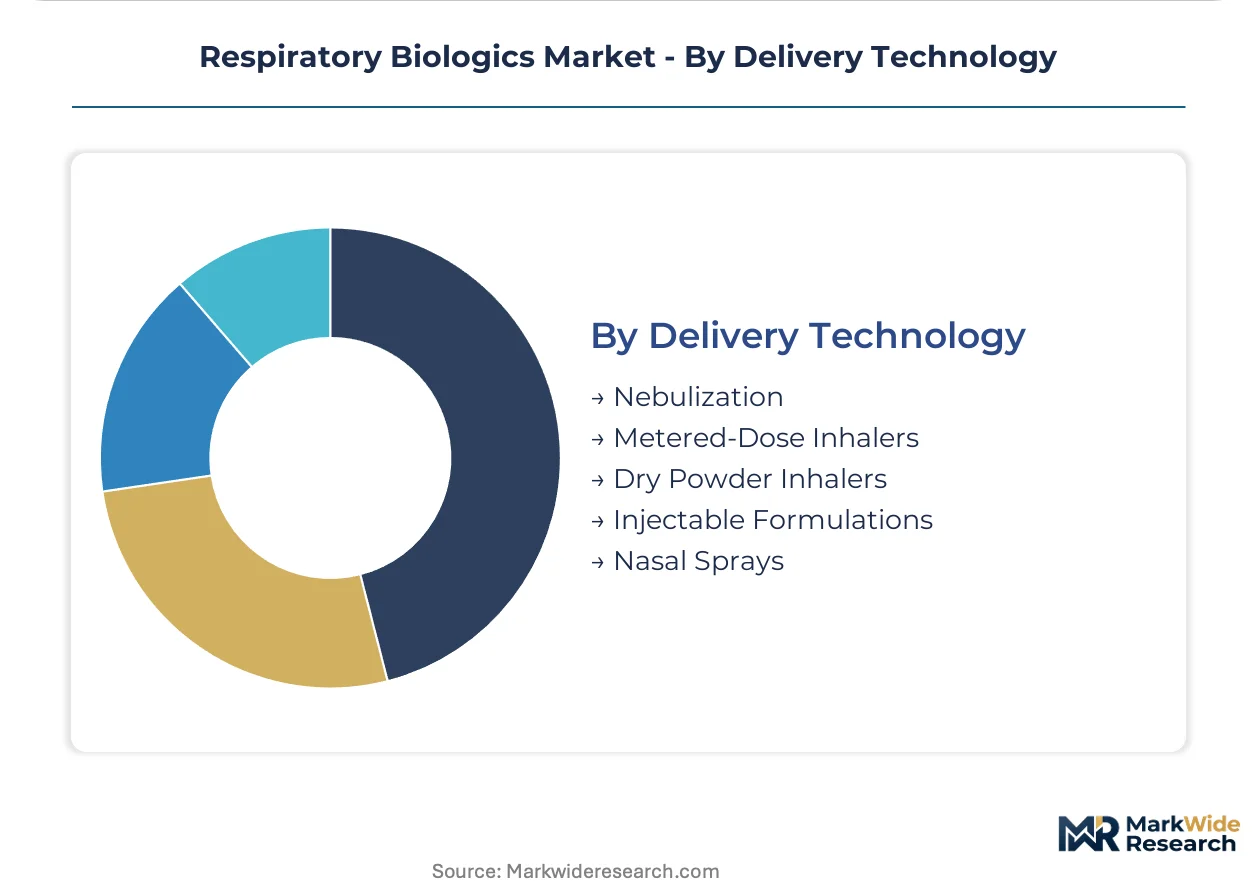
Delivery Technology:
Technology maturity separates clinic-dependent administration from patient-administered alternatives, with EPA and EMA regulations differentially impacting propellant chemistry and device combination products.
- Nebulization:Aerosol generation via compressed air or vibrating mesh for high-viscosity biologic solutions. European manufacturing capacity concentrates in select facilities, creating supply vulnerability for EU markets dependent on nebulized monoclonal antibodies.
- Metered-Dose Inhalers:Pressurized propellant systems delivering precise doses with coordination requirements. EPA mandates on hydrofluoroalkane propellant chemistry force reformulation investments that alter partnership economics with device manufacturers.
- Dry Powder Inhalers:Breath-actuated systems eliminating propellant dependence and enabling patient self-administration. United States specialty pharmacy networks are adopting Bluetooth-enabled adherence monitoring to track real-world usage patterns.
- Injectable Formulations:Subcutaneous and intravenous delivery of monoclonal antibodies and fusion proteins with established cold-chain requirements. FDA interchangeability standards for biosimilar respiratory biologics open payer contracting flexibility for substitutable products.
- Nasal Sprays:Mucosal delivery systems for local and systemic biologic absorption in allergic rhinitis. EU MDR intensifies post-market surveillance requirements for combination biologic-device products entering European markets.
Clinical dependency favors injectable formulations; patient autonomy favors dry powder inhalers with connected device integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital formulary committees in the United States concentrate procurement authority for biologic asthma therapies, while European manufacturing clusters for nebulized formulations face single-source vulnerability. Japanese specialty clinic networks adopt Bluetooth-enabled adherence monitoring fastest. German integrated delivery systems mandate outcomes-based contracts.
United States
Medicare Advantage penetration above forty percent in metropolitan clusters drives concentrated purchasing power within integrated delivery networks. FDA breakthrough therapy designation compresses development timelines for severe asthma biologics. Boston and San Francisco specialty clinic networks expand formulary access while compressing purchasing cycles for nebulized formulations.
Germany
EMA adaptive licensing frameworks accelerate conditional approvals for respiratory biologics before full Phase III completion. EU MDR intensifies post-market surveillance requirements for combination biologic-device products. Bavaria and North Rhine-Westphalia anchor European manufacturing capacity for monoclonal antibody formulations with established cold-chain infrastructure.
Japan
PMDA accelerated approval pathways enable faster patient access for cytokine-targeting biologics in severe asthma. METI standards for smart medical device connectivity shape nebulizer technology adoption. Tokyo and Osaka specialty clinic networks fragment historical infusion center concentration through home-based specialty pharmacy expansion.
United Kingdom
NHS Integrated Care Systems consolidate procurement authority for biologic asthma therapies across regional hospital networks. MHRA recognition of FDA approvals streamlines entry timelines for breakthrough respiratory biologics. London and Greater Manchester specialty pharmacy benefit managers adopt risk-sharing arrangements with outcomes guarantees.
Switzerland
Swissmedic adaptive licensing frameworks reward early regulatory investment with conditional approval pathways for pulmonary fibrosis biologics. ISO 13485 certification requirements for inhaler-delivery partnerships extend negotiation timelines with device manufacturers. Basel and Zurich biotechnology clusters concentrate contract development and manufacturing capacity for clinical supply.
Respiratory Biologics Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with mammalian cell culture infrastructure and established biologic portfolios. Market structure concentrates around manufacturers possessing validated cold-chain logistics and inhaled-delivery platform expertise. Two strategic archetypes dominate: vertically integrated biopharmaceuticals with device partnerships, and specialty biotechnology firms with cytokine-targeting R&D intensity. Competitive moves center on delivery technology licensing agreements and European manufacturing capacity expansion for nebulized formulations.
Within the integrated biopharmaceutical tier, AstraZeneca and GSK exemplify archetypes leveraging platform-scale manufacturing and regional production clustering. Regeneron Pharmaceuticals occupies a position among R&D-intensive specialists targeting severe asthma indications through cytokine pathway modulation. These three anchors represent divergent strategic postures: platform breadth versus targeted therapeutic depth, with each archetype commanding distinct partnership leverage in inhaler-delivery negotiations.
| Leading Market Players |
|---|
| Sanofi |
| AstraZeneca |
| GSK |
| Novartis |
| Roche |
| Amgen |
| Regeneron Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
Mammalian cell culture capacity utilization above 85 percent in Bavaria and North Rhine-Westphalia manufacturing clusters concentrates supply-side leverage among GSK and Roche production networks, simultaneously establishing price floors for nebulized monoclonal antibodies and compressing margin headroom for second-tier entrants lacking comparable scale economies.
Pricing Analysis
Cost-plus contracts with mammalian cell culture input indexation dominate procurement between biologics manufacturers and integrated delivery networks, with price differentiation resting on ISO 13485 certification tier and cold-chain validation depth. Three-tier pricing structure across premium, standard, and economy levels separates originator monoclonal antibodies from biosimilar candidates and compounded alternatives. Pricing pressure stems from EPA-mandated hydrofluoroalkane reformulation investments altering metered-dose inhaler partnership economics. United States specialty clinic networks exhibit highest price sensitivity due to Medicare Advantage outcomes guarantee requirements, while cystic fibrosis specialty clinics demonstrate lowest sensitivity given complex handling protocol lock-in.
Supply Chain Analysis
Inventory lead times for nebulized biologic formulations extend 18-24 weeks due to European manufacturing concentration in Germany, Switzerland, and Ireland facilities with validated aseptic filling lines. Raw material dependencies center on Chinese-sourced recombinant protein media, German-engineered vibrating mesh nebulizer components, and United States-origin hydrofluoroalkane propellants. Single-source vulnerability pervades EU nebulized capacity following GSK's consolidation of monoclonal antibody formulation networks. Distribution runs through integrated delivery network central pharmacies and home-based specialty pharmacies with Bluetooth-enabled adherence monitoring capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against small-molecule JAK inhibitors and oral biologic formulations threatening clinic-injection models for severe asthma indications.
For Market Incumbents: Shield formulary position through backward integration into dry powder inhaler device manufacturing, eliminating ISO 13485 partnership negotiation delays that extend AstraZeneca's commercialization timelines. Secure cytokine-targeting R&D talent pools in Boston and San Francisco through long-term employment guarantees, addressing specialist scarcity inflating compensation costs. Prioritize European nebulized capacity redundancy to mitigate single-source vulnerability exposure. For New Entrants and Emerging Players: Anchor in cystic fibrosis specialty clinic networks where complex biologic handling protocols create defensible positions against established monoclonal antibody portfolios. Target pulmonary fibrosis indications with EMA adaptive licensing traction, where conditional approval pathways compress capital requirements before full Phase III completion. Pursue licensing agreements with Bluetooth-enabled adherence monitoring platform developers to fragment historical infusion center concentration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated biopharmaceuticals with captive mammalian cell culture infrastructure and established inhaler-delivery partnerships, suggesting superior cash-flow quality versus R&D-intensive specialists. Long-term viability across the 5-10 year window favors manufacturers with validated cold-chain logistics and nebulized formulation expertise. Watch FDA interchangeability guidance finalization as the critical inflection signal for biosimilar substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Adaptive Licensing Pathway | Accelerates conditional approval for pulmonary fibrosis biologics before full Phase III completion. |
| Dry Powder Inhaler Platform Development | Enables patient-administered alternatives fragmenting clinic-injection models for severe asthma. |
| European Manufacturing Scale-Up | Addresses single-source vulnerability in nebulized monoclonal antibody formulation capacity. |
| Bluetooth-Enabled Adherence Monitoring | Compresses site-of-care economics through home-based specialty pharmacy expansion. |
| Cytokine-Targeting R&D Intensification | Differentiates severe asthma portfolios through IL-4, IL-5, and IL-13 pathway modulation. |
Research Methodology
Cross-validation between primary interviews with formulary directors, regulatory affairs leads, payer access specialists, and hospital procurement managers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases anchors the qualitative findings. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation reconcile volume estimates across the analysis window.
Sensitivity analysis across treatment line, dosage form, administration route, and regional regulatory cluster segmentation dimensions shapes the analytical framework over the projection horizon. CAGRs derive from patient population growth, biologic penetration rate assumptions, and pricing trajectory modeling for originator and biosimilar portfolios. Forecast inputs incorporate Medicare Advantage penetration thresholds and EPA propellant chemistry compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA breakthrough therapy designation velocity and stable mammalian cell culture input costs; material deviation would warrant model refresh. Revision becomes warranted when biosimilar interchangeability standards or EPA hydrofluoroalkane phase-out schedules cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.