
 Asia Pacific Tourism Vehicle Rental Market | 2026-2036
Asia Pacific Tourism Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Tourism Vehicle Rental Market Outlook
Subscription-based fleet access is hardening into the core revenue model across the Asia Pacific tourism vehicle rental sector. Beijing China Auto Rental leverages captive partnerships with domestic hotel chains and airports to sustain utilization rates above regional averages. Zoomcar India Pvt. Ltd. anchors its position through technology leadership in peer-to-peer fleet aggregation, while Avis Budget Group competes on brand recognition among inbound corporate travelers.
Asia Pacific tourism vehicle rental encompasses the short-term provision of passenger vehicles to travelers for leisure or business purposes, typically featuring daily or weekly pricing, insurance bundling, and optional navigation or connectivity add-ons. The fleet composition spans internal combustion, hybrid, and increasingly battery-electric powertrains sized between compact and full-size SUV categories to accommodate diverse terrain and group requirements. SUV and minivan categories command the widest margin pools due to their suitability for multi-generational family travel across Australia's outback routes and Southeast Asian island circuits. Mobile app booking channels represent the fastest-growing access point, displacing walk-in transactions as platform integration with airline and hospitality ecosystems deepens.
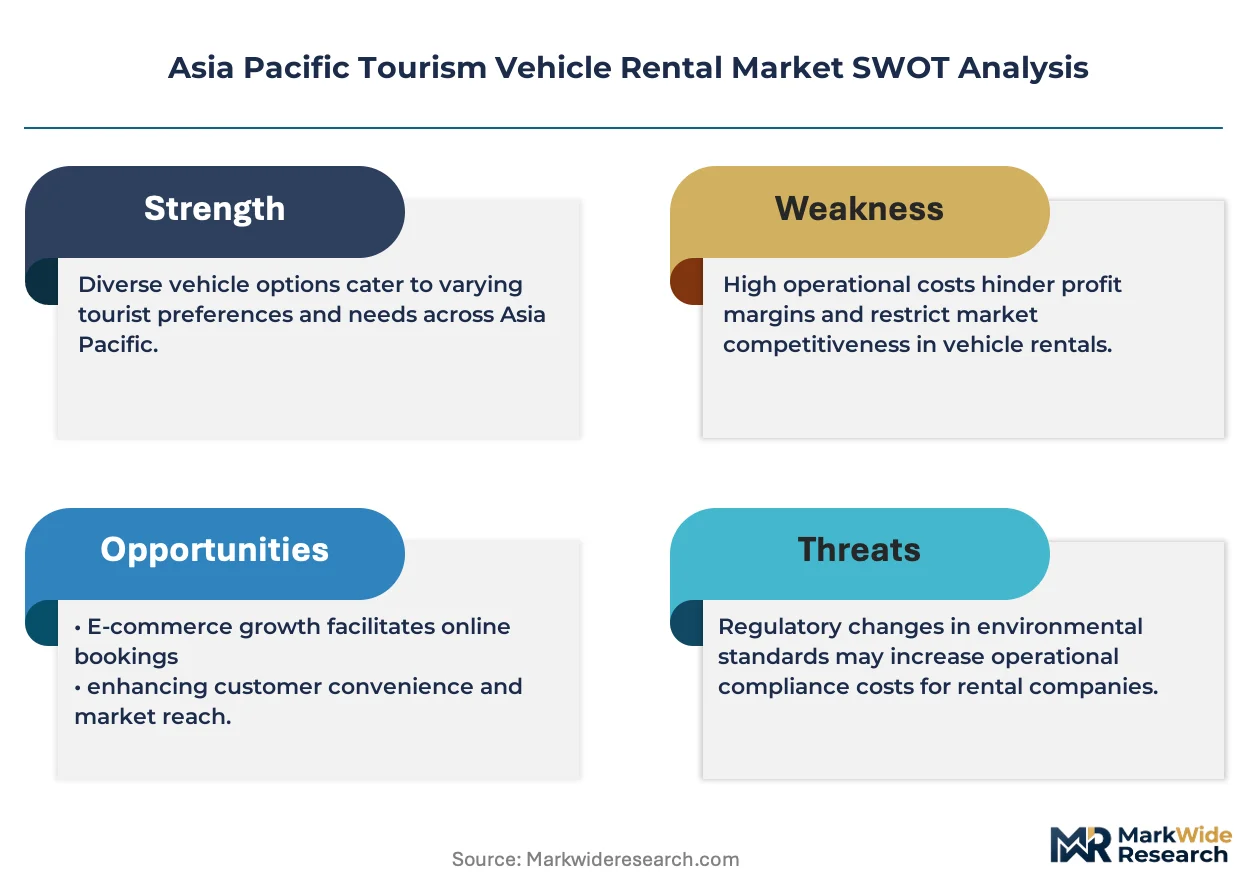
China's SAMR enforces national standards for vehicle safety and emissions that directly determine which models enter rental fleets, while India's BIS certification requirements shape equipment specifications for vehicles operating in Himalayan and coastal tourism zones. Thailand's Department of Land Transport imposes commercial registration protocols that influence fleet turnover rates and investment recovery timelines for rental operators. Stakeholders must monitor how fragmented national compliance regimes affect cross-border fleet redeployment strategies as regional tourism corridors mature.
Market Dynamics
China's dual carbon goals and India's PLI scheme for automotive manufacturing are forcing rental operators to accelerate fleet electrification timelines while renegotiating supplier contracts and residual value assumptions.
Growth Catalysts
- Leisure Tourist Preference Shift:Post-pandemic travelers across Thailand's resort corridors and Australia's outback routes prioritize independent exploration over packaged tours, expanding addressable demand for flexible vehicle access.
- MIIT New Energy Vehicle Mandates:China's Ministry of Industry and Information Technology production quotas push domestic OEMs to prioritize EV output, expanding rental-grade electric model availability at competitive lease rates.
- Airport-Hotel Ecosystem Integration:Beijing Capital International Airport and Bangkok Suvarnabhumi Airport have installed dedicated rental processing infrastructure, reducing customer friction and extending booking windows.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Raw material price swings for cobalt and nickel compress margins on electric fleet commitments, forcing operators to shorten lease terms or demand manufacturer buyback guarantees.
- Semiconductor Supply Concentration:Taiwan-based foundries dominate automotive chip fabrication, creating vulnerability for fleet management system upgrades and connected vehicle feature rollouts across the region.
- Thailand Commercial Registration Protocols:The Department of Land Transport imposes extended inspection cycles and documentation burdens that lengthen vehicle deployment timelines and tie up working capital.
Strategic Opportunities
- Vietnam Central Coast Tourism Corridor:Da Nang to Hue infrastructure investments create virgin territory for premium SUV and minivan rental services targeting multi-generational family segments.
- BIS Certification Streamlining:India's Bureau of Indian Standards is piloting unified equipment specifications for Himalayan and coastal tourism zones, reducing compliance duplication for cross-terrain operators.
- Telematics-Insurance Convergence:Real-time driving behavior data enables usage-based coverage products that lower premiums for safe renters and unlock new revenue streams for platform operators.
Industry Challenges
- EV Technician Skill Scarcity:High-voltage system certification programs remain underdeveloped across Indonesia and Philippines, constraining maintenance network expansion and roadside assistance reliability.
- Legacy Reservation System Integration:Established operators struggle to graft mobile-first booking architectures onto mainframe-dependent inventory platforms without disrupting real-time availability accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Tourism Vehicle Rental Market |
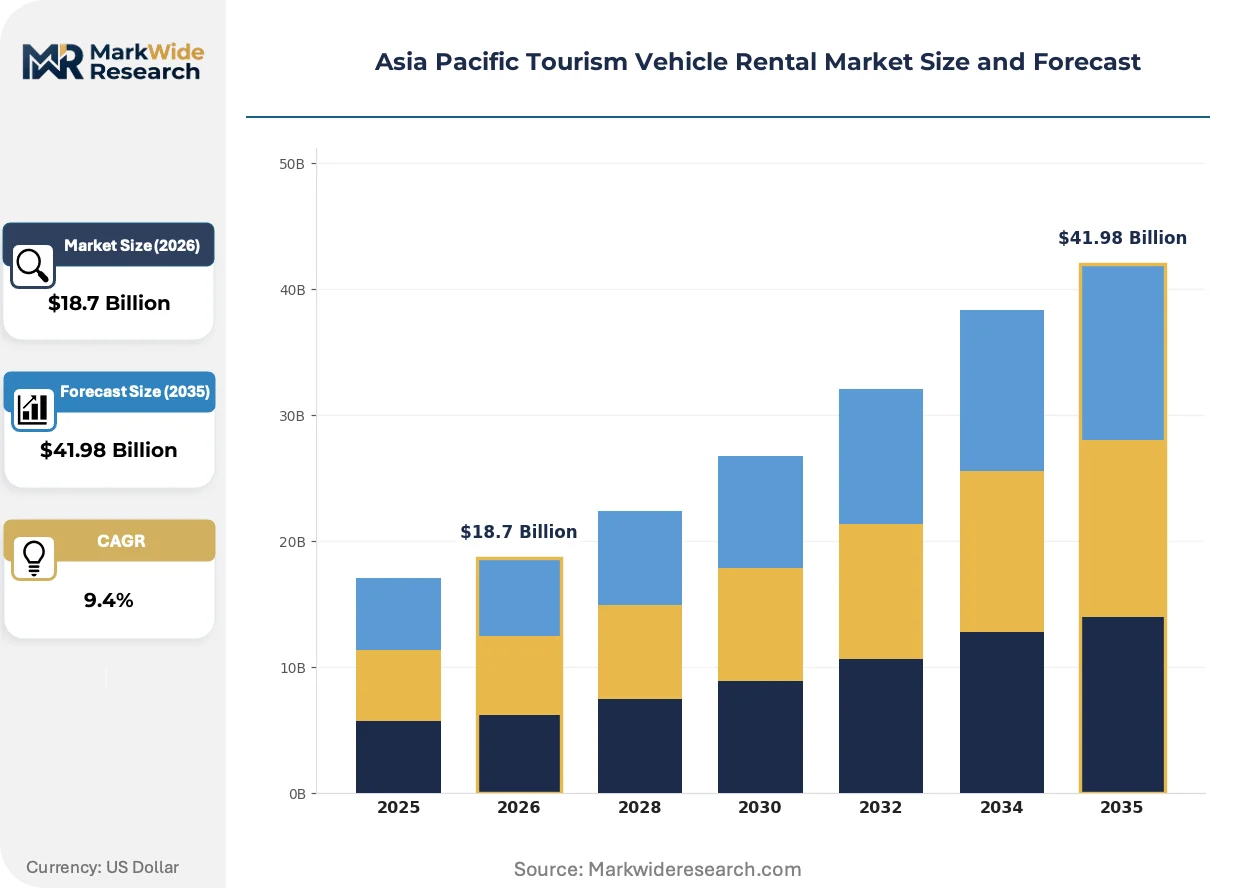
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Minivan, Convertible Rental Duration: Short-Term, Long-Term, Weekly, Monthly Customer Type: Business Travelers, Leisure Tourists, Families, Backpackers Booking Channel: Online Platforms, Travel Agencies, Walk-In, Mobile Apps |
| Companies Covered | eHi Car Service Limited, Zoomcar India Pvt. Ltd., Hertz Corporation, Beijing China Auto Rental (CAR Inc.), Avis Budget Group, Sixt SE, Carzonrent India Pvt. Ltd., Shouqi Car Rental, Drivezy, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Tourism Vehicle Rental Market Strategic Shifts
Digital platform architecture is compressing the traditional rental value chain, eliminating intermediaries while embedding vehicles directly into travel booking ecosystems. Three developments dominate strategic planning.
Connected fleet telematics is rewriting how operators manage asset utilization and customer risk profiles. Real-time location, diagnostic, and behavioral data streams enable dynamic pricing algorithms that adjust rates by traffic patterns and weather conditions. Premium leisure segments in Australia's Gold Coast and Japan's Hokkaido ski regions are adopting these capabilities fastest, accepting location tracking in exchange for guaranteed vehicle class availability and expedited checkout.
China's SAMR national standards for vehicle safety and emissions are tightening allowable fleet composition faster than replacement cycles permit. The State Administration for Market Regulation now mandates specific crash-test protocols and particulate limits that disqualify older internal combustion models from commercial registration. Coastal province operators in Guangdong and Zhejiang are responding by accelerating partnerships with domestic EV manufacturers offering guaranteed residual value programs.
Subscription-based access models are displacing traditional daily-rate structures among corporate travel managers and extended-stay leisure segments. Flat-fee monthly packages with bundled insurance and maintenance appeal to digital nomads and project-based consultants operating across multiple Asia Pacific cities. Singapore and Sydney show the highest penetration of these arrangements, where parking scarcity and congestion charges make vehicle ownership economically irrational for intermittent users.
Asia Pacific Tourism Vehicle Rental Market Segmentation
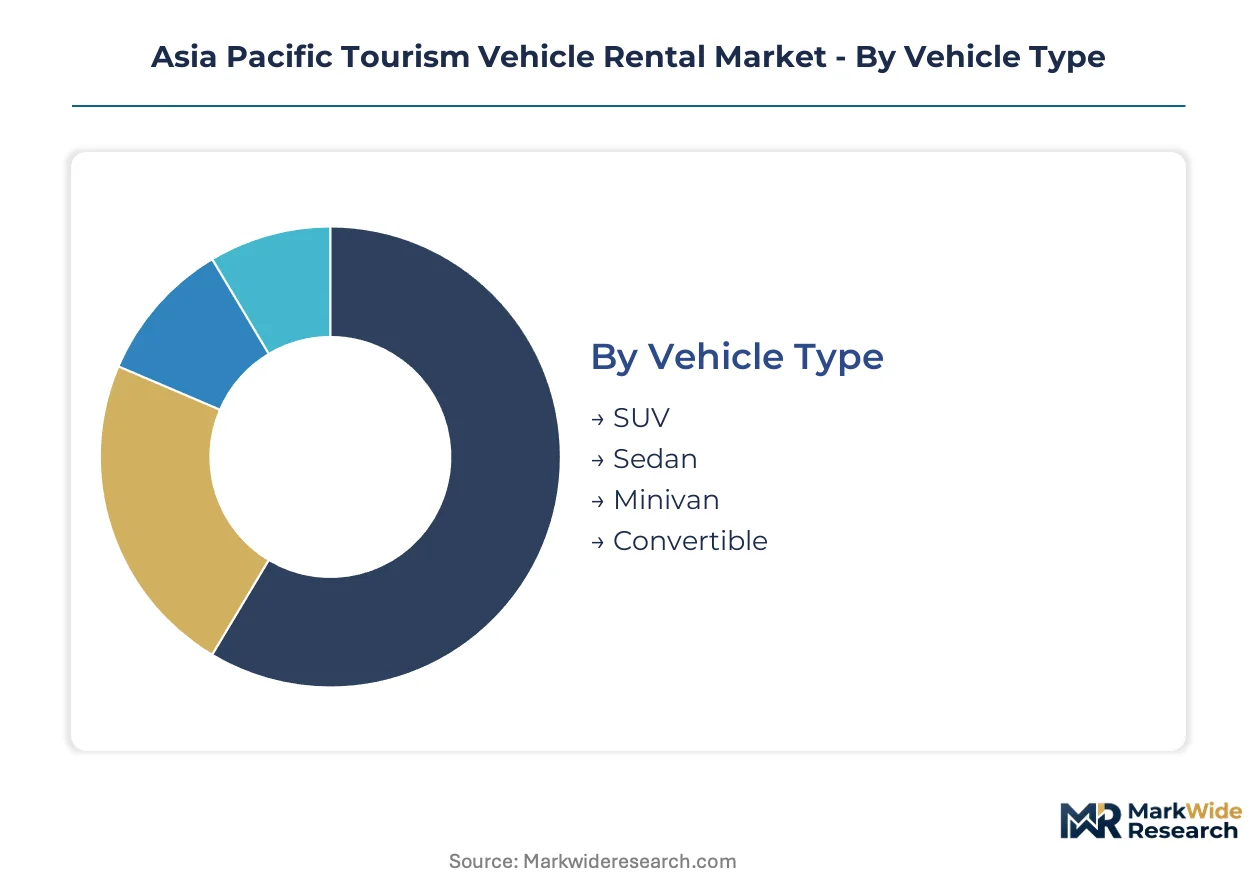
Tourism vehicle rental operators across Asia Pacific configure fleet composition and pricing architecture around distinct traveler profiles and trip characteristics. Understanding how segments intersect—family size against vehicle capacity, trip duration against booking behavior—determines utilization rates and margin capture in seasonal destination markets.
Vehicle Type:
Buyer decisions here pivot on passenger capacity against terrain requirements, with fuel efficiency and luggage volume as secondary filters.
- SUV:Higher ground clearance and all-wheel-drive configurations suit Australia's outback routes and Himalayan access roads in India. Multi-generational family segments across Thailand's resort corridors sustain premium daily rates for this category.
- Minivan:Sliding-door access and fold-flat seating accommodate airport-to-hotel transfers for tour groups in Vietnam's central coast and Indonesia's Bali corridor. Operators in these markets report extended booking windows for this configuration.
- Sedan:Compact and mid-size variants dominate urban business travel between Shanghai, Singapore, and Sydney central business districts.
- Convertible:Limited seasonal demand concentrates in Australia's Gold Coast and Thailand's Phuket during dry-season months.
Volume sits with SUV configurations; growth tilts toward minivan demand as multi-generational travel patterns strengthen.
Rental Duration:
Trip length directly determines working capital intensity and insurance bundling complexity for fleet managers.
- Short-Term:Daily and weekend rentals at airport counters serve inbound corporate travelers with fixed itineraries. China's MIIT emissions standards now restrict which models qualify for this high-turnover segment.
- Long-Term:Monthly and quarterly agreements appeal to project consultants and digital nomads operating across multiple Asia Pacific cities. Singapore operators pioneered subscription-flat-fee structures for this segment.
- Weekly:Seven-day packages with bundled mileage dominate leisure road-trip planning in Australia's coastal circuits.
- Monthly:Extended-stay tourists in Thailand and Vietnam favor this duration for regional exploration without ownership burdens.
Short-term rentals still generate the highest transaction velocity; long-term contracts are climbing fastest as remote work normalization extends average trip lengths.
Customer Type:
Travel purpose shapes ancillary service attachment rates and vehicle class selection more than price sensitivity alone.
- Leisure Tourists:Independent explorers prioritize flexible pickup locations and GPS-enabled navigation for self-directed itineraries across Japan's Hokkaido ski regions and New Zealand's South Island. Post-pandemic preference shifts favor this segment.
- Families:Child-safety seat requirements and entertainment system availability drive vehicle selection in Australia's domestic market and China's coastal province tourism zones.
- Business Travelers:Corporate account relationships with Avis and Hertz sustain utilization at Beijing Capital and Bangkok Suvarnabhumi airports.
- Backpackers:Budget-conscious segments concentrate in Southeast Asian hub cities, selecting compact manual-transmission vehicles for island-hopping itineraries.
Business travelers anchor volume commitments; leisure tourists are expanding most quickly as packaged tour dependence declines.
Booking Channel:
Channel selection reflects traveler digital sophistication and trip planning horizon length.
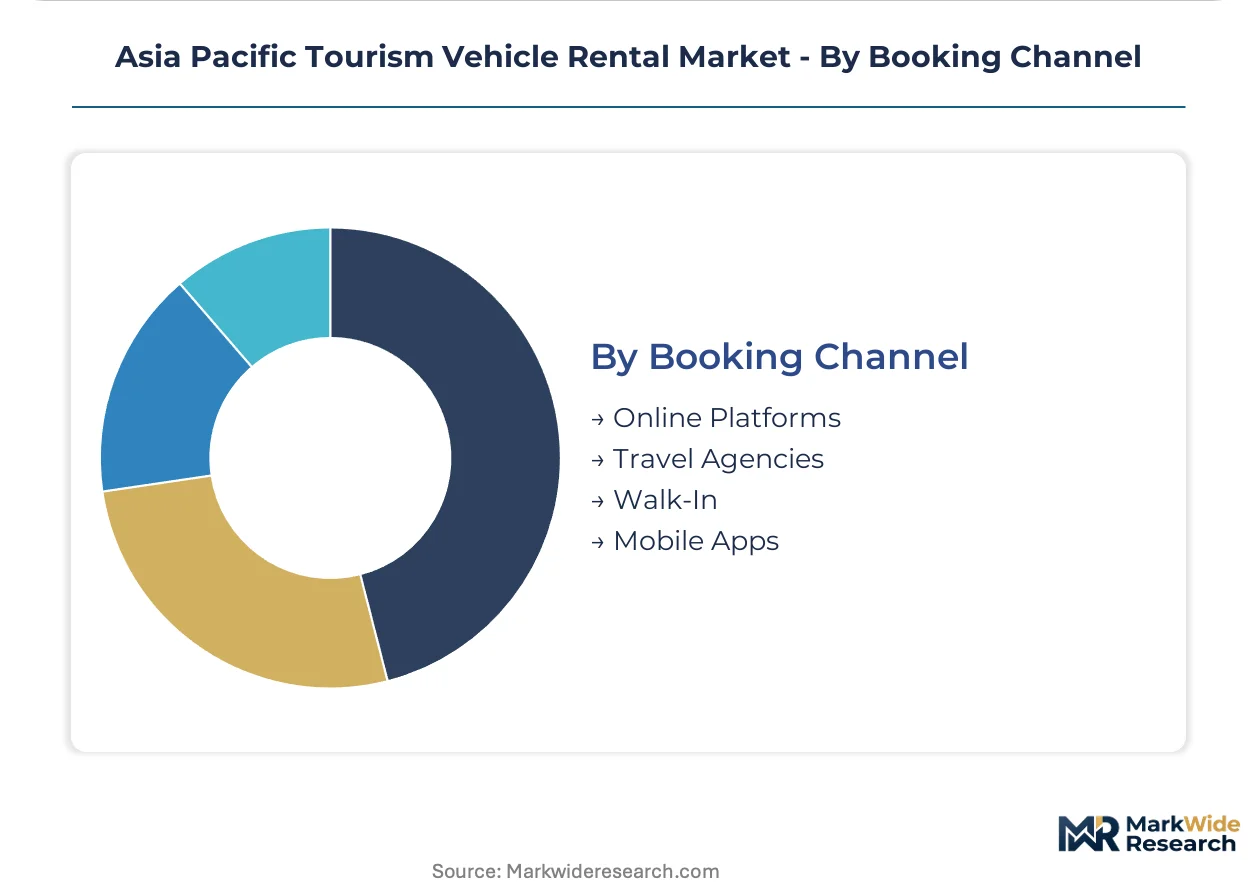
- Mobile Apps:Real-time availability and integrated payment rails dominate among younger demographics in India's urban centers and Southeast Asian metropolitan markets. Zoomcar's peer-to-peer platform architecture exemplifies this channel's disruption potential.
- Online Platforms:Comparison engines and loyalty program integration sustain share among pre-planned international arrivals.
- Travel Agencies:Package tour operators in Japan and South Korea still channel significant volume through traditional intermediaries.
- Walk-In:Counter transactions persist for unplanned extensions and weather-related itinerary changes in remote destination markets.
Online platforms retain the largest transaction base; mobile apps are gaining share fastest as airline and hospitality ecosystem integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates vehicle production capacity while consumption spreads across coastal tourism corridors. Fleet operators face divergent regulatory timelines as national emissions mandates outpace replacement cycles.
China
Guangdong and Zhejiang provinces absorb the highest rental transaction volumes through airport-hotel corridor density. MIIT production quotas for new energy vehicles accelerate domestic EV model availability at lease-competitive rates. Shenzhen and Shanghai operators now structure guaranteed residual value partnerships with BYD and NIO to manage fleet turnover risk.
India
Leisure road-trip demand along Himalayan access routes and coastal circuits drives SUV and minivan category preference. PLI scheme incentives for automotive manufacturing expand domestic EV assembly capacity, though charging infrastructure lags in tourism zones. Karnataka and Maharashtra clusters host the largest peer-to-peer platform aggregations, with Bangalore operators pioneering subscription-flat-fee structures for extended-stay segments.
Thailand
Phuket and Chiang Mai resort corridors sustain premium daily rates for multi-generational family vehicle configurations. Department of Land Transport commercial registration protocols impose extended inspection cycles that lengthen deployment timelines. Bangkok Suvarnabhumi Airport dedicated rental processing infrastructure reduces customer friction and extends advance booking windows.
Australia
Outback route exploration and Gold Coast leisure circuits anchor demand for higher-ground-clearance vehicle categories. TGA-equivalent vehicle safety certifications apply to commercial fleet registration, though state-level variations persist. Queensland and New South Wales operators report fastest adoption of connected fleet telematics for dynamic pricing adjustments.
Vietnam
Da Nang to Hue central coast infrastructure investments create expansion territory for premium family-oriented rental services. National transport ministry guidelines on commercial vehicle registration are stabilizing after years of provincial variation. Ho Chi Minh City and Hanoi operators concentrate fleet assets near international airport terminals to capture inbound corporate traveler volume.
Asia Pacific Tourism Vehicle Rental Market Competitive Environment
Capital-heavy fleet owners compete with asset-light platform aggregators for customer acquisition and utilization efficiency. The market structure tiered between integrated national operators, technology-enabled intermediaries, and specialized regional players. Strategic archetypes separate around captive airport infrastructure access, peer-to-peer network density, and corporate account relationship depth. Dominant competitive moves include ecosystem integration with hospitality and airline booking platforms, plus accelerated fleet electrification commitments tied to manufacturer residual value guarantees.
Within the integrated national operator tier, Beijing China Auto Rental and Shouqi Car Rental exemplify asset-heavy positioning through captive airport-hotel partnerships. Zoomcar India Pvt. Ltd. anchors the platform-aggregator archetype, leveraging peer-to-peer fleet aggregation technology to expand inventory without balance-sheet vehicle ownership. Avis Budget Group and Hertz Corporation represent multinational brand recognition strategies targeting inbound corporate traveler segments with standardized service protocols across multiple Asia Pacific markets.
| Leading Market Players |
|---|
| eHi Car Service Limited |
| Zoomcar India Pvt. Ltd. |
| Hertz Corporation |
| Beijing China Auto Rental (CAR Inc.) |
| Avis Budget Group |
| Sixt SE |
| Carzonrent India Pvt. Ltd. |
| Shouqi Car Rental |
| Drivezy |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up fleet operators in China and Thailand exercise pricing discipline through captive airport-hotel infrastructure, while China's PLI scheme and India's BIS certification requirements reshape procurement toward domestic EV manufacturers and standardized equipment tiers. This ownership pattern concentrates pricing power with scale players who negotiate guaranteed residual value programs, compressing margin pools for smaller operators dependent on spot-market vehicle sourcing.
Pricing Analysis
Margin tightening in the short-term airport rental tier reflects MIIT emissions mandates disqualifying older internal combustion models from commercial registration faster than fleet replacement cycles permit. Three-tier pricing structure across premium SUV, standard sedan, and economy compact levels separates business travelers at Beijing Capital and Bangkok Suvarnabhumi from leisure tourists and backpackers. Cost-down pressure on electric fleet commitments accelerates because lithium-ion battery raw material volatility forces operators to demand manufacturer buyback guarantees. Backpackers in Southeast Asian hub cities exhibit highest price sensitivity; corporate account relationships with integrated national operators show lowest.
Supply Chain Analysis
India's PLI scheme for automotive manufacturing and China's dual carbon goals are reshaping sourcing toward domestic EV assembly capacity and local-content battery partnerships. Vehicle production concentrates in China, India, and Thailand, with lithium-ion cells and semiconductor components drawing from Taiwan-based foundries and Korean-Japanese battery specialists. Single-source vulnerability in automotive chip fabrication creates exposure for fleet management system upgrades across Indonesia and Philippines. Distribution runs through airport-terminal counters, mobile-app platforms, and hospitality ecosystem integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric powertrains are displacing internal combustion fleet composition across Asia Pacific tourism corridors, forcing asset-heavy operators to renegotiate supplier contracts and residual value assumptions while platform aggregators capture share through technology-enabled inventory access.
For Market Incumbents: Hedge fleet turnover risk through guaranteed residual value partnerships with BYD and NIO in China's coastal provinces, and backward integration into charging infrastructure networks across Thailand's resort corridors. MIIT emissions mandates threaten older vehicle stranding; certification investment in BIS-compliant equipment specifications for Himalayan and coastal tourism zones in India secures cross-terrain operating rights. For New Entrants and Emerging Players: Peer-to-peer fleet aggregation technology offers entry into Vietnam's Da Nang to Hue central coast corridor, where infrastructure investments have created virgin territory for premium SUV and minivan services targeting multi-generational family segments. Target extended-stay digital nomads in Singapore and Sydney through subscription-flat-fee structures with bundled insurance and maintenance, leveraging parking scarcity and congestion charges that make ownership economically irrational. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light platform aggregators in India's Karnataka and Maharashtra clusters, where Zoomcar's technology leadership has validated peer-to-peer model economics. Five-to-ten year viability hinges on telematics-insurance convergence unlocking usage-based coverage revenue streams. Watch EV technician certification program development across Indonesia and Philippines as inflection indicator for maintenance network reliability and roadside assistance scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Guaranteed Residual Value Partnerships | BYD and NIO contracts in Guangdong and Zhejiang reduce fleet turnover risk for coastal province operators. |
| Telematics-Insurance Platform Integration | Real-time driving behavior data enables usage-based coverage products lowering premiums for safe renters. |
| Airport-Hotel Ecosystem Embedding | Beijing Capital and Bangkok Suvarnabhumi dedicated processing infrastructure extends advance booking windows. |
| Peer-to-Peer Fleet Aggregation Expansion | Zoomcar's technology architecture validates asset-light inventory scaling without balance-sheet vehicle ownership. |
| EV Technician Certification Program Investment | High-voltage system training across Indonesia and Philippines unlocks maintenance network reliability for electric fleets. |
Study Parameters
Document review covered fleet operator financial disclosures, national transport ministry registration databases, and MIIT production quota filings, complemented by interviews with rental platform executives, airport concession managers, hospitality distribution partners, and automotive OEM fleet sales directors. Secondary validation drew from customs vehicle import records, tourism arrival statistics, and charging infrastructure deployment registries. Bottom-up transaction volume estimates triangulated against top-down fleet size and utilization assumptions.
Cross-referencing historical utilization patterns against panel input from procurement leads and revenue management specialists anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, rental duration, customer purpose, and booking channel, with propulsion architecture and regional regulatory cluster as industry-specific overlays. CAGRs were derived from fitted growth curves calibrated to tourism corridor maturity and EV adoption S-cycles, incorporating battery cost trajectory assumptions and semiconductor supply normalization timelines.
Several conditions sit outside the modeled scope, including abrupt shifts in China's dual carbon policy implementation pace, Thailand Department of Land Transport registration protocol amendments, and unanticipated lithium-ion raw material supply disruptions. Forecasts reflect documented assumptions about tourism recovery trajectories and infrastructure investment completion schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
India Car Rental Market
Transportation Services
Driving Vacation Market
Transportation Services
Cross Docking Services Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Scooter Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Water Truck Rental Market