
 Car Rental Service Market | 2026-2036
Car Rental Service Market Size, Share, and Industry Trends Forecast 2026-2036
Car Rental Service Market Analysis
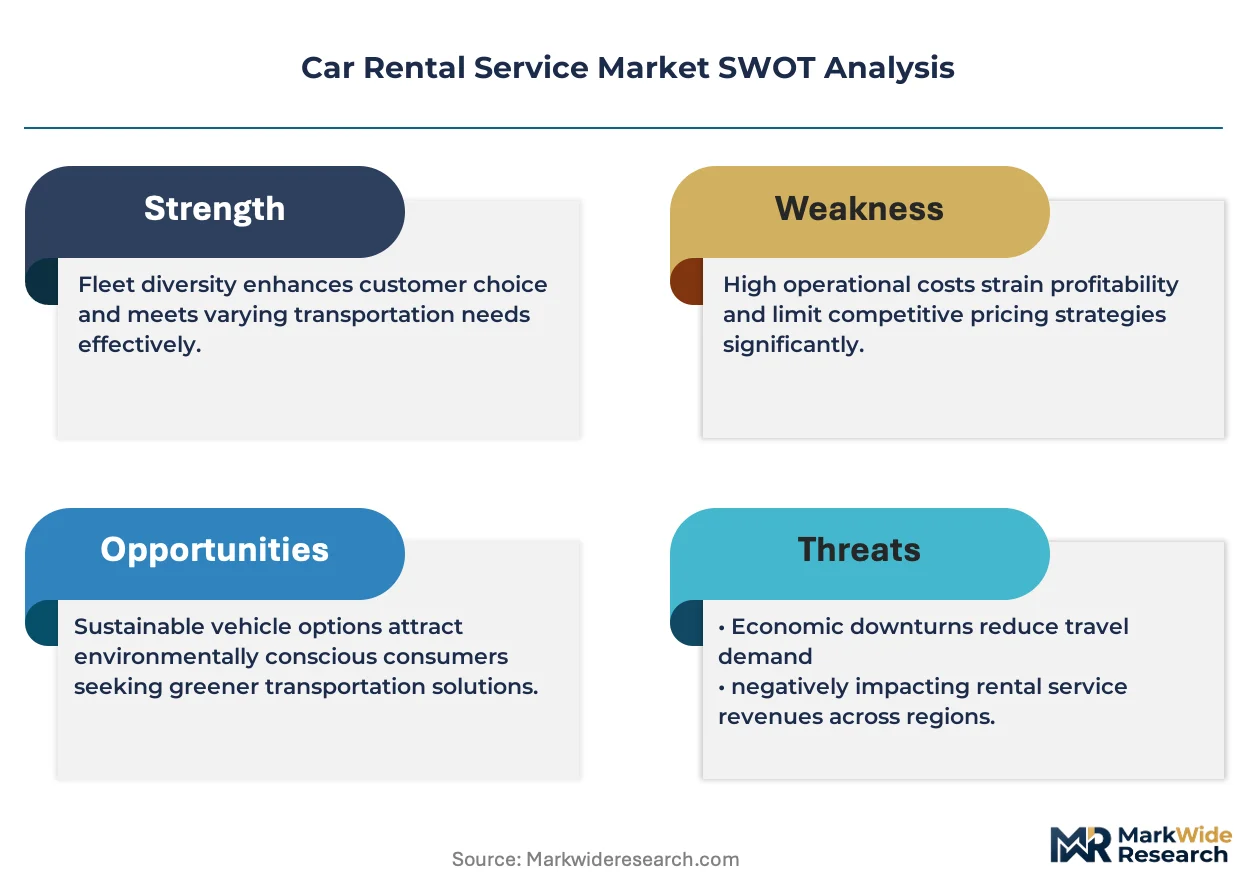
Asset-light fleet leasing and third-party vehicle sourcing is reshaping competitive economics in car rental services. Enterprise Holdings Inc. leverages its integrated neighborhood and airport network to sustain coverage density. Avis Budget Group anchors North American corporate accounts through centralized fleet management contracts. Sixt SE differentiates via premium vehicle positioning and digital-first booking infrastructure.
Car rental service denotes a short-duration vehicle provision model where operators maintain titled fleets available for hourly, daily, or monthly use against fee-based contracts, with fleet composition governed by residual value forecasting and manufacturer repurchase agreements. The service functions as flexible mobility infrastructure for travelers, temporary workers, and fleet-short enterprises. Short-term rental and car subscription segments capture expanding margin pools as utilization-based billing replaces fixed ownership. Electric vehicle type demand accelerates fastest where charging infrastructure density supports operational viability. Corporate client bookings dominate revenue stability against leisure travel seasonality.
FAA oversight of airport concession agreements shapes rental counter access and fee structures at major US hubs. EPA tailpipe standards and NHTSA safety mandates dictate fleet procurement cycles and vehicle retirement timing. The EU Green Deal and national zero-emission zones in France, Germany, and the Netherlands are forcing diesel fleet phaseouts. Stakeholders must monitor regulatory compliance costs against subscription revenue models.
Market Dynamics
Fleet operators face a structural pivot as EPA emissions standards tighten vehicle ownership economics for corporate clients, forcing accelerated outsourcing of mobility programs and reshaping procurement patterns across airport and urban rental networks.
Growth Catalysts
- EPA Tailpipe Standards:Tightening emissions mandates in the United States are compressing corporate fleet ownership timelines and accelerating outsourced mobility program adoption.
- Business Travel Recovery:Post-pandemic normalization of corporate travel patterns is restoring airport-centric rental volume leadership at major US hubs.
- Electric Vehicle Infrastructure:Charging network density expansion in Germany, France, and the Netherlands is enabling operational viability for zero-emission fleet segments.
Market Restraints
- Residual Value Volatility:Used vehicle price fluctuations compress fleet monetization timelines and constrain manufacturer repurchase agreement terms.
- FAA Concession Structures:Airport fee obligations and counter access restrictions at major US hubs elevate fixed cost burdens relative to off-airport operators.
- Diesel Phaseout Mandates:EU Green Deal implementation and national zero-emission zones in France, Germany, and the Netherlands force accelerated fleet turnover before depreciation cycles complete.
Strategic Opportunities
- Car Subscription Models:Flexible monthly billing structures are capturing margin pools from traditional ownership in urban Germany and the Netherlands.
- Corporate Fleet Shortfalls:Temporary vehicle shortages at enterprise clients create recurring demand for centralized fleet management contracts.
- Digital-First Booking:Mobile-native reservation platforms are displacing legacy counter-based transactions among leisure travelers in France.
Industry Challenges
- Charging Infrastructure Coordination:Fleet electrification requires real-time availability data integration across fragmented regional charging networks.
- EU Green Deal Compliance:National zero-emission zone implementation timelines vary across France, Germany, and the Netherlands, complicating cross-border fleet deployment.
- Legacy System Integration:Established reservation platforms require costly API modernization to support dynamic pricing and subscription billing modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Rental Service Market |
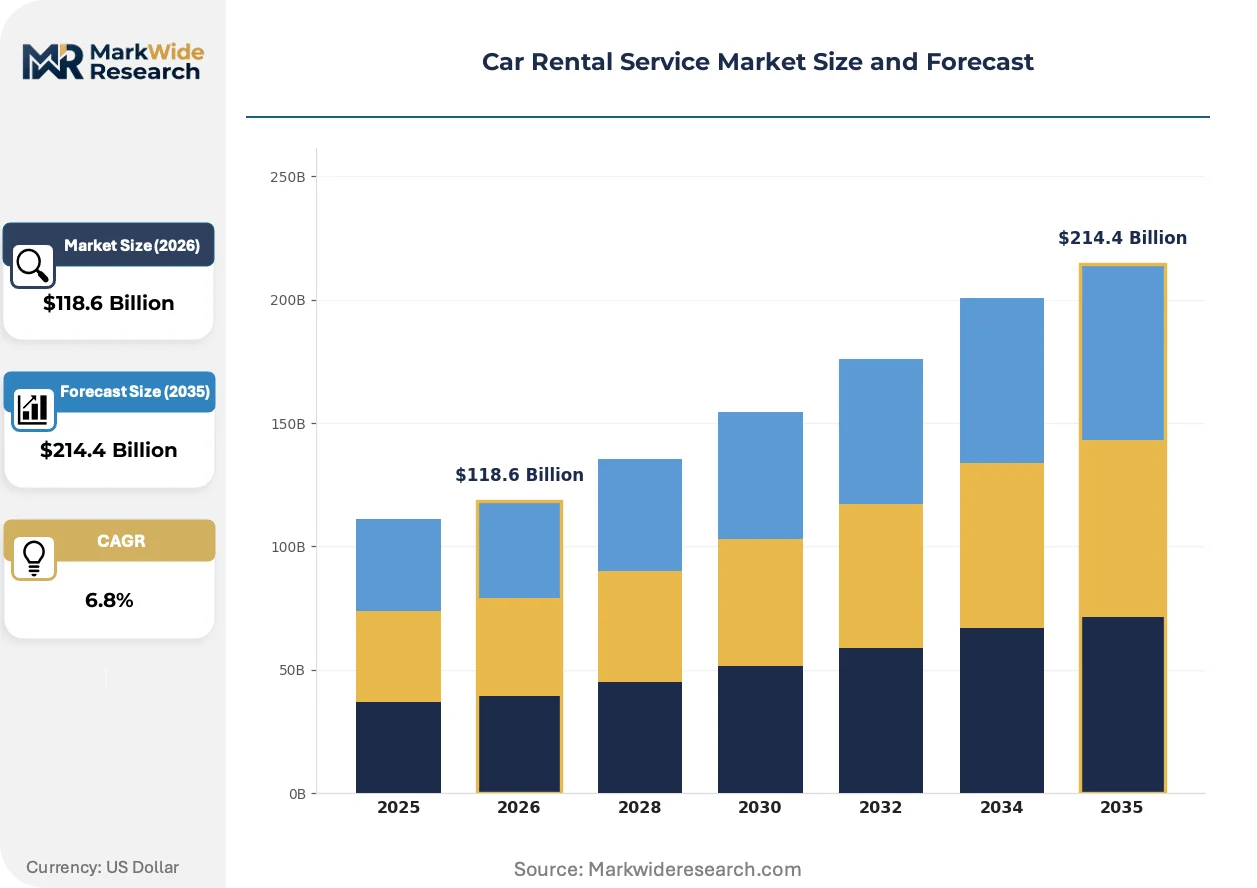
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rental, Long-Term Rental, Luxury Rental, Car Subscription Customer Type: Corporate Clients, Leisure Travelers, Government Agencies, Tour Operators Vehicle Type: Economy, SUV, Van, Electric Booking Channel: Online, Mobile App, Travel Agency, Direct |
| Companies Covered | Enterprise Holdings Inc., Avis Budget Group, The Hertz Corporation, Europcar Group, Sixt SE, Localiza, Zoomcar Holdings Inc., Alamo Rent-A-Car LLC, National Car Rental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Rental Service Market Emerging Trajectories
Telematics-enabled fleet management and dynamic pricing algorithms are compressing traditional rental economics, while regulatory pressure on emissions accelerates vehicle mix transformation across major operating regions.
Connected vehicle platforms are virtualizing fleet oversight functions previously managed through manual inspection and paper-based check-in protocols. Airport and neighborhood operators are deploying these systems to automate damage assessment and fuel verification. The technology is virtualizing counter staff roles and compressing transaction times at high-volume locations.
The EU Green Deal and national zero-emission zone designations in France, Germany, and the Netherlands are mandating diesel fleet phaseouts ahead of standard replacement cycles. This regulatory pressure is compressing residual value realization windows and elevating capital intensity for fleet refresh programs. Operators in these markets are responding with accelerated electric vehicle procurement and charging infrastructure partnerships.
Corporate procurement departments are consolidating mobility spend under centralized fleet management contracts with utilization-based billing terms. This purchasing pattern is displacing fragmented departmental rental arrangements and elevating vendor scale requirements. The shift is most visible in the United States, where enterprise accounts prioritize single-source national coverage density over point solutions.
Car Rental Service Market Segmentation
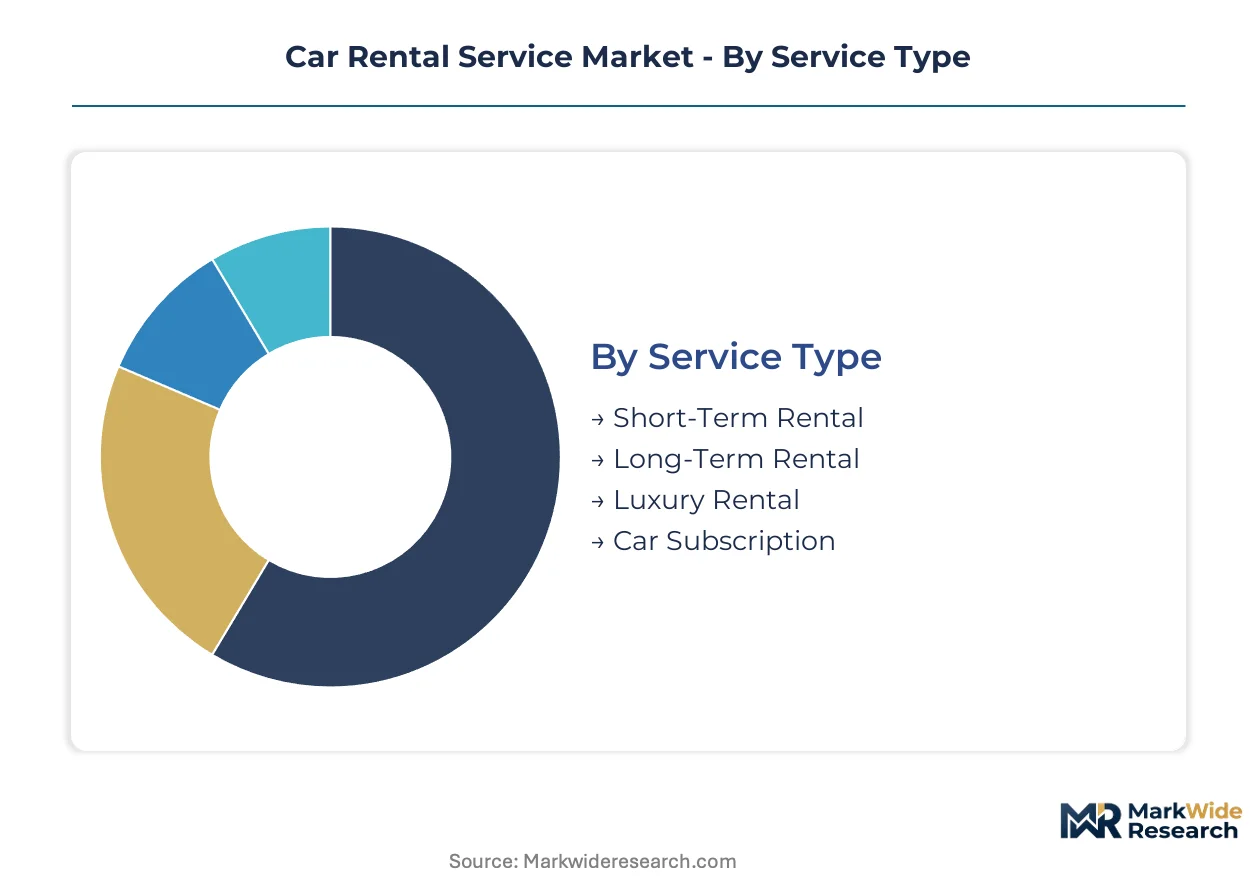
Fleet monetization models diverge sharply across service duration and customer procurement patterns. Segmentation reveals which contract structures capture premium pricing versus volume throughput in the evolving mobility landscape.
Service Type:
Mature daily-rate operations coexist with emerging subscription formats as utilization-based billing displaces fixed ownership.
- Short-Term Rental:Hourly and daily contracts dominate airport-centric operations with rapid vehicle turnover. Corporate travel recovery at major US hubs sustains volume leadership against leisure seasonality.
- Long-Term Rental:Weekly and monthly agreements serve temporary workers and fleet-short enterprises. Germany and the Netherlands show strongest demand where employer mobility allowances favor flexible duration terms.
- Luxury Rental:Premium vehicle positioning commands rate premiums in urban France and business districts.
- Car Subscription:All-inclusive monthly billing bundles insurance, maintenance, and vehicle swaps. This format climbs fastest in Germany and the Netherlands where urban consumers reject ownership depreciation risk.
Short-term rental handles the majority of throughput; car subscription is expanding most quickly on share.
Customer Type:
Procurement centralization separates enterprise accounts with utilization-based billing from fragmented leisure transactions.
- Corporate Clients:Centralized fleet management contracts with national coverage density requirements. EPA emissions standards are compressing ownership timelines and accelerating outsourced mobility program adoption across US enterprise accounts.
- Leisure Travelers:Mobile-native reservation platforms displace legacy counter-based transactions. France shows strongest digital migration among vacation rental demand.
- Government Agencies:Public sector procurement operates through structured RFP processes with domestic content preferences.
- Tour Operators:Volume commitments and seasonal fleet guarantees characterize this channel.
Corporate clients anchor revenue stability; leisure travelers are gaining share fastest through digital channel migration.
Vehicle Type:
Margin concentration follows powertrain transition and cabin configuration versatility across operating regions.
- Economy:Compact sedans and hatchbacks serve price-sensitive airport and urban demand. Residual value volatility constrains fleet monetization timelines for this high-depreciation category.
- SUV:Crossover and sport-utility vehicles command rate premiums in suburban and leisure corridors. US airport networks prioritize SUV availability for family travel segments.
- Van:Passenger and cargo configurations address contractor and small business mobility gaps.
- Electric:Zero-emission fleet segments accelerate where charging infrastructure density supports operational viability. The Netherlands and Germany lead procurement as EU Green Deal mandates force diesel phaseouts.
SUV configurations capture the widest rate premiums; electric vehicle procurement shows the steepest expansion trajectory.
Booking Channel:
Transaction virtualization compresses counter economics while elevating platform scale requirements.
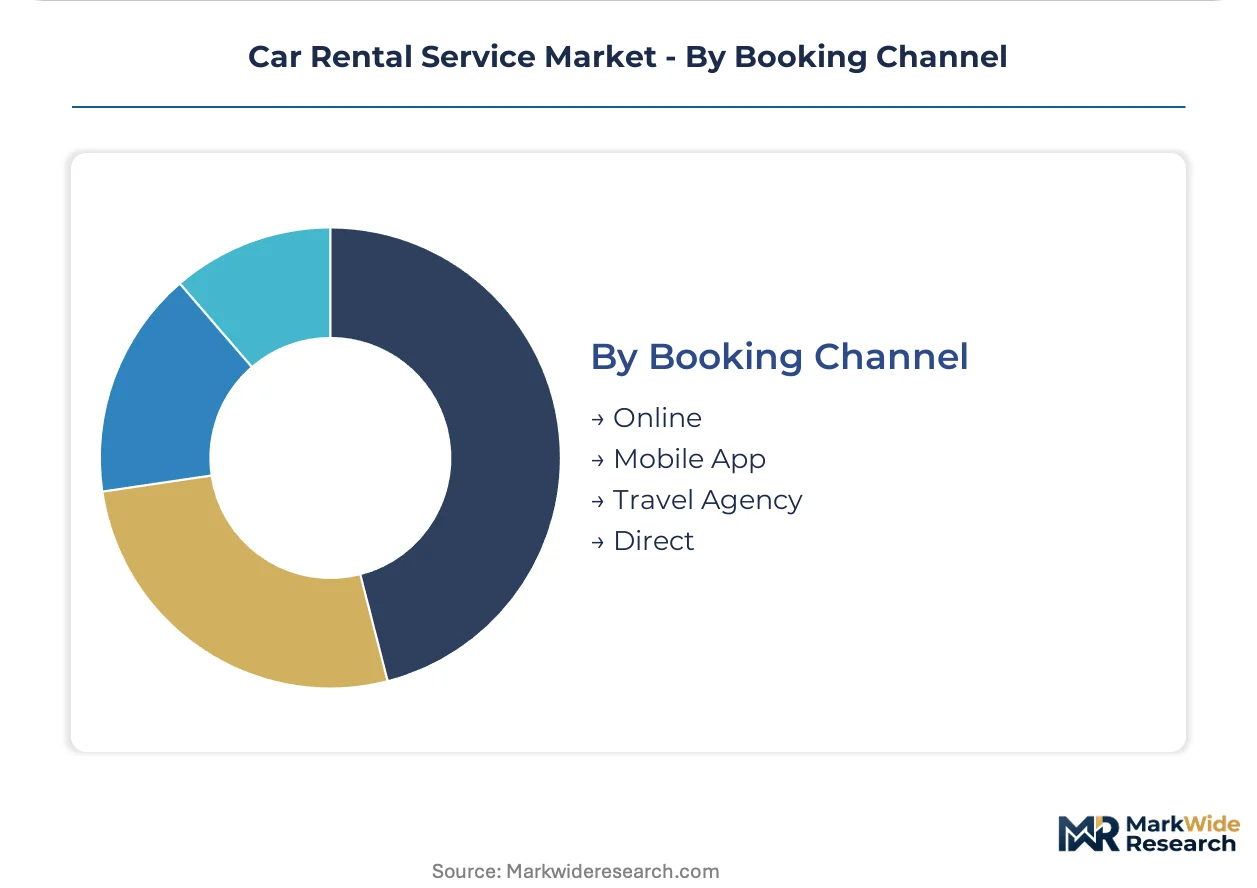
- Online:Web-based reservation engines with dynamic pricing algorithms. Corporate procurement departments consolidate spend through centralized online portals with utilization-based billing terms.
- Mobile App:Native smartphone platforms enable contactless pickup and digital key integration. France demonstrates highest mobile adoption among leisure travelers seeking counter bypass.
- Travel Agency:Intermediary bookings through corporate travel management companies and tour operators.
- Direct:Walk-up and phone reservations at airport counters and neighborhood locations.
Online channels process the majority of corporate volume; mobile app adoption is climbing fastest among leisure segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe standards and EU Green Deal mandates are restructuring fleet economics across major operating regions, accelerating outsourced mobility adoption while forcing diesel phaseouts ahead of standard replacement cycles.
United States
Corporate travel recovery at major hubs sustains airport-centric rental volume leadership. FAA concession agreements govern counter access and fee structures at Atlanta, Dallas-Fort Worth, and Denver. Enterprise Holdings anchors national coverage density through integrated neighborhood and airport networks.
Germany
Employer mobility allowances favor flexible long-term rental duration terms in urban centers. National zero-emission zone implementation in Berlin, Munich, and Hamburg forces accelerated diesel fleet turnover. Charging infrastructure density expansion in the Rhine-Ruhr and Stuttgart regions enables electric vehicle operational viability.
Netherlands
Urban consumers reject ownership depreciation risk, driving car subscription format expansion fastest. EU Green Deal compliance timelines compress residual value realization windows for legacy diesel fleets. Amsterdam and Rotterdam operators deploy charging infrastructure partnerships to support zero-emission procurement.
France
Leisure travelers demonstrate highest mobile-native reservation platform adoption, displacing legacy counter-based transactions. ANSM and national regulators enforce EU Green Deal diesel phaseout mandates ahead of depreciation cycles. Paris and Lyon business districts sustain premium luxury rental rate premiums.
United Kingdom
Corporate procurement departments consolidate mobility spend under centralized fleet management contracts. CSRD and national emissions regulations compress corporate fleet ownership timelines. London Heathrow and Manchester airport networks prioritize SUV availability for family travel segments.
Car Rental Service Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented network configurations. The vendor base organizes around airport concession access, neighborhood density coverage, and digital platform scale. Three archetypes dominate: integrated network operators with dual airport-neighborhood presence, premium-positioned specialists with digital-first infrastructure, and regional consolidators with emerging market density. M&A activity targets fleet management technology capabilities, while strategic partnerships address charging infrastructure coordination.
Within the integrated network tier, Enterprise Holdings Inc. and Avis Budget Group exemplify scale-driven coverage models. Sixt SE occupies a premium-positioned specialist archetype with digital-first booking infrastructure. These three anchors represent divergent strategic vectors: national density consolidation, corporate account centralization, and premium segment specialization.
| Leading Market Players |
|---|
| Enterprise Holdings Inc. |
| Avis Budget Group |
| The Hertz Corporation |
| Europcar Group |
| Sixt SE |
| Localiza |
| Zoomcar Holdings Inc. |
| Alamo Rent-A-Car LLC |
| National Car Rental |
| Others |
Supply Flow & Price Mechanics
Atlanta's airport-centric rental infrastructure concentrates fleet procurement volume, compressing manufacturer repurchase negotiations and elevating pricing power for operators with counter access at Hartsfield-Jackson and Dallas-Fort Worth. This geographic concentration of fleet sourcing tightens residual value realization windows across the United States while amplifying margin pressure on off-airport independents lacking concession agreements.
Pricing Analysis
Vehicle class tiering creates the primary spread between economy compacts and premium SUVs, with crossover configurations commanding rate premiums in suburban corridors and family travel segments. Corporate fleet management contracts with utilization-based billing terms anchor volume stability, while leisure travelers exhibit highest price sensitivity during off-peak periods. Pricing pressure stems from residual value volatility compressing fleet monetization timelines, particularly for high-depreciation economy segments. Subscription billing models with bundled insurance and maintenance capture expanding margin pools from traditional daily-rate operations in Germany and the Netherlands.
Supply Chain Analysis
Export-control scrutiny on connected vehicle telematics platforms limits technology transfer flows between United States, European Union, and Chinese manufacturing jurisdictions. Fleet procurement draws from Germany, Japan, and South Korea for vehicle sourcing, with charging infrastructure components anchored in Chinese and South Korean supply bases. Semiconductor availability for infotainment and advanced driver-assistance systems creates single-source vulnerability during automotive chip allocation cycles. Distribution runs through manufacturer repurchase agreements, third-party fleet lessors, and direct OEM procurement channels serving airport and neighborhood rental networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Car rental service operators should treat fleet management technology and subscription billing infrastructure as the primary service-attach layers, with recurring-revenue platforms expanding faster than vehicle hardware procurement across Germany and the Netherlands.
For Market Incumbents: Harden neighborhood network density against digital-native entrants by accelerating API modernization for dynamic pricing and subscription modules. Consolidate airport concession access at FAA-governed hubs to defend counter economics against off-airport competitors. Prioritize charging infrastructure partnerships in EU zero-emission zones to secure electric vehicle operational viability before diesel phaseout mandates complete. For New Entrants and Emerging Players: Build out mobile-native reservation platforms targeting leisure travelers in France, where counter bypass adoption climbs fastest among vacation rental demand. Target corporate fleet shortfall segments with flexible duration terms and centralized billing integration. Establish white-label fleet management partnerships with employer mobility allowance programs in urban Germany. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-infrastructure play because utilization-based billing displaces fixed ownership depreciation risk across urban European markets. Target fleet management technology specialists with real-time telematics and dynamic pricing capabilities. Monitor EU Green Deal implementation timelines across France, Germany, and the Netherlands as the inflection signal for accelerated electric vehicle procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | EU Green Deal mandates in France, Germany, and Netherlands force zero-emission fleet transitions ahead of standard replacement cycles. |
| API Modernization for Subscription Billing | Legacy reservation platforms require dynamic pricing integration to capture recurring-revenue pools from corporate mobility programs. |
| Airport Concession Consolidation | FAA-governed counter access at Atlanta, Dallas-Fort Worth, and Denver secures volume leadership against off-airport competitors. |
| Telematics Platform Deployment | Connected vehicle systems automate damage assessment and fuel verification, compressing transaction times at high-volume locations. |
| Corporate Fleet Management Contract Expansion | Centralized procurement with utilization-based billing terms displaces fragmented departmental rental arrangements across US enterprise accounts. |
Methodological Framework
Cross-validation between fleet operator procurement executives and automotive OEM fleet sales directors anchors the qualitative findings, with secondary validation drawing from FAA concession filings, EPA emissions compliance databases, and EU Green Deal implementation trackers. Primary fieldwork encompassed interviews with airport rental operations managers, corporate travel procurement officers, fleet lessor underwriting teams, and charging infrastructure developers across the United States, Germany, France, and the Netherlands. Bottom-up triangulation of fleet size data and top-down revenue reconciliation across service type segments ensured methodological consistency.
Calibration against historical fleet turnover rates and residual value indices shaped the projection framework across the analysis window. Segmentation dimensions modeled include service duration tier, customer procurement pattern, vehicle powertrain architecture, and booking channel virtualization level. CAGRs derived from regression analysis of fleet expansion trajectories, incorporating charging infrastructure density curves and regulatory compliance cost assumptions specific to EPA tailpipe standards and EU zero-emission zone timelines.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification moves by integrated network operators would shift outcomes beyond modeled parameters. Material shifts in residual value volatility or EU Green Deal acceleration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
Germany Car Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Car Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Drayage Services Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Ship Management Software Market
Transportation Services
Vietnam Taxi Market