
 Europe Refrigerated Truck Rental Market | 2026-2036
Europe Refrigerated Truck Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refrigerated Truck Rental Market Intelligence
Euro VI diesel compliance tier is collapsing the cost gap between owned and rented refrigerated fleets across European logistics corridors. TIP Group leverages its pan-European service network to sustain maintenance coverage for multi-temperature units. Petit Forestier anchors its position through specialized cold chain expertise spanning pharmaceutical and fresh produce segments. Fraikin Limited competes with flexible rental terms calibrated to seasonal agricultural harvest cycles.
A refrigerated truck rental fleet comprises insulated commercial vehicles equipped with mechanical refrigeration units maintaining cargo temperatures between minus 25 degrees Celsius and plus 25 degrees Celsius for temperature-sensitive goods transport. These vehicles employ vapor compression or absorption cooling cycles with polyurethane foam insulation barriers to preserve pharmaceutical products, fresh food, and frozen commodities across distribution networks. Small and medium truck sizes lead rental volumes in urban last-mile delivery where maneuverability constraints dominate route planning. Long-term rental structures capture the strongest margin pools by locking fleet operators into multi-year maintenance contracts. Hybrid refrigeration technology is gaining fastest traction among logistics companies seeking to balance diesel range requirements with emerging low-emission zone access restrictions.
The EU F-Gas Regulation and ECHA REACH framework mandate phasedown of hydrofluorocarbon refrigerants while CE marking requirements enforce thermal performance standards for insulated vehicle bodies. Germany's KBA enforces periodic technical inspections that elevate compliance costs for self-operated fleets and redirect demand toward rental providers bearing certification burden. Fleet managers and procurement directors must weigh total cost of ownership against regulatory compliance exposure when structuring cold chain capacity decisions.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerated fleet operators to retire hydrofluorocarbon-based cooling systems ahead of mechanical end-of-life, compressing replacement cycles and expanding rental absorption as compliance burdens shift to specialized providers.
Growth Catalysts
- Pharmaceutical cold chain expansion:EMA serialization mandates and temperature excursion tracking requirements are elevating rental demand for validated multi-temperature units across continental distribution networks.
- Low-emission zone proliferation:German cities including Berlin and Hamburg are restricting Euro V diesel access, pushing food distributors toward rental fleets with hybrid refrigeration and pre-certified compliance.
- CE marking thermal performance standards:Insulated body certification complexity is redirecting small fleet operators toward rental providers bearing ongoing compliance verification costs.
Market Restraints
- Low-GWP refrigerant supply concentration:R-452A and R-513A production remains concentrated with limited European suppliers, exposing rental operators to input cost volatility and allocation risk.
- Technical limitation in electric range:Battery-electric refrigerated trucks face payload-tradeoff constraints below 12-tonne gross vehicle weight, restricting full electrification of urban delivery segments.
- Regulatory friction from KBA inspection intervals:Germany's Kraftfahrt-Bundesamt mandates compressed technical inspection cycles for modified refrigeration units, elevating administrative burden for cross-border operators.
Strategic Opportunities
- Underpenetrated Poland and Czech Republic corridors:Central European food processing clusters lack sufficient refrigerated rental density relative to throughput growth, creating white space for fleet deployment.
- Technology convergence of telematics and predictive maintenance:Real-time cargo temperature monitoring combined with compressor vibration analytics is enabling outcome-based rental pricing models.
- Regulatory tailwind from EU Green Deal fleet renewal incentives:Member state subsidy programs for low-emission commercial vehicles are compressing payback periods for rental providers investing in hybrid and electric units.
Industry Challenges
- Refrigeration technician scarcity:Qualified service personnel for transcritical CO2 and propane-based systems remain concentrated in Western European markets, constraining fleet expansion velocity.
- Multi-temperature certification timeline:ATP agreement compliance for dual-compartment vehicles requires extended homologation periods, delaying revenue recognition on new build specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refrigerated Truck Rental Market |
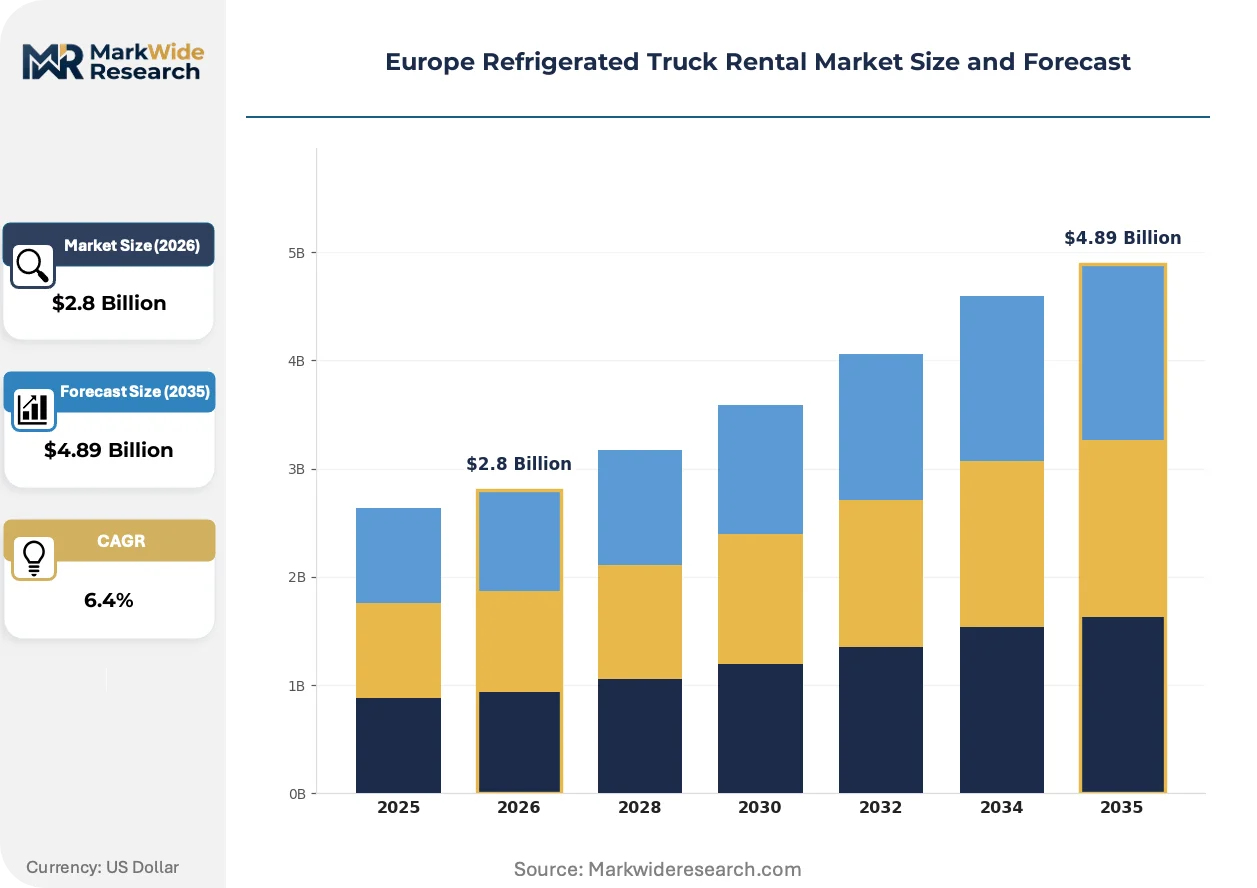
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Size: Small, Medium, Large, Extra Large Refrigeration Technology: Vapor Compression, Absorption, Thermoelectric, Hybrid Rental Duration: Short-Term, Long-Term, Seasonal, Flexible Customer Type: Retail Chains, Food Distributors, Logistics Companies, Caterers |
| Companies Covered | Penske Corporation, Inc., TIP Group, Ryder System, Inc., LAMBERET SAS, Polar Leasing, Inc., Petit Forestier, The Hertz Corporation, KRONE, Fraikin Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refrigerated Truck Rental Market Strategic Shifts & Innovations
Refrigerated transport technology is pivoting toward refrigerant chemistry substitution and powertrain electrification, compressing legacy equipment residual values while elevating service integration requirements.
Transcritical CO2 refrigeration is supplanting conventional hydrofluorocarbon vapor compression in medium-duty urban distribution vehicles. Dutch fresh produce distributors and French pharmaceutical logistics operators are adopting these units at accelerating pace despite higher upfront capital requirements. The technology is supplanting incumbent diesel-mechanical systems in low-emission zone applications where regulatory access determines route viability.
The EU F-Gas Regulation phasedown mandates 79% reduction in hydrofluorocarbon consumption by 2030 against 2015 baseline. Rental fleet operators face accelerated write-downs of existing refrigeration assets and compressed replacement timelines for multi-temperature units. Pharmaceutical cold chain segments across Germany and the Netherlands are responding by locking long-term rental contracts with providers holding certified low-GWP inventory.
Food service distributors are consolidating supplier relationships around integrated cold chain providers offering temperature-validated last-mile coverage. Traditional asset-light brokers and spot-market hauliers are losing share to rental operators bundling equipment, maintenance, and compliance certification. This concentration is most visible in Benelux urban corridors where supermarket consolidation has compressed approved vendor lists to three or fewer qualified rental partners per retail network.
Europe Refrigerated Truck Rental Market Segmentation
Refrigerated truck rental demand fragments across equipment specifications, contract structures, and customer procurement patterns. Each segmentation axis reveals distinct margin dynamics and competitive positioning requirements for fleet operators navigating European cold chain logistics.
Truck Size:
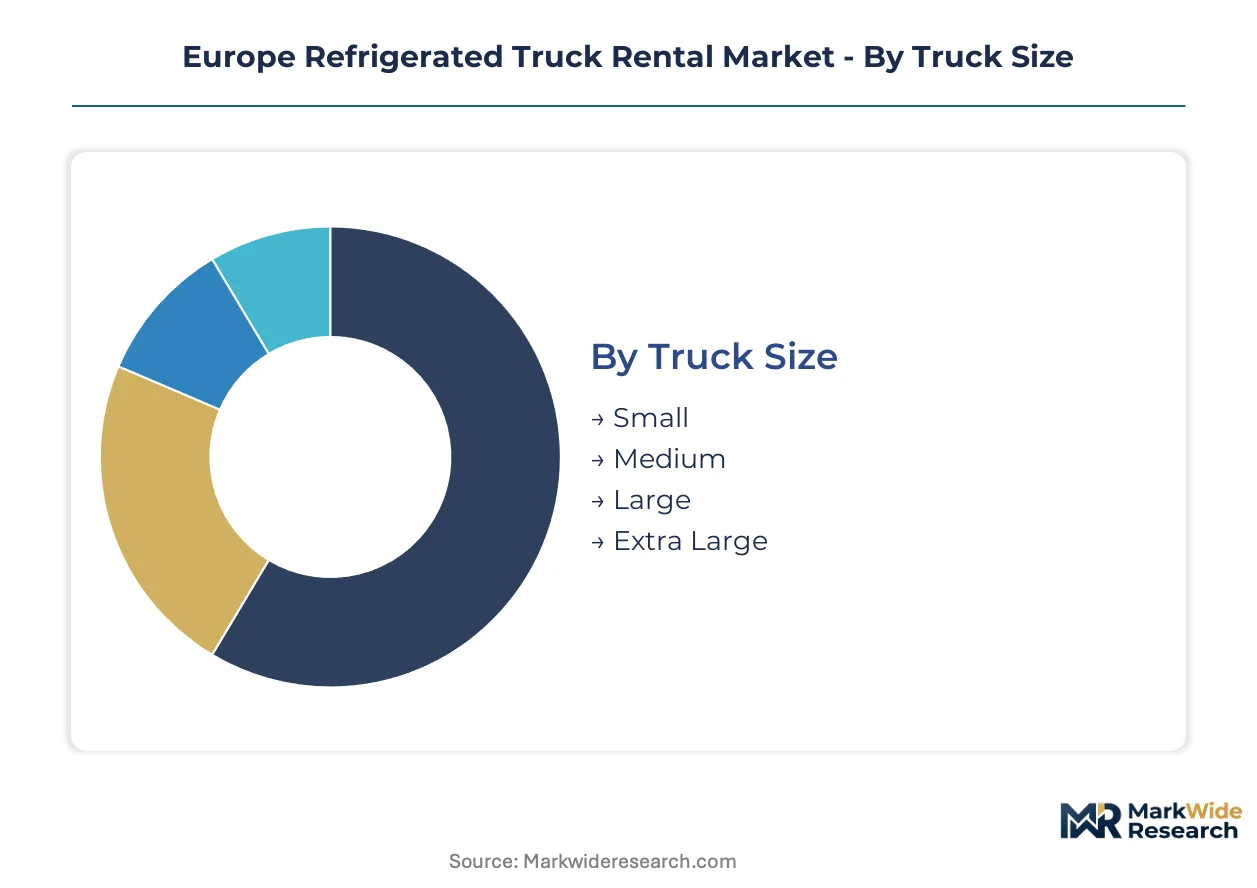
Margin pools concentrate in small and medium configurations where urban access restrictions and maneuverability premiums sustain rate premiums over highway tractors.
- Small:Vehicles below 7.5 tonnes gross vehicle weight dominate last-mile pharmaceutical and fresh produce delivery in German and Dutch city centers. Dense supermarket networks and LEZ compliance requirements in Berlin, Hamburg, and Amsterdam lock in sustained rental demand.
- Medium:Ranging 7.5-12 tonnes, these units balance payload capacity with urban accessibility for regional food distribution. French and Benelux logistics corridors show strongest absorption where intercity routes connect to dense retail consolidation points.
- Large:Highway-configured tractors above 12 tonnes serve long-haul frozen commodity transport between Spanish agricultural zones and Northern European distribution hubs.
- Extra Large:Specialized multi-temperature articulated configurations address pharmaceutical bulk distribution and frozen food consolidation across continental corridors.
The dominant share belongs to Small, while Medium is closing the gap fastest as regional food service networks expand beyond city cores.
Refrigeration Technology:
Technology choice determines compliance runway against EU F-Gas Regulation phasedown mandates and LEZ access permissions.
- Vapor Compression:Conventional hydrofluorocarbon-based systems face accelerated depreciation as ECHA REACH restrictions tighten refrigerant availability. Legacy fleet operators in Southern Europe retain these units for cost-sensitive frozen food transport where temperature stability outweighs regulatory exposure.
- Hybrid:Diesel-electric configurations with low-GWP refrigerants command rate premiums in German and French urban corridors where pre-certified LEZ access determines contract viability. Battery-assisted compressor operation reduces engine idling hours and extends maintenance intervals.
- Absorption:Waste-heat-driven systems find niche application in chemical and industrial waste heat recovery scenarios, limited by thermal efficiency constraints in mobile applications.
- Thermoelectric:Solid-state cooling serves compact pharmaceutical courier boxes and small-format urban delivery where payload minimization outweighs energy efficiency penalties.
Hybrid configurations are expanding most quickly as fleet operators front-load compliance investments, though Vapor Compression retains volume leadership in cost-optimized frozen commodity segments.
Rental Duration:
Contract length directly maps to customer working capital constraints and demand predictability across seasonal agricultural and pharmaceutical cycles.
- Long-Term:Multi-year agreements with embedded maintenance capture the strongest margin pools by locking fleet operators into predictable utilization and service revenue streams. Pharmaceutical distributors across Germany and the Netherlands favor these structures for validated cold chain capacity.
- Seasonal:Harvest-aligned contracts for Spanish citrus, Italian stone fruit, and French vegetable producers concentrate demand in discrete windows with premium spot pricing.
- Short-Term:Spot rentals address equipment failure coverage and demand spikes, competing primarily on availability and geographic proximity rather than rate.
- Flexible:Usage-based structures with telematics-verified kilometer and temperature-hour billing are gaining traction among mid-size food distributors managing demand volatility.
Long-Term contracts anchor provider profitability, while Flexible structures are climbing the fastest as digital fleet monitoring enables outcome-based pricing experimentation.
Customer Type:
Procurement sophistication and compliance requirements vary sharply across buyer categories, fragmenting service bundling strategies.
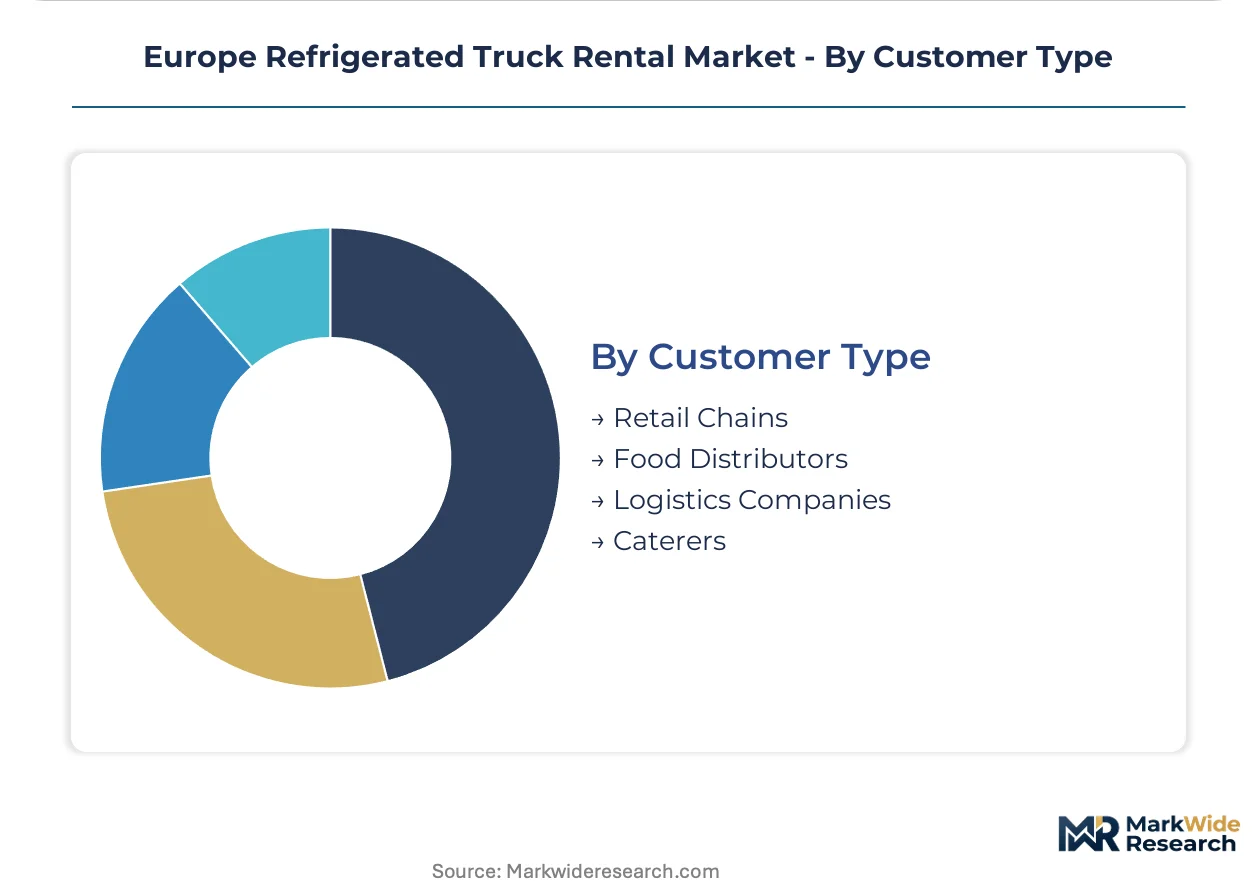
- Food Distributors:Integrated cold chain operators serving supermarket consolidation networks demand multi-temperature certification and real-time tracking. Benelux and German distributors are consolidating approved vendor lists to three or fewer rental partners per network.
- Logistics Companies:Asset-light 3PL providers and freight forwarders prioritize fleet flexibility and cross-border compliance coverage, favoring rental providers with pan-European service networks.
- Retail Chains:Direct-operated fleet programs at major supermarket groups are outsourcing refrigerated capacity to rental specialists as Euro VI compliance and refrigerant transition costs escalate.
- Caterers:Event and institutional food service operators drive volatile short-term demand with limited technical specification requirements and high price sensitivity.
Food Distributors command the deepest provider relationships, while Logistics Companies are gaining share fastest as outsourcing accelerates across European cold chain networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across European cold chain corridors are reshaping fleet deployment patterns. Northern distribution hubs absorb inbound Mediterranean produce while pharmaceutical exports flow toward Benelux ports. Rental providers cluster capacity around these directional trade flows.
Germany
Pharmaceutical distribution networks in Berlin and Hamburg drive multi-temperature rental demand. The KBA enforces compressed technical inspection cycles for modified refrigeration units, elevating compliance costs for self-operated fleets. Food retailers in the Rhine-Ruhr corridor are consolidating approved vendor lists to three or fewer rental partners per network.
France
Fresh produce logistics connecting Spanish agricultural zones to Parisian consolidation points sustains seasonal rental peaks. The EU F-Gas Regulation accelerates retirement of hydrofluorocarbon-based cooling systems in Lyon and Marseille distribution networks. Petit Forestier anchors specialized cold chain expertise spanning pharmaceutical and fresh produce segments.
Netherlands
Rotterdam port logistics and dense supermarket networks generate sustained small-truck rental absorption. CE marking thermal performance standards redirect small fleet operators toward rental providers bearing compliance verification costs. Dutch fresh produce distributors are adopting transcritical CO2 refrigeration at accelerating pace.
Spain
Citrus and stone fruit harvest cycles concentrate seasonal demand in Valencia and Murcia agricultural clusters. Fraikin Limited competes with flexible rental terms calibrated to these discrete windows. Southern European logistics corridors retain vapor compression systems for cost-sensitive frozen food transport.
Poland
Central European food processing clusters lack sufficient refrigerated rental density relative to throughput growth. The EU Green Deal fleet renewal incentives compress payback periods for rental providers investing in hybrid units. Warsaw and Łódź distribution hubs present white space for fleet deployment.
Europe Refrigerated Truck Rental Market Key Industry Players
Listed leaders compete with private specialists across pan-European service coverage and specialized cold chain expertise. The vendor base fragments across three tiers: pan-European networks with maintenance integration, regional specialists with temperature-validated fleets, and asset-light brokers losing share to bundled providers. Two strategic archetypes dominate: integrated cold chain operators bundling equipment, maintenance, and compliance certification; and flexible rental specialists aligning contract structures to seasonal agricultural cycles. Competitive moves concentrate on geographic expansion into underpenetrated Central European corridors and technology convergence of telematics with predictive maintenance capabilities.
Among pan-European rental networks, TIP Group leverages its service infrastructure to sustain maintenance coverage for multi-temperature units, while Fraikin Limited occupies a position calibrated to flexible contract structures. Petit Forestier exemplifies the specialized cold chain archetype through concentrated expertise in pharmaceutical and fresh produce temperature validation. These three anchors represent distinct competitive vectors: scale-driven network coverage, contractual flexibility, and segment-specific technical depth.
| Leading Market Players |
|---|
| Penske Corporation, Inc. |
| TIP Group |
| Ryder System, Inc. |
| LAMBERET SAS |
| Polar Leasing, Inc. |
| Petit Forestier |
| The Hertz Corporation |
| KRONE |
| Fraikin Limited |
| Others |
Cost & Logistics Intelligence
CE marking thermal performance standards gate both fleet bodybuilder qualification and rate differentiation between certified and uncertified rental providers across European cold chain corridors. The regulation compresses supplier pools while elevating price premiums for pre-validated multi-temperature units that pharmaceutical distributors and food retailers demand.
Pricing Analysis
Food distributors anchor rental rate structures through multi-year contracts with embedded maintenance and compliance certification. Three-tier pricing stratification separates premium hybrid-electric configurations with guaranteed low-emission zone access from standard diesel-mechanical units and economy vapor-compression fleets facing accelerated F-Gas phasedown. Price differentiation rests on ATP certification grade and real-time telematics integration. Cost compression in standard diesel tiers is intensifying as Euro VI compliance escalates ownership economics for self-operated fleets. Caterers and event food service operators exhibit highest price sensitivity, while pharmaceutical logistics companies accept rate premiums for validated cold chain documentation.
Supply Chain Analysis
Low-GWP refrigerant supply concentration in Germany, France, and the Netherlands underwrites fleet technology transition timelines across the continent. R-452A and R-513A production draws from limited European chemical manufacturers, while transcritical CO2 compressor systems rest on specialized component suppliers in Italy and Denmark. Single-source vulnerability in refrigerant allocation exposes rental operators to input cost volatility during F-Gas phasedown acceleration. Distribution runs through pan-European service networks with maintenance integration, compressing spot-market broker participation as food retailers consolidate approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical cold chain expansion represents an early-cycle penetration story as EMA serialization mandates and temperature excursion tracking requirements elevate rental absorption for validated multi-temperature units across continental distribution networks.
For Market Incumbents: Compound defensive positioning through backward integration into transcritical CO2 service technician training programs and captive refrigerant supply agreements. Accelerate fleet renewal in Poland and Czech Republic corridors before subsidy windows compress. The threat of asset-light telematics-native entrants demands pre-emptive predictive maintenance capability deployment. For New Entrants and Emerging Players: ATP certification fast-track for dual-compartment vehicles opens immediate contract viability with Benelux supermarket consolidation networks. White space concentrates in Warsaw and Łódź distribution hubs where refrigerated rental density lags food processing throughput growth. Target mid-size regional food distributors with flexible usage-based billing verified through temperature-hour telematics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid and electric refrigerated fleet segments as EU Green Deal incentives compress equipment payback periods. Long-term viability favors rental operators with integrated maintenance networks and certified low-GWP inventory positions. Acquisition target archetype: regional specialists with temperature-validated pharmaceutical expertise and scalable service infrastructure. The signal to watch is refrigerant allocation priority shifts among European chemical suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Transcritical CO2 Fleet Conversion | Secures low-emission zone access in Berlin, Hamburg, and Amsterdam ahead of diesel restrictions. |
| Predictive Maintenance Platform Deployment | Combines compressor vibration analytics with real-time cargo monitoring for outcome-based contract pricing. |
| Central European Corridor Expansion | Captures underpenetrated Poland and Czech Republic food processing clusters with hybrid unit deployment. |
| Pharmaceutical Validation Service Integration | Bundles temperature documentation and EMA serialization compliance into long-term rental structures. |
| Refrigerant Supply Backward Integration | Locks R-452A and R-513A allocation priority through direct manufacturer agreements during F-Gas phasedown. |
Research Approach
Operator-level perspectives from fleet managers, procurement directors at pharmaceutical distributors, cold chain logistics executives, and refrigerated bodybuilder technical directors anchored the qualitative base. Secondary validation drew from KBA technical inspection records, ECHA REACH substance restriction updates, EU F-Gas Regulation phasedown schedules, and ATP agreement certification databases. Bottom-up fleet deployment modeling triangulated against top-down cold chain logistics spending estimates across the analysis window.
Sensitivity analysis framed volume and value outputs across the projection horizon through multi-dimensional segmentation. The analytical framework modeled truck size configurations, refrigeration technology compliance runways, rental duration structures, and customer procurement sophistication tiers. CAGRs were derived from equipment replacement cycle compression, regulatory mandate timelines, and adoption curve positioning for hybrid and electric configurations. Forecast inputs incorporated LEZ expansion schedules and pharmaceutical serialization mandate enforcement patterns.
Decision-makers should treat outputs as directional under sustained EU Green Deal subsidy availability and F-Gas phasedown adherence; material deviation in refrigerant supply allocation or subsidy program suspension would warrant model refresh. Practitioners should keep alternative scenarios live as low-GWP refrigerant production capacity and battery-electric range economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Bike and Scooter Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Drayage Services Market
Transportation Services
Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Global Taxi Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Refuse Truck Market
Transportation Services
Driving Vacation Market