
 Asia-Pacific Rickshaw Ride Hailing Service Market | 2026-2036
Asia-Pacific Rickshaw Ride Hailing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rickshaw Ride Hailing Service Market Outlook
A capital-intensity divergence between asset-light platform operators and fleet-owning incumbents is redrawing competitive boundaries across the Asia-Pacific rickshaw hailing landscape. Grab leverages its super-app infrastructure to bundle ride hailing with food delivery and financial services across Southeast Asian markets. Ola Cabs anchors its position through deep driver-network density in Indian urban corridors. Jugnoo specializes in tier-two and tier-three city penetration, sustaining growth where larger platforms compete less aggressively.
The Asia-Pacific Rickshaw Ride Hailing Service encompasses digitally intermediated on-demand transportation using motorized three-wheelers, typically powered by compressed natural gas, liquefied petroleum gas, or lithium-ion battery packs with 3-5 kilowatt-hour capacity, designed for short-haul passenger movement through congested urban thoroughfares. Electric service variants now command disproportionate regulatory attention and infrastructure investment as cities impose emission curbs on legacy two-stroke fleets. Mobile app technology dominates customer acquisition channels, while GPS tracking enables route optimization and safety monitoring that prepaid payment models cannot deliver without. Shared ride configurations attract price-sensitive commuters, though premium service tiers capture disproportionate margin pools from airport transfers and tourist segments.
India's Ministry of Road Transport and Highways enforces motor vehicle type-approval standards that rickshaw manufacturers must satisfy, while the country's FAME subsidy framework directly shapes fleet procurement economics for platform operators. Bangladesh's Bangladesh Road Transport Authority governs three-wheeler route licensing and driver permit issuance, constraining market entry density in Dhaka. Stakeholders must monitor how Indonesia's Ministry of Transportation adapts ride-hailing regulations to Gojek's expanding two-wheeler and three-wheeler services across Jakarta and Surabaya.
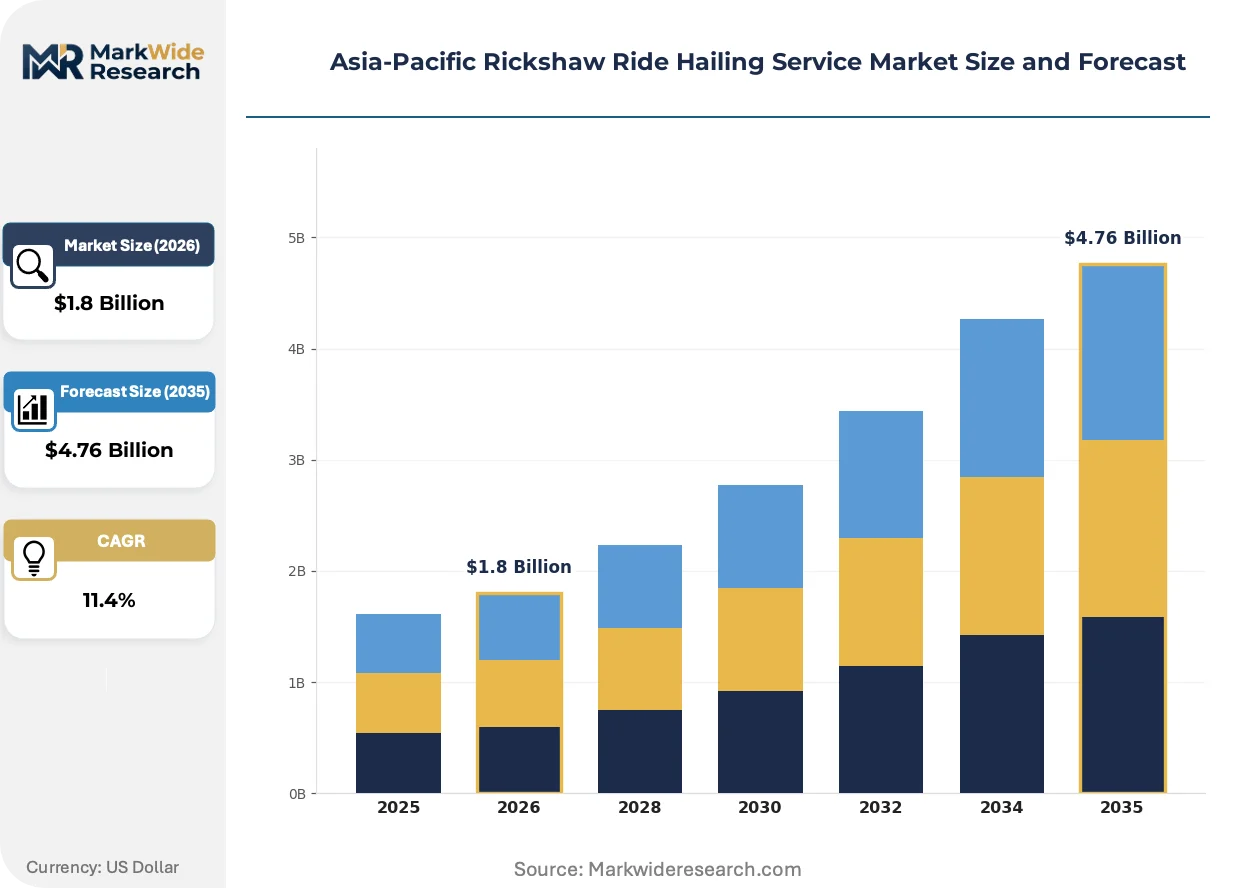
Market Dynamics
Fleet electrification mandates and QR-based payment infrastructure are compressing operating margins for combustion-engine operators while rewarding platforms that integrate battery-swapping networks with digital wallets.
Growth Catalysts
- FAME subsidy framework:India's production-linked incentive scheme for electric vehicle procurement reduces capital outlay for battery-powered three-wheeler acquisition by platform operators.
- Dhaka metropolitan density:Severe traffic congestion and narrow street infrastructure in Bangladesh's capital sustain structural demand for compact three-wheeler mobility.
- Lithium-ion battery cost curves:Declining cell prices for 3-5 kilowatt-hour packs enable total-cost-of-ownership parity with CNG and LPG alternatives across Indian urban corridors.
Market Restraints
- Driver permit scarcity:Bangladesh Road Transport Authority constraints on three-wheeler route licensing limit fleet expansion velocity in Dhaka.
- Battery degradation uncertainty:Rapid charge-cycle wear on low-cost lithium cells elevates replacement cost volatility for electric fleet operators.
- Two-stroke legacy overhang:Surplus refurbished petrol engines from informal secondary markets undercut new electric vehicle economics in price-sensitive segments.
Strategic Opportunities
- Tier-two India penetration:Cities like Jaipur, Lucknow, and Indore present underpenetrated demand corridors where platform density remains below saturation thresholds.
- Battery-as-a-service models:Swappable powerpack subscriptions decouple vehicle ownership from energy infrastructure, lowering driver entry barriers.
- Airport transfer premium tiers:Tourist corridors in Bali, Phuket, and Goa generate disproportionate margin pools through fixed-price premium booking channels.
Industry Challenges
- Driver onboarding friction:Document verification and vehicle inspection protocols stretch platform recruitment timelines across multiple municipal jurisdictions.
- Interoperability gaps:Proprietary QR code systems prevent wallet-agnostic payment acceptance, fragmenting transaction liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rickshaw Ride Hailing Service Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard, Premium, Electric, Shared Payment Model: Pay-Per-Ride, Subscription, Prepaid, Corporate Customer Type: Tourists, Commuters, Students, Local Residents Technology: Mobile App, GPS Tracking, Digital Payments, Ride Analytics |
| Companies Covered | Uber Technologies Inc, Jugnoo, Grab, Mauto Electric Mobility Pvt Ltd, e-Yana, Gojek, DiDi Chuxing, SmartShift Logistics Solutions Pvt Ltd, Ola Cabs, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rickshaw Ride Hailing Service Market Strategic Shifts
Technology convergence between GPS tracking, digital payments, and battery monitoring is compressing the operational gap between asset-light platforms and fleet-owning incumbents across Southeast Asian and South Asian corridors.
Swappable battery architecture is fragmenting traditional fleet ownership models. Battery-swapping stations enable drivers to lease powerpacks by the kilometer rather than purchasing capital-intensive lithium-ion assets outright. Platform operators in Indian megacities deploy modular swap infrastructure at petrol pump forecourts and metro station peripheries, decoupling vehicle uptime from overnight charging cycles.
Indonesia's Ministry of Transportation is adapting ride-hailing regulations to encompass three-wheeler services through revised route licensing and safety certification requirements. The regulatory expansion forces platform compliance investments in driver training and vehicle inspection protocols. Gojek's Jakarta and Surabaya operations face accelerated compliance timelines as the ministry phases in mandatory GPS tracking and digital trip logging.
Commuter preference is rotating toward shared-ride configurations as price sensitivity intensifies across Bangladeshi and Indian urban corridors. Solo-hailing premium tiers cede volume to pooled services that aggregate multiple passengers along similar vectors. Airport transfer and tourist segments remain the exception, where fixed-price premium bookings sustain margin extraction in Bali, Phuket, and Goa resort corridors.
Asia-Pacific Rickshaw Ride Hailing Service Market Segmentation
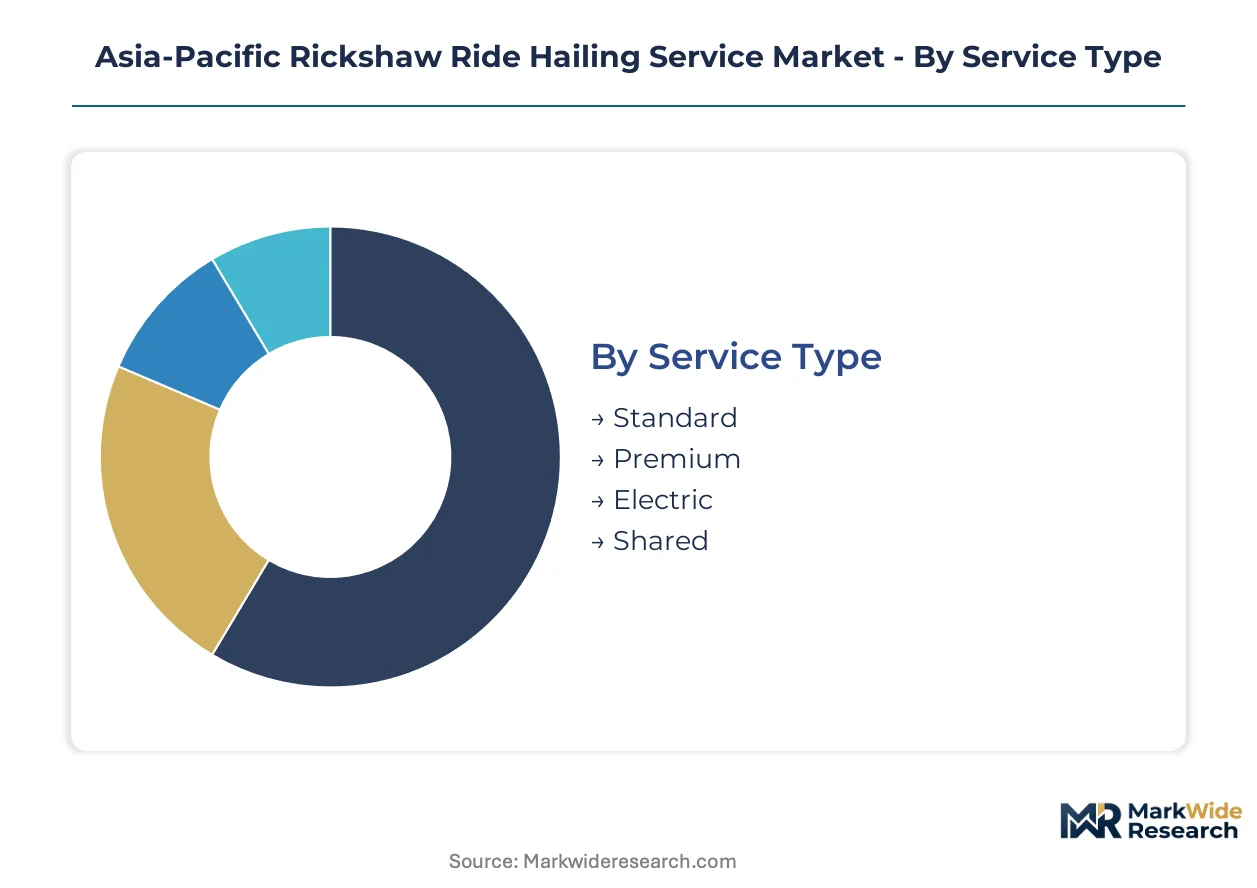
Segmentation reveals how margin pools concentrate across service tiers and payment modalities in Asia-Pacific rickshaw hailing. Platform operators calibrate fleet composition and pricing architecture to capture divergent willingness-to-pay across Indian megacities and Bangladeshi urban corridors.
Service Type:
Premium and electric service tiers extract disproportionate margins from airport transfers and regulatory-compliant fleet renewals, while standard combustion-engine services compete on volume density.
- Standard:Compressed natural gas and liquefied petroleum gas three-wheelers dominate trip volume across Mumbai and Delhi corridors. Dhaka's narrow street infrastructure sustains structural demand for these compact vehicles despite emission pressures.
- Premium:Fixed-price bookings with guaranteed vehicle quality and trained drivers command elevated fares in tourist corridors including Bali, Phuket, and Goa resort clusters. Airport transfer routes generate the highest per-trip margins.
- Electric:Battery-powered variants with 3-5 kilowatt-hour lithium-ion packs attract FAME subsidy support and regulatory preference in Indian urban markets.
- Shared:Pooled configurations aggregate multiple passengers along similar vectors, compressing per-rider fares while maximizing asset utilization in price-sensitive segments.
Standard service holds installed capacity. Electric is rotating up the share rankings.
Payment Model:
Subscription and corporate arrangements lock in predictable revenue streams, insulating platforms from per-trip demand volatility in seasonal tourist markets.
- Pay-Per-Ride:QR-based digital wallet integration dominates transaction flow across Indian and Bangladeshi urban corridors. UPI infrastructure enables instant settlement without proprietary platform lock-in.
- Subscription:Monthly unlimited-ride packages reduce marginal cost perception for daily commuters in Jakarta and Surabaya. Gojek's super-app bundling accelerates adoption velocity.
- Prepaid:Wallet top-up mechanisms with promotional bonus credits improve working capital position for platform operators.
- Corporate:Enterprise contracts with fixed monthly billing serve employee transportation needs across Indian IT corridors and Bangladeshi garment manufacturing zones.
Pay-per-ride maintains transaction dominance. Subscription models are climbing the fastest in revenue contribution.
Customer Type:
Commuter segments drive weekday volume consistency, while tourists concentrate margin extraction in narrow seasonal windows.
- Tourists:Foreign visitors in Thai and Indonesian resort destinations accept 3-5x fare multiples for English-speaking drivers and fixed-price certainty. Premium booking channels capture this demand.
- Commuters:Daily office workers across Dhaka and Indian tier-one cities generate predictable morning-evening peak demand. Metro station last-mile connectivity represents the highest-frequency use case.
- Students:Discounted fare tiers with verified institutional email requirements penetrate university towns including Pune, Bangalore, and Dhaka's Dhanmondi district.
- Local Residents:Price-sensitive non-commuting trips for shopping and social visits sustain off-peak utilization rates.
Commuters anchor weekday capacity planning. Tourist segments exhibit steepest expansion trajectory in margin-per-trip metrics.
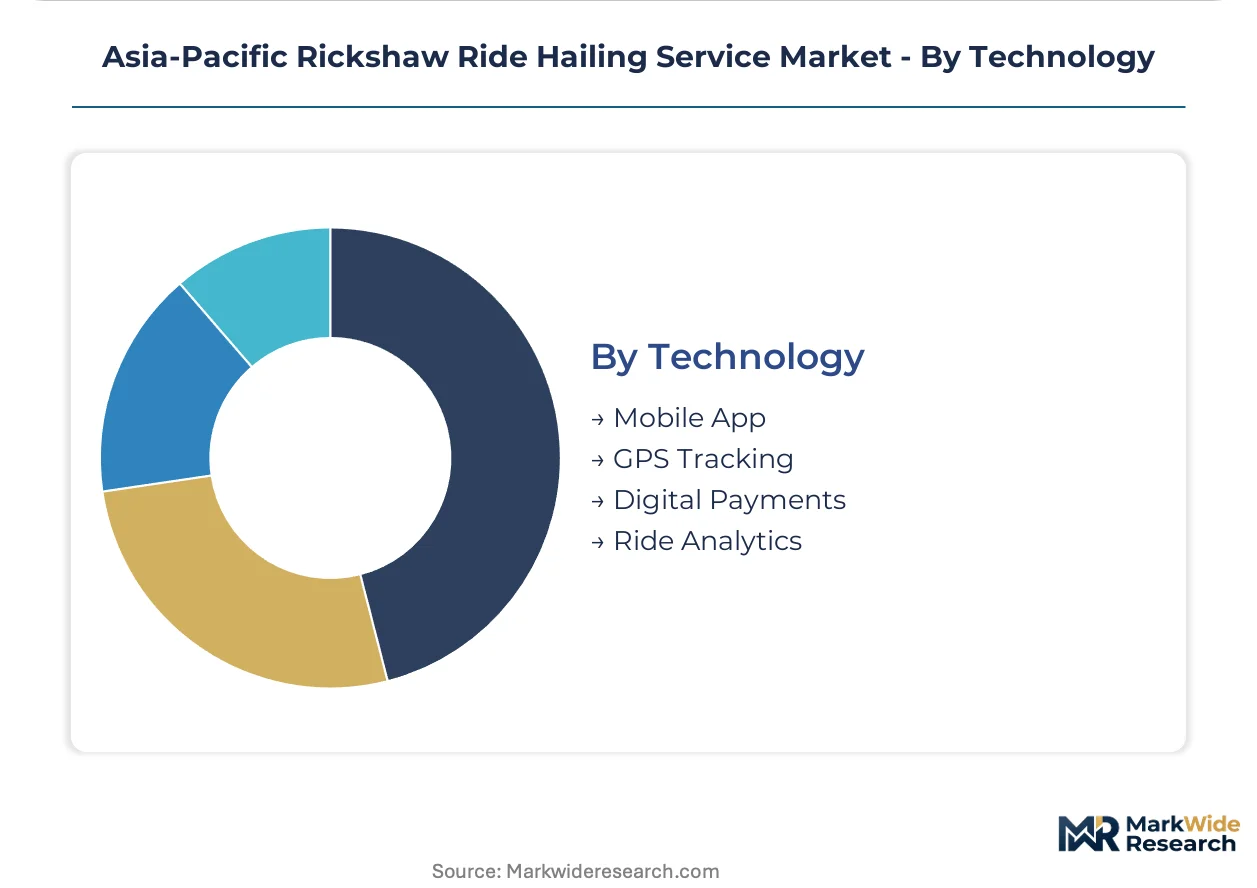
Technology:
GPS tracking and digital payment infrastructure now constitute baseline competitive hygiene rather than differentiation vectors.
- Mobile App:Native iOS and Android applications with real-time vehicle tracking and ETA prediction dominate customer acquisition. Super-app bundling with food delivery improves retention economics.
- GPS Tracking:Mandatory trip logging under Indonesian Ministry of Transportation regulations forces platform investment in driver device subsidies and data compliance infrastructure.
- Digital Payments:UPI, bKash, and proprietary wallet integration eliminates cash handling friction and enables dynamic pricing algorithms.
- Ride Analytics:Demand forecasting and route optimization engines reduce deadheading kilometers and improve driver earnings per hour.
Mobile app penetration saturates urban markets. Ride analytics capabilities are gaining share fastest as competitive differentiators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform operators export digital payment infrastructure and fleet management software while importing lithium-ion battery packs and vehicle chassis from Chinese manufacturing clusters. Trade flows concentrate technology licensing revenues in Singapore and Bangkok headquarters while production hardware moves through Shenzhen and Ningbo ports.
India
Mumbai and Delhi corridors generate the highest trip densities for last-mile metro connectivity. The Ministry of Road Transport and Highways enforces motor vehicle type-approval standards that shape manufacturer compliance costs. Bengaluru and Hyderabad clusters host platform engineering centers developing route optimization algorithms for tier-two city expansion.
Bangladesh
Dhaka's narrow street infrastructure sustains structural demand for compact three-wheeler mobility through severe congestion corridors. The Bangladesh Road Transport Authority constrains fleet expansion through route licensing and driver permit scarcity. Chittagong's port zone exhibits growing commuter demand from garment manufacturing employment clusters.
Indonesia
Jakarta and Surabaya operations face accelerating compliance timelines under revised three-wheeler service regulations. The Ministry of Transportation mandates GPS tracking and digital trip logging for platform operators. Bali's tourist corridors generate premium-tier margin pools through fixed-price airport transfer bookings.
Thailand
Phuket and Bangkok resort destinations concentrate foreign visitor demand for English-speaking driver services. The Department of Land Transport governs three-wheeler commercial licensing and safety inspection protocols. Chiang Mai's university district shows emerging subscription model adoption among student commuters.
Vietnam
Ho Chi Minh City's dense urban core drives app-based hailing adoption for short-haul passenger movement. The Ministry of Transport regulates ride-hailing platforms through Decree 10 compliance requirements for driver certification. Da Nang's coastal tourism zone presents underdeveloped premium service tier opportunities.
Asia-Pacific Rickshaw Ride Hailing Service Market Competitive Environment
Concentration sits with super-app operators bundling mobility with financial services and food delivery. The competitive structure fragments between asset-light technology platforms and fleet-owning incumbents managing driver networks directly. Two strategic archetypes dominate: infrastructure-heavy aggregators optimizing for trip density, and vertical specialists penetrating tier-two markets where larger platforms compete less aggressively. Dominant competitive moves include battery-swapping network partnerships and QR-wallet integration deepening payment ecosystem lock-in.
Among India-based mobility platforms, Jugnoo, Ola Cabs, and SmartShift Logistics Solutions Pvt Ltd exemplify contrasting scale strategies. Jugnoo occupies a position within the tier-two penetration archetype, targeting cities like Jaipur and Lucknow where network density remains below saturation. Ola Cabs anchors the megacity infrastructure tier through deep driver-network deployment across Mumbai and Delhi corridors. SmartShift Logistics Solutions Pvt Ltd represents the logistics-adjacent specialization vector, extending three-wheeler utility into freight movement beyond passenger services.
| Leading Market Players |
|---|
| Uber Technologies Inc |
| Jugnoo |
| Grab |
| Mauto Electric Mobility Pvt Ltd |
| e-Yana |
| Gojek |
| DiDi Chuxing |
| SmartShift Logistics Solutions Pvt Ltd |
| Ola Cabs |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of chassis inventory at Indian assembly plants compresses working capital cycles while amplifying pricing leverage for lithium-ion pack integrators serving platform operators. This lead-time band concentrates procurement power among fleet aggregators with swap-network scale, forcing smaller operators toward refurbished two-stroke alternatives.
Pricing Analysis
The customization-premium spread between configured-to-order electric fleet packages and standard CNG vehicle procurement runs wide across Dhaka and Indian tier-one corridors. Three-tier pricing structure across premium, standard, and economy levels segments by battery certification grade and driver training tier. Cost compression in the economy segment intensifies because informal secondary markets flood refurbished petrol engines. Daily commuters exhibit highest price sensitivity, while tourist airport transfers tolerate 3-5x fare multiples.
Supply Chain Analysis
Shenzhen-Ningbo port congestion periodically chokes lithium-cell import velocity into Indian assembly hubs. China, South Korea, and Taiwan supply concentrated lithium-ion cell capacity, while Bangladesh and Vietnam provide CNG conversion kit manufacturing. The chain rests on nickel-manganese-cobalt cathode chemistry and rare-earth magnet motors. Single-source vulnerability sits with Chinese battery management system controllers. Distribution runs through platform-operated swap stations and traditional petrol pump forecourts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
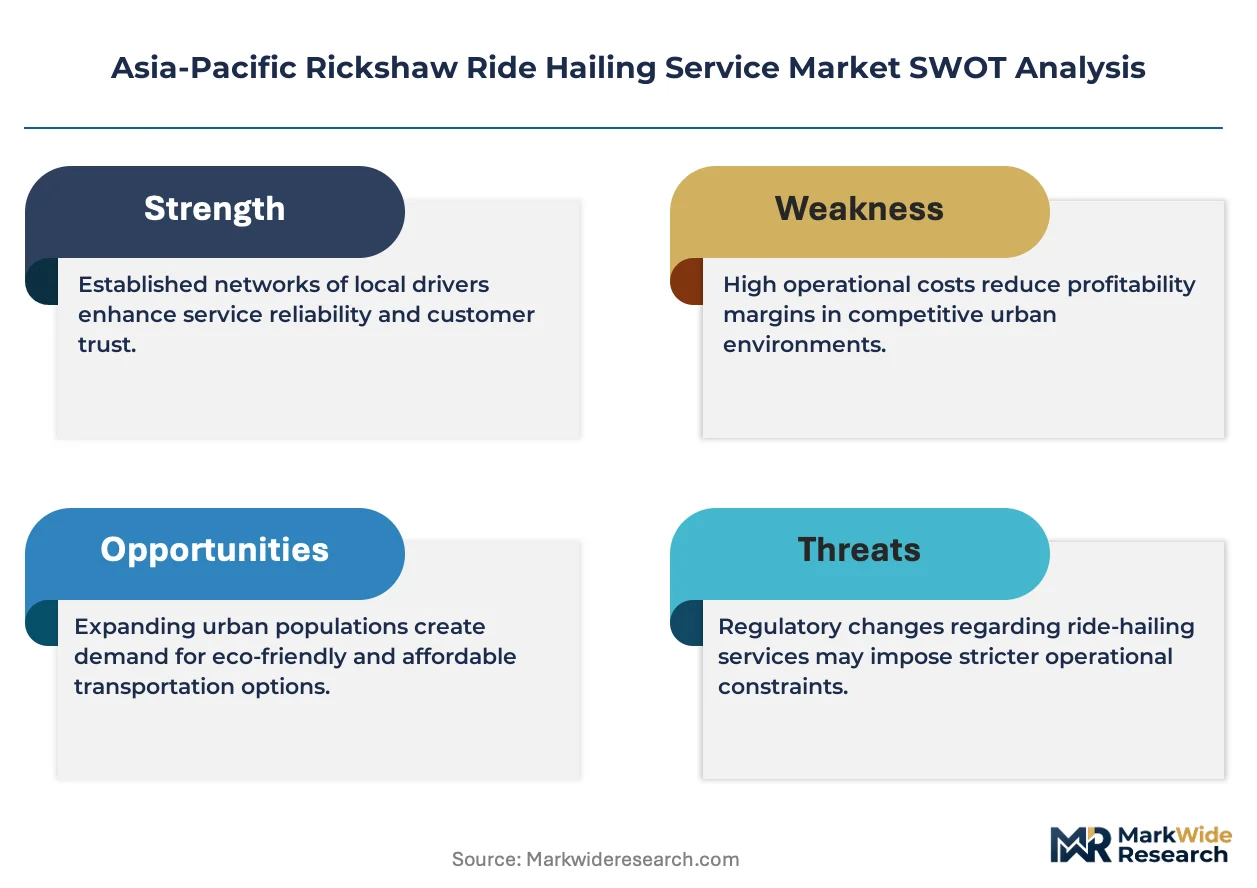
Asia-Pacific rickshaw ride hailing sits in early-cycle expansion as FAME subsidy frameworks and QR-wallet penetration in tier-two Indian cities accelerate platform adoption beyond megacity saturation points.
For Market Incumbents: Shield fleet renewal economics by locking long-term lithium-cell offtake agreements before commodity volatility intensifies. Deepen driver-network density in Dhaka permit-constrained corridors to raise rival entry barriers. Battery-as-a-service subscriptions represent the critical defensive lever against asset-light challengers. For New Entrants and Emerging Players: Lead with battery-swapping infrastructure partnerships in Jaipur, Lucknow, and Indore where platform density remains below commuter demand thresholds. Target corporate employee transportation contracts in Indian IT corridors for predictable revenue anchoring. White-label fleet management software for traditional owner-operator associations offers lowest-friction go-to-market positioning. For Investors and Strategic Acquirers: Long-term, this sits as a platform-aggregation play because swap-network scale and payment ecosystem lock-in concentrate returns toward infrastructure-heavy operators. Acquisition targets should display captive driver density in permit-scarce Bangladeshi routes and integrated wallet transaction flow. Monitor Indonesia Ministry of Transportation compliance timeline acceleration as the signal for regulatory-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Network Expansion | Swap-station density at metro peripheries decouples driver capital barriers from fleet electrification mandates. |
| QR-Wallet Payment Integration | UPI and bKash interoperability deepens transaction liquidity beyond proprietary platform lock-in. |
| Tier-Two City Geographic Expansion | Jaipur and Indore penetration captures underexploited commuter demand before rival density saturation. |
| Corporate Transportation Contracting | Enterprise billing arrangements insulate revenue from seasonal tourist demand volatility. |
| Driver Permit Portfolio Acquisition | Bangladesh Road Transport Authority scarcity makes permit holdings strategic moat assets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade databases, and platform operator disclosures across Indian, Bangladeshi, and Indonesian markets. Interviews with fleet operations managers, driver cooperative leaders, battery swap station operators, and municipal transport regulators informed demand-side assumptions. Secondary validation drew from Ministry of Road Transport and Highways type-approval records, Bangladesh Road Transport Authority permit issuance data, and Indonesia Ministry of Transportation regulatory circulars. Bottom-up trip-volume estimates triangulate against top-down fleet size and utilization rate benchmarks.
Segmentation dimensions modeled span service tier, payment modality, customer archetype, and propulsion technology across the projection horizon. Electric service share trajectories incorporate FAME subsidy phase-out schedules and lithium-cell cost curve assumptions. Driver permit scarcity constraints in Dhaka and Jakarta compliance timeline acceleration represent industry-specific forecast inputs. CAGRs derive from logistic diffusion curves fitted to observed adoption velocities in comparable mobility platform markets.
Forecasts assume regulatory continuity in Indian FAME frameworks and Bangladeshi route licensing regimes; material subsidy elimination or permit issuance liberalization would require re-modeling. Battery degradation rate uncertainty and informal two-stroke engine import enforcement volatility constitute specific revision risks. Practitioners should keep alternative scenarios live as Indonesia Ministry of Transportation GPS mandate implementation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Driving Vacation Market
Transportation Services
United States Car Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Brazil Car Rentals Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Peer-To-Peer (P2P) Car-Sharing Market
Transportation Services
Car Rental Service Market
Transportation Services
Car Rental Market
Transportation Services
Corporate Car Sharing Market