
 Europe Van Rental Market | 2026-2036
Europe Van Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Van Rental Market Foresight
SME logistics operators is unwinding the traditional dominance of large corporate fleet buyers in contract structures. Europcar Mobility Group leverages its urban hub density to capture last-mile delivery demand. Fraikin SAS anchors long-term leasing relationships with cold-chain transporters. Sixt SE competes through premium service tiers targeting executive shuttle segments.
Europe van rental encompasses the short-to-medium term provision of commercial and passenger vans through contractual or on-demand arrangements, with vehicle specifications ranging from sub-3.5-tonne light commercial vans to heavy-duty configurations exceeding 12 tonnes gross vehicle weight, typically governed by EU Whole Vehicle Type Approval frameworks. The primary commercial purpose centers on providing flexible capacity without capital commitment for businesses facing seasonal demand volatility or route expansion. Light commercial vans lead volume throughput due to their ubiquity in urban parcel delivery, while long-term rental structures capture the most stable margin pools through multi-year maintenance-inclusive contracts. Self-drive arrangements represent the fastest-growing usage category as digital check-in platforms reduce counter friction for business users.
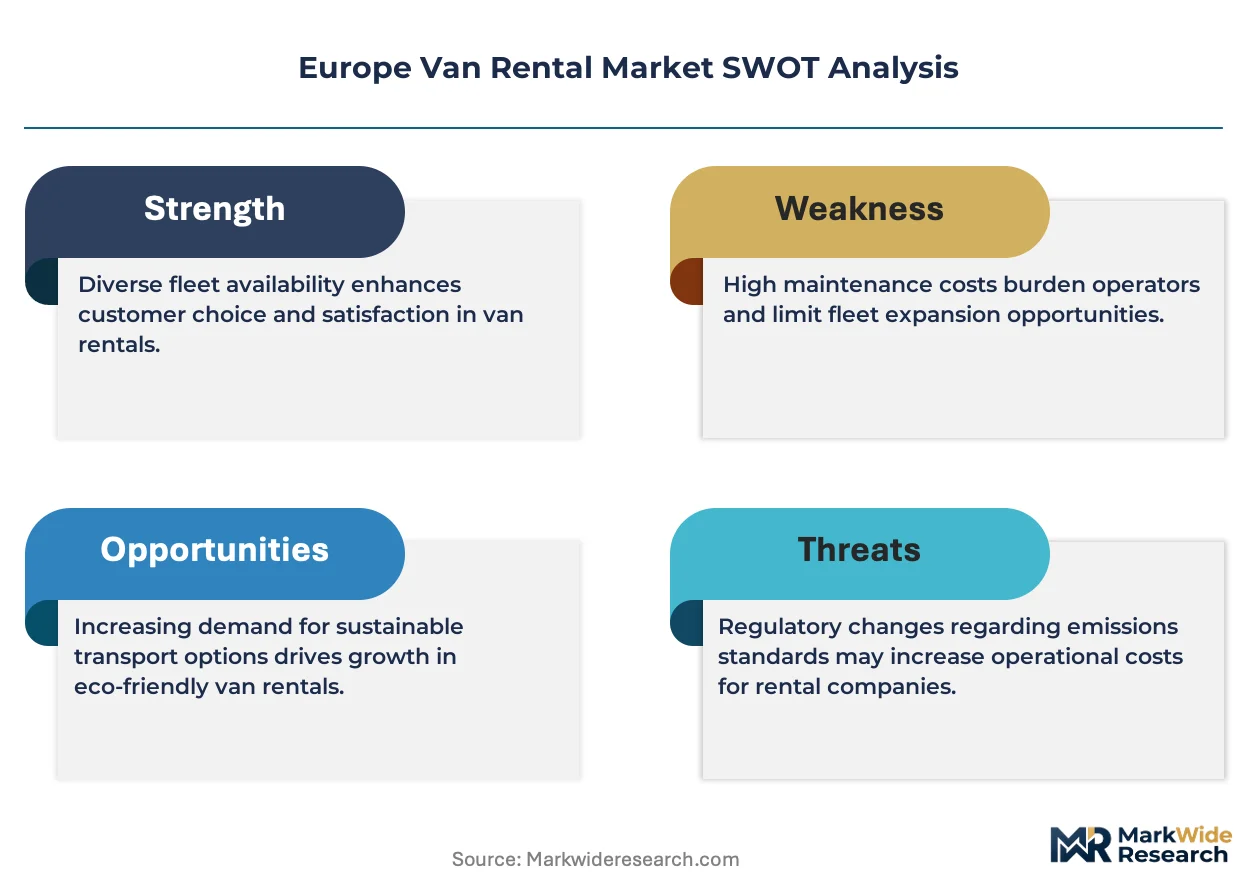
EU Green Deal emission benchmarks and CE marking requirements under the EU Vehicle Type Approval system are reshaping fleet procurement timelines toward zero-emission van models. ECHA chemical compliance for battery supply chains adds secondary compliance layers for rental operators electrifying holdings. National regulators in France, Germany, and Italy enforce divergent low-emission zone access rules that fragment cross-border fleet deployment strategies. Stakeholders must monitor how pending Euro 7 standards recalibrate total cost of ownership calculations across diesel, electric, and hydrogen van portfolios.
Market Dynamics
The EU Green Deal's CO2 emission targets for commercial vehicles are compressing fleet procurement timelines toward zero-emission van models while fragmenting cross-border deployment strategies across divergent national low-emission zone frameworks.
Growth Catalysts
- E-commerce logistics expansion:Parcel delivery operators across France, Germany, and the Netherlands are scaling rental contracts to match seasonal demand volatility without capital commitment.
- EU Green Deal mandates:The regulatory framework is accelerating electrification decisions among fleet operators facing 2030 emission benchmarks for commercial vehicles.
- Digital check-in platforms:Self-drive arrangements are reducing counter friction for SME logistics operators seeking flexible urban hub access.
Market Restraints
- Battery supply chain concentration:ECHA chemical compliance requirements for battery supply chains add secondary cost layers for rental operators electrifying holdings.
- Cross-border regulatory fragmentation:Divergent low-emission zone access rules enforced by national regulators in France, Germany, and Italy complicate fleet deployment optimization.
- Total cost of ownership uncertainty:Pending Euro 7 standards recalibrate depreciation calculations across diesel, electric, and hydrogen van portfolios.
Strategic Opportunities
- Urban cold-chain specialization:Temperature-controlled last-mile delivery represents an underpenetrated segment within European metropolitan logistics corridors.
- CE marking alignment:The EU Vehicle Type Approval system creates compliance advantages for rental operators standardizing zero-emission fleets ahead of competitors.
- Subscription-based maintenance bundling:Long-term rental structures can deepen customer retention through predictive service integration and telematics-enabled uptime guarantees.
Industry Challenges
- Technician electrification skills gap:Fleet maintenance networks require retraining programs to service high-voltage battery systems and thermal management components.
- Legacy fleet depreciation compression:Residual value uncertainty for internal combustion engine vans is compressing remarketing timelines and collateral values.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Van Rental Market |
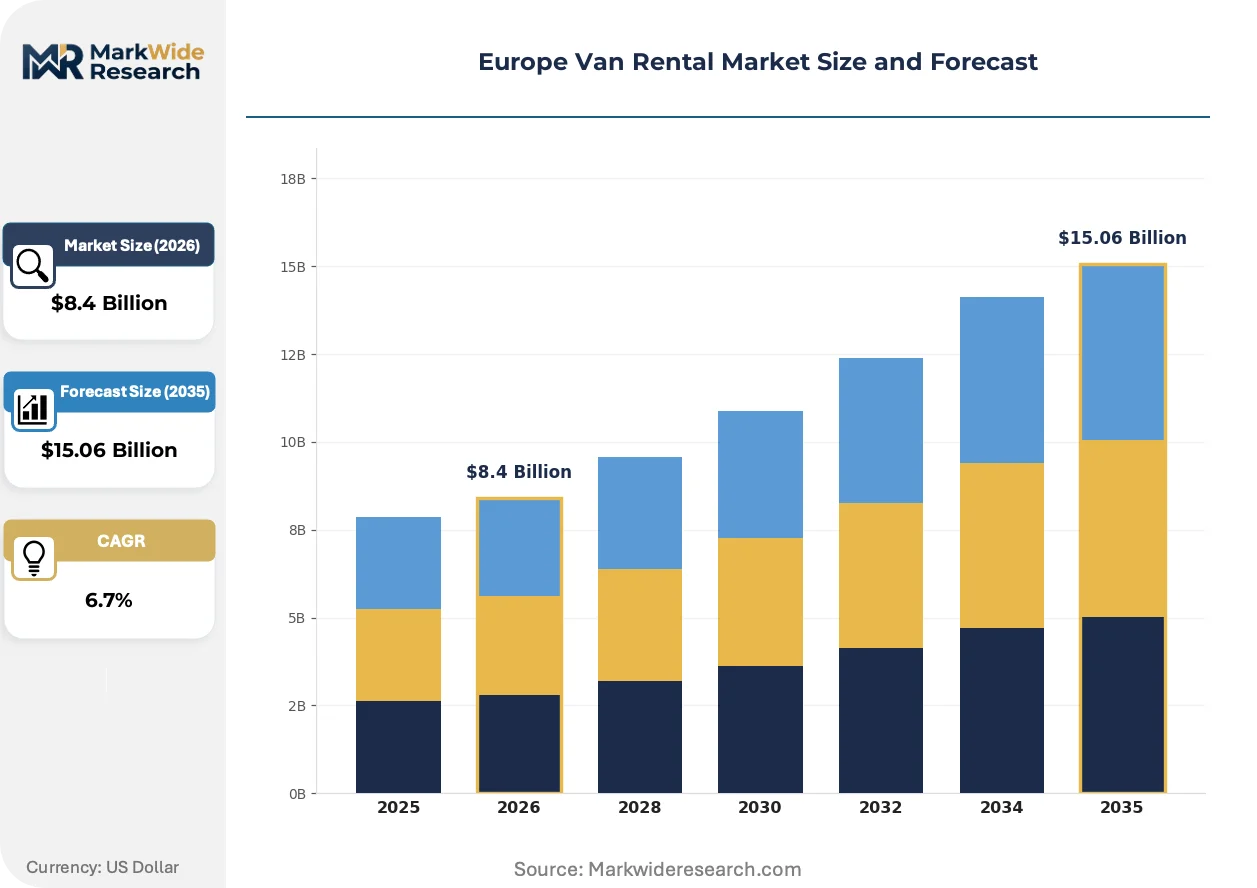
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Commercial Vans, Heavy Duty Vans, Minivans, Cargo Vans Usage Type: Short-Term Rental, Long-Term Rental, Self-Drive, Chauffeur-Driven End User: Corporate Clients, Individual Consumers, Government Agencies, Non-Profit Organizations Distribution Channel: Online Booking, Travel Agents, Direct Sales, Franchise Networks |
| Companies Covered | Avis Budget Group, Fraikin SAS, Europcar Mobility Group, OK Mobility Group, LeasePlan Corporation, Sixt SE, Hertz Global Holdings Inc, Ryder System, Inc., Enterprise Holdings, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Van Rental Market Shifts & Advancements
Telematics integration is compressing rental contract structures toward usage-based pricing models while enabling predictive maintenance bundling that reshapes operator economics across European logistics corridors.
Telematics hardware is miniaturizing to embed directly into van chassis architectures without aftermarket installation overhead. SME logistics operators are adopting these factory-integrated systems at accelerating pace to reduce insurance premiums and optimize route efficiency. The technology is miniaturizing total cost visibility for rental providers, enabling real-time asset utilization tracking that compresses pricing differentiation between short-term and long-term contract structures.
The EU Green Deal's CO2 emission benchmarks for commercial vehicles are mandating fleet electrification timelines that compress diesel van procurement windows. Rental operators face stranded asset risk on internal combustion engine holdings as national regulators in France, Germany, and Italy accelerate low-emission zone expansion. Cold-chain transporters and urban parcel delivery fleets are responding by front-loading electric van adoption into 2026-2028 contract renewals ahead of regulatory deadlines.
Usage-based rental contracts are displacing fixed-term structures among SME logistics operators seeking seasonal capacity flexibility. Digital platforms are disrupting traditional counter-based check-in processes, with self-drive arrangements capturing volume growth in urban hub networks. This behavioral shift is most visible in the Netherlands and German metropolitan corridors where e-commerce delivery density supports per-kilometer pricing models.
Europe Van Rental Market Segmentation
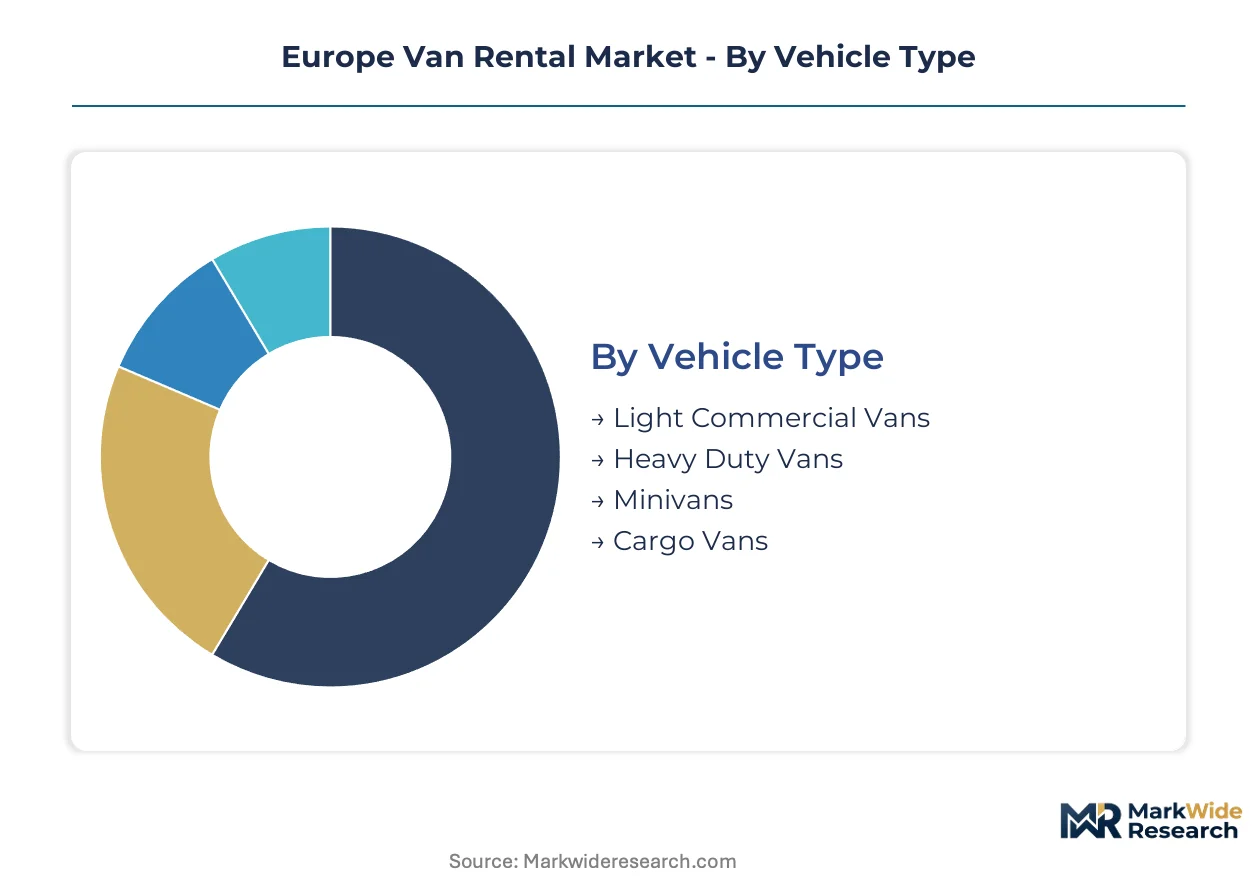
Segmentation in the Europe van rental market reveals how regulatory frameworks, operational requirements, and customer procurement patterns create distinct competitive arenas. Rental operators must align fleet composition and contract structures with the specific compliance and flexibility demands of each segment cluster.
Vehicle Type:
EU Whole Vehicle Type Approval frameworks and divergent national low-emission zone rules fragment procurement strategies across weight classifications and powertrain configurations.
- Light Commercial Vans:Sub-3.5-tonne configurations dominate urban parcel delivery corridors in France, Germany, and the Netherlands. E-commerce logistics operators concentrate rental demand here, driven by EU Green Deal emission benchmarks compressing diesel procurement timelines toward electric alternatives.
- Heavy Duty Vans:Exceeding 12 tonnes gross vehicle weight, these units serve cold-chain transporters and specialized freight corridors. Fraikin SAS anchors long-term leasing relationships in this tier, though cross-border regulatory fragmentation complicates fleet deployment across French, German, and Italian low-emission zone boundaries.
- Minivans:Passenger-focused configurations target executive shuttle segments and small-group mobility. Sixt SE competes through premium service tiers in this category.
- Cargo Vans:Enclosed load-space designs serve SME logistics operators seeking flexible capacity without capital commitment.
Light commercial vans handle the majority of throughput; heavy duty vans are gaining share fastest as cold-chain specialization deepens.
Usage Type:
Contract duration and driver control arrangements determine margin stability and asset utilization rates across European rental networks.
- Short-Term Rental:Daily or weekly arrangements serve seasonal demand volatility in e-commerce logistics. Digital check-in platforms reduce counter friction for business users seeking immediate urban hub access.
- Long-Term Rental:Multi-year maintenance-inclusive contracts capture the most stable margin pools. Predictive service integration and telematics-enabled uptime guarantees deepen customer retention in this tier.
- Self-Drive:Digital platforms are disrupting traditional counter-based processes. This arrangement is expanding most quickly in Dutch and German metropolitan corridors where per-kilometer pricing models align with delivery density.
- Chauffeur-Driven:Professional driver provision targets executive shuttle segments and specialized logistics requirements where regulatory compliance or cargo sensitivity demands certified operation.
Long-term rental secures the deepest margin pools; self-drive arrangements are climbing the fastest on volume growth.
End User:
Procurement scale and contract complexity separate enterprise fleet buyers from fragmented SME and consumer demand.
- Corporate Clients:Large fleet buyers traditionally dominated contract structures, though SME logistics operators are now unwinding this concentration. Seasonal route expansion and emission compliance drive rental adoption over ownership.
- Individual Consumers:Personal mobility and small-scale relocation needs generate sporadic demand with higher per-transaction margins but lower volume predictability.
- Government Agencies:Public procurement frameworks prioritize CE marking alignment and EU Vehicle Type Approval compliance, creating standardization advantages for rental operators with certified zero-emission holdings.
- Non-Profit Organizations:Budget-constrained operations favor flexible short-term arrangements over capital-intensive fleet ownership.
Corporate clients anchor contract value; government agencies are expanding most quickly on green procurement mandates.
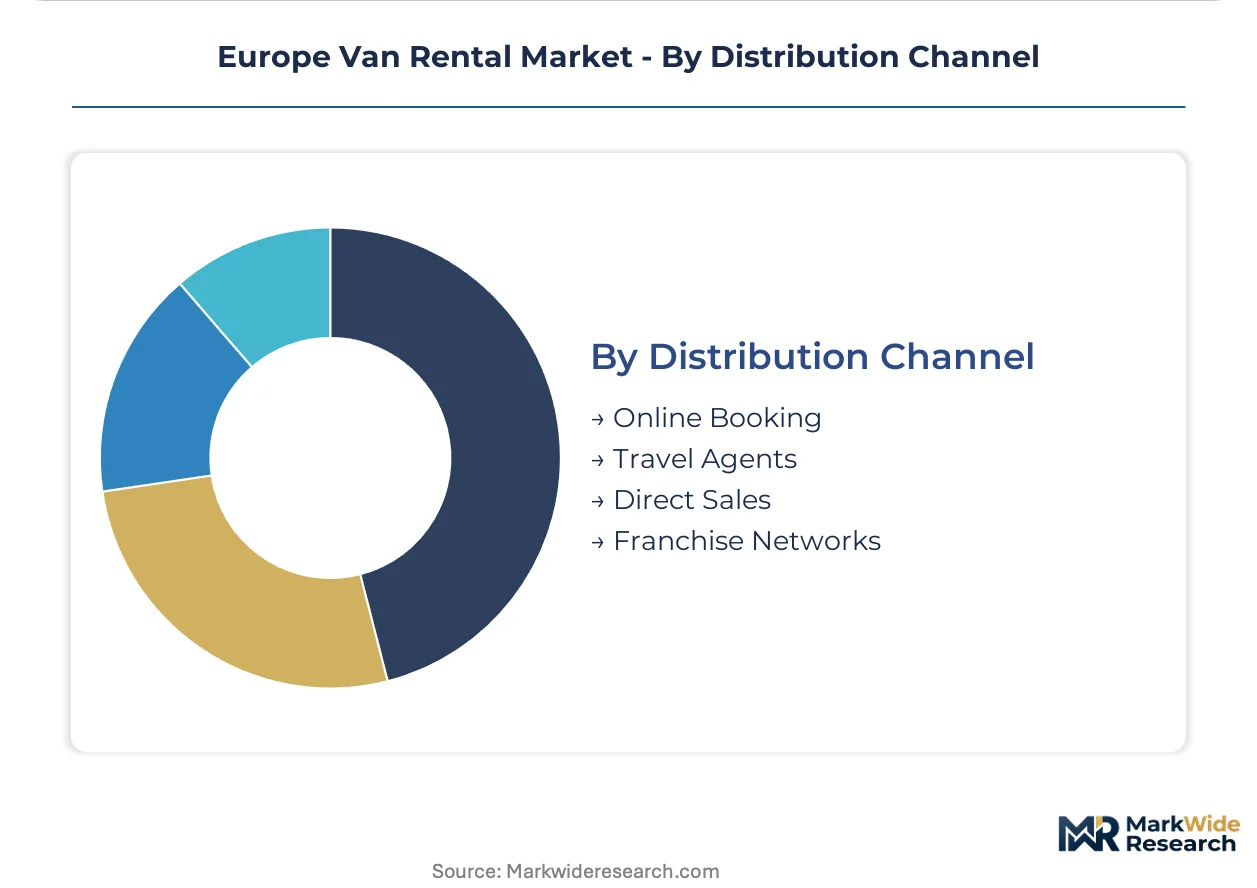
Distribution Channel:
Customer acquisition economics and service touchpoint density vary sharply between digital-first and relationship-driven channels.
- Online Booking:Digital platforms enable real-time fleet visibility and automated contract generation. SME logistics operators adopt these systems to reduce insurance premiums and optimize route efficiency through embedded telematics.
- Travel Agents:Intermediary networks retain relevance in corporate travel management and international logistics coordination where bundled service packaging adds value.
- Direct Sales:Relationship-based acquisition targets large fleet buyers and cold-chain transporters requiring customized maintenance bundling and uptime guarantees.
- Franchise Networks:Europcar Mobility Group leverages urban hub density through this model to capture last-mile delivery demand with localized service presence.
Online booking captures the steepest expansion trajectory; direct sales retains the highest contract values per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SME logistics operators and e-commerce fulfillment networks concentrate rental demand across metropolitan corridors in France, Germany, and the Netherlands, with fleet procurement decisions increasingly shaped by divergent national low-emission zone frameworks.
Germany
Parcel delivery operators in Berlin, Hamburg, and the Rhine-Ruhr corridor are scaling short-term rental contracts to match seasonal e-commerce volatility. The KBA enforces divergent low-emission zone access rules that complicate cross-border fleet deployment into neighboring jurisdictions. Munich and Stuttgart anchor the densest cold-chain logistics clusters, where Fraikin SAS maintains long-term leasing relationships with temperature-controlled transporters.
France
Urban hub networks in Paris, Lyon, and Marseille drive self-drive arrangement growth as digital check-in platforms reduce counter friction for SME operators. ANSM and CNIL oversight intersects with EU Green Deal emission benchmarks to accelerate electric van procurement timelines ahead of 2030 deadlines. The Île-de-France region concentrates the highest rental contract density, with Europcar Mobility Group leveraging franchise networks to capture last-mile delivery demand.
Netherlands
Amsterdam-Rotterdam-The Hague logistics corridors support per-kilometer pricing models that align with exceptional e-commerce delivery density. REACH and ECHA chemical compliance requirements for battery supply chains add secondary cost layers for rental operators electrifying holdings. Eindhoven and Utrecht metropolitan areas exhibit the fastest adoption of telematics-integrated usage-based contracts among SME logistics operators.
Italy
Milan and Rome metropolitan logistics networks face regulatory fragmentation as national low-emission zone expansion accelerates diesel van depreciation timelines. CE marking requirements under the EU Vehicle Type Approval system create compliance advantages for rental operators standardizing zero-emission fleets. Northern Italian industrial corridors around Turin and Bologna anchor heavy-duty van demand from specialized freight operators.
United Kingdom
London's ultra-low emission zone and expanding clean air zones across Birmingham, Manchester, and Bristol compress internal combustion engine fleet viability. The UK's departure from EU regulatory alignment creates parallel compliance tracks for rental operators managing cross-channel fleet deployment. Southeast England logistics clusters exhibit accelerating adoption of subscription-based maintenance bundling through predictive service integration.
Europe Van Rental Market Competitive Landscape
Player mix skews toward multinational mobility conglomerates with diversified fleet portfolios and specialized leasing subsidiaries focused on commercial vehicle segments. Market structure concentrates around three strategic tiers: urban hub density operators capturing last-mile delivery demand, long-term leasing specialists anchoring cold-chain and heavy-duty relationships, and premium service tier providers targeting executive shuttle segments. Dominant competitive moves include telematics-enabled contract restructuring toward usage-based pricing and accelerated electrification of holdings ahead of regulatory deadlines.
Within the multinational mobility tier, Europcar Mobility Group, Sixt SE, and Avis Budget Group exemplify divergent strategic positioning. Europcar represents the urban hub density archetype through franchise network expansion. Sixt occupies the premium service tier targeting executive shuttle segments. Avis Budget Group anchors the diversified portfolio approach spanning short-term and long-term contract structures across European metropolitan corridors.
| Leading Market Players |
|---|
| Avis Budget Group |
| Fraikin SAS |
| Europcar Mobility Group |
| OK Mobility Group |
| LeasePlan Corporation |
| Sixt SE |
| Hertz Global Holdings Inc |
| Ryder System, Inc. |
| Enterprise Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Battery-electric van substitution for diesel fleets is compressing residual value calculations while redrawing procurement geography toward Chinese and South Korean cell manufacturing corridors. This dual displacement simultaneously elevates upfront capital requirements for rental operators and fragments pricing power across divergent national low-emission zone compliance tiers.
Pricing Analysis
Three-tier pricing structure across premium telematics-enabled, standard maintenance-inclusive, and economy self-serve tiers dominates contract structures. Price differentiation hinges on CE marking alignment and volume scale commitments from e-commerce logistics operators. Pricing pressure stems from residual value uncertainty on internal combustion engine holdings as KBA and ANSM accelerate diesel restrictions. SME logistics operators exhibit acute price sensitivity, while cold-chain transporters prioritize uptime guarantees over per-unit rates.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for European van electrification programs. Battery module assembly draws from German and Hungarian manufacturing clusters, with raw material processing concentrated in Indonesian nickel and Chilean lithium corridors. Single-source vulnerability in cathode chemistry supply creates exposure to ECHA REACH compliance disruptions. Distribution runs through OEM captive networks and independent leasing subsidiaries with divergent electrification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where urban hub density creates network effects that entrench incumbent positions against new fleet entrants.
For Market Incumbents: Consolidate urban hub networks in Paris, Berlin, and Amsterdam-Rotterdam corridors to deepen last-mile capture before low-emission zone expansion locks out non-compliant competitors. Acquire specialized cold-chain maintenance capabilities to anchor long-term leasing relationships as Fraikin SAS has demonstrated. Battery supply agreements represent the critical lever for securing electrified fleet rollout timelines ahead of EU Green Deal benchmarks. For New Entrants and Emerging Players: Lead with telematics-native usage-based contracts targeting Dutch and German SME logistics operators underserved by legacy counter-based systems. Urban cold-chain specialization in Milan and Barcelona metropolitan corridors offers the most penetrable white space. Digital check-in platforms with embedded insurance optimization provide the necessary go-to-market differentiation against established franchise networks. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors asset-heavy operators with certified zero-emission holdings and established CE marking pathways. Long-term viability across the analysis window hinges on electrification capex execution rather than fleet scale alone. Acquisition targets should display dense urban hub positioning and predictive maintenance integration; the signal to watch is Euro 7 standard finalization timing and its recalibration of diesel residual curves.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Rollout | CE marking alignment ahead of EU Green Deal deadlines secures cross-border operational flexibility. |
| Telematics Platform Integration | Embedded chassis systems from German OEMs enable per-kilometer pricing models for SME operators. |
| Urban Hub Network Expansion | Franchise density in French and Dutch metropolitan corridors captures e-commerce delivery volume. |
| Cold-Chain Specialization | Temperature-controlled maintenance bundling anchors long-term contracts with ANSM-regulated transporters. |
| Battery Supply Partnership | Direct agreements with South Korean cell manufacturers reduce ECHA compliance cost layers. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors at e-commerce logistics operators, rental network operations managers, and regulatory affairs leads at OEMs, then refined through secondary validation across EU Vehicle Type Approval databases, KBA registration statistics, ANSM cold-chain compliance filings, and ECHA REACH substance inventories. Bottom-up contract volume analysis triangulated against top-down fleet penetration estimates across France, Germany, and the Netherlands.
Variance decomposition across vehicle type, usage duration, powertrain configuration, and end-user scale drove the analytical framework throughout the projection horizon. CAGRs were derived from segment-level fleet replacement cycles and electrification adoption curves. Industry-specific inputs included low-emission zone expansion schedules from national regulators and battery cost trajectory assumptions from cell supply agreements.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated Euro 7 implementation would require recalibration. Forecasts reflect documented assumptions regarding e-commerce logistics growth and residual value depreciation curves for internal combustion engine holdings. Recalibration cycles align with material shifts in emission benchmark deadlines and battery supply chain concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
ASEAN Car Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Australia Taxi Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Truck Sharing Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Brazil Car Rentals Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Enclosed Car Transportation Service Market