
 North America International Express Service Market | 2026-2036
North America International Express Service Market Size, Share, and Industry Trends Forecast 2026-2036
North America International Express Service Market Insights
Canadian carrier networks is broadening transborder sortation capacity ahead of peak season volumes. FedEx Corporation leverages integrated air-ground infrastructure to sustain next-day delivery commitments across the Great Lakes corridor. DHL Express anchors European-North American lane density through its Cincinnati hub operations. Purolator competes on customs pre-clearance specialization for Ontario-Michigan manufacturing flows.
North America International Express Service encompasses time-definite cross-border shipment solutions utilizing integrated air cargo networks, bonded ground fleets, and electronic customs pre-filing systems to enable door-to-door delivery within one to five business days. The service category relies on harmonized tariff classification, advance commercial information filing, and real-time track-and-trace protocols to satisfy commercial and consumer consignees. Air Freight captures premium-margin same-day and next-day commitments for high-velocity manufacturing inputs, while Ground Delivery absorbs mid-tier e-commerce volume through densified line-haul networks. Customs Brokerage represents a margin-accretive attach service as USMCA origin verification complexity rises for automotive and aerospace shippers.
The USMCA Secretariat, Canada Border Services Agency, and US Customs and Border Protection collectively determine duty-de minimis thresholds, rules-of-origin documentation, and entry-type eligibility that shape carrier routing economics and compliance technology investment. The USMCA automotive rules-of-origin phase-in is forcing express providers to deploy enhanced certificate-of-origin validation tools or risk customs delays at Detroit-Windsor and Laredo-Nuevo Laredo gateways. Stakeholders must monitor whether congressional review of de minimis reform advances, as such changes would restructure cross-border parcel economics for e-commerce retailers and their logistics partners.
Market Dynamics
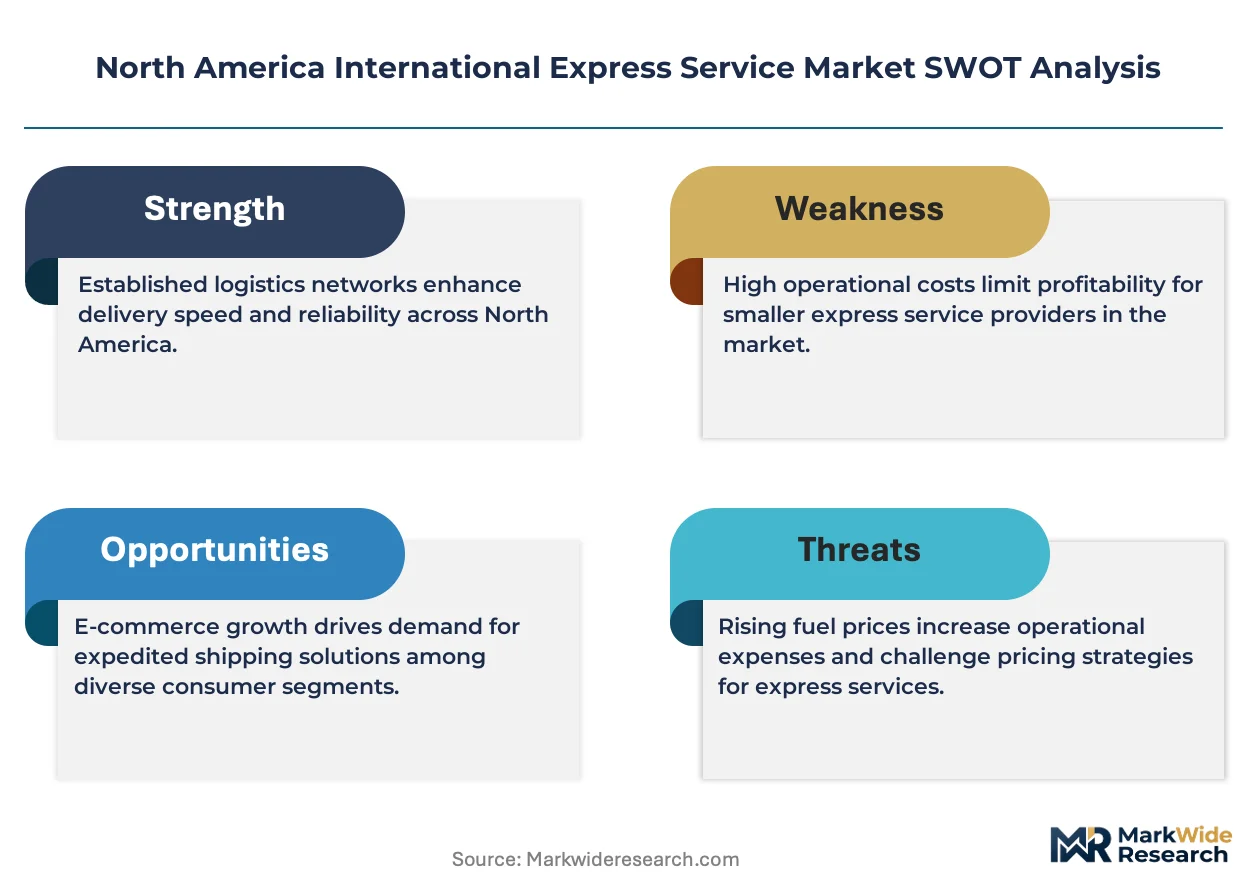
USMCA origin verification protocols are forcing express carriers to reconfigure customs pre-clearance infrastructure at Detroit-Windsor and Laredo-Nuevo Laredo, compressing clearance timelines while elevating compliance technology spend across the trade corridor.
Growth Catalysts
- E-commerce parcel density:Cross-border online retail flows between Mexico and the United States are saturating existing ground networks, pulling dedicated sortation investment into the Monterrey-San Antonio corridor.
- USMCA automotive rules-of-origin:The phased regional value-content requirements for passenger vehicles and light trucks are generating certificate-of-origin documentation volume that express providers capture through bonded warehouse integration.
- Harmonized tariff streamlining:Advance commercial information systems deployed by Canada Border Services Agency are reducing dwell times at Ontario-Michigan gateways, accelerating per-shipment velocity for just-in-time manufacturing inputs.
Market Restraints
- Jet fuel price volatility:Air freight operations remain exposed to kerosene-type jet fuel cost swings that compress margin on next-day commitments without fuel surcharge pass-through elasticity.
- Gateway concentration risk:Over half of Mexico-US express volume funnels through Laredo-Nuevo Laredo, creating single-point vulnerability to customs staffing surges or infrastructure bottlenecks.
- Ground fleet electrification capex:California Air Resources Board mandates and parallel Canadian federal zero-emission vehicle targets are forcing premature tractor replacement cycles ahead of battery range maturity for long-haul line-haul.
Strategic Opportunities
- Central Mexican manufacturing zones:Guanajuato and Querétaro automotive supplier parks remain underserved by bonded express infrastructure, offering first-mover density for carriers establishing Guadalajara-hubbed networks.
- USMCA de minimis reform tailwind:Congressional review of the USD 800 duty-free threshold could expand customs brokerage attach rates as formal entry requirements apply to previously exempt e-commerce parcels.
- Blockchain-EDI convergence:Distributed ledger validation of certificates of origin layered atop existing electronic data interchange systems is unifying compliance documentation across multi-party automotive supply chains.
Industry Challenges
- Licensed customs broker scarcity:USMCA origin verification complexity is outpacing the supply of brokers credentialed for both US CBP and Canada Border Services Agency entry types, inflating wage costs at corridor gateways.
- Legacy warehouse management system integration:Bonded facility operators struggle to retrofit mainframe-era inventory tracking for real-time USMCA data element capture without multimillion-dollar replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America International Express Service Market |
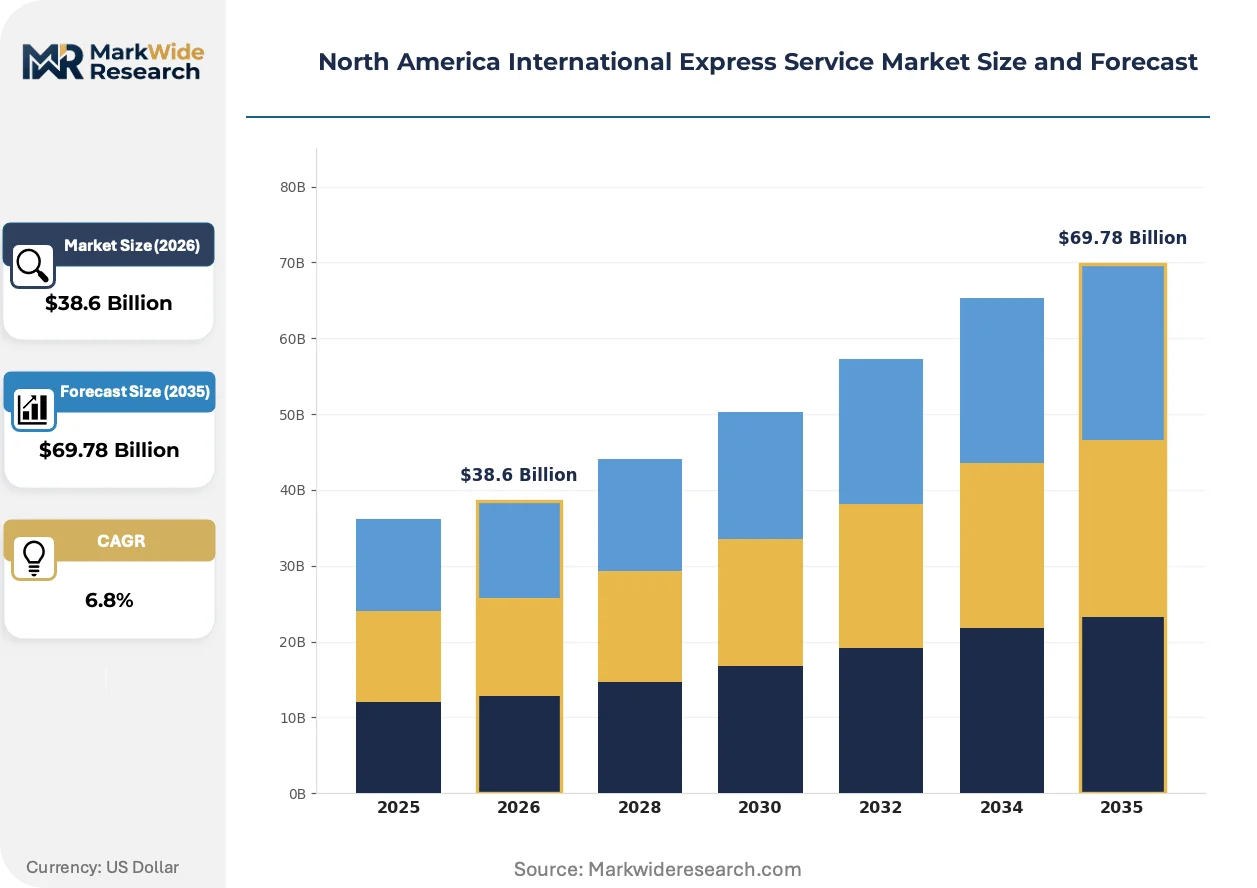
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ground Delivery, Logistics Management, Customs Brokerage Delivery Model: Business-to-Business, Business-to-Consumer, Cross-Border, Last Mile Customer Type: E-commerce Businesses, Retailers, Manufacturers, Individuals Shipment Weight: Small Packages, Medium Shipments, Heavy Cargo, Oversized Loads |
| Companies Covered | United Parcel Service (UPS), FedEx Corporation, DHL Express, Amazon Logistics, United States Postal Service (USPS), Purolator, OnTrac, LaserShip, C.H. Robinson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America International Express Service Market Trends and Innovations
Real-time shipment visibility and predictive customs risk scoring are compressing the information asymmetry that previously separated premium air freight from ground alternatives, flattening service-tier differentiation across the Mexico-US-Canada triangle.
Machine learning-based harmonized tariff classification engines are unifying product categorization accuracy across disparate shipper datasets. Mid-market e-commerce platforms are adopting these tools fastest, shaving 12-24 hours from pre-clearance preparation. The technology is unifying service-level expectations across air and ground modes by reducing customs hold probability.
US Customs and Border Protection's Section 321 data pilot and parallel Canada Border Services Agency advance commercial information requirements are tightening low-value shipment documentation standards. Automotive and aerospace shippers face stepped-up origin verification audits. Mexico-based maquiladora operators are responding by consolidating express contracts with providers offering embedded customs brokerage.
Shippers are unbundling expedited transport from integrated customs services, selecting carriers via reverse auction for line-haul while retaining specialized brokers for USMCA compliance. This bifurcation is most visible among Ontario-Michigan automotive suppliers managing high-frequency, low-weight tooling shipments. The pattern is compressing carrier pricing power on pure transport while elevating margin capture for compliance-specialized intermediaries.
North America International Express Service Market Segmentation
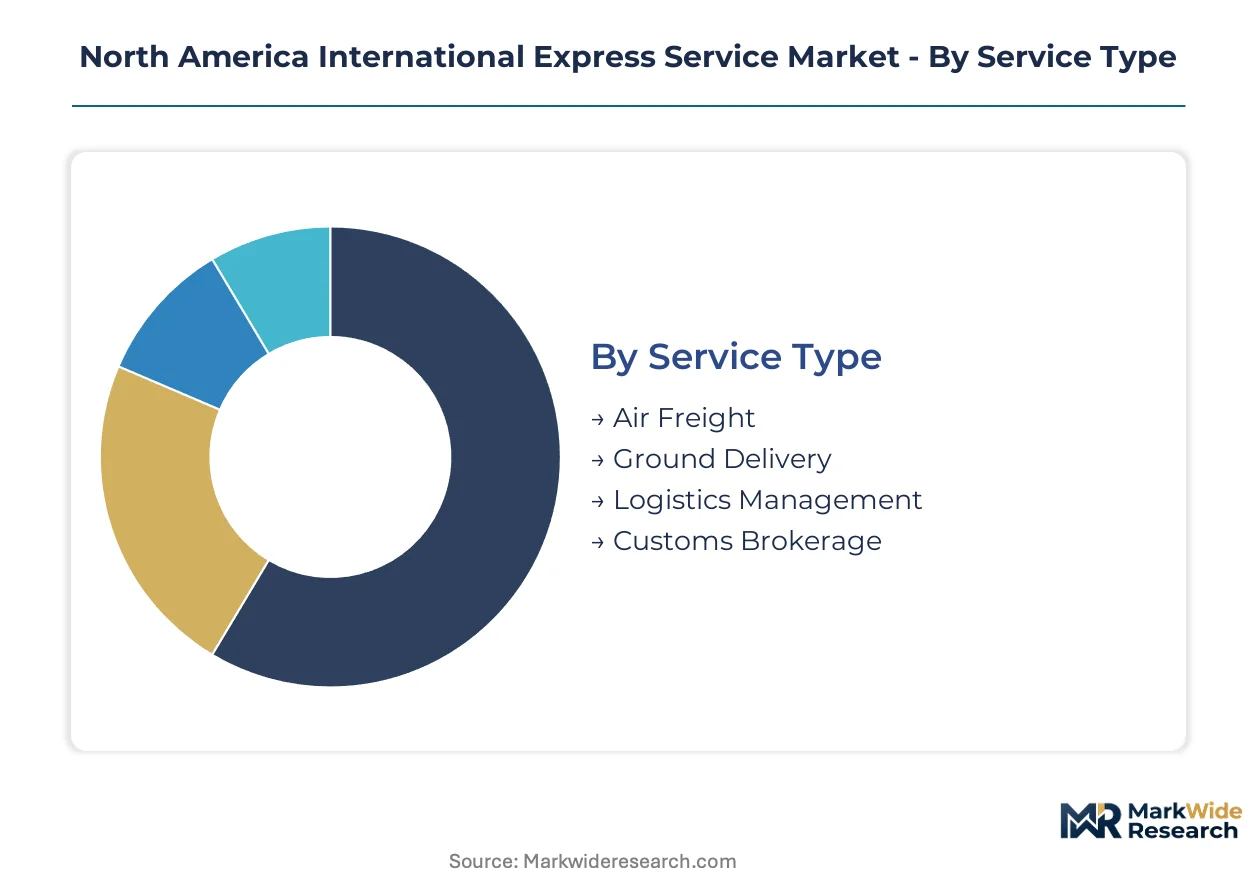
Express carriers configure network assets and pricing architectures around service velocity, customs complexity, and shipment density. Segmentation clarity determines where integrated air-ground infrastructure outperforms specialized customs brokerage or pure ground alternatives.
Service Type:
Supply concentration in bonded sortation hubs and customs pre-clearance technology investment varies sharply across service tiers.
- Air Freight:Time-definite cargo movements utilizing integrated freighter networks and express carrier belly space for next-day and second-day commitments. Premium manufacturing inputs from Guanajuato automotive supplier parks concentrate demand here, with USMCA origin verification compressing booking-to-wheels-up timelines.
- Ground Delivery:Bonded tractor-trailer networks operating within USMCA corridor infrastructure for deferred cross-border service. E-commerce parcel density between Monterrey and San Antonio is saturating existing line-haul capacity, pulling dedicated sortation investment into this mid-tier segment.
- Logistics Management:End-to-end supply chain orchestration including inventory positioning and multi-modal optimization.
- Customs Brokerage:Licensed entry preparation and USMCA compliance documentation. Rising certificate-of-origin validation requirements for automotive and aerospace shippers are elevating attach rates to core transport services.
Ground Delivery absorbs the bulk of installed capacity; Customs Brokerage is expanding most quickly.
Delivery Model:
Cost tier differentiation separates asset-heavy network operations from variable-cost brokerage and final-mile arrangements.
- Business-to-Business:Contractual volume commitments with defined service level agreements for manufacturing and wholesale distribution. Ontario-Michigan automotive tooling corridors represent the densest B2B flows, with just-in-time requirements dictating pre-cleared bonded warehouse positioning.
- Business-to-Consumer:Direct-to-door delivery for e-commerce platforms and brand retailers. Cross-border online retail saturation is forcing line-haul densification investments in the Mexico-US corridor ahead of peak season capacity constraints.
- Cross-Border:International express movements requiring harmonized customs documentation and duty reconciliation.
- Last Mile:Final delivery segment from gateway sortation to consignee address, often contracted to regional operators.
Business-to-Business retains the highest revenue per shipment; Business-to-Consumer is climbing the fastest.
Customer Type:
Application-specific requirements shape whether customers bundle customs services with transport or unbundle for reverse auction pricing.
- E-commerce Businesses:High-frequency, low-weight parcel shippers requiring automated customs documentation and consumer-duty prepayment. Section 321 data pilot requirements from US Customs and Border Protection are tightening documentation standards for this segment.
- Retailers:Omnichannel merchants balancing store replenishment with direct-to-consumer fulfillment.
- Manufacturers:Industrial shippers of production inputs, tooling, and finished goods. USMCA automotive rules-of-origin phase-in is forcing enhanced certificate-of-origin validation tools for this customer set.
- Individuals:Occasional cross-border shippers with minimal volume leverage and higher per-shipment customs complexity.
Manufacturers contribute the highest absolute revenue; E-commerce Businesses are gaining share fastest.
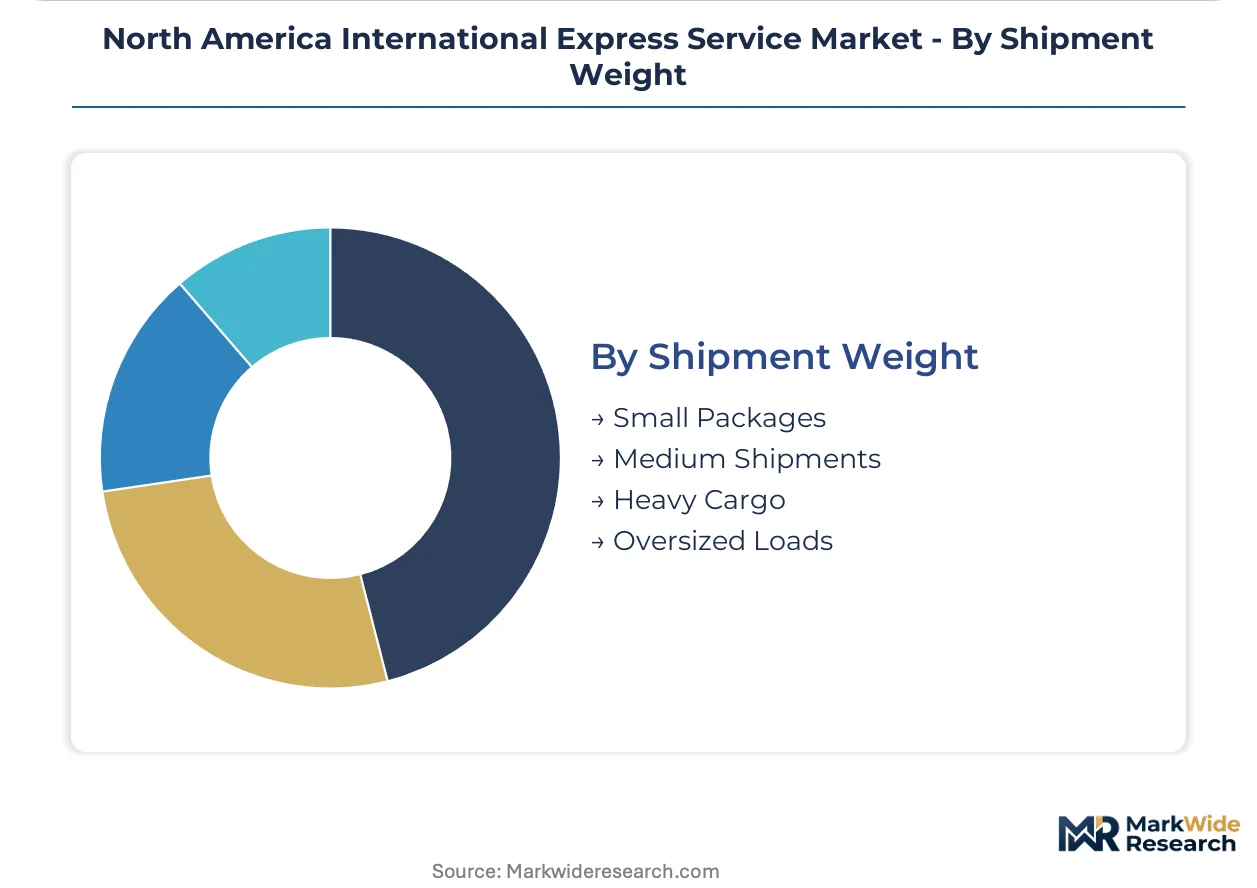
Shipment Weight:
Volume and margin profiles diverge across weight breaks, with network design favoring specific density corridors.
- Small Packages:Parcel shipments under defined weight thresholds optimized for automated sortation and last-mile density. De minimis reform discussions in Congress threaten to restructure economics for this segment if formal entry requirements expand.
- Medium Shipments:Mid-weight freight requiring palletized handling but not dedicated truckload capacity.
- Heavy Cargo:Industrial shipments demanding specialized equipment and customs brokerage coordination.
- Oversized Loads:Non-standard dimensions requiring permit routing and extended clearance timelines.
Small Packages moves the highest shipment count; Heavy Cargo captures the steepest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American express infrastructure density, with bonded warehouse positioning concentrated where just-in-time manufacturing supply chains intersect cross-border customs gateways.
United States
E-commerce parcel saturation between Texas and California is pulling dedicated sortation investment into the Laredo-San Antonio corridor. US Customs and Border Protection's Section 321 data pilot is tightening low-value shipment documentation standards for cross-border retailers. The Great Lakes manufacturing belt around Detroit and Chicago maintains the densest B2B express flows for automotive tooling and aerospace components.
Canada
Ontario-Michigan automotive supplier networks are driving demand for customs pre-clearance specialization at Windsor and Sarnia gateways. Canada Border Services Agency advance commercial information systems are reducing dwell times for just-in-time manufacturing inputs. The Toronto-Montréal corridor concentrates bonded express infrastructure serving European-North American trade lanes through Eastern Canada.
Mexico
Guanajuato and Querétaro automotive supplier parks are generating certificate-of-origin documentation volume that express providers capture through bonded warehouse integration. Mexico's customs administration is phasing in enhanced origin verification protocols under USMCA automotive rules-of-origin timelines. The Monterrey industrial cluster represents the fastest-growing source of mid-tier e-commerce parcel density crossing into Texas.
North America International Express Service Market Competitive Landscape
Global majors compete with regional champions across integrated air-ground infrastructure and customs brokerage specialization. The market structure tiers between asset-heavy integrated carriers with owned freighter networks and variable-cost ground operators relying on contracted line-haul capacity. Three archetypes dominate: integrated express networks with customs pre-clearance technology, regional ground specialists with corridor density, and e-commerce platforms with captive logistics arms. Competitive moves concentrate on bonded facility expansion at corridor gateways and technology licensing for harmonized tariff classification engines.
Among integrated network operators, FedEx Corporation and United Parcel Service occupy positions defined by owned air cargo infrastructure and multi-modal corridor density. DHL Express anchors European-North American lane specialization through hub-and-spoke configurations. These three exemplify the premium-tier archetype where customs brokerage attach rates rise with USMCA compliance complexity.
| Leading Market Players |
|---|
| United Parcel Service (UPS) |
| FedEx Corporation |
| DHL Express |
| Amazon Logistics |
| United States Postal Service (USPS) |
| Purolator |
| OnTrac |
| LaserShip |
| C.H. Robinson |
| Others |
Pricing and Supply Chain Analysis
Jet fuel cost volatility cascades through air freight pricing tiers, compressing margins on next-day commitments unless carriers achieve fuel surcharge pass-through elasticity with automotive and aerospace shippers.
Pricing Analysis
Warranty and service bundling separates integrated customs brokerage from pure transport rates, with USMCA compliance documentation increasingly unbundled for reverse auction. Three-tier pricing structure across premium, standard, and economy levels stratifies by velocity commitment and origin verification complexity. Price differentiation hinges on customs pre-clearance technology and bonded warehouse positioning. E-commerce retailers exhibit highest price sensitivity due to de minimis threshold exposure, while automotive OEMs absorb premium rates for just-in-time reliability.
Supply Chain Analysis
Reverse logistics flows for failed customs clearances and return parcels concentrate remediation costs at Detroit-Windsor and Laredo-Nuevo Laredo gateways. Supply chain configuration draws from Mexico manufacturing zones, United States distribution hubs, and Canadian transborder corridors. Kerosene-type jet fuel, bonded tractor-trailer capacity, and licensed customs broker labor constitute critical inputs. Single-point vulnerability at Laredo-Nuevo Laredo threatens corridor resilience. Distribution runs through integrated air-ground networks with customs pre-clearance technology.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning-based harmonized tariff classification is displacing legacy manual customs documentation, compressing pre-clearance timelines from 24 hours to near-real-time.
For Market Incumbents: Hedge against margin compression by deepening captive customs brokerage capabilities at USMCA corridor gateways. Integrate certificate-of-origin validation tools to defend against compliance-specialized intermediaries capturing attach revenue. Prioritize bonded warehouse positioning in Guanajuato and Querétaro automotive supplier parks ahead of competitor densification. For New Entrants and Emerging Players: Blockchain-EDI convergence for multi-party automotive supply chains offers technology-first wedge into certificate-of-origin validation services. Target Ontario-Michigan tooling corridors where shippers unbundle transport from compliance. Deploy harmonized tariff classification engines as embedded software licensing to mid-market e-commerce platforms. For Investors and Strategic Acquirers: Congressional review of de minimis reform is the leading indicator that customs brokerage attach rates will expand across previously exempt e-commerce volume. Long-term viability favors platforms integrating compliance technology with corridor density. Monitor USMCA automotive rules-of-origin phase-in timelines for accelerated carrier technology investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Expansion | Positions inventory within USMCA automotive supplier parks for just-in-time clearance velocity. |
| Customs Technology Licensing | Monetizes harmonized tariff classification engines to mid-market e-commerce platforms. |
| Broker Credential Investment | Addresses licensed customs broker scarcity at Detroit-Windsor and Laredo-Nuevo Laredo. |
| Ground Fleet Electrification | Preempts California Air Resources Board and Canadian zero-emission mandates ahead of compliance deadlines. |
| Cross-Border Partnership | Secures dedicated line-haul capacity in Monterrey-San Antonio corridor ahead of peak saturation. |
Research Methodology
Document review covered carrier network disclosures, USMCA regulatory filings, and customs agency advance commercial information requirements, complemented by interviews with express carrier operations executives, licensed customs brokers, automotive supply chain managers, and e-commerce logistics directors. Secondary validation drew from Canada Border Services Agency bulletins, US Customs and Border Protection pilot program documentation, and bonded facility operator filings. Bottom-up shipment volume modeling and top-down corridor capacity assessments were triangulated.
Historical volume trajectories were cross-referenced against executive panel input on USMCA compliance technology deployment timelines. Segmentation dimensions modeled include service velocity tier, customs complexity level, and corridor density cluster across the projection horizon. CAGRs were derived from shipment volume elasticity to e-commerce penetration rates and manufacturing reshoring indicators. Forecast inputs incorporated jet fuel price scenarios and de minimis reform probability assessments.
Several conditions sit outside the modeled scope, including specific congressional legislative timelines, unilateral tariff rate adjustments, and pandemic-scale border closures. Forecasts reflect assumptions on USMCA rules-of-origin phase-in adherence and carrier technology investment pacing. Practitioners should monitor customs staffing levels at Laredo-Nuevo Laredo and congressional de minimis reform hearings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
United States Car Rental Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Poland Car Rental Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Car Rental Service Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Russia Car Rental Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Australia Taxi Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Global Moto Taxi Service Market