
 Global Vertebral Compression Fracture Devices Market | 2026-2036
Global Vertebral Compression Fracture Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vertebral Compression Fracture Devices Market Foresight
The capital-intensity divergence between large diversified orthopedics manufacturers and focused spine device specialists is bifurcating competitive dynamics in vertebral compression fracture treatment. Medtronic leverages its integrated navigation and cement delivery platforms to sustain premium positioning across hospital systems. Globus Medical specializes in expandable technologies and competes through surgeon training programs that anchor loyalty in high-volume spine centers.
Vertebral compression fracture devices comprise balloon-assisted cement delivery systems, percutaneous injection kits, polymethylmethacrylate or alternative bone cements, and precision needle assemblies designed to restore vertebral body height and stabilize spinal columns following osteoporotic collapse or traumatic injury. Balloon kyphoplasty devices command the largest revenue pool due to established reimbursement and superior height-restoration outcomes, while biodegradable implants represent the fastest-growing technology segment as surgeons seek alternatives to permanent cement burden in younger patients. Image-guided navigation systems are gaining structural importance as facilities invest in radiation-reduction protocols and procedural accuracy.
FDA 510(k) clearance pathways and EU MDR conformity requirements determine market access timelines and clinical evidence burdens for manufacturers entering the United States and European markets. ISO 13485 quality management standards and biocompatibility testing protocols under ISO 10993 further shape product development costs and supplier qualification processes. Stakeholders must monitor evolving CMS reimbursement decisions for kyphoplasty versus vertebroplasty procedures and assess how Japan's PMDA regulatory convergence with global standards affects competitive entry sequencing.
Market Dynamics
Minimally invasive spine intervention protocols are compressing hospital length-of-stay metrics and redirecting procedure volumes away from open surgical suites toward dedicated ambulatory surgery centers, fundamentally restructuring capital deployment patterns across the vertebral compression fracture treatment ecosystem.
Growth Catalysts
- EU MDR Conformity Pathways:Harmonized clinical evidence requirements for CE marking are accelerating cross-border product standardization and reducing redundant testing burdens for manufacturers targeting multiple European markets simultaneously.
- Japan's PMDA Regulatory Convergence:Alignment with international standards for medical device approval timelines is compressing market entry delays for foreign manufacturers seeking access to Japanese spine surgery centers.
- Biodegradable Implant Materials:Polymer-ceramic composites designed for gradual resorption are capturing surgeon preference in younger patient cohorts seeking alternatives to permanent polymethylmethacrylate cement burden.
Market Restraints
- Polymethylmethacrylate Supply Concentration:Specialty bone cement manufacturing capacity clusters among a limited number of European and North American chemical suppliers, creating input vulnerability during demand surges.
- Reimbursement Compression:CMS coverage determinations distinguishing kyphoplasty from vertebroplasty reimbursement rates are constraining facility revenue per procedure and dampening capital equipment refresh cycles.
- Radiation Exposure Protocols:Stringent occupational safety limits on fluoroscopy time during percutaneous procedures are extending operative durations and limiting daily case throughput in high-volume centers.
Strategic Opportunities
- India's Underpenetrated Osteoporosis Treatment Infrastructure:Low screening rates and limited access to interventional radiology capabilities in tier-2 and tier-3 cities present whitespace for mobile C-arm equipped procedure units.
- Image-Guided Navigation Convergence:Integration of optical tracking systems with robotic needle positioning is enabling sub-millimeter accuracy in vertebral body targeting without continuous fluoroscopic visualization.
- Outpatient Procedure Migration:Ambulatory surgery center licensing expansions in Germany and Switzerland are redirecting case volumes from inpatient settings toward lower-cost environments with faster patient turnover.
Industry Challenges
- Interventional Radiology Training Pipeline:Fellowship programs producing spine-focused interventionalists are failing to match procedure volume growth, creating staffing bottlenecks in high-demand metropolitan markets.
- FDA 510(k) Substantial Equivalence Documentation:Evolving predicate device requirements and clinical data expectations are extending clearance timelines and increasing regulatory consulting expenditures for novel delivery system designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vertebral Compression Fracture Devices Market |
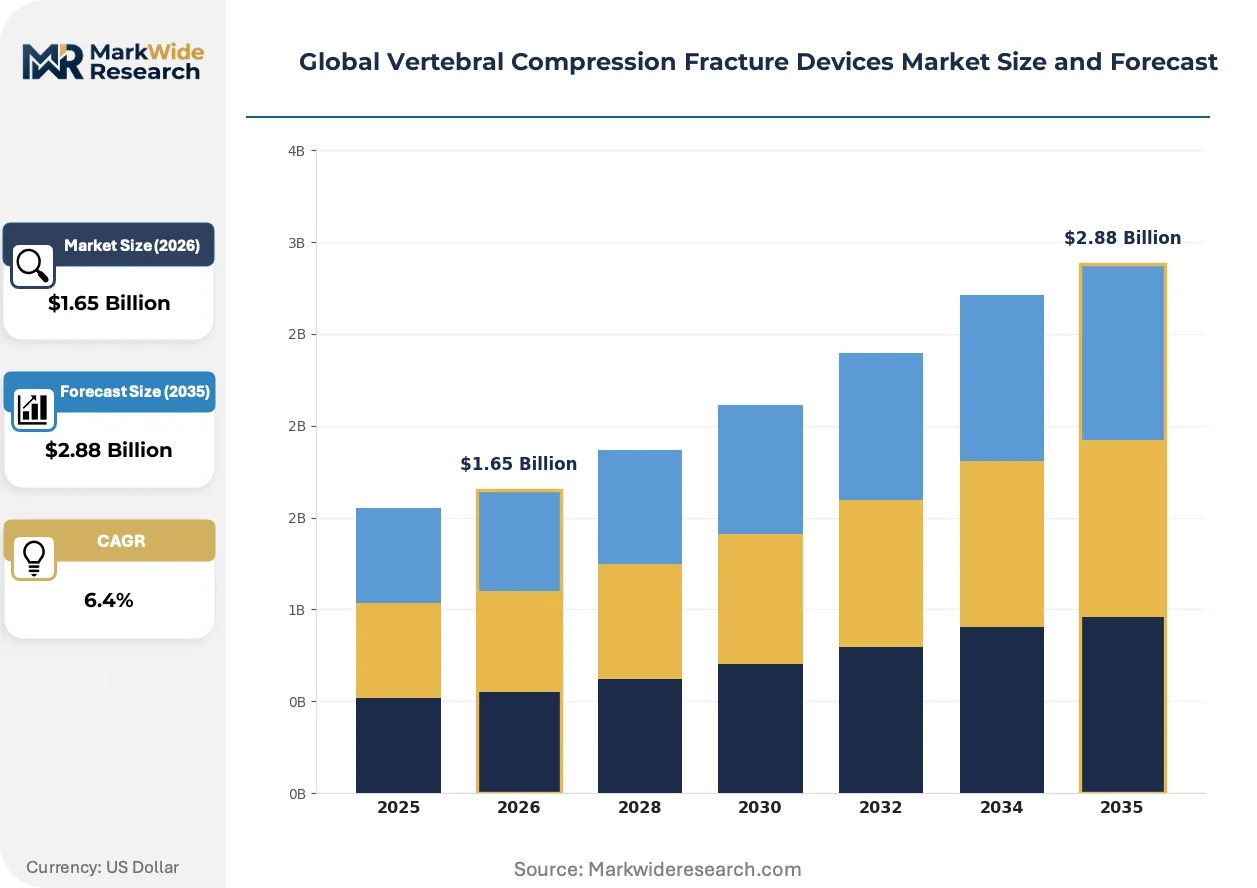
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Kyphoplasty Devices, Vertebroplasty Kits, Bone Cement Materials, Needle Systems Technology: Minimally Invasive Systems, Image-Guided Navigation, Radiofrequency Kyphoplasty, Biodegradable Implants Application: Osteoporotic Fracture Treatment, Traumatic Injury Repair, Tumor-Induced Compression, Post-Surgical Stabilization End User: Specialty Clinics, Orthopedic Surgeons, Spine Surgery Centers, Rehabilitation Facilities |
| Companies Covered | Medtronic, Stryker Corporation, Globus Medical, DePuy Synthes, Zimmer Biomet, Merit Medical Systems, Alphatec Spine, Benvenue Medical, IZI Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vertebral Compression Fracture Devices Market Shifts & Advancements
Digital surgical planning platforms and radiation-reduction technologies are converging to reshape procedural workflows, while alternative biomaterials challenge the decades-long dominance of acrylic bone cements in vertebral augmentation.
Radiofrequency-targeted vertebral augmentation is fragmenting traditional kyphoplasty market segmentation by offering controlled thermal energy delivery alongside cement injection, reducing the risk of cement leakage. High-volume spine centers in the United States are piloting this hybrid approach for pathological fractures with cortical disruption. The technology is compressing the addressable market for conventional balloon systems in complex cases.
EU MDR Article 10 technical documentation requirements are intensifying post-market surveillance obligations and mandating systematic clinical follow-up for implantable devices. Manufacturers must now maintain updated clinical evaluation reports throughout product lifecycles, not solely at initial conformity assessment. Mid-sized device firms are responding by consolidating regulatory affairs functions and outsourcing post-market clinical follow-up to specialized contract research organizations.
Hospital procurement departments are consolidating spine device purchasing through integrated delivery networks and group purchasing organizations, unbundling historically surgeon-driven vendor relationships. Academic medical centers in Japan and Germany are piloting value-based procurement frameworks that weight complication rates and readmission metrics alongside unit price. This behavioral shift is most pronounced in German hospital networks where regional purchasing cooperatives now dominate capital equipment acquisition decisions.
Global Vertebral Compression Fracture Devices Market Segmentation
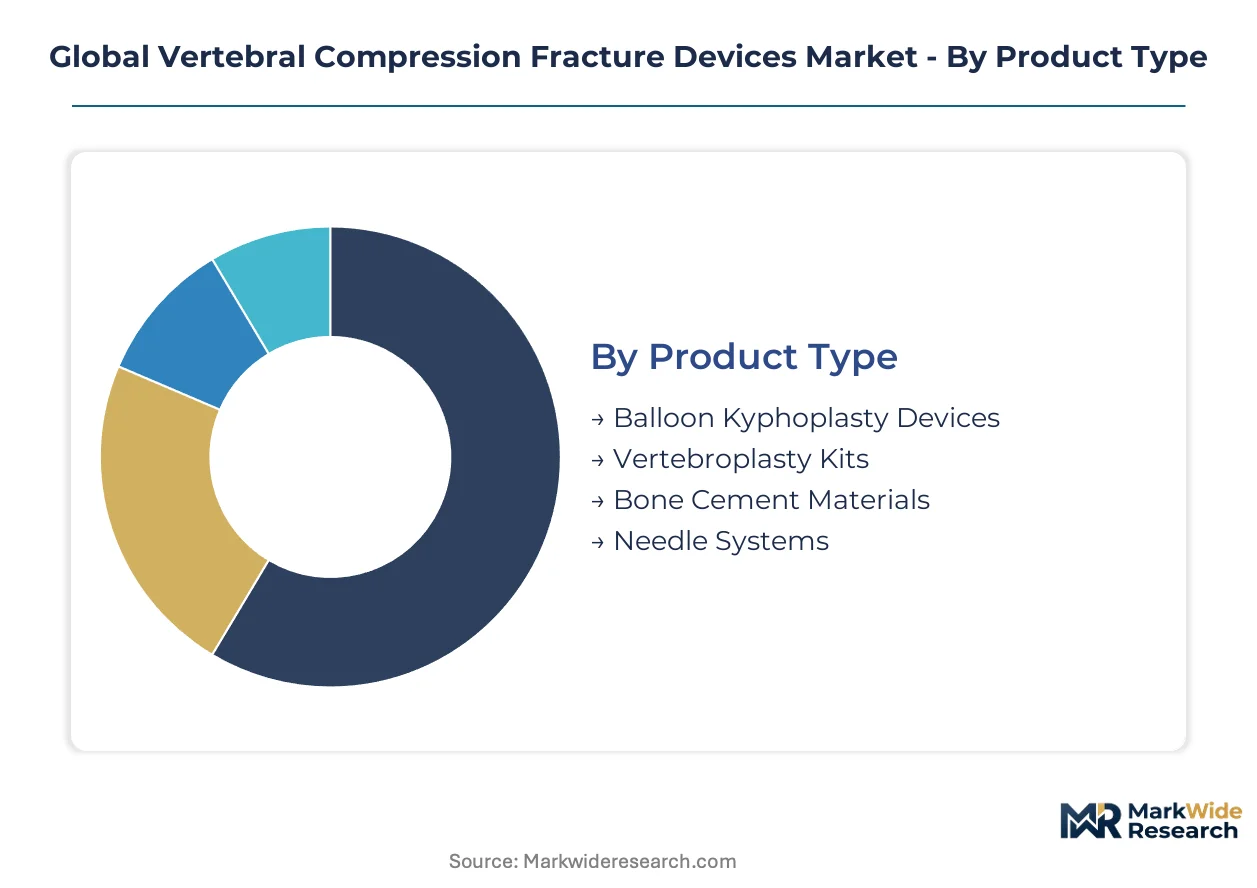
Device segmentation in vertebral compression fracture treatment reveals distinct competitive arenas where cement-based systems face erosion from biodegradable alternatives and navigation-enabled platforms. Understanding substitution dynamics across product, technology, application, and end-user dimensions clarifies where incumbents must defend positioning versus where challengers can capture share.
Product Type:
Balloon-assisted cement delivery systems confront the most acute substitution pressure as radiofrequency-targeted vertebral augmentation and biodegradable implants erode their procedural dominance in younger patient cohorts.
- Balloon Kyphoplasty Devices:Inflatable bone tamps create cavity space for controlled polymethylmethacrylate injection under fluoroscopic guidance. Demand concentrates in United States hospital systems where CMS reimbursement differentials favor height-restoration outcomes; established predicate device pathways sustain manufacturer margins despite lengthening FDA clearance timelines.
- Vertebroplasty Kits:Percutaneous needle assemblies deliver bone cement directly without cavity creation, trading height restoration for procedural simplicity. German spine surgery centers and Japanese academic hospitals drive kit volumes as cost-containment pressures intensify; reimbursement compression dampens facility enthusiasm for premium balloon systems in straightforward osteoporotic cases.
- Bone Cement Materials:Polymethylmethacrylate formulations dominate with radiopaque additives enabling visualization; calcium phosphate cements gain traction in pediatric applications seeking resorbable alternatives.
- Needle Systems:Precision cannulae with beveled tips and depth markers enable transpedicular and extrapedicular access; single-use disposable configurations align with ambulatory surgery center infection protocols.
Balloon kyphoplasty devices retain volume leadership; biodegradable implant materials hold the steepest expansion curve.
Technology:
Cost-tier stratification separates capital-intensive navigation platforms from disposable kit-based approaches, with mid-range minimally invasive systems capturing the highest procedure volumes across mixed-reimbursement environments.
- Minimally Invasive Systems:Percutaneous access instruments reduce tissue disruption and enable outpatient discharge protocols. United States ambulatory surgery centers and Swiss licensed day-clinics anchor demand as length-of-stay metrics compress; faster patient turnover justifies capital investment despite higher per-procedure device costs.
- Image-Guided Navigation:Optical tracking and robotic needle positioning eliminate continuous fluoroscopy. Academic medical centers in Germany and Japan pilot radiation-reduction protocols; occupational safety limits on fluoroscopy time create structural demand for navigation convergence.
- Radiofrequency Kyphoplasty:Controlled thermal energy delivery alongside cement injection reduces leakage risk in pathological fractures. High-volume United States spine centers pilot hybrid approaches for cortical disruption cases.
- Biodegradable Implants:Polymer-ceramic composites designed for gradual resorption eliminate permanent cement burden. Younger traumatic injury patients in Japan and select European markets drive surgeon preference shifts.
Minimally invasive systems command the largest installed base; image-guided navigation platforms are climbing the fastest as radiation protocols tighten.
Application:
Procedure volumes concentrate in osteoporotic fracture treatment, though traumatic injury repair offers superior reimbursement rates and faster patient turnover in ambulatory settings.
- Osteoporotic Fracture Treatment:Age-related vertebral body collapse drives the majority of kyphoplasty and vertebroplasty procedures. United States Medicare populations and Japan's aging demographic anchor demand; screening infrastructure gaps in India and tier-2 Chinese cities represent whitespace expansion targets.
- Traumatic Injury Repair:High-energy compression fractures in younger patients require height restoration and mechanical stability. German trauma networks and United States level-1 trauma centers prioritize rapid stabilization; biodegradable implant adoption concentrates here due to longer life expectancy post-procedure.
- Tumor-Induced Compression:Pathological fractures from metastatic disease demand cement augmentation with leakage mitigation. Radiofrequency-targeted systems capture share in cortical-compromised cases.
- Post-Surgical Stabilization:Adjacent-level fractures following prior fusion procedures require targeted augmentation. Revision surgery protocols in Japanese and German academic centers drive specialized needle system configurations.
Osteoporotic fracture treatment retains volume leadership; traumatic injury repair holds the steepest expansion curve as biodegradable alternatives mature.
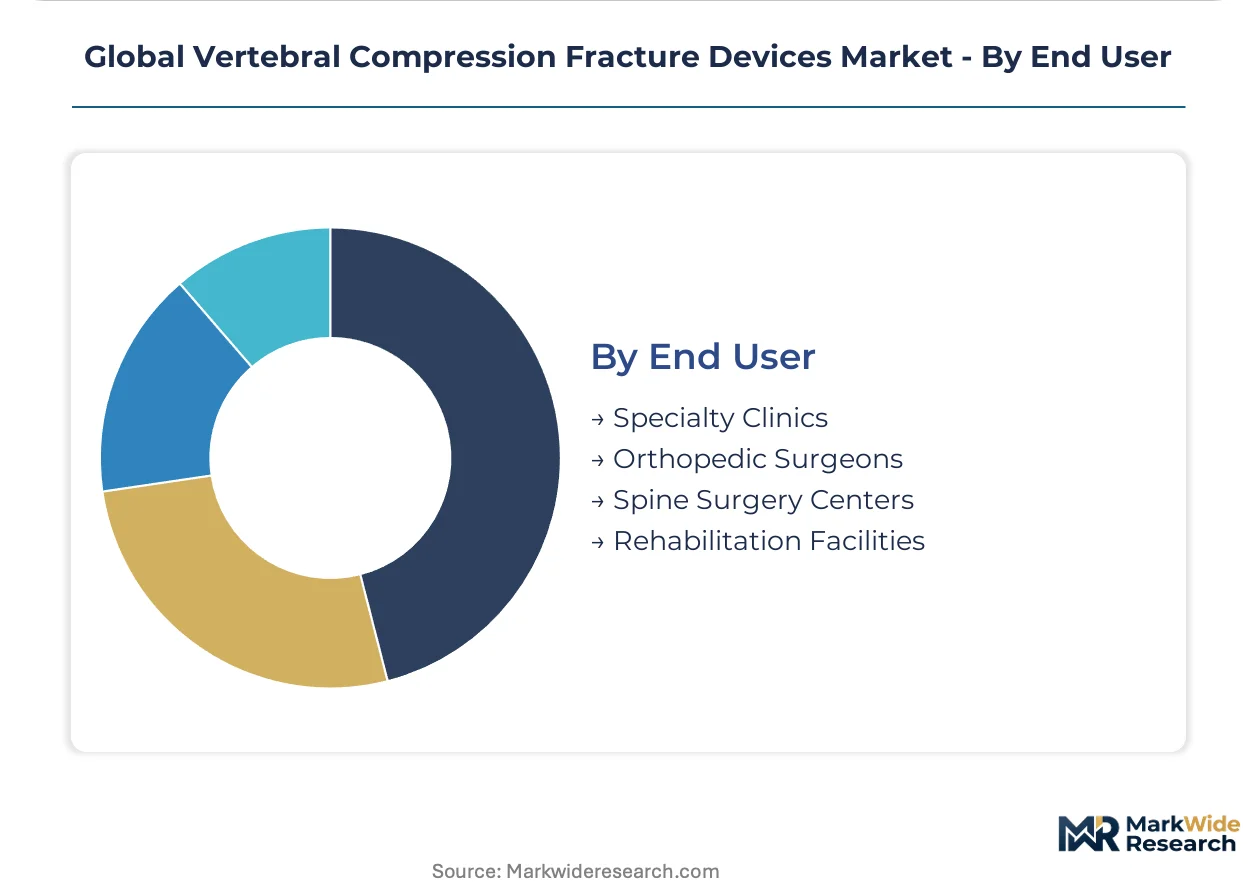
End User:
Procurement authority is shifting from individual surgeons toward integrated delivery networks and group purchasing organizations, restructuring vendor relationships across all facility types.
- Specialty Clinics:Focused interventional radiology and pain management practices perform high volumes of outpatient vertebral augmentation. United States metropolitan markets and German urban centers concentrate clinic density; staffing bottlenecks limit expansion in underserved regions.
- Orthopedic Surgeons:Spine-focused orthopedists historically drove device selection through individual preference. Hospital procurement consolidation in Japan and Germany is unbundling these relationships; value-based frameworks now weight complication rates alongside unit price.
- Spine Surgery Centers:Dedicated facilities optimize workflow for vertebral compression fracture procedures. Ambulatory licensing expansions in Switzerland and Germany redirect case volumes from inpatient settings.
- Rehabilitation Facilities:Post-acute settings manage conservative care and non-surgical candidates. Limited interventional capabilities restrict device demand to referral coordination rather than direct procurement.
Spine surgery centers retain volume leadership; specialty clinics hold the steepest expansion curve as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers prioritize height-restoration outcomes and navigation integration, accepting premium device costs. German and Japanese procurement departments apply stricter value-based frameworks, compressing margins for undifferentiated systems.
United States
Medicare-covered osteoporotic procedures anchor global procedure volumes. FDA 510(k) clearance pathways determine competitive entry sequencing for novel delivery platforms. Spine surgery centers in Phoenix and Dallas-Fort Worth metro areas are expanding ambulatory licensing to capture outpatient migration.
Germany
Regional purchasing cooperatives now dominate capital equipment decisions, unbundling surgeon-driven vendor relationships. EU MDR Article 10 technical documentation requirements intensify post-market surveillance obligations for implantable devices. University hospitals in Bavaria and North Rhine-Westphalia pilot value-based procurement weighting complication rates alongside unit price.
Japan
Aging demographics and PMDA regulatory convergence with international standards compress market entry delays for foreign manufacturers. METI-supported spine surgery infrastructure investments concentrate in Kanto and Kansai regions. Academic medical centers in Tokyo and Osaka are piloting radiation-reduction protocols using optical tracking systems.
India
Low osteoporosis screening rates and limited interventional radiology access in tier-2 and tier-3 cities create whitespace for mobile C-arm equipped units. CDSCO medical device regulations under the Drugs and Cosmetics Act govern import and manufacturing licensing. Hyderabad and Chennai clusters are attracting contract manufacturing partnerships for precision needle assemblies.
Switzerland
Licensed day-clinic expansions redirect vertebral augmentation volumes from inpatient settings toward lower-cost environments. Swissmedic conformity assessment requirements align with EU MDR for market access. Zurich and Geneva spine centers are optimizing workflow for faster patient turnover in ambulatory configurations.
Global Vertebral Compression Fracture Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Large diversified orthopedics manufacturers leverage integrated navigation and cement delivery platforms to sustain premium positioning across hospital systems. Focused spine device specialists compete through expandable technologies and surgeon training programs that anchor loyalty in high-volume centers. The two dominant competitive moves are portfolio diversification into biodegradable alternatives and strategic partnerships for image-guided navigation convergence.
Among diversified orthopedics manufacturers, Medtronic and Stryker Corporation exemplify the integrated-platform archetype. Globus Medical occupies a position within the spine-focused specialist tier. These three entities represent the competitive anchors around which procurement consolidation and technology licensing patterns are reorganizing vendor relationships across United States hospital systems and European purchasing cooperatives.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Globus Medical |
| DePuy Synthes |
| Zimmer Biomet |
| Merit Medical Systems |
| Alphatec Spine |
| Benvenue Medical |
| IZI Medical Products |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day cement formulation lead times from European specialty chemical suppliers concentrate pricing power among polymethylmethacrylate manufacturers, while hospital procurement consolidation across United States integrated delivery networks compresses device margins through volume-based contracting.
Pricing Analysis
After-sales revenue from surgeon training programs and extended technical service contracts drives lifetime value for navigation-enabled platform vendors. Three-tier pricing structure across premium navigation-integrated systems, standard balloon-assisted kits, and economy vertebroplasty configurations reflects FDA clearance tier and institutional purchasing volume. Pricing pressure stems from CMS reimbursement compression distinguishing kyphoplasty from vertebroplasty rates. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with research budgets demonstrate lowest.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and trans-Atlantic container availability constrain polymethylmethacrylate delivery schedules to North American device assemblers. Manufacturing concentration clusters in Germany, Switzerland, and the United States for precision needle assemblies; polymer-ceramic composite sourcing feeds from Japanese and South Korean specialty material suppliers. Single-source vulnerability runs through limited European bone cement chemical manufacturers. Distribution runs through regional medical device distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
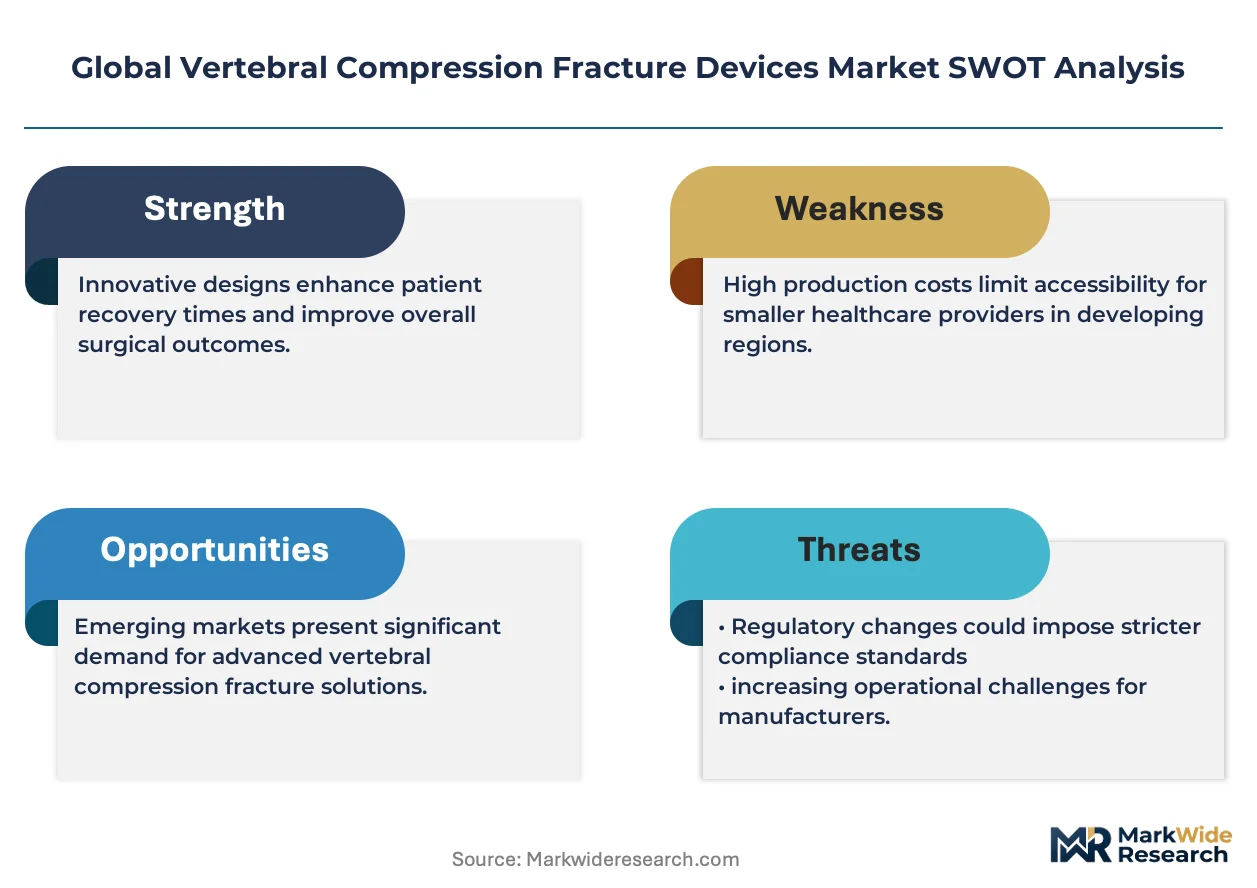
Regulatory entrenchment through FDA 510(k) predicate pathways and EU MDR technical documentation requirements creates defensive moats for established manufacturers, as switching costs for hospital systems escalate with integrated navigation platform adoption.
For Market Incumbents: Compound defensive positioning through backward integration into polymethylmethacrylate formulation capabilities and expansion of radiation-reduction navigation software ecosystems. Biodegradable implant substitution threats from polymer-ceramic specialists demand R&D allocation toward resorbable material platforms. CE marking investment under EU MDR Article 10 sustains European market access against mid-sized competitor consolidation.
For New Entrants and Emerging Players: Lead with image-guided navigation convergence partnerships targeting German and Japanese academic medical centers piloting fluoroscopy-reduction protocols. India's tier-2 and tier-3 city whitespace offers lowest competitive density for mobile C-arm equipped procedure units. Go-to-market execution through interventional radiology training program sponsorship anchors surgeon loyalty before procurement consolidation advances.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedics manufacturers seeking to divest non-core spine assets; mid-sized European device firms facing EU MDR compliance cost burdens present acquisition opportunities. Long-term viability frames around navigation platform installed base expansion and biodegradable material patent portfolios. Signal to monitor: CMS coverage determination shifts affecting kyphoplasty reimbursement differentials.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Investment | Post-market surveillance obligations under EU MDR Article 10 reshape competitive entry barriers for implantable devices. |
| Biodegradable Implant R&D Partnership | Polymer-ceramic composite development addresses surgeon preference shifts in younger traumatic injury patient cohorts. |
| Navigation Platform Hospital System Partnership | Optical tracking system pilots at Tokyo and Osaka academic centers establish radiation-reduction protocol credibility. |
| Surgeon Training Program Expansion | High-volume spine center loyalty programs defend against procurement consolidation through integrated delivery networks. |
| Mobile C-Arm Unit Deployment | India tier-2 and tier-3 city penetration captures whitespace before domestic competitors establish interventional radiology infrastructure. |
Research Methodology
A spread of perspectives from spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying procedure volume trajectories. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement filings, and hospital procurement contract registries. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored value estimates.
Segmentation dimensions modeled span product type, technology platform, application indication, and end-user facility category across the projection horizon. CAGRs derived from procedure volume elasticity to aging demographic penetration rates and reimbursement policy stability. Forecast inputs incorporated PMDA regulatory convergence timelines and ambulatory surgery center licensing expansion patterns.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR conformity assessment regimes; material policy shifts would require re-modeling. Specific risks include CMS coverage determination reversals and polymethylmethacrylate supply disruption from European chemical manufacturer consolidation. Recalibration cycles align with material shifts in reimbursement policy and navigation technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Gel Implants Market
Medical Devices
Medical Electronics Market
Medical Devices
Knee Braces Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Band Ligators Market
Medical Devices
Morcellators Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Arthroscopy Procedures and Products Market