
 Brazil Fruits and Vegetables Market | 2026-2036
Brazil Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Fruits and Vegetables Market Outlook
Multi-source procurement among Brazilian fresh produce distributors is rebalancing toward vertically integrated farm-to-retail networks. SLC Agrícola leverages its massive land bank in the Cerrado to sustain year-round vegetable output. Citrosuco anchors Brazil's orange juice supply chain through integrated processing and port logistics. Cutrale competes on frozen concentrate exports with controlled orchard and manufacturing assets.
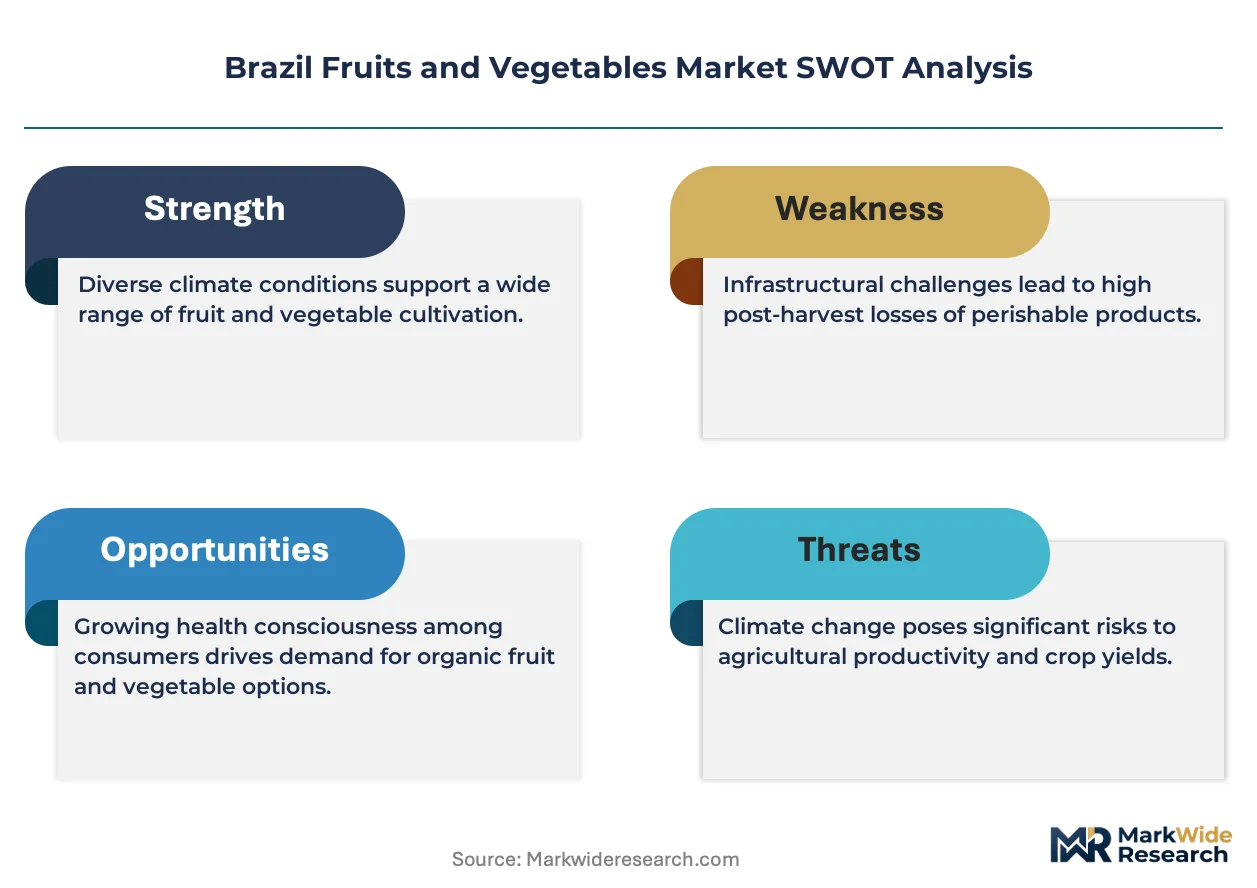
Brazil fruits and vegetables encompass fresh and minimally processed plant products harvested for human consumption, typically graded by Brix content, firmness, and visual defect thresholds before cold-chain distribution. The category serves domestic retail, industrial processing, and international export channels requiring phytosanitary certification. Citrus and leafy greens occupy the largest volume positions, while organic quality grade commands premium positioning in supermarkets and online retail. Root vegetables sustain margin pools through extended shelf life and lower perishability losses in wholesale channels.
ANVISA governs pesticide maximum residue limits and food safety standards for domestic sale and export eligibility. The Ministry of Agriculture's MAPA enforces phytosanitary protocols and origin certification under international trade agreements. Stakeholders must monitor evolving EU Green Deal import requirements and ANVISA's alignment with Codex Alimentarius standards to preserve market access for premium-grade shipments.
Market Dynamics
ANVISA's tightening pesticide residue limits for export-bound citrus is compressing farm-gate margins while forcing rapid adoption of integrated pest management protocols across São Paulo's citrus belt. This regulatory pressure is accelerating consolidation among mid-sized growers who lack capital for compliance infrastructure.
Growth Catalysts
- EU Green Deal import alignment:ANVISA's harmonization with Codex Alimentarius standards preserves preferential market access for Brazilian citrus exporters facing European deforestation-free supply chain mandates.
- Juice concentrate industrial demand:Food processing companies are expanding tropical fruit pulp procurement for downstream manufacturing, pulling volume through Minas Gerais processing corridors.
- Minas Gerais vegetable production corridors:Controlled-environment agriculture investments in this region enable year-round leafy greens output for domestic retail chains.
Market Restraints
- Agrochemical input cost volatility:Fertilizer and pesticide price swings squeeze margins for citrus growers operating on fixed-price annual contracts with processors.
- Export logistics concentration:Port of Santos congestion and container availability constraints create shipment delays for frozen concentrate orange juice bound for European and North American buyers.
- Fresh produce perishability:Cold-chain infrastructure gaps in Brazil's interior states limit shelf-life extension for leafy greens and berries targeting distant urban markets.
Strategic Opportunities
- Organic certification premium capture:Supermarket chains in São Paulo and Rio de Janeiro are expanding dedicated organic produce sections, creating price differentiation for certified growers.
- Amazon region underpenetration:Northern state vegetable production remains minimal relative to population growth, offering first-mover positioning for greenhouse operators near Manaus distribution nodes.
- E-commerce direct-to-consumer channels:Online grocery platforms are bypassing traditional CEASA wholesale markets, enabling farm-box subscriptions with traceability guarantees.
Industry Challenges
- Phytosanitary certification timeline compression:MAPA inspection backlogs delay export clearance for time-sensitive fresh shipments, forcing air freight substitution that erodes margins.
- Skilled agronomist scarcity:Precision agriculture and integrated pest management deployment outpaces trained technician supply in Brazil's interior production zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Fruits and Vegetables Market |
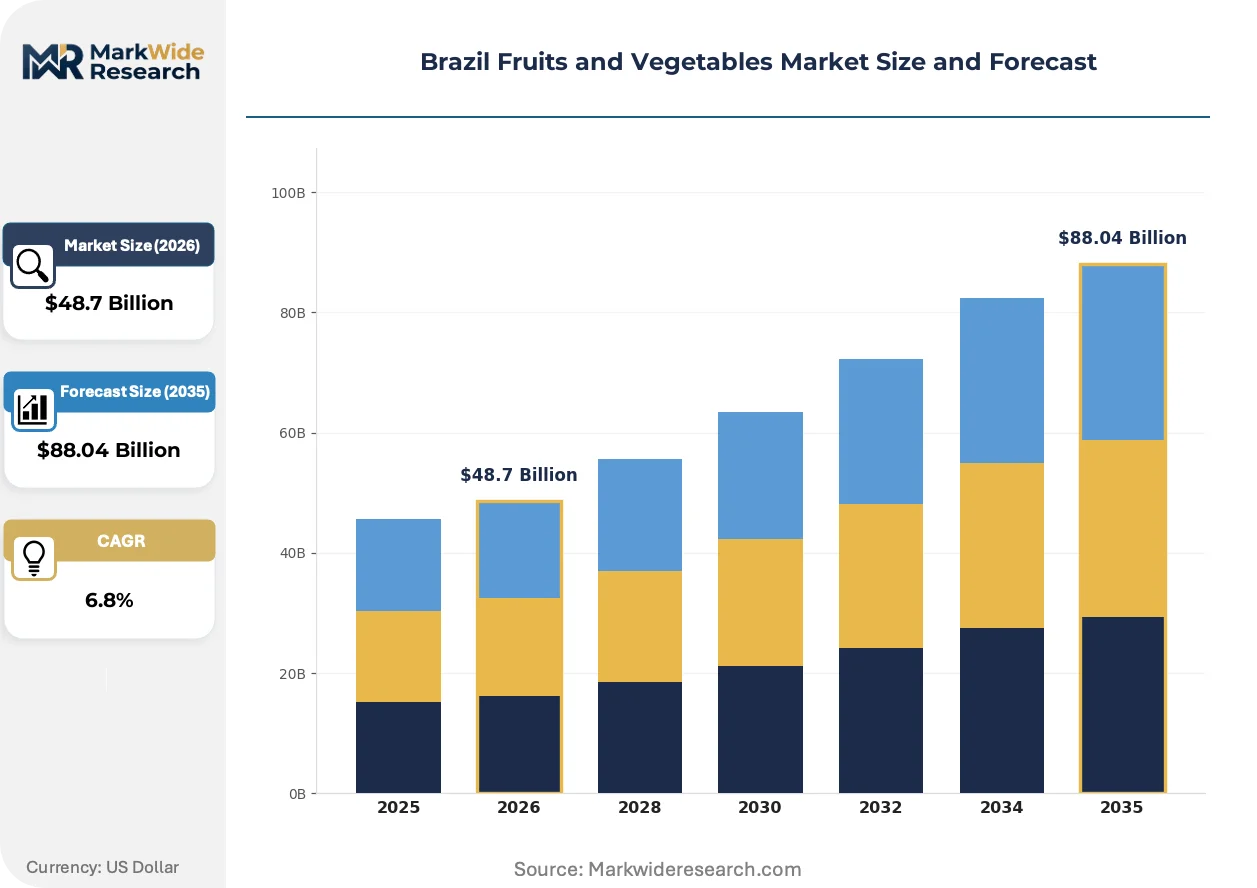
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Online Retail, Supermarkets, Farmers' Markets, Wholesalers End User: Households, Restaurants, Food Processing, Exporters Quality Grade: Organic, Conventional, Premium, Grade-A |
| Companies Covered | SLC Agrícola, Limagrain, Citrosuco, Sakata, Rijk Zwaan, Syngenta, Bunge Brasil, Enza Zaden, Cutrale, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Fruits and Vegetables Market Strategic Shifts
Digital traceability systems and climate-controlled logistics are restructuring how Brazilian produce moves from field to retail shelf. These technologies are compressing traditional wholesale intermediation layers.
Precision agriculture sensor networks are absorbing capital deployment across São Paulo citrus orchards. Large-scale growers are installing soil moisture and foliar analysis systems at accelerating pace. This technology is absorbing labor-intensive scouting functions while compressing input application windows.
ANVISA's updated federal pesticide residue standards are tightening maximum residue limits for export-bound citrus categories. Processors must now maintain dual compliance tracks for domestic and international shipments. Frozen concentrate orange juice destined for EU markets faces the most stringent testing protocols.
Retail procurement consolidation is compressing supplier bases as supermarket chains centralize buying through direct farm partnerships. Traditional CEASA wholesale market intermediaries are losing volume share to vertically integrated distributors. São Paulo state's organized retail sector exhibits the most pronounced channel disintermediation.
Brazil Fruits and Vegetables Market Segmentation
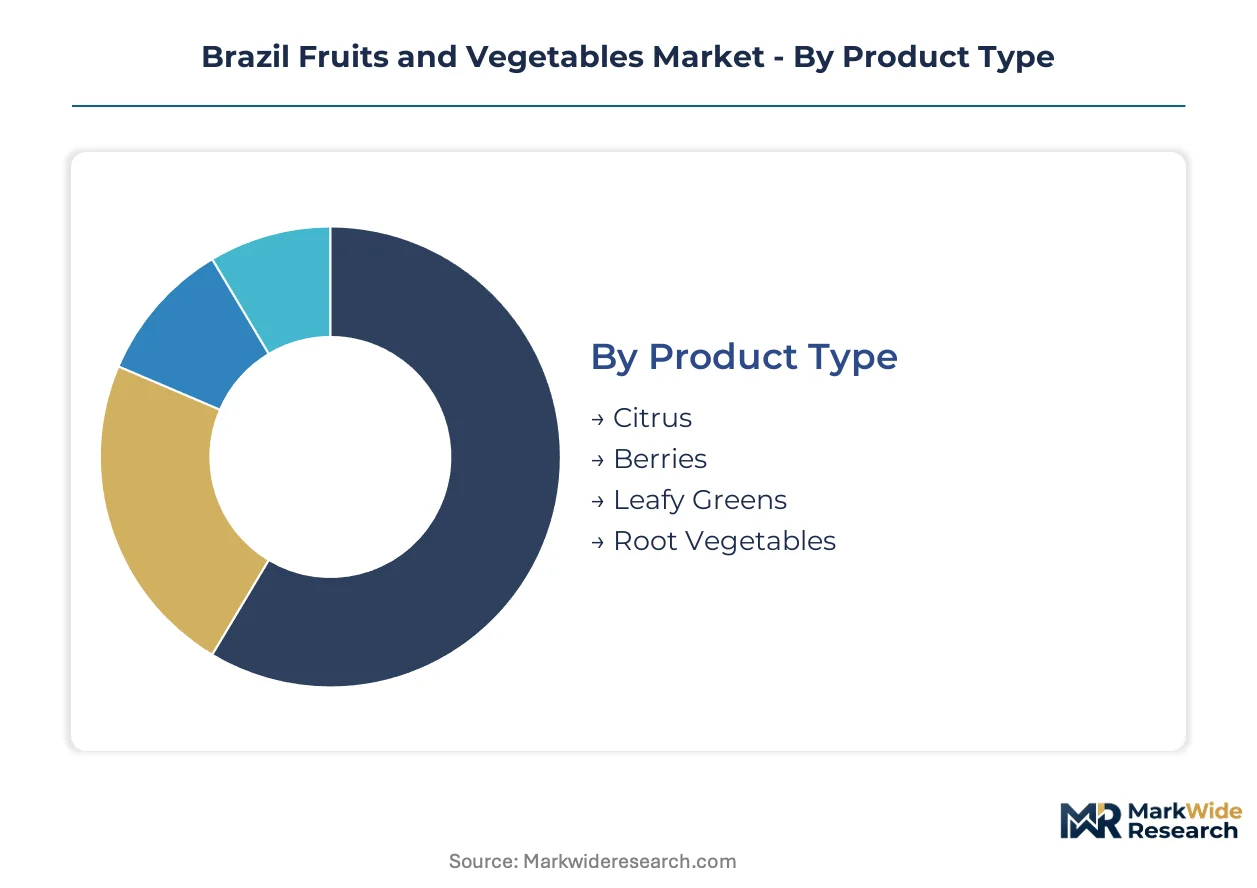
Brazil's fruits and vegetables market segments along four distinct axes that determine pricing power, shelf placement, and regulatory burden. Each segmentation layer reveals divergent margin structures and capital intensity requirements across the supply chain.
Product Type:
Citrus dominates standardized bulk procurement contracts with processors, while berries and leafy greens command customization premiums through rapid variety turnover and packaging differentiation.
- Citrus:Oranges, limes, and grapefruits harvested for Brix content specifications and processed into frozen concentrate or fresh juice. São Paulo's citrus belt supplies Citrosuco and Cutrale with controlled-environment orchards meeting EU Green Deal phytosanitary protocols. ANVISA residue testing creates dual compliance tracks for export-bound versus domestic shipments.
- Berries:Strawberries, blueberries, and blackberries requiring precision-controlled cold chains from Minas Gerais highland farms. Perishability windows compress distribution radius to São Paulo and Rio de Janeiro retail clusters, forcing air freight substitution for export orders.
- Leafy Greens:Lettuce, spinach, and kale cultivated in Cerrado greenhouse corridors with hydroponic systems reducing water consumption.
- Root Vegetables:Carrots, cassava, and sweet potatoes sustaining wholesale margin pools through extended shelf stability and lower cold-chain dependency.
Most installed capacity flows through Citrus. Expansion is steepest in Berries.
Distribution Channel:
Channel selection determines traceability investment requirements and working capital cycles, with direct-to-retail formats absorbing compliance costs that wholesale intermediaries cannot shoulder.
- Online Retail:Farm-box subscription platforms and quick-commerce apps bypassing CEASA wholesale markets with GPS-tracked deliveries. São Paulo-based operators capture premium pricing through same-day fulfillment guarantees and organic certification transparency.
- Supermarkets:Organized retail chains in São Paulo and Rio de Janeiro centralizing procurement through direct farm partnerships and dedicated organic produce sections. SLC Agrícola leverages vertical integration to supply year-round vegetable programs.
- Farmers' Markets:Municipal feiras livres serving price-sensitive household segments with minimal packaging and no cold-chain intermediation.
- Wholesalers:Traditional CEASA market intermediaries losing volume share to integrated distributors as retail consolidation accelerates.
Supermarkets command the largest throughput volume. Online Retail is climbing the fastest.
End User:
End-user segmentation separates specification-driven industrial buyers from quality-sensitive foodservice operators and price-elastic household consumers.
- Households:Domestic consumers purchasing through retail channels with preference bifurcation between organic premium positioning and conventional price tiers.
- Restaurants:Foodservice operators in São Paulo and Rio de Janeiro demanding consistent sizing, visual grading, and reliable delivery windows for menu planning.
- Food Processing:Juice concentrate manufacturers and frozen pulp processors in Minas Gerais corridors pulling tropical fruit volume through long-term procurement contracts.
- Exporters:EU and North American-bound shipments requiring MAPA phytosanitary certification and ANVISA-aligned residue testing for market access preservation.
Food Processing absorbs the highest absolute tonnage. Exporters are gaining share fastest.
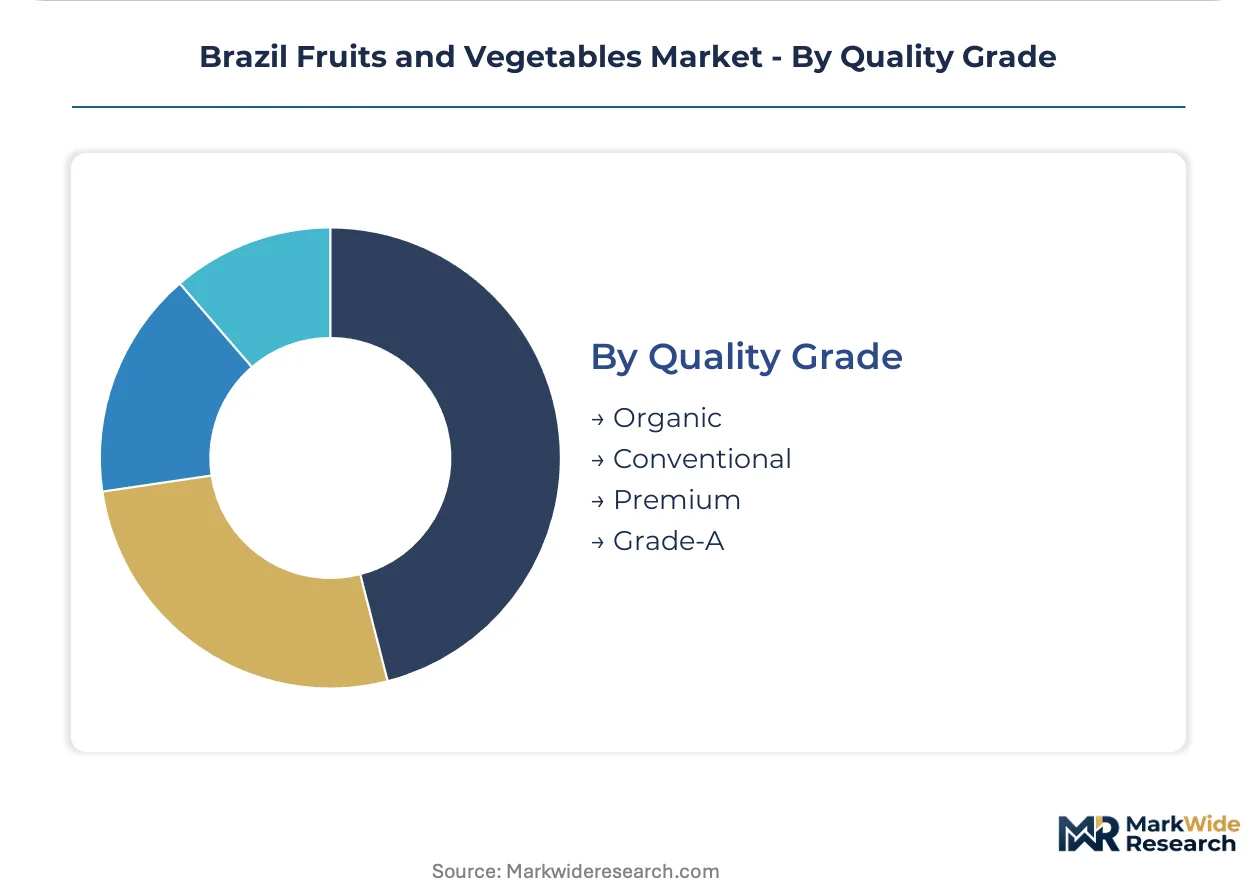
Quality Grade:
Quality stratification creates price differentiation that separates commodity bulk flows from certified premium channels with distinct margin structures.
- Organic:Certified production meeting EU organic standards and Brazilian organic regulations, commanding shelf price premiums in supermarket dedicated sections and online subscription boxes.
- Conventional:Standard pesticide-managed cultivation serving price-elastic household demand through wholesale and traditional retail channels.
- Premium:Above-grade sizing, extended shelf-life varieties, and enhanced visual defect thresholds targeting foodservice and upscale retail.
- Grade-A:Export-certified lots meeting destination market phytosanitary and residue specifications with full traceability documentation.
Conventional grade moves the largest volume. Organic is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's citrus belt anchors Brazil's fruit and vegetable production infrastructure, concentrating processing capacity and export logistics in a single contiguous zone that shapes national supply patterns.
São Paulo
Orange juice concentrate manufacturers drive procurement volume through long-term contracts with controlled-environment orchards. ANVISA's updated pesticide residue standards force dual compliance tracks for export-bound citrus. The Port of Santos corridor processes frozen concentrate shipments bound for European and North American buyers.
Minas Gerais
Controlled-environment agriculture investments enable year-round leafy greens output for domestic retail chains. MAPA enforces phytosanitary protocols and origin certification for corridor-bound shipments. Belo Horizonte distribution nodes pull vegetable volume through greenhouse clusters in the state's central highlands.
Rio de Janeiro
Foodservice operators in metropolitan zones demand consistent sizing and visual grading for menu planning. Municipal health surveillance agencies coordinate with federal regulators on cold-chain safety inspections. Niterói and Duque de Caxias logistics parks handle last-mile distribution for perishable produce.
Rio Grande do Sul
Apple and grape production clusters serve processing and fresh export channels with varietal specialization. State agricultural research institutes collaborate with MAPA on pest resistance breeding programs. Serra Gaúcha municipalities concentrate cooperative packing infrastructure for southern cone trade routes.
Bahia
Mango and papaya cultivation expands through irrigated perimeters in the São Francisco Valley. CODEVASF federal development programs finance water infrastructure for year-round tropical fruit output. Juazeiro and Petrolina twin cities anchor the hemisphere's largest irrigated fruit production zone.
Brazil Fruits and Vegetables Market Competitive Environment
Global majors compete with regional champions across seed genetics, processing infrastructure, and farm management technology. Market structure tilts toward consolidation at the processing tier while fragmentation persists among mid-sized growers lacking compliance capital. Three archetypes dominate: integrated farm-to-processor operators, input technology suppliers, and specialized seed breeders. Capacity expansion and backward integration into captive orchard supply represent the dominant competitive moves.
Among integrated operators, SLC Agrícola and Citrosuco occupy positions exemplifying scale-driven farm management and processing control respectively. Cutrale anchors the frozen concentrate export tier with controlled manufacturing assets. Input technology suppliers including Syngenta represent the agritech archetype serving compliance-intensive production zones.
| Leading Market Players |
|---|
| SLC Agrícola |
| Limagrain |
| Citrosuco |
| Sakata |
| Rijk Zwaan |
| Syngenta |
| Bunge Brasil |
| Enza Zaden |
| Cutrale |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal deforestation-free supply chain mandates gate qualified supply and premium-tier pricing access for Brazilian citrus exporters, compressing farm-gate margins for non-compliant growers while rewarding integrated operators with dual ANVISA-Codex certification tracks. ANVISA's tightening maximum residue limits force processors to maintain parallel compliance infrastructure, with export-bound frozen concentrate orange juice commanding measurable premiums over domestic-grade shipments.
Pricing Analysis
Input-cost pass-through from agrochemical volatility squeezes citrus growers locked into fixed-price annual contracts with processors like Citrosuco and Cutrale. Three-tier pricing structure across organic, Grade-A export, and conventional domestic levels reflects certification burden and traceability investment. Pricing pressure stems from fertilizer price swings and MAPA inspection delays forcing air freight substitution. Households through traditional CEASA channels exhibit highest price sensitivity; EU-bound exporters demonstrate lowest sensitivity due to contract pass-through mechanisms.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket demand while CEASA wholesale intermediaries lose volume share to vertically integrated distributors. Supply concentrates in São Paulo's citrus belt, Minas Gerais greenhouse corridors, and Bahia's São Francisco Valley irrigated perimeters. The chain draws from agrochemical inputs, controlled-environment infrastructure, and cold-chain logistics assets. Single-source vulnerability runs through Port of Santos congestion and container availability constraints. Distribution runs through farm-to-retail networks, e-commerce platforms, and traditional wholesale markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by household demand-shift toward organic certification and EU-compliant Grade-A export specifications. Premium positioning now requires traceability infrastructure and dual regulatory compliance.
For Market Incumbents: Anchor compliance capital deployment in ANVISA-aligned integrated pest management systems to defend against mid-sized grower consolidation pressure. Prioritize backward integration into captive orchard supply in Minas Gerais and São Paulo to secure volume under tightening residue standards. Channel control through direct supermarket partnerships offers margin defense against CEASA disintermediation. For New Entrants and Emerging Players: Capture white-space positioning in Amazon region greenhouse operations near Manaus distribution nodes, where population growth outpaces local vegetable production. Target e-commerce farm-box subscriptions with GPS-tracked traceability guarantees as the most penetrable channel bypassing traditional wholesale intermediation. Lead with organic certification transparency to differentiate in São Paulo and Rio de Janeiro premium retail clusters. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized compliant growers because ANVISA's regulatory timeline compression forces capital-constrained operators toward exit. Long-term viability centers on 5-10 year organic certification transition and EU market access preservation. Acquisition target archetype: São Paulo citrus belt operators with installed integrated pest management infrastructure. Watch MAPA inspection backlog resolution as signal for air freight margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Pest Management Deployment | ANVISA residue compliance preserves EU market access for export-bound citrus shipments. |
| Direct Farm-to-Retail Partnerships | Supermarket procurement consolidation displaces CEASA wholesale intermediaries in São Paulo. |
| Cold-Chain Infrastructure Expansion | Climate-controlled logistics extend perishability windows for Minas Gerais leafy greens. |
| Organic Certification Program | EU organic standards command shelf price premiums in dedicated supermarket sections. |
| Port of Santos Logistics Investment | Container availability solutions reduce shipment delays for frozen concentrate orange juice. |
Study Parameters
Bottom-up food processing and retail procurement modeling reconciled against top-down agricultural output tracking forms the analytical core of this study. Primary interviews with citrus orchard managers, MAPA regulatory inspectors, supermarket category buyers, cold-chain logistics operators, and juice concentrate procurement directors combined with secondary validation from ANVISA residue limit publications, MAPA phytosanitary trade data, CEASA wholesale market volume reports, and EU Green Deal regulatory filings. Triangulation across supply-side capacity and demand-side procurement patterns ensures cross-verified outputs.
Input-output matrix framing connects planted area, yield assumptions, and Brix content specifications to downstream pricing tiers across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user category, and quality grade certification level. CAGRs derive from compounded annual movement in volume and value outputs. Industry-specific forecast inputs incorporate ANVISA regulatory alignment timelines and EU deforestation-free supply chain implementation phases.
Regulatory enforcement variance, agrochemical input cost spikes, and port logistics congestion are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding compliance adoption rates and trade agreement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Asia Pacific Orange Market