
 Brazil Food Hydrocolloids Market | 2026-2036
Brazil Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Hydrocolloids Market Outlook
Premium-grade hydrocolloid specifications is bifurcating the competitive landscape in Brazil. Cargill Incorporated leverages its vertical integration into guar supply chains to control raw material quality from farm to formulation. Kerry Group differentiates through specialized stabilizer blends tailored to tropical dairy processing conditions. AgarGel anchors its position in the high-purity agar segment serving pharmaceutical-adjacent food applications.
Food hydrocolloids are high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify rheology, typically functioning at concentrations between 0.1% and 2.0% by weight to achieve viscosity or gelation targets. Their primary commercial purpose centers on texture engineering, shelf-life extension, and phase stabilization in processed foods. Guar gum and xanthan gum dominate volume flows through the dairy products channel, where thermal stability under UHT processing creates durable margin pools. Pectin exhibits the most rapid expansion within confectionery and clean-label sauces, as acid-stable gelling performance aligns with reduced-sugar formulation trends. Powdered hydrocolloids sustain overwhelming form preference due to logistics efficiency and extended ambient storage stability across Brazil's distribution infrastructure.
ANVISA governs food additive approvals and maximum usage levels, while the Ministry of Agriculture's MAPA enforces Good Manufacturing Practices across hydrocolloid processing facilities. Both frameworks elevate compliance costs for imported specialty grades while creating protected demand pockets for domestically manufactured, certified-clean-label alternatives. Stakeholders must monitor pending ANVISA consultations on revised xanthan gum purity specifications, as these determinations will reshape sourcing strategies and reformulation investments across Brazilian processed food portfolios.
Market Dynamics
ANVISA's updated food additive regulations are compressing formulation timelines across Brazilian processed food portfolios, forcing manufacturers to accelerate substitution toward natural hydrocolloids before compliance deadlines crystallize.
Growth Catalysts
- Clean-label mandates:ANVISA's revised purity specifications for synthetic additives are pushing dairy processors toward guar gum and pectin alternatives. São Paulo's concentrated food manufacturing base amplifies adoption velocity.
- Tropical processing requirements:Heat-stable hydrocolloid blends enable UHT dairy operations to maintain texture integrity across Brazil's ambient distribution infrastructure without cold-chain dependency.
- Reduced-sugar confectionery:Pectin's acid-stable gelling performance supports reformulation in candy and sauce segments as MAPA enforces stricter nutritional labeling thresholds.
Market Restraints
- Guar seed supply volatility:Rainfall-dependent cultivation in Rajasthan and Gujarat creates raw material price instability that compresses margin predictability for Brazilian formulators.
- Import certification friction:MAPA's Good Manufacturing Practice enforcement elevates compliance costs for specialty hydrocolloid grades manufactured outside Mercosur trade zones.
- Xanthan gum purity uncertainty:Pending ANVISA consultations on revised microbial specifications are freezing long-term sourcing commitments across bakery and beverage channels.
Strategic Opportunities
- Pharmaceutical-adjacent food segments:High-purity agar specifications for clinical nutrition and infant formula applications command premium positioning above commodity hydrocolloid tiers.
- Northeast Brazil logistics gaps:Underdeveloped cold-chain infrastructure in Pernambuco and Ceará creates demand for ambient-stable powdered hydrocolloid systems in processed meat and bakery distribution.
- Biotechnology convergence:Precision fermentation-derived hydrocolloids are emerging as alternatives to agricultural extraction, though ANVISA's novel food approval pathways remain untested for these inputs.
Industry Challenges
- Reformulation technical debt:Legacy synthetic stabilizer systems in established Brazilian product lines require complete texture engineering rebuilds, stretching R&D capacity at mid-tier processors.
- Specialized talent scarcity:Hydrocolloid functionality expertise combining rheology, food chemistry, and tropical processing conditions concentrates among a limited pool of formulation scientists in Campinas and São Paulo research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Hydrocolloids Market |
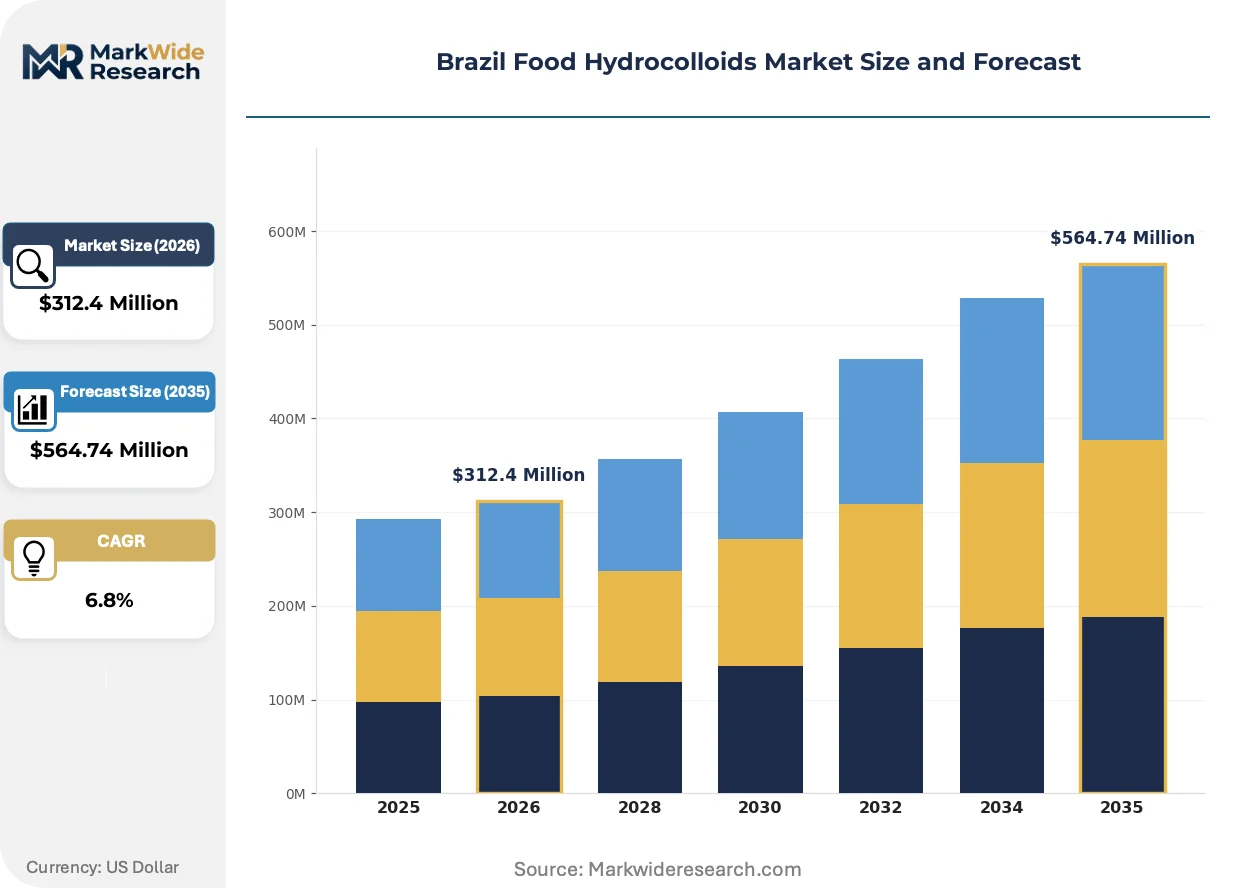
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Guar Gum, Xanthan Gum, Pectin Application: Dairy Products, Bakery, Confectionery, Sauces Functionality: Thickener, Stabilizer, Gelling Agent, Emulsifier Form: Powder, Liquid, Granules, Gel |
| Companies Covered | Cargill Incorporated, DuPont, Ingredion Inc, CP Kelco, Kerry Group, Tate & Lyle, Archer-Daniels Midland, Vogler Ingredients, AgarGel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Hydrocolloids Market Strategic Shifts
Formulation science is pivoting toward precision functionality as Brazilian processors reject one-size-fits-all hydrocolloid specifications in favor of application-specific performance guarantees.
Encapsulated hydrocolloid delivery systems are miniaturizing active ingredient protection for probiotic and omega-3 fortification in ambient dairy beverages. Minas Gerais dairy cooperatives are piloting these systems at commercial scale. The technology is miniaturizing protection windows from months to years without refrigeration dependency.
ANVISA's pending consultation framework for microbial-derived food additives is compressing approval timelines for precision fermentation hydrocolloids. Brazilian ingredient distributors are pre-positioning technical dossiers ahead of regulatory clarity. Dairy alternative manufacturers in São Paulo state's plant-based corridor face the most immediate reformulation pressure from these pending determinations.
Direct-procurement relationships between food manufacturers and agricultural cooperatives are displacing traditional ingredient distributor intermediaries in guar and tara gum sourcing. Large Brazilian meat processors are negotiating volume commitments with Rio Grande do Sul farmers. This channel consolidation is most visible in the clean-label sausage and prepared meals segments where traceability documentation carries premium value.
Brazil Food Hydrocolloids Market Segmentation
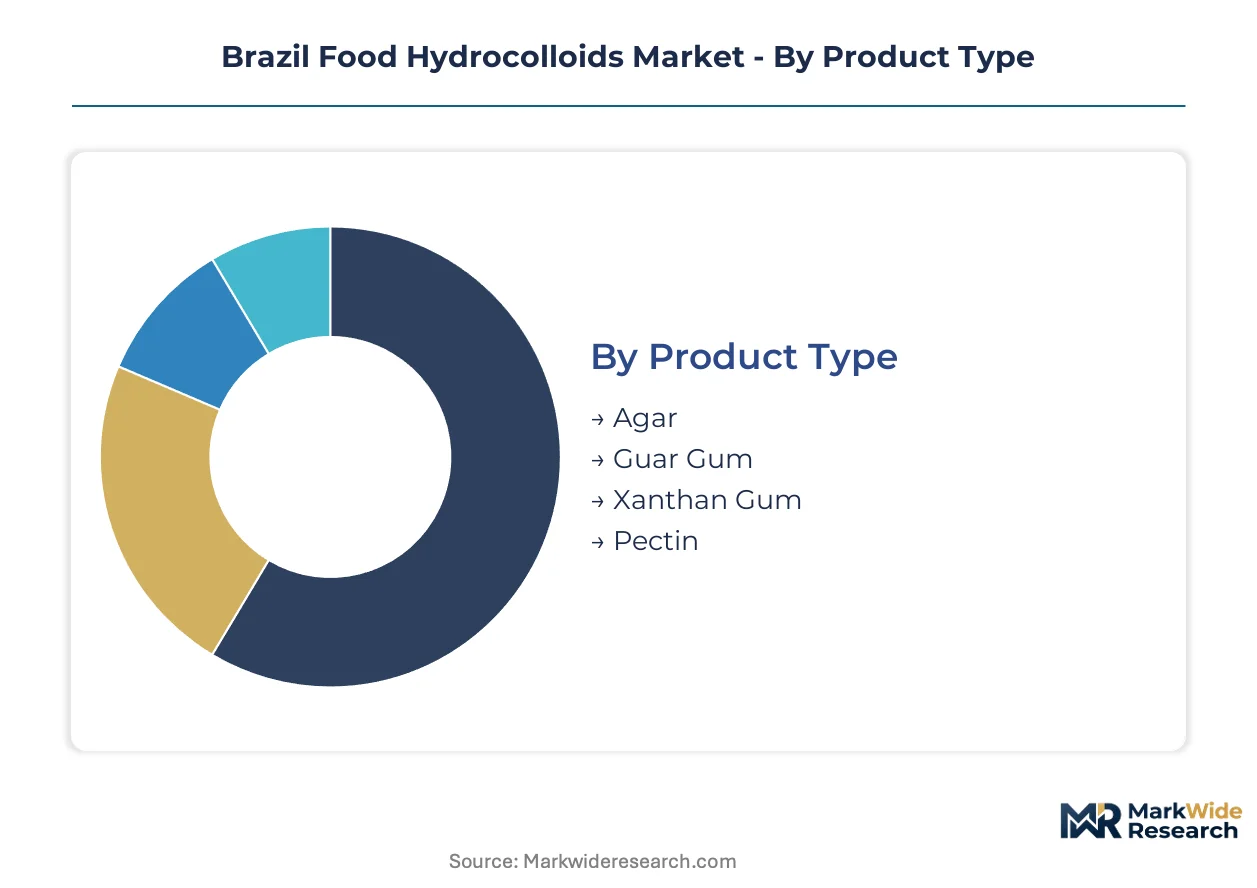
Hydrocolloid procurement patterns in Brazil diverge sharply between commodity dairy processors seeking cost-optimized volume and premium confectionery houses demanding certified-clean-label specifications. Channel fragmentation forces suppliers to maintain parallel inventory strategies across São Paulo's industrial corridor and Northeast Brazil's logistics-constrained markets.
Product Type:
Guar gum and xanthan gum dominate dairy and bakery channels through São Paulo distributors, while agar and pectin concentrate in pharmaceutical-adjacent and reduced-sugar applications respectively.
- Guar Gum:Cold-water-soluble galactomannan polysaccharide derived from Cyamopsis tetragonoloba seeds, functioning as a viscosity builder at concentrations below 1.0%. São Paulo state's UHT dairy processors account for concentrated demand as ANVISA's additive purity deadlines accelerate synthetic replacement timelines.
- Xanthan Gum:Microbial exopolysaccharide produced via Xanthomonas campestris fermentation, delivering pseudoplastic rheology and exceptional thermal stability. Brazilian beverage manufacturers stockpile inventory ahead of pending ANVISA microbial specification consultations that threaten supply continuity.
- Agar:Red algae-extracted sulfated galactan with high gel strength and reversible thermal hysteresis, commanding premium positioning in clinical nutrition segments.
- Pectin:Citrus peel and apple pomace-derived heteropolysaccharide with acid-stable gelling performance, expanding fastest in reduced-sugar confectionery reformulations.
By volume, guar gum leads. By growth pace, pectin is ahead.
Application:
Cost tier stratification separates commodity dairy applications from premium confectionery and clean-label sauce segments, with bakery occupying the contested middle ground.
- Dairy Products:UHT milk, yogurt, and cheese systems requiring heat-stable viscosity control through ambient distribution chains. Northeast Brazil's cold-chain gaps amplify powdered hydrocolloid preference in this channel.
- Bakery:Bread, cake, and pastry applications leveraging hydrocolloid moisture retention and crumb structure modification. São Paulo industrial bakeries drive specification standardization.
- Confectionery:Gummy candy, jellies, and reduced-sugar sweets demanding precise gel strength and acid stability. MAPA nutritional labeling thresholds accelerate pectin adoption here.
- Sauces:Clean-label ketchup, mayonnaise, and dressings requiring emulsion stability without synthetic stabilizers. Premium positioning commands ingredient cost premiums of 40-60% above commodity tiers.
Dairy Products captures the largest volume flows. Confectionery exhibits the steepest expansion trajectory.
Functionality:
Application requirements dictate whether processors prioritize single-function purity or multi-functional blends, with tropical processing conditions favoring heat-stable stabilizer combinations.
- Thickener:Viscosity modification in aqueous systems through molecular entanglement and hydration. Beverage and sauce applications concentrate demand in Minas Gerais processing clusters.
- Stabilizer:Phase separation prevention in emulsions and suspensions, critical for UHT dairy shelf-life extension. Heat-stable specifications command 15-25% price premiums over standard grades.
- Gelling Agent:Three-dimensional network formation via hydrogen bonding and ionic crosslinking. Confectionery and dairy dessert segments drive specification diversity.
- Emulsifier:Interface stabilization between immiscible phases, often combined with protein systems in processed meat and bakery applications.
Thickener functionality leads by installed base. Stabilizer specifications are climbing the fastest as clean-label dairy reformulations accelerate.
Form:
Logistics infrastructure maturity determines form preference, with powder dominating ambient-stable distribution and liquid concentrates penetrating integrated processing facilities.
- Powder:Dehydrated hydrocolloid with extended ambient storage stability, preferred across Brazil's distribution infrastructure. São Paulo dairy processors specify powder for inventory flexibility.
- Liquid:Pre-hydrated solutions enabling direct dosing and dust-free handling, penetrating large-scale beverage and sauce manufacturing. Cold-chain requirements limit Northeast Brazil penetration.
- Granules:Intermediate particle size for controlled hydration kinetics, niche positioning in specialized bakery premixes.
- Gel:Pre-formed hydrocolloid matrices for precise texture engineering in premium confectionery and pharmaceutical-adjacent food applications.
Powder leads by volume margin. Liquid form is gaining share fastest in integrated São Paulo processing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's food hydrocolloids trade flows through São Paulo's port infrastructure, with import dependency for specialty grades contrasting against domestic extraction capacity in southern states. Regional consumption clusters align with processed food manufacturing corridors rather than population distribution alone.
São Paulo
UHT dairy processors in Campinas and Sorocaba drive concentrated demand for heat-stable guar gum and xanthan gum specifications. ANVISA's regulatory consultations on additive purity create compliance urgency among manufacturers headquartered in the state capital. The ABC Paulista industrial belt hosts formulation laboratories serving national bakery and confectionery accounts.
Minas Gerais
Dairy cooperatives in the Triângulo Mineiro region pilot encapsulated hydrocolloid systems for probiotic fortification in ambient-stable beverages. MAPA enforcement of Good Manufacturing Practices elevates certification requirements for local processing facilities. Belo Horizonte's research clusters concentrate rheology expertise for tropical dairy applications.
Rio Grande do Sul
Direct procurement relationships between meat processors and tara gum agricultural cooperatives are displacing traditional distributor channels. The state's southern plains support cultivation trials for domestic hydrocolloid feedstock alternatives. Porto Alegre's food technology institutes collaborate with processors on clean-label sausage reformulations.
Bahia
Northeast Brazil's underdeveloped cold-chain infrastructure creates demand for powdered hydrocolloid systems in processed meat distribution. Salvador's port facilities handle import flows for specialty grades serving regional bakery manufacturers. Feira de Santana's logistics hub struggles with ambient storage conditions that favor dehydrated stabilizer forms.
Paraná
Soy-based dairy alternative manufacturers in Londrina and Maringá face reformulation pressure from pending ANVISA determinations on microbial-derived additives. The state's agricultural research network experiments with precision fermentation feedstocks. Curitiba's ingredient distributors pre-position technical dossiers ahead of regulatory clarity.
Brazil Food Hydrocolloids Market Competitive Environment
Listed leaders compete with private specialists across formulation capabilities and supply chain control dimensions. The vendor base separates into three functional tiers: integrated agricultural processors commanding raw material security, blended stabilizer specialists capturing premium positioning, and regional distributors holding logistics advantages in underserved corridors. Strategic moves concentrate on backward integration into cultivation networks and technical partnership structures with dairy cooperatives.
Among North American-based multinationals, Cargill Incorporated and DuPont exemplify the integrated processor archetype through upstream control over agricultural supply chains. Kerry Group represents the formulation specialist tier with customized stabilizer blends. AgarGel occupies a position within the high-purity segment serving pharmaceutical-adjacent applications.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont |
| Ingredion Inc |
| CP Kelco |
| Kerry Group |
| Tate & Lyle |
| Archer-Daniels Midland |
| Vogler Ingredients |
| AgarGel |
| Others |
Value Chain & Pricing Dynamics
Scale economies in Rajasthan and Gujarat guar seed processing anchor Brazil's hydrocolloid price floors, compressing margin pools for São Paulo formulators when Indian monsoon failures trigger raw material volatility. ANVISA's additive purity deadlines accelerate demand for certified-clean-label grades, widening spreads between commodity and specialty specifications as buyers absorb compliance premiums.
Pricing Analysis
Industrial OEM buyers anchor Brazil's hydrocolloid pricing structure around contract-based long-term offtake agreements with quarterly price adjustments tied to Indian guar seed futures. Price differentiation separates pharmaceutical-grade agar certified to ANVISA microbial specifications from standard food-grade pectin used in mass-market confectionery. Pricing pressure intensifies in the commodity dairy segment as MAPA enforcement elevates certification costs for imported xanthan gum. Mid-tier meat processors exhibit highest price sensitivity, while infant formula manufacturers absorb premiums for traceability documentation.
Supply Chain Analysis
Rajasthan monsoon-dependent cultivation creates a chokepoint that underwrites supply volatility for Brazilian guar gum formulators, forcing inventory stockpiling ahead of ANVISA compliance deadlines. Raw material flows draw from India, China, and Argentina, with xanthan gum fermentation capacity concentrated in Shandong province and tara gum extraction anchored in Peruvian Andes cooperatives. Single-source vulnerability runs through Indian guar seed dependence, where drought cycles trigger 18-24 month price spikes. Distribution runs through São Paulo port infrastructure, with specialty grades clearing MAPA Good Manufacturing Practice inspection before inland trucking to Campinas dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's food hydrocolloids market operates as a substitution defense against precision fermentation-derived alternatives, where ANVISA's pending novel food approval pathways threaten to bypass agricultural extraction entirely if microbial production achieves cost parity.
For Market Incumbents: Fortify backward integration into tara gum cultivation networks across Rio Grande do Sul to secure traceability documentation for clean-label meat processors. Lock in multi-year supply agreements with Triângulo Mineiro dairy cooperatives before precision fermentation alternatives achieve ANVISA clearance, preserving volume commitments that block entrant access.
For New Entrants and Emerging Players: Anchor in Northeast Brazil's logistics-constrained markets where powdered hydrocolloid systems command 25-30% premiums over liquid alternatives due to cold-chain gaps. Target Feira de Santana distribution hubs serving Bahia's processed meat manufacturers, leveraging direct procurement relationships with agricultural cooperatives to displace traditional São Paulo-based distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulation specialists delivering customized stabilizer blends with embedded technical service contracts. Prioritize acquisition targets with captive agar extraction capacity serving pharmaceutical-adjacent segments, where clinical nutrition applications insulate margins from commodity dairy cycles. Monitor ANVISA consultation outcomes on microbial-derived additive specifications as the critical signal for fermentation entrant viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Networks | Direct procurement from Rio Grande do Sul tara cooperatives secures traceability premiums in clean-label sausage segments. |
| Encapsulation Technology Licensing | Probiotic protection systems from Minas Gerais research clusters enable ambient dairy shelf-life extension without refrigeration. |
| Specialty Grade Certification Investment | ANVISA microbial specification compliance opens pharmaceutical-adjacent infant formula channels above commodity tiers. |
| Regional Distribution Hub Expansion | Feira de Santana logistics capacity captures Northeast Brazil meat processing demand outside São Paulo control. |
| Precision Fermentation Dossier Pre-positioning | Technical submissions ahead of ANVISA novel food clarity secure first-mover advantage in microbial hydrocolloid approval. |
Study Parameters
A standing panel of hydrocolloid procurement managers at São Paulo dairy processors, MAPA compliance officers, formulation scientists at Campinas research clusters, and ingredient distributors across Brazil's Northeast corridor provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from ANVISA additive consultation records, MAPA Good Manufacturing Practice inspection reports, Brazilian customs import data, and trade flow databases from India and Argentina. Bottom-up volume estimates from individual processor consumption patterns triangulated against top-down market sizing from supply-side capacity assessments.
Consistency checks against external benchmarks validated projection outputs across the analysis window, with segmentation models disaggregating by hydrocolloid type, application channel, functionality requirement, and physical form. CAGRs derived from logarithmic trend fitting across annual volume and value estimates, incorporating ANVISA regulatory timeline assumptions and Indian monsoon pattern correlations as industry-specific forecast inputs.
Material uncertainties — ANVISA consultation outcomes on microbial-derived additives, Rajasthan rainfall variability, and precision fermentation cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and agricultural supply stability that practitioners should keep alternative scenarios live as these conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Europe Food Premix Market